
 Chlorine Market | 2026-2036
Chlorine Market Size, Share, and Industry Trends Forecast 2026-2036
Chlorine Market Intelligence
Modular chlorine delivery systems are restructuring buyer choice across municipal and industrial accounts. Olin Corporation leverages integrated chlor-alkali complexes to sustain cost leadership in North American bulk supply. INEOS anchors European chlorine derivatives production through its Antwerp-Rotterdam corridor network. Tosoh Corporation dominates membrane-cell technology leadership in Asian specialty chlorine grades.
Chlorine is a halogen element produced industrially through membrane-cell or mercury-cell electrolysis of brine, yielding high-purity gas or liquid for oxidation and disinfection applications. Liquid chlorine captures the largest volume share in water treatment due to storage efficiency and dosing precision. Chemical Manufacturing represents the fastest-growing application segment as chlorinated intermediates feed pharmaceutical and agrochemical synthesis. Municipalities command the most concentrated procurement volume among end users, with tender-based contracts locking multi-year supply agreements.
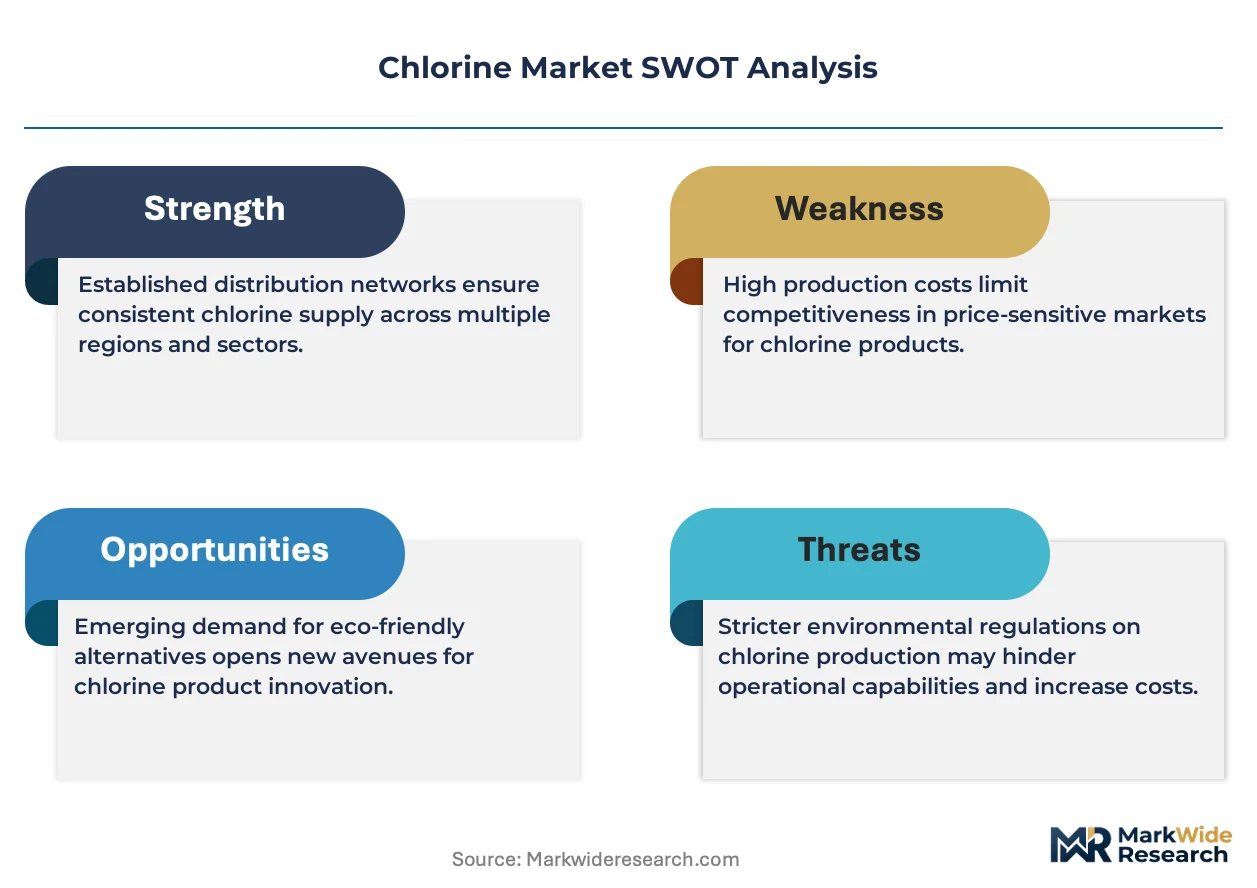
The EPA enforces Maximum Contaminant Level standards that constrain allowable disinfection byproduct levels in finished drinking water, elevating demand for higher-purity chlorine and alternative dosing technologies. OSHA's Process Safety Management standard governs chlorine handling thresholds at industrial facilities, shaping capital deployment for containment and leak-mitigation systems. ECHA's REACH framework restricts certain chlorinated solvent categories in European manufacturing, redirecting formulation demand toward compliant substitute chemistries. Stakeholders must monitor regulatory divergence between EPA and EU frameworks to anticipate product-grade specifications and regional supply allocation shifts.
Market Dynamics
Membrane-cell electrolysis is displacing mercury-cell production across chlor-alkali complexes, compressing capital recovery timelines while elevating purity specifications for downstream pharmaceutical and electronics-grade applications.
Growth Catalysts
- EPA Maximum Contaminant Level tightening:Utilities in the United States must reduce disinfection byproducts in finished drinking water, forcing upgrades to higher-purity chlorine grades and advanced dosing systems.
- Jal Jeevan Mission infrastructure rollout:India's national rural water supply program is driving bulk chlorination procurement across thousands of village-level treatment facilities.
- Membrane-cell technology diffusion:Energy-efficient electrolysis methods are lowering unit production costs while enabling on-site generation for industrial users seeking supply security.
Market Restraints
- Brine input cost volatility:Salt feedstock prices fluctuate with regional weather patterns and energy-intensive evaporation economics, squeezing margin predictability for producers.
- European chlorinated solvent restrictions:ECHA REACH framework limitations on perchloroethylene and trichloroethylene are redirecting formulation demand toward fluorinated and aqueous alternatives.
- Transportation infrastructure concentration:Liquid chlorine movement depends on specialized rail tankers and pressurized tank trucks, creating bottlenecks where carrier capacity tightens seasonally.
Strategic Opportunities
- On-site generation systems for remote municipalities:Modular electrolytic units bypass bulk delivery logistics for island and mountain communities lacking pipeline or rail access.
- Pharmaceutical intermediate synthesis expansion:Chlorinated building blocks for active pharmaceutical ingredients face supply tightness as Western drugmakers reshore critical starting material production.
- OSHA Process Safety Management compliance services:Industrial facilities require third-party risk assessment and containment engineering to meet handling threshold mandates.
Industry Challenges
- Electrolyzer membrane replacement skill scarcity:Specialized technicians for ion-exchange membrane maintenance are concentrated at original equipment manufacturers, extending downtime for independent operators.
- Legacy mercury-cell facility decommissioning complexity:Soil and groundwater remediation liabilities at retired plants demand prolonged environmental monitoring and regulatory sign-off before site redevelopment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chlorine Market |
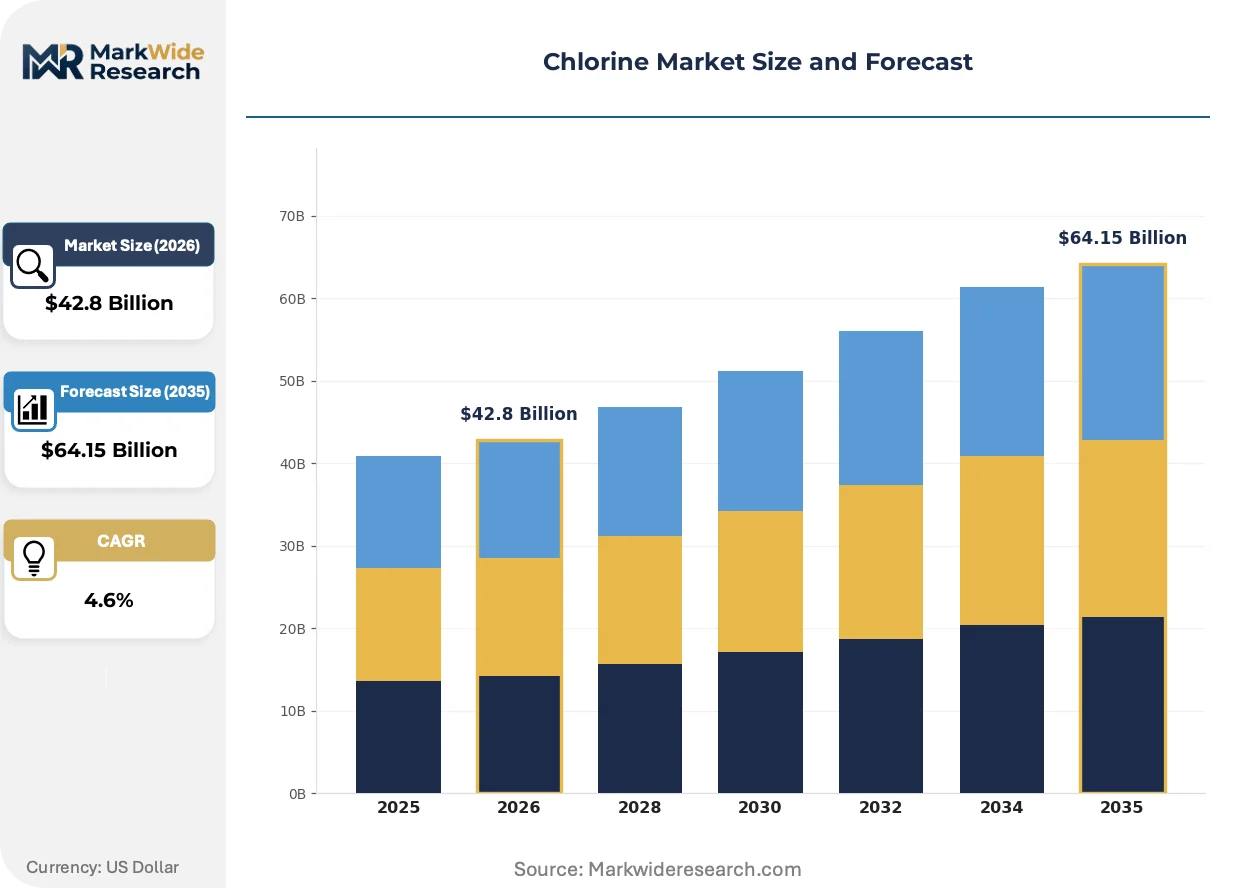
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $64.15 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Chlorine, Chlorine Gas, Chlorinated Solvents, Calcium Hypochlorite Application: Water Treatment, Bleaching Agents, Pulp & Paper, Chemical Manufacturing End User: Municipalities, Industrial Plants, Agriculture, Swimming Pools Distribution Channel: Direct Sales, Online Sales, Distributors, Retailers |
| Companies Covered | Olin Corporation, Westlake Corporation, INEOS, Occidental Petroleum Corporation, Hanwha Solutions, Solvay, Tosoh Corporation, Covestro AG, Formosa Plastics Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chlorine Market Strategic Shifts & Innovations
Electrochemical process intensification and digital dosing control are compressing the gap between production and point-of-use, reshaping how chlorine moves through industrial and municipal supply chains.
Membrane-cell electrolysis with coated titanium anodes is consolidating technical leadership in chlor-alkali production. Municipal utilities in Germany and Japan are retrofitting aging mercury-cell plants to meet corporate sustainability commitments and avoid carbon border adjustments. The technology is consolidating supplier bases as only capital-rich integrated producers can finance the billion-dollar conversion timelines.
EPA's updated Disinfectants and Disinfection Byproducts Rule is forcing granular operational changes across United States drinking water systems. Finished water monitoring requirements now mandate continuous trihalomethane and haloacetic acid testing, elevating demand for real-time analyzer integration with chlorine feed systems. Small community systems in the Midwest and Southeast are consolidating into regional authorities to spread compliance capital burdens.
Bulk tender contracts with five-to-seven year durations are giving way to shorter-term agreements with price-adjustment clauses tied to energy indices. Industrial buyers in chemical manufacturing are unbundling chlorine supply from technical service packages, selecting separate engineering contractors for dosing optimization. This pattern is most pronounced in India, where state pollution control boards are mandating third-party environmental audits independent of chemical suppliers.
Chlorine Market Segmentation
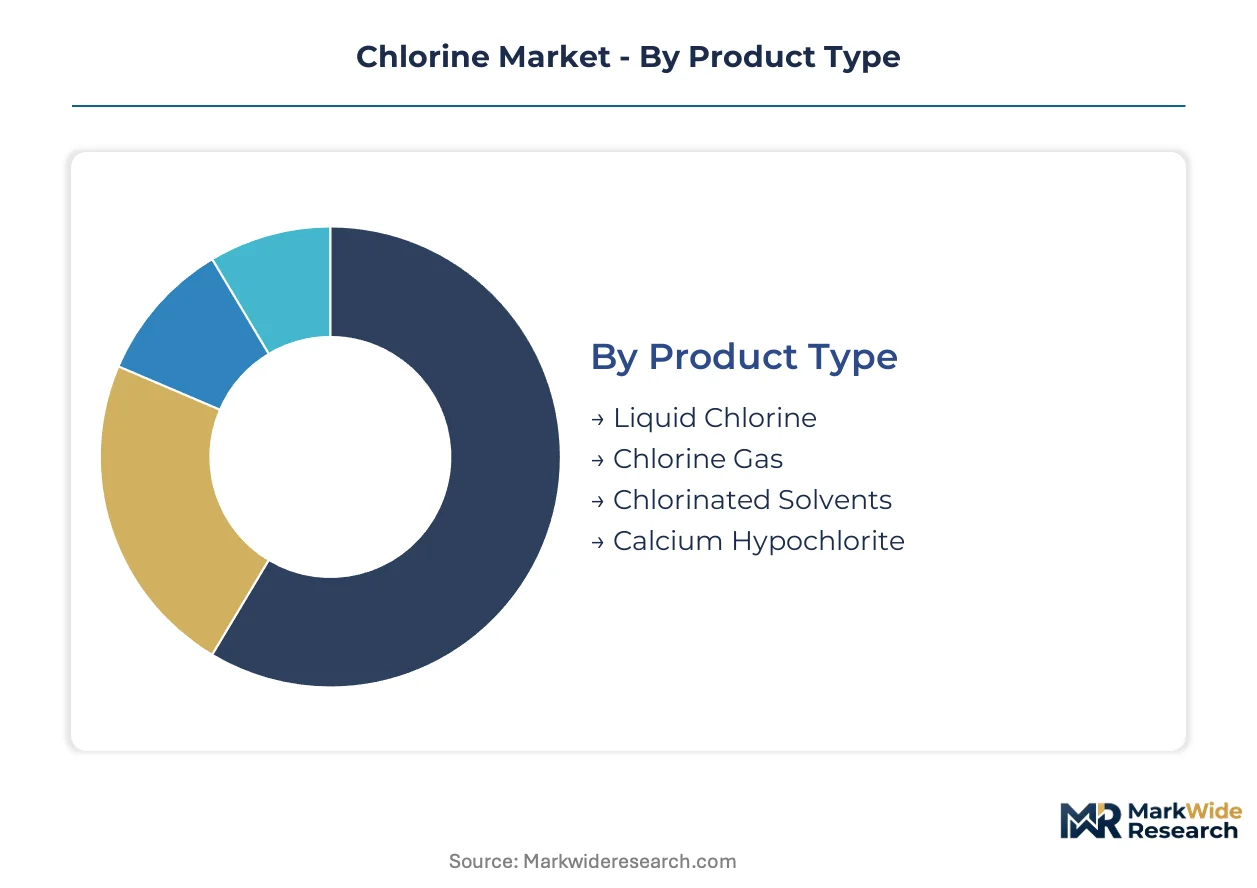
Chlorine procurement patterns diverge sharply across physical form, application chemistry, and buyer sophistication. Specification requirements for disinfection byproduct compliance are fragmenting product grades, while logistics constraints favor different delivery modes for municipal versus industrial accounts.
Product Type:
Membrane-cell purity specifications and storage economics define competitive positioning across physical forms.
- Liquid Chlorine:Compressed and liquefied under pressure to maximize transport density and dosing precision. Municipalities in India and the United States concentrate procurement here, driven by Jal Jeevan Mission infrastructure and EPA Maximum Contaminant Level compliance mandates for continuous disinfection systems.
- Chlorine Gas:Delivered in pressurized cylinders for high-volume industrial oxidation. Chemical manufacturers in Germany and Japan favor direct pipeline injection for pharmaceutical intermediate synthesis, where membrane-cell purity grades reduce downstream purification steps.
- Chlorinated Solvents:Perchloroethylene and trichloroethylene face ECHA REACH restrictions redirecting formulation demand.
- Calcium Hypochlorite:Solid tablet and granular forms serve remote municipalities lacking liquid handling infrastructure.
Mature deployment sits with liquid chlorine. Newer deployment is concentrated in calcium hypochlorite for decentralized systems.
Application:
End-use chemistry determines purity thresholds and contract structures across buyer segments.
- Water Treatment:Municipal disinfection consumes membrane-cell grades with minimized bromide and iodide content. India's state pollution control boards mandate third-party audits independent of chemical suppliers, compressing tender timelines.
- Chemical Manufacturing:Chlorinated intermediates for active pharmaceutical ingredients face supply tightness as Western drugmakers reshore production. This segment is gaining share fastest among applications.
- Bleaching Agents:Textile and paper mills in Bangladesh and Vietnam drive specification differentiation around organic halogen content.
- Pulp & Paper:ECF and TCF bleaching sequences reduce chlorine intensity per ton of pulp produced.
Volume concentration favors water treatment. Margin expansion is concentrating in chemical manufacturing.
End User:
Procurement sophistication and regulatory exposure separate buyer tiers.
- Municipalities:Tender-based contracts with five-to-seven year durations lock multi-year supply agreements. EPA Disinfectants and Disinfection Byproducts Rule compliance is forcing continuous analyzer integration with feed systems.
- Industrial Plants:OSHA Process Safety Management thresholds govern handling infrastructure capital. Chemical manufacturers unbundle supply from technical service packages, selecting separate engineering contractors.
- Agriculture:Irrigation system disinfection and pesticide synthesis drive seasonal procurement spikes.
- Swimming Pools:Residential and commercial aquatics favor calcium hypochlorite tablets for simplified handling.
Contract standardization sits with municipalities. Procurement flexibility is expanding among industrial plants.
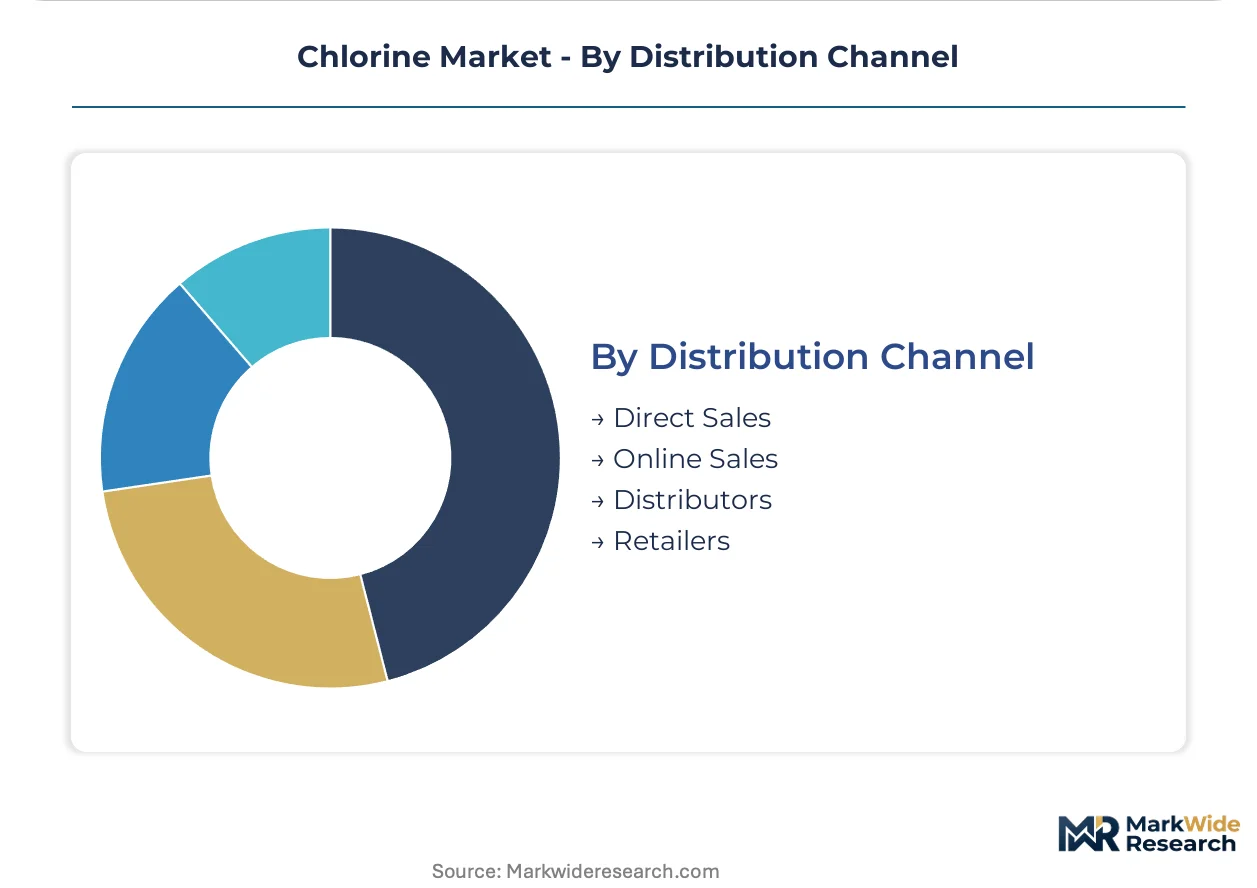
Distribution Channel:
Logistics infrastructure and buyer scale determine channel economics.
- Direct Sales:Integrated chlor-alkali producers serve high-volume municipal and chemical accounts through dedicated rail and pipeline networks. Olin Corporation leverages this channel for North American bulk supply.
- Distributors:Regional chemical distributors aggregate small industrial and agricultural buyers, managing specialized tanker fleets.
- Online Sales:Calcium hypochlorite and specialty grades move through digital procurement platforms for swimming pool and small agricultural accounts.
- Retailers:Hardware and pool supply chains serve residential end users with packaged hypochlorite products.
Channel maturity sits with direct sales. Digital penetration is expanding fastest among smaller volume buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters along coastal industrial corridors where brine access and export logistics converge, while consumption spreads across inland municipalities and chemical manufacturing zones. The United States, Germany, China, India, and Japan concentrate both chlor-alkali output and derivative demand.
United States
EPA Maximum Contaminant Level enforcement drives utility procurement of membrane-cell grades across Midwest and Southeast drinking water systems. The Disinfectants and Disinfection Byproducts Rule mandates continuous trihalomethane monitoring, forcing small community systems into regional consolidation. The Gulf Coast petrochemical corridor anchors bulk chlorine supply for downstream chemical synthesis.
Germany
ECHA REACH restrictions on chlorinated solvents redirect formulation demand toward compliant substitute chemistries. The country's national chemical regulator enforces stringent occupational exposure limits at industrial handling facilities. The Antwerp-Rotterdam corridor network supports integrated chlor-alkali complexes serving pharmaceutical intermediate manufacturers.
China
Dual carbon goals accelerate mercury-cell plant retirements in favor of membrane-cell electrolysis with coated titanium anodes. The Ministry of Ecology and Environment encloses chlor-alkali capacity within designated chemical industry parks. The Yangtze River Delta concentrates production for electronics-grade chlorine serving semiconductor fabrication.
India
The Jal Jeevan Mission drives bulk chlorination procurement across thousands of village-level treatment facilities. State pollution control boards mandate third-party environmental audits independent of chemical suppliers. Gujarat's industrial corridor hosts membrane-cell capacity serving textile bleaching and pharmaceutical synthesis.
Japan
METI industrial standards elevate purity specifications for electronics and pharmaceutical-grade chlorine. Corporate sustainability commitments accelerate mercury-cell plant retrofits to avoid carbon border adjustments. The Osaka-Kobe chemical cluster specializes in high-purity derivatives for active pharmaceutical ingredient production.
Chlorine Market Key Industry Players
The competitive structure tilts toward integrated chlor-alkali producers with captive brine sourcing and pipeline distribution networks. Three archetypes dominate: North American integrated producers with Gulf Coast export positioning, European corridor-network operators linking Antwerp-Rotterdam infrastructure, and Asian membrane-cell technology specialists serving electronics-grade demand. Capacity expansion and strategic partnerships constitute the primary competitive moves, with producers securing long-term municipal tender contracts and industrial offtake agreements.
Among North American integrated producers, Olin Corporation and Westlake Corporation exemplify scale-driven archetypes with dedicated rail and pipeline networks. INEOS anchors European chlorine derivatives production through corridor-network positioning. Tosoh Corporation occupies a technology-leadership position in Asian specialty grades. These three represent distinct geographic and capability clusters rather than direct substitutability.
| Leading Market Players |
|---|
| Olin Corporation |
| Westlake Corporation |
| INEOS |
| Occidental Petroleum Corporation |
| Hanwha Solutions |
| Solvay |
| Tosoh Corporation |
| Covestro AG |
| Formosa Plastics Corporation |
| Others |
Cost & Logistics Intelligence
Membrane-cell purity grades command substantial premiums over mercury-cell commodity output, and this bifurcation manifests in contract structures that tie pricing to EPA Maximum Contaminant Level compliance tiers while concentrating supply chain investment around dedicated rail tanker fleets and pressurized pipeline networks serving municipal utilities.
Pricing Analysis
Margin tightening in standard-grade chlorine reflects brine input cost volatility and seasonal carrier capacity constraints. Contract-based long-term offtake agreements dominate municipal procurement, with price-adjustment clauses indexed to energy costs. Premium-mid-economy pricing differentiation tracks membrane-cell certification tiers and bromide-iodide content specifications. Chemical manufacturers show least price sensitivity due to downstream purification cost avoidance, while agricultural buyers face acute sensitivity during seasonal procurement spikes.
Supply Chain Analysis
Regional distribution centers along the Gulf Coast, Antwerp-Rotterdam corridor, and Gujarat industrial belt enable hub-and-spoke patterns for liquid chlorine delivery. Production draws from integrated chlor-alkali complexes in the United States, Germany, China, India, and Japan. Salt feedstock, coated titanium anodes, and ion-exchange membranes anchor raw material dependencies. Single-source vulnerability concentrates around specialized membrane replacement technicians. Distribution runs through dedicated rail tankers, pressurized tank trucks, and pipeline injection systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance arena where EPA Maximum Contaminant Level enforcement erects formidable barrier-to-entry moats for membrane-cell certified producers, marginalizing legacy mercury-cell operators unable to finance billion-dollar conversion timelines.
For Market Incumbents: Anchor membrane-cell capacity leadership through captive brine sourcing and backward integration into salt evaporation assets. Defend against on-site generation substitutes by locking multi-year municipal tender contracts with embedded technical service packages. Prioritize corridor-network positioning along coastal industrial zones to minimize transport bottlenecks. For New Entrants and Emerging Players: EPA Disinfectants and Disinfection Byproducts Rule compliance in the United States opens a window for modular electrolytic system deployment targeting small community water systems facing regional consolidation pressure. Target remote municipalities lacking rail access in India's Jal Jeevan Mission rollout. Pursue third-party environmental audit certification as a differentiated go-to-market angle. For Investors and Strategic Acquirers: Re-rating potential sits with integrated chlor-alkali operators possessing pipeline distribution networks and membrane-cell technology licenses given carbon border adjustment exposure accelerating mercury-cell retirements. Long-term viability favors producers with captive brine and pharmaceutical-grade certification. Monitor EPA enforcement intensity across Midwest and Southeast drinking water systems as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane-Cell Capacity Conversion | Billion-dollar retrofits at legacy plants secure EPA compliance and carbon border adjustment immunity. |
| Backward Integration into Brine Sourcing | Captive salt evaporation assets insulate margin from regional weather-driven feedstock volatility. |
| On-Site Generation System Deployment | Modular electrolytic units bypass rail bottlenecks for island and mountain municipalities. |
| Third-Party Environmental Audit Certification | Independent compliance verification meets India's state pollution control board mandates. |
| Long-Term Municipal Tender Contracting | Five-to-seven year agreements with price-adjustment clauses lock volume against spot market exposure. |
Research Approach
Trade databases, chlor-alkali industry association filings, and EPA enforcement records formed the secondary backbone, cross-referenced with primary interviews involving chlor-alkali plant managers, municipal water utility procurement leads, chemical manufacturing R&D directors, and specialized tanker fleet operators. Bottom-up volume estimates triangulated against top-down capacity assessments across membrane-cell and mercury-cell production bases.
Historical trendline analysis tracked grade-specific pricing spreads and contract duration patterns across the projection horizon. Segmentation modeling incorporated physical form, application chemistry, end-user sophistication, and regional regulatory cluster dimensions. CAGRs derived from elasticity-adjusted demand projections for water treatment compliance, pharmaceutical intermediate reshoring, and electronics-grade purity requirements.
The model assumes a particular technology adoption path; alternative pathways for mercury-cell retrofit acceleration or on-site generation diffusion would alter the outlook. Forecasts reflect assumptions around EPA enforcement continuity, brine cost normalization, and carrier capacity expansion. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
1,3-Propanediol (PDO) Market
Industrial Chemicals
N-Ethyl-2-Pyrrolidone Market
Industrial Chemicals
Food Grade Sodium Hypochlorite Market
Industrial Chemicals
Process Chromatography Market
Industrial Chemicals
Hydrogenated Bisphenol a Market
Industrial Chemicals
Global Alkylated Naphthalene Market
Industrial Chemicals
Inorganic Coagulants Market
Industrial Chemicals
Metal Treatment Chemical Market
Industrial Chemicals
Global Microencapsulated Pesticides Market
Industrial Chemicals
Global Silica Gel Market
Industrial Chemicals
Fluidized Bed Reactors Market
Industrial Chemicals
Oilfield Scale Inhibitors Market
Industrial Chemicals
Middle-East and Africa Surface Treatment Chemicals Market
Industrial Chemicals
Carbon Molecular Sieves Market
Industrial Chemicals
2-Ethoxy Propene Market
Industrial Chemicals
Multi Component Injection Moulding Technology Market