
 Sulfolane Market | 2026-2036
Sulfolane Market Size, Share, and Industry Trends Forecast 2026-2036
Sulfolane Market Analytics
Specialized chemical process engineering talent is redrawing competitive boundaries in sulfolane production. Chevron Phillips Chemical Company leverages its integrated Gulf Coast manufacturing complex to sustain captive feedstock advantages. Liaodong Fine Chemical anchors Chinese supply through specialized sulfolane purification capabilities. Sumitomo Seika Chemical differentiates via advanced solvent recycling technologies that reduce operational waste.
Sulfolane is a cyclic sulfone compound (tetrahydrothiophene 1,1-dioxide) with a boiling point of 285°C and exceptional thermal stability, manufactured through hydrogen peroxide oxidation of tetrahydrothiophene or sulfur dioxide addition to butadiene. Its primary industrial purpose centers on selective extraction of aromatic hydrocarbons (benzene, toluene, xylene) from mixed refinery streams in the petrochemical sector. The solvent product type dominates current revenue as refiners prioritize extraction efficiency in BTX unit retrofits. Pharmaceutical-grade chemical intermediate applications are expanding fastest, driven by API synthesis demand and tightening purity thresholds from FDA and EMA inspectors.
EPA effluent guidelines and OSHA process safety management standards govern US sulfolane handling, storage, and emissions disclosure, directly shaping capital allocation toward closed-loop recovery systems. REACH registration requirements in Europe and China's GB standards on hazardous chemical storage are elevating compliance costs for cross-border suppliers. Stakeholders must monitor evolving per- and polyfluoroalkyl substances scrutiny, as regulatory analogies could extend to sulfone-class solvents in downstream environmental assessments.
Market Dynamics
Refiners are retrofitting BTX extraction units with closed-loop solvent recovery systems to comply with tightening emissions protocols from MEE and EPA, compressing payback periods for high-purity sulfolane investments and concentrating procurement among integrated petrochemical complexes.
Growth Catalysts
- Shale-derived feedstock abundance:US Gulf Coast crackers are expanding aromatic extraction trains, lifting solvent-grade offtake from regional suppliers.
- API synthesis demand:Pharmaceutical-grade sulfolane consumption is climbing as FDA and EMA inspectors enforce tighter purity thresholds for chemical intermediates.
- MEE emissions enforcement:China's refiners are replacing degraded sulfolane cycles ahead of schedule, accelerating replacement demand.
Market Restraints
- Butadiene price volatility:Feedstock cost swings compress margins for producers lacking captive butadiene supply.
- Supply concentration in East Asia:Three specialized purification houses control pharmaceutical-grade output, creating single-source risk.
- N-methyl-2-pyrrolidone substitution:NMP competes in select extraction applications where thermal stability requirements are relaxed.
Strategic Opportunities
- India's petrochemical buildout:Reliance and Indian Oil are commissioning integrated BTX complexes with solvent extraction blocks.
- Solvent recycling technology convergence:Membrane separation plus distillation hybrid systems cut operational waste and extend solvent life.
- EU Green Deal chemical sector incentives:REACH-registered suppliers qualify for green procurement preferences in European refinery tenders.
Industry Challenges
- Process safety engineering scarcity:OSHA PSM-qualified talent commands premium wages, delaying project commissioning.
- Pharmaceutical-grade certification timelines:FDA DMF filing and EMA CEP approval cycles stretch 18-24 months for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sulfolane Market |
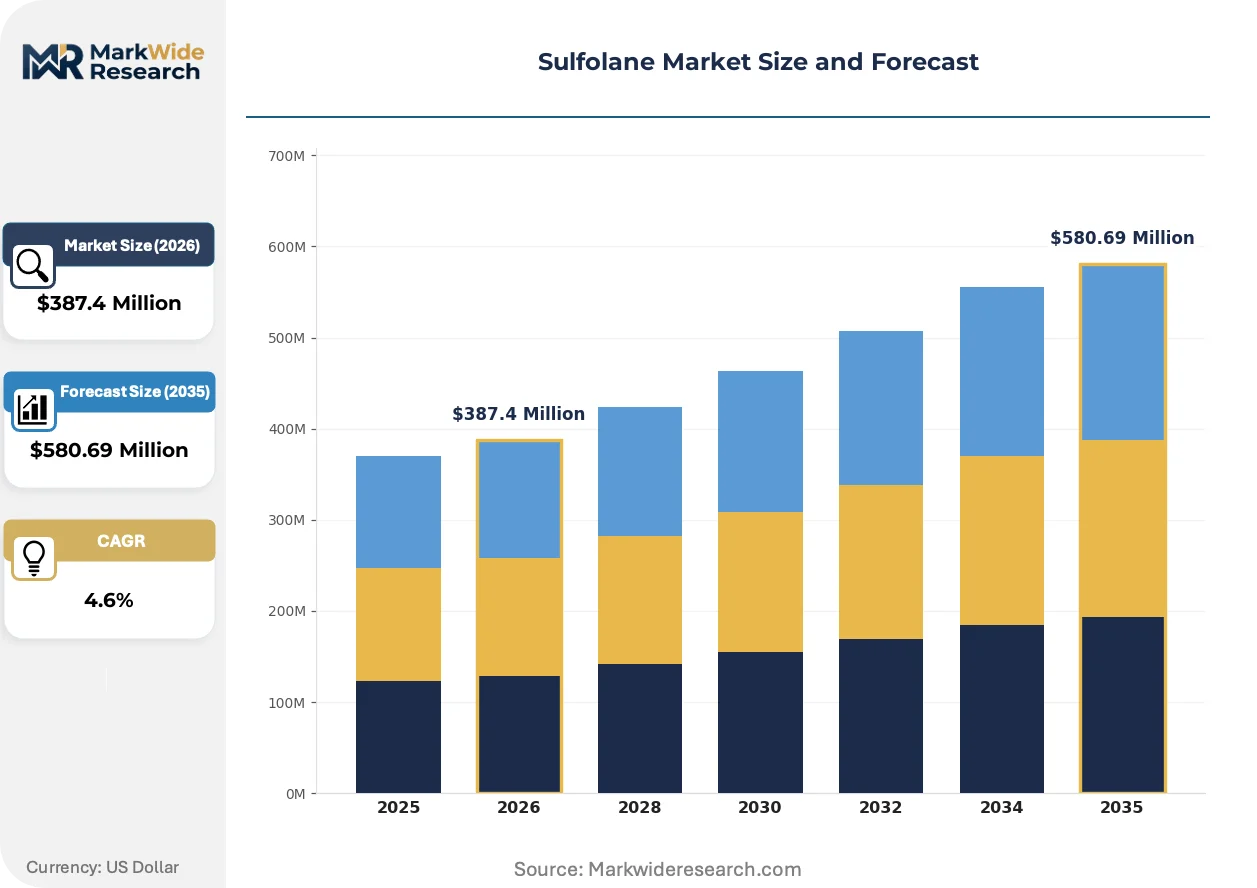
| Market Size in 2026 | $387.4 Million |
| Market Size in 2035 | $580.69 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solvent, Chemical Intermediate, Extraction Agent, Reaction Medium Application: Petrochemical, Pharmaceutical, Flavoring Agent, Polymer Processing End User: Oil & Gas, Chemical Manufacturing, Pharmaceuticals, Food Industry Distribution Channel: Direct Sales, Distributors, Online Sales, Retail |
| Companies Covered | New Japan Chemical, Liaodong Fine Chemical, Chevron Phillips Chemical Company, Changle Haizhou Chemical, CASIL Industries, Liaoyang Guanghua Chemical, Jinzhou Petrochemical Corporation, Cadila Pharmaceuticals, Sumitomo Seika Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sulfolane Market Evolving Landscape
Process intensification and regulatory precision are compressing equipment footprints while elevating purity thresholds, forcing technology choices that favor integrated solvent management over discrete unit operations.
Membrane-assisted solvent recovery is miniaturizing extraction unit footprints by embedding selective permeation stages before thermal regeneration. Refiners in Texas and Louisiana are piloting these skids to cut steam consumption. The technology is miniaturizing the traditional three-tower solvent loop into single-vessel architectures, reducing plot space requirements by half.
REACH registration dossiers now mandate granular exposure scenarios for sulfone-class solvents, forcing suppliers to generate substance-specific toxicology data. ECHA's 2023 substance evaluation wave targeted cyclic sulfones, elevating compliance costs for European importers. German and Dutch refiners are pre-qualifying suppliers with complete SVHC screening documentation to avoid supply interruption.
Long-term offtake agreements are displacing spot procurement in BTX extraction chemical purchasing. Integrated petrochemical operators in China and the US are signing five-year solvent supply contracts with embedded purity escalation clauses. This pattern is most pronounced along the US Gulf Coast, where shale economics favor capital commitment over inventory flexibility.
Sulfolane Market Segmentation
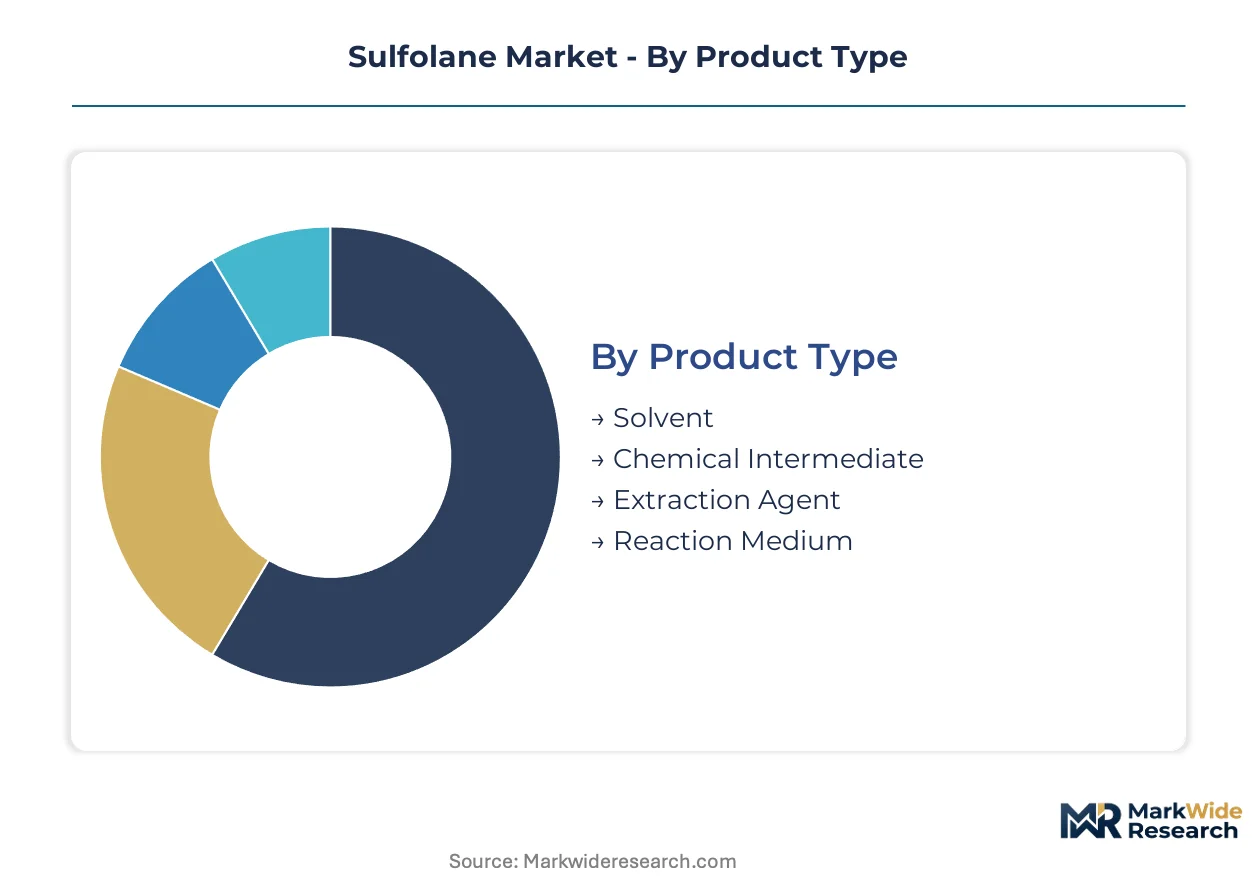
Sulfolane demand fragments across extraction chemistry, pharmaceutical synthesis, and specialty polymer processing, with each segment imposing distinct purity specifications and regulatory compliance burdens. Procurement patterns diverge sharply between captive refinery supply chains and merchant pharmaceutical-grade distribution.
Product Type:
Domestic consumption dominates solvent-grade volumes tied to US Gulf Coast and Chinese refinery complexes, while pharmaceutical-grade and specialty chemical intermediates flow through export-oriented purification houses in East Asia and Europe.
- Solvent:Tetrahydrothiophene 1,1-dioxide formulation with 285°C boiling point serves BTX extraction loops in petrochemical complexes. Demand concentrates along the US Gulf Coast where shale-derived feedstock supports expanded aromatic extraction capacity, with Chevron Phillips Chemical and regional refiners driving procurement.
- Chemical Intermediate:High-purity grades meet API synthesis specifications under FDA and EMA oversight. Liaodong Fine Chemical and Sumitomo Seika Chemical anchor supply through specialized purification capabilities, with replacement cycles accelerating under China's MEE emissions enforcement.
- Extraction Agent:Selective aromatic recovery from mixed refinery streams. Refiners in Texas and Louisiana pilot membrane-assisted recovery skids to cut steam consumption.
- Reaction Medium:Thermal stability supports high-temperature polymerization chemistry. Pharmaceutical contract manufacturers in India and Germany represent emerging offtake.
Solvent holds the largest share; momentum sits with chemical intermediate as FDA and EMA purity thresholds tighten.
Application:
Cost tier stratification separates commodity extraction chemicals from certified pharmaceutical intermediates, with margin structures diverging threefold between base solvent and API-grade specifications.
- Petrochemical:BTX unit retrofits and new aromatic extraction trains consume solvent-grade volumes. US Gulf Coast crackers expand capacity using shale economics, while Chinese refiners replace degraded cycles ahead of MEE compliance deadlines.
- Pharmaceutical:API synthesis and chemical intermediate applications demand 99.9%+ purity with full FDA DMF and EMA CEP documentation. Certification timelines stretch 18-24 months for new entrants, concentrating supply among three specialized purification houses.
- Flavoring Agent:Food-grade specifications under FSSAI and FDA food additive regulations. Limited volume niche with concentrated European and North American demand.
- Polymer Processing:High-temperature reaction medium for specialty polymer synthesis. Japanese and German chemical manufacturers anchor technical-grade offtake.
Petrochemical applications dominate volume; pharmaceutical represents the steepest expansion trajectory as generic API manufacturing scales in India and China.
End User:
Customer type determines procurement modality, with integrated oil and gas operators favoring long-term offtake agreements while merchant pharmaceutical buyers prioritize certified supplier relationships.
- Oil & Gas:Integrated refiners and petrochemical complexes operate captive BTX extraction units. Five-year solvent supply contracts with embedded purity escalation clauses are displacing spot procurement along the US Gulf Coast.
- Chemical Manufacturing:Merchant producers of specialty chemicals and polymer intermediates. REACH-registered suppliers qualify for green procurement preferences in European refinery tenders.
- Pharmaceuticals:API manufacturers and contract development organizations. Sumitomo Seika Chemical differentiates via advanced solvent recycling technologies that reduce operational waste.
- Food Industry:Flavor and fragrance compound manufacturers. Stringent purity requirements limit qualified supplier base.
Oil and gas end users command the largest share; pharmaceuticals are gaining share fastest as FDA and EMA inspection intensity climbs.
Distribution Channel:
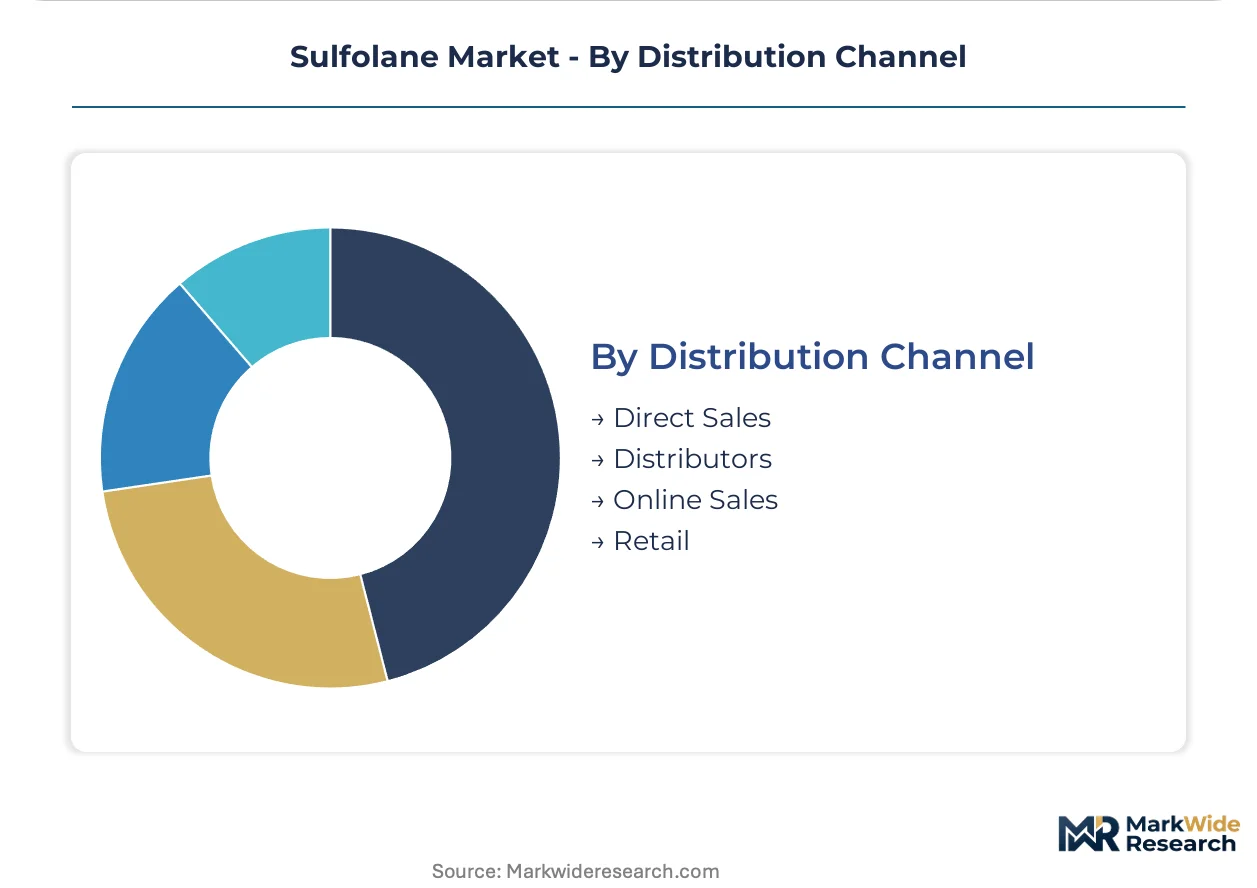
Supply concentration shapes channel selection, with direct sales dominating high-volume refinery contracts and distributor networks handling fragmented pharmaceutical and specialty chemical accounts.
- Direct Sales:Long-term supply agreements between sulfolane producers and integrated petrochemical operators. Liaodong Fine Chemical anchors Chinese supply through direct refinery relationships.
- Distributors:Regional chemical distributors serve merchant pharmaceutical and polymer processing accounts. REACH registration dossiers and SVHC screening documentation drive supplier pre-qualification.
- Online Sales:Limited to small-volume research-grade and laboratory chemical procurement. ECHA substance evaluation waves elevate compliance costs for European importers using digital channels.
- Retail:Minimal presence; restricted to specialty chemical reagents in laboratory supply catalogs.
Direct sales capture the largest share; distributor channels are expanding most quickly as pharmaceutical-grade certification requirements fragment supplier relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. US Gulf Coast refiners deploy sulfolane primarily for shale-derived BTX extraction, while Chinese operators face accelerated replacement cycles under tightening MEE emissions protocols. European demand concentrates in pharmaceutical-grade certification, with REACH-registered suppliers commanding procurement preference.
United States
Shale-derived feedstock abundance drives solvent-grade consumption along the Texas-Louisiana petrochemical corridor. EPA effluent guidelines and OSHA process safety management standards govern handling protocols. Chevron Phillips Chemical leverages its integrated Gulf Coast manufacturing complex to sustain captive supply advantages for regional refiners.
China
Refiners replace degraded sulfolane cycles ahead of schedule under MEE industrial emissions enforcement. GB standards on hazardous chemical storage elevate compliance costs for cross-border suppliers. Liaodong Fine Chemical anchors domestic supply through specialized purification capabilities serving petrochemical complexes.
Japan
Advanced solvent recycling technologies reduce operational waste in high-specification applications. METI oversight shapes chemical sector decarbonization roadmaps. Sumitomo Seika Chemical occupies a position within the technology-intensive tier serving pharmaceutical and polymer processing accounts.
Germany
REACH registration dossiers mandate granular exposure scenarios for sulfone-class solvents, forcing substance-specific toxicology data generation. ECHA substance evaluation waves elevate compliance costs for European importers. German refiners pre-qualify suppliers with complete SVHC screening documentation.
India
Reliance and Indian Oil commission integrated BTX complexes with solvent extraction blocks as part of national petrochemical buildout. CDSCO and FSSAI regulations govern pharmaceutical-grade applications. API synthesis demand climbs as generic manufacturing scales in Gujarat and Maharashtra clusters.
Sulfolane Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in sulfolane manufacturing. The upper tier commands captive feedstock access and long-term refinery offtake agreements. The specialist tier competes on purification technology and pharmaceutical-grade certification. Dominant competitive moves include backward integration into butadiene feedstock and membrane-assisted solvent recovery technology licensing.
Within the integrated petrochemical tier, Chevron Phillips Chemical Company exemplifies scale-driven positioning through Gulf Coast manufacturing concentration. Among East Asian purification specialists, Liaodong Fine Chemical and Sumitomo Seika Chemical occupy positions defined by pharmaceutical-grade certification capabilities. New Japan Chemical represents the technology-intensive archetype with advanced solvent recycling competencies.
| Leading Market Players |
|---|
| New Japan Chemical |
| Liaodong Fine Chemical |
| Chevron Phillips Chemical Company |
| Changle Haizhou Chemical |
| CASIL Industries |
| Liaoyang Guanghua Chemical |
| Jinzhou Petrochemical Corporation |
| Cadila Pharmaceuticals |
| Sumitomo Seika Chemical |
| Others |
Value Network & Pricing Analysis
Scale economies at US Gulf Coast petrochemical complexes compress unit costs for solvent-grade sulfolane, anchoring price floors while concentrating procurement power among integrated refiners with captive feedstock access. This concentration feeds into contract structures that favor multi-year offtake agreements over spot market flexibility, with purity escalation clauses shifting margin risk onto merchant suppliers lacking backward integration into butadiene feedstock.
Pricing Analysis
Long-term offtake contracts dominate solvent-grade procurement, displacing spot transactions as US Gulf Coast refiners lock in five-year supply agreements with embedded purity escalation clauses. Price differentiation rests on certification grade—pharmaceutical-grade commands threefold premiums over base solvent—and volume scale, with integrated petrochemical operators extracting favorable terms through captive consumption. Cost compression in standard-grade runs through butadiene price volatility, which squeezes margins for non-integrated producers. Merchant pharmaceutical buyers exhibit lowest price sensitivity due to FDA DMF and EMA CEP certification barriers, while commodity refiners drive hardest bargain negotiations.
Supply Chain Analysis
Strategic stockpiling characterizes Chinese refinery procurement patterns under MEE emissions enforcement, with operators holding replacement cycles ahead of compliance deadlines rather than just-in-time replenishment. Manufacturing concentrates in China, the United States, and Japan, with East Asian purification houses controlling pharmaceutical-grade output. Feedstock draws from butadiene, tetrahydrothiophene, and hydrogen peroxide suppliers, with sulfur dioxide availability tethered to regional refinery operations. Single-source vulnerability pervades pharmaceutical-grade segments where three specialized houses dominate FDA-certified supply. Distribution runs through direct sales channels for high-volume refinery contracts, while regional distributors fragment pharmaceutical and specialty chemical accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized purification capabilities and pharmaceutical-grade certification requirements fragment competitive space, creating defendable niches as FDA and EMA inspection intensity climbs and replacement cycle acceleration under Chinese emissions enforcement generates predictable demand pockets.
For Market Incumbents: Consolidate backward integration into butadiene feedstock to neutralize margin compression from raw material volatility, while expanding membrane-assisted solvent recovery technology licensing to capture value from refinery retrofit cycles. N-methyl-2-pyrrolidone substitution threat in relaxed thermal stability applications demands defensive purity escalation clause negotiation in contract renewals. For New Entrants and Emerging Players: Lead with solvent recycling technology convergence as entry wedge, targeting Indian petrochemical buildout where Reliance and Indian Oil commissioning schedules create supplier qualification windows. Pharmaceutical-grade certification in India offers most penetrable pathway given CDSCO regulatory alignment with FDA standards and generic API manufacturing scale-up in Gujarat clusters. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated Gulf Coast operators with captive refinery offtake agreements and embedded purity escalation clauses. Long-term viability favors targets with REACH-registered dossiers and complete SVHC screening documentation positioning for EU Green Deal procurement preferences. Watch MEE enforcement intensity in China as inflection indicator for replacement cycle predictability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Butadiene Feedstock | Captive supply neutralizes raw material volatility compressing merchant producer margins. |
| Membrane-Assisted Solvent Recovery Licensing | Texas and Louisiana refinery pilots validate technology for steam consumption reduction. |
| Pharmaceutical-Grade Certification Investment | FDA DMF and EMA CEP documentation opens API synthesis demand from inspection-intense regulators. |
| Long-Term Supply Agreement Expansion | Five-year contracts with purity escalation clauses displace spot procurement along US Gulf Coast. |
| REACH Registration Dossier Completion | Granular exposure scenarios for sulfone-class solvents qualify suppliers for EU green procurement preferences. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with plant managers at sulfolane production facilities, procurement leads at downstream petrochemical complexes, distribution channel partners, and technical R&D directors specializing in solvent purification; and secondary validation through customs and trade data, ACC and Cefic chemical industry reports, SEC 10-K filings from listed petrochemical operators, and EPA effluent guideline documentation. Bottom-up volume triangulation across grade tiers and end-use applications converged with top-down value estimates anchored to reported capacity utilization and pricing benchmarks.
Across the analysis window, the forecasting framework modeled segmentation dimensions including product grade tier, end-use industry classification, and regional production hub clustering. CAGRs derived from fitted growth curves applied to bottom-up demand build across petrochemical, pharmaceutical, and polymer processing applications, with shale-derived feedstock abundance and MEE emissions enforcement cycles as primary industry-specific demand drivers.
Forecasts assume regulatory continuity in EPA effluent guidelines, OSHA process safety management standards, and MEE industrial emissions protocols; material policy shifts would require re-modeling. Revision becomes warranted when butadiene price volatility crosses thresholds that trigger feedstock substitution or when pharmaceutical-grade certification timelines compress supply concentration below three qualified houses.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
E-Fluids Market
Industrial Chemicals
Volatile Organic Compounds (VOC) Concentrator Market
Industrial Chemicals
Non-PVC Waterstop Market
Industrial Chemicals
Thermic Fluids Market
Industrial Chemicals
Global Alkylated Naphthalene Market
Industrial Chemicals
Polyepoxysuccinic Acid Market
Industrial Chemicals
Explosive Chargers Market
Industrial Chemicals
Chemical Reactors Market
Industrial Chemicals
Enzymatically Hydrolyzed Carboxymethyl Cellulose Market
Industrial Chemicals
Gypsum-Free Cement Market
Industrial Chemicals
Methyl Isobutyl Carbinol Market
Industrial Chemicals
Hazardous Chemicals Packaging Market
Industrial Chemicals
Surface Treatment Chemicals Market
Industrial Chemicals
Plastic Contract Manufacturing Market
Industrial Chemicals
Global N-Methyl-2-Pyrrolidone (NMP) Market
Industrial Chemicals
Anhydrous Ammonia Storage Tank Market