
 Aminic Antioxidants Market | 2026-2036
Aminic Antioxidants Market Size, Share, and Industry Trends Forecast 2026-2036
Aminic Antioxidants Market Analysis
The capital-intensity divergence between integrated petrochemical giants and specialty chemical pure-plays is redrawing competitive boundaries in aminic antioxidants. BASF SE leverages backward integration into aniline feedstocks to control raw material costs across European production hubs. Jiangsu Sinorgchem Technology Co., Ltd. anchors its position through captive alkylated diphenylamine capacity serving Asian polymer compounders. Songwon Industrial Co., Ltd. differentiates via dedicated antioxidant technology leadership in secondary amine derivatives for lubricant applications.
Aminic antioxidants comprise nitrogen-containing organic compounds, primarily arylamines and diphenylamines, that interrupt radical chain reactions by donating hydrogen atoms to peroxy radicals, typically functioning at concentrations between 0.1% and 1.0% in stabilized matrices. These additives serve essential preservation and stabilization roles across lubricants, fuels, elastomers, and polyolefins where thermal-oxidative degradation threatens material performance and service life. Secondary aminic antioxidants occupy the dominant volume position due to their cost-performance balance in automotive lubricant formulations, while tertiary aminic antioxidants represent the fastest-expanding category driven by demand for lower-volatility stabilizers in high-temperature polymer processing. Blended product formats capture concentrated margin pools as compounders seek multi-mechanism stabilization solutions combining aminic antioxidants with phenolic co-stabilizers or phosphite synergists.
REACH registration requirements administered by ECHA mandate comprehensive toxicological dossiers for aminic antioxidant imports into Europe, directly elevating compliance costs for non-integrated suppliers. FDA food-contact regulations and EPA environmental release standards in the United States impose additional purity and migration limits that shape product specifications for domestic manufacturers. Stakeholders must monitor evolving chemical hazard classifications under EU CLP and state-level disclosure mandates in California and New Jersey to anticipate reformulation requirements and supply chain qualification barriers.
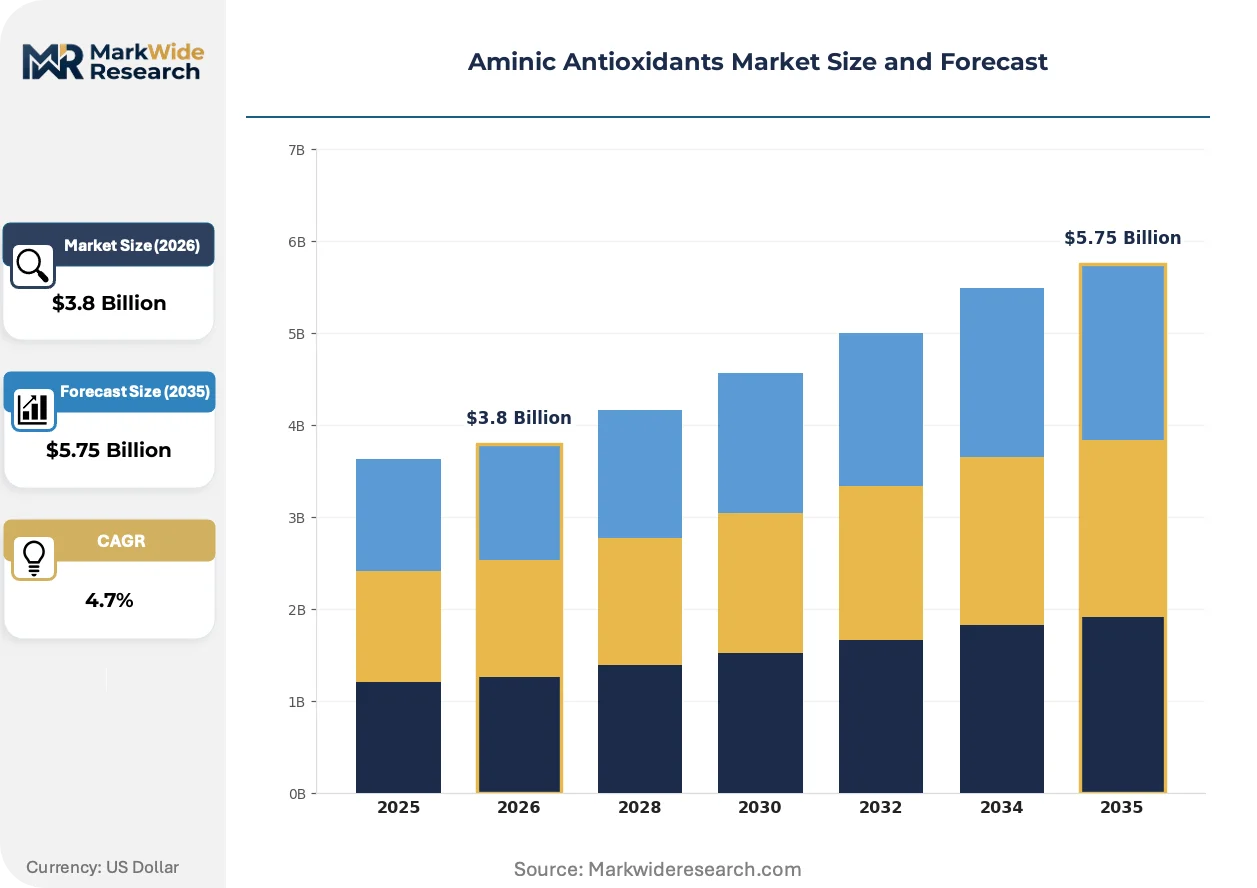
Market Dynamics
REACH compliance administered by ECHA is compressing import channels into Europe while China's petrochemical expansion redirects volume flows toward domestic additive consumption, forcing non-integrated suppliers to absorb toxicological dossier costs or exit the market entirely.
Growth Catalysts
- Polymer stabilization demand:Petrochemical expansion across China's eastern seaboard feeds captive consumption of alkylated diphenylamines in polyolefin compounding operations.
- High-temperature processing requirements:Automotive under-hood specifications are displacing conventional stabilizers with lower-volatility tertiary aminic antioxidants.
- Blended formulation preference:Lubricant compounders are specifying multi-mechanism packages combining aminic antioxidants with phenolic co-stabilizers and phosphite synergists.
Market Restraints
- Aniline feedstock volatility:Crude benzene price swings transmit directly into arylamine production economics, squeezing margin structures for non-integrated compounders.
- REACH registration burden:ECHA-mandated toxicological dossiers elevate fixed compliance costs for European import channels, disadvantaging smaller specialty chemical pure-plays.
- Phenolic antioxidant substitution:Food-contact applications in polymer packaging are migrating toward BHT and related phenolics to satisfy FDA migration limits.
Strategic Opportunities
- Secondary amine derivatives for lubricants:Formulators are specifying dedicated antioxidant technology for Group II/III base oil stabilization in extended-drain service intervals.
- EU Green Deal alignment:The European Commission's sustainable chemistry incentives are creating qualification pathways for bio-based aniline feedstock alternatives.
- Captive alkylated diphenylamine capacity:Integrated producers are monetizing backward control into feedstocks through long-term offtake arrangements with Asian polymer compounders.
Industry Challenges
- Toxicological assessment expertise:ECHA dossier preparation requires specialized regulatory affairs capabilities that concentrate in Basel and Ludwigshafen consulting clusters.
- Reactor asset specificity:Alkylation and hydrogenation units for secondary amine production demand capital commitments that strain mid-cap balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aminic Antioxidants Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Primary Aminic Antioxidants, Secondary Aminic Antioxidants, Tertiary Aminic Antioxidants, Blends End User: Food Industry, Personal Care, Pharmaceuticals, Plastics Application: Preservation, Formulation, Stabilization, Coatings Distribution Channel: Online Retail, Direct Sales, Distributors, Others |
| Companies Covered | Lubrizol Corporation, Chevron Oronite Company LLC, BASF SE, Nouryon, SI Group, Inc., LANXESS, Eastman Chemical Company, Jiangsu Sinorgchem Technology Co., Ltd., Songwon Industrial Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aminic Antioxidants Market Emerging Trajectories
Reactive stabilization chemistry is compressing additive loading levels while regulatory hazard reclassifications are forcing reformulation cycles across lubricant and polymer end-uses.
Encapsulated aminic antioxidant delivery systems are miniaturizing active ingredient domains within polymer matrices, enabling sub-percentage loadings without migration or bloom. Compounders serving automotive interior applications are adopting these systems to satisfy OEM volatile organic compound specifications. The technology is miniaturizing the effective stabilizer domain while maintaining radical scavenging efficiency, compressing per-kilogram additive economics for high-performance grades.
ECHA's evolving classification under EU CLP for certain diphenylamine derivatives is triggering downstream reformulation mandates across lubricant blending operations. The hazard communication requirements are elevating safety data sheet complexity and elevating insurance costs for European distributors. Lubricant formulators in Germany and the Netherlands are responding by accelerating qualification of alternative secondary amine structures with improved toxicological profiles.
Long-term offtake contracting is displacing spot purchasing in polymer additive procurement, compressing price volatility exposure for compounders while locking in volume commitments for integrated producers. Tier-1 automotive suppliers are driving this pattern through supplier consolidation programs that favor dual-source arrangements with annual framework agreements. The shift is most visible in China's Yangtze River Delta petrochemical corridor, where polypropylene compounders are migrating toward 12-24 month supply contracts.
Aminic Antioxidants Market Segmentation
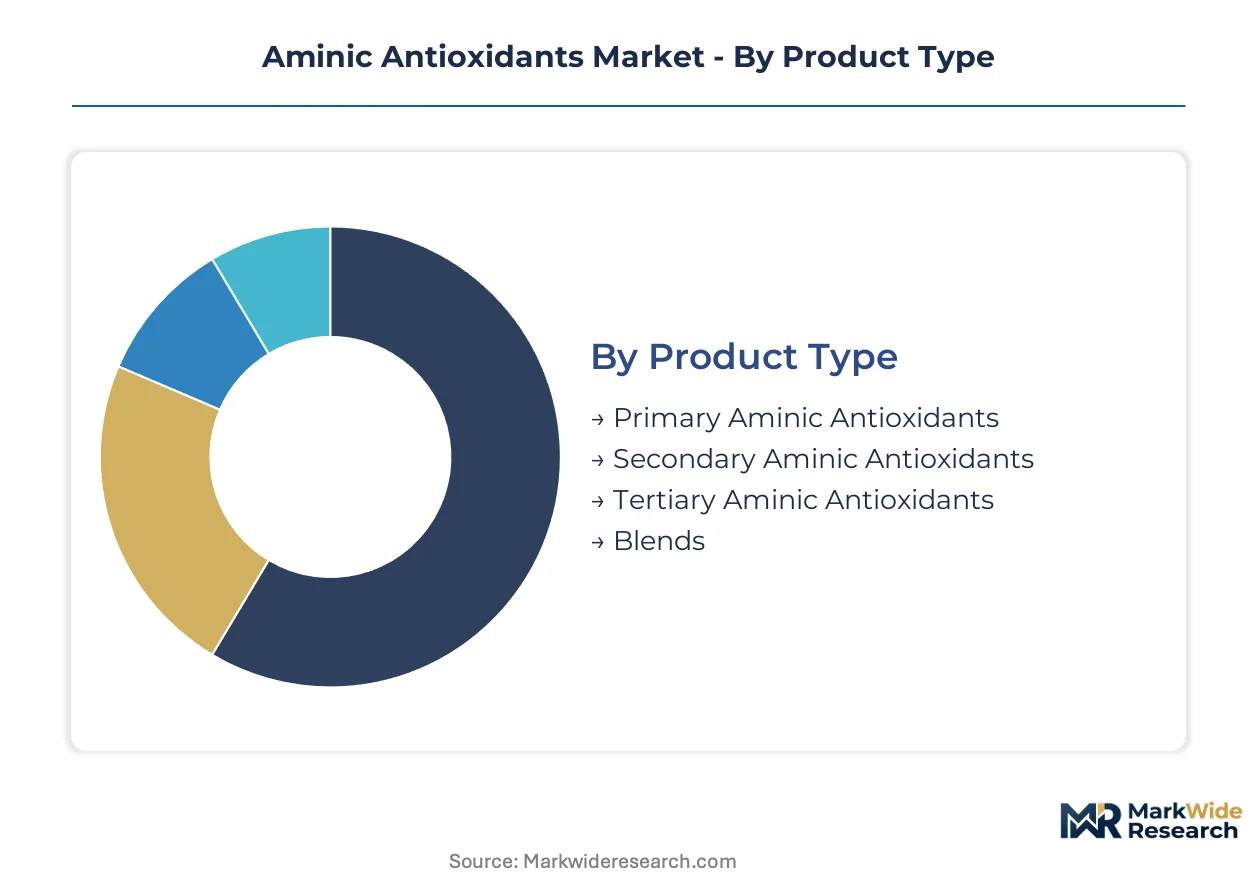
Segmentation in aminic antioxidants reveals how technical specifications and regulatory exposure fragment margin capture across nitrogen-containing stabilizer categories. Product chemistry, end-use compliance burdens, and channel economics each create distinct competitive battlegrounds for suppliers navigating REACH dossier costs and polymer compounding specifications.
Product Type:
Margin pools concentrate in tertiary structures and blended formats where formulation complexity commands premium pricing over commodity secondary amines.
- Secondary Aminic Antioxidants:These alkylated diphenylamine structures dominate volume flows through cost-performance optimization in automotive lubricant formulations. Demand concentrates in China's Yangtze River Delta petrochemical corridor where domestic polypropylene compounding absorbs captive alkylated diphenylamine output from integrated producers.
- Tertiary Aminic Antioxidants:Lower-volatility nitrogen architectures enable high-temperature polymer processing without stabilizer loss through evaporation. Momentum sits with automotive under-hood specifications in Germany and Japan where OEM thermal endurance requirements exceed conventional secondary amine capabilities.
- Primary Aminic Antioxidants:Arylamine structures with unsubstituted nitrogen positions serve specialized rubber stabilization where radical scavenging kinetics favor primary hydrogen donation.
- Blends:Multi-mechanism packages combining aminic antioxidants with phenolic co-stabilizers or phosphite synergists capture concentrated margin pools through formulation integration services.
Secondary aminic antioxidants hold the largest share; momentum sits with tertiary aminic antioxidants.
End User:
Regulatory stringency varies sharply across end-use categories, with food-contact applications imposing the steepest purity and migration limit burdens on supplier qualification.
- Plastics:Polyolefin stabilization in extrusion and injection molding operations consumes the dominant volume share of alkylated diphenylamines. China's petrochemical expansion along the eastern seaboard feeds captive additive consumption in domestic compounding operations serving automotive and packaging tiers.
- Pharmaceuticals:Nitrogen-containing stabilizers protect active pharmaceutical ingredients against oxidative degradation in parenteral formulations and biologics. FDA purity benchmarks and USP monograph compliance elevate supplier qualification barriers compared to industrial applications.
- Food Industry:Food-contact polymer packaging applications face FDA migration limits that are displacing aminic antioxidants toward phenolic alternatives like BHT in barrier film specifications.
- Personal Care:Cosmetic formulations employ aminic antioxidants in emulsion stabilization where ECHA CLP hazard classifications for certain diphenylamine derivatives are triggering reformulation mandates across European personal care compounders.
Plastics commands the dominant volume position; pharmaceuticals offers the steepest margin expansion trajectory.
Application:
Functional role determines loading level economics, with stabilization applications requiring sustained radical scavenging over service life versus preservation's shorter-acting protection.
- Stabilization:Long-term thermal-oxidative protection in lubricants and polymers demands persistent hydrogen donation capacity across extended service intervals. Automotive extended-drain specifications in Germany and the United States are specifying dedicated antioxidant technology for Group II/III base oil stabilization.
- Preservation:Short-to-medium term protection against oxidative spoilage in fuels and elastomers requires rapid radical interception without long-term persistence in the matrix.
- Formulation:Active ingredient integration into multi-component additive packages demands compatibility engineering with dispersants, detergents, and viscosity modifiers.
- Coatings:Surface protection applications in industrial and automotive finishes employ aminic antioxidants to prevent film embrittlement and color shift during cure and weathering exposure.
Stabilization anchors volume consumption; coatings is climbing the fastest on specialty formulation premiums.
Distribution Channel:
Channel economics split between technical specification intensity favoring direct engagement and geographic coverage efficiency through distributor networks.
- Direct Sales:Integrated petrochemical producers and large lubricant blenders negotiate long-term offtake arrangements with annual framework agreements. Tier-1 automotive suppliers in China's Yangtze River Delta are consolidating procurement through dual-source direct contracts spanning 12-24 month horizons.
- Distributors:Regional chemical distributors serve mid-cap polymer compounders and specialty lubricant formulators requiring technical service support and smaller lot flexibility.
- Online Retail:E-procurement platforms capture spot purchasing for standard grades where specification complexity is low and delivery speed dominates supplier selection.
- Others:Agent and broker channels persist in fragmented geographies where regulatory registration barriers limit direct supplier presence.
Direct sales holds the largest share; online retail is gaining share fastest on procurement digitization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power asymmetry between China and Germany is redrawing volume flows in aminic antioxidants. Chinese petrochemical expansion along the eastern seaboard is compressing import dependency while German REACH compliance costs elevate regional production premiums. This divergence concentrates margin capture in integrated producers with captive feedstock positions.
China
Petrochemical capacity expansion in the Yangtze River Delta and Pearl River Delta is absorbing domestic alkylated diphenylamine output for polypropylene compounding. The Ministry of Ecology and Environment enforces dual carbon goals that shape emission standards for aniline production facilities. Ningbo and Shanghai anchor polymer additive demand through integrated refinery-chemical complexes serving automotive and packaging tiers.
Germany
Automotive under-hood specifications from BMW and Mercedes-Benz are specifying lower-volatility tertiary aminic antioxidants for extended thermal endurance. ECHA REACH registration requirements mandate comprehensive toxicological dossiers that elevate fixed costs for antioxidant imports. The BASF Ludwigshafen complex and Lanxess Leverkusen operations concentrate European production of arylamine feedstocks and downstream stabilizer formulations.
United States
Group II/III base oil expansion in the Gulf Coast refining corridor is pulling dedicated antioxidant technology for extended-drain lubricant formulations. FDA food-contact regulations and EPA environmental release standards impose purity benchmarks that shape product specifications for domestic compounders. Houston and Baytown host lubricant blending operations that source aminic stabilizers through long-term offtake arrangements with integrated producers.
Japan
Automotive OEM thermal endurance requirements from Toyota and Honda are displacing conventional stabilizers with high-performance tertiary aminic structures. METI industrial standards govern chemical substance management in polymer additive applications. The Chubu region around Nagoya concentrates precision polymer compounding for automotive and electronics applications requiring sub-percentage stabilizer loadings.
South Korea
Petrochemical expansion in the Ulsan-Busan corridor is feeding captive consumption of alkylated diphenylamines for polyolefin export markets. MFDS pharmaceutical-grade standards create qualification pathways for high-purity aminic antioxidants serving parenteral formulation applications. The Daegu-Gyeongbuk region hosts specialty chemical operations producing secondary amine derivatives for regional lubricant blenders.
Aminic Antioxidants Market Vendor Landscape
Concentration sits with integrated petrochemical giants controlling backward positions into aniline feedstocks. The vendor base stratifies between European chemical conglomerates with REACH dossier capabilities and Asian producers leveraging captive alkylated diphenylamine capacity. Three archetypes dominate: backward-integrated majors, specialty additive pure-plays, and regional polymer-compounding captives. Competitive moves center on long-term offtake contracting and toxicological assessment capability accumulation.
Among integrated chemical majors, BASF SE anchors European production through Ludwigshafen-based aniline integration. Jiangsu Sinorgchem Technology Co., Ltd. exemplifies the China-based captive capacity archetype serving domestic polymer compounders. Songwon Industrial Co., Ltd. occupies a position within the Korean specialty chemical tier focused on secondary amine derivative technology. These three represent distinct geographic and structural positions rather than direct product rivalry.
| Leading Market Players |
|---|
| Lubrizol Corporation |
| Chevron Oronite Company LLC |
| BASF SE |
| Nouryon |
| SI Group, Inc. |
| LANXESS |
| Eastman Chemical Company |
| Jiangsu Sinorgchem Technology Co., Ltd. |
| Songwon Industrial Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Sixty-to-ninety-day inventory cycles for alkylated diphenylamine feedstocks concentrate pricing power with backward-integrated producers in China and Germany, while spot purchasers absorb aniline price volatility through compressed margin structures.
Pricing Analysis
Configured-to-order pricing for tertiary aminic antioxidants commands a 15-25% premium over standard secondary amine grades due to lower-volatility specifications for automotive under-hood applications. Contract-based long-term offtake arrangements dominate volume flows, with annual framework agreements locking in price bands that insulate integrated producers from benzene feedstock swings. Price differentiation hinges on REACH dossier completeness and purity certification tiers, with ECHA-registered suppliers capturing premium positioning over unregistered imports. Small specialty lubricant blenders exhibit highest price sensitivity, while Tier-1 automotive suppliers prioritize supply security over unit cost optimization.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for non-integrated European compounders sourcing alkylated diphenylamines from Chinese producers. Supply concentrates in China, Germany, and South Korea, with the Yangtze River Delta, Ludwigshafen, and Ulsan-Busan corridor hosting integrated aniline-to-antioxidant production. Raw material dependencies center on crude benzene, aniline, and hydrogenation catalysts, with feedstock volatility transmitting directly into production economics. Single-source vulnerability to REACH registration revocation poses structural risk for distributors lacking toxicological assessment capabilities. Distribution runs through direct sales channels for large polymer compounders and regional chemical distributors serving mid-cap lubricant formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion in aminic antioxidants is accelerating through China's petrochemical capacity buildout, with domestic additive consumption outpacing import dependency as the dominant volume trajectory.
For Market Incumbents: Consolidate backward integration positions into aniline feedstocks through long-term benzene supply arrangements with refinery operators, while accumulating ECHA toxicological dossier capabilities to defend European market access against emerging Asian entrants. Phenolic antioxidant substitution in food-contact applications threatens volume erosion in polymer packaging segments, requiring certification investment in FDA-compliant migration-limited formulations. For New Entrants and Emerging Players: Lead with bio-based aniline feedstock alternatives aligned to EU Green Deal incentives, targeting German automotive lubricant formulators seeking sustainable chemistry qualification pathways. The most penetrable white space sits in tertiary aminic antioxidants for high-temperature polymer processing, where lower-volatility specifications command premium pricing and incumbent capacity constraints create supply gaps. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because REACH compliance costs and reactor asset specificity are forcing mid-cap specialty chemical pure-plays toward exit, creating acquisition targets with captive customer relationships and regional registration assets. Watch ECHA hazard reclassification announcements for diphenylamine derivatives as the inflection signal triggering downstream reformulation demand and supplier consolidation mandates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aniline Feedstocks | BASF and Jiangsu Sinorgchem control raw material costs through captive alkylated diphenylamine production serving polymer compounders. |
| REACH Dossier Capability Accumulation | ECHA-mandated toxicological assessments concentrate regulatory expertise in Basel and Ludwigshafen consulting clusters, elevating barriers for non-integrated importers. |
| Long-term Supply Agreement Structuring | Twelve-to-twenty-four month offtake contracts in China's Yangtze River Delta compress price volatility for polypropylene compounders. |
| Green Manufacturing Transition | EU Green Deal alignment creates qualification pathways for bio-based aniline alternatives targeting sustainable chemistry incentives. |
| Joint Venture with Regional Distributors | Partnerships with European chemical distributors extend geographic coverage for mid-cap lubricant formulators requiring technical service support. |
Methodological Framework
A spread of perspectives from plant managers at integrated petrochemical facilities, procurement leads at downstream polymer compounders, distribution channel partners, and technical R&D directors converged on the working assumptions shaping volume and value estimates. Primary interviews with European lubricant blenders and Asian polymer additive specialists were cross-validated against customs and trade data, Cefic industry reports, SEC 10-K filings from listed chemical producers, and ECHA registration dossiers. Bottom-up demand modeling from end-use consumption patterns was reconciled with top-down supply-side capacity assessments to establish consensus range boundaries.
Segmentation dimensions modeled include product chemistry tier, end-use industry vertical, application functional role, and distribution channel structure across the projection horizon. CAGRs were derived from trend extrapolation of historical volume flows adjusted for capacity expansion announcements and regulatory impact coefficients. Forecast inputs incorporated petrochemical capacity buildout timelines in China's eastern seaboard, automotive thermal endurance specification evolution in Germany and Japan, and REACH registration cost trajectories for non-integrated suppliers.
Forecasts assume regulatory continuity in ECHA REACH administration and FDA food-contact enforcement; material policy shifts such as accelerated EU Green Deal chemistry restrictions or aniline feedstock carbon border adjustments would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Global Specialty Oils Market
Industrial Chemicals
Fabric Starch Market
Industrial Chemicals
Lignin Market
Industrial Chemicals
Industrial Phenol Market
Industrial Chemicals
Emulsifiable Metalworking Fluid Market
Industrial Chemicals
Sulphur Recovery Technologies Market
Industrial Chemicals
Ultra-High-Purity Lithium Bis(fluorosulfonyl)imide (LiFSI) Electrolyte Salt Market
Industrial Chemicals
Metal Removal Fluids Market
Industrial Chemicals
Acetylene Market
Industrial Chemicals
Molecular Sieve for Air Separation Market
Industrial Chemicals
Antiscalant Market
Industrial Chemicals
Bio Derived Enzymes for Detergents Market
Industrial Chemicals
Batch Reactors Market
Industrial Chemicals
Aerosol Sprayers Market
Industrial Chemicals
Middle-East and Africa Surface Treatment Chemicals Market
Industrial Chemicals
Alkyl Acrylate Market