
 Kraft Lignin Products Market | 2026-2036
Kraft Lignin Products Market Size, Share, and Industry Trends Forecast 2026-2036
Kraft Lignin Products Market Foresight
Specialty chemical formulators is reorganizing procurement priorities away from petroleum-derived phenols toward Kraft lignin derivatives for adhesive and resin applications. Borregaard Lignotech leverages its integrated Norwegian wood-chemical complex to sustain cost-competitive lignosulfonate and Kraft lignin output. Stora Enso anchors its biorefinery strategy through captive pulp mill access in Finland and Poland. UPM Biochemicals differentiates via its Leuna biorefinery scale and pharmaceutical-grade lignin purification capabilities.
Kraft lignin products comprise aromatic biopolymers isolated from the alkaline pulping of softwood and hardwood, typically containing 60-65% carbon, 30-35% oxygen, and variable sulfur content below 3% depending on recovery method; these macromolecules serve primarily as renewable dispersants, binders, and carbon precursors across industrial formulations. Technical lignin dominates current volume flows due to established supply from pulp mill black liquor recovery, while sodium lignin variants command premium positioning in concrete admixture and oilfield chemical applications where water solubility governs performance. Nutraceuticals represents the fastest-expanding application channel as pharmaceutical-grade purity standards unlock lignin-derived antioxidant and prebiotic ingredient demand.
EPA renewable fuel standard pathways and EU REACH authorization requirements for phenol-formaldehyde alternatives are tightening compliance thresholds for lignin-derived substitutes in construction and automotive bonding systems. ECHA substance evaluation protocols and FDA food-contact substance notifications shape product purity benchmarks and market access timelines for lignin migrating into packaging and nutraceutical end uses. Stakeholders must monitor evolving biobased content certification schemes and carbon accounting methodologies that will determine competitive eligibility for green procurement tenders.
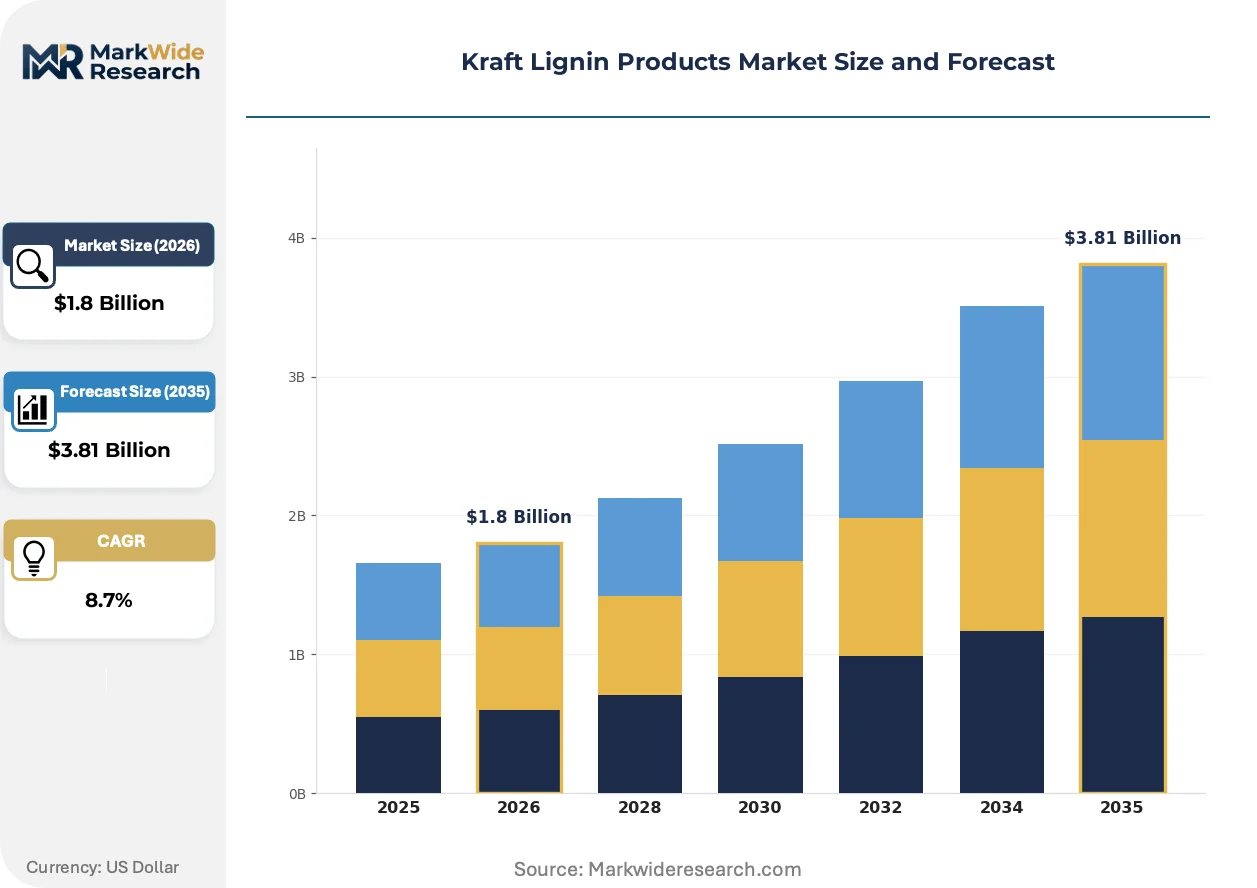
Market Dynamics
Automotive OEMs are reorganizing material procurement around bio-based carbon feedstocks as REACH compliance tightens across the European Union. This regulatory pressure is compressing formulation timelines and forcing adhesive and resin suppliers to validate lignin-derived phenol substitutes at commercial scale.
Growth Catalysts
- EU REACH Authorization:Phenol-formaldehyde restrictions under Annex XIV are forcing construction and automotive bonding systems toward lignin-derived alternatives. Formulators in Germany's Rhineland cluster are accelerating qualification protocols.
- Concrete Admixture Demand:Sodium lignin variants are displacing synthetic dispersants in high-performance concrete for infrastructure projects. Water solubility specifications in oilfield chemicals are pulling additional volume.
- Biorefinery Integration:Captive pulp mill access in Finland and Poland is anchoring regional supply security. Integrated wood-chemical complexes are compressing unit costs through black liquor recovery optimization.
Market Restraints
- Softwood Input Cost Volatility:Kraft lignin yields depend on consistent softwood pulp feedstock. Baltic and Nordic timber supply fluctuations transmit directly to black liquor availability.
- Sulfur Content Variability:Recovery method differences produce sulfur levels between 0.5% and 3%. Pharmaceutical-grade applications require costly purification to meet FDA food-contact substance notification thresholds.
- Petroleum Phenol Substitution Economics:Crude oil price swings periodically compress the cost gap between lignin derivatives and incumbent aromatic feedstocks. Buyers revert to petroleum routes during oil market troughs.
Strategic Opportunities
- Nutraceutical Ingredient Channel:Pharmaceutical-grade lignin purification is unlocking antioxidant and prebiotic applications. EFSA novel food approval pathways are creating first-mover advantages for compliant suppliers.
- Carbon Precursor Applications:Battery anode and carbon fiber feedstock specifications are converging with lignin macromolecular properties. Hard carbon yields from lignin pyrolysis are approaching synthetic pitch performance benchmarks.
- Green Procurement Tenders:EU Green Deal biobased content certification schemes are mandating renewable feedstock shares in public construction contracts. Lignin derivatives qualify for elevated scoring in German federal infrastructure bids.
Industry Challenges
- Pharmaceutical-Grade Purification Scale-Up:FDA food-contact substance notification timelines extend 18-24 months. Capital intensity for GMP-compliant lignin isolation is concentrating investment among integrated biorefinery operators.
- Formulation Compatibility Testing:Legacy phenol-formaldehyde curing protocols require extensive revalidation for lignin substitution. Adhesive compounders face technical service bottlenecks in automotive OEM qualification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kraft Lignin Products Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Technical Lignin, Sugar Lignin, Sodium Lignin, Calcium Lignin Application: Biofuels, Adhesives, Plastics, Nutraceuticals End User: Agriculture, Automotive, Construction, Pharmaceutical Distribution Channel: Direct Sales, Online Sales, Distributors, Retailers |
| Companies Covered | West Fraser, Borregaard Lignotech, Stora Enso, Rayonier Advanced Materials, Nippon Paper Industries Co., Ltd., Domtar Corporation, UPM Biochemicals, Suzano, WestRock Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kraft Lignin Products Market Shifts & Advancements
Alkaline pulping chemistry advances are fragmenting lignin macromolecules into more reactive fractions. These process intensifications are reshaping product specifications across dispersant, binder, and carbon precursor applications.
Organosolv fractionation is decomposing native lignin into lower-molecular-weight aromatic monomers and oligomers. Specialty chemical formulators in construction adhesives are adopting these fractions at pilot scale. This molecular weight reduction is decomposing the traditional technical-grade versus high-purity product boundary.
EPA renewable fuel standard pathways are tightening lifecycle carbon accounting for biorefinery coproducts. Lignin-derived materials must now document biogenic carbon content through mass balance certification. Construction and automotive segments in the US are responding by requiring third-party verification for green procurement eligibility.
Long-term offtake contracting is displacing spot purchasing in nutraceutical and pharmaceutical ingredient channels. Buyers are locking five-year supply agreements to secure pharmaceutical-grade purity tiers. This contractual shift is most visible in German and Nordic markets where EFSA novel food approval investments require volume certainty.
Kraft Lignin Products Market Segmentation
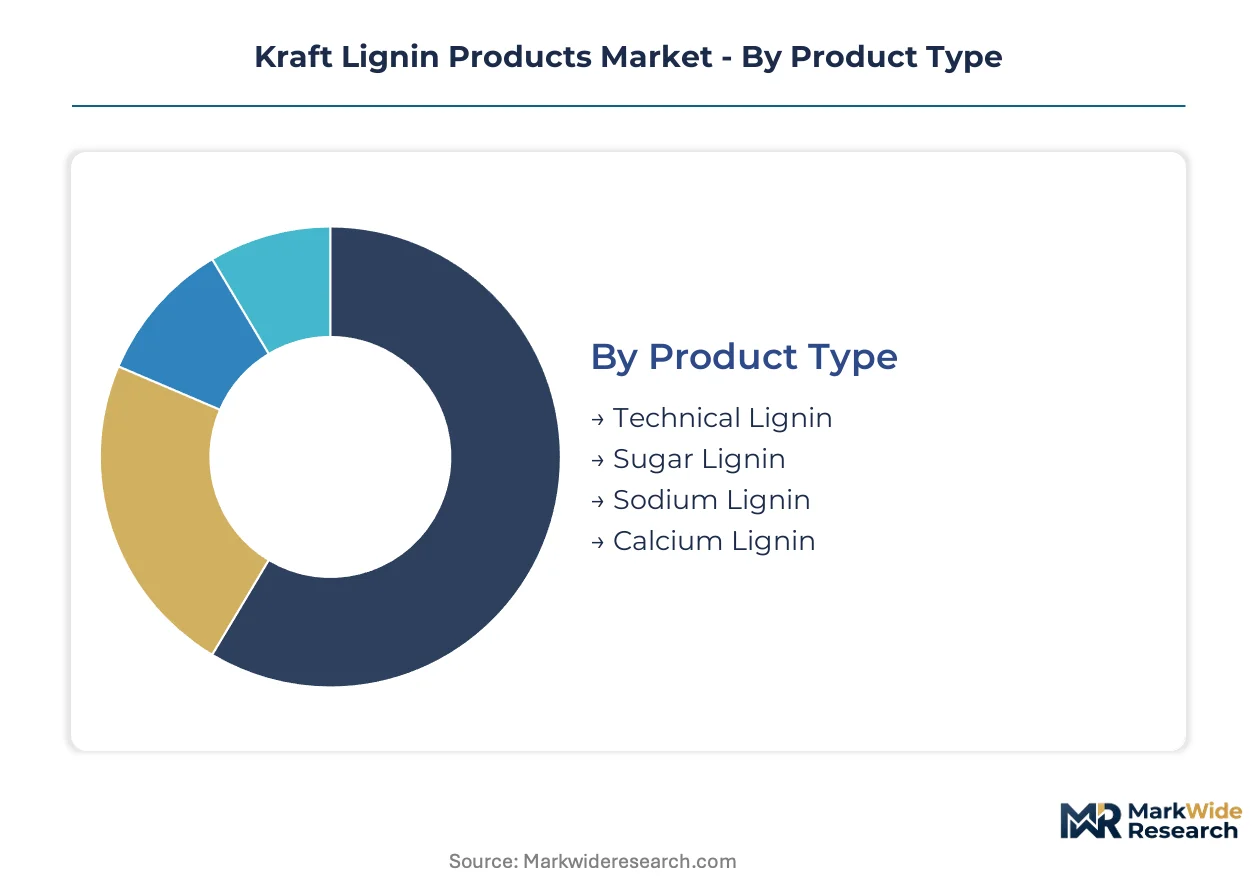
Kraft lignin product segmentation reveals distinct supply chain configurations across purity grades and end-use specifications. Each category carries different regulatory burdens, geographic demand concentrations, and margin structures that shape procurement strategies.
Product Type:
Domestic consumption dominates technical and sodium lignin flows through captive pulp mill supply chains, while sugar lignin and calcium variants serve more export-oriented specialty chemical channels.
- Technical Lignin:Recovered directly from black liquor through acid precipitation, this grade contains 60-65% carbon with sulfur content between 0.5% and 3%. Demand concentrates in Germany's Rhineland chemical cluster where construction adhesive formulators are validating REACH-compliant phenol substitutes. Softwood input cost volatility from Baltic timber markets constrains margin stability.
- Sodium Lignin:Water-soluble sulfonated derivatives command premium positioning in concrete admixture and oilfield chemical applications. Infrastructure projects across Finland and Poland are pulling volume through integrated biorefinery supply chains. ECHA substance evaluation protocols shape product purity benchmarks for construction sector eligibility.
- Sugar Lignin:Organosolv-derived fractions with lower molecular weight serve emerging carbon precursor applications. Battery anode specifications are converging with lignin macromolecular properties in pilot-scale validation.
- Calcium Lignin:Insoluble calcium salt variants anchor agricultural dispersant and soil amendment formulations. Regional demand clusters in Nordic agricultural input markets.
Technical lignin holds the largest share; momentum sits with sodium lignin variants.
Application:
Cost tier differentiation separates commodity-scale dispersant applications from pharmaceutical-grade ingredient channels requiring GMP-compliant isolation infrastructure.
- Biofuels:EPA renewable fuel standard pathways require mass balance certification for biogenic carbon content. US construction and automotive segments demand third-party verification for green procurement eligibility.
- Adhesives:Automotive OEMs in Germany are reorganizing material procurement around bio-based carbon feedstocks as REACH Annex XIV restrictions tighten on phenol-formaldehyde systems. Legacy curing protocols require extensive revalidation for lignin substitution.
- Plastics:Renewable aromatic feedstock integration into thermoset and thermoplastic formulations proceeds through compounder qualification cycles. EU Green Deal biobased content certification schemes mandate renewable shares in public contracts.
- Nutraceuticals:Pharmaceutical-grade purification unlocks antioxidant and prebiotic ingredient demand. EFSA novel food approval pathways create first-mover advantages for compliant suppliers in German and Nordic markets.
Adhesives applications anchor current volume; nutraceuticals are expanding most quickly.
End User:
Customer type fragmentation concentrates procurement power among integrated construction chemical formulators while pharmaceutical buyers lock long-term offtake agreements.
- Agriculture:Dispersant and soil amendment applications leverage calcium lignin insolubility for controlled-release fertilizer coatings. Nordic agricultural input distributors maintain regional supply relationships.
- Automotive:OEM qualification cycles for bonding systems compress formulation timelines as REACH compliance deadlines approach. Rhineland adhesive compounders face technical service bottlenecks in validation protocols.
- Construction:Concrete admixture demand for sodium lignin variants displaces synthetic dispersants in German federal infrastructure bids. Green procurement tender scoring elevates biobased content certification.
- Pharmaceutical:FDA food-contact substance notification timelines extend 18-24 months for GMP-compliant lignin isolation. Five-year supply agreements secure pharmaceutical-grade purity tiers.
Construction commands the dominant share; pharmaceutical channels show steepest expansion trajectory.
Distribution Channel:
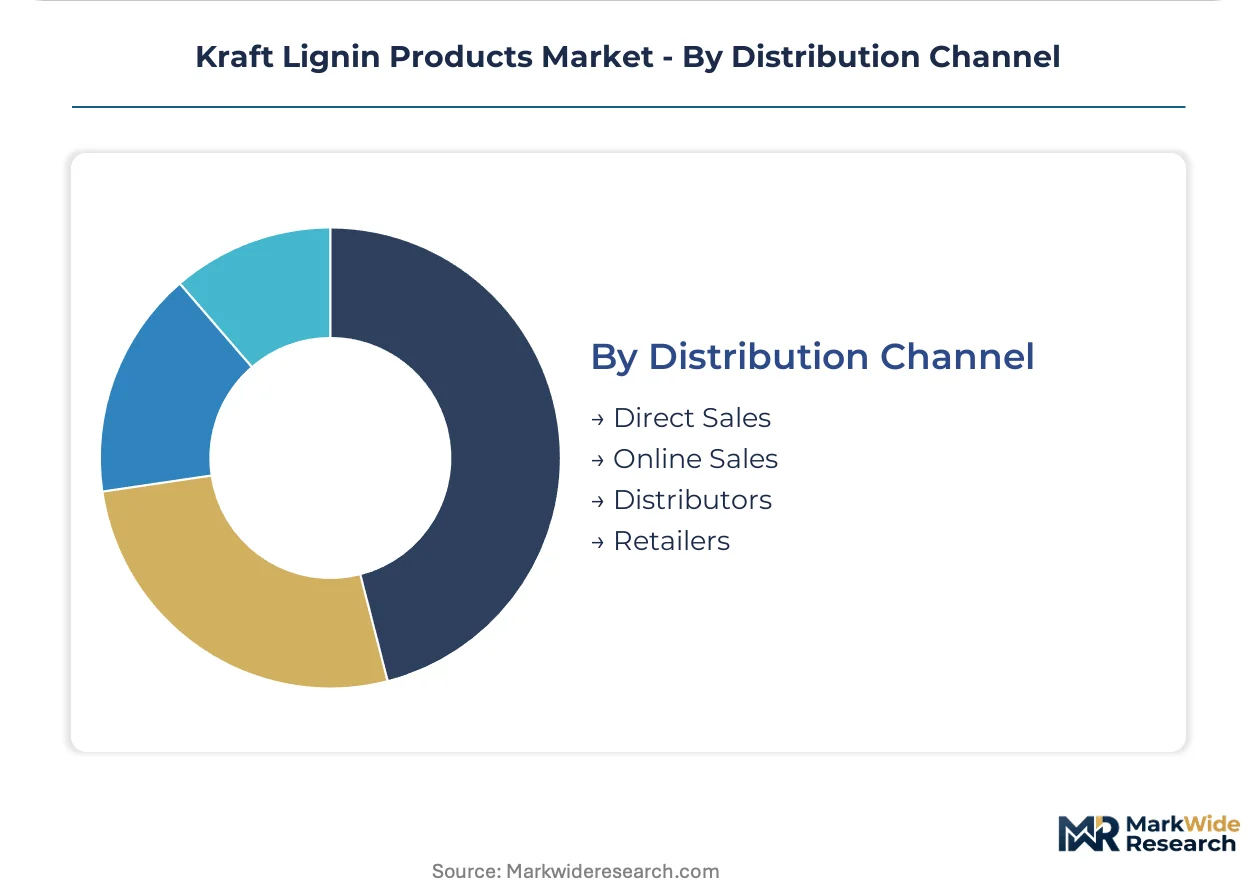
Volume scale determines channel economics with bulk chemical flows favoring direct mill relationships and specialty grades requiring technical service intermediation.
- Direct Sales:Captive pulp mill access in Finland and Poland anchors supply security for technical lignin volume buyers. Integrated wood-chemical complexes compress unit costs through black liquor recovery optimization.
- Distributors:Regional chemical distributors manage formulation compatibility testing and technical service for mid-tier adhesive and concrete admixture customers.
- Online Sales:Sample and pilot-scale volumes for research institutions and specialty compounders flow through digital procurement platforms.
- Retailers:Agricultural input retailers handle calcium lignin soil amendment products in Nordic regional markets.
Direct sales capture the largest share; distributor channels are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Leuna chemical complex in eastern Germany anchors European lignin processing infrastructure through its integrated pipeline network connecting Saxony-Anhalt biorefineries to Rhineland formulators.
Germany
Automotive OEMs in Stuttgart and Munich are accelerating REACH-compliant adhesive qualification timelines. ECHA Annex XIV restrictions on phenol-formaldehyde systems are compressing supplier validation cycles. The Rhineland chemical cluster around Leverkusen and Düsseldorf hosts the continent's densest concentration of lignin-derived resin formulators.
United States
EPA renewable fuel standard mass balance certification requirements are reshaping procurement protocols for construction and automotive segments. The agency's lifecycle carbon accounting rules now govern biogenic content claims. Integrated pulp-to-lignin facilities in the Pacific Northwest and Southeast supply volume to concrete admixture compounders.
Finland
Captive pulp mill access through Kotka and Kemi biorefineries secures cost-competitive technical lignin output for dispersant applications. EFSA novel food approval pathways for antioxidant ingredients are attracting pharmaceutical-grade investment. The Kemi-Tornio industrial corridor concentrates Nordic lignin purification capacity.
China
Dual carbon policy targets are redirecting construction chemical procurement toward biobased dispersant alternatives. NMPA and MIIT co-regulation of industrial biochemicals is standardizing purity benchmarks. Yangtze River Delta concrete admixture formulators in Jiangsu and Zhejiang are piloting sodium lignin substitution at scale.
Japan
METI biomanufacturing initiative funding is accelerating carbon precursor applications for battery anode materials. JIS standards for construction chemicals are incorporating renewable content specifications. The Chubu region around Nagoya hosts specialty chemical compounders validating lignin-derived phenol substitutes.
Kraft Lignin Products Market Competitive Landscape
Listed leaders compete with private specialists across integrated versus merchant supply models. The vendor base fragments across pulp-integrated biorefineries, standalone lignin processors, and diversified wood-chemical conglomerates. Three archetypes dominate: captive pulp mill operators, merchant specialty chemical producers, and backward-integrated construction material suppliers. Capacity expansion and strategic partnerships represent the primary competitive moves as qualification timelines compress.
Within the integrated biorefinery tier, Borregaard Lignotech and Stora Enso occupy positions defined by captive wood-chemical complex access. UPM Biochemicals exemplifies the scale-driven pharmaceutical-grade purification specialist. These three entities represent divergent strategic postures around regional supply security versus premium-tier purity positioning.
| Leading Market Players |
|---|
| West Fraser |
| Borregaard Lignotech |
| Stora Enso |
| Rayonier Advanced Materials |
| Nippon Paper Industries Co., Ltd. |
| Domtar Corporation |
| UPM Biochemicals |
| Suzano |
| WestRock Company |
| Others |
Supply & Pricing Matrix
Phenol-formaldehyde substitution by lignin derivatives in German automotive bonding systems is simultaneously compressing Rhineland supplier margins and redrawing procurement geography toward Nordic pulp-integrated sources. This dual restructuring rewards backward-integrated biorefineries with captive black liquor access while exposing merchant processors to softwood input cost volatility.
Pricing Analysis
Three-tier pricing structure across pharmaceutical-grade, technical, and commodity sodium lignin levels dominates transaction architecture. Price differentiation centers on sulfur content certification and EFSA novel food approval status, with automotive adhesive formulators least sensitive due to REACH compliance deadlines. Cost compression in technical lignin is intensifying because Baltic timber supply fluctuations transmit directly to black liquor availability. Concrete admixture compounders in infrastructure procurement show highest price elasticity, reverting to synthetic dispersants during oil market troughs.
Supply Chain Analysis
Strategic stockpiling of softwood pulp feedstock prevails over just-in-time approaches given Baltic and Nordic timber supply seasonality. Production gravity centers on Finland, Poland, and Germany, with supply chains drawing from captive pulp mill complexes, sulfuric acid precipitation recovery systems, and GMP-compliant purification infrastructure. Single-source vulnerability concentrates in pharmaceutical-grade isolation capacity where FDA food-contact notification timelines extend qualification cycles. Distribution runs through direct mill relationships for volume buyers and regional chemical distributors for mid-tier formulation customers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across purity grades and end-use specifications creates multiple niche entry points as nutraceutical and carbon precursor applications diverge from commodity dispersant channels.
For Market Incumbents: Secure captive pulp mill access in Finland and Poland to defend against merchant processor margin erosion. Lock five-year offtake agreements with pharmaceutical buyers to amortize GMP-compliant purification capital intensity. Prioritize EFSA novel food approval investments to capture antioxidant ingredient premiums before regulatory pathways congest. For New Entrants and Emerging Players: Anchor in Chinese sodium lignin concrete admixture demand where dual carbon policy targets redirect procurement toward biobased alternatives. Target Yangtze River Delta formulators in Jiangsu and Zhejiang piloting displacement of synthetic dispersants. Pursue organosolv fractionation partnerships to access lower-molecular-weight carbon precursor fractions bypassing incumbent technical-grade positioning. For Investors and Strategic Acquirers: Capital is best deployed toward integrated biorefinery operators with captive black liquor recovery and existing pharmaceutical-grade purification infrastructure. Long-term viability over the next decade hinges on regulatory compliance depth rather than commodity volume scale. Monitor ECHA substance evaluation protocol expansions as the inflection signal for accelerated phenol-formaldehyde substitution timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Softwood Pulp Supply | Captive feedstock access insulates margin stability against Baltic timber price volatility. |
| Pharmaceutical-Grade Purification Scale-Up | GMP-compliant lignin isolation unlocks nutraceutical antioxidant and prebiotic ingredient premiums. |
| Long-Term Supply Agreement with Automotive OEMs | REACH Annex XIV compliance deadlines compress qualification cycles toward committed volume relationships. |
| Organosolv Fractionation Partnership | Lower-molecular-weight aromatic monomers bypass technical-grade boundaries for carbon precursor applications. |
| EFSA Novel Food Approval Investment | First-mover regulatory positioning captures antioxidant ingredient channel expansion in German and Nordic markets. |
Research Methodology
Cross-validation between primary interviews with pulp mill operations directors, adhesive formulation chemists, pharmaceutical procurement managers, and concrete admixture technical sales leads anchors the qualitative findings. Secondary validation draws from ECHA substance evaluation protocols, EPA renewable fuel standard pathway documentation, EU Green Deal biobased certification schemes, and customs trade data for lignin derivative flows. Bottom-up segment sizing triangulates against top-down macroeconomic drivers across the analysis window.
Sensitivity analysis around softwood input cost assumptions and REACH enforcement timelines shapes the analytical framework. Segmentation dimensions modeled include purity grade tier, end-use industry cluster, and regional regulatory compliance burden. CAGRs derive from volume trajectory analysis incorporating biorefinery capacity expansion announcements and automotive OEM qualification pipeline status. Industry-specific forecast inputs encompass Baltic timber supply forecasts and EFSA novel food approval velocity indicators.
Underlying assumptions cover sustained REACH Annex XIV enforcement stringency and stable Nordic pulp mill operating rates, with deviation risk concentrated in crude oil price volatility reversing phenol substitution economics. Revision becomes warranted when pharmaceutical-grade purification capacity expansion crosses thresholds that eliminate current supply scarcity premiums.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
South America Starch Derivatives Market
Industrial Chemicals
Hydrofluoroolefin (HFO) Blowing Agent Systems for Rigid PU Foam Market
Industrial Chemicals
Industrial Explosives Market
Industrial Chemicals
Butadiene Extraction Market
Industrial Chemicals
Nitrogen Trifluoride (NF3) Market
Industrial Chemicals
Trimethylolpropane (TMP) Market
Industrial Chemicals
Defatting Systems Market
Industrial Chemicals
Global Isocyanate Market
Industrial Chemicals
Soil Hardening Agent Market
Industrial Chemicals
Vacuum Degreasers Market
Industrial Chemicals
Global Continuous Manufacturing Market
Industrial Chemicals
Global Low GWP Refrigerants Market
Industrial Chemicals
Blow Torch Market
Industrial Chemicals
Global Acid Proof Lining Market
Industrial Chemicals
Diisobutylaluminum Chloride Market
Industrial Chemicals
Europe Hydrocarbon Refrigerants Market