
 Sulfuryl Fluoride Market | 2026-2036
Sulfuryl Fluoride Market Size, Share, and Industry Trends Forecast 2026-2036
Sulfuryl Fluoride Market Analytics
Buyer concentration across North American grain elevators and commodity storage cooperatives is broadening as regional agribusiness networks consolidate procurement decisions. Syngenta AG leverages its integrated crop protection portfolio to anchor fumigant supply relationships with large-scale grain handlers. Dow Chemical Company sustains manufacturing scale through backward integration into fluorochemical feedstocks. Sumitomo Chemical Co., Ltd. competes on application technology leadership, particularly in precision-dosing equipment for sealed-structure treatments.
Sulfuryl fluoride is a colorless, odorless gas with the chemical formula SO₂F₂ and a molecular weight of 102.06 g/mol, manufactured through direct fluorination of sulfur dioxide or reaction of sulfur trioxide with potassium bifluoride; it functions primarily as a broad-spectrum fumigant that penetrates wood, commodities, and structural voids to eliminate drywood termites, powderpost beetles, and stored-product pests without leaving persistent surface residues. The gas formulation dominates commercial fumigation due to its superior penetration coefficient and rapid aeration properties compared to liquid alternatives. Pest control applications generate the deepest margin pools, while food preservation segments face tightening residue tolerance limits that constrain formulation flexibility. Direct sales channels control the largest volume flows, particularly for certified applicator networks serving agricultural end users.
EPA FIFRA registration requirements govern product labeling, application rates, and buffer zone specifications across the United States, while OSHA permissible exposure limits shape worker safety protocols during structural fumigation operations. Health Canada's PMRA conducts parallel regulatory reviews that influence cross-border product standardization for North American grain trade corridors. Stakeholders must monitor evolving phosphine resistance patterns and corresponding regulatory tolerance adjustments to anticipate substitution timing and fumigant portfolio rebalancing decisions.
Market Dynamics
Phosphine resistance mutations in stored-product insects are forcing grain elevator operators across the United States to accelerate sulfuryl fluoride adoption, restructuring fumigant procurement portfolios and tightening applicator certification requirements.
Growth Catalysts
- EPA FIFRA registration protocols:Federal buffer zone specifications and application rate standards create compliance-driven demand for certified sulfuryl fluoride formulations in structural fumigation services.
- Fluorochemical feedstock availability:Captive production of sulfur dioxide and hydrogen fluoride precursors secures supply continuity for domestic manufacturing operations.
- Grain storage infrastructure expansion:Elevated commodity warehousing capacity across the Great Plains and Corn Belt generates recurring fumigation service contracts.
Market Restraints
- Fluorine gas input volatility:Electrolytic fluorine production depends on electricity-intensive processes vulnerable to regional grid pricing fluctuations.
- Single-source concentration:Domestic manufacturing capacity clusters in Gulf Coast chemical corridors, exposing supply chains to hurricane disruption risk.
- Residual tolerance compression:FDA food additive regulations and EPA tolerance reassessments constrain post-fumigation commodity clearance timelines.
Strategic Opportunities
- Precision-dosing equipment convergence:Integration of sealed-structure sensors with automated gas distribution systems enables dose-optimization services for commodity handlers.
- California agricultural corridor:Nut and dried fruit storage facilities in the Central Valley present underpenetrated demand for alternative fumigants amid methyl bromide phase-out.
- OSHA respiratory protection mandates:Stricter permissible exposure limit enforcement drives recurring training and monitoring service attach rates.
Industry Challenges
- Certified applicator pipeline constraints:EPA-mandated training hour requirements and examination pass rates limit workforce expansion for structural fumigation crews.
- Equipment amortization cycles:Sealed-structure tenting systems and gas monitoring instrumentation demand five-to-seven-year capital recovery timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sulfuryl Fluoride Market |
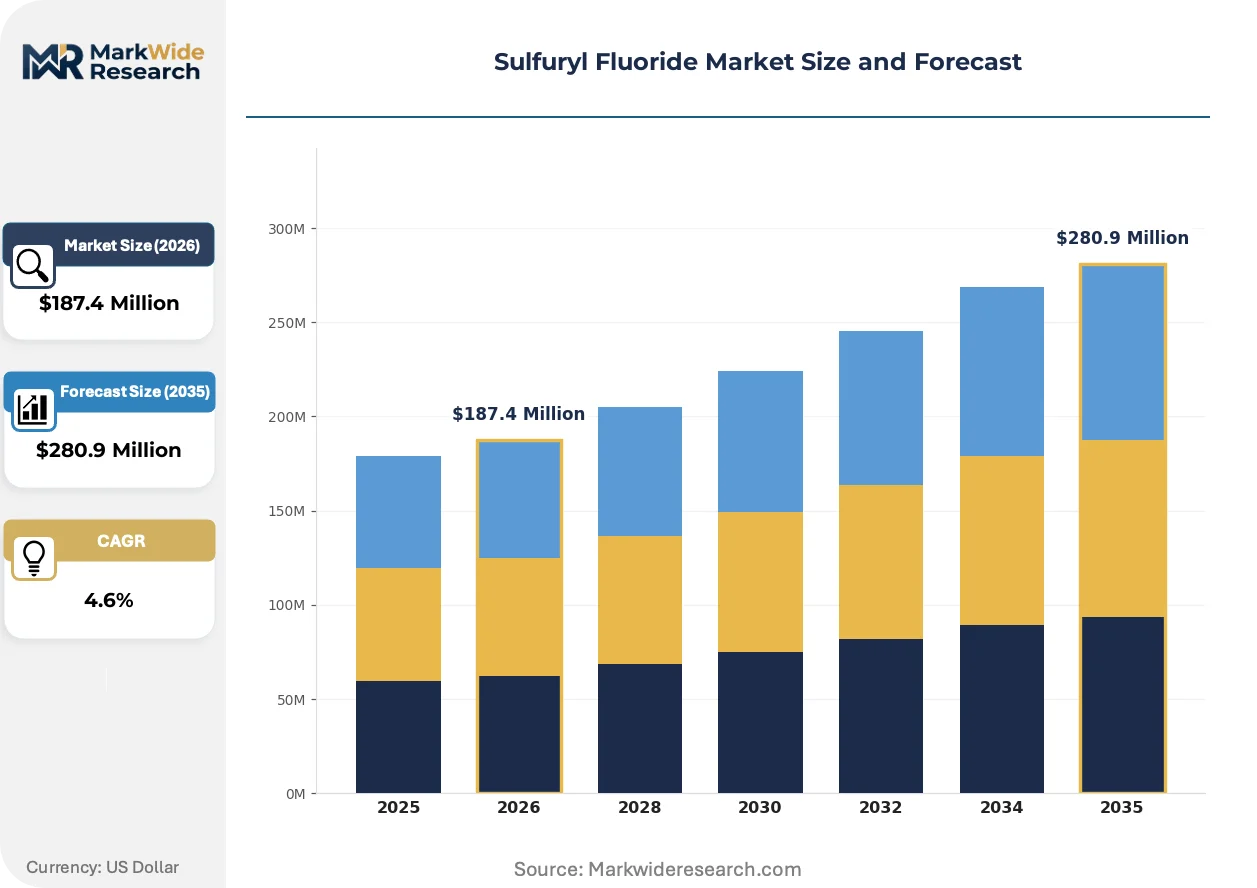
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $280.9 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Gas, Solid, Powder Application: Pest Control, Fumigation, Food Preservation, Chemical Synthesis End User: Agriculture, Residential, Commercial, Industrial Distribution Channel: Online, Retail, Direct Sales, Distributors |
| Companies Covered | Syngenta AG, Sumitomo Chemical Co., Ltd., Dow Chemical Company, Nufarm Limited, Shin-Etsu Chemical Co., Ltd., FMC Corporation, UPL Limited, Solvay, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sulfuryl Fluoride Market Evolving Landscape
Real-time gas monitoring systems are compressing fumigation cycle times while regulatory pressure on residual chemistries intensifies formulation innovation priorities across the stored-product protection sector.
Wireless sensor networks with SO₂F₂-specific electrochemical detectors are decentralizing fumigation oversight from centralized command posts to field-deployed tablets. Large-scale grain cooperatives in Nebraska and Iowa are adopting these systems at pilot scale. The technology is decentralizing quality assurance responsibility toward elevator-site managers rather than third-party applicator firms.
EPA's ongoing tolerance reassessment for fluoride residues in processed foods is tightening post-fumigation aeration requirements. The agency's 2023 draft guidance proposes extended ventilation periods for high-oil commodities. Nut processors in California and Texas are most affected, with several facilities retrofitting aeration infrastructure to meet anticipated final rules.
Commodity buyers are consolidating fumigation procurement under multi-year service agreements rather than spot treatments. Regional grain handlers in Illinois and Indiana are negotiating three-year bundled contracts covering sulfuryl fluoride, phosphine, and monitoring services. This consolidation is most visible in the Corn Belt, where elevator networks seek volume-based pricing predictability amid input cost volatility.
Sulfuryl Fluoride Market Segmentation
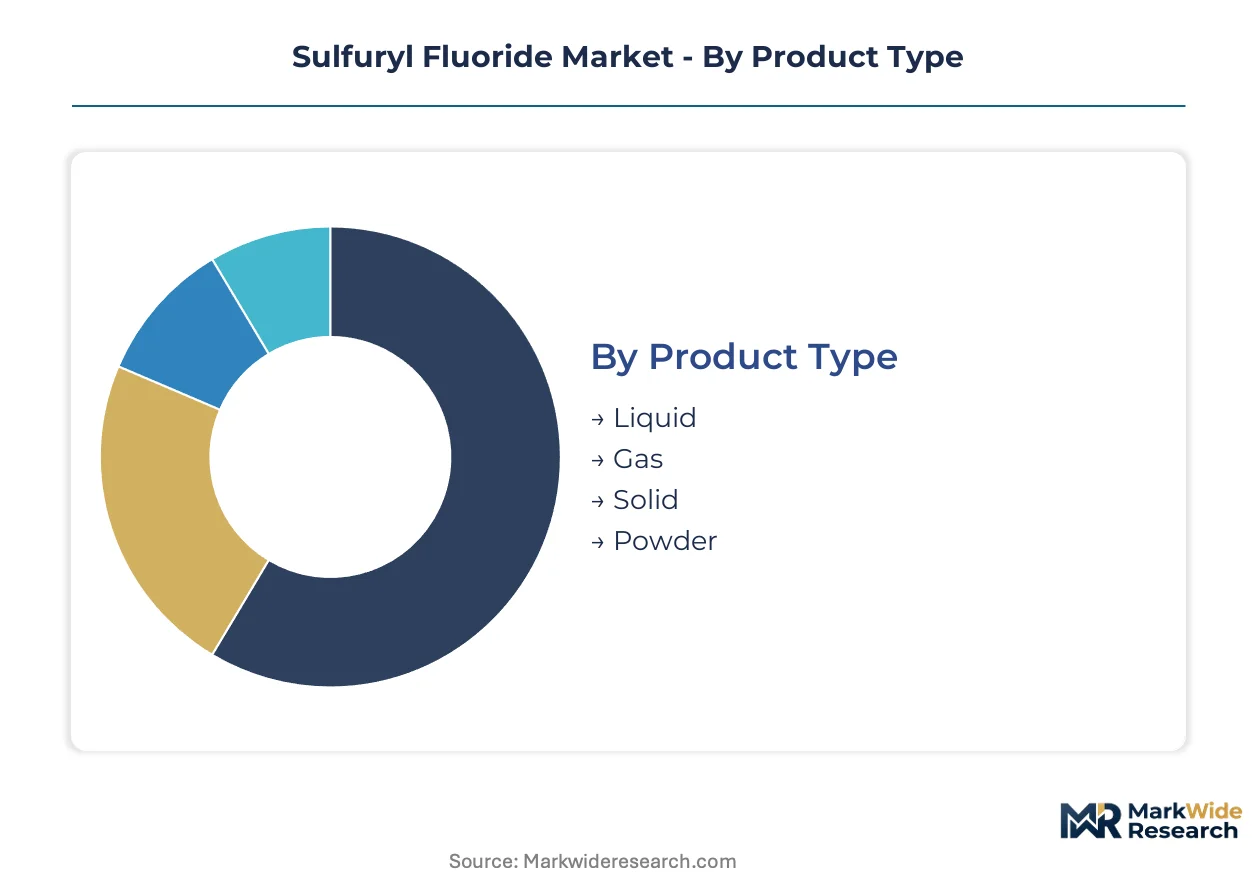
Sulfuryl fluoride procurement patterns diverge sharply across formulation states and application environments, with gas formulations commanding premium positioning in structural fumigation while liquid alternatives serve spot-treatment niches. Understanding segment boundaries clarifies where margin pools concentrate and where regulatory tolerance constraints reshape competitive positioning.
Product Type:
Upgrade cycles in fumigation equipment favor gas formulations with superior penetration coefficients, while legacy infrastructure in smaller facilities sustains demand for liquid alternatives.
- Gas:SO₂F₂ in compressed cylinder delivery dominates commercial structural fumigation due to rapid aeration properties and superior wood penetration. Grain elevators across Nebraska and Iowa specify gas formulations for sealed-structure treatments where phosphine resistance has eliminated alternative chemistries.
- Liquid:Aqueous solutions of sulfuryl fluoride serve localized spot treatments and pre-shipment quarantine applications where full tenting proves uneconomical. California nut processors deploy liquid formulations for in-transit container fumigation amid methyl bromide phase-out pressures.
- Solid:Tablet and pellet formulations enable controlled-release applications in confined storage environments with limited ventilation infrastructure.
- Powder:Micronized particulate forms support specialized blending operations with inert carriers for custom application protocols.
Gas sits at the top of the volume ranking, with liquid climbing the fastest as containerized trade corridors expand quarantine treatment requirements.
Application:
Application intensity varies directly with commodity throughput and regulatory scrutiny, with food preservation segments facing the tightest residue tolerance compression.
- Pest Control:Structural fumigation for drywood termites and powderpost beetles in residential and commercial buildings generates recurring service revenue. EPA FIFRA buffer zone specifications and OSHA permissible exposure limits shape crew certification requirements and equipment investment thresholds.
- Fumigation:Commodity treatment in grain elevators, warehouses, and shipping containers constitutes the largest volume application. Phosphine resistance mutations in stored-product insects across the Great Plains are accelerating sulfuryl fluoride substitution in elevator networks.
- Food Preservation:Post-harvest treatment of nuts, dried fruits, and spices faces tightening FDA fluoride residue limits. Extended aeration requirements proposed in EPA draft guidance are compressing treatment cycle economics for high-oil commodities.
- Chemical Synthesis:Fluorinating agent applications in pharmaceutical and agrochemical intermediate production represent a specialized industrial niche with distinct purity specifications.
Fumigation commands the deepest margin pools, with food preservation gaining share fastest as methyl bromide alternatives face regulatory pressure.
End User:
Customer scale determines procurement modality, with large agricultural networks consolidating multi-year service agreements while residential demand fragments across local pest control operators.
- Agriculture:Grain cooperatives and commodity storage facilities in the Corn Belt generate the largest concentrated demand. Regional elevator networks in Illinois and Indiana negotiate bundled three-year contracts covering fumigant supply, application services, and monitoring equipment.
- Commercial:Warehousing, logistics, and food processing facilities require recurring fumigation services tied to inventory turnover cycles. California Central Valley nut storage operations present underpenetrated demand amid structural methyl bromide phase-out.
- Residential:Single-family and multi-unit structural fumigation for termite control operates through certified applicator networks with localized service territories.
- Industrial:Manufacturing facilities with wooden infrastructure and export-oriented commodity handlers with quarantine compliance requirements.
Agriculture dominates volume concentration, with commercial expanding most quickly as third-party logistics providers assume inventory management responsibility.
Distribution Channel:
Channel selection tracks customer scale and regulatory compliance complexity, with direct relationships controlling certified applicator networks and retail channels serving fragmented residential demand.
- Direct Sales:Manufacturer-to-applicator relationships control the largest volume flows, particularly for certified fumigation crews serving agricultural end users. Syngenta AG and Dow Chemical Company anchor supply relationships with large-scale grain handlers through dedicated account management.
- Distributors:Regional chemical distributors serve mid-sized pest control operators and independent applicators with inventory stocking and technical support services.
- Retail:Limited consumer-accessible formulations for small-scale residential applications through hardware and agricultural supply stores.
- Online:Emerging procurement channel for monitoring equipment, replacement sensors, and training materials rather than bulk fumigant supply.
Direct sales maintains volume leadership, with distributors gaining traction fastest among mid-tier applicators seeking procurement flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States grain elevators generate substantially larger sulfuryl fluoride volumes than Canadian agricultural storage networks, though both markets face parallel phosphine resistance pressures. Regulatory divergence between EPA FIFRA protocols and Health Canada PMRA standards shapes cross-border formulation compliance. Industrial clusters concentrate in agricultural heartlands where commodity throughput drives recurring fumigation demand.
United States
Phosphine resistance mutations in stored-product insects across Nebraska and Iowa grain elevators are accelerating sulfuryl fluoride substitution for commodity protection. EPA FIFRA registration requirements govern buffer zone specifications and certified applicator protocols for structural fumigation operations. Corn Belt elevator networks in Illinois and Indiana negotiate multi-year bundled service contracts covering fumigant supply and monitoring equipment.
Canada
Prairie grain cooperatives in Saskatchewan and Alberta are expanding sulfuryl fluoride procurement as methyl bromide alternatives face phase-out timelines. Health Canada PMRA conducts parallel regulatory reviews that influence product standardization for North American grain trade corridors. Vancouver-area port facilities handle rising quarantine treatment volumes for containerized agricultural exports to Asian markets.
Germany
Industrial chemical synthesis applications in the Rhine-Ruhr corridor generate specialized demand for high-purity sulfuryl fluoride fluorinating agents. ECHA REACH registration requirements shape import compliance and formulation disclosure standards for fumigant products. Bavarian pharmaceutical intermediate manufacturers source SO₂F₂ for active ingredient production under strict purity specifications.
China
Grain storage infrastructure expansion in the Yangtze River Delta and North China Plain is broadening fumigant procurement across state-owned agricultural networks. MIIT industrial chemical standards and GB national standards govern manufacturing quality and application safety protocols. Shandong Province chemical clusters are scaling fluorochemical feedstock production to serve domestic sulfuryl fluoride manufacturing.
Brazil
Soybean and corn export corridors through Santos port are driving container fumigation service expansion for quarantine compliance. ANVISA pesticide registration requirements and Ministry of Agriculture phytosanitary protocols shape product formulation and application standards. São Paulo-state agricultural cooperatives are consolidating fumigation procurement under multi-year service agreements with certified applicator networks.
Sulfuryl Fluoride Market Competitive Landscape
North American producers anchor one tier; European and Asian specialists hold differentiated positions in fluorochemical feedstocks and application technology. The market structures around three strategic archetypes: integrated agrochemical conglomerates with crop protection portfolios, diversified chemical manufacturers with captive fluorine supply, and precision-equipment specialists dosing-system capabilities. Competitive moves concentrate on backward integration into sulfur dioxide and hydrogen fluoride precursors, plus strategic partnerships for sealed-structure monitoring technology.
Within the integrated agrochemical tier, Syngenta AG and Dow Chemical Company exemplify scale-driven supply relationships with large-scale grain handlers. Sumitomo Chemical Co., Ltd. occupies a distinct position emphasizing precision-dosing equipment for sealed-structure treatments. These three entities represent the dominant competitive anchors without exhaustively mapping competitive dynamics.
| Leading Market Players |
|---|
| Syngenta AG |
| Sumitomo Chemical Co., Ltd. |
| Dow Chemical Company |
| Nufarm Limited |
| Shin-Etsu Chemical Co., Ltd. |
| FMC Corporation |
| UPL Limited |
| Solvay |
| BASF SE |
| Others |
Value Network & Pricing Analysis
Grain elevator networks across the Corn Belt negotiate multi-year bundled contracts that anchor contract-based long-term offtake pricing. Volume consolidation among regional cooperatives in Illinois and Indiana compresses margin capture for applicator firms while securing supply predictability.
Pricing Analysis
Capacity additions in Shandong Province are reshaping price floors for fluorochemical feedstocks. Three-tier pricing structure across certified-applicator, distributor, and direct-procurement levels separates EPA-registered formulations from unbranded alternatives. Pricing pressure stems from phosphine substitution urgency as resistance spreads through Great Plains elevator networks. Small-scale residential pest control operators exhibit highest price sensitivity, while agricultural cooperatives prioritize service bundling over unit cost.
Supply Chain Analysis
Regional distribution centers in Houston and New Orleans operate hub-and-spoke patterns for cylinder gas delivery. Manufacturing concentrates in United States Gulf Coast corridors, China Shandong chemical clusters, and Germany Rhine-Ruhr industrial zones. Production draws from sulfur dioxide, hydrogen fluoride, and electrolytic fluorine inputs. Hurricane exposure threatens Gulf Coast capacity concentration. Distribution runs through certified applicator networks with EPA-mandated training credentials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through precision-dosing equipment attach rates and premium-tier monitoring service bundles that capture value beyond commodity fumigant supply.
For Market Incumbents: Hedge phosphine resistance-driven demand volatility by deepening backward integration into sulfur dioxide and hydrogen fluoride precursors. Secure captive fluorochemical feedstock supply against electrolytic fluorine production cost swings. Invest in sealed-structure sensor integration to defend service revenue pools from equipment commoditization. For New Entrants and Emerging Players: Enter via California Central Valley nut storage corridors where methyl bromide phase-out has created applicator capacity gaps. Target precision-dosing equipment retrofit opportunities among mid-sized grain handlers in Nebraska and Iowa. Lead with wireless gas monitoring system pilots that shift procurement decisions toward technology-enabled service providers. For Investors and Strategic Acquirers: Integrated agrochemical conglomerates with crop protection portfolios are the most active acquirer in this space. Five-to-ten year viability hinges on EPA tolerance reassessment outcomes for fluoride residues in processed foods. Monitor phosphine resistance mutation mapping across stored-product insect populations as inflection indicator for substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive sulfur dioxide and hydrogen fluoride production insulates margin from feedstock volatility. |
| Precision-Dosing Equipment Convergence | Sealed-structure sensor integration enables dose-optimization services for commodity handlers. |
| Certified Applicator Network Expansion | EPA-mandated training pipelines constrain workforce growth and create channel control value. |
| Multi-Year Service Agreement Consolidation | Bundled fumigant and monitoring contracts lock in volume predictability across Corn Belt elevators. |
| Wireless Monitoring Technology Deployment | Real-time SO₂F₂ detection systems compress fumigation cycle times and shift quality assurance responsibility. |
Research Methodology
Multiple input streams — primary interviews with fumigation applicators, grain elevator procurement managers, and fluorochemical plant engineers; secondary validation through EPA registration databases, FIFRA compliance filings, and customs trade records; plus ACC industry reports — were reconciled through bottom-up and top-down triangulation.
Historical shipment data cross-referenced against panel input from certified applicator networks established baseline parameters across the projection horizon. Segmentation modeling incorporated formulation state, application environment, end-user scale, and regional regulatory cluster dimensions. CAGRs derived from volume trajectory analysis calibrated to phosphine resistance spread patterns and grain storage infrastructure expansion timelines.
Inputs from EPA tolerance reassessment proceedings and Health Canada PMRA parallel reviews were available through the study window; gaps in proprietary phosphine resistance surveillance data introduce uncertainty bands around substitution velocity assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Disinfectants and Preservatives
Pyrethroids Market
Disinfectants and Preservatives
Preservatives Market
Disinfectants and Preservatives
Chlorine Dioxide Market
Disinfectants and Preservatives
Phenoxyethanol Preservatives Market
Disinfectants and Preservatives
Middle East and Africa Surface Disinfectants Market
Disinfectants and Preservatives
Sodium Nitrite Market
Disinfectants and Preservatives
Diquat Dibromide Market
Disinfectants and Preservatives
Disinfectant & Antimicrobial Chemicals Market
Disinfectants and Preservatives
Disinfection Cap Market
Disinfectants and Preservatives
Brazil High-Level Disinfectants and Terminal Sterilization Services Market
Disinfectants and Preservatives
Fumigant Products Market
Disinfectants and Preservatives
Surface Disinfectant Chemicals Market
Disinfectants and Preservatives
Bactericides Market
Disinfectants and Preservatives
UVC Disinfection Products Market
Disinfectants and Preservatives
Trichloroethylene Market
Disinfectants and Preservatives
Clean Label Preservatives Market