
 Commercial Electronic Detonator Market | 2026-2036
Commercial Electronic Detonator Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Electronic Detonator Market Insights
Subscription-based blast optimization software is pivoting the commercial electronic detonator value proposition from hardware sales to recurring revenue tied to fragmentation outcomes. Orica Limited leverages its BlastIQ platform to anchor digital contracts across Australian iron ore and Chilean copper operations. Dyno Nobel sustains competitive pressure through differential energy charging integrated with its electronic initiation systems. MAXAM specializes in programmable delay sequences for complex underground geometries, occupying a technical niche in European limestone and Iberian pyrite operations.
Commercial electronic detonators are precision initiation devices employing semiconductor bridges or exploding foil initiators to deliver nanosecond-accurate detonation timing, typically operating at capacitive discharge energies below five joules with programmable delay increments of one millisecond or finer. Their primary commercial purpose centers on optimizing rock fragmentation while controlling ground vibration, air overpressure, and flyrock in surface and subsurface excavation. Electric detonators retain the largest installed base across mature mining jurisdictions, though microprocessor-based programmable systems capture the fastest expansion as blast engineers demand shot-to-shot customization. Remote-controlled initiation architectures concentrate margin pools in hazardous-environment applications such as underground metalliferous mines and avalanche control corridors where personnel exclusion zones are mandatory.
The US Bureau of Alcohol, Tobacco, Firearms and Explosives regulates electronic detonator storage and transport through federal explosive licensing, while Australia's Department of Industry mandates blast vibration monitoring tied to electronic initiation records. The EU's F-Gas Regulation and REACH frameworks indirectly shape component material selection for sealed electronics in European-sourced systems. Stakeholders must monitor regulatory divergence between permissive jurisdictions and those mandating full digital blast traceability, as compliance architecture will determine which technology suppliers retain market access.
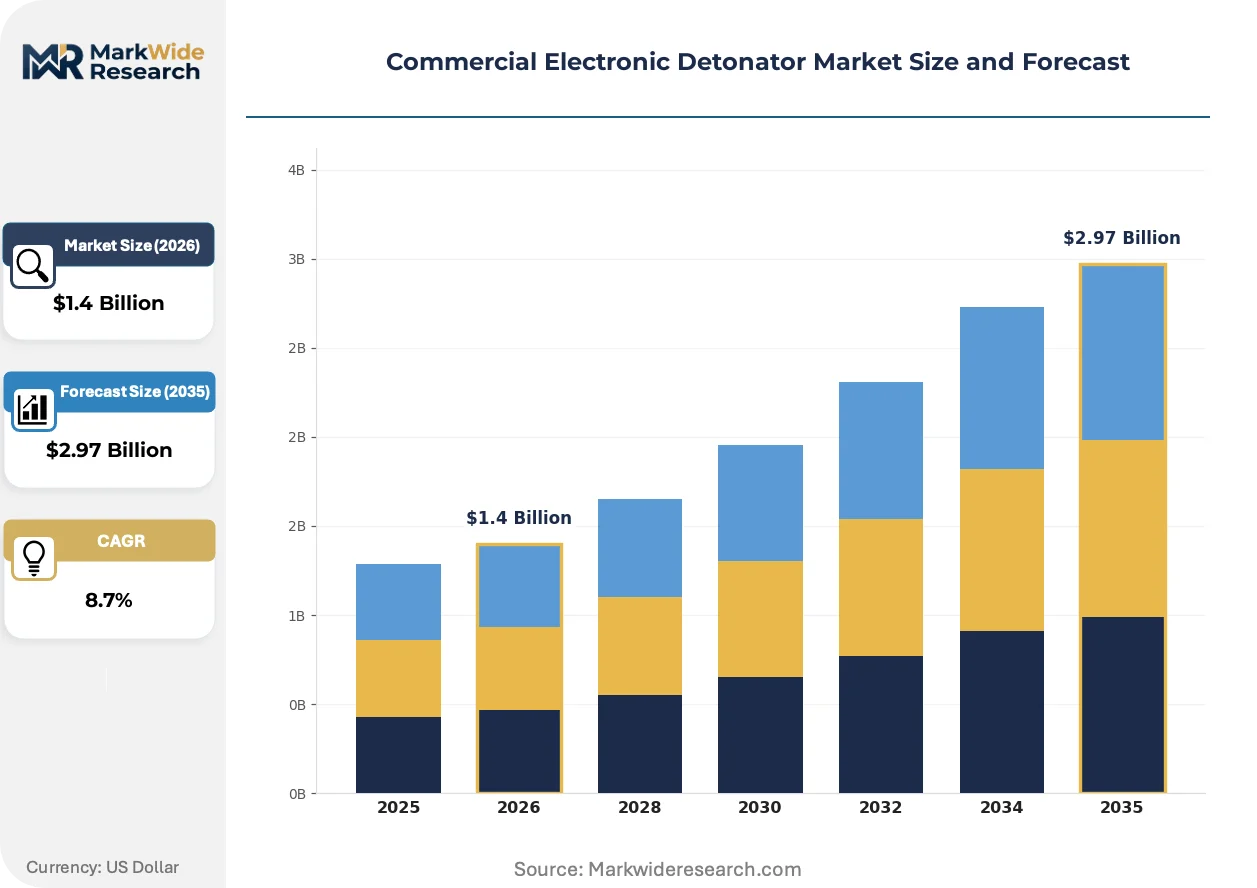
Market Dynamics
Subscription-based blast optimization software is compressing hardware margins while anchoring multi-year digital contracts to fragmentation outcomes, forcing suppliers to rebuild revenue models around recurring performance fees rather than unit sales.
Growth Catalysts
- Precision-delay mandates:Australia's Department of Industry, Science and Resources enforces blast vibration limits that disqualify legacy fuse systems from new permits in Western Australia's Pilbara iron ore belt.
- Underground metalliferous expansion:Chile's SERNAGEOMIN regulations accelerate replacement of electric detonators with programmable electronic systems in copper-rich Atacama subsurface operations.
- Semiconductor bridge miniaturization:Exploding foil initiator technology achieves nanosecond timing accuracy at capacitive discharge energies below five joules, enabling finer delay increments.
Market Restraints
- Capacitor supply concentration:High-reliability tantalum capacitors for sealed electronics concentrate among a limited supplier base in East Asian manufacturing corridors.
- Federal explosive licensing friction:The US Bureau of Alcohol, Tobacco, Firearms and Explosives imposes multi-month approval timelines for electronic detonator storage and transport permits.
- Electric detonator installed base:Mature mining jurisdictions retain substantial legacy electric initiation infrastructure with sunk capital resisting full replacement cycles.
Strategic Opportunities
- Avalanche control corridors:Remote-controlled initiation architectures address mandatory personnel exclusion zones in Alpine and Rocky Mountain hazard corridors.
- EU F-Gas Regulation alignment:REACH and F-Gas frameworks create compliance-based preference for European-sourced sealed electronic systems with verified material traceability.
- Fragmentation outcome monetization:BlastIQ-style digital platforms convert detonator sales into recurring software revenue tied to measurable rock breakage metrics.
Industry Challenges
- Blast engineer specialization gap:Microprocessor-based programmable systems require shot-to-shot customization skills scarce in mature mining workforces trained on electric initiation.
- Digital blast traceability integration:Regulatory mandates for full initiation record-keeping force retrofit of legacy fleet management systems with electronic firing data capture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Electronic Detonator Market |
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shock Tube, Electric Detonators, Non-Electric Detonators, Safety Fuse End User: Mining, Construction, Demolition, Quarrying Technology: Microprocessor-Based, Programmable, Remote-Controlled, Wireless Application: Surface Blasting, Underground Blasting, Controlled Blasting, Avalanche Control |
| Companies Covered | Orica Limited, Dyno Nobel, Austin Powder Company, MAXAM, Enaex, BME, AEL Mining Services, Hanwha Corporation, Solar Industries India Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Electronic Detonator Market Trends and Innovations
Detonator architecture is bifurcating between commodity hardware and software-defined blast control, with margin pools migrating toward data-driven fragmentation optimization and away from unit manufacturing.
Exploding foil initiator technology is modularizing precision initiation into interchangeable sub-assemblies that separate energy storage, timing logic, and firing elements. Tier-one miners in Australian iron ore and Chilean copper operations adopt these swappable configurations to reduce field inventory complexity. This modularity is compressing supplier service revenue by enabling in-house maintenance of standardized electronic modules.
REACH and the EU F-Gas Regulation are reshaping component material selection for sealed electronics in European-sourced detonator systems. Manufacturers reformulate encapsulants and conformal coatings to eliminate restricted fluorinated compounds while maintaining moisture ingress protection. Underground limestone operations in Iberian and Alpine jurisdictions face accelerated compliance timelines for replacement of legacy sealed units.
Blast optimization software unbundling is fragmenting traditional supply relationships as miners license digital platforms independently from hardware procurement. Australian Pilbara operators now contract fragmentation analytics separately from detonator supply, forcing hardware vendors to interoperate with third-party optimization tools. This pattern concentrates most visibly in Western Australian iron ore where tier-one miners possess internal blast engineering capabilities.
Commercial Electronic Detonator Market Segmentation
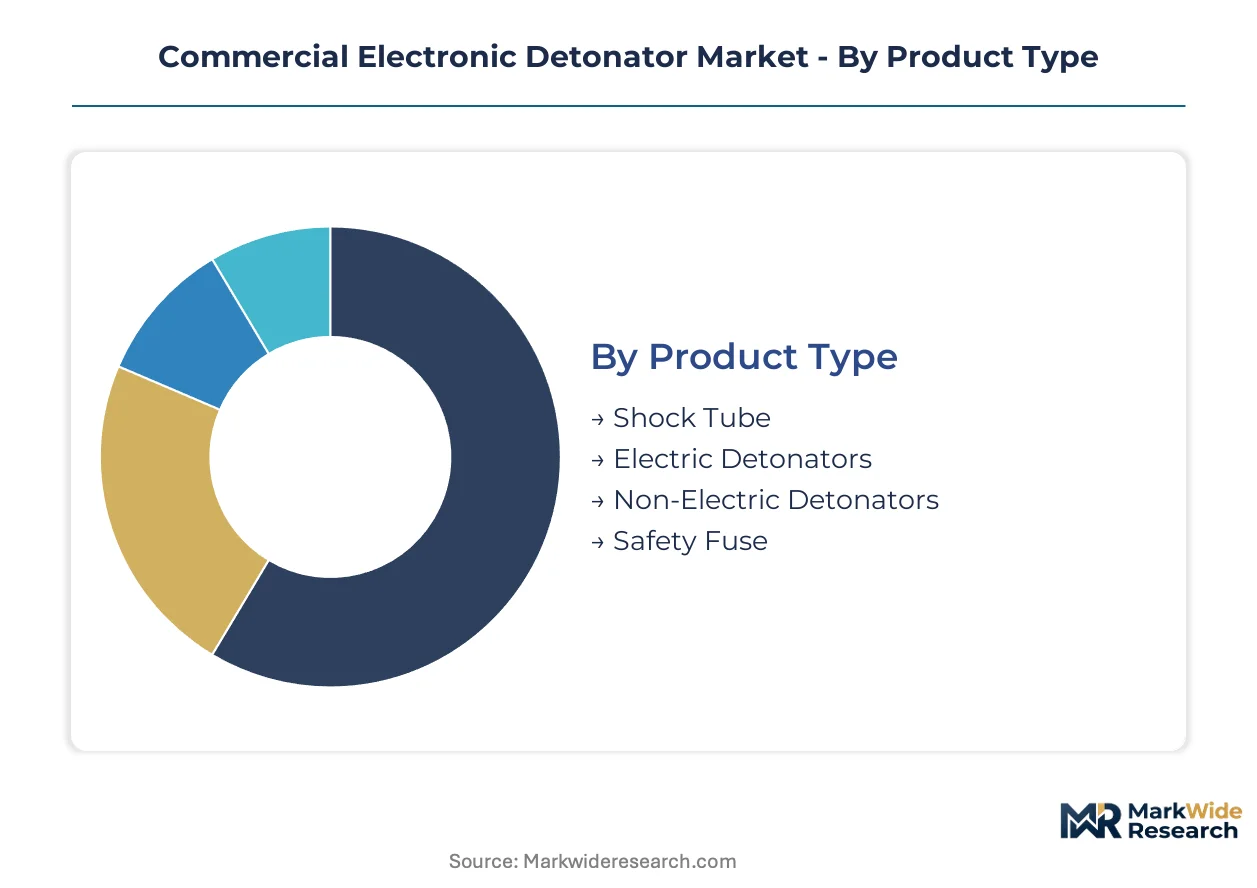
Electronic detonator segmentation reveals how procurement priorities diverge between precision-dependent metalliferous mining and cost-sensitive quarrying operations. Buyers sort across technology tiers, application environments, and regulatory exposure, with each axis commanding distinct supplier relationships and margin structures.
Product Type:
Cost tolerance and blast complexity separate procurement patterns across initiation hardware categories.
- Electric Detonators:Legacy copper-wire initiation systems deliver millisecond-accurate firing through direct current discharge. Mining operations in Australia's Pilbara iron ore belt and Chile's Atacama copper belt retain substantial installed base, though Australia's Department of Industry vibration limits now disqualify these systems from new permit applications in surface operations.
- Non-Electric Detonators:Shock tube and detonating cord systems eliminate electromagnetic interference risks in radio-dense environments. Underground metalliferous operations in Iberian pyrite and Alpine limestone jurisdictions favor these for personnel safety in confined geometries where stray currents threaten premature initiation.
- Shock Tube:Plastic-lined tubing transmits low-velocity detonation signals without electrical components, reducing component cost for quarrying and construction demolition.
- Safety Fuse:Black powder-cored textile tubing persists in remote construction corridors and developing mining jurisdictions with minimal regulatory enforcement.
Volume sits with Electric Detonators; growth tilts toward Non-Electric Detonators.
End User:
Regulatory stringency and fragmentation economics drive technology selection across buyer verticals.
- Mining:Tier-one copper and iron ore operators demand nanosecond timing accuracy for wall stability and ore recovery optimization. Australia's Department of Industry, Science and Resources mandates blast vibration monitoring tied to electronic initiation records, forcing programmable system adoption across Western Australian surface operations.
- Demolition:Urban decommissioning projects require precise delay sequencing to control flyrock and structural collapse patterns. Remote-controlled initiation architectures address mandatory personnel exclusion zones in dense European and North American metropolitan environments.
- Construction:Road cutting and foundation excavation prioritize unit cost over precision, sustaining demand for shock tube and electric initiation in developing infrastructure corridors.
- Quarrying:Aggregate producers balance fragmentation quality against blasting economics, with European limestone operations facing accelerated compliance timelines under REACH and F-Gas Regulation for sealed electronic replacement.
Revenue concentrates in Mining; Demolition climbs fastest on urban densification and safety mandates.
Technology:
Capability depth and integration requirements fragment supplier value propositions across intelligence tiers.
- Microprocessor-Based:Embedded timing logic enables programmable delay increments of one millisecond or finer through semiconductor bridge architecture. Chile's SERNAGEOMIN regulations accelerate replacement of electric detonators with these systems in copper-rich Atacama subsurface operations.
- Programmable:Shot-to-shot customization software allows blast engineers to optimize fragmentation patterns and vibration signatures. Subscription-based platforms like BlastIQ convert hardware sales into recurring revenue tied to measurable rock breakage metrics in Australian iron ore.
- Remote-Controlled:Personnel exclusion zone compliance drives adoption in hazardous underground metalliferous mines and avalanche control corridors where electromagnetic isolation is mandatory.
- Wireless:Radio-frequency initiation eliminates physical connections, reducing setup labor in complex blast geometries though spectrum licensing constraints limit deployment in regulated jurisdictions.
Installed base favors Microprocessor-Based; Programmable gains share fastest on outcome-based contracting.
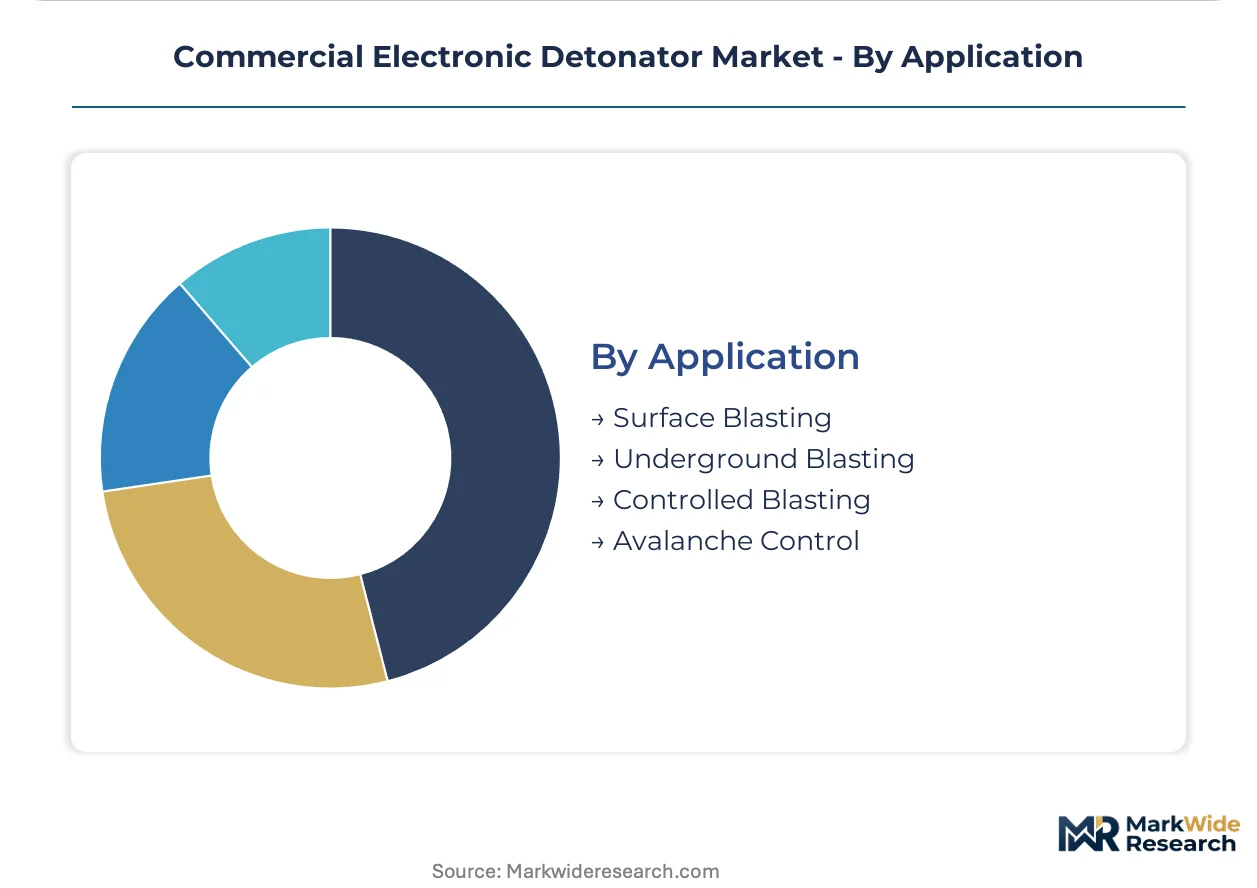
Application:
Environmental exposure and regulatory visibility shape initiation system specification.
- Surface Blasting:Open-pit iron ore and copper operations face stringent vibration monitoring tied to community proximity. Australia's Pilbara belt enforces blast limits that mandate electronic initiation with digital traceability.
- Underground Blasting:Confined metalliferous environments prioritize personnel safety and wall stability. Chile's SERNAGEOMIN mandates programmable electronic systems for new copper mine approvals.
- Controlled Blasting:Precision fragmentation for ore processing and construction aggregate demands delay accuracy unavailable in legacy fuse systems.
- Avalanche Control:Alpine and Rocky Mountain hazard corridors require remote initiation with weather-sealed electronics and mandatory personnel exclusion compliance.
Activity concentrates in Surface Blasting; Avalanche Control expands most quickly on climate adaptation infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters in East Asian manufacturing corridors while consumption concentrates in resource-rich mining jurisdictions. Australia and Chile import programmable electronic systems for precision blasting in iron ore and copper extraction. The United States maintains dual demand from surface mining and demolition sectors.
Australia
Western Australia's Pilbara iron ore belt drives procurement of nanosecond-accurate initiation systems as tier-one miners replace legacy fuse infrastructure. The Department of Industry, Science and Resources enforces blast vibration limits that disqualify electric detonators from new surface permits. Perth-based engineering teams coordinate fleet-wide adoption of digital traceability platforms across the Pilbara cluster.
Chile
Copper-rich Atacama subsurface operations accelerate replacement of electric detonators with programmable electronic systems for wall stability control. SERNAGEOMIN mandates electronic initiation for new underground metalliferous mine approvals. Santiago-headquartered procurement divisions standardize delay programming protocols across the northern mining corridor.
United States
Surface coal and aggregate operations sustain demand alongside urban demolition projects requiring remote-controlled initiation. The Bureau of Alcohol, Tobacco, Firearms and Explosives imposes multi-month approval timelines for storage and transport permits. Appalachian mining districts and Rocky Mountain avalanche control corridors represent distinct application clusters.
China
Domestic manufacturing capacity supplies programmable electronic detonators for coal mining and infrastructure excavation. National standards authorities regulate component material selection for sealed electronics in hazardous environments. Shanxi Province coal basins and Yangtze River Delta construction corridors anchor internal consumption.
Germany
Underground limestone operations in Bavaria and Baden-Württemberg face accelerated compliance timelines under REACH and F-Gas Regulation for sealed electronic replacement. ECHA frameworks reshape encapsulant formulations for moisture ingress protection. Alpine avalanche control installations in Bavaria deploy remote initiation with mandatory personnel exclusion compliance.
Commercial Electronic Detonator Market Competitive Landscape
Capital-heavy producers compete with asset-light designers as the market structure consolidates around integrated blasting service providers. Tier-one miners favor suppliers bundling hardware with software-defined optimization platforms. Three archetypes dominate: diversified explosives conglomerates with digital platforms, specialized initiation technology developers, and regional blasting service contractors. Competitive moves center on outcome-based contracting structures and interoperability agreements with third-party fragmentation analytics.
Among diversified explosives conglomerates, Orica Limited and Dyno Nobel occupy positions exemplifying the integrated service model. MAXAM represents the specialized initiation technology archetype with programmable delay expertise. These three anchors illustrate how revenue models pivot from unit sales toward recurring performance fees tied to measurable rock breakage outcomes.
| Leading Market Players |
|---|
| Orica Limited |
| Dyno Nobel |
| Austin Powder Company |
| MAXAM |
| Enaex |
| BME |
| AEL Mining Services |
| Hanwha Corporation |
| Solar Industries India Limited |
| Others |
Pricing and Supply Chain Analysis
Backward integration into semiconductor bridge manufacturing anchors pricing power for tier-one suppliers while compressing margins for hardware-only vendors. Orica Limited and Dyno Nobel leverage captive production of exploding foil initiators to defend premium positioning in Australian iron ore and Chilean copper contracts, whereas smaller competitors absorb volatility in East Asian tantalum capacitor spot markets.
Pricing Analysis
Margin tightening in programmable electronic systems reflects software unbundling as miners license BlastIQ-style platforms separately from detonator procurement. Three-tier pricing structure across premium, standard, and economy levels separates outcome-based digital contracts from transactional hardware sales and legacy electric detonator replacements. Certification tier under Australia's Department of Industry digital traceability mandates commands price premiums, while quarrying operations in developing jurisdictions remain most price-sensitive. Cost compression in commodity shock tube segments intensifies because construction contractors prioritize unit economics over nanosecond precision.
Supply Chain Analysis
High-reliability tantalum capacitor supply rests on Japanese and South Korean specialty component manufacturers with limited qualified alternatives. Semiconductor bridge architecture draws from Taiwan semiconductor foundries and German precision engineering clusters for exploding foil initiator sub-assemblies. Single-source vulnerability concentrates in moisture-sealed encapsulant formulations governed by REACH and F-Gas Regulation compliance timelines. Distribution runs through integrated blasting service providers who bundle hardware, software, and field engineering across Pilbara iron ore and Atacama copper corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The commercial electronic detonator market is a vertical-integration race where upstream control over semiconductor bridge manufacturing and downstream capture of fragmentation analytics determine margin sustainability.
For Market Incumbents: Anticipate software unbundling by accelerating interoperability agreements with third-party blast optimization platforms before miners complete independent procurement splits. Lock in multi-year digital contracts across Australian Department of Industry-mandated vibration compliance programs to preempt hardware commoditization. Reinforce captive supply of exploding foil initiator components to maintain cost advantage over module-assemblers. For New Entrants and Emerging Players: Begin with avalanche control corridors in Alpine and Rocky Mountain jurisdictions where remote-controlled initiation mandates create personnel exclusion zone requirements that favor specialized entrants over diversified conglomerates. Target Iberian and Bavarian underground limestone operations facing accelerated REACH replacement timelines for legacy sealed electronics. Lead with modular sub-assembly designs that enable in-house maintenance and reduce field inventory complexity for cost-conscious quarry operators. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified explosives conglomerates seeking programmable delay expertise and digital platform capabilities. Long-term viability hinges on recurring revenue share from outcome-based fragmentation contracts rather than transactional hardware multiples. Watch the pace of Australia's Department of Industry permit enforcement as the signal indicating when vibration mandate coverage reaches critical mass for software-defined market tipping.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Semiconductor Bridges | Captive production of exploding foil initiators insulates margin from East Asian capacitor volatility. |
| Digital Platform Interoperability | Third-party software agreements retain miner relationships as procurement unbundles across Pilbara operations. |
| REACH-Compliant Encapsulant Reformulation | ECHA-aligned material traceability secures access to European underground limestone and quarry markets. |
| Remote-Controlled Initiation Certification | Alpine and Rocky Mountain avalanche corridor compliance creates defensible niche in hazardous-environment applications. |
| Fragmentation Outcome Monetization | Subscription revenue tied to measurable rock breakage metrics converts hardware vendors into recurring service providers. |
Research Methodology
Document review covered SERNAGEOMIN regulatory filings, Australia's Department of Industry blast vibration monitoring guidelines, and EU REACH substance restriction databases, complemented by interviews with mine blasting engineers, procurement directors at tier-one copper and iron ore operators, electronic detonator R&D leads, and blasting service contractor field supervisors. Secondary validation drew from customs trade data for tantalum capacitor imports, SEC 10-K explosives segment disclosures, and mining equipment procurement databases. Bottom-up unit shipment estimates across programmable, microprocessor-based, and legacy electric categories were triangulated against top-down market value reconstruction.
Installed base and replacement cycle modeling produced volume and value trajectories across the projection horizon by technology tier, end-use vertical, and regional regulatory cluster. Segmentation dimensions included initiation system architecture, application environment surface versus underground, and compliance intensity under national mining safety frameworks. CAGRs were derived from fitted growth curves incorporating semiconductor bridge miniaturization adoption rates and digital platform penetration assumptions. Industry-specific inputs captured SERNAGEOMIN underground metalliferous approval timelines and Australia's Department of Industry permit disqualification thresholds for legacy fuse systems.
Underlying measurement precision varies by segment; programmable electronic system forecasts carry tighter precision than legacy electric detonator replacement projections due to more visible procurement pipelines. Forecasts reflect assumptions about regulatory enforcement continuity and capacitor supply chain stability that Australia's Department of Industry mandate expansion or East Asian component export restrictions could revise. A small set of triggers—SERNAGEOMIN rulemaking acceleration, REACH substance ban additions, and tier-one miner software procurement unbundling announcements—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Carbamate Insecticides Market
Industrial Chemicals
Global Antifreeze Market
Industrial Chemicals
Global Continuous Manufacturing Market
Industrial Chemicals
Volatile Organic Compounds (VOC) Concentrator Market
Industrial Chemicals
Aluminium Production Chemicals Market
Industrial Chemicals
Backing Material Market
Industrial Chemicals
Pesticide Inert Ingredients Market
Industrial Chemicals
Global Sponge Applicator Market
Industrial Chemicals
Pyrethrin Market
Industrial Chemicals
Nonylphenol Ethoxylate Market
Industrial Chemicals
Hydrofluoroolefin (HFO) Blowing Agent Systems for Rigid PU Foam Market
Industrial Chemicals
1-Octanol Market
Industrial Chemicals
Fireworks and Firecrackers Market
Industrial Chemicals
Thermic Fluids Market
Industrial Chemicals
E-Fluids Market
Industrial Chemicals
Tall Oil Fatty Acid Market