
 Global Ethylene Carbonate Market | 2026-2036
Global Ethylene Carbonate Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ethylene Carbonate Market Foresight
The EU Green Deal is shifting procurement criteria for electrolyte solvents across European cell plants. Mitsubishi Chemical Group Corporation leverages captive epichlorohydrin feedstock to sustain integrated ethylene carbonate output in Japan. TOAGOSEI CO., LTD. anchors high-purity production for domestic battery makers. BASF SE competes through specialized pharmaceutical-grade streams alongside industrial volumes.
Ethylene carbonate is a cyclic carbonate ester with molecular formula C₃H₄O₃, produced via ethylene oxide carbonation using carbon dioxide under catalytic conditions, functioning primarily as a high-dielectric-constant solvent and electrolyte additive. Battery-grade material commands premium positioning as cathode-active-material producers enforce sub-10 ppm chloride specifications. Solvent manufacturing applications retain volume leadership in industrial-grade channels. Pharmaceutical-grade segments occupy narrower but defensible margin pools tied to FDA and EMA excipient certifications.
REACH registration in the European Union, China's GB/T standards for lithium-ion battery electrolytes, and EPA toxic substance reporting in the United States collectively elevate compliance costs for non-integrated producers. Battery OEMs now require full material pedigree documentation from carbonate suppliers. Stakeholders must monitor regulatory divergence between jurisdictions as carbonation process emissions face tightening scrutiny.
Market Dynamics
Battery-grade ethylene carbonate purity specifications are tightening faster than process technology can adapt, forcing solvent producers to reconfigure carbonation catalyst systems and chloride removal stages ahead of regulatory deadlines in multiple jurisdictions.
Growth Catalysts
- Lithium-ion electrolyte demand:Cell manufacturers in China, South Korea, and Germany are scaling solvent procurement to match cathode-active-material expansion, pulling high-purity carbonate volumes into dedicated supply agreements.
- EU Green Deal procurement criteria:European cell plants must now document carbon footprint and circularity metrics for electrolyte inputs, redirecting contracts toward producers with verified low-emission carbonation processes.
- REACH registration completion:Full dossier compliance for ethylene carbonate in the European Union has cleared market access for registered suppliers while creating barriers for unregistered imports.
Market Restraints
- Epichlorohydrin feedstock volatility:Integrated producers with captive ethylene oxide supply hold structural cost advantages over merchant-market dependent competitors, compressing margins during feedstock price spikes.
- Chloride specification compression:Sub-10 ppm chloride requirements for battery-grade material demand capital-intensive purification retrofits that smaller carbonation operators cannot finance.
- Propylene carbonate substitution:Lower-viscosity cyclic carbonate alternatives are gaining formulation share in certain electrolyte blends, particularly where low-temperature performance takes priority over dielectric constant.
Strategic Opportunities
- Indian cell manufacturing buildout:PLI scheme incentives for domestic battery production are creating first-mover positioning for carbonate suppliers establishing local blending and distribution infrastructure.
- Solid-state electrolyte precursor applications:Polymer-ceramic composite electrolyte developers are evaluating ethylene carbonate derivatives as plasticizers and interface modifiers in next-generation cell architectures.
- Pharmaceutical-grade channel expansion:FDA and EMA excipient certifications open defensible margin pools in controlled-release drug formulations, with pricing power decoupled from industrial-grade commodity cycles.
Industry Challenges
- Analytical chemistry talent scarcity:Battery-grade certification requires specialized chromatography and ion chromatography expertise that carbonation plants historically did not staff, forcing competitive recruitment against pharmaceutical laboratories.
- Dual carbonation-purification capex cycles:Simultaneous reactor upgrades and chloride removal system installations are straining balance sheets, particularly for mid-scale producers without parent-company financing access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ethylene Carbonate Market |
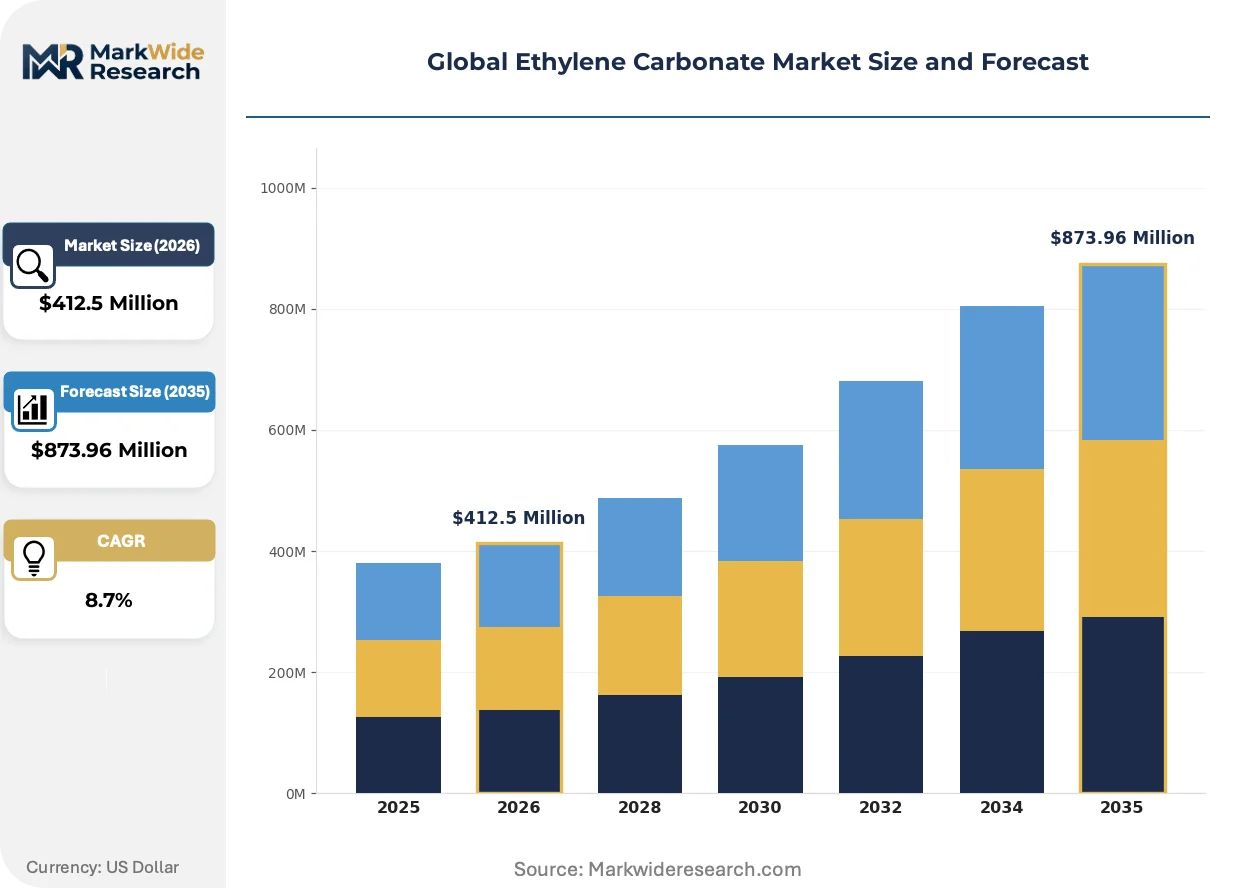
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $873.96 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Battery Grade, Industrial Grade, Electronic Grade, Pharmaceutical Grade, Agricultural Grade Application: Lithium-ion Batteries, Solvent Manufacturing, Coatings, Agrochemicals, Pharmaceuticals End Use Industry: Consumer Electronics, Chemical Manufacturing, Crop Protection, Drug Formulation, Automotive OEMs Packaging Type: Drums, Bulk Containers, Intermediate Bulk Containers, Jerricans, Totes |
| Companies Covered | TOAGOSEI CO., LTD., Shinghwa Advanced Material Group Co., Ltd., Mitsubishi Chemical Group Corporation, Empower Materials, Zibo Donghai Industries Co., Ltd, Huntsman International LLC, Oriental Union Chemical Corporation, FUJIFILM Wako Pure Chemical Corporation, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ethylene Carbonate Market Shifts & Advancements
Process intensification and regulatory data architecture are reshaping competitive advantage in ethylene carbonate production, separating producers with integrated digital compliance systems from those managing certification through manual documentation workflows.
Membrane-based chloride removal is overtaking traditional crystallization and distillation sequences in new carbonation plant designs. Korean and Chinese battery chemical producers are specifying membrane-polished material in procurement tenders, compressing acceptable lead times for purification system commissioning from eighteen months to under twelve.
China's GB/T standards for lithium-ion battery electrolytes are tightening impurity thresholds faster than harmonization with IEC or JIS frameworks, creating a bifurcated certification landscape. Producers seeking multi-jurisdiction supply contracts must maintain parallel quality management systems, with the China-specific stream driving the most stringent process controls and documentation protocols.
Direct long-term contracting between carbonate producers and cathode-active-material manufacturers is displacing merchant market spot purchasing in major cell manufacturing clusters. Korean battery chemical groups now negotiate three-to-five-year solvent supply agreements with fixed volume floors and indexed pricing, with this contractual shift most visible in the Ulsan and Ochang industrial corridors where material pedigree documentation requirements are strictest.
Global Ethylene Carbonate Market Segmentation
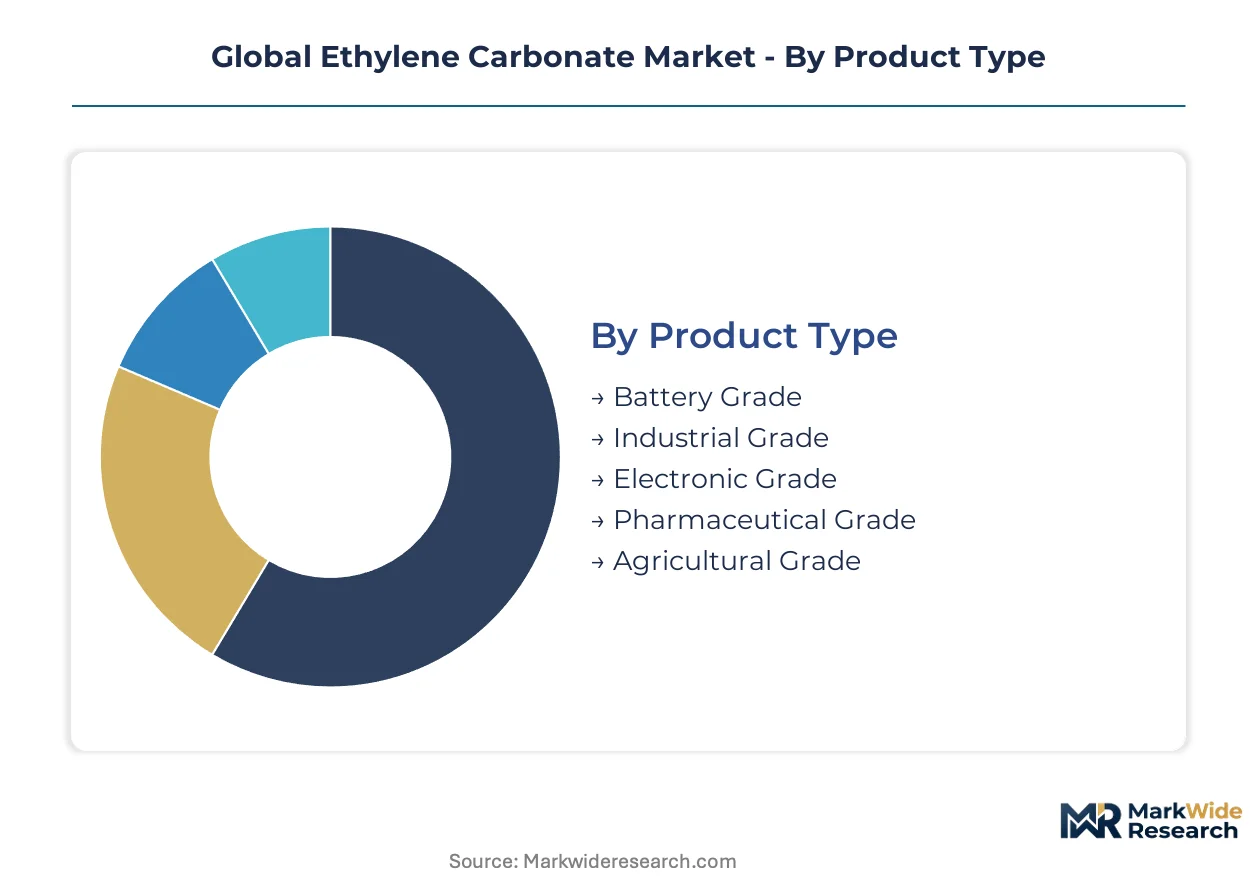
Purity specifications and regulatory certifications fragment ethylene carbonate procurement into sharply differentiated tiers. Buyers select grades based on end-use compliance requirements rather than price alone, with certification costs creating structural barriers between segments.
Product Type:
Purchasing decisions in this category hinge on chloride thresholds and documentation depth rather than unit economics.
- Battery Grade:Material meeting sub-10 ppm chloride specifications serves lithium-ion electrolyte formulations. Chinese and Korean cathode-active-material producers now mandate full pedigree documentation from carbonate suppliers, locking procurement to registered producers with verified carbonation processes.
- Industrial Grade:Standard-purity streams supply solvent manufacturing and coatings applications without battery-certification overhead. German chemical manufacturers absorb volume here for ethylene glycol derivative production, prioritizing feedstock reliability over trace impurity control.
- Electronic Grade:Semiconductor cleaning applications demand particulate control beyond battery specifications. Japanese chip packaging facilities specify this tier for wafer processing solvents.
- Pharmaceutical Grade:FDA and EMA excipient certifications enable controlled-release drug formulations. Pricing power here decouples entirely from industrial-grade commodity cycles.
- Agricultural Grade:Pesticide intermediate applications tolerate broader impurity windows. Indian crop protection manufacturers source this tier for generic agrochemical synthesis.
Volume sits with Industrial Grade; growth tilts toward Battery Grade.
Application:
End-use performance requirements determine formulation flexibility and substitution risk across demand channels.
- Lithium-ion Batteries:Electrolyte solvent applications command premium positioning as electric vehicle OEMs tighten purity specifications. Korean cell manufacturers in Ulsan and Ochang industrial corridors now negotiate three-to-five-year supply agreements with fixed volume floors.
- Solvent Manufacturing:Ethylene glycol and polycarbonate precursor applications retain volume leadership through established industrial supply chains. BASF SE and Mitsubishi Chemical Group Corporation maintain dedicated streams for this channel.
- Coatings:High-boiling-point solvent properties suit polyurethane and epoxy formulations. Chinese construction chemical producers absorb material here for industrial coating systems.
- Agrochemicals:Herbicide and fungicide intermediate synthesis consumes lower-purity carbonate streams. Brazilian crop protection manufacturers source via merchant distributors.
- Pharmaceuticals:Controlled-release tablet excipient applications require full GMP compliance. Swiss and German drug formulators specify certified material with batch-level documentation.
Revenue concentrates in Lithium-ion Batteries; margin stability favors Pharmaceuticals.
End Use Industry:
Customer scale and integration depth shape contracting structures and service requirements.
- Automotive OEMs:Direct solvent procurement from integrated battery cell manufacturers is displacing merchant market purchasing. German and South Korean vehicle producers now require carbon footprint documentation under EU Green Deal procurement criteria.
- Consumer Electronics:Smartphone and laptop battery supply chains demand rapid certification turnaround for new cell designs. Chinese electronics assemblers prioritize suppliers with parallel GB/T and IEC quality management systems.
- Chemical Manufacturing:Commodity solvent buyers negotiate on feedstock cost pass-through mechanisms. Integrated producers with captive ethylene oxide supply hold structural advantages here.
- Drug Formulation:Pharmaceutical excipient procurement requires FDA or EMA site inspections and Drug Master File submissions. Swissmedic and Health Canada oversight adds compliance layers for North American supply.
- Crop Protection:Seasonal demand patterns and price sensitivity characterize this channel. Indian PLI scheme incentives for domestic manufacturing are redirecting some procurement toward local blending facilities.
Contract value peaks with Automotive OEMs; margin defense succeeds in Drug Formulation.
Packaging Type:
Logistics economics and handling safety requirements segment container selection by shipment scale and destination infrastructure.
- Bulk Containers:Rail and vessel shipments serve integrated chemical manufacturing sites with dedicated unloading infrastructure. German and Chinese industrial corridors favor this format for carbonation plant-to-plant transfers.
- Intermediate Bulk Containers:Flexible capacity suits mid-scale battery chemical blenders without fixed tankage. Korean electrolyte compounders specify IBCs for just-in-time solvent delivery.
- Drums:Standard 200-liter steel drums remain the default for pharmaceutical and agricultural distributors requiring smaller lot traceability. Swiss and Indian formulators prefer this format for excipient and agrochemical applications.
- Totes:Collapsible intermediate containers reduce return logistics costs for high-frequency customers. Japanese electronics chemical distributors specify totes for coastal shipping efficiency.
- Jerricans:Laboratory and pilot-scale sampling applications consume this format. R&D facilities across multiple geographies source certified material in 20-25 liter containers.
Shipment volume aggregates in Bulk Containers; flexibility premiums accrue to Intermediate Bulk Containers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ulsan anchors the densest concentration of ethylene carbonate procurement activity, with Korean battery chemical groups negotiating multi-year solvent agreements that lock in volume floors and indexed pricing structures.
China
GB/T standards for lithium-ion battery electrolytes are tightening impurity thresholds faster than IEC harmonization, forcing carbonation operators to maintain parallel quality management systems. The Yangtze River Delta cell manufacturing clusters near cathode and anode facilities are absorbing dedicated high-purity carbonate volumes through direct long-term contracts.
South Korea
The Ochang industrial corridor demands full material pedigree documentation from carbonate suppliers, with three-to-five-year supply agreements displacing merchant market spot purchasing. MFDS oversight of battery chemical imports adds compliance layers that registered producers leverage to exclude unregistered competitors.
Germany
EU Green Deal procurement criteria now require carbon footprint and circularity metrics for electrolyte inputs at European cell plants. BASF SE and industrial chemical manufacturers in the Rhine-Ruhr region absorb standard-purity streams for ethylene glycol derivative production.
Japan
METI guidance on battery supply chain security is reinforcing domestic carbonation capacity, with producers leveraging captive epichlorohydrin feedstock for integrated output. Tokyo-Osaka industrial corridors specify electronic-grade material for semiconductor cleaning applications beyond battery specifications.
India
PLI scheme incentives for domestic battery production are creating first-mover positioning for carbonate suppliers establishing local blending infrastructure. Maharashtra and Gujarat manufacturing zones are emerging as procurement destinations as cell manufacturing buildout accelerates.
Global Ethylene Carbonate Market Competitive Landscape
The competitive structure tilts toward integrated chemical conglomerates with captive ethylene oxide supply. Three archetypes dominate: diversified multinational chemical groups with pharmaceutical-grade certification streams, Asian battery chemical specialists with membrane-based purification capabilities, and regional industrial-grade producers serving solvent manufacturing channels. Capacity expansion and strategic partnerships represent the dominant competitive moves, with producers securing long-term cathode-active-material offtake agreements to justify carbonation-purification capex cycles.
Within the integrated multinational tier, Mitsubishi Chemical Group Corporation and BASF SE exemplify archetypes combining industrial volume leadership with premium-grade certification capabilities. TOAGOSEI CO., LTD. occupies a position among Japanese specialists anchoring high-purity production for domestic battery makers. Zibo Donghai Industries Co., Ltd. represents the scale-driven Chinese producer archetype supplying carbonation output to regional cell manufacturing clusters.
| Leading Market Players |
|---|
| TOAGOSEI CO., LTD. |
| Shinghwa Advanced Material Group Co., Ltd. |
| Mitsubishi Chemical Group Corporation |
| Empower Materials |
| Zibo Donghai Industries Co., Ltd |
| Huntsman International LLC |
| Oriental Union Chemical Corporation |
| FUJIFILM Wako Pure Chemical Corporation |
| BASF SE |
| Others |
Supply & Pricing Matrix
EU Green Deal procurement criteria gate both qualified supply and premium-tier pricing access, as carbon footprint documentation requirements disqualify uncertified carbonation operators from European cell plant contracts while rewarding membrane-polished material with indexed pricing premiums. Battery-grade ethylene carbonate commands substantial markups over industrial streams when cathode-active-material producers enforce sub-10 ppm chloride specifications with full pedigree documentation.
Pricing Analysis
Yield-based pricing anchors battery-grade contracts, with Korean electrolyte compounders in Ulsan and Ochang industrial corridors negotiating three-to-five-year offtake agreements featuring fixed volume floors and raw material indexation. Price differentiation separates membrane-polished battery-grade material from standard industrial streams, with certification overhead and chloride removal capex embedding cost premiums. Cost compression in industrial-grade channels intensifies as merchant-market dependent producers lose share to integrated operators with captive ethylene oxide supply. Chemical manufacturing buyers exhibit highest price sensitivity, while pharmaceutical-grade procurement decouples entirely from commodity cycles through FDA and EMA excipient certifications.
Supply Chain Analysis
Analytical chemistry talent scarcity in Chinese and Korean manufacturing zones constrains carbonation plant commissioning schedules, as battery-grade certification demands ion chromatography expertise that carbonation operators historically lacked. Supply concentrates in China, South Korea, and Germany, with Yangtze River Delta and Ulsan-Ochang corridors anchoring procurement gravity. Feedstock draws from captive ethylene oxide production and merchant epichlorohydrin markets, with carbon dioxide sourcing and membrane purification equipment adding dependency layers. Single-source vulnerability in membrane technology suppliers poses structural risk. Distribution runs through direct long-term contracts between carbonate producers and cathode-active-material manufacturers, displacing spot purchasing in major cell manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ethylene carbonate market sits in a technology-transition phase, with solid-state electrolyte precursor applications displacing conventional liquid electrolyte formulations in next-generation cell architectures. Membrane-based chloride removal and carbonation process intensification separate competitive positions.
For Market Incumbents: Anchor membrane-polished production capacity in Korean and Chinese industrial corridors to defend against propylene carbonate substitution in low-temperature electrolyte blends. Secure captive ethylene oxide supply through backward integration or long-term feedstock agreements to neutralize margin compression during epichlorohydrin price spikes. Prioritize GB/T and REACH parallel certification investments to maintain multi-jurisdiction supply eligibility as regulatory divergence accelerates.
For New Entrants and Emerging Players: Enter via pharmaceutical-grade channel expansion, where FDA and EMA excipient certifications create defensible margin pools with pricing power decoupled from industrial commodity cycles. Target Indian PLI scheme incentives for domestic battery production, establishing local blending infrastructure ahead of Maharashtra and Gujarat cell manufacturing buildout. Pursue toll manufacturing arrangements with integrated chemical conglomerates lacking battery-grade purification capabilities.
For Investors and Strategic Acquirers: MFDS registration completion for Korean battery chemical imports is the leading indicator that carbonation operators have cleared compliance barriers sufficient to justify carbonation-purification capex cycles. Over the medium-term horizon, acquisition targets should emphasize mid-scale producers with membrane-based purification capabilities but lacking parent-company financing access for dual reactor and chloride removal upgrades. Watch for cathode-active-material manufacturers negotiating direct long-term solvent supply agreements as signal of contracting structure permanence.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethylene Oxide | Captive feedstock supply neutralizes epichlorohydrin volatility for carbonation operators serving Korean battery chemical groups. |
| Membrane-Based Purification Capacity Addition | Membrane-polished material specifications in Chinese and Korean procurement tenders compress acceptable commissioning lead times. |
| Dual GB/T and REACH Certification Investment | Parallel quality management systems enable multi-jurisdiction supply contracts as regulatory divergence accelerates between jurisdictions. |
| Long-Term Cathode-Active-Material Supply Agreement | Three-to-five-year offtake contracts with fixed volume floors displace merchant spot purchasing in Ulsan and Ochang corridors. |
| Pharmaceutical-Grade Channel Certification | FDA and EMA excipient certifications open margin pools in controlled-release drug formulations with pricing power decoupled from industrial cycles. |
Research Methodology
Independent corroboration across carbonation plant managers, procurement leads at Korean and Chinese cathode-active-material producers, electrolyte compounding technical directors, and distribution channel partners underwrites the qualitative findings in this study. Secondary validation draws from customs and trade data, chemical industry association reports, SEC filings of integrated chemical conglomerates, and regulatory dossier submissions to ECHA and Chinese standardization authorities. Bottom-up capacity and demand modeling triangulates against top-down market sizing across grade tiers and end-use industries.
Comparable-period anchoring to historical carbonation capacity utilization and electrolyte solvent procurement patterns shaped the forecast window construction across the analysis window. Segmentation dimensions modeled include purity grade tier, end-use industry application, packaging format, and regional production hub concentration. CAGRs derive from demand elasticity analysis against electric vehicle production trajectories and cathode-active-material expansion schedules, with carbonation process emission intensity and regulatory compliance cost curves as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt regulatory divergence between REACH and GB/T frameworks or feedstock supply disruptions. Forecasts reflect assumptions regarding membrane technology adoption curves and cathode-active-material manufacturer vertical integration intentions. Material deviation in solid-state electrolyte commercialization timelines or carbonation process emission regulations warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Beneficiation Reagents Market
Industrial Chemicals
Mass Finishing Consumables Market
Industrial Chemicals
Aerosol Refrigerants Market
Industrial Chemicals
Global N-Methyl-2-Pyrrolidone (NMP) Market
Industrial Chemicals
Gypsum-Based Products Market
Industrial Chemicals
Singapore Sealants Market
Industrial Chemicals
Global Cyanuric Chloride Market
Industrial Chemicals
Silicates Market
Industrial Chemicals
Multi Component Injection Moulding Technology Market
Industrial Chemicals
Hydrofluoroolefin (HFO) Blowing Agent Systems for Rigid PU Foam Market
Industrial Chemicals
Caustic Calcined Magnesia Market
Industrial Chemicals
Global Activated Carbon Canisters Market
Industrial Chemicals
Blow Torch Market
Industrial Chemicals
US Anhydrous Hydrogen Fluoride Market
Industrial Chemicals
Global Industrial Separators Market
Industrial Chemicals
Europe Molecular Sieve Market