
 Global High Throughput Process Development Market | 2026-2036
Global High Throughput Process Development Market Size, Share, and Industry Trends Forecast 2026-2036
Global High Throughput Process Development Market Intelligence
Expanded biomanufacturing capacity in China and India is narrowing the gap in process development timelines with established Western markets. Thermo Fisher Scientific leverages its extensive portfolio of instruments and reagents to support this global expansion. Sartorius AG specializes in integrated solutions for both upstream and downstream bioprocessing. Meanwhile, Merck KGaA differentiates through its strong focus on single-use technologies and comprehensive bioprocess services.
High throughput process development uses automated, miniaturized, and parallelized systems to rapidly screen and optimize biomanufacturing conditions. This approach significantly accelerates the determination of optimal parameters for cell culture, purification, and formulation. Pharmaceutical firms and biotechnology companies are the largest end-user segments, driven by intense pressure for faster drug discovery timelines. Demand for integrated instruments and advanced data analytics software is currently outpacing growth for standalone consumables and reagents.
Regulatory bodies including the US FDA, the European EMA, and China's NMPA directly influence process validation and documentation requirements. These agencies' guidelines on process analytical technology (PAT) and quality by design (QbD) encourage the adoption of data-rich development methods. Stakeholders must decide how to balance investment in advanced robotics and automation against the evolving complexity of regulatory data submission packages worldwide.
Market Dynamics
The convergence of robotics, miniaturized bioreactors, and advanced analytics software is the central force reshaping bioprocess development. This technological fusion enables parallel experimentation at a scale that fundamentally accelerates timelines for developing biologics and cell therapies.
Growth Catalysts
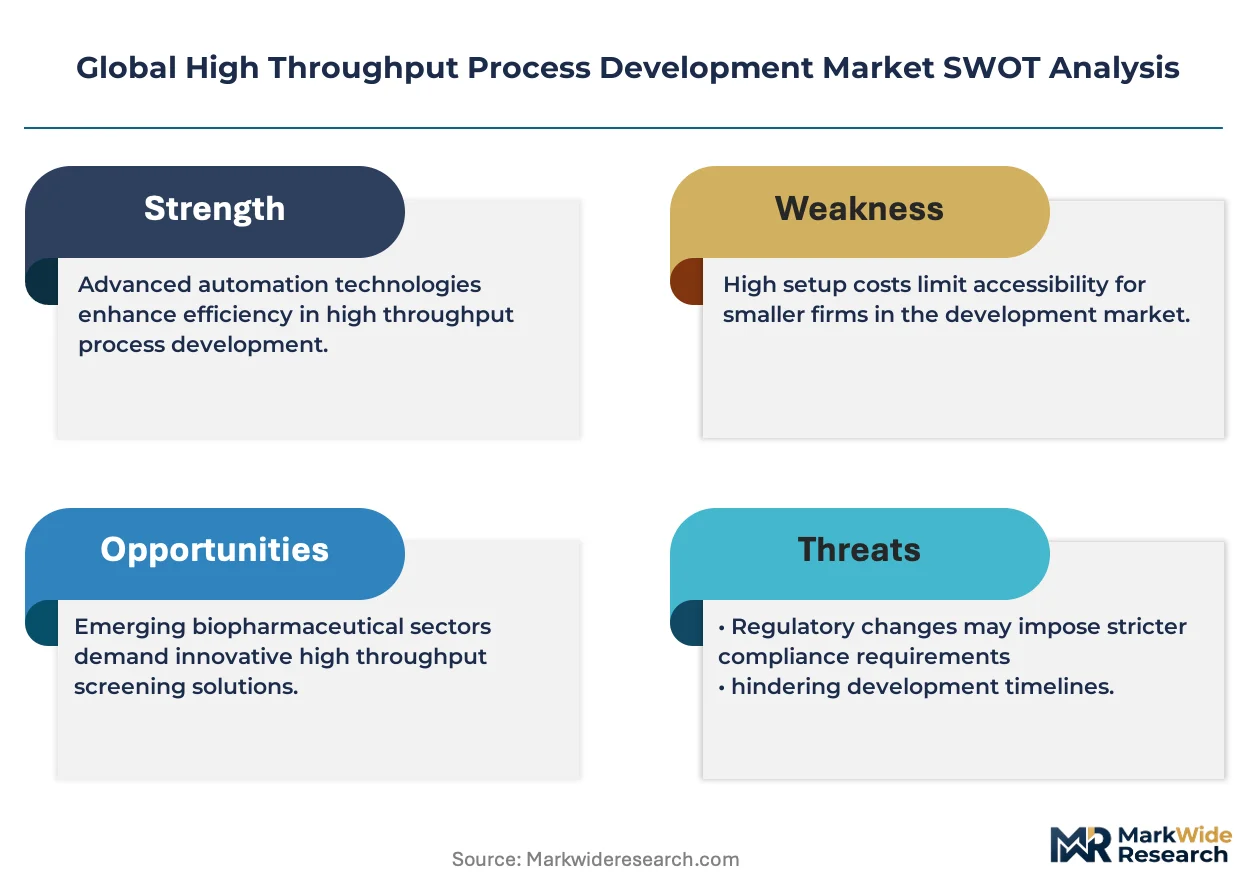
- QbD Regulatory Guidance:FDA and EMA guidelines on Quality by Design (QbD) incentivize data-intensive approaches used in high throughput process characterization.
- Complex Biologics Pipeline:The expanding pipeline of cell and gene therapies necessitates rapid manufacturing optimization, a core capability of parallelized screening systems.
- Biopharma Hub Investment:Concentrated R&D investment in biopharmaceutical clusters in the US and China drives demand for technologies accelerating development.
Market Restraints
- High Capital Investment:The upfront cost of integrated robotics and automated bioreactors is a major adoption barrier for smaller biotech firms.
- Process Scalability Challenges:Translating optimal conditions from miniaturized systems to large-scale cGMP manufacturing requires extensive, costly re-validation.
- Regulatory Data Burden:Managing and submitting massive datasets to agencies like the FDA and EMA in compliant formats is a complex operational challenge.
Strategic Opportunities
- AI-Driven Experimental Design:Integrating machine learning with screening data allows predictive modeling of optimal conditions, reducing physical experiments and accelerating development.
- Rapid Vaccine Development:Applying high throughput systems to accelerate process development for new mRNA and viral vector vaccines is a key opportunity.
- Biopharma Growth in India:India's expanding biopharmaceutical sector, backed by the PLI scheme, is an underpenetrated market for process development automation.
Industry Challenges
- Specialized Talent Scarcity:A shortage of personnel with interdisciplinary skills in biology, automation engineering, and data science is a primary operational bottleneck for implementing high throughput systems.
- Integrating Disparate Systems:Ensuring seamless data flow between instruments, software, and laboratory information management systems (LIMS) from different vendors remains a significant technical hurdle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global High Throughput Process Development Market |
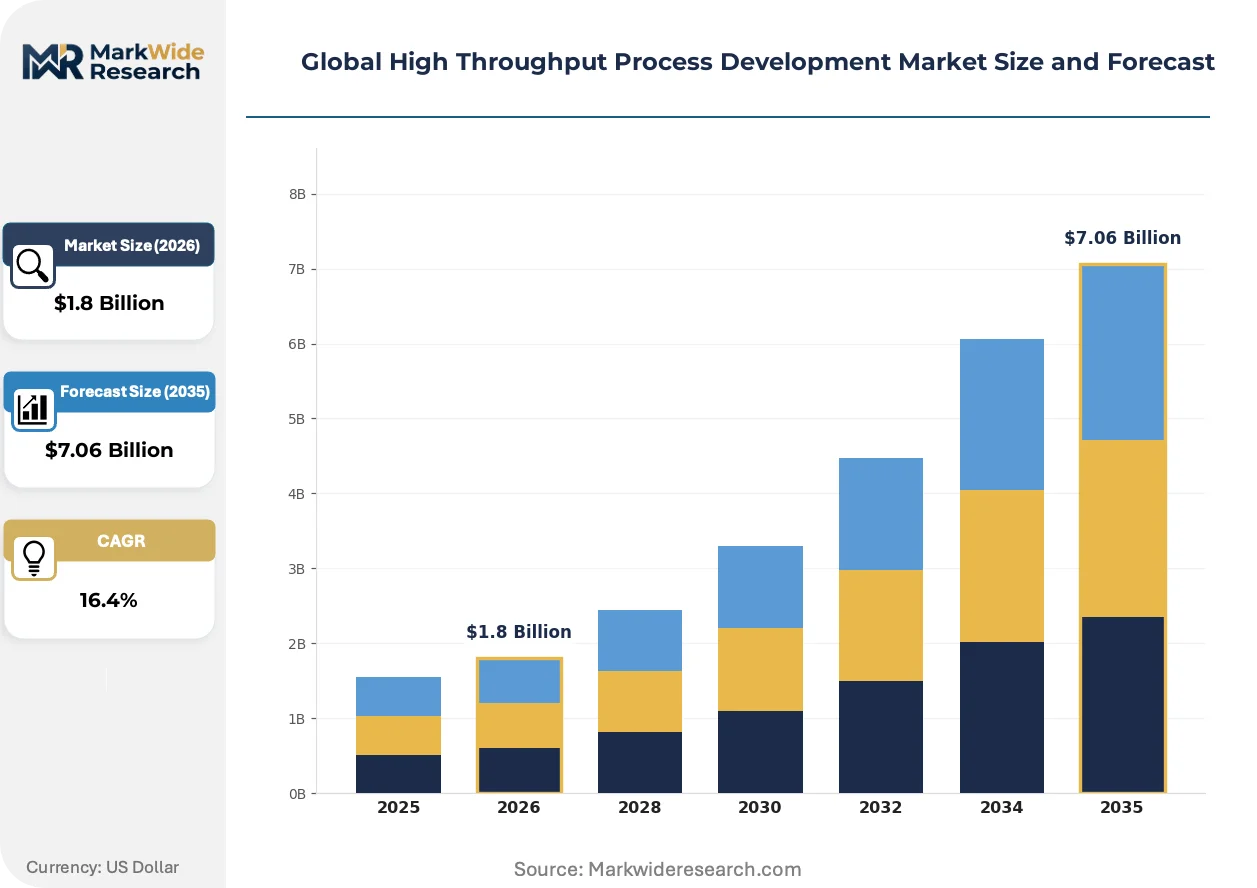
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $7.06 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Microfluidics, Automation, Robotics, Data Analytics End User: Biotechnology Companies, Pharmaceutical Firms, Academic Institutions, Research Organizations Application: Drug Discovery, Clinical Trials, Genomic Research, Enzyme Engineering Product Type: Instruments, Reagents, Software, Consumables |
| Companies Covered | Merck KGaA, GE Healthcare, Thermo Fisher Scientific, PerkinElmer, Bio-Rad Laboratories, Sartorius AG, Agilent Technologies, Eppendorf AG, Danaher Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global High Throughput Process Development Market Strategic Shifts & Innovations
The evolution from sequential, isolated process development steps to integrated, data-centric workflows is altering biomanufacturing timelines. This shift prioritizes platform technologies that unify data streams for holistic process optimization.
Advanced microfluidics integrated into automated bioreactor systems enables precise control over minute liquid volumes for cell culture experiments. Biopharmaceutical firms and CDMOs are rapidly adopting these platforms for clone selection and media optimization. This technology is collapsing the time and material costs associated with early-stage process screening.
New guidance from the International Council for Harmonisation (ICH), specifically the Q12 guideline, addresses pharmaceutical product lifecycle management. The framework facilitates managing post-approval CMC changes, promoting a prospective, data-driven approach to process control. Biologics developers leverage these principles, using high throughput data to justify process improvements to regulators like Japan's PMDA.
A significant behavioral shift is occurring as end-users move from purchasing standalone instruments towards acquiring integrated, end-to-end process development platforms. This disrupts the component-based sales model, favoring vendors who provide a single hardware, software, and service package. This trend is most pronounced among large pharmaceutical companies seeking to standardize global R&D operations.
Global High Throughput Process Development Market Segmentation
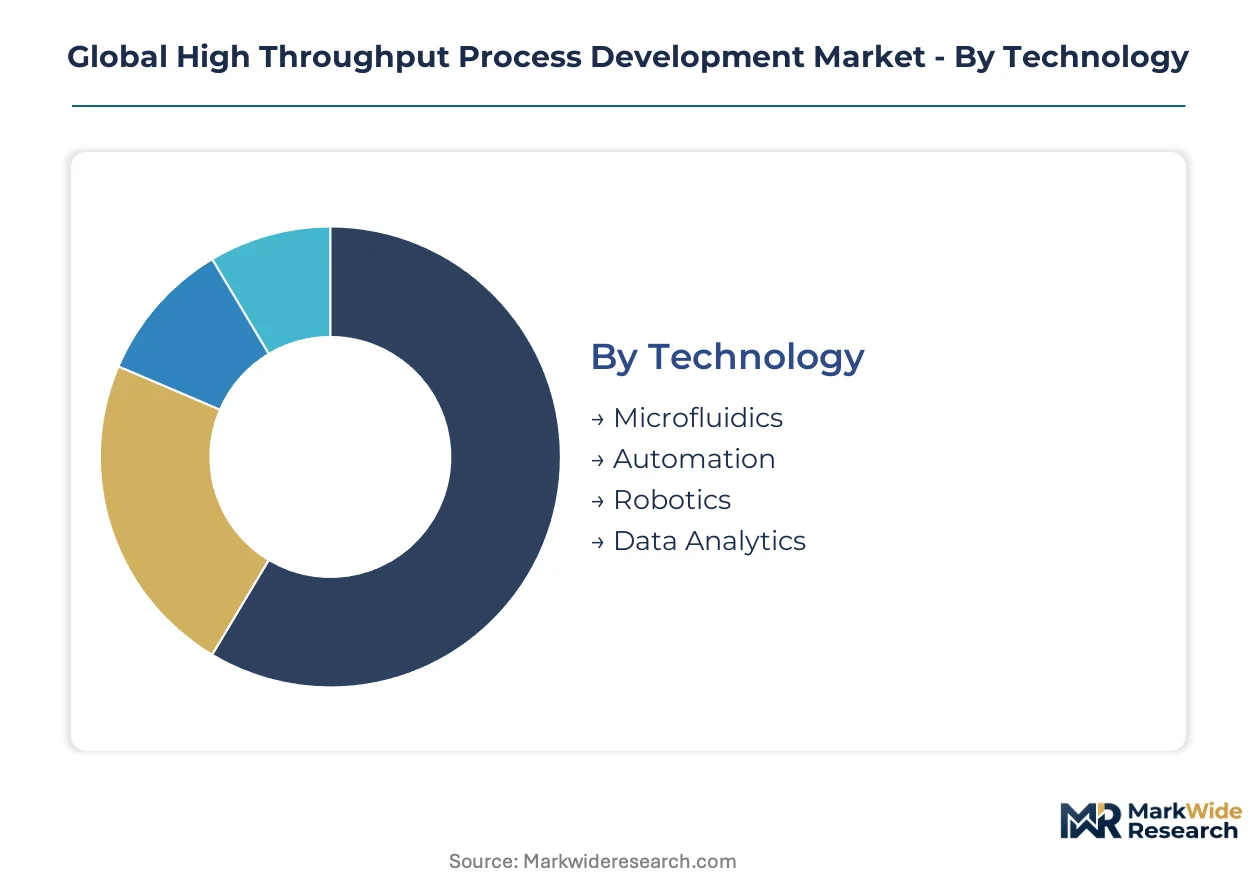
Segmentation of the Global High Throughput Process Development Market provides a granular view of demand patterns and technological preferences across various end-user groups. This analysis highlights where investment is concentrating and which solutions are gaining traction in accelerating bioprocess optimization. Understanding these segments is crucial for stakeholders to align product development with evolving industry needs.
Technology:
The technology landscape for high throughput process development spans both mature and rapidly emerging solutions, each addressing distinct stages of bioprocess optimization.
- Automation:This segment includes automated liquid handling systems, robotic plate readers, and integrated platforms designed for parallel experimentation. Pharmaceutical firms demand automation for high-volume screening to accelerate biologics and cell therapy development.
- Data Analytics:This encompasses specialized software and algorithms for experimental design, data interpretation, and predictive modeling of bioprocess conditions. Biopharmaceutical R&D teams leverage data analytics to optimize parameters and manage complex datasets for regulatory submissions.
- Microfluidics:Microfluidic devices enable precise control over minute liquid volumes, facilitating miniaturized cell culture experiments and high-density screening. This technology collapses the time and material costs associated with early-stage process screening.
- Robotics:Robotics integrates with automated systems for precise sample handling, plate movement, and instrument loading, enhancing throughput and reproducibility. Robotics supports the parallelization of complex laboratory workflows.
Automation retains volume leadership; Data Analytics holds the steepest expansion curve.
End User:
The end-user segmentation reflects varied operational scales and investment capacities across the biopharmaceutical ecosystem.
- Biotechnology Companies:These firms often focus on novel therapies, including cell and gene therapies, requiring agile and rapid process development capabilities. Biotechnology companies utilize high throughput systems to accelerate their complex biologics pipeline.
- Pharmaceutical Firms:Large pharmaceutical companies operate extensive R&D pipelines and manufacturing facilities, facing intense pressure for faster drug discovery and commercialization. Pharmaceutical firms seek integrated platforms to standardize global R&D operations and reduce timelines.
- Academic Institutions:Universities and research centers conduct fundamental research into biological processes and method development for biomanufacturing. Academic institutions adopt high throughput tools for early-stage screening and proof-of-concept studies.
- Research Organizations:Contract research organizations (CROs) and contract development and manufacturing organizations (CDMOs) provide specialized services to biopharma clients. Research organizations integrate high throughput systems to offer efficient and comprehensive bioprocess development services.
Pharmaceutical Firms represent the largest segment; Biotechnology Companies are expanding most quickly.
Application:
Applications for high throughput process development span the entire drug development lifecycle and beyond, each with distinct requirements.
- Drug Discovery:This involves identifying, validating, and optimizing lead compounds or biologics candidates for therapeutic potential. High throughput methods accelerate the identification of promising therapeutic candidates by rapidly screening libraries.
- Clinical Trials:During clinical development, high throughput process development optimizes manufacturing conditions for investigational medicinal products. This ensures consistent product quality and scalability for regulatory requirements from agencies like the US FDA and European EMA.
- Genomic Research:High-throughput sequencing and screening techniques are applied to identify genetic targets, understand disease mechanisms, and develop gene therapies. Genomic research leverages parallelized systems for rapid analysis of vast biological data.
- Enzyme Engineering:This application focuses on optimizing enzyme function, stability, and specificity for various industrial, diagnostic, and therapeutic uses. Enzyme engineering benefits from rapid screening of enzyme variants for improved performance.
Drug Discovery drives significant demand; Clinical Trials applications are gaining momentum due to regulatory scrutiny.
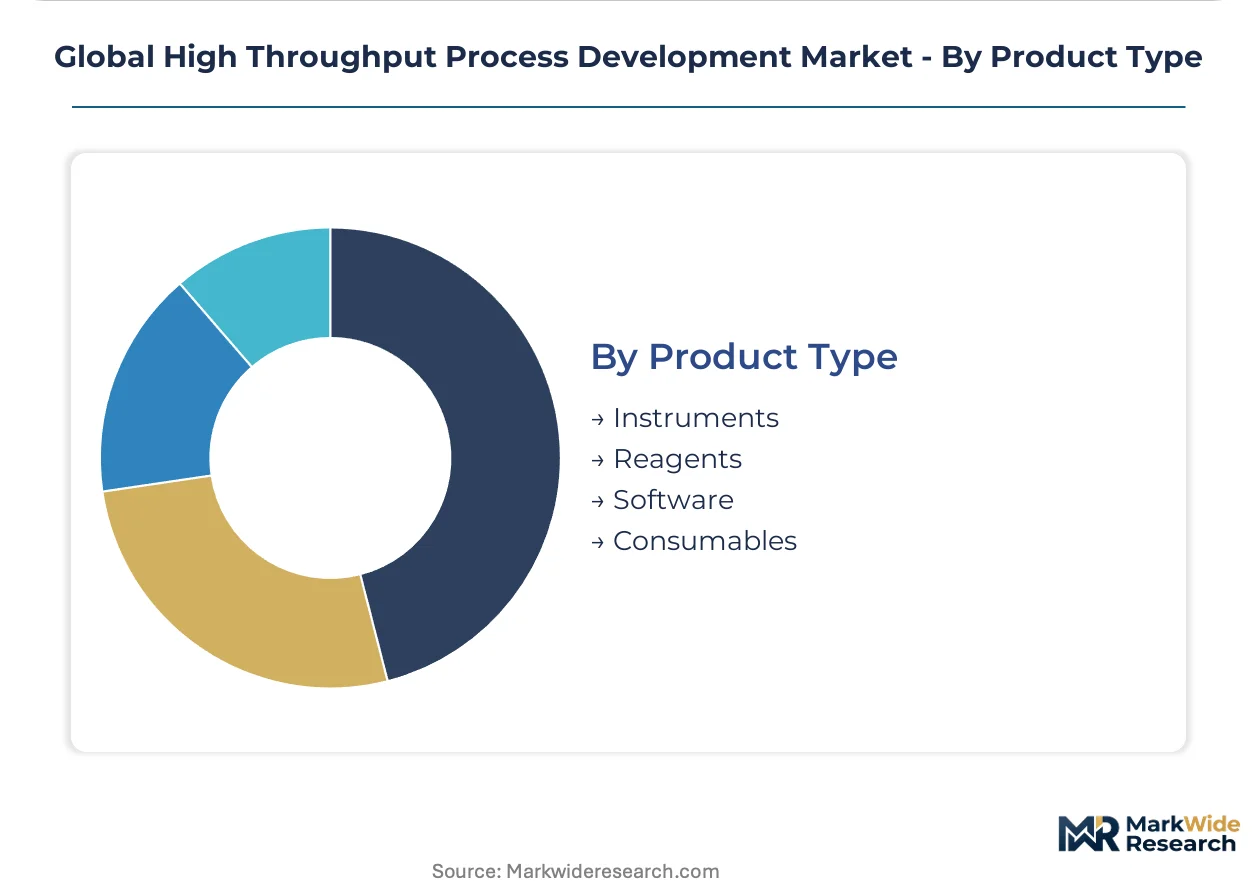
Product Type:
The product type segmentation reflects the diverse components required for high throughput systems, from hardware to analytical tools.
- Instruments:This category includes automated bioreactors, liquid handling robotics, and integrated analytical devices essential for parallel experimentation. Demand for integrated instruments currently outpaces growth for standalone consumables.
- Software:Software solutions encompass advanced data analytics platforms, experimental design tools, and laboratory information management systems (LIMS) for data integration. Software enables predictive modeling and streamlined regulatory data submission packages.
- Reagents:Reagents include cell culture media, buffers, purification resins, and assay kits necessary for conducting bioprocess experiments. These consumables are fundamental inputs for high throughput screening.
- Consumables:Consumables comprise microplates, miniaturized bioreactor vessels, pipette tips, and other single-use items critical for maintaining sterile and efficient automated workflows. Consumables support high-volume, parallelized experiments.
Instruments command the largest revenue share; Software demonstrates the most rapid market penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
This market's growth is underpinned by extensive biopharmaceutical infrastructure, which facilitates the rapid adoption of high throughput process development technologies. These advanced systems are critical for accelerating drug discovery and manufacturing optimization across key global regions. Investment in these capabilities is concentrating in established and emerging biopharma hubs worldwide.
United States
The United States drives significant demand for high throughput process development, fueled by substantial R&D investment and a complex biologics pipeline. US FDA guidelines on Quality by Design (QbD) incentivize data-intensive approaches for process characterization. The Boston-Cambridge bio-cluster exemplifies this trend, with numerous pharmaceutical firms and biotechnology companies adopting advanced automation.
China
China's expanded biomanufacturing capacity and concentrated R&D investment propel the adoption of high throughput systems. China's NMPA directly influences process validation and documentation, encouraging data-rich development methods. Major biopharma clusters in Shanghai and Suzhou are rapidly integrating advanced robotics and analytics.
In Germany
In Germany, a robust pharmaceutical industry and advanced biotechnology research contribute substantially to high throughput process development demand. European EMA guidelines on process analytical technology (PAT) encourage adoption of data-intensive methods. Clusters in Bavaria and North Rhine-Westphalia are key centers for developing and implementing integrated bioprocess solutions.
India
India's expanding biopharmaceutical sector presents an underpenetrated market for process development automation, supported by the PLI scheme. India's CDSCO influences manufacturing standards and encourages efficient process validation. Biopharma hubs in Hyderabad and Bengaluru are increasingly investing in high throughput systems.
Japan
Japan's advanced biologics R&D and strong focus on manufacturing quality create consistent demand for high throughput solutions. Japan's PMDA leverages ICH Q12 guidelines to facilitate post-approval CMC changes. Major biopharma centers in Tokyo and Osaka are adopting integrated platforms for holistic process optimization.
Global High Throughput Process Development Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream, supplying essential reagents and consumables. The market structure is tiered, featuring large conglomerates offering comprehensive solutions alongside niche providers focusing on specific technologies. Strategic archetypes include full-service platform providers, specialized automation developers, and reagent/consumable suppliers. Dominant competitive moves involve strategic partnerships to integrate disparate systems and continuous portfolio diversification to cover the entire bioprocess workflow.
Among full-service platform providers, Thermo Fisher Scientific leverages its extensive portfolio of instruments and reagents, representing a broad market presence across diverse bioprocess needs. Sartorius AG occupies a position as a specialized integrated solutions provider, focusing on both upstream and downstream bioprocessing. Merck KGaA, a German-based company, exemplifies differentiation through a strong focus on single-use technologies and comprehensive bioprocess services, addressing evolving industry demands. These entities anchor distinct segments, catering to varied customer needs from early-stage research to large-scale manufacturing.
| Leading Market Players |
|---|
| Merck KGaA |
| GE Healthcare |
| Thermo Fisher Scientific |
| PerkinElmer |
| Bio-Rad Laboratories |
| Sartorius AG |
| Agilent Technologies |
| Eppendorf AG |
| Danaher Corporation |
| Others |
Cost & Logistics Intelligence
Expanded biomanufacturing capacity in China and India initially creates localized overcapacity pressure, influencing supplier behavior and pricing postures for process development services. This shift drives competitive pricing strategies among service providers targeting these regions.
Pricing Analysis
US FDA guidelines on Quality by Design (QbD) influence the pricing tier structure for data-intensive process development services. The dominant pricing model combines project-based fees for integrated solutions with subscription-tiered access for data analytics software. Price differentiation stems from customization levels for complex workflows and the brand premium of established instrument providers. Pricing softness emerges from increased competition in expanding biomanufacturing hubs, with smaller biotechnology companies exhibiting higher price sensitivity than large pharmaceutical firms.
Supply Chain Analysis
Upstream feedstock for high throughput process development relies heavily on specialized reagents and precision-engineered components, with geographic supply concentrating in Germany, the United States, and increasingly China. Raw material dependencies include advanced cell culture media, purification resins, and microfluidic chips. Single-source vulnerability for highly specialized instrumentation components represents a significant structural risk. The dominant distribution model involves direct sales channels from equipment manufacturers to pharmaceutical firms and contract research organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a significant fragmentation opportunity, driven by the expanding and complex biologics pipeline that necessitates highly specialized process development solutions. Niche demands for specific cell and gene therapy optimization create numerous market entry points.
For Market Incumbents: Insulate core market share by deepening portfolio integration and standardizing global R&D platforms for large pharmaceutical clients. This defends against niche players leveraging advanced AI-driven experimental design. Invest in strategic partnerships with data analytics firms to enhance predictive modeling capabilities. Expand comprehensive bioprocess services in emerging markets to leverage existing infrastructure.
For New Entrants and Emerging Players: Build out specialized software solutions for AI-driven experimental design and predictive modeling. Target the underpenetrated market of India's expanding biopharmaceutical sector, focusing on efficient process development automation. Offer value-based pricing models that demonstrate clear return on investment for smaller biotechnology companies. Develop integrated microfluidics platforms tailored for early-stage cell therapy screening.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across integrated automated bioprocessing instruments, indicating sustained investment for long-term operational efficiency. The market offers strong viability for platforms enabling Quality by Design and Process Analytical Technology over the next decade. Target acquisition archetypes include specialized data analytics software developers and advanced microfluidics technology providers. The signal to watch is increasing regulatory mandates for data-rich process characterization.
| Strategic Initiative | Industry Significance |
|---|---|
| Integrated Platform Development | Consolidates disparate instruments and software, offering end-to-end solutions for pharmaceutical firms like Thermo Fisher Scientific. |
| AI/ML Software Development | Predictive modeling capabilities accelerate experimental design, reducing physical experiments for biotechnology companies. |
| Targeted Geographic Expansion | Penetrating emerging markets like India leverages government incentives and growing biopharmaceutical sectors. |
| Single-Use Technology Focus | Addresses evolving industry demands for sterile, flexible, and efficient bioprocess operations, championed by Merck KGaA. |
| Enhanced Regulatory Compliance Services | Supports complex data submission packages, assisting clients with US FDA and European EMA guidelines. |
Research Approach
A spread of perspectives from drug development executives, process engineers, regulatory affairs leads, and CDMO project managers converged on the working assumptions underpinning this analysis. The methodology combined extensive primary interviews with rigorous secondary validation. Secondary data sources included US FDA filings, European EMA submissions, relevant industry association reports, and scientific literature databases. This approach ensured bottom-up market sizing and top-down validation through triangulation.
Demand-supply-balance dynamics informed the analytical framework, integrating technology adoption curves and regulatory influence across the modeling period. The study segmented the market by technology, end-user, application, product type, and regional regulatory cluster. Compound Annual Growth Rates were derived using regression analysis on historical growth trends. Biologics pipeline growth rates served as a key industry-specific forecast input.
The forecast holds incumbent behavior within observed patterns; aggressive moves by large pharmaceutical firms or specialized automation developers would shift outcomes. Forecasts reflect assumptions regarding sustained R&D investment. Cross-checking against industry investment reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Metal Forming Fluids Market
Industrial Chemicals
Sulfolane Market
Industrial Chemicals
Quicklime Market
Industrial Chemicals
Dewatering Aids Market
Industrial Chemicals
Pelletized Activated Carbon Market
Industrial Chemicals
Plastic Contract Manufacturing Market
Industrial Chemicals
Surface Treatment Chemicals Market
Industrial Chemicals
Global Isocyanate Market
Industrial Chemicals
Gypsum Market
Industrial Chemicals
Fluidized Bed Reactors Market
Industrial Chemicals
Continuous Reactors Market
Industrial Chemicals
Aminic Antioxidants Market
Industrial Chemicals
South America Starch Derivatives Market
Industrial Chemicals
Thermally Stable Antiscalant Market
Industrial Chemicals
Wood Vinegar Market
Industrial Chemicals
North America Paper Machine Oil Market