
 2-Ethylhexanol (2-EH) Market | 2026-2036
2-Ethylhexanol (2-EH) Market Size, Share, and Industry Trends Forecast 2026-2036
2-Ethylhexanol (2-EH) Market Outlook
Technical-grade purity specifications are bifurcating the competitive landscape as buyers in coatings and adhesives enforce stricter contaminant thresholds. BASF SE leverages its integrated C4 value chain to sustain feedstock cost advantages across European production hubs. Dow anchors North American supply through Gulf Coast propylene infrastructure, while SINOPEC dominates Asian volume with state-backed refining-to-chemicals integration.
2-Ethylhexanol is a C8 branched alcohol produced via propylene hydroformylation and subsequent aldol condensation-hydrogenation, yielding a colorless liquid with a boiling point near 184°C and primary utility as a chemical intermediate for plasticizer esters, acrylate monomers, and lubricant additives. The plasticizers segment leads absolute consumption as construction and automotive suppliers convert flexible PVC formulations, while the intermediates category records the fastest structural expansion driven by 2-EH acrylate demand in pressure-sensitive adhesives and textile coatings. Industrial grade captures the dominant margin pool due to volume scale, though pharmaceutical grade commands premium pricing from stringent USP monograph compliance.
EPA oversight under TSCA governs 2-EH manufacturing emissions and worker exposure limits in the United States, while REACH registration and ECHA substance evaluation enforce hazard communication and authorization protocols across Europe. China's MEE implements GB standards for volatile organic compound emissions from alcohol production facilities, reshaping plant upgrade cycles and import qualification requirements. Stakeholders must monitor regulatory divergence between jurisdictions to align capital allocation with emerging compliance thresholds and grade certification demands.
Market Dynamics
Propylene feedstock volatility and tightening purity mandates are restructuring 2-EH procurement patterns, forcing buyers to qualify alternative suppliers and upgrade specification protocols.
Growth Catalysts
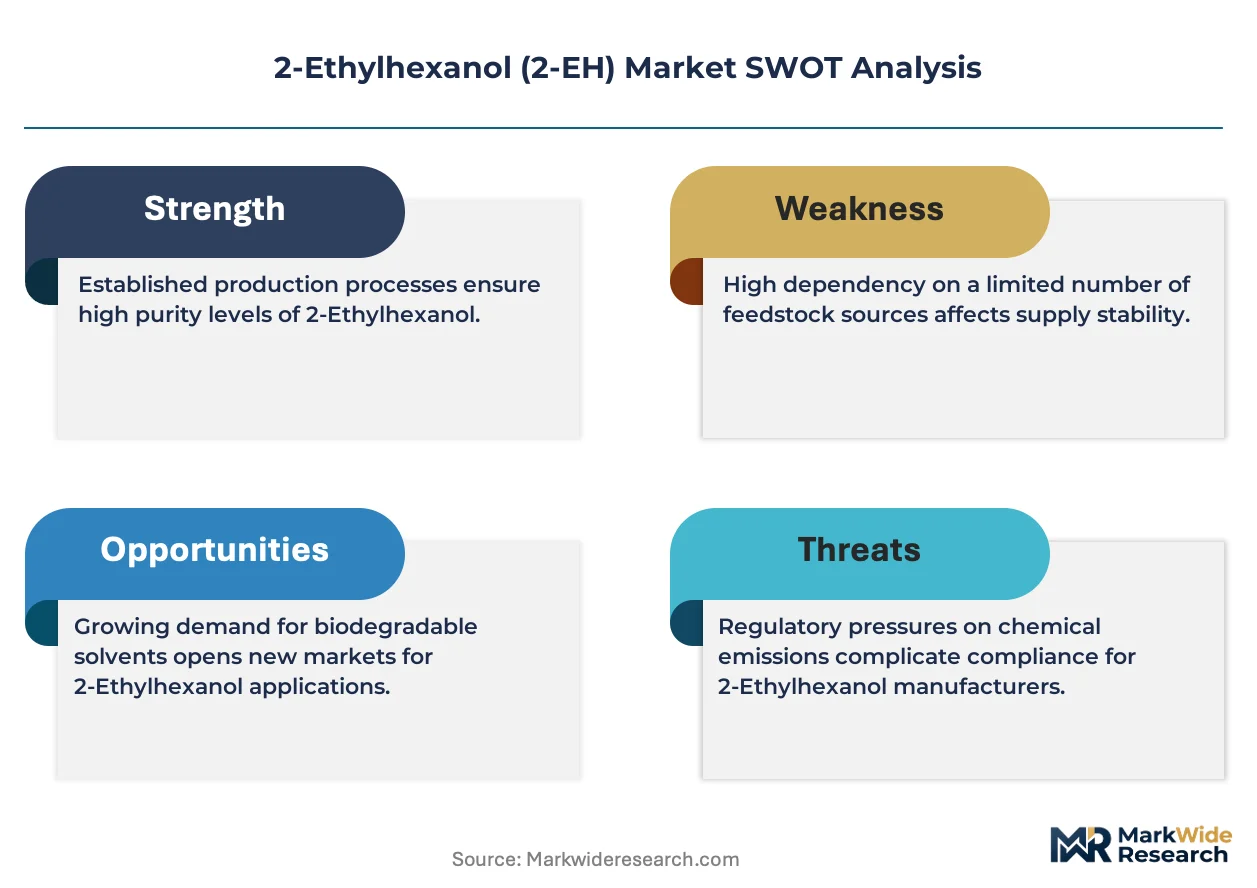
- Phthalate substitution mandates:REACH authorization pressures and China's GB 38508 standards accelerate demand for 2-EH-based non-phthalate plasticizers in flexible PVC applications.
- Acrylate monomer expansion:Pressure-sensitive adhesive producers in packaging and textiles are scaling 2-EH acrylate consumption for high-tack formulations.
- Construction chemicals clustering:Chemical parks in China and Germany concentrate downstream plasticizer capacity, anchoring regional 2-EH offtake.
Market Restraints
- Propylene cost pass-through limitations:Crude-linked naphtha and shale gas economics create margin compression for non-integrated 2-EH producers.
- Asian supply concentration:State-backed refining complexes in China control disproportionate export volumes, exposing buyers to single-source qualification risks.
- Biobased C8 alcohol substitution:Renewable octanol from biomass fermentation threatens technical-grade 2-EH in coating solvent applications.
Strategic Opportunities
- India specialty chemical expansion:PLI scheme incentives and domestic plasticizer capacity builds create captive 2-EH demand outside established trade flows.
- Pharmaceutical-grade certification:USP monograph compliance for excipient applications opens premium pricing tiers in drug formulation supply chains.
- Carbon accounting integration:EU Green Deal embodied carbon tracking favors low-carbon-intensity 2-EH from bio-propylene or carbon-capture routes.
Industry Challenges
- Process control engineering scarcity:Aldol condensation-hydrogenation unit optimization requires specialized catalysis expertise concentrated at legacy European and Gulf Coast facilities.
- Multi-jurisdiction certification timelines:Simultaneous REACH registration, TSCA PMN filings, and China MEE emission permits extend product qualification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 2-Ethylhexanol (2-EH) Market |
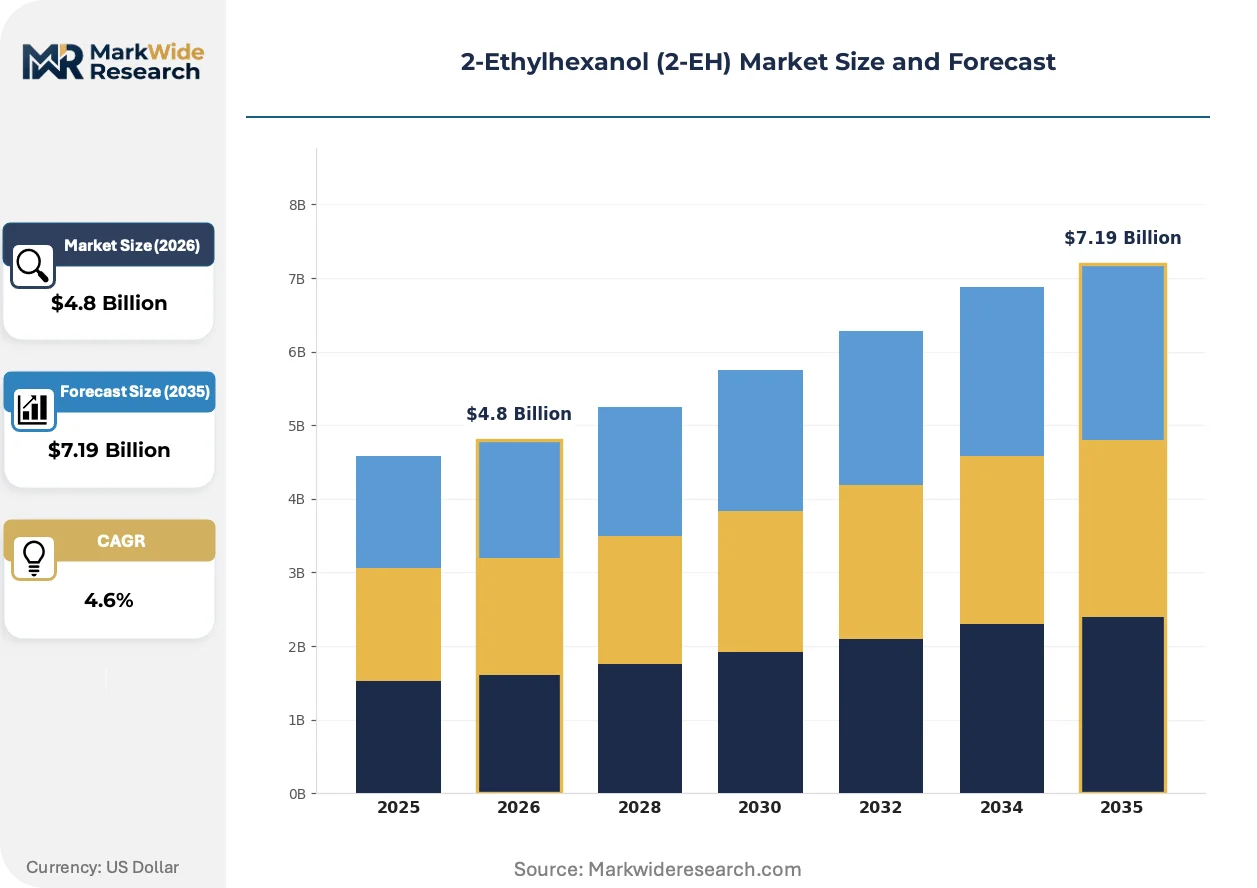
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plasticizers, Solvents, Lubricants, Intermediates Grade: Industrial, Food Grade, Pharmaceutical, Technical Application: Coatings, Adhesives, Automotive, Textile End User: Construction, Automotive Suppliers, Paint Manufacturers, Chemical Industries |
| Companies Covered | SABIC, INEOS, BASF SE, OQ Chemicals GmbH, LG Chem, Dow, Mitsubishi Chemical Corporation, SINOPEC, Eastman Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
2-Ethylhexanol (2-EH) Market Strategic Shifts
Digital process control and feedstock diversification are compressing production economics while regulatory transparency tools reshape supplier qualification protocols across chemical value chains.
Membrane separation technology for 2-EH purification is miniaturizing. Coating manufacturers in automotive and industrial applications are adopting compact, modular distillation units to achieve pharmaceutical-grade purity without centralized refinery economics. This distributed purification architecture is compressing the traditional scale advantages of integrated petrochemical complexes.
REACH substance evaluation and authorization protocols are tightening hazard communication requirements for C8 alcohols used in consumer-facing applications. ECHA's systematic evaluation of reproductive toxicity endpoints forces downstream formulators to document exposure scenarios and substitute pathways. Coating producers in Germany and France are accelerating migration to certified low-impurity grades to preempt authorization listing.
Buyers are consolidating supplier panels and demanding real-time carbon intensity data. Large construction chemical distributors in Western Europe now require Scope 1-3 emissions disclosures for 2-EH procurement decisions, displacing spot-market purchasing with long-term offtake agreements tied to verified low-carbon production routes. This behavioral shift is most pronounced in Germany's automotive supply chain, where OEM sustainability scorecards cascade to plasticizer tier-2 sourcing.
2-Ethylhexanol (2-EH) Market Segmentation
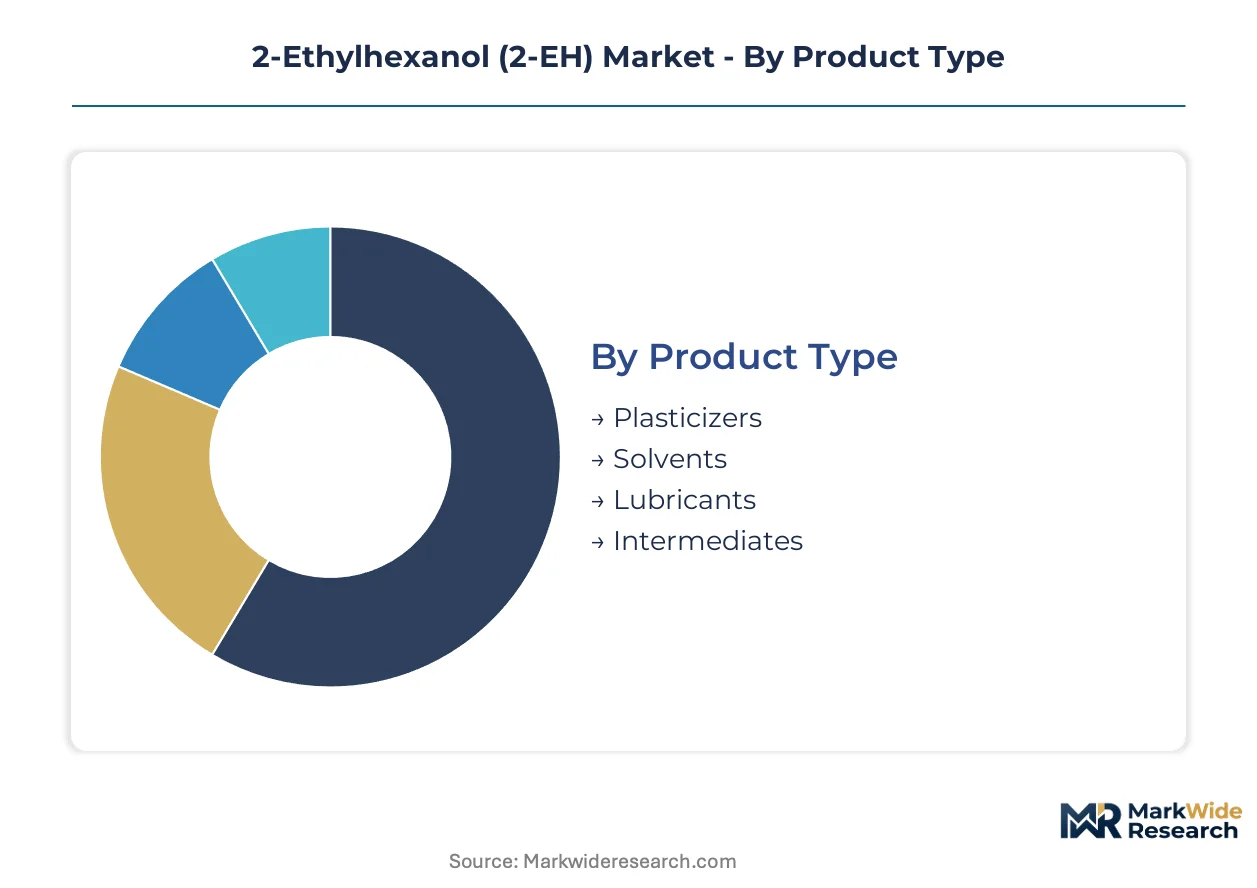
2-Ethylhexanol flows through distinct channel configurations depending on purity certification and end-use technical requirements. Procurement patterns bifurcate between bulk industrial offtake via long-term contracts and specialty-grade spot purchasing tied to regulatory qualification cycles.
Product Type:
Channel mix varies sharply: plasticizers and intermediates move through integrated chemical park pipelines, while solvents and lubricants distribute through regional distributor networks serving fragmented formulation customers.
- Plasticizers:Dominant volume category comprising phthalate and non-phthalate esters for flexible PVC. Demand concentrates in China and Germany as construction chemical clusters scale phthalate alternative production under REACH authorization pressures and China's GB 38508 standards.
- Intermediates:2-EH acrylates and other chemical building blocks. Pressure-sensitive adhesive producers in packaging and textiles are scaling consumption fastest for high-tack formulations, with automotive OEM sustainability scorecards cascading to tier-2 sourcing decisions.
- Solvents:Coating and ink formulation applications. Biobased C8 alcohol from biomass fermentation threatens technical-grade positioning in solvent applications.
- Lubricants:Synthetic ester base stocks and functional additives. Automotive suppliers qualify material against proprietary performance specifications.
By volume, plasticizers leads. By growth pace, intermediates is ahead.
Grade:
Cost tier stratification separates commodity industrial material from certified pharmaceutical and food-grade premiums requiring specialized purification infrastructure.
- Industrial:Standard purity for bulk chemical synthesis. Captures dominant margin pool due to volume scale and integrated refinery-to-chemicals production economics.
- Technical:Enhanced purity for coatings and adhesives with stricter contaminant thresholds. Coating manufacturers in automotive and industrial applications are adopting compact membrane separation units to achieve pharmaceutical-grade purity without centralized refinery economics.
- Pharmaceutical:USP monograph compliance for excipient applications. Commands premium pricing from stringent documentation requirements and opens premium tiers in drug formulation supply chains.
- Food Grade:Regulatory compliance for indirect food contact applications. Subject to FDA and EFSA safety evaluations.
Industrial grade dominates absolute tonnage. Pharmaceutical grade achieves the steepest price premiums per kilogram.
Application:
Customer type fragmentation drives specification divergence: automotive OEMs enforce sustainability scorecards while textile coaters prioritize tack performance and drying speed.
- Coatings:Architectural and industrial protective finishes. REACH substance evaluation tightening hazard communication requirements forces downstream formulators to document exposure scenarios.
- Adhesives:Pressure-sensitive and structural bonding formulations. ECHA's systematic evaluation of reproductive toxicity endpoints accelerates migration to certified low-impurity grades.
- Automotive:Interior trim, underhood components, and sealants. OEM sustainability scorecards cascade to plasticizer tier-2 sourcing, displacing spot-market purchasing with long-term offtake agreements.
- Textile:Fabric coatings and finishing treatments. Expanding most quickly in Asia-Pacific packaging applications.
Coatings commands the largest absolute volume. Textile applications are climbing the fastest on packaging sector expansion.
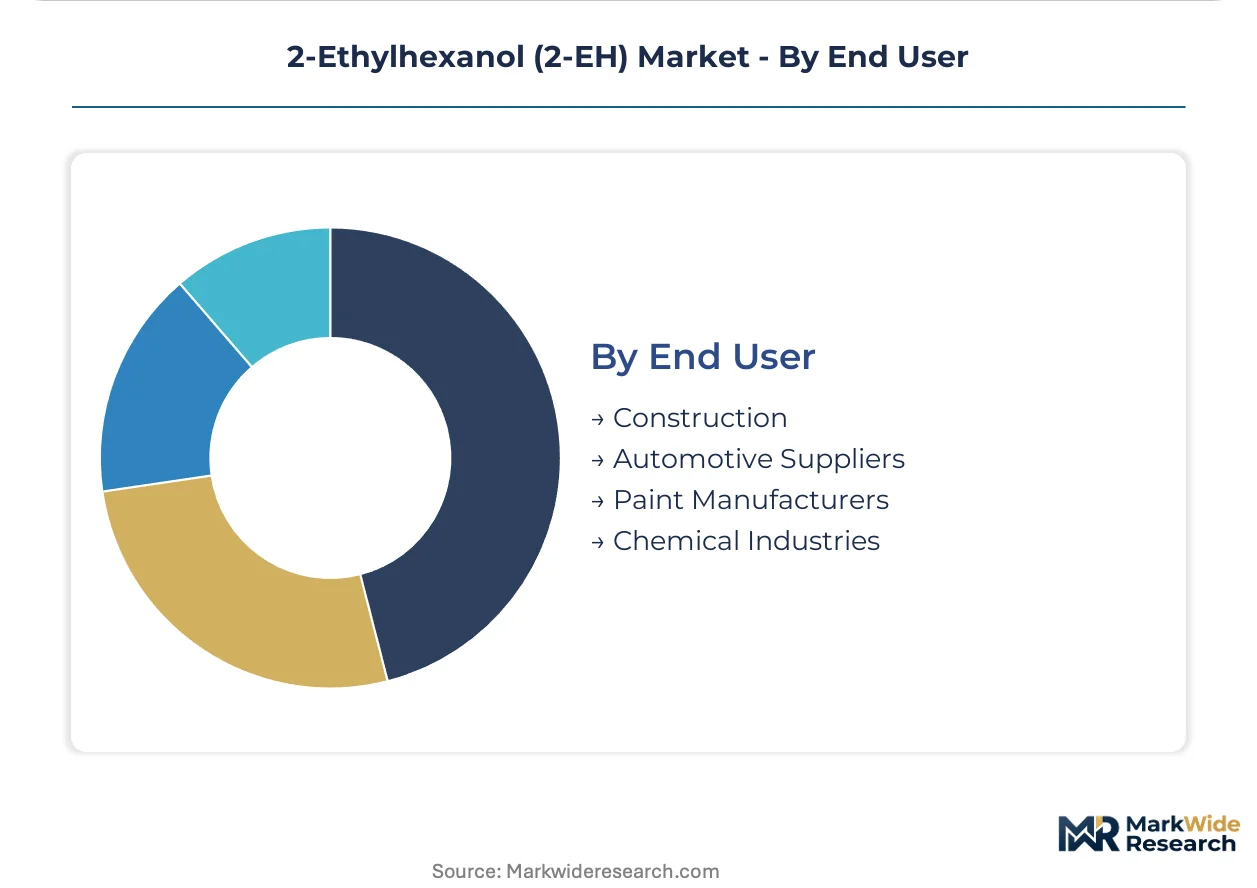
End User:
Supply concentration varies by vertical: construction chemicals cluster in chemical parks while paint manufacturers distribute through regional blending facilities.
- Construction:Flexible PVC for flooring, roofing, and cable sheathing. Chemical parks in China and Germany concentrate downstream plasticizer capacity, anchoring regional 2-EH offtake.
- Automotive Suppliers:Interior and exterior component manufacturers. Large construction chemical distributors in Western Europe now require Scope 1-3 emissions disclosures for procurement decisions.
- Paint Manufacturers:Architectural and industrial coating formulators. Subject to China's MEE GB standards for volatile organic compound emissions.
- Chemical Industries:Captive consumption for downstream derivative production. State-backed refining complexes control disproportionate export volumes.
Construction leads in tonnage absorption. Automotive suppliers are gaining share fastest on electrification-driven interior material redesigns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and the United States absorb price premiums for pharmaceutical-grade certification without volume elasticity, while Chinese construction chemical purchasers negotiate aggressively on industrial-grade tonnage.
China
State-backed refining-to-chemicals complexes in Nanjing and Ningbo dominate 2-EH supply, feeding downstream phthalate alternative production. MEE enforcement of GB standards for volatile organic compound emissions forces continuous plant upgrade cycles. The Yangtze River Delta chemical parks concentrate plasticizer capacity expansion under REACH-equivalent domestic substitution mandates.
Germany
Automotive OEM sustainability scorecards cascade to tier-2 plasticizer sourcing, creating captive demand for low-carbon-intensity grades. ECHA substance evaluation under REACH authorization protocols tightens hazard communication for C8 alcohols in consumer-facing applications. The BASF Ludwigshafen complex anchors European supply through integrated C4 value chain economics.
United States
Flexible PVC construction demand concentrates in the Gulf Coast chemical corridor, with buyers qualifying alternative suppliers amid propylene feedstock volatility. EPA oversight under TSCA governs manufacturing emissions and worker exposure limits at Texas and Louisiana production hubs. Dow's Gulf Coast propylene infrastructure secures regional supply continuity against import disruption.
India
PLI scheme incentives accelerate domestic plasticizer capacity builds, creating captive 2-EH demand outside established Asian trade flows. CDSCO pharmaceutical-grade requirements open premium pricing tiers for USP monograph compliance in excipient applications. Gujarat and Maharashtra chemical clusters scale phthalate alternative production for construction and automotive verticals.
Saudi Arabia
SABIC's Yanbu and Jubail complexes leverage feedstock cost advantages from integrated petrochemical economics, exporting technical-grade material to coating and adhesive buyers in Europe and Asia. SFDA pharmaceutical-grade standards align with Gulf Cooperation Council harmonization efforts. The Eastern Province refining corridor concentrates C4 derivative capacity expansion.
2-Ethylhexanol (2-EH) Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with European specialists commanding premium-grade certification and Asian state-backed complexes dominating industrial-scale tonnage. The market structures around three tiers: integrated petrochemical majors with captive feedstock, regional specialists with purification technology advantages, and emerging low-carbon producers with bio-propylene or carbon-capture routes. Dominant competitive moves include backward integration into propylene supply and portfolio diversification toward pharmaceutical-grade certification.
Among European-based chemical majors, BASF SE and INEOS exemplify the integrated archetype through C4 value chain control, while OQ Chemicals GmbH occupies a position within the specialty-grade tier. SINOPEC and SABIC anchor the scale-driven end through state-backed refining integration, with LG Chem representing the Asian specialist model. These five entities collectively illustrate the geographic and technological bifurcation shaping procurement qualification protocols.
| Leading Market Players |
|---|
| SABIC |
| INEOS |
| BASF SE |
| OQ Chemicals GmbH |
| LG Chem |
| Dow |
| Mitsubishi Chemical Corporation |
| SINOPEC |
| Eastman Chemical Company |
| Others |
Value Chain & Pricing Dynamics
Sixty-day inventory cycles at European coating distributors signal supply-chain rigidity that amplifies pricing power for integrated propylene producers while squeezing margin flexibility at non-integrated 2-EH converters.
Pricing Analysis
After-sales service contracts for technical-grade purification and regulatory documentation drive lifetime value beyond base chemical sales. Three-tier pricing structure across pharmaceutical, technical, and industrial grade levels captures value from certification intensity rather than volume alone. Cost compression in technical-grade material is intensifying because membrane separation miniaturization erodes centralized refinery scale advantages. Construction chemical buyers in China exhibit highest price sensitivity, while automotive OEM sustainability procurement officers in Germany absorb premiums without volume elasticity.
Supply Chain Analysis
Inventory cycles stretching sixty days at European distributors expose just-in-time fragility across the 2-EH value chain. Supply concentrates in China, Germany, and Saudi Arabia through state-backed refining complexes and integrated C4 derivative hubs. Propylene feedstock draws from naphtha crackers, shale gas steam crackers, and refinery fluid catalytic cracking units. Single-source vulnerability from Chinese state-backed export concentration exposes buyers to qualification disruption. Distribution runs through chemical park pipeline networks for plasticizer offtake, with spot-market distributor channels serving fragmented coating and adhesive formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
2-Ethylhexanol demand tracks construction and automotive cycles, with recovery momentum tied to China's chemical park capacity expansion and Germany's automotive interior material redesign programs.
For Market Incumbents: Fortify backward integration into propylene supply to offset feedstock volatility compression at non-integrated competitors. Invest in pharmaceutical-grade USP monograph certification to capture premium pricing tiers as CDSCO and SFDA standards harmonize. Prioritize carbon-intensity disclosure infrastructure to meet Scope 1-3 reporting mandates from Western European construction chemical distributors. For New Entrants and Emerging Players: Technical-grade membrane purification services represent an under-served layer where incumbents lack distributed unit deployment expertise. Target Indian chemical clusters scaling phthalate alternative production under PLI scheme incentives. Pursue joint venture structures with state-backed refining complexes to secure captive offtake without greenfield capital intensity. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because specialty-grade certification barriers and regulatory compliance burdens favor scaled operators with dedicated quality infrastructure. Acquire regional specialists with purification technology advantages and established REACH-TSCA-China MEE multi-jurisdiction registration portfolios. Monitor biobased C8 alcohol cost curves as inflection signal for technical-grade substitution risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive propylene supply from Gulf Coast or European C4 crackers insulates margin from naphtha volatility. |
| Pharmaceutical-Grade Certification | USP monograph compliance opens premium tiers in CDSCO-regulated excipient supply chains. |
| Carbon Accounting Integration | Verified low-carbon production routes satisfy EU Green Deal embodied carbon tracking for automotive OEM scorecards. |
| Membrane Separation Deployment | Modular purification units compress scale advantages of centralized petrochemical complexes in coating applications. |
| Long-term Supply Agreement | Contractual offtake with Yangtze River Delta chemical parks locks volume ahead of Indian capacity builds. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of trade customs data, SEC 10-K chemical segment disclosures, and ECHA REACH registration databases. Plant managers at European and Gulf Coast production facilities, procurement leads at downstream plasticizer and adhesive OEMs, distribution channel partners serving coating formulators, and technical R&D directors specializing in aldol condensation catalysis provided operational perspective. Bottom-up capacity and utilization estimates triangulate against top-down consumption models derived from derivative production volumes.
Segmentation dimensions modeled span grade tier, end-use industry, and regional production hub concentration across the projection horizon. CAGRs derive from elasticity-adjusted demand projections for plasticizer and acrylate intermediate offtake, with propylene feedstock cost curves and regulatory compliance cost burdens as primary forecast inputs.
Underlying assumptions cover sustained construction chemical demand in China and India, automotive interior material redesign cadence, and REACH authorization timeline execution, with deviation risk concentrated in biobased C8 alcohol substitution rates and propylene feedstock cost volatility. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Fischer-Tropsch (FT) Wax Market
Industrial Chemicals
Global Antifreeze Market
Industrial Chemicals
Quenching Fluids and Salts Market
Industrial Chemicals
Liquid Electrolyte Market
Industrial Chemicals
Electro-Erosion Fluids Market
Industrial Chemicals
India Thermic Fluid Market
Industrial Chemicals
Machine Tool Oils Market
Industrial Chemicals
Dynamite Market
Industrial Chemicals
Global CMP Slurry Market
Industrial Chemicals
Pressure Filter Market
Industrial Chemicals
Tallow Fatty Acid Market
Industrial Chemicals
Formaldehyde Market
Industrial Chemicals
Deoiler Chemicals Market
Industrial Chemicals
Wood Vinegar Market
Industrial Chemicals
6-KT Mother Liquor Market
Industrial Chemicals
Process Fluid Market