
 Europe Molecular Sieve Market | 2026-2036
Europe Molecular Sieve Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Molecular Sieve Market Foresight
German synthetic zeolite producers is rebalancing capacity toward higher-grade lithium-exchanged variants for battery electrolyte drying. BASF SE leverages its Ludwigshafen integrated site to sustain captive supply chains for petrochemical clients. Arkema Group competes through fluoropolymer-molecular sieve hybrid membranes for aggressive chemical separations. Clariant anchors its position in pharmaceutical-grade desiccants via FDA-inspected Swiss manufacturing.
Europe molecular sieves are crystalline aluminosilicates with uniform pore diameters typically ranging from 3 to 10 angstroms, synthesized through hydrothermal crystallization of alkali metal aluminosilicate gels and subsequently ion-exchanged to tune selectivity for specific molecular dimensions. These microporous solids function primarily as selective adsorbents, catalysts, and ion-exchange media across process industries where molecular-level separation precision determines product purity and energy efficiency. Sodium-type zeolites dominate volume consumption in natural gas dehydration and air separation units across Northwest Europe's refining corridor. Potassium-exchanged variants represent the fastest-growing product category, driven by demand from pharmaceutical manufacturers requiring ultra-low moisture environments for active ingredient stability. Gas drying applications command the largest margin pools due to stringent moisture specifications in ethylene and propylene pipeline transmission.
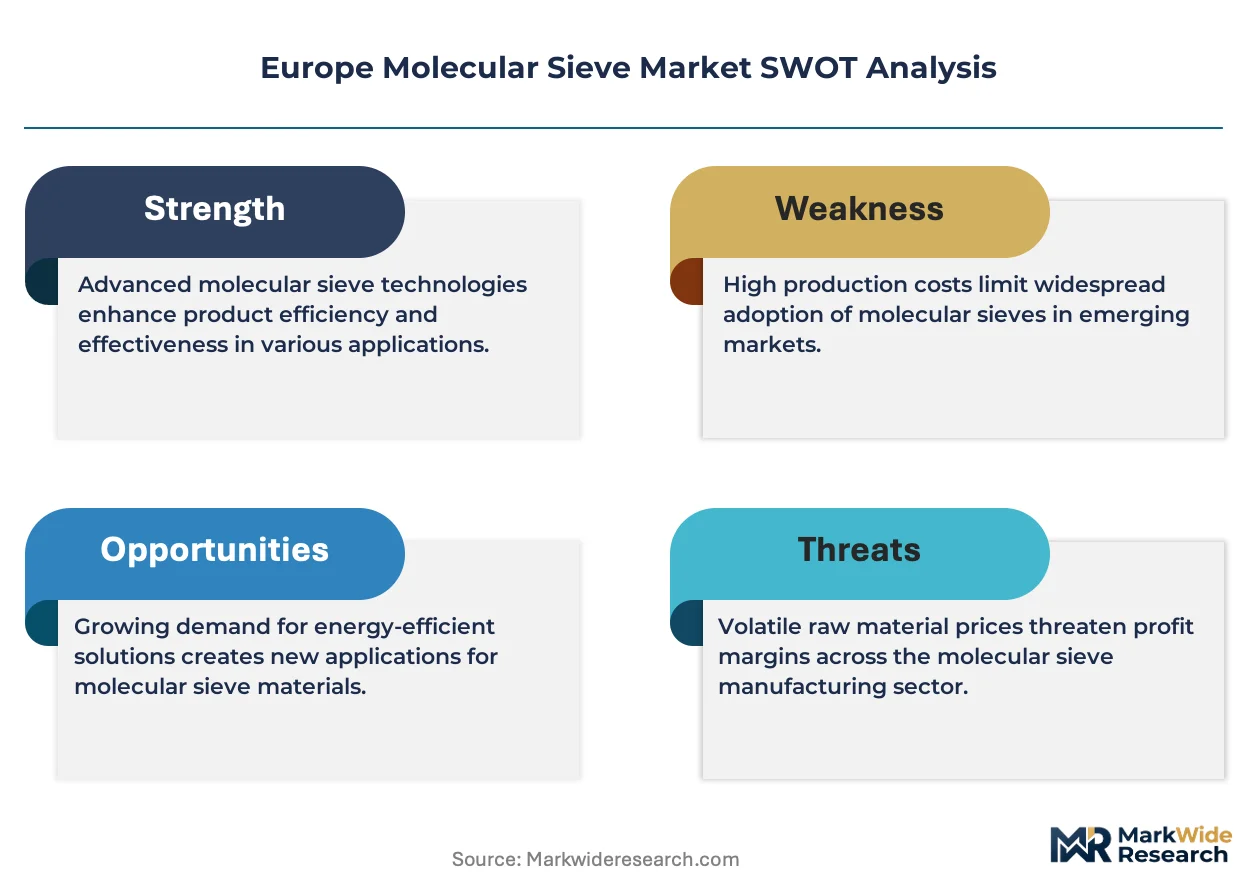
REACH registration requirements and the EU F-Gas Regulation are reshaping specifications for refrigerant dehydration media, forcing reformulation away from certain synthetic zeolite binders. ECHA's persistent scrutiny of crystalline silica classifications adds compliance costs for extruded and pelletized product formats. The EU Green Deal's industrial decarbonization targets are redirecting R&D investment toward energy-efficient pressure-swing adsorption cycles. Stakeholders must monitor how the EU AI Act's predictive maintenance mandates for critical infrastructure could accelerate smart desiccant bed monitoring adoption.
Market Dynamics
EU Green Deal decarbonization mandates are redirecting molecular sieve R&D toward energy-efficient pressure-swing adsorption cycles, compressing payback periods for refinery upgrades while tightening purity specifications for industrial desiccants.
Growth Catalysts
- REACH compliance tightening:Stricter purity standards for crystalline silica classifications are forcing reformulation of extruded zeolite formats, creating replacement demand for compliant alternatives.
- Battery electrolyte drying:German synthetic zeolite producers are expanding lithium-exchanged variant capacity to serve electric vehicle battery manufacturing clusters.
- Northwest Europe refining corridor:Petrochemical expansions across Germany and the Netherlands are adding adsorption capacity for natural gas dehydration and olefin pipeline transmission.
Market Restraints
- Alkali metal input volatility:Sodium and potassium carbonate prices fluctuate with energy-intensive chlor-alkali production economics, squeezing margin stability for ion-exchange operations.
- ECHA crystalline silica scrutiny:Persistent reclassification risk for synthetic zeolite dust exposure adds compliance insurance and workplace monitoring costs.
- Fluoropolymer hybrid substitution:Aggressive chemical separation applications face displacement from membrane technologies in select pharmaceutical and specialty chemical streams.
Strategic Opportunities
- EU AI Act predictive maintenance:Mandates for critical infrastructure monitoring create openings for smart desiccant bed sensor integration and digital twin deployment.
- Pharmaceutical-grade desiccants:FDA-inspected Swiss manufacturing anchors serve as a template for expanding GMP-certified capacity into Eastern European markets.
- F-Gas Regulation refrigerant reformulation:Binding phase-down schedules for hydrofluorocarbons force dehydration media replacement in commercial cooling systems.
Industry Challenges
- Hydrothermal crystallization expertise:Specialized reactor operations and seed crystal preparation require skilled technicians that chemical engineering programs are not producing at sufficient rates.
- Integrated site reconfiguration:Captive supply chain restructuring at Ludwigshafen-scale complexes demands multi-year capital allocation against uncertain demand curves.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Molecular Sieve Market |
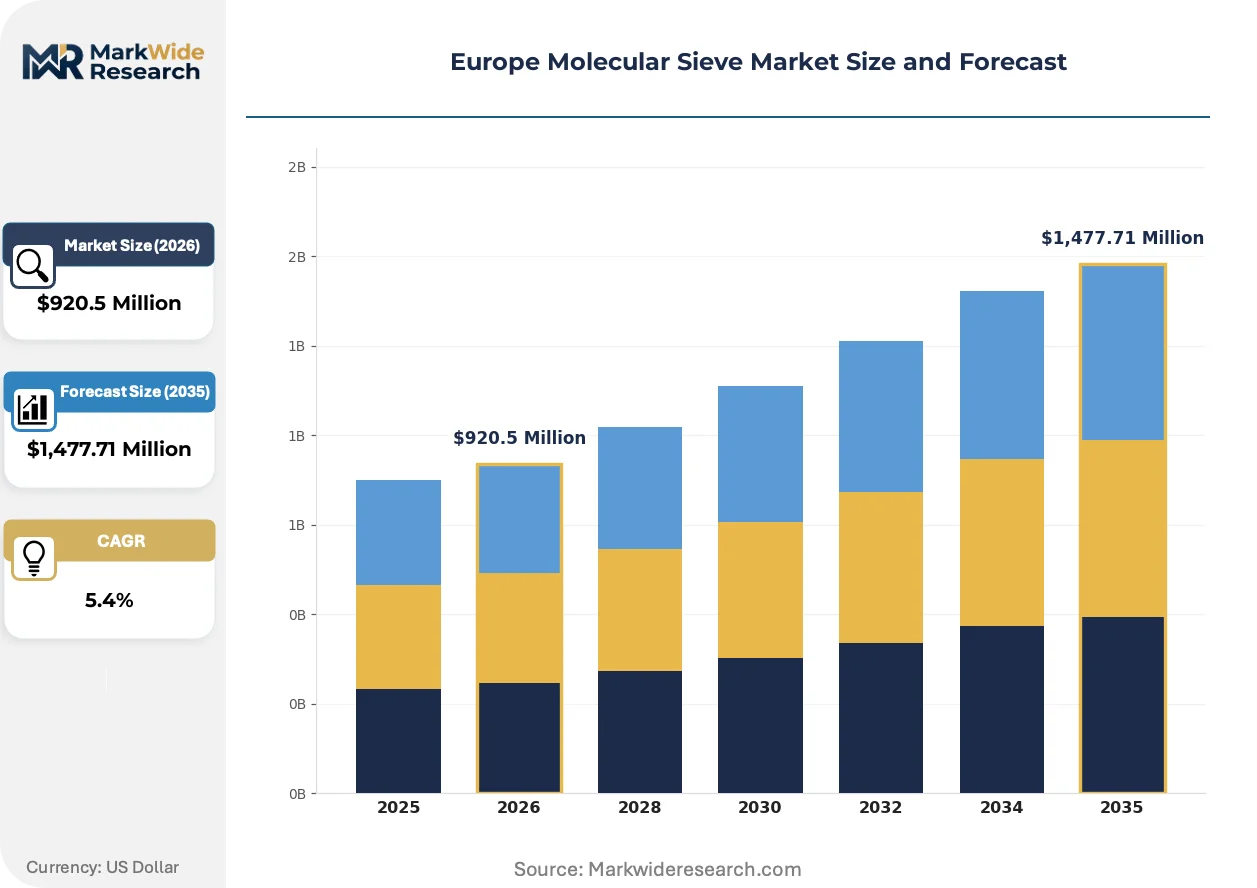
| Market Size in 2026 | $920.5 Million |
| Market Size in 2035 | $1,477.71 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sodium, Calcium, Potassium, Magnesium Application: Adsorption, Catalytic Cracking, Gas Drying, Air Separation End User: Chemicals, Oil & Gas, Pharmaceuticals, Food & Beverage Technology: Extrusion, Pelletizing, Granulation, Coating |
| Companies Covered | Honeywell International Inc, Arkema Group, BASF SE, W. R. Grace & Co.-Conn., Clariant, Tosoh Corporation, Axens, Cabot Corporation, Zeochem, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Molecular Sieve Market Shifts & Advancements
Pressure-swing adsorption cycle optimization and ion-exchange selectivity tuning dominate European molecular sieve innovation, driven by energy cost pressures and end-use purity requirements.
Hybrid fluoropolymer-molecular sieve membrane composites are absorbing aggressive chemical separation workloads previously handled by standalone zeolite beds. Arkema Group and specialty chemical processors in France's Rhône-Alpes cluster are piloting these laminates for corrosive stream applications. The technology is absorbing market share from conventional pelletized configurations in pharmaceutical active ingredient isolation.
EU F-Gas Regulation binding phase-down schedules are forcing refrigerant dehydration media reformulation away from certain synthetic zeolite binder chemistries. Equipment OEMs serving commercial HVAC and industrial cooling must recertify desiccant cartridges for lower-global-warming-potential working fluids. German compressor manufacturers are accelerating qualification timelines for alternative 3A and 4A zeolite formats.
Specification-driven procurement now dominates molecular sieve purchasing for ethylene and propylene pipeline transmission. Dutch and Belgian petrochemical traders are consolidating supplier panels around certified low-dust, high-crush-strength pellet grades. This concentration is visible across Rotterdam-Antwerp-Ghent storage and distribution hubs, where moisture specification non-compliance triggers automatic rejection penalties.
Europe Molecular Sieve Market Segmentation
Molecular sieve purchasing decisions in Europe hinge on ion-exchange selectivity, end-use moisture specifications, and regulatory compliance burdens. Segmentation reveals where capital deployment concentrates and which technical specifications command premium positioning.
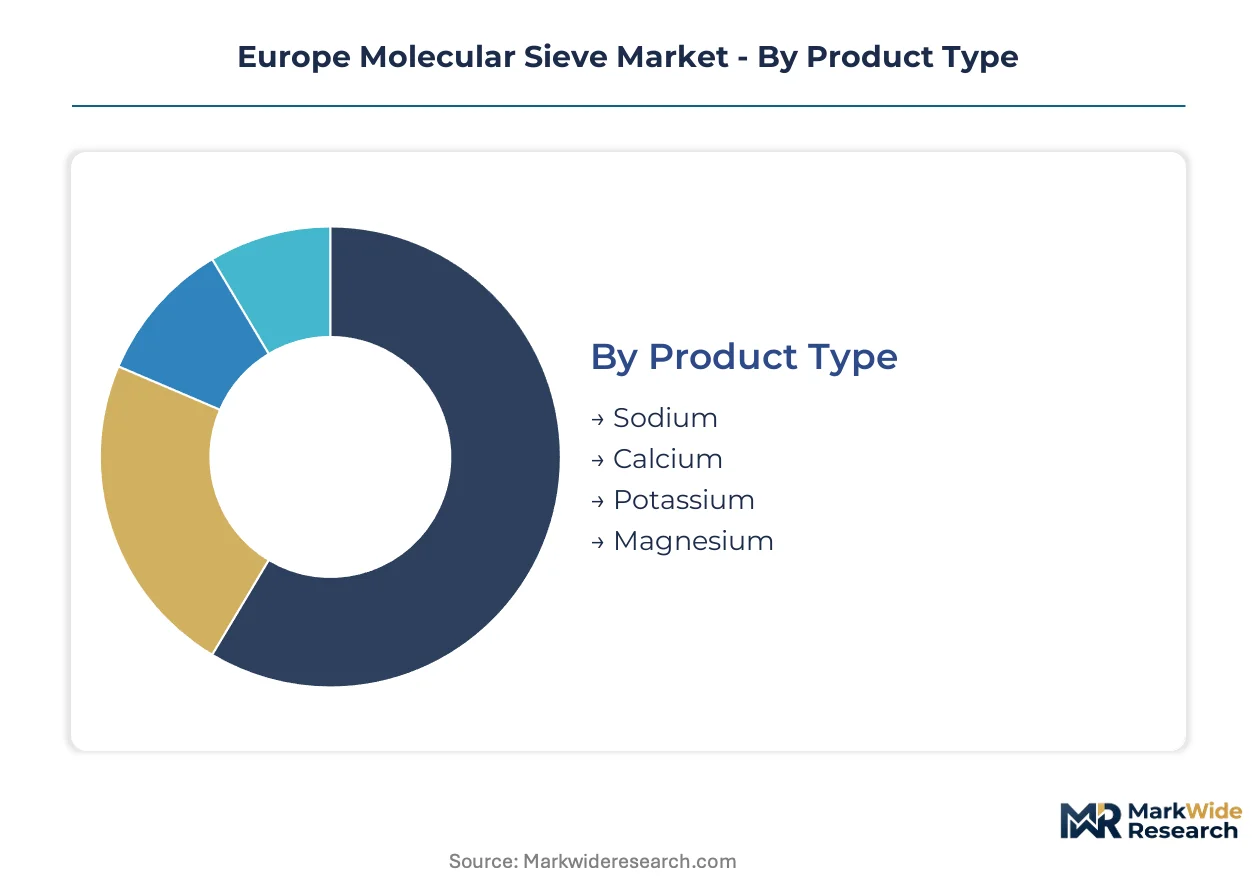
Product Type:
Capital intensity varies sharply across ion-exchange variants, with lithium-exchanged production requiring specialized hydrothermal reactors and extended crystallization cycles.
- Sodium:Standard 4A and 13X zeolites synthesized through conventional alkali aluminosilicate gel crystallization. Natural gas dehydration units across Germany's chemical corridor and Rotterdam-Antwerp refining hubs specify sodium-type for pipeline moisture control, with REACH crystalline silica classifications adding compliance costs to extruded formats.
- Potassium:Ion-exchanged variants with narrowed pore apertures for selective polar molecule capture. Pharmaceutical manufacturers in Switzerland and Eastern Europe require potassium-exchanged grades for ultra-low moisture active ingredient stability, with FDA-inspected capacity anchoring premium supply chains.
- Calcium:Calcium-exchanged 5A zeolites for linear paraffin separation and air separation unit pre-purification. BASF SE's Ludwigshafen complex maintains captive calcium-type capacity for integrated petrochemical operations.
- Magnesium:Specialized variants for aggressive chemical environments and corrosion-resistant applications. Limited production scale concentrates in French Rhône-Alpes specialty chemical clusters.
Most installed capacity flows through Sodium. Expansion is steepest in Potassium.
Application:
Application selection tracks end-use purity thresholds and energy recovery economics, with gas-phase separations dominating volume and liquid-phase catalysis commanding technical premiums.
- Gas Drying:Ethylene and propylene pipeline transmission mandates sub-ppm moisture specifications, with Dutch and Belgian traders imposing automatic rejection penalties for non-compliance. Pressure-swing adsorption cycle optimization is redirecting R&D investment under EU Green Deal decarbonization targets.
- Adsorption:Selective hydrocarbon capture and solvent recovery operations. Northwest Europe petrochemical expansions are adding adsorption capacity for olefin purification, with specification-driven procurement consolidating supplier panels around certified low-dust pellet grades.
- Catalytic Cracking:Fluid catalytic cracking additive applications in refinery operations. Declining European refining throughput is compressing demand for this segment.
- Air Separation:Pre-purification units for cryogenic oxygen and nitrogen production. Energy-intensive operations face margin pressure from electricity cost volatility.
Volume concentrates in Gas Drying. Margin expansion is strongest in Adsorption.
End User:
End-user procurement patterns diverge between specification-driven process industries and cost-optimized commodity applications.
- Oil & Gas:Petrochemical refiners and natural gas processors across Germany and the Netherlands. Expanding adsorption capacity for dehydration and pipeline transmission is tightening purity standards for industrial desiccants.
- Chemicals:Integrated producers with captive molecular sieve operations. BASF SE and Arkema Group leverage backward integration into synthetic zeolite production for supply security.
- Pharmaceuticals:GMP-certified desiccant demand from Swiss and emerging Eastern European manufacturing. Clariant anchors this segment via FDA-inspected Swiss facilities.
- Food & Beverage:Ethanol dehydration and packaging desiccant applications. REACH compliance and food contact material regulations constrain formulation flexibility.
Procurement scale peaks in Oil & Gas. Certification requirements are tightest in Pharmaceuticals.
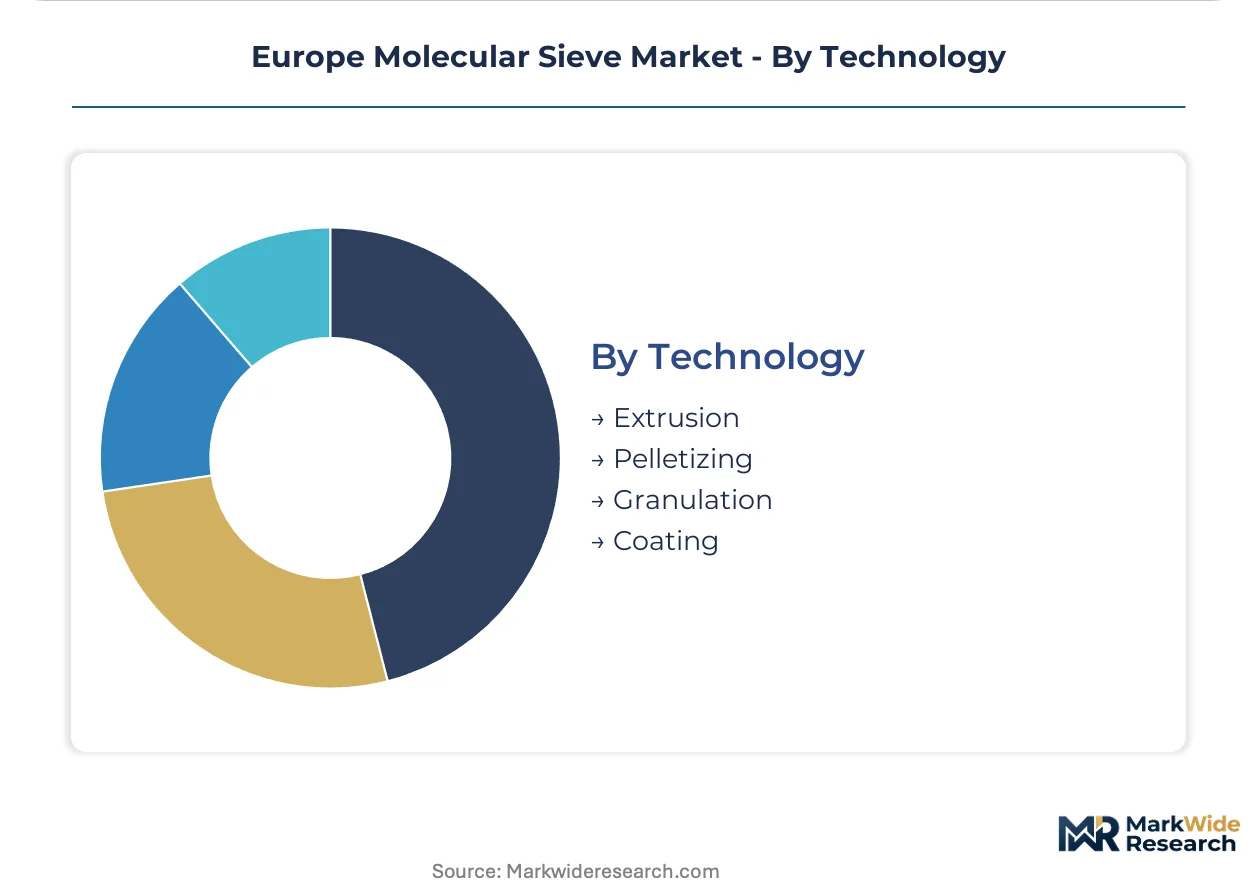
Technology:
Manufacturing technology selection determines dust generation profiles, crush strength specifications, and regulatory compliance pathways.
- Extrusion:Continuous forming of cylindrical pellets with controlled porosity. ECHA crystalline silica scrutiny adds workplace monitoring and insurance costs to extruded product formats.
- Pelletizing:High-pressure compaction of zeolite powder with inorganic binders. Dutch and Belgian petrochemical traders are consolidating supplier panels around certified low-dust, high-crush-strength pellet grades.
- Granulation:Fluid bed agglomeration for irregular particle geometries. Lower capital intensity suits specialty batch production.
- Coating:Thin-film zeolite deposition on ceramic or metal substrates. Hybrid fluoropolymer-molecular sieve membrane composites are piloting in aggressive chemical separation applications.
Volume production runs through Extrusion. Technical differentiation is advancing fastest in Coating.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH compliance cost differentials are redirecting molecular sieve investment toward jurisdictions with streamlined chemical registration pathways. Switzerland and select Eastern European markets attract GMP-certified capacity expansion as German producers absorb ECHA crystalline silica reclassification burdens.
Germany
Petrochemical refiners in the Ludwigshafen chemical corridor expand adsorption capacity for ethylene pipeline dehydration. BASF SE leverages its integrated site to sustain captive synthetic zeolite supply chains under tightening EU Green Deal emissions targets. The Rhine-Neckar metropolitan region concentrates lithium-exchanged variant production for battery electrolyte drying applications.
Netherlands
Rotterdam-Antwerp storage hubs enforce automatic rejection penalties for moisture non-compliance in olefin transmission. Dutch traders consolidate supplier panels around certified low-dust pellet grades. The Port of Rotterdam industrial cluster anchors specification-driven procurement for natural gas dehydration units serving Northwest Europe refining.
Switzerland
Pharmaceutical manufacturers demand ultra-low moisture environments for active ingredient stability. FDA-inspected manufacturing anchors premium desiccant supply chains under Swissmedic oversight. The Basel pharmaceutical cluster sustains Clariant's GMP-certified capacity for global drug stability applications.
France
The Rhône-Alpes specialty chemical cluster pilots hybrid fluoropolymer-molecular sieve membrane composites for aggressive separations. Arkema Group operates integrated production facilities competing through corrosion-resistant formats. Auvergne-Rhône-Alpes concentrates coating technology R&D under EU F-Gas Regulation refrigerant reformulation mandates.
Belgium
Antwerp-Ghent petrochemical traders impose stringent crush-strength specifications on molecular sieve procurement. The Flemish chemical cluster processes specification-driven demand for ethylene and propylene pipeline transmission. ECHA REACH registrations add compliance costs to extruded product formats crossing Belgian distribution hubs.
Europe Molecular Sieve Market Competitive Landscape
German producers anchor the integrated-tier segment; Swiss and French specialists hold premium certification positions. The vendor base concentrates around three strategic archetypes: captive chemical conglomerates with backward integration into zeolite synthesis, standalone desiccant specialists with FDA-inspected pharmaceutical capacity, and membrane technology hybridizers. Dominant competitive moves include hydrothermal reactor capacity expansion and strategic partnerships for smart desiccant bed sensor integration under EU AI Act predictive maintenance mandates.
Among Germany-based chemical conglomerates, BASF SE exemplifies the integrated production archetype through its Ludwigshafen complex operations. Arkema Group occupies a position within the specialty membrane tier, representing French Rhône-Alpes technology hybridization. Clariant anchors the pharmaceutical-grade certification segment through Swiss-based GMP manufacturing. These three entities collectively illustrate how geographic concentration, regulatory compliance depth, and end-use specialization stratify competitive positioning across the European molecular sieve landscape.
| Leading Market Players |
|---|
| Honeywell International Inc |
| Arkema Group |
| BASF SE |
| W. R. Grace & Co.-Conn. |
| Clariant |
| Tosoh Corporation |
| Axens |
| Cabot Corporation |
| Zeochem |
| Others |
Supply & Pricing Matrix
Specification-driven procurement for ethylene and propylene pipeline transmission is compressing supplier margins and forcing consolidation around certified low-dust pellet grades. Dutch and Belgian petrochemical traders now impose automatic rejection penalties for moisture non-compliance, redirecting supply chain investment toward REACH-compliant extrusion capacity and ECHA-aligned workplace monitoring systems.
Pricing Analysis
Distributor margins absorb the steepest compression in standard-grade sodium zeolite formats, while direct-to-OEM contracts for pharmaceutical-grade potassium-exchanged variants retain pricing power. Three-tier pricing structure across premium, standard, and economy levels separates FDA-inspected Swiss supply from REACH-compliant German extrusion and commodity-grade Eastern European imports. Price differentiation hinges on certification tier and crush-strength specification, with gas-phase dehydration applications showing least price sensitivity due to pipeline rejection risk. Cost compression in standard 4A and 13X zeolites is intensifying because alkali metal input volatility squeezes ion-exchange operation economics.
Supply Chain Analysis
Freight cost differentials between Rhine barge transport and road haulage are widening procurement spreads for Rotterdam-Antwerp storage hub deliveries. Supply concentrates in Germany, the Netherlands, and Switzerland, with captive production at Ludwigshafen-scale complexes drawing from sodium carbonate and potassium salt feedstocks. Raw material dependencies rest on energy-intensive chlor-alkali production economics for alkali metal inputs and specialized hydrothermal reactor vessels for crystallization. Single-source vulnerability concentrates in lithium-exchanged variant seed crystal preparation, where skilled technician scarcity constrains capacity expansion. Distribution runs through petrochemical trader panels consolidated around certified pellet grades for pipeline transmission applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through energy-efficient pressure-swing adsorption cycle optimization and premium-tier shift toward pharmaceutical-grade certification. Cost-down drivers include smart desiccant bed sensor integration reducing unplanned maintenance spend.
For Market Incumbents: Hedge against fluoropolymer-molecular sieve hybrid membrane displacement by deepening captive supply chain control over lithium-exchanged variant production. Expand hydrothermal reactor capacity in Rhine-Neckar metropolitan region to secure battery electrolyte drying demand from German automotive OEMs. Prioritize EU AI Act predictive maintenance certification for smart desiccant bed monitoring to defend service revenue streams. For New Entrants and Emerging Players: Membrane coating technology for aggressive chemical separations offers the most penetrable white-space entry point, with Rhône-Alpes specialty chemical cluster showing unmet demand for corrosion-resistant formats. Target Eastern European pharmaceutical manufacturing expansion where GMP-certified capacity scarcity creates procurement bottlenecks. Pursue toll-manufacturing partnerships with established hydrothermal crystallization operators to bypass reactor construction lead times. For Investors and Strategic Acquirers: Asymmetric upside sits with membrane technology hybridizers possessing fluoropolymer lamination expertise and FDA-inspected pharmaceutical-grade desiccant specialists with Swissmedic oversight. Long-term viability centers on EU Green Deal compliance depth and REACH registration asset value rather than commodity volume scale. Watch EU F-Gas Regulation refrigerant dehydration media recertification timelines as inflection indicator for equipment OEM demand pull-through.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lithium-Exchanged Zeolite Production | BASF SE's Ludwigshafen complex secures captive supply for battery electrolyte drying demand from German EV manufacturers. |
| Smart Desiccant Bed Sensor Integration | EU AI Act predictive maintenance mandates accelerate digital twin deployment for refinery adsorption unit monitoring. |
| GMP-Certified Capacity Expansion | Clariant's FDA-inspected Swiss facilities anchor premium pharmaceutical desiccant supply chains under Swissmedic oversight. |
| Hybrid Fluoropolymer-Molecular Sieve Membrane Development | Arkema Group pilots corrosion-resistant laminates for aggressive chemical separations in Rhône-Alpes specialty chemical cluster. |
| REACH-Compliant Extrusion Process Reformulation | ECHA crystalline silica scrutiny forces workplace monitoring investment and insurance cost absorption for pelletized product formats. |
Research Methodology
Bottom-up petrochemical refinery modeling reconciled against top-down synthetic zeolite production tracking forms the analytical core. Primary interviews with plant managers at Northwest Europe refining hubs, procurement leads at Dutch olefin traders, technical R&D directors at membrane technology developers, and distribution channel partners for desiccant cartridges combined with secondary validation from ECHA REACH registration databases, Cefic chemical industry reports, customs trade data for alkali metal aluminosilicate imports, and SEC 10-K filings for integrated chemical conglomerates. Triangulation between demand-side capacity expansion announcements and supply-side hydrothermal reactor commissioning data ensures statistical integrity.
Input-output matrices map ion-exchange variant production volumes against end-use application demand across gas drying, adsorption, catalytic cracking, and air separation segments. Segmentation dimensions modeled include product type, application, end user, and technology format across the projection horizon. CAGRs derive from regression analysis of historical capacity utilization rates and forward-looking petrochemical expansion schedules. Industry-specific forecast inputs incorporate EU Green Deal decarbonization target compliance timelines and EU F-Gas Regulation refrigerant phase-down schedules.
The model holds under stable REACH registration pathways and continued EU emissions target enforcement; deviation in ECHA crystalline silica reclassification rulings or alkali metal input cost spikes would shift capacity expansion timelines. Stakeholders should weight assumptions against their own operating context and regulatory compliance burden assessments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Honing Oil Market
Industrial Chemicals
Slimicides Market
Industrial Chemicals
Ethyl Acrylate Market
Industrial Chemicals
Hydrogenated Bisphenol a Market
Industrial Chemicals
1-Octanol Market
Industrial Chemicals
HFO (Hydrofluoro-Olefin) Refrigerants Market
Industrial Chemicals
Sulfur Recovery Technology Market
Industrial Chemicals
Flame-Retardant Phosphate Esters for EV E-Drivetrains Market
Industrial Chemicals
Global N-MDEA Market
Industrial Chemicals
Lithium Hexafluorophosphate Market
Industrial Chemicals
1, 6 Hexanediol Market
Industrial Chemicals
Global Bio Based Isoprene Market
Industrial Chemicals
Explosion Venting Market
Industrial Chemicals
FCCL Coating Machine Market
Industrial Chemicals
Blow Torch Market
Industrial Chemicals
Dewatering Aids Market