
 Heat Treating Market | 2026-2036
Heat Treating Market Size, Share, and Industry Trends Forecast 2026-2036
Heat Treating Market Analysis
North American automotive transmission suppliers is pivoting toward integrated heat treating capabilities to meet OEM durability specifications. Allison Transmission leverages captive vacuum heating operations for precision gear hardening. Ford Motor Company sustains large-scale normalizing and tempering throughput across its powertrain manufacturing network. Dana Corporation differentiates through specialized induction heating lines serving commercial vehicle axle programs.
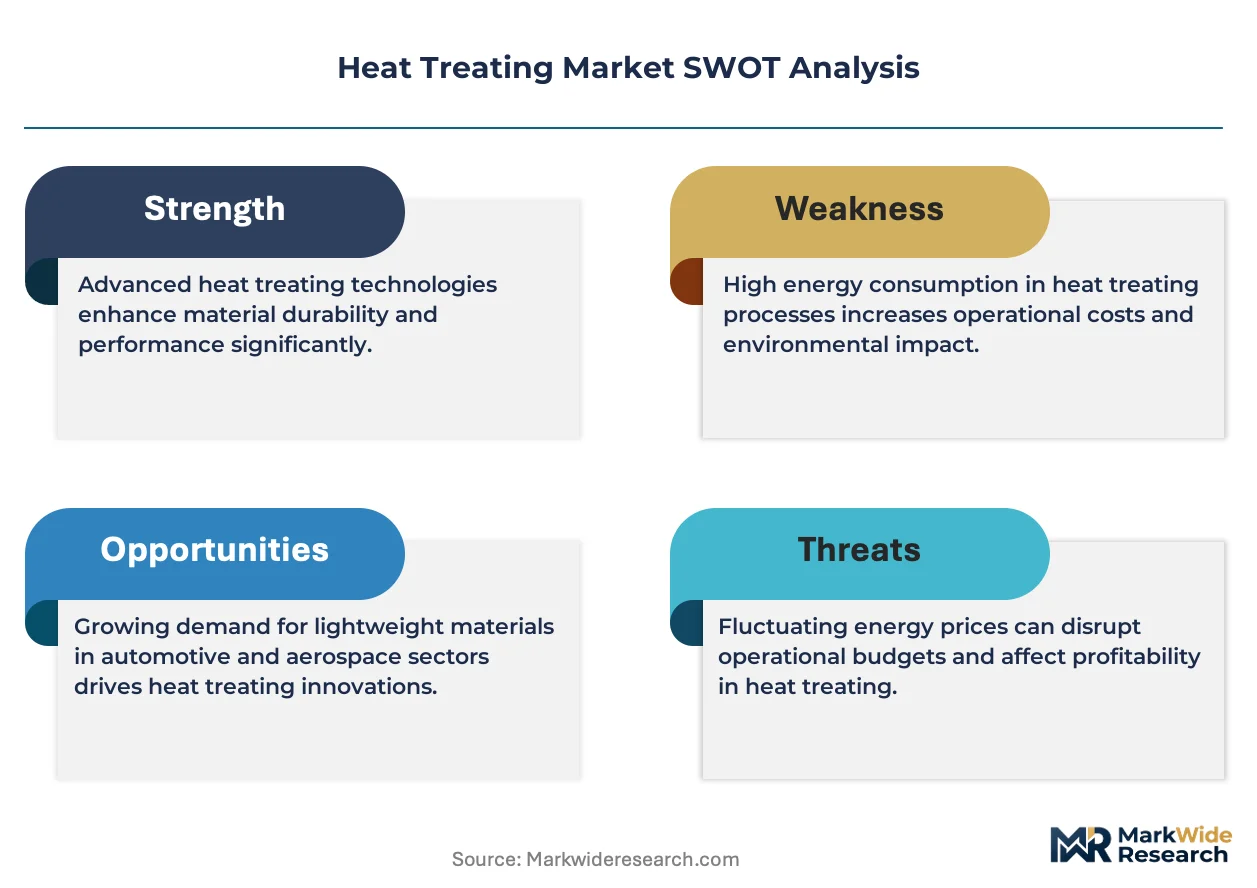
Heat treating alters the microstructure of ferrous and non-ferrous alloys through controlled thermal cycles—typically ranging from 300°C to 1,200°C—to achieve specified hardness, ductility, or wear resistance for finished components. The process serves as a critical intermediate step in producing gears, shafts, cutting tools, and aircraft landing gear rated for cyclic mechanical loading. Vacuum heating commands premium positioning in aerospace and defense end-use segments where oxidation-free surface integrity determines component service life. Induction heating expands fastest in automotive applications driven by throughput requirements for camshaft and crankshaft production. Annealing retains volume leadership across industrial machinery applications where stress relief in welded fabrications remains routine.
EPA emissions standards for combustion-based heating equipment push facilities toward electric resistance and vacuum alternatives with lower atmospheric discharge profiles. NHTSA fuel economy mandates cascade into material strength requirements that only precision-quenched drivetrain components satisfy. EASA certification protocols for aircraft propulsion systems enforce traceable heat treat records for every flight-critical alloy batch. Stakeholders must weigh capital intensity against regulatory exposure when selecting between flame heating retrofit and full vacuum system replacement.
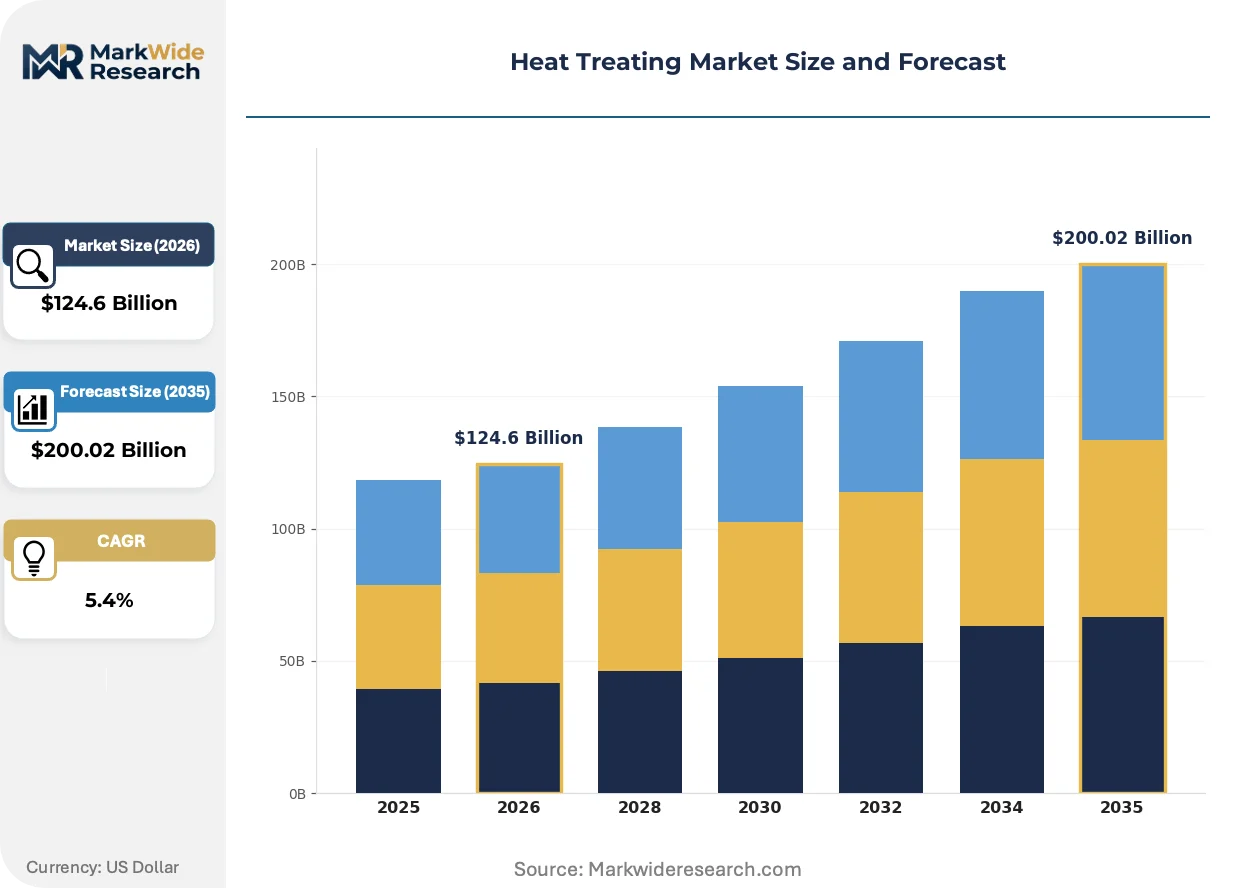
Market Dynamics
Vacuum heating technology is consolidating control over precision component fabrication as EPA emissions standards and EASA airworthiness directives simultaneously compress conventional flame heating economics and elevate traceability requirements for flight-critical alloys.
Growth Catalysts
- MIIT Metallurgical Mandates:China's Ministry of Industry and Information Technology enforces stricter standards for automotive drivetrain suppliers, forcing heat treat upgrades across the eastern industrial corridor.
- EASA Certification Protocols:European Aviation Safety Agency traceability requirements for turbine components drive vacuum system investments among aerospace manufacturers in Germany and France.
- Induction Heating Throughput:Camshaft and crankshaft producers favor electromagnetic heating for cycle-time compression in high-volume powertrain operations.
Market Restraints
- Natural Gas Price Volatility:Combustion-based flame heating facilities face margin compression from input cost swings, accelerating electric resistance migration.
- Vacuum System Capital Intensity:Full replacement of conventional equipment requires eight-figure investments that freeze mid-cap facility modernization timelines.
- Specialized Alloy Supply Concentration:Premium vacuum-grade nickel-based superalloy sourcing clusters in limited smelter networks, creating batch-to-batch variability risk.
Strategic Opportunities
- India Automotive Drivetrain Expansion:Domestic OEMs and tier suppliers lack captive heat treat depth, opening contract service penetration in Pune and Chennai manufacturing clusters.
- Electric Vehicle Motor Laminations:Silicon steel annealing for high-efficiency stator cores represents a process extension opportunity from traditional gear hardening capabilities.
- CE Marking Convergence:EU machinery safety and environmental compliance integration creates bundled certification service demand among export-oriented component fabricators.
Industry Challenges
- Pyrometry and Atmosphere Control Expertise:Vacuum furnace operation demands scarce metallurgical engineering talent, extending commissioning timelines for new installations.
- Legacy Flame System Integration:Hybrid facilities struggle to synchronize batch tracking across discontinuous vacuum and continuous conveyor operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heat Treating Market |
| Market Size in 2026 | $124.6 Billion |
| Market Size in 2035 | $200.02 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Annealing, Normalizing, Quenching, Tempering Technology: Induction Heating, Flame Heating, Resistance Heating, Vacuum Heating End User: Aerospace, Automotive, Defense, Industrial Machinery Application: Tool Manufacturing, Gear Production, Component Fabrication, Surface Hardening |
| Companies Covered | Allison Transmission, John Deere, Ford Motor Company, Dana Corporation, Linamar, JATCO (Japan Automatic Transmission Co., Ltd.), Dauch Corporation, ZF Transmission, GKN Driveline, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heat Treating Market Emerging Trajectories
Process digitization and predictive atmosphere control are redefining competitive differentiation in heat treating, compressing quality variance windows and enabling real-time certification documentation.
Predictive maintenance algorithms embedded in vacuum furnace control systems is expanding into aerospace supplier networks. Tier-one turbine component manufacturers deploy sensor arrays to anticipate heating element degradation and atmosphere leakage before batch contamination occurs. This capability compresses unplanned downtime intervals and sustains EASA-mandated traceability continuity.
EPA emissions standards for combustion-based industrial heating equipment tighten discharge thresholds annually, forcing facility operators toward electric resistance and vacuum alternatives. NHTSA fuel economy mandates cascade into material strength specifications that only precision-quenched drivetrain components satisfy, binding automotive suppliers to upgraded heat treat infrastructure.
After-sales service unbundling accelerates among contract heat treaters serving fragmented industrial machinery end-users. Component manufacturers separate furnace maintenance contracts from per-batch processing fees, shifting risk to equipment specialists. This pattern concentrates in Germany's Mittelstand supplier base, where capital constraints favor operational expenditure models over asset ownership.
Heat Treating Market Segmentation
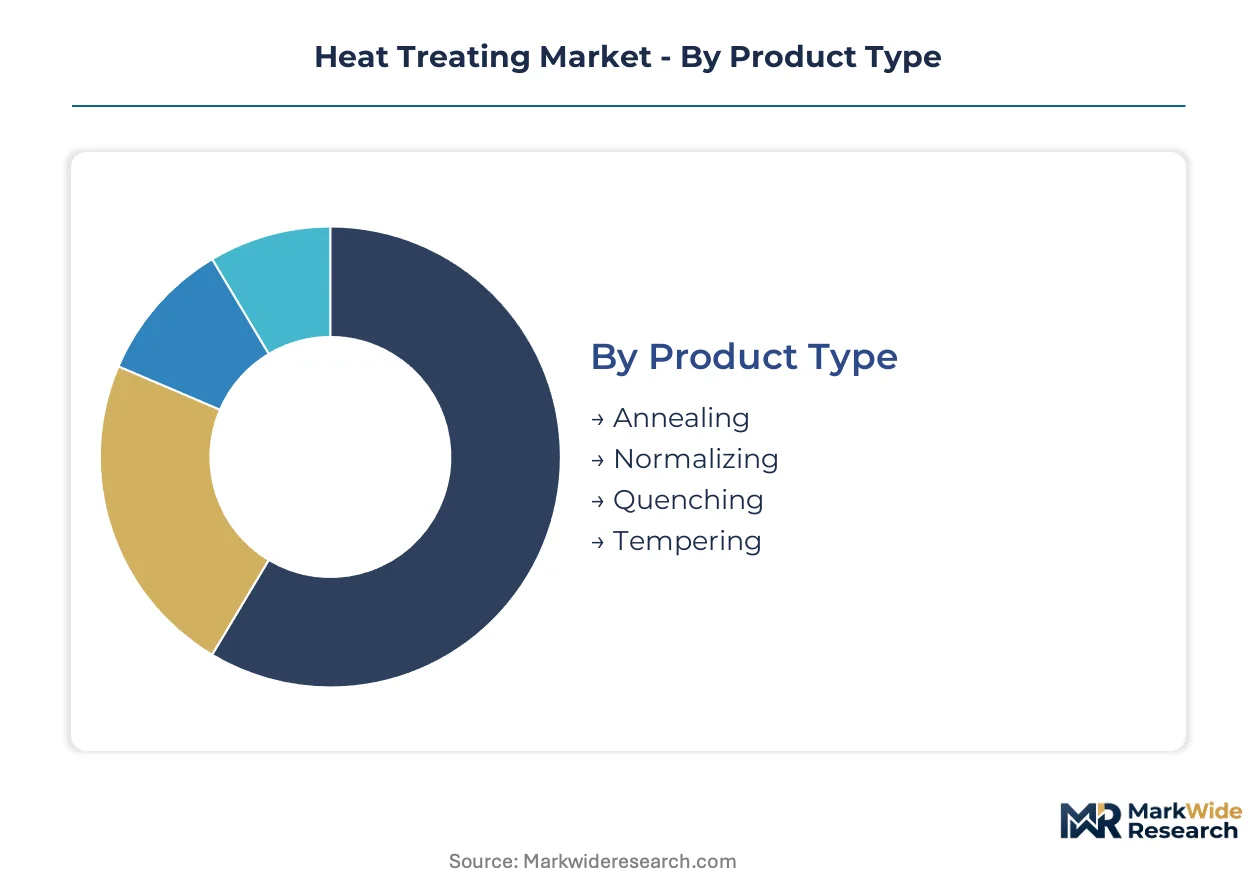
Heat treating service selection hinges on metallurgical outcome requirements, throughput economics, and regulatory traceability mandates. Distinct process technologies and end-use specifications fragment procurement patterns across aerospace certification networks and automotive volume programs.
Product Type:
Component durability specifications and stress-state requirements determine process selection across gear, shaft, and structural fabrication programs.
- Quenching:Rapid cooling from austenitizing temperatures locks martensitic microstructures into high-carbon steels for wear-resistant surfaces. Automotive transmission suppliers in Germany and France specify pressurized gas quenching for precision gear sets under NHTSA durability mandates.
- Tempering:Sub-critical reheating reduces brittleness in quenched components while retaining hardness above specification thresholds. Demand concentrates in aerospace landing gear fabrication where EASA traceability requirements enforce batch-level thermal cycle documentation.
- Annealing:Full furnace cooling softens work-hardened alloys for subsequent machining operations in welded industrial machinery fabrications.
- Normalizing:Air cooling from austenitizing range refines grain structure in heavy-section forgings for construction equipment axle housings.
Annealing leads on scale across routine industrial stress-relief applications; quenching leads on momentum as drivetrain hardness specifications tighten.
Technology:
Capital intensity and atmospheric control precision stratify equipment choices between high-volume automotive lines and aerospace certification cells.
- Vacuum Heating:Oxygen-free environments prevent surface decarburization in nickel-based superalloys for turbine blade fabrication. EASA airworthiness directives in Germany and France mandate vacuum processing for all flight-critical rotating components.
- Induction Heating:Electromagnetic field penetration delivers localized heating with sub-second cycle times for camshaft and crankshaft production. China's eastern industrial corridor favors induction lines for MIIT-mandated drivetrain throughput targets.
- Resistance Heating:Electric element furnaces eliminate combustion emissions for EPA-compliant batch processing of tool steels.
- Flame Heating:Natural gas combustion retains cost advantage for low-specification annealing of structural fabrications despite margin compression from fuel price volatility.
Flame heating leads on installed base across legacy industrial machinery suppliers; vacuum heating gains share fastest where aerospace certification requirements concentrate.
End User:
Quality system rigor and volume predictability shape contract terms between captive heat treat departments and merchant service providers.
- Automotive:Powertrain suppliers operate captive vacuum and induction cells to satisfy OEM durability specifications for transmission gears and axle shafts.
- Aerospace:Turbine component manufacturers in Germany and France expand vacuum furnace capacity under EASA directives requiring full thermal cycle traceability.
- Defense:Armored vehicle and ordnance specifications demand controlled tempering of high-hardness steels with restricted alloy sourcing.
- Industrial Machinery:Welded fabrication stress-relief annealing represents the largest volume category with lowest margin and specification stringency.
Industrial machinery leads on batch count; aerospace leads on revenue per pound processed.
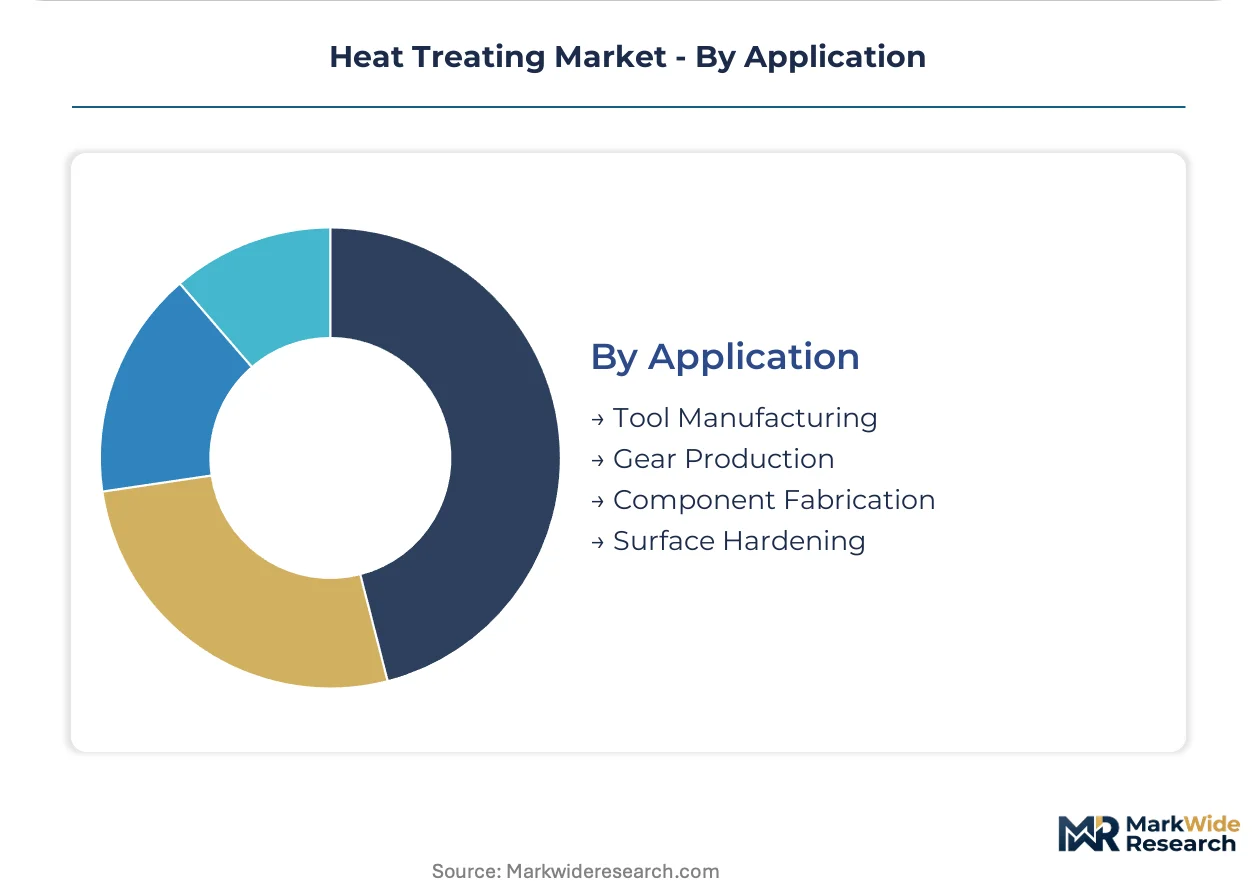
Application:
Surface integrity requirements and geometric complexity determine equipment configuration and atmosphere control investment levels.
- Gear Production:Case hardening and through-hardening of drivetrain components requires precision-controlled carbon potential and quench severity for contact fatigue resistance.
- Surface Hardening:Selective heating of wear surfaces preserves core ductility in crankshaft journals and camshaft lobes for automotive powertrain programs.
- Tool Manufacturing:High-speed steel and carbide cutting tool vacuum hardening demands tight temperature uniformity for edge retention.
- Component Fabrication:General-purpose normalizing and tempering of machined structural parts serves industrial machinery build schedules with minimal specification overhead.
Component fabrication leads on volume breadth; gear production leads on process complexity premium capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Heat treating capacity migrates toward jurisdictions where EPA-level emissions compliance costs remain manageable and aerospace certification infrastructure already exists. Germany and France absorb vacuum furnace investments under EASA directives while China's eastern corridor consolidates automotive throughput.
United States
Automotive powertrain suppliers in Michigan and Ohio operate captive normalizing and tempering lines to satisfy NHTSA fuel economy mandates. EPA emissions standards for combustion-based equipment accelerate electric resistance furnace adoption across the Midwest manufacturing belt. Detroit-area transmission plants integrate vacuum heating cells for precision gear hardening under OEM durability specifications.
Germany
Aerospace turbine manufacturers in Bavaria and Baden-Württemberg expand vacuum furnace capacity for nickel-based superalloy components. EASA airworthiness directives enforce full thermal cycle traceability for all flight-critical rotating parts. The Mittelstand supplier base around Stuttgart favors operational expenditure models over asset ownership for heat treat services.
China
Automotive drivetrain suppliers in Shanghai and Jiangsu province face MIIT-mandated metallurgical upgrades for transmission gear production. The eastern industrial corridor concentrates induction heating lines for camshaft and crankshaft throughput targets. Vacuum technology penetration remains limited to aerospace sub-tier suppliers serving COMAC programs.
India
Domestic OEMs and tier suppliers in Pune and Chennai manufacturing clusters lack captive heat treat depth for transmission and axle components. The country's national automotive regulator enforces stricter material certification for critical drivetrain parts. Contract service providers from Germany and Japan establish technical joint ventures in Maharashtra to capture localized demand.
France
Turbine component fabricators in Île-de-France and Auvergne-Rhône-Alpes regions invest in vacuum heating systems under EASA certification protocols. Safran and sub-tier suppliers expand thermal processing capacity for LEAP engine alloy batches. Lyon-area aerospace clusters drive premium vacuum-grade nickel superalloy consumption for rotating component manufacture.
Heat Treating Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue electric vehicle motor lamination and silicon steel annealing adjacent to traditional gear hardening. The vendor base stratifies across captive automotive powertrain departments, aerospace-certified contract service providers, and merchant heat treaters serving fragmented industrial machinery demand. Three archetypes dominate: integrated OEM transmission suppliers with in-house vacuum cells, aerospace-focused contract specialists with EASA-traceable batch systems, and regional merchant operators handling routine annealing for welded fabrications. Competitive moves concentrate on M&A for geographic coverage and technology licensing for vacuum furnace commissioning.
Among North American automotive transmission suppliers, Allison Transmission, Ford Motor Company, and Dana Corporation exemplify the captive integration archetype. Allison Transmission represents vacuum heating adoption for precision gear hardening within powertrain manufacturing networks. Ford Motor Company anchors large-scale normalizing and tempering throughput across integrated production facilities. Dana Corporation occupies a specialized position in induction heating lines for commercial vehicle axle programs.
| Leading Market Players |
|---|
| Allison Transmission |
| John Deere |
| Ford Motor Company |
| Dana Corporation |
| Linamar |
| JATCO (Japan Automatic Transmission Co., Ltd.) |
| Dauch Corporation |
| ZF Transmission |
| GKN Driveline |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up contract heat treat specialists in Germany's Mittelstand belt have compressed pricing discipline through operational expenditure models that shift asset ownership risk onto equipment financiers. This ownership pattern tightens supply chain responsiveness to EASA certification premiums while feeding back into selective capacity investments that concentrate vacuum furnace availability among aerospace-certified providers.
Pricing Analysis
Distributor margin capture runs through captive automotive powertrain departments that internalize precision gear hardening rather than outsource to merchant providers. Pricing stratifies across EASA-traceable vacuum processing, MIIT-mandated induction throughput, and routine industrial annealing with minimal specification overhead. Cost compression in flame heating tiers is intensifying because natural gas price volatility erodes combustion-based economics against electric resistance alternatives. Tier-one aerospace suppliers exhibit lowest price sensitivity where flight-critical alloy batch documentation commands premium positioning; fragmented machinery fabricators remain most price-sensitive across commoditized stress-relief services.
Supply Chain Analysis
Domestic-content mandates in China's eastern industrial corridor are reshaping sourcing patterns for automotive drivetrain suppliers facing MIIT metallurgical upgrades. Premium vacuum-grade nickel-based superalloy supply draws from limited smelter networks concentrated in Germany, France, and specialized Japanese producers. Batch-to-batch variability risk in specialized alloy sourcing creates single-source vulnerability for aerospace turbine component manufacturers. Distribution runs through technical joint ventures in India's Maharashtra cluster where German and Japanese contract service providers localize capabilities to capture Pune and Chennai manufacturing demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Heat Treating Market reads as a late-cycle quality story where EASA airworthiness directives and MIIT metallurgical mandates simultaneously shift procurement toward vacuum and induction systems with full thermal cycle traceability.
For Market Incumbents: Deploy predictive maintenance algorithms embedded in vacuum furnace control systems to sustain EASA-mandated traceability continuity. Backward integration into specialized alloy sourcing mitigates batch-to-batch variability risk from concentrated smelter networks. Channel control through unbundled after-sales service contracts concentrates risk onto equipment specialists while securing recurring revenue from Germany's Mittelstand supplier base. For New Entrants and Emerging Players: Enter via silicon steel annealing for electric vehicle motor laminations adjacent to traditional gear hardening capabilities. India's Pune and Chennai manufacturing clusters offer the most penetrable geography where domestic OEMs and tier suppliers lack captive heat treat depth for transmission and axle components. A technical joint venture structure with established German or Japanese contract service providers accelerates localized certification credibility. For Investors and Strategic Acquirers: Valuations sit cheapest among regional merchant operators handling routine industrial machinery annealing with minimal specification overhead. Long-term viability hinges on regulatory tailwinds from EPA emissions standards and NHTSA fuel economy mandates that bind automotive suppliers to upgraded heat treat infrastructure. The signal to watch is MIIT enforcement intensity across China's eastern industrial corridor as a proxy for global metallurgical standard convergence.| Strategic Initiative | Industry Significance |
|---|---|
| Vacuum Furnace Capacity Expansion | EASA directives in Germany and France mandate full thermal cycle traceability for flight-critical rotating components. |
| Predictive Atmosphere Control Investment | Sensor arrays anticipate heating element degradation before batch contamination occurs in aerospace supplier networks. |
| Induction Heating Line Deployment | MIIT throughput targets in China's eastern corridor favor electromagnetic heating for camshaft and crankshaft production. |
| Technical Joint Venture Formation | German and Japanese providers establish localized credibility in India's Maharashtra cluster for transmission component processing. |
| After-Sales Service Unbundling | Risk shift to equipment specialists concentrates in capital-constrained Mittelstand suppliers around Stuttgart. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to capture both volume trajectories and operational constraints in thermal processing infrastructure. Primary engagement with vacuum furnace operators, automotive powertrain procurement leads, aerospace supplier quality directors, and metallurgical engineering specialists informed capacity utilization patterns and certification bottlenecks. Secondary validation drew from EPA emissions compliance filings, EASA airworthiness directive documentation, MIIT metallurgical standard releases, and customs data tracking specialized alloy trade flows. Bottom-up facility capacity tallies triangulated against top-down end-use demand segmentation across automotive, aerospace, and industrial machinery applications.
Segment-weighting approaches distributed value and volume across process technology, end-use industry, and geographic regulatory cluster dimensions. Modeled projections incorporated equipment replacement cycles, regulatory enforcement timelines, and OEM durability specification evolution throughout the forecast period. CAGRs derived from regression analysis of historical capital expenditure patterns and announced capacity additions by major vacuum furnace manufacturers. Industry-specific inputs included EASA certification queue lengths, MIIT inspection intensity proxies, and natural gas price volatility indices affecting flame heating economics.
The model holds under steady regulatory enforcement intensity and continued OEM outsourcing of precision heat treat operations; deviation in sovereign industrial policy shifts or breakthrough alternative material adoption would shift capacity investment timing and geographic distribution. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Global Activated Carbon Canisters Market
Industrial Chemicals
Explosive Chargers Market
Industrial Chemicals
Shea Olein Market
Industrial Chemicals
Permethrin Market
Industrial Chemicals
Industrial Biocides Market
Industrial Chemicals
Soap Noodles Market
Industrial Chemicals
Commercial Electronic Detonator Market
Industrial Chemicals
US Anhydrous Hydrogen Fluoride Market
Industrial Chemicals
Mass Finishing Consumables Market
Industrial Chemicals
Gypsum-Free Cement Market
Industrial Chemicals
Chrome Plating Market
Industrial Chemicals
Fireworks and Firecrackers Market
Industrial Chemicals
Fluidized Bed Reactors Market
Industrial Chemicals
Industrial Cyclohexylamine Market
Industrial Chemicals
Foam Market
Industrial Chemicals
Global N-Methyl-2-Pyrrolidone (NMP) Market