
 Aluminium Production Chemicals Market | 2026-2036
Aluminium Production Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Aluminium Production Chemicals Market Outlook
Digital twin integration across smelter operations is rewriting how aluminium producers optimize bath chemistry and energy consumption. BASF SE leverages its catalyst and process chemical portfolio to anchor European smelter modernization programs. Aluminum Corporation of China Limited sustains captive supply advantages through backward integration into cryolite and alumina refining. Evonik Industries AG differentiates via high-purity specialty additives tailored to low-carbon smelting protocols.
Aluminium production chemicals encompass the reagents, fluxes, and process aids employed in Bayer refining, Hall-Héroult electrolysis, and casthouse operations, typically formulated to precise purity thresholds such as minimum 98.5 percent aluminium oxide content in smelter-grade alumina to ensure current efficiency above 94 percent in reduction cells. Their primary purpose centers on lowering energy intensity, controlling impurities, and extending pot life in primary metal output. Cryolite and alumina formulations dominate volume flows, with cryolite experiencing renewed supply pressure as synthetic production capacity tightens against natural mineral depletion. Water treatment applications within smelter circuits represent a faster-growing demand pocket, driven by zero-liquid-discharge mandates and rising process water recycling ratios. Granular and powder forms retain preference for bath chemistry control, though liquid delivery systems are gaining traction in automated dosing installations.
The EU F-Gas Regulation and China's MEE emissions standards are jointly elevating demand for fluorine-efficient bath chemistries and alternative flux systems with lower perfluorocarbon generation profiles. EPA oversight of US smelter fluoride emissions reinforces product certification requirements for chemical suppliers seeking North American market access. ISO 14001-aligned environmental management systems are becoming baseline qualifiers in procurement frameworks across major primary producers. Stakeholders must now weigh capital allocation between conventional bath chemistry optimization and emerging inert anode technologies that could structurally alter chemical demand profiles.
Market Dynamics
Digital twin deployment across smelter operations is compressing optimization cycles for bath chemistry and energy efficiency, forcing chemical suppliers to embed real-time dosing algorithms into their service models.
Growth Catalysts
- Automotive lightweighting mandates:OEM substitution programs in Germany, Japan, and the United States are pulling high-purity aluminium alloys into chassis and powertrain components, expanding cryolite and alumina demand from tier-one casthouses.
- EU F-Gas Regulation:Fluorine emission caps are accelerating adoption of low-PFC bath chemistries across Dutch and Norwegian smelters, creating premium product tiers for compliant chemical formulations.
- GCC capacity expansion:Saudi Arabia and the UAE are integrating captive chemical supply chains into new primary aluminium megaprojects, concentrating regional procurement volumes.
Market Restraints
- Synthetic cryolite supply tightness:Natural cryolite depletion in Greenland is forcing reliance on fluorite-derived production, exposing smelters to acid-grade fluorspar price volatility from Chinese export quotas.
- Smelter-grade alumina concentration:Four integrated producers control over 70 percent of Atlantic basin refining capacity, creating single-source risk for European and North American reduction cell operators.
- Inert anode development timelines:Rio Tinto and Alcoa pilot programs suggest commercial deployment remains 8-12 years distant, delaying structural demand shifts away from conventional bath chemicals.
Strategic Opportunities
- Indonesia's smelter buildout:The country's nickel-aluminium industrial corridor is greenfield territory for chemical suppliers lacking established relationships with Chinese or Gulf incumbents.
- Zero-liquid-discharge mandates:China's MEE standards are forcing smelters to close process water loops, opening demand for specialized flocculants and membrane treatment chemicals in Shanxi and Shandong provinces.
- Carbon border adjustment mechanisms:The EU CBAM is incentivizing low-carbon smelter certifications, creating attach rates for traceability-verified chemical inputs in premium metal segments.
Industry Challenges
- Electrochemical process engineering talent:The retirement wave of Hall-Héroult specialists is outpacing university training programs, narrowing the pool of technicians capable of diagnosing cell instability from bath chemistry deviations.
- ISO 14001 certification timelines:Major primary producers are requiring 18-24 month environmental management system audits before approving new chemical suppliers, extending sales cycles for mid-tier entrants.
- Legacy SCADA integration:Automated dosing systems must interface with 1990s-era pot control architectures, forcing costly middleware development for digital chemistry offerings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aluminium Production Chemicals Market |
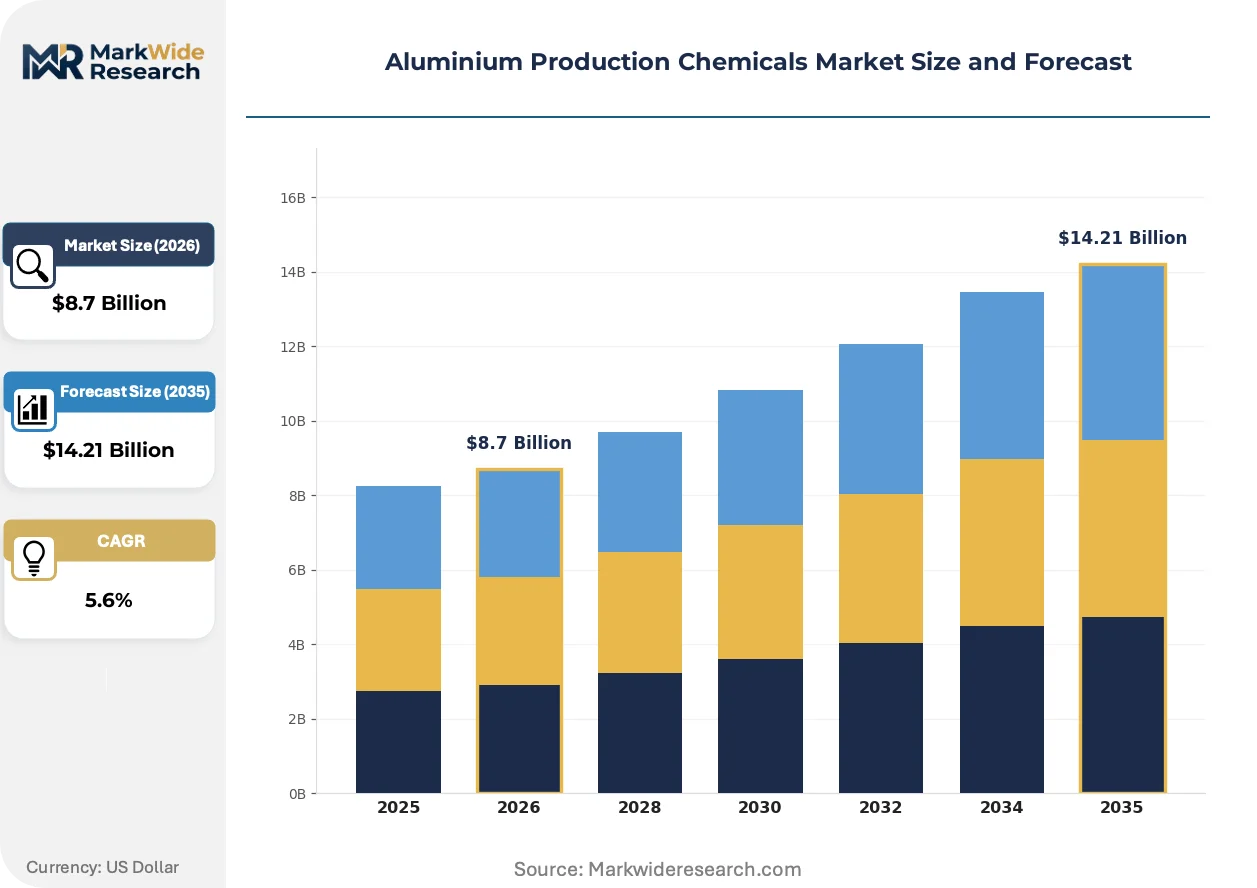
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alumina, Cryolite, Fluxes, Coagulants Application: Metal Manufacturing, Water Treatment, Pulp & Paper, Petrochemical End User: Construction, Automotive, Aerospace, Electronics Form: Granules, Powder, Liquid, Tablets |
| Companies Covered | Alcoa Corporation, Aluminum Corporation of China Limited, BASF SE, Cabot Corporation, Evonik Industries AG, United Company Rusal, Sasol Limited, Sumitomo Chemical Co. Ltd., W.R. Grace & Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aluminium Production Chemicals Market Strategic Shifts
Smelter digitalization is rewiring how bath chemistry gets specified, dosed, and optimized, collapsing the traditional separation between chemical supplier and process control vendor.
Digital twin platforms for electrolytic cell management are virtualizing the relationship between real-time sensor data and chemical adjustment protocols. Nordic and Canadian smelters are deploying these systems at commercial scale, compressing response times for alumina feeding and fluoride addition from hours to minutes. The technology is virtualizing traditional technical service relationships, as suppliers must now embed their expertise directly into algorithmic decision layers rather than periodic site visits.
The EU F-Gas Regulation's 2024 tightening of perfluorocarbon emission limits is forcing bath chemistry reformulation across German and French reduction operations. Smelters are trialing alternative flux systems with reduced cryolite ratios and elevated aluminium fluoride content to suppress anode effects. Low-carbon certification tiers are emerging as procurement differentiators, with chemical suppliers competing on verified carbon intensity per tonne of metal produced rather than purity metrics alone.
Buyer concentration among primary producers is consolidating procurement decisions into centralized technical committees at headquarters level. Smelters in Quebec and Western Australia are bypassing regional distributors to negotiate direct multi-year supply agreements with integrated chemical manufacturers. This channel compression is most visible in high-volume alumina contracts, where spot market participation has collapsed in favor of formula-priced annual frameworks indexed to LME aluminium prices.
Aluminium Production Chemicals Market Segmentation
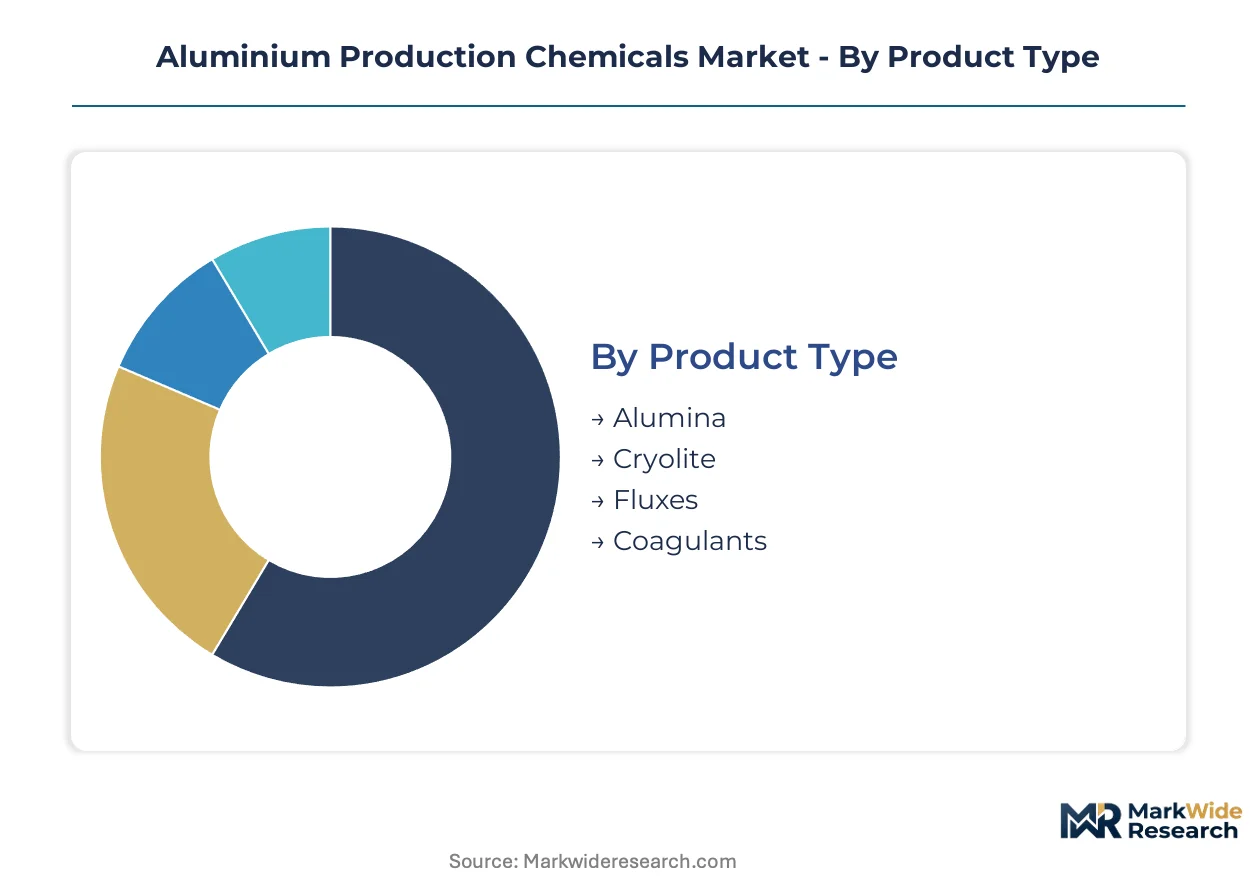
Aluminium production chemicals serve distinct process stages across the value chain, from Bayer refining through Hall-Héroult electrolysis to casthouse finishing. Segmentation reveals how formulation requirements diverge by metallurgical application, regulatory exposure, and integration depth with smelter automation systems.
Product Type:
Mature commodity chemistries dominate volume flows, while specialty formulations emerge around low-carbon smelting protocols and emission control mandates.
- Alumina:Smelter-grade aluminium oxide meeting minimum 98.5 percent purity thresholds ensures current efficiency above 94 percent in reduction cells. Demand concentrates in GCC megaprojects in Saudi Arabia and the UAE, where integrated refineries feed captive smelter complexes with multi-year supply agreements indexed to LME pricing.
- Cryolite:Synthetic sodium aluminium fluoride functions as the essential bath component lowering alumina melting point from 2050°C to approximately 950°C. Supply tightness from Greenland natural mineral depletion is forcing reliance on fluorite-derived production, exposing European and North American smelters to Chinese acid-grade fluorspar export quota volatility.
- Fluxes:Aluminium fluoride and calcium fluoride additives fine-tune bath chemistry ratios to suppress anode effects and perfluorocarbon generation under EU F-Gas Regulation limits.
- Coagulants:Polymeric and inorganic flocculants treat process water in zero-liquid-discharge circuits mandated by China's MEE standards in Shanxi and Shandong provinces.
Alumina handles the majority of throughput; coagulants are climbing the fastest on share as water treatment mandates tighten.
Application:
Cost tier stratification separates high-volume metallurgical inputs from premium-priced specialty chemicals serving adjacent industrial sectors.
- Metal Manufacturing:Primary aluminium smelting consumes the largest chemical volumes through Bayer refining and Hall-Héroult electrolysis. Procurement concentrates in tier-one casthouses supplying automotive OEM lightweighting programs in Germany, Japan, and the United States.
- Water Treatment:Smelter circuit closure for zero-liquid-discharge compliance drives specialized membrane treatment chemicals and flocculants. China's MEE emissions standards are forcing process water recycling ratios upward across Shanxi and Shandong reduction operations.
- Pulp & Paper:Alumina hydrates and specialty coagulants serve sizing and retention applications with moderate purity requirements.
- Petrochemical:Catalyst support materials and process chemicals leverage aluminium-derived substrates for refinery and chemical plant operations.
Metal manufacturing commands the dominant share of procurement spend; water treatment is expanding most quickly as regulatory mandates proliferate.
End User:
Customer type segmentation tracks how downstream industry specifications propagate upstream into chemical purity and certification requirements.
- Construction:Standard-grade aluminium alloys for building systems and infrastructure tolerate moderate impurity levels, supporting commodity chemical procurement.
- Automotive:OEM lightweighting mandates in chassis and powertrain components pull high-purity alloys requiring precise bath chemistry control and traceability-verified inputs under EU CBAM frameworks.
- Aerospace:Premium-grade alloys for airframe and engine applications demand ultra-high-purity alumina and specialized flux systems with documented impurity thresholds.
- Electronics:Capacitor foil and semiconductor packaging applications require controlled sodium and iron content driving specialty chemical specifications.
Automotive absorbs the largest chemical volume by alloy tonnage; aerospace maintains the steepest premium pricing tier for certified formulations.
Form:
Physical delivery format selection reflects automation maturity and dosing system architecture across smelter generations.
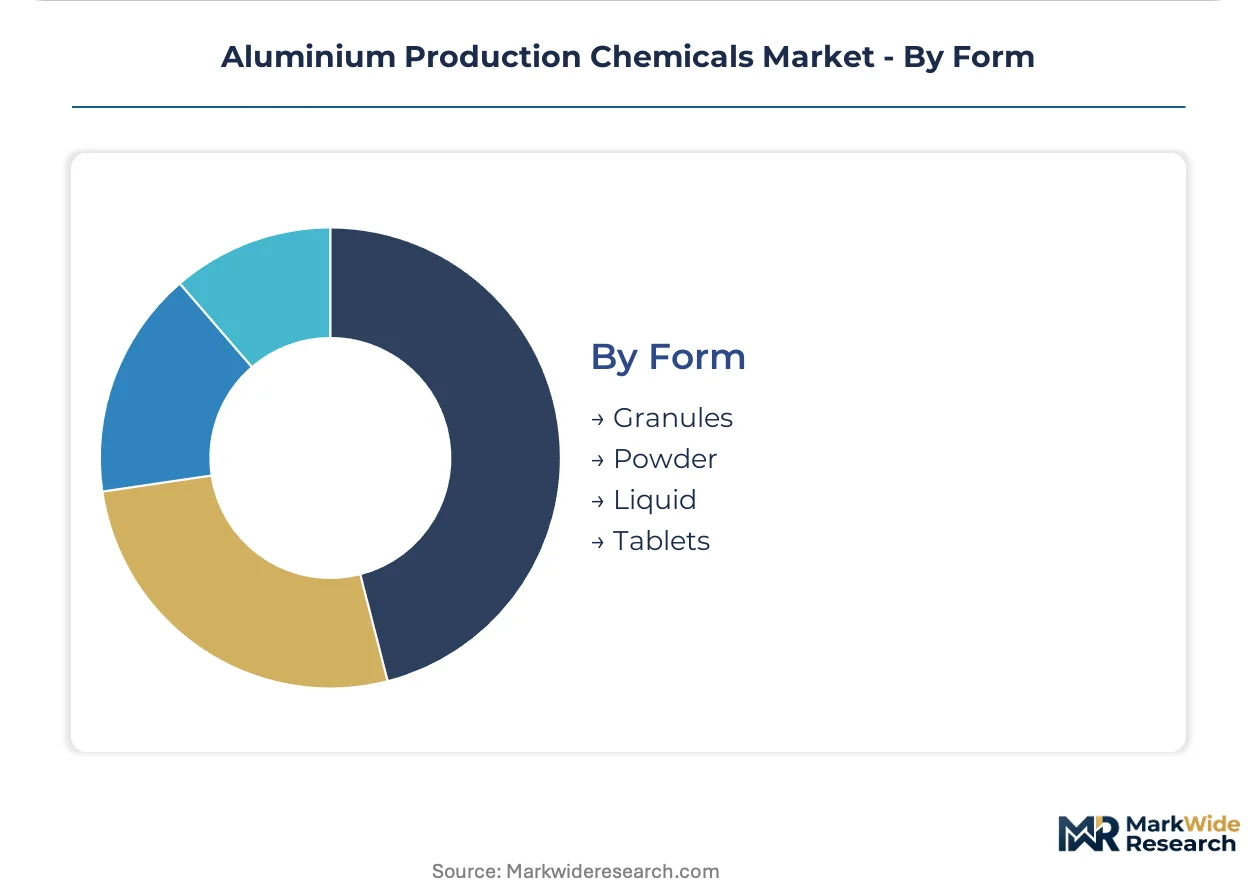
- Granules:Controlled particle size distribution enables precise bath chemistry adjustment in manual and semi-automated dosing systems prevalent in legacy potlines.
- Powder:Fine-ground formulations dissolve rapidly for rapid fluoride addition response, though dust control requirements complicate handling in older facilities.
- Liquid:Pre-dissolved solutions integrate directly with automated dosing installations and digital twin platforms compressing optimization cycles from hours to minutes in Nordic and Canadian smelters.
- Tablets:Compressed solid forms simplify transport and storage for remote smelter locations with limited material handling infrastructure.
Granules and powder retain the installed base majority; liquid delivery is gaining share fastest where digital twin integration penetrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Primary aluminium smelters in China, Saudi Arabia, and the United States concentrate the largest procurement volumes for production chemicals, with integrated producers and independent casthouses driving divergent sourcing patterns across regulatory environments.
China
Shandong and Shanxi provinces host the densest concentration of reduction capacity, where Chalco and private smelters consume cryolite and alumina at massive scale. MEE emissions standards mandate zero-liquid-discharge compliance, forcing investments in water treatment chemicals across the Yellow River industrial corridor. The dual carbon goals accelerate low-carbon smelting pilots in Xinjiang and Yunnan, reshaping chemical specifications for renewable-powered operations.
Saudi Arabia
Ma'aden's Ras Al-Khair complex anchors GCC chemical demand, with captive supply chains integrating alumina refining and smelting in a single industrial zone. The Saudi Industrial Development Fund backs capacity expansions requiring long-term chemical offtake agreements. Jubail's petrochemical infrastructure supports localized production of fluxes and specialty additives, reducing import dependence for bath chemistry inputs.
United States
Alcoa's Pacific Northwest smelters and Century Aluminum's Kentucky operations pull high-purity alumina through Gulf Coast import terminals. EPA fluoride emission oversight tightens product certification requirements for suppliers seeking access to domestic reduction cells. The Inflation Reduction Act's clean energy provisions incentivize low-carbon primary metal output, creating attach rates for traceability-verified chemical inputs in premium segments.
Germany
Trimet Aluminium's Essen and Hamburg casthouses serve automotive OEM lightweighting programs with precision alloy specifications. The EU F-Gas Regulation's 2024 tightening forces bath chemistry reformulation across Rheinland smelters to suppress perfluorocarbon generation. The KBA's vehicle efficiency mandates propagate upstream into chemical purity requirements for chassis and powertrain aluminium grades.
Canada
Rio Tinto Alcan's Quebec smelter network deploys digital twin platforms for real-time bath chemistry optimization, compressing response times for alumina and fluoride dosing. Hydro-Québec's renewable power advantage supports low-carbon metal certifications that cascade into chemical input traceability requirements. The Saguenay-Lac-Saint-Jean region concentrates casthouse capacity feeding North American automotive and aerospace tier-one suppliers.
Aluminium Production Chemicals Market Competitive Environment
Channel-controlling players compete with product-specialist players across a market structured by integration depth and geographic captive supply. Integrated aluminium producers with backward-linked chemical operations command volume advantages in alumina and cryolite, while independent specialty houses capture premium tiers in flux systems and water treatment formulations. Three archetypes dominate: state-linked national champions with captive refining-smelter-chemical chains; European diversified chemical conglomerates leveraging catalyst and process technology portfolios; and regional pure-plays focused on bath chemistry optimization. Competitive moves concentrate on multi-year supply agreement negotiations indexed to LME pricing, and technology licensing partnerships embedding supplier expertise into smelter automation layers.
Among the state-linked tier, Aluminum Corporation of China Limited exemplifies vertical captive supply from bauxite through cryolite production. BASF SE occupies a position anchoring European smelter modernization through its catalyst and process chemical portfolio. Evonik Industries AG represents the specialty additive vector, with high-purity formulations aligned to low-carbon smelting protocols. These three anchors illustrate how competitive positioning stratifies across integration depth, geographic origin, and technical specialization rather than scale alone.
| Leading Market Players |
|---|
| Alcoa Corporation |
| Aluminum Corporation of China Limited |
| BASF SE |
| Cabot Corporation |
| Evonik Industries AG |
| United Company Rusal |
| Sasol Limited |
| Sumitomo Chemical Co. Ltd. |
| W.R. Grace & Co. |
| Others |
Value Chain & Pricing Dynamics
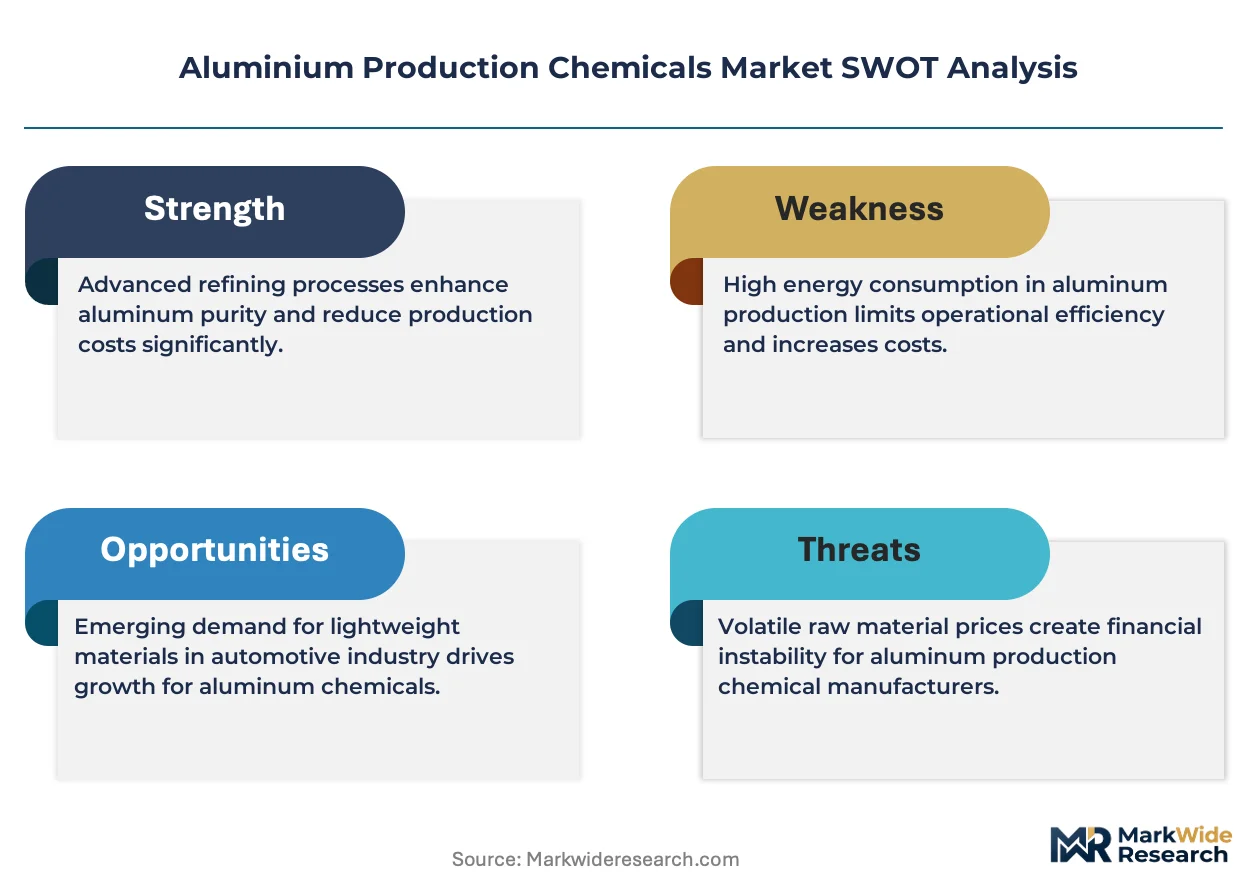
Undercapacity in European synthetic cryolite production is forcing smelters toward Asian supply commitments, compressing margin buffers for bath chemistry suppliers while amplifying price volatility transmission from acid-grade fluorspar markets. This utilization squeeze binds pricing power to raw material access, with long-term offtake terms displacing spot flexibility.
Pricing Analysis
Cost-plus contracts indexed to LME aluminium prices and acid-grade fluorspar quotations dominate procurement frameworks across Atlantic basin smelters. Price differentiation separates ISO 14001-certified formulations from standard-grade alternatives, with EU F-Gas compliance tiers commanding premiums. Cost compression in synthetic cryolite is intensifying because Greenland natural mineral depletion has eliminated the lowest-cost supply tier. Tier-one casthouses exhibit lowest price sensitivity due to alloy specification rigidity, while construction-grade alloy producers negotiate aggressively on volume.
Supply Chain Analysis
Contract manufacturing concentration among Chinese fluorochemical processors and Saudi integrated refineries controls the bulk of cryolite and smelter-grade alumina conversion capacity. Supply draws from Chinese acid-grade fluorspar mines, Jamaican and Australian bauxite deposits, and GCC petrochemical feedstocks. Single-source vulnerability runs through the four integrated producers commanding Atlantic basin alumina refining. Distribution runs through direct multi-year supply agreements with smelter headquarters technical committees, bypassing regional distributors in high-volume segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Inert anode technology represents a structural substitution threat that could eliminate conventional bath chemistry demand within a decade, forcing incumbents to defend revenue pools while hedging technological obsolescence.
For Market Incumbents: Build captive supply moats through backward integration into fluorite refining or alumina conversion in GCC and Indonesian corridors. Secure multi-year offtake agreements with Ma'aden and Indonesian nickel-aluminium projects before Chinese incumbents consolidate positions. Prioritize ISO 14001 certification investments to qualify for EU CBAM-tier procurement frameworks. For New Entrants and Emerging Players: Pursue white-space positioning in Indonesia's greenfield smelter corridor, where established Gulf and Chinese relationships remain underdeveloped. Target zero-liquid-discharge chemical formulations for Shanxi and Shandong provinces under tightening MEE standards. Lead with digital twin integration capabilities rather than commodity volume to bypass entrenched supplier incumbency. For Investors and Strategic Acquirers: Capital is best deployed toward specialty additive houses with high-purity formulation expertise aligned to low-carbon smelting protocols, where technical differentiation sustains pricing power against commodity cyclicality. Monitor Rio Tinto and Alcoa inert anode pilot milestones as the critical inflection signal for conventional bath chemistry demand destruction.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluorite Refining | Secures cryolite supply against Chinese export quota volatility and Greenland depletion. |
| Long-term Supply Agreement with GCC Smelters | Locks volume commitments from Ma'aden expansion projects before competitor encirclement. |
| Digital Twin Platform Partnership | Embeds supplier algorithms into Nordic and Canadian smelter automation layers. |
| ISO 14001 Certification Acceleration | Qualifies suppliers for EU CBAM-tier procurement at Trimet and Rheinland operations. |
| Zero-Liquid-Discharge Chemical Development | Captures MEE-mandated demand in Shanxi and Shandong water treatment circuits. |
Study Parameters
Cross-validation between primary interviews with smelter technical directors, procurement leads at tier-one casthouses, fluorochemical plant managers, and distribution channel partners anchors the qualitative findings against secondary sources including customs trade data, SEC filings from integrated producers, and ACC industry reports. Bottom-up volume estimates from individual smelter capacity utilization and top-down aluminium production forecasts were reconciled to constrain projection variance.
Calibration against historical LME price elasticity and fluorspar cost pass-through patterns shaped the analytical framework across the analysis window. Segmentation dimensions modeled include product purity grade, end-use industry metallurgical application, physical delivery form, and regional production hub regulatory cluster. CAGRs were derived from slope-constrained growth trajectories fitted to announced capacity expansion timelines and emissions compliance investment cycles.
Sensitivities concentrate around inert anode commercialization pace, Chinese acid-grade fluorspar export quota tightening, and EU F-Gas Regulation enforcement intensity. Quarterly review of smelter digital twin deployment rates and low-carbon certification adoption curves is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Global Foundry Chemicals Market
Industrial Chemicals
Polyepoxysuccinic Acid Market
Industrial Chemicals
Knitting Oils Market
Industrial Chemicals
Acetylene Market
Industrial Chemicals
Industrial Biocides Market
Industrial Chemicals
Fatty Amines Market
Industrial Chemicals
Backing Material Market
Industrial Chemicals
Global Flow Chemistry Market
Industrial Chemicals
Global High Throughput Process Development Market
Industrial Chemicals
Europe Surface Treatment Chemicals Market
Industrial Chemicals
Molecular Sieve for Air Separation Market
Industrial Chemicals
Ceramic Corona Discharge Ozone Generator Market
Industrial Chemicals
Activated Carbon for Sugar Decolorization Market
Industrial Chemicals
Multi Component Injection Moulding Technology Market
Industrial Chemicals
Non-Corrosive Fluxes Market
Industrial Chemicals
South Africa Lime Market