
 Automotive Chemicals Market | 2026-2036
Automotive Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
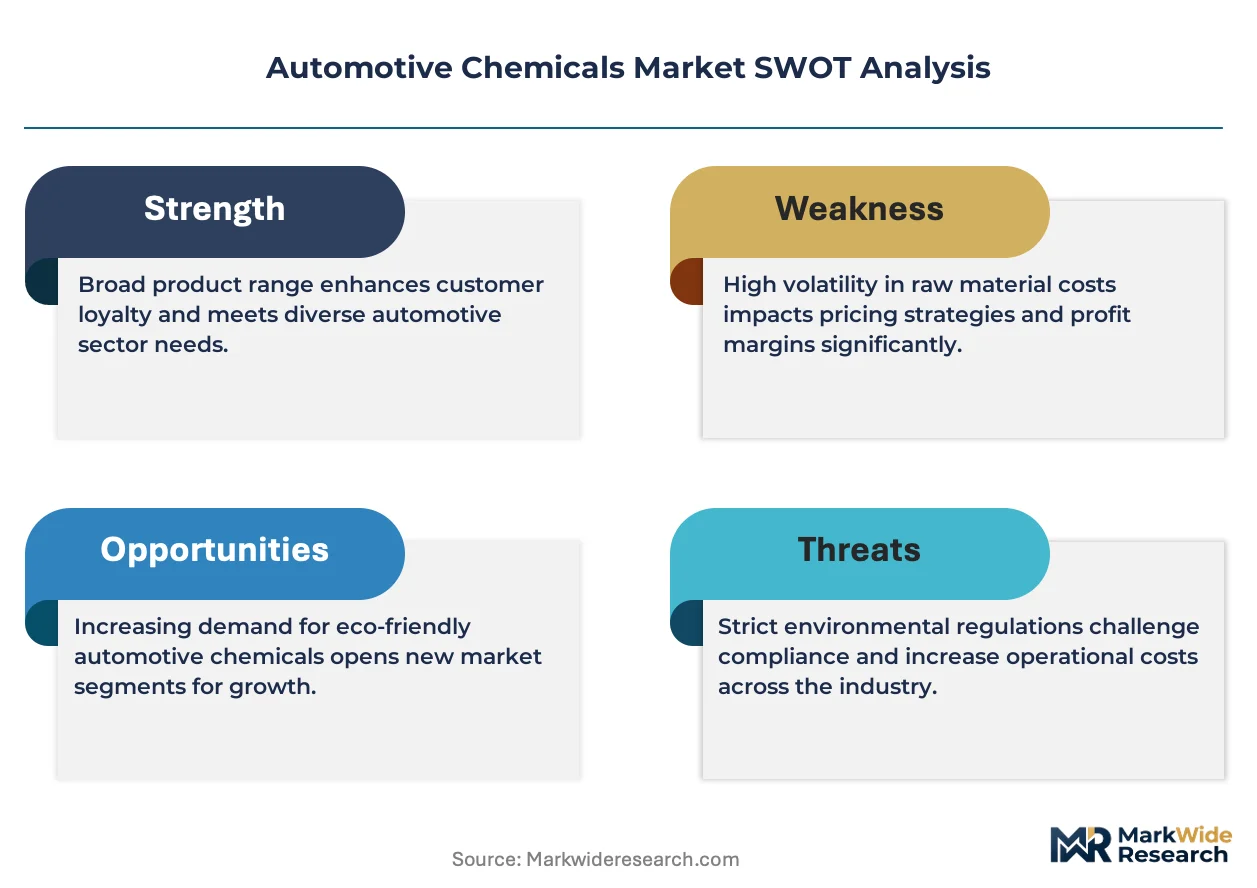
Automotive Chemicals Market Analysis
Buyer concentration across the automotive value chain is broadening as EV-native manufacturers and battery system integrators join established OEM procurement networks. Shell leverages its integrated base oil and additive technology platforms to serve both conventional powertrain and electrified vehicle segments. BASF SE anchors its position through high-performance coating formulations tailored to aluminum-intensive body-in-white architectures. DuPont differentiates via fluoropolymer and silicone-based sealants engineered for thermal stability in electric drivetrain applications.
Automotive chemicals encompass formulated substances including lubricants, adhesives, coatings, and sealants designed to protect, enhance, or enable vehicle components under operating stresses ranging from minus 40 degrees Celsius to sustained temperatures above 150 degrees Celsius in engine and battery zones. These formulations serve critical functions in corrosion prevention, friction reduction, thermal management, and structural bonding across vehicle assemblies. Lubricants occupy the largest value pool within product type segmentation, reflecting sustained internal combustion engine fleet maintenance alongside emerging e-axle and reduction gear fluid demand. Coatings command premium margin structures as OEMs adopt multi-layer electrocoat and clearcoat systems compatible with diverse substrate materials including aluminum, composites, and high-strength steels. Adhesives represent the fastest-expanding category, driven by mixed-material vehicle construction and battery pack assembly requirements for structural bonding and fire-resistant encapsulation.
EPA emission standards and REACH chemical registration requirements in the United States and Europe constrain solvent-based formulation chemistries and mandate hazardous substance disclosure throughout supply chains. China's MIIT enforces GB standards for vehicle material recyclability and restricted substance content that directly shape local automotive chemical specifications. Stakeholders must monitor evolving battery safety regulations and substrate material transitions to align product development roadmaps with next-generation vehicle platform requirements.
Market Dynamics
Electric vehicle platform proliferation is fragmenting demand patterns across the automotive chemicals value chain, as battery thermal management requirements diverge sharply from legacy powertrain specifications and force reformulation investments across lubricant, coating, and adhesive portfolios.
Growth Catalysts
- GB Standard Compliance:China's MIIT-enforced material recyclability mandates are accelerating domestic demand for waterborne coating systems and low-VOC adhesive platforms in vehicle assembly operations.
- Aluminum-Intensive Architecture:Multi-material body construction is absorbing specialty pretreatment chemicals and conversion coatings designed for dissimilar metal galvanic protection.
- REACH Phase-In:ECHA's extended substance evaluation timelines are pushing European formulators toward bio-based solvent alternatives and disclosed supply chain chemistry ahead of restriction deadlines.
Market Restraints
- Base Oil Supply Concentration:API Group II/III base stock production clusters in the US Gulf Coast and Northeast Asia expose lubricant blenders to hurricane and shipping lane disruption risks.
- Fluoropolymer Feedstock Volatility:PTFE and PVDF resin supply tightness, tied to fluorspar mining concentration in China and Mexico, compresses margins for high-performance sealant manufacturers.
- Technical Substitution Limits:Silicone thermal interface materials face performance ceilings above 180 degrees Celsius, constraining adoption in next-generation silicon carbide inverter modules.
Strategic Opportunities
- Battery Pack Encapsulation:Fire-resistant polyurethane and epoxy potting compounds represent underpenetrated white space as OEMs redesign pack architectures for cell-to-chassis integration.
- India Production Scale-Up:PLI scheme incentives for domestic EV manufacturing are creating first-mover openings for localized coolant and dielectric fluid formulation capacity.
- Closed-Loop Chemistry:EU Battery Regulation passport requirements are enabling service-contract models where chemical suppliers retain ownership and responsibility for coolant recycling.
Industry Challenges
- Formulation Talent Scarcity:Electrification is compressing the available pool of chemists experienced in both dielectric fluid engineering and conventional tribology.
- Dual Certification Burden:Suppliers must simultaneously maintain EPA SNAP approvals for low-GWP refrigerants and state-level prop 65 compliance for California-distributed products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Chemicals Market |
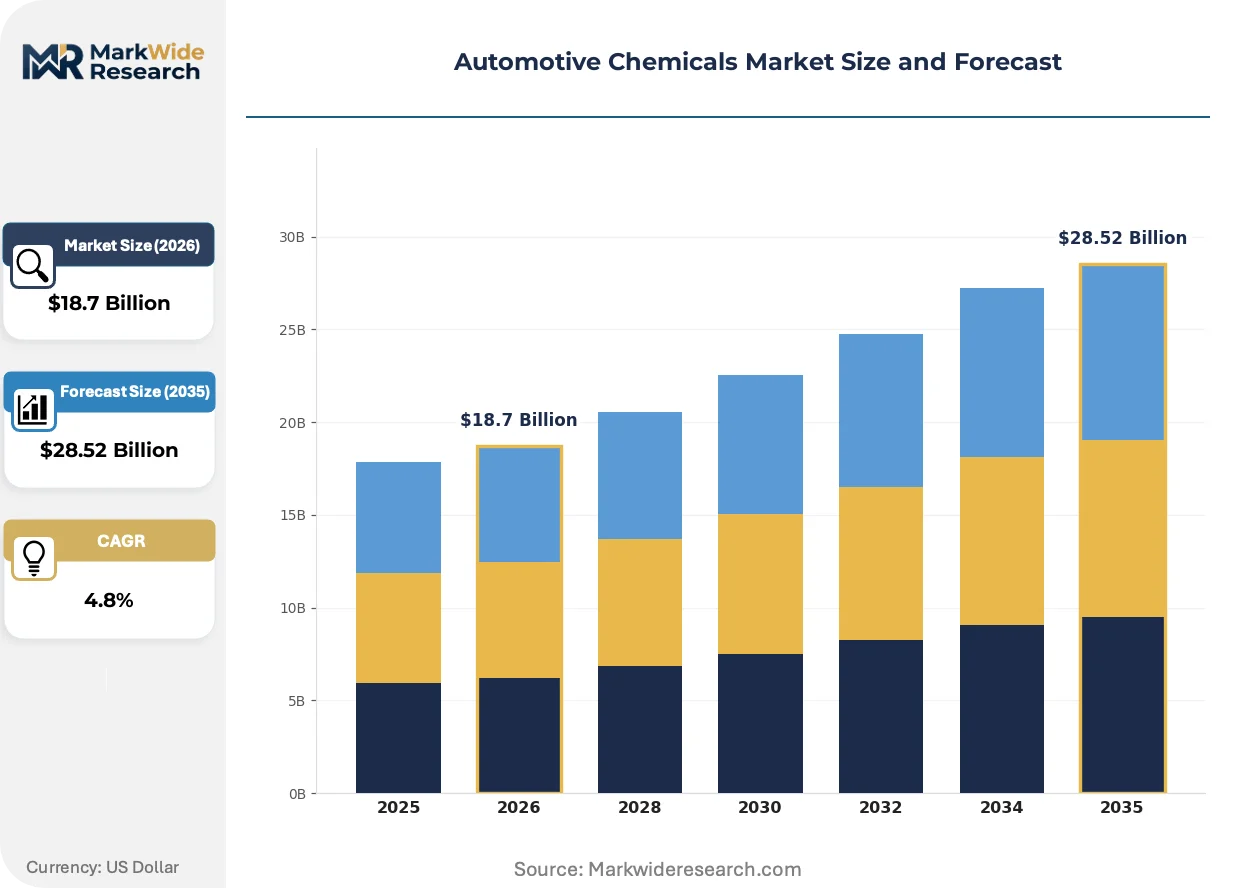
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adhesives, Coatings, Sealants, Lubricants End User: OEMs, Aftermarket Providers, Component Manufacturers, Distributors Application: Bodywork, Engine Treatment, Interior Materials, Fluid Systems Material: Plastics, Metals, Composites, Ceramics |
| Companies Covered | Shell, DuPont, ExxonMobil, Fuchs Lubricants, AkzoNobel, BASF SE, Chevron Corporation, CNPC, The Dow Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Chemicals Market Emerging Trajectories
Synthetic ester and polyalkylene glycol chemistries are displacing mineral oil foundations across drivetrain applications, while regulatory pressure on substance transparency accelerates digital product passport adoption throughout chemical supply chains.
Dielectric immersion coolants are absorbing thermal management responsibility in high-performance battery packs and power electronics, with Porsche and Mercedes-Benz integrating these fluids into series production EV platforms during 2023-2024 development cycles. The shift is compressing demand for traditional air-cooling hardware and aluminum heat exchanger assemblies.
REACH Annex XIV authorization requirements are forcing reformulation of chromium-based corrosion inhibitors and certain epoxy curing agents used in automotive coatings and adhesives. German and French coating houses are accelerating bio-based polyol and isocyanate-free curing system development to maintain market access.
Fleet operators and battery leasing subsidiaries are consolidating procurement authority previously dispersed across individual OEM after-sales networks. This concentration favors chemical suppliers offering integrated fluid monitoring and predictive replacement services, with the model taking hold most visibly in European commercial vehicle electrification programs.
Automotive Chemicals Market Segmentation
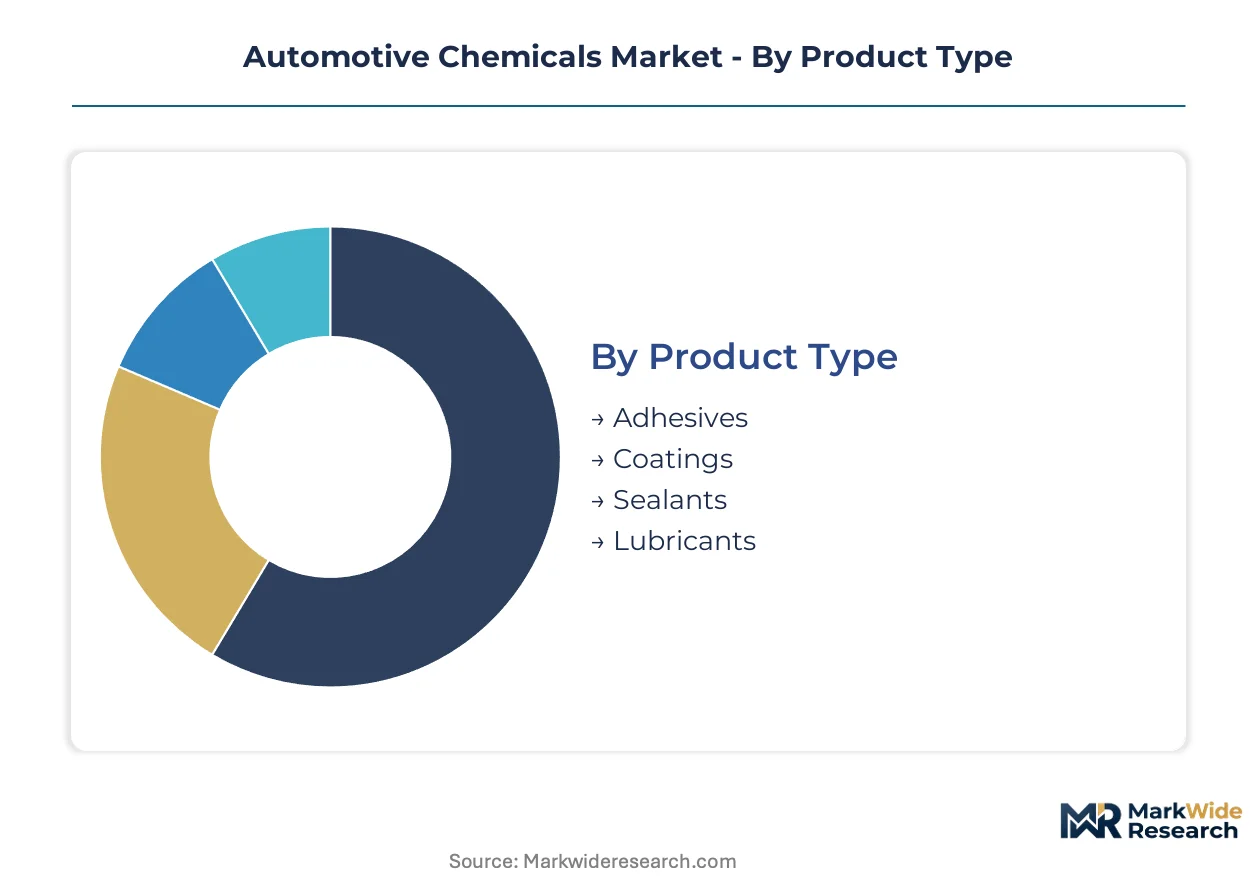
Segmentation in automotive chemicals reveals how formulation requirements diverge across powertrain architectures and assembly stages. Battery thermal management and multi-material body construction are fragmenting traditional demand patterns, forcing suppliers to maintain parallel technical competencies.
Product Type:
Standalone consumables dominate aftermarket revenue, while embedded formulations integrate into manufacturing processes with multi-year supply contracts.
- Lubricants:Mineral and synthetic base stocks blended with additive packages reduce friction in engines, transmissions, and e-axle reduction gears. Fleet maintenance contracts in China and Germany sustain bulk volume placements, though electrification is compressing engine oil demand per vehicle.
- Coatings:Multi-layer electrocoat, primer, basecoat, and clearcoat systems protect substrates from corrosion and UV degradation. OEM specification authority in Stuttgart, Wolfsburg, and Shanghai drives premium-grade absorption for aluminum-intensive architectures.
- Adhesives:Structural bonding agents enable mixed-material construction and battery pack assembly.
- Sealants:Elastomeric and thermoset formulations prevent fluid ingress and NVH transmission.
Volume placements concentrate in Lubricants; the faster expansion belongs to Adhesives.
End User:
Direct procurement authority is consolidating as EV-native manufacturers bypass traditional tiered supply structures.
- OEMs:Vehicle assemblers specify chemical formulations through platform-level engineering agreements. Tesla, BYD, and Volkswagen Group exercise outsized influence over thermal fluid and coating chemistry roadmaps through captive R&D partnerships.
- Aftermarket Providers:Independent distributors and service chains supply replacement lubricants, adhesives, and sealants to maintenance workshops. Quick-lube networks in the US and authorized service centers in Japan generate recurring demand for API-certified engine oils and chassis greases.
- Component Manufacturers:Tier suppliers integrate pretreatment and bonding chemistries into subassembly production.
- Distributors:Wholesalers buffer inventory between formulators and end-use points.
Contract value pools deepest with OEMs; aftermarket channels deliver the most stable replacement revenue.
Application:
Functional zones impose distinct thermal, chemical, and mechanical stress profiles on formulation selection.
- Fluid Systems:Coolants, brake fluids, and dielectric immersion media manage heat transfer and electrical isolation. Porsche and Mercedes-Benz production lines specify synthetic ester-based dielectric fluids for battery pack integration.
- Bodywork:Pretreatment, conversion coating, and paint film layers protect exterior panels from stone chip and environmental corrosion. European OEMs enforce REACH-compliant waterborne systems for assembly plants in Germany, France, and Spain.
- Engine Treatment:Friction modifiers and deposit control additives extend powertrain durability.
- Interior Materials:Adhesives and coatings bond soft-touch surfaces and control VOC emissions.
Specification complexity peaks in Fluid Systems; standardization remains highest in Interior Materials.
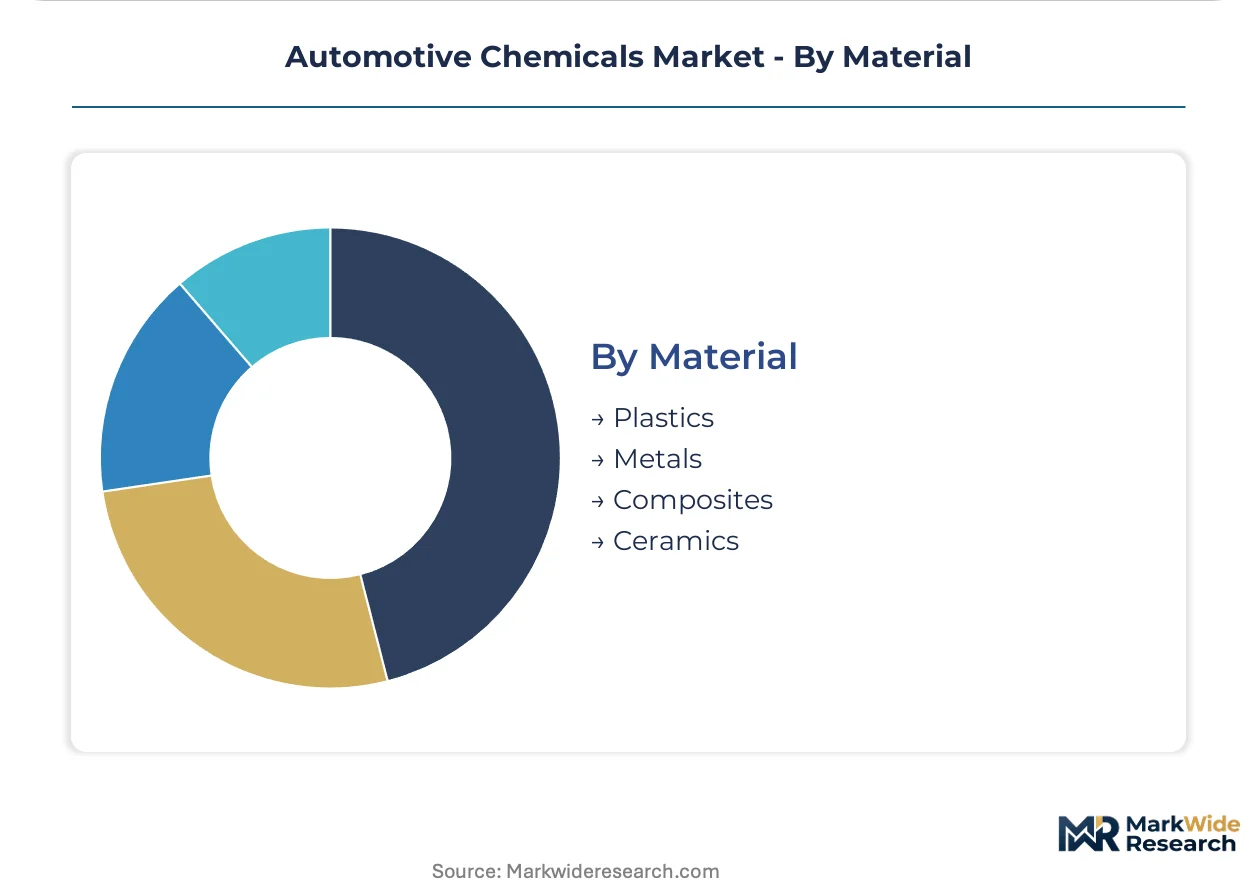
Material:
Substrate chemistry dictates pretreatment protocols and bonding surface preparation requirements.
- Metals:Steel, aluminum, and magnesium alloys require conversion coatings and galvanic isolation layers. Chinese MIIT recyclability mandates favor chrome-free pretreatment for aluminum body-in-white construction in domestic EV platforms.
- Composites:Carbon fiber and glass-reinforced polymers need specialized surface activation and structural adhesives. BMW i-series and Lucid Air production integrates epoxy-based bonding for CFRP passenger cell modules.
- Plastics:Polypropylene and polycarbonate substrates demand adhesion promoters and UV-stabilized coatings.
- Ceramics:Thermal barrier coatings and electrical substrates use specialized ceramic-forming precursors.
Process maturity is greatest for Metals; technical development investment flows most heavily into Composites.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fluorspar mining concentration in China and Mexico anchors feedstock supply for fluoropolymer sealants, while Group II/III base oil production clusters along the US Gulf Coast and in Northeast Asia expose blenders to geographic disruption risks.
China
Domestic EV production scale drives outsized consumption of advanced coatings and dielectric fluids. MIIT-enforced GB standards for material recyclability and restricted substance content shape local automotive chemical specifications. The Yangtze River Delta cluster around Shanghai absorbs premium waterborne coating systems for aluminum-intensive body-in-white construction.
Germany
OEM specification authority in Stuttgart and Wolfsburg drives premium-grade absorption for multi-layer electrocoat systems. ECHA's REACH Annex XIV authorization requirements force reformulation of chromium-based corrosion inhibitors and certain epoxy curing agents. The Baden-Württemberg automotive corridor accelerates bio-based polyol development to maintain market access.
United States
Fleet maintenance contracts sustain bulk lubricant volume placements, though electrification compresses engine oil demand per vehicle. EPA SNAP approvals for low-GWP refrigerants operate alongside state-level Prop 65 compliance burdens for California-distributed products. The Gulf Coast petrochemical corridor concentrates API Group II/III base stock production, exposing blenders to hurricane disruption risks.
India
PLI scheme incentives for domestic EV manufacturing create first-mover openings for localized coolant and dielectric fluid formulation capacity. BIS standards govern vehicle material specifications alongside emerging battery safety regulations. The Maharashtra-Gujarat industrial corridor attracts capacity investments from multinational chemical formulators seeking proximity to Tata Motors and Mahindra EV platforms.
Japan
Authorized service centers generate recurring demand for API-certified engine oils and chassis greases in the mature aftermarket. METI oversees industrial chemical standards while JIS specifications govern automotive fluid performance tiers. The Kanto region around Tokyo anchors R&D partnerships between coating houses and Toyota, Honda, and Nissan engineering centers.
Automotive Chemicals Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue battery-native thermal management formulations and closed-loop chemistry service models. The supplier base organizes around three archetypes: integrated oil majors with captive base oil positions, diversified chemical conglomerates with coating and adhesive portfolios, and specialty lubricant houses focused on high-performance tribology. Competitive moves concentrate on backward integration into additive manufacturing and geographic expansion into India and Southeast Asia to capture EV production scale-up.
Within the integrated oil major tier, Shell and ExxonMobil represent archetypes leveraging upstream base oil control to serve both conventional powertrain and electrified vehicle segments. Among diversified chemical conglomerates, BASF SE and DuPont occupy positions exemplifying high-performance coating and sealant specialization for aluminum-intensive architectures and thermal stability requirements. The specialty lubricant vector includes Fuchs Lubricants, a German GmbH-structured entity, representing focused tribology expertise for industrial and automotive applications.
| Leading Market Players |
|---|
| Shell |
| DuPont |
| ExxonMobil |
| Fuchs Lubricants |
| AkzoNobel |
| BASF SE |
| Chevron Corporation |
| CNPC |
| The Dow Chemical Company |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap lubricant blenders in Germany and Japan anchor regional pricing discipline through captive additive manufacturing, while their limited balance-sheet capacity constrains aggressive expansion into dielectric fluid formulations where integrated oil majors extract premium returns.
Pricing Analysis
Volume placements in mineral-based engine lubricants compress margins to commodity levels, whereas dielectric immersion coolants and battery encapsulation compounds command substantial premiums through OEM specification lock-in. Three-tier pricing structure across premium, standard, and economy levels separates REACH-compliant waterborne coatings from solvent-based alternatives and generic imports. Cost compression in mid-tier lubricants is intensifying because Chinese domestic producers scale Group II/III base oil capacity. Fleet operators exhibit highest price sensitivity in bulk aftermarket procurement; OEM platform engineering agreements show lowest sensitivity due to qualification switching costs.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Houston buffer inventory between Northeast Asian base oil production and European formulation plants. Feedstock supply draws from China and Mexico for fluorspar-derived fluoropolymers, the US Gulf Coast and South Korea for API Group II/III base stocks, and Germany for specialty additive packages. Single-source vulnerability concentrates in Chinese fluorspar mining for high-performance sealant resins. Distribution runs through authorized distributor networks for aftermarket lubricants and direct platform-level contracts for OEM coating systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where captive control over base oil refining and additive synthesis determines who captures margin in electrified powertrain fluids.
For Market Incumbents: Deepen backward integration into bio-based solvent alternatives ahead of REACH Annex XIV authorization deadlines for chromium-based corrosion inhibitors. Add dedicated dielectric fluid blending capacity in India near Tata Motors and Mahindra EV platforms. Battery-native entrants with silicone thermal interface expertise threaten premium positioning in next-generation silicon carbide inverter modules.
For New Entrants and Emerging Players: Battery leasing subsidiaries and fleet operators consolidating procurement authority represent the most accessible buyer archetype for predictive fluid monitoring service contracts. White space concentrates in fire-resistant polyurethane potting compounds for cell-to-chassis architectures and localized coolant recycling under EU Battery Regulation passport requirements. A technical service partnership model with European commercial vehicle electrification programs offers lowest barrier to initial revenue.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap coating houses in Germany facing REACH reformulation cost burdens but holding qualified supplier status with Stuttgart and Wolfsburg OEM engineering centers. Long-term viability over a multi-year horizon hinges on dielectric fluid formulation capabilities displacing traditional thermal management hardware. Watch for silicon carbide inverter module adoption rates above 180 degrees Celsius as signal for silicone thermal interface material substitution inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Additive Manufacturing | Captive supply of friction modifier packages insulates margin from API Group II/III base oil volatility in the US Gulf Coast. |
| Dielectric Fluid Capacity Expansion | Localized production in Maharashtra-Gujarat corridor secures qualification with Tata Motors and Mahindra EV platforms. |
| Closed-Loop Chemistry Service Model | EU Battery Regulation passport requirements enable coolant recycling contracts retaining supplier ownership responsibility. |
| Bio-Based Solvent Transition | REACH Annex XIV authorization timelines force German and French coating houses toward isocyanate-free curing systems. |
| Battery Pack Encapsulation Compound Development | Fire-resistant polyurethane and epoxy potting compounds address cell-to-chassis integration safety requirements from Porsche and Mercedes-Benz. |
Methodological Framework
Independent corroboration across primary interviews with Tier 1 supplier procurement leads, OEM platform engineers, aftermarket distributors, and technical R&D directors, combined with secondary validation through customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and vehicle production databases, underwrites the qualitative findings. Bottom-up segment sizing triangulates against top-down market envelope estimates.
Rate-of-change decomposition separates volume growth from value mix shifts across the projection horizon. Segmentation dimensions modeled include product grade tier, propulsion architecture, content per vehicle, and regional production cluster. CAGRs derive from fitted growth curves anchored to disclosed OEM platform launch timelines and regulatory phase-in schedules. Forecast inputs incorporate MIIT GB standard compliance deadlines and ECHA substance evaluation timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to battery thermal management technology transitions and fluorspar supply disruptions. Forecasts reflect documented assumptions regarding EV production scale trajectories and regulatory enforcement intensity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Metal Forming Fluids Market
Industrial Chemicals
Global CMP Slurry Market
Industrial Chemicals
Heat Treating Market
Industrial Chemicals
Global Chemical Mechanical Planarization Market
Industrial Chemicals
Sulfolane Market
Industrial Chemicals
Soil Hardening Agent Market
Industrial Chemicals
Enzymatically Hydrolyzed Carboxymethyl Cellulose Market
Industrial Chemicals
Monoethanol Amine Market
Industrial Chemicals
Ferrocene Market
Industrial Chemicals
Plant-Based Hydraulic Oil Market
Industrial Chemicals
Carbamate Insecticides Market
Industrial Chemicals
Anti-Corrosive Agents Market
Industrial Chemicals
Global Refrigerants Market
Industrial Chemicals
Toluene Diisocyanates (TDI) Market
Industrial Chemicals
Perchloroethylene Market
Industrial Chemicals
Global Antifreeze Market