
 Diphenyl Oxide (DPO) Market | 2026-2036
Diphenyl Oxide (DPO) Market Size, Share, and Industry Trends Forecast 2026-2036
Diphenyl Oxide (DPO) Market Outlook
Bisphenol A is decoupling from certain thermal fluid formulations as processors seek alternatives with superior oxidative stability. Solvay S.A. leverages its integrated aromatics chain to secure feedstock cost advantages across European production hubs. Lanxess AG anchors its DPO position through specialized flake and liquid grades tailored to pharmaceutical intermediate specifications. Eastman Chemical Company differentiates via stringent quality protocols that meet FDA and EPA dual compliance for heat transfer applications.
Diphenyl oxide is a diaryl ether compound with the formula (C6H5)2O, typically manufactured through the Ullmann condensation of chlorobenzene and phenol over copper catalysts at elevated temperatures, yielding a product with a boiling point near 258°C that serves primarily as a heat transfer medium and chemical synthesis precursor. The application dimension shows heat transfer fluids commanding the largest volume share due to established deployment across chemical processing infrastructure, while chemical intermediate usage generates premium margins driven by pharmaceutical and agrochemical downstream demand. Product type segmentation reveals liquid formulations leading in tonnage for bulk industrial offtake, whereas flake and powder grades capture higher unit economics in specialized synthesis applications requiring precise dosing control.
EPA standards under the Toxic Substances Control Act govern DPO manufacturing emissions and workplace exposure limits in the United States, while REACH registration requirements in Europe mandate comprehensive safety dossiers for import and production volumes exceeding one tonne annually. China's MEE enforces GB standards for volatile organic compound emissions from aromatic ether production facilities, creating compliance barriers for unqualified market entrants. Stakeholders must monitor evolving chemical inventory notifications across multiple jurisdictions as regulatory divergence between EPA, ECHA, and SAMR frameworks intensifies classification and labeling complexity for cross-border trade.
Market Dynamics
Heat transfer fluid specification tightening across chemical processing infrastructure is forcing DPO producers to recalibrate purity thresholds and thermal stability benchmarks simultaneously.
Growth Catalysts
- REACH Phase-in Substances:ECHA's updated dossier requirements for diaryl ethers above one tonne annual volume are accelerating substitution away from non-registered alternatives in European chemical manufacturing.
- China's Dual Carbon Goals:MEE emissions standards for volatile organic compounds from aromatic production are consolidating domestic capacity toward qualified producers with integrated environmental controls.
- Pharmaceutical Intermediate Synthesis:Agrochemical and active pharmaceutical ingredient manufacturers are expanding DPO offtake for Grignard reaction solvents and etherification precursors.
Market Restraints
- Chlorobenzene Feedstock Volatility:Copper-catalyzed Ullmann condensation relies on chlorobenzene pricing tied to benzene-chlorine derivative markets, compressing margin predictability for non-integrated producers.
- European Import Concentration:REACH-registered supply chains concentrate qualified import sources through Rotterdam and Antwerp hubs, creating single-point vulnerability for inland chemical processors.
- Synthetic Ester Substitution:Polyol ester heat transfer fluids with superior oxidative stability are displacing DPO in high-temperature solar thermal and concentrated solar power applications above three hundred degrees Celsius.
Strategic Opportunities
- India Specialty Chemical Expansion:CDSCO-aligned pharmaceutical intermediate demand and BIS standardization for industrial heat transfer fluids are opening qualified supply relationships with domestic formulators.
- Flake Grade Precision Dosing:Solid-state DPO formulations enable automated batch control in agrochemical synthesis, capturing premium positioning against liquid bulk alternatives.
- EPA TSCA Section 5 Pre-manufacture Notifications:New chemical review pathways for modified diaryl ether structures create first-mover advantages for producers with existing PMN submission capabilities.
Industry Challenges
- Catalyst Deactivation Management:Copper-based Ullmann systems require continuous regeneration expertise that concentrates operational knowledge among legacy production engineers.
- Dual Jurisdiction Labeling Complexity:Divergent GHS classification between EPA hazard communication standards and EU CLP inventory entries forces SKU proliferation for cross-border shippers.
- Legacy Heat Transfer System Retrofit Integration:Chemical processors with decades-old thermal fluid infrastructure face compatibility testing burdens when upgrading to higher-purity DPO grades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diphenyl Oxide (DPO) Market |
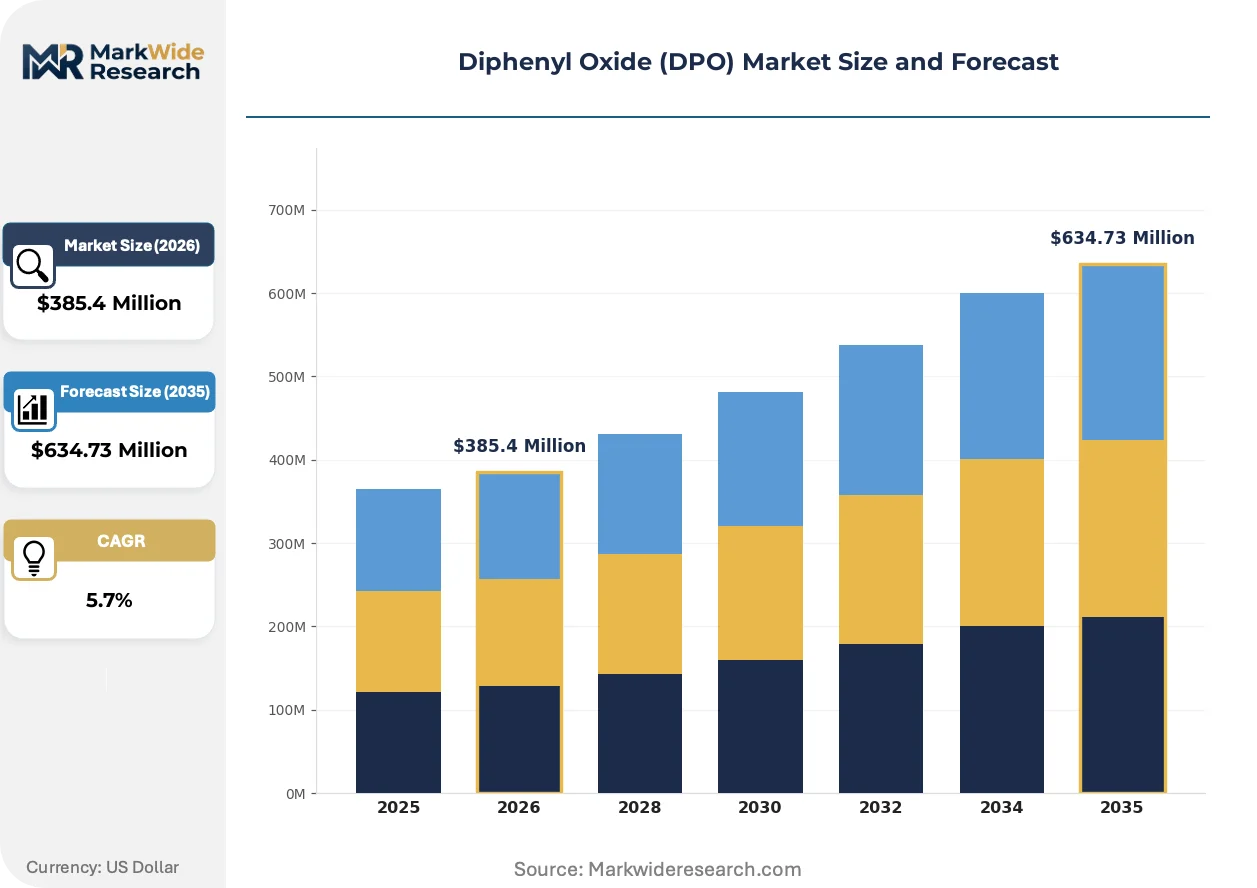
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $634.73 Million |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flakes, Granules, Liquid, Powder Application: Heat Transfer Fluids, Solvent, Chemical Intermediate, Plastic Additive End User: Chemical Manufacturing, Pharmaceutical, Agrochemicals, Plastics Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesale |
| Companies Covered | Solvay S.A., Lanxess AG, Eastman Chemical Company, INEOS Group Holdings S.A., Arkema Group, Dow, BASF SE, Jiangsu Zhongneng Chemical Technology Co. Ltd., SI Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diphenyl Oxide (DPO) Market Strategic Shifts
Process intensification and regulatory harmonization pressures are converging to reshape how DPO is manufactured, specified, and procured across industrial value chains.
Membrane separation technology for post-reaction purification is electrifying quality consistency in high-purity DPO production. Specialty chemical distributors serving pharmaceutical synthesis customers are adopting membrane-polished grades to reduce downstream distillation burdens. This capability compression is enabling smaller batch producers to meet FDA intermediate specifications without capital-intensive crystallization investments.
REACH Annex XIV authorization candidate listing for certain chlorinated aromatic byproducts is tightening emission control mandates at European production facilities. Industrial heat transfer fluid blenders face reformulation timelines to exclude restricted substance concentrations above threshold limits. German chemical processors are accelerating supply chain audits to verify registered substance compliance across imported DPO volumes.
Specification-driven procurement is consolidating buyer power among large chemical manufacturing conglomerates with centralized technical standards. Distributors serving mid-scale agrochemical synthesis operations are losing volume to direct mill relationships with qualified producers. This channel compression is most visible in China's Shandong and Jiangsu chemical clusters where domestic producers have established technical service partnerships with downstream formulators.
Diphenyl Oxide (DPO) Market Segmentation
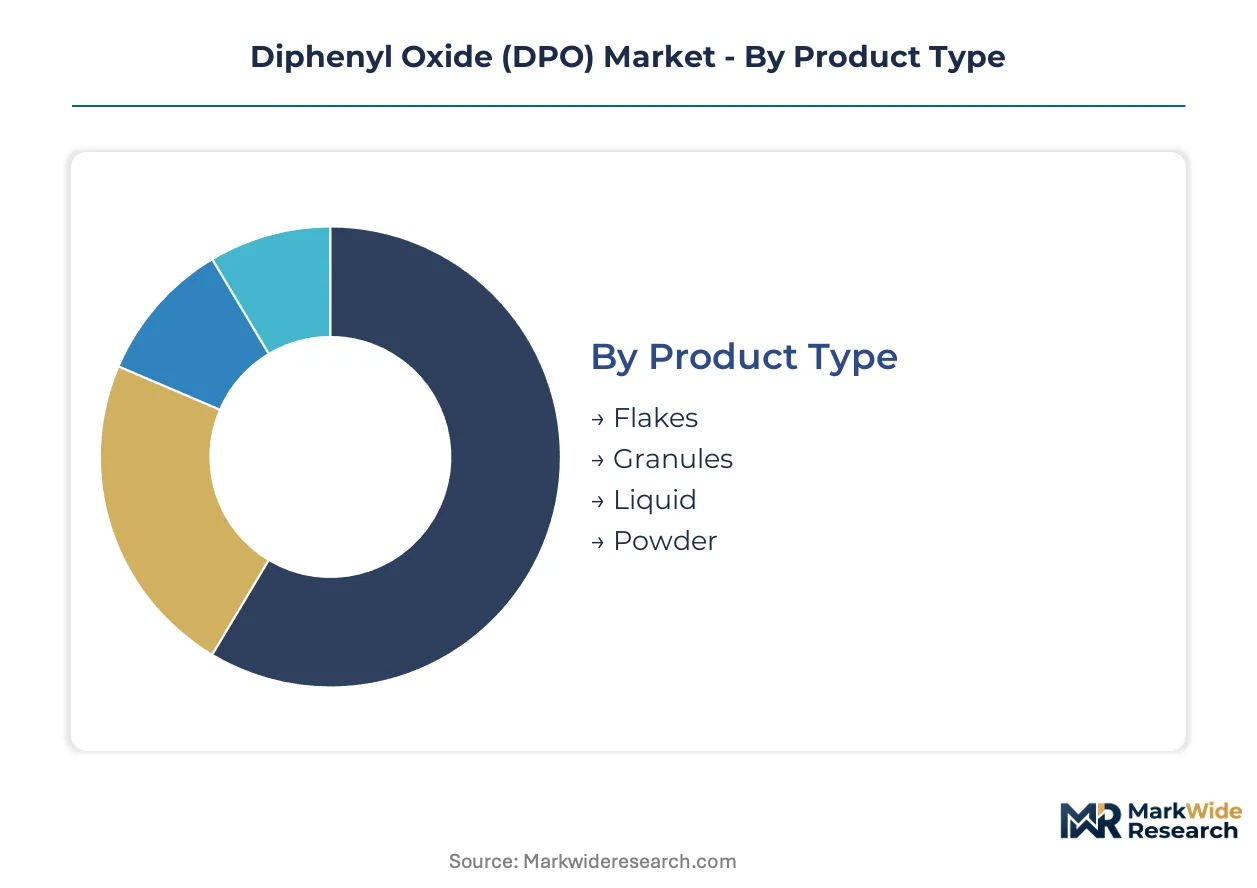
DPO procurement patterns diverge sharply across physical forms and application contexts, with specification requirements driving distinct supply relationships. Understanding these segment boundaries clarifies why certain producers command premium positioning while others compete on volume throughput.
Product Type:
Facility thermal system upgrades are reshaping grade selection, as chemical processors retrofit legacy infrastructure with higher-purity formulations that demand specific physical states for compatibility.
- Liquid:Bulk industrial offtake dominates this formulation, with tanker-delivered volumes serving continuous-process chemical manufacturing in China's Shandong and Jiangsu clusters. MEE emissions compliance costs are pushing domestic Chinese producers toward liquid-grade specialization to capture economies of scale.
- Flakes:Solid-state DPO enables precise automated dosing in pharmaceutical intermediate synthesis, where batch reproducibility requirements exceed liquid handling tolerances. CDSCO-aligned Indian pharmaceutical manufacturers are expanding flake-grade procurement relationships with qualified European exporters.
- Granules:Intermediate particle size suits agrochemical formulation lines requiring controlled dissolution rates without dust generation hazards.
- Powder:Fine-milled grades serve specialty etherification reactions where surface area maximization accelerates reaction kinetics.
Liquid sits at the top of the volume ranking, with Flakes climbing the fastest.
Application:
Cost tier stratification separates commodity thermal fluid contracts from premium chemical intermediate supply, with specification stringency determining margin capture.
- Heat Transfer Fluids:Established deployment across chemical processing infrastructure commands the largest tonnage position, with EPA TSCA compliance and REACH registration requirements filtering qualified suppliers. German chemical processors are consolidating procurement through Rotterdam hub relationships to secure registered substance documentation.
- Chemical Intermediate:Grignard reaction solvents and etherification precursors generate premium margins, with FDA and EMA intermediate specifications restricting supply to membrane-polished production capabilities. Agrochemical and active pharmaceutical ingredient manufacturers are expanding offtake for this application.
- Solvent:Extraction and purification processes in specialty chemical synthesis utilize DPO for its thermal stability and selective solubility properties.
- Plastic Additive:Flame retardant and processing aid applications leverage DPO's aromatic ether structure for polymer compatibility.
Heat Transfer Fluids maintains volume leadership, though Chemical Intermediate gains share fastest on margin expansion.
End User:
Customer type concentration varies by certification burden, with pharmaceutical and agrochemical buyers demanding documentation intensity that excludes commodity suppliers.
- Chemical Manufacturing:Continuous-process facilities with decades-old thermal fluid infrastructure drive replacement-cycle demand, particularly in US Gulf Coast and German Ruhr industrial corridors. Compatibility testing burdens slow upgrade timelines for higher-purity DPO grades.
- Pharmaceutical:Active pharmaceutical ingredient manufacturers require FDA and EMA intermediate specifications that concentrate supply among membrane-polished producers with established drug master file relationships.
- Agrochemicals:Synthesis operations in India and China are expanding DPO offtake for pesticide intermediate production, with BIS and GB standardization creating qualified supplier lists.
- Plastics:Polymer additive applications serve commodity compounders with lower specification barriers and price-sensitive procurement patterns.
Chemical Manufacturing anchors volume demand, with Pharmaceutical expanding most quickly on specification premium capture.
Distribution Channel:
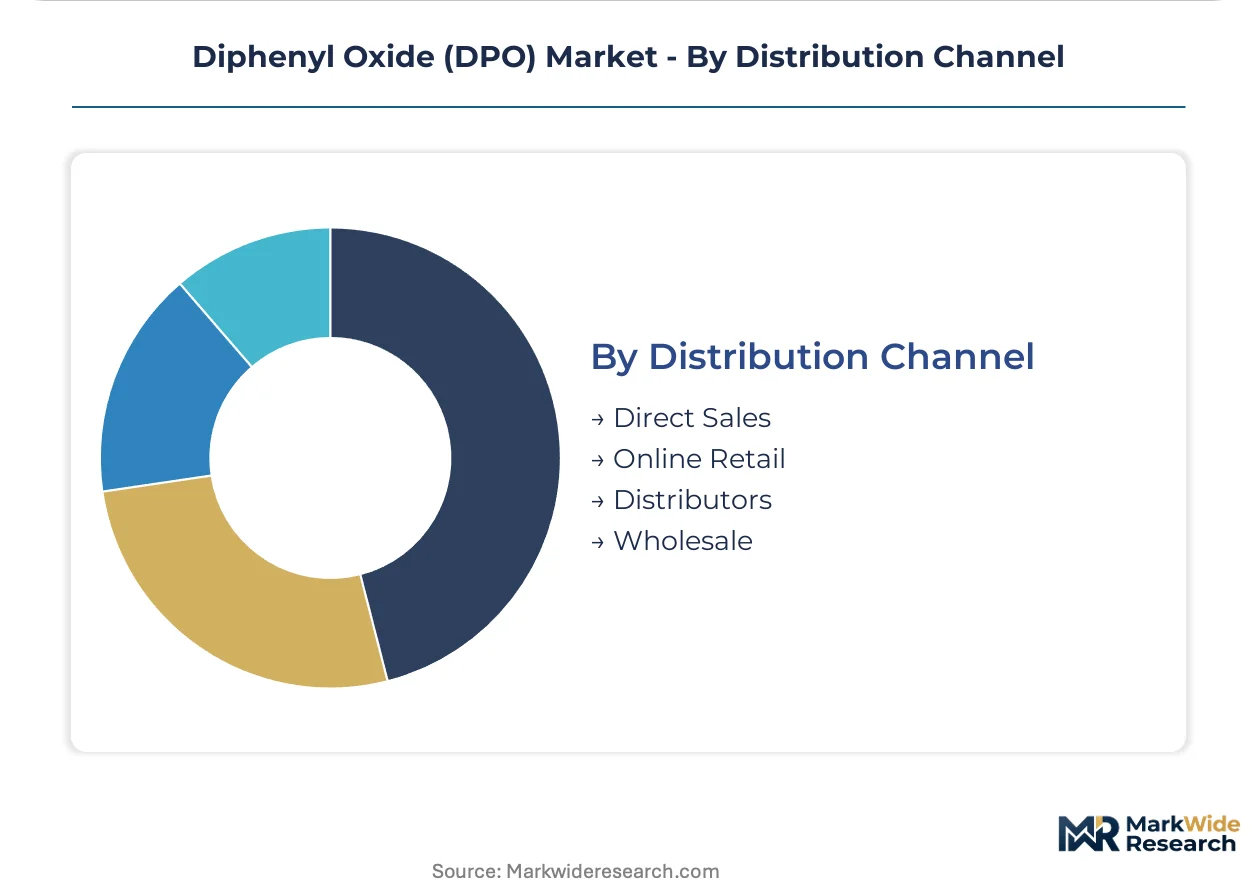
Supply concentration dynamics favor direct mill relationships for large-volume chemical conglomerates, while mid-scale buyers remain dependent on distributor technical service capabilities.
- Direct Sales:Large chemical manufacturing conglomerates with centralized technical standards are consolidating procurement through direct producer relationships, bypassing distributor margins. This channel compression is most visible in China's domestic chemical clusters.
- Distributors:Specialty chemical distributors serving pharmaceutical synthesis customers retain relevance through membrane-polished grade access and regulatory documentation support.
- Wholesale:Bulk liquid volumes move through tank farm and terminal networks serving regional chemical processing hubs.
- Online Retail:Small-laboratory and research-scale procurement utilizes digital channels for sample and pilot-scale quantities.
Direct Sales leads volume throughput, with Distributors defending position fastest through technical service differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Shandong and Jiangsu chemical clusters anchor the dominant share of DPO manufacturing capacity, with domestic producers scaling membrane-polished output to serve pharmaceutical intermediate demand. EPA TSCA compliance costs and REACH registration barriers are reshaping import flows into the United States and European Union.
China
Shandong and Jiangsu provinces concentrate domestic DPO production, with chemical manufacturers upgrading thermal fluid infrastructure under MEE emissions standards. GB standardization for volatile organic compounds is filtering qualified producers toward integrated environmental controls. Domestic specialty chemical producers in these coastal clusters are expanding downstream agrochemical synthesis capacity.
United States
Gulf Coast chemical processors drive replacement-cycle demand for heat transfer fluid grades, with EPA TSCA Section 5 pre-manufacture notification pathways creating regulatory moats. OSHA workplace exposure limits govern chlorobenzene derivative handling at Texas and Louisiana production facilities. Houston-area distributors are consolidating procurement relationships with REACH-registered European suppliers.
Germany
Ruhr industrial corridor facilities retrofit decades-old thermal systems, with ECHA REACH dossier requirements filtering qualified import sources. German chemical processors concentrate procurement through Rotterdam and Antwerp hub relationships to secure registered substance documentation. BASF SE and Lanxess AG anchor domestic production expertise in Ludwigshafen and Leverkusen.
India
Maharashtra and Gujarat pharmaceutical manufacturers expand CDSCO-aligned intermediate demand, with BIS standardization for industrial heat transfer fluids opening qualified supply relationships. Mumbai-Pune chemical clusters are establishing technical service partnerships with membrane-polished grade exporters. Domestic formulators are automating flake-grade dosing systems for agrochemical synthesis.
Japan
Kanto and Kansai chemical processors maintain stringent JIS quality protocols for pharmaceutical-grade DPO procurement. METI industrial safety standards govern aromatic ether handling at Osaka and Nagoya manufacturing facilities. Japanese agrochemical producers are sourcing flake grades for precision batch control in pesticide intermediate synthesis.
Diphenyl Oxide (DPO) Market Competitive Environment
Capacity expansion dominates the current landscape as integrated aromatics producers scale membrane-polished output to capture pharmaceutical intermediate premiums. The vendor base stratifies between multinational chemical conglomerates with captive feedstock positions and regional specialists serving bulk industrial offtake. Three archetypes define positioning: integrated aromatics majors, pharmaceutical-grade specialists, and commodity-scale regional producers. Geographic expansion and portfolio diversification toward high-purity grades represent the dominant competitive moves.
Among European integrated producers, Solvay S.A. and Lanxess AG occupy positions anchored by backward control over chlorobenzene feedstock chains. Eastman Chemical Company exemplifies the pharmaceutical-grade specialist archetype through FDA-aligned quality protocols. These three entities represent the tier capturing premium margins in chemical intermediate applications while commodity-scale competition concentrates in Chinese domestic clusters.
| Leading Market Players |
|---|
| Solvay S.A. |
| Lanxess AG |
| Eastman Chemical Company |
| INEOS Group Holdings S.A. |
| Arkema Group |
| Dow |
| BASF SE |
| Jiangsu Zhongneng Chemical Technology Co. Ltd. |
| SI Group |
| Others |
Value Chain & Pricing Dynamics
Membrane-polished pharmaceutical grades and commodity industrial liquids occupy divergent pricing bands that reshape procurement geography. REACH-registered European supply commands substantial premia over Chinese bulk volumes, yet MEE emissions compliance costs are compressing that spread as domestic producers scale membrane capabilities.
Pricing Analysis
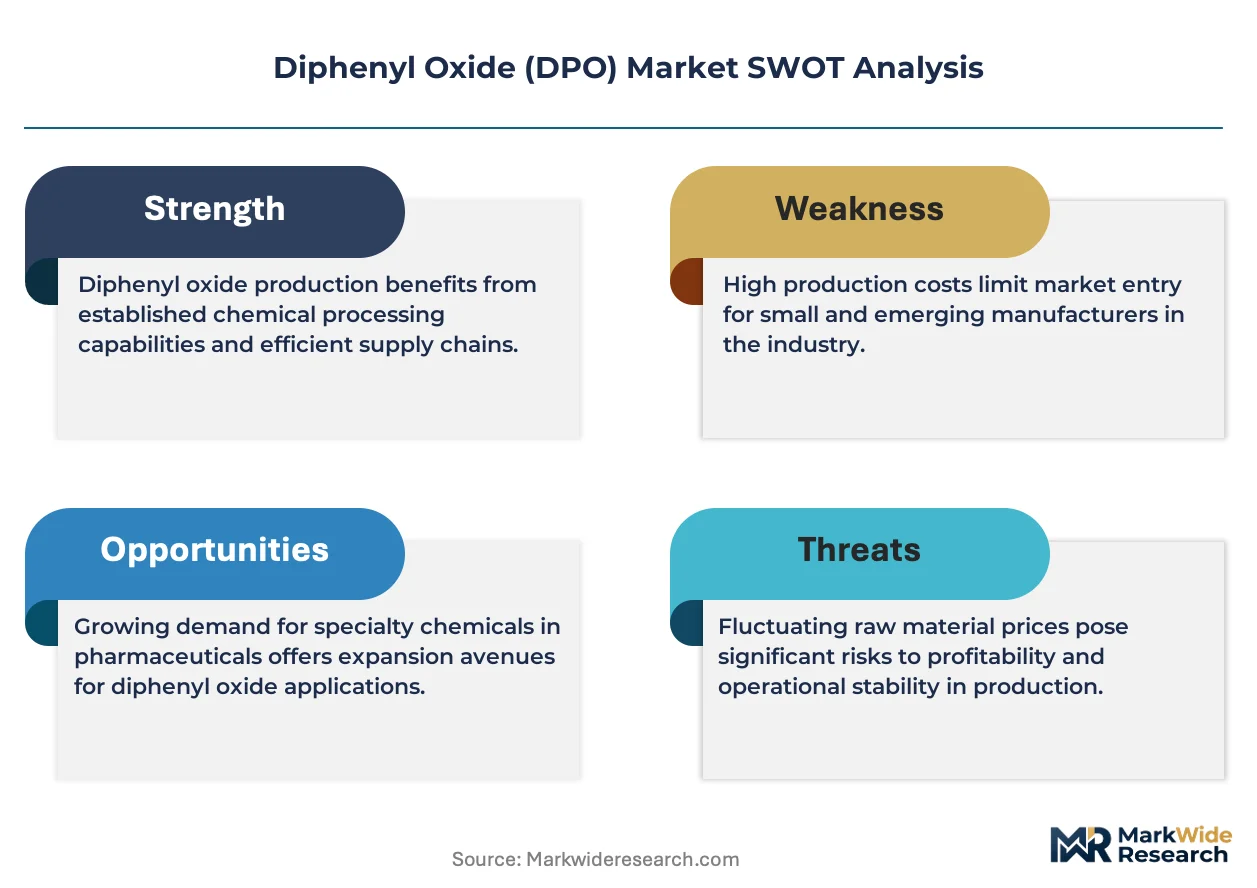
Chlorobenzene feedstock pass-through dominates cost structures for non-integrated producers, with benzene-chlorine derivative volatility compressing margin predictability. Three-tier pricing structure across pharmaceutical-grade, industrial-purity, and bulk commodity levels reflects certification burden and thermal stability benchmarks. Pricing pressure stems from synthetic ester substitution in concentrated solar power above 300°C, where polyol esters claim oxidative stability advantages. Chemical manufacturing conglomerates with centralized technical standards exhibit lowest price sensitivity, while mid-scale agrochemical formulators face acute margin pressure.
Supply Chain Analysis
REACH registration and FDA intermediate specifications gate qualified supply, concentrating pharmaceutical-grade flows through Rotterdam and Antwerp hub relationships. Manufacturing capacity clusters in China, Germany, and India, with Shandong and Jiangsu provinces anchoring membrane-polished expansion. Copper-catalyzed Ullmann condensation draws from chlorobenzene, phenol, and copper catalyst inputs. Single-source vulnerability concentrates in European import dependence on qualified Asian exporters. Distribution runs through direct mill relationships for large chemical conglomerates, with specialty distributors retaining pharmaceutical synthesis documentation roles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic-arbitrage opportunities emerge from divergent MEE emissions compliance costs in China versus EPA TSCA registration burdens in the United States, enabling qualified producers to capture margin by routing supply through optimal regulatory jurisdictions.
For Market Incumbents: Hedge synthetic ester substitution threats by accelerating membrane-polished capacity additions in China's Jiangsu corridor, where integrated environmental controls satisfy both domestic MEE standards and export-facing REACH dossier requirements. Backward integration into chlorobenzene feedstock secures margin predictability against benzene derivative volatility. Channel control through direct technical service partnerships with pharmaceutical API manufacturers defends premium positioning against distributor disintermediation.
For New Entrants and Emerging Players: Launch via specialty distributor relationships serving CDSCO-aligned Indian pharmaceutical manufacturers, where flake-grade precision dosing demand outpaces qualified supply. White-space concentration appears in agrochemical synthesis automation, where solid-state DPO enables batch reproducibility that liquid handling cannot match. Target BIS-standardized industrial heat transfer fluid procurement in Maharashtra and Gujarat chemical clusters, where domestic formulators seek alternatives to European import dependence.
For Investors and Strategic Acquirers: Asymmetric upside sits with membrane-polished specialists possessing existing drug master file relationships and EPA PMN submission capabilities. Long-term viability across the analysis window favors producers with dual jurisdiction compliance infrastructure as regulatory divergence intensifies. Watch for inflection in chlorobenzene feedstock contract structures, where backward-integrated aromatics majors signal pricing power consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chlorobenzene Feedstock | Captive phenol-chlorine derivative supply secures margin predictability against benzene volatility. |
| Membrane-Polished Capacity Expansion | Membrane separation technology enables FDA intermediate specifications without crystallization capital intensity. |
| REACH-Registered Import Hub Relationships | Rotterdam and Antwerp concentration provides registered substance documentation for European chemical processors. |
| Flake-Grade Automation Partnerships | Precision dosing systems in agrochemical synthesis capture premium positioning against liquid bulk alternatives. |
| Dual Jurisdiction Compliance Investment | EPA TSCA and ECHA REACH dossier capabilities create regulatory moats as classification divergence intensifies. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plant managers at Shandong and Jiangsu production facilities, procurement leads at German Ruhr chemical processors, pharmaceutical intermediate synthesis directors, and specialty chemical distribution channel partners with secondary validation against customs trade data, ACC and Cefic industry reports, EPA TSCA filings, ECHA registration databases, and SEC 10-K disclosures from integrated aromatics producers. Bottom-up capacity assessments and top-down demand modeling triangulated volume estimates.
Segment-weighting approaches distributed value across grade tier, end-use application, physical form, and regional production hub dimensions throughout the projection horizon. CAGRs derived from regression analysis against chlorobenzene pricing indices, MEE emissions compliance cost trajectories, and pharmaceutical intermediate demand expansion. Industry-specific inputs included Ullmann condensation yield rates, membrane separation adoption curves, and REACH registration timeline assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt chlorobenzene feedstock disruption or accelerated synthetic ester substitution in high-temperature thermal applications. Model outputs reflect assumptions regarding regulatory harmonization pace and pharmaceutical outsourcing trends. A model refresh is warranted upon material change in EPA-ECHA classification divergence or MEE emissions standard enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Europe Antifreeze Coolant Market
Industrial Chemicals
Global Ethylene Carbonate Market
Industrial Chemicals
Pelletized Activated Carbon Market
Industrial Chemicals
Gypsum-Based Products Market
Industrial Chemicals
Toluene Diisocyanates (TDI) Market
Industrial Chemicals
1-Octanol Market
Industrial Chemicals
Global CMP Slurry Market
Industrial Chemicals
Dicumyl Peroxide Market
Industrial Chemicals
VOC Concentrator Market
Industrial Chemicals
Aerosol Sprayers Market
Industrial Chemicals
Calciner Market
Industrial Chemicals
N-Ethyl-2-Pyrrolidone Market
Industrial Chemicals
Naphthenic Acid Market
Industrial Chemicals
Drag Reducing Agents Market
Industrial Chemicals
Metal Treatment Chemical Market
Industrial Chemicals
Chrome Plating Market