
 Polyepoxysuccinic Acid Market | 2026-2036
Polyepoxysuccinic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Polyepoxysuccinic Acid Market Analytics
ISO 14001 environmental management certification is redrawing competitive boundaries in polyepoxysuccinic acid supply. Nippon Shokubai leverages its integrated maleic anhydride feedstock position to control raw material costs across Asian markets. Dow anchors its presence through specialized water treatment application laboratories in North America and Europe. Evonik differentiates via high-purity pharmaceutical-grade production capabilities that serve stringent regulatory channels.
Polyepoxysuccinic acid is a biodegradable polycarboxylic acid polymer synthesized through epoxidation of maleic acid followed by polymerization, typically yielding molecular weights between 400 and 800 g/mol that function as calcium carbonate scale inhibitors and dispersants in aqueous systems. Liquid formulations dominate volume shipments due to ease of dosing in continuous water treatment operations, while powder grades command margin premiums in remote mining and oilfield applications where freight costs favor reduced water content. The corrosion inhibitor application segment leads value generation as power plants and desalination facilities replace phosphorus-based programs with phosphorus-free alternatives.
REACH registration requirements in Europe and China's MEE environmental discharge standards are accelerating substitution away from traditional phosphonate chemistries. EPA guidelines on nutrient pollution limits in US watersheds are expanding addressable demand for biodegradable antiscalants in cooling tower and boiler applications. Stakeholders must monitor regulatory timeline synchronization across jurisdictions, as divergent compliance deadlines will create arbitrage opportunities for manufacturers with multi-plant certification portfolios.
Market Dynamics
Biodegradable antiscalant mandates are restructuring procurement priorities across municipal water treatment networks, with phosphorus-free formulation requirements now embedded in discharge permits across multiple jurisdictions.
Growth Catalysts
- REACH Phosphorus Restrictions:ECHA's tightening limits on phosphonate discharge in European cooling tower operations redirect specification demand toward polyepoxysuccinic acid alternatives.
- Desalination Capacity Expansion:Reverse osmosis facilities in Saudi Arabia and Israel require high-performance scale inhibitors compatible with membrane sensitivity thresholds.
- Shandong Manufacturing Cluster:Concentrated maleic anhydride production in China's chemical corridor compresses feedstock logistics costs for regional formulators.
Market Restraints
- Maleic Anhydride Price Volatility:Crude oil derivative fluctuations transmit directly to polyepoxysuccinic acid production economics, squeezing margin stability for non-integrated producers.
- Single-Source Feedstock Dependency:Asian supply chains concentrate maleic anhydride output among three dominant petrochemical complexes, amplifying disruption risk.
- Performance Ceiling in High-Temperature Brines:Thermal stability limitations below 120°C restrict deployment in deep oilfield extraction applications where phosphonates retain efficacy.
Strategic Opportunities
- India Municipal Water Infrastructure:Jal Jeevan Mission investments in rural pipeline networks create specification windows for biodegradable scale inhibitors in new treatment plants.
- Closed-Loop Cooling Tower Retrofits:EPA nutrient pollution limits in Chesapeake Bay watersheds mandate phosphorus-free chemistry conversions across legacy industrial facilities.
- Pharmaceutical-Grade Purity Standards:USP and EP monograph compliance for excipient applications opens margin-differentiated channels in drug manufacturing supply chains.
Industry Challenges
- ISO 14001 Certification Timeline:Environmental management system audits average 14-18 months for specialty chemical producers, delaying qualification for municipal procurement frameworks.
- Legacy Phosphonate Infrastructure Lock-In:Existing dosing equipment and analytical protocols in power generation facilities require costly retrofitting to accommodate polyepoxysuccinic acid chemistry.
- Formulation Technical Support Scarcity:Field application engineering expertise concentrates among incumbent phosphonate suppliers, constraining customer transition support capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyepoxysuccinic Acid Market |
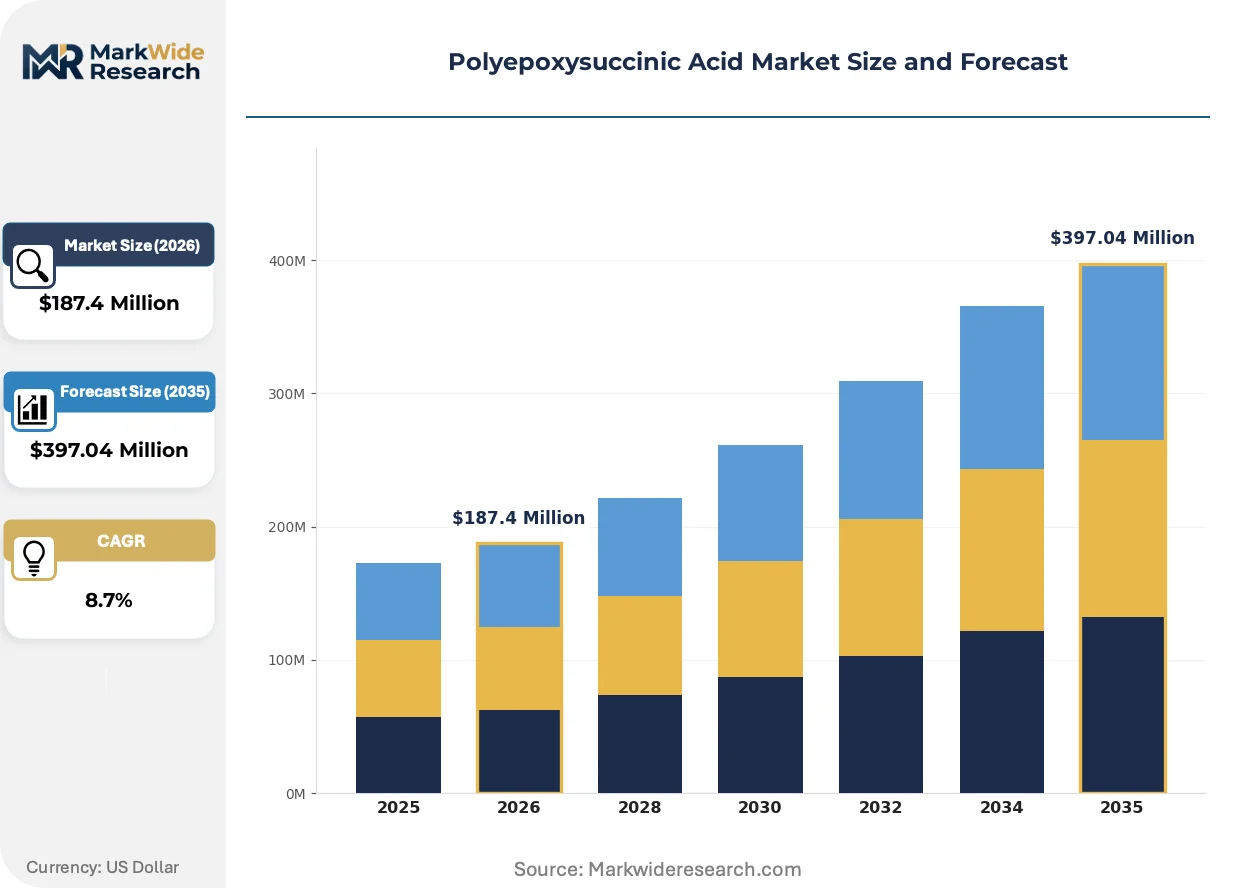
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Granule, Emulsion End Use Industry: Water Treatment, Coatings, Textile, Agriculture Application: Corrosion Inhibitor, Dispersant, Surfactant, Binder Purity Grade: Industrial Grade, Pharmaceutical Grade, Research Grade, Others |
| Companies Covered | Nippon Shokubai, Anhui Renxin, Dow, Shandong Yuanlian Chemical, Fangda Science, Evonik, Sanlian Chem, Shandong Taihe Water Treatment Technologies, Mitsubishi Rayon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyepoxysuccinic Acid Market Evolving Landscape
Phosphorus-free chemistry platforms are gaining specification traction across water-intensive industries, with formulation science advancing to close performance gaps against legacy antiscalants in demanding thermal environments.
Hybrid polyepoxysuccinic acid-zinc phosphonate copolymers are supplanting pure phosphonate programs in North American power plant cooling systems. Duke Energy and Southern Company operations teams have accelerated pilot timelines from 18 months to 6 months for chemistry validation. This compression is enabling faster market penetration for biodegradable alternatives in previously resistant heavy industrial segments.
China's MEE environmental discharge standards now enforce total phosphorus limits in Yangtze River basin industrial zones that match EU REACH stringency. Shandong and Jiangsu province environmental bureaus have synchronized enforcement calendars, eliminating regulatory arbitrage between coastal manufacturing clusters. Formulators serving both export and domestic markets must now maintain single compliance standards across all production batches.
Water treatment chemical buyers are consolidating supplier relationships from 8-12 vendors to 3-4 strategic partners with full-service technical capabilities. This concentration favors integrated producers with captive maleic anhydride supply and in-house application laboratories. The shift is most pronounced in German automotive manufacturing, where BMW and Volkswagen group facilities now require single-source accountability for entire cooling water chemistry programs.
Polyepoxysuccinic Acid Market Segmentation
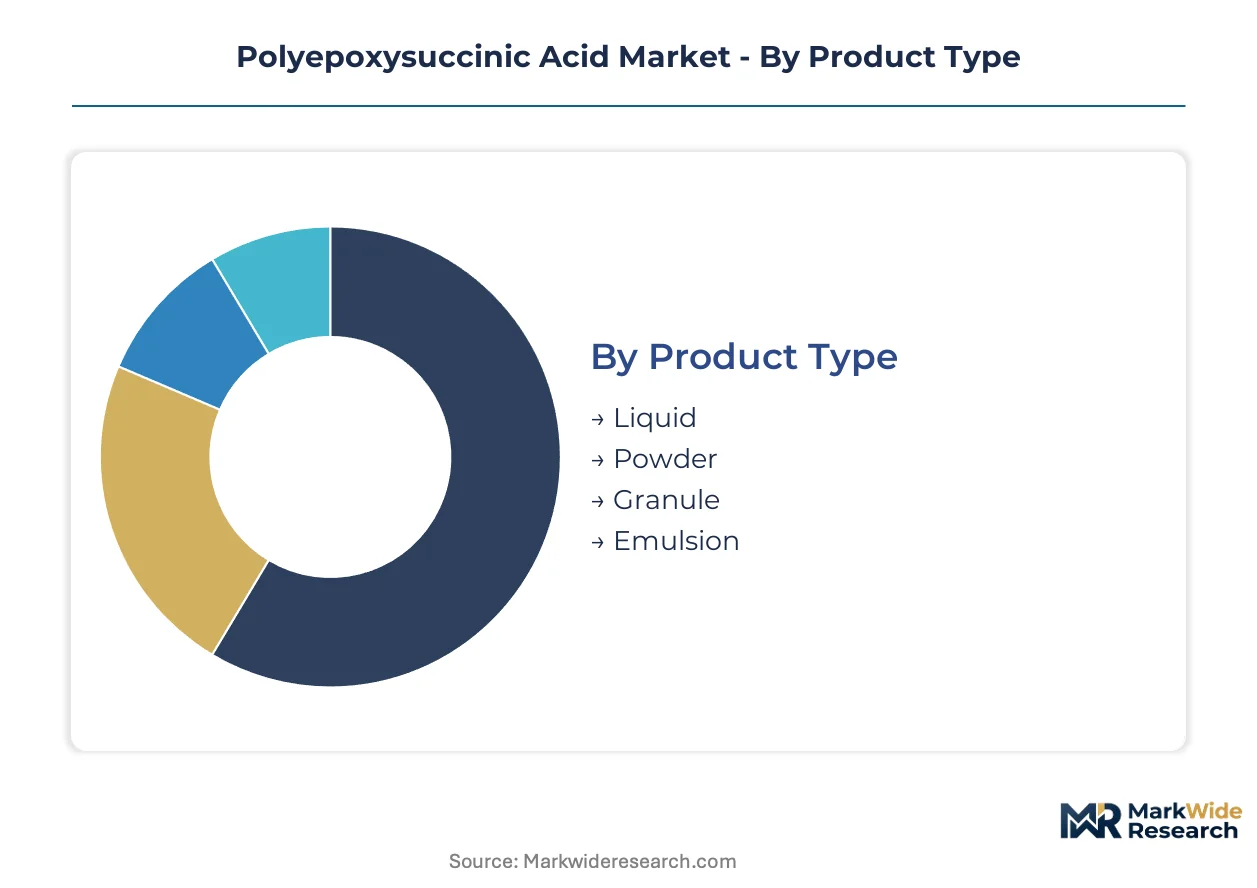
Polyepoxysuccinic acid formulation specifications diverge sharply across procurement channels, with municipal water treatment operators favoring bulk liquid deliveries while pharmaceutical and remote industrial buyers absorb premium logistics for solid grades. Channel economics dictate that segmentation strategy must align with dosing infrastructure, regulatory compliance tier, and freight cost sensitivity rather than product performance alone.
Product Type:
Liquid formulations flow through direct tanker contracts to continuous treatment operations, while powder and solid grades route through specialty chemical distributors serving intermittent-demand customers.
- Liquid:Aqueous solutions at 40-50% active content enable automated dosing in cooling towers and reverse osmosis plants without dissolution equipment. Demand concentrates in Saudi desalination facilities where membrane sensitivity requires precise concentration control and continuous feed compatibility.
- Powder:Spray-dried solids reduce water content to below 5% for freight-efficient shipment to remote mining and oilfield sites lacking liquid handling infrastructure. Australian iron ore operations and Canadian oil sands projects absorb premium pricing to offset logistics costs in regions without established chemical supply chains.
- Granule:Free-flowing particulate grades suit agricultural drip-irrigation systems and small-scale textile processing where metering equipment handles solids more reliably than viscous liquids.
- Emulsion:Stabilized oil-in-water dispersions serve coating manufacturers requiring controlled release characteristics in architectural paint formulations.
Liquid dominates installed base. Powder is where expansion concentrates.
End Use Industry:
Cost tier segmentation separates specification-grade buyers with compliance-driven procurement from price-sensitive commodity consumers.
- Water Treatment:Municipal and industrial facilities deploy polyepoxysuccinic acid as calcium carbonate scale inhibitors in cooling towers, boilers, and membrane systems. REACH phosphorus restrictions and EPA nutrient pollution limits in Chesapeake Bay watersheds are redirecting specification demand from phosphonate alternatives.
- Coatings:Architectural and industrial paint formulators utilize polyepoxysuccinic acid as dispersants and corrosion inhibitors for pigment stabilization. German automotive coating lines at BMW and Volkswagen facilities now mandate single-source accountability for entire water chemistry programs.
- Textile:Dyeing and finishing operations employ the polymer as chelating agents to sequester calcium and magnesium ions that interfere with color fixation.
- Agriculture:Drip-irrigation systems incorporate polyepoxysuccinic acid to prevent emitter clogging from carbonate precipitation in hard water sources.
Water treatment commands margin premiums. Coatings is climbing the fastest.
Application:
Volume concentration tracks end-use capital intensity, with power generation and desalination driving corrosion inhibitor tonnage while dispersant applications fragment across smaller industrial consumers.
- Corrosion Inhibitor:Phosphorus-free programs in power plants and desalination facilities replace legacy phosphonate chemistries. Duke Energy and Southern Company operations teams have compressed pilot validation timelines from 18 months to 6 months, accelerating chemistry conversion in previously resistant segments.
- Dispersant:Pigment stabilization in coatings and mineral processing suspensions relies on polyepoxysuccinic acid's polycarboxylate functionality for particle surface charge modification.
- Surfactant:Limited deployment as auxiliary wetting agents in specialized cleaning formulations where biodegradability requirements override cost considerations.
- Binder:Ceramic and refractory manufacturing employs the polymer as temporary binders for green body formation before high-temperature firing.
Corrosion inhibitor anchors revenue. Dispersant is gaining share fastest.
Purity Grade:
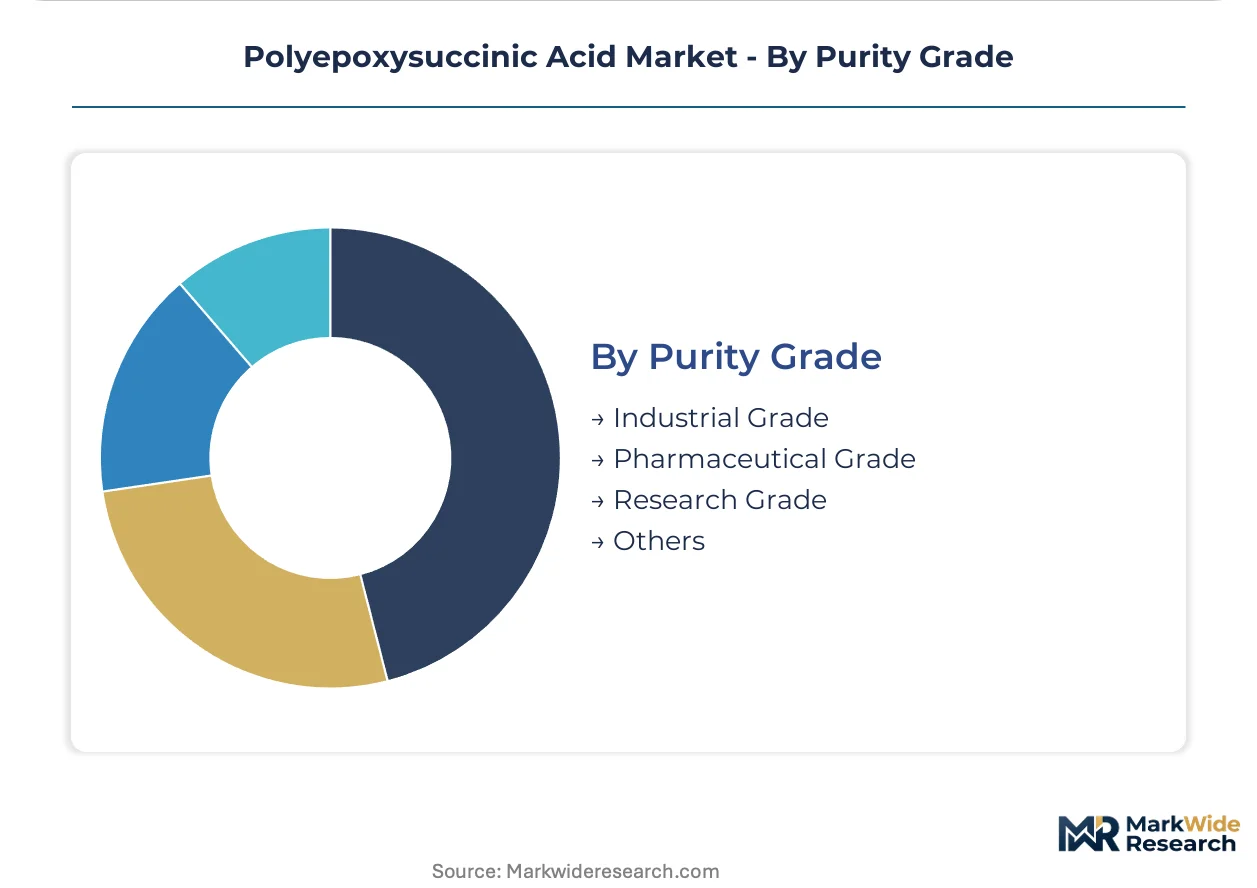
Margin structure stratifies sharply across certification tiers, with pharmaceutical and research grades capturing 3-4x industrial grade pricing through regulatory compliance overhead.
- Industrial Grade:Standard purity levels serve water treatment and coatings applications where functional performance outweighs trace impurity constraints. Shandong province manufacturers cluster production alongside maleic anhydride feedstock sources to compress logistics costs for commodity buyers.
- Pharmaceutical Grade:USP and EP monograph compliance enables excipient applications in drug manufacturing supply chains. Evonik differentiates via high-purity production capabilities that serve stringent regulatory channels with dedicated production lines and analytical protocols.
- Research Grade:Ultra-high purity specifications support analytical standards and specialty synthesis applications in academic and contract research laboratories.
- Others:Custom purity specifications serve niche applications including food-contact materials and cosmetic formulations with jurisdiction-specific compliance requirements.
Industrial grade dominates volume shipments. Pharmaceutical grade shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Qingdao port complex on China's Shandong Peninsula anchors Asia-Pacific feedstock flows for maleic anhydride derivatives, while Rotterdam's chemical terminals distribute European antiscalant formulations across North Sea industrial corridors.
China
Shandong province hosts concentrated maleic anhydride production alongside downstream water treatment chemical consumers. MEE environmental discharge standards in the Yangtze River basin now match EU REACH phosphorus limits, eliminating regulatory arbitrage between coastal manufacturing clusters. Qingdao and Weifang chemical parks compress logistics costs for regional polyepoxysuccinic acid formulators serving both domestic and export markets.
United States
Power utilities in the Ohio River Valley and Chesapeake Bay watersheds retrofit cooling tower chemistry to comply with EPA nutrient pollution limits. Duke Energy and Southern Company operations teams have compressed pilot validation timelines from 18 months to 6 months for phosphorus-free alternatives. The Gulf Coast petrochemical corridor supplies maleic anhydride feedstock to regional specialty chemical producers.
Germany
BMW and Volkswagen group facilities mandate single-source accountability for entire cooling water chemistry programs, consolidating supplier relationships. ECHA's tightening phosphonate discharge limits redirect specification demand toward biodegradable alternatives. The Rhine-Main industrial cluster around Frankfurt and Ludwigshafen concentrates formulation expertise and application laboratory capabilities.
Saudi Arabia
Reverse osmosis desalination facilities on the Red Sea and Arabian Gulf require high-performance scale inhibitors compatible with membrane sensitivity thresholds. SFDA regulatory frameworks align procurement standards with European pharmaceutical-grade specifications where applicable. Jubail Industrial City hosts integrated water treatment chemical production serving regional desalination capacity expansion.
India
Jal Jeevan Mission investments in rural pipeline networks create specification windows for biodegradable scale inhibitors in new municipal treatment plants. BIS standards for drinking water treatment chemicals are converging with ISO benchmarks for phosphorus-free formulations. Gujarat and Maharashtra industrial zones concentrate textile processing and dyeing operations that deploy polycarboxylate dispersants.
Polyepoxysuccinic Acid Market Competitive Landscape
Listed leaders compete with private specialists across certification tiers and feedstock integration levels. The vendor base stratifies between integrated petrochemical conglomerates with captive maleic anhydride supply and independent formulators purchasing feedstock on spot markets. Three archetypes dominate: Shandong-based producers leveraging regional feedstock clustering, European specialists commanding pharmaceutical-grade premiums, and diversified chemical majors with water treatment application laboratories. Competitive moves center on ISO 14001 environmental management certification acceleration and backward integration into maleic anhydride production.
Within the integrated petrochemical tier, Nippon Shokubai and Dow exemplify contrasting geographic anchoring strategies. Nippon Shokubai occupies a position tied to Asian maleic anhydride sourcing corridors, while Dow sits within North American and European technical service networks. Evonik represents the high-purity specialization archetype, with production capabilities aligned to pharmaceutical-grade regulatory channels. These three companies illustrate how feedstock security, certification depth, and application support density define competitive positioning boundaries.
| Leading Market Players |
|---|
| Nippon Shokubai |
| Anhui Renxin |
| Dow |
| Shandong Yuanlian Chemical |
| Fangda Science |
| Evonik |
| Sanlian Chem |
| Shandong Taihe Water Treatment Technologies |
| Mitsubishi Rayon |
| Others |
Value Network & Pricing Analysis
Capacity utilization rates above 85% at Shandong's maleic anhydride complexes compress feedstock conversion costs for integrated polyepoxysuccinic acid producers, while non-integrated formulators absorb spot-market volatility that sets regional price floors. This scale asymmetry concentrates margin power among producers with captive upstream supply, forcing independent competitors toward specialty-grade differentiation or volume-contract erosion.
Pricing Analysis
Volume-discount tiering structures separate municipal procurement frameworks from spot-market transactions, with three-tier pricing differentiation across pharmaceutical-grade, industrial-grade, and commodity bulk liquid segments. ISO 14001 certification premiums add 12-18% to base pricing for European municipal buyers under REACH-mandated environmental procurement rules. Price erosion runs through commodity liquid grades as Shandong manufacturers expand tanker-direct contracts to Middle Eastern desalination operators. Mining and oilfield buyers in remote geographies show lowest price sensitivity, absorbing powder-grade premiums to offset freight costs in supply-chain-constrained regions.
Supply Chain Analysis
Qingdao port congestion periodically chokes Asia-Pacific export flows for maleic anhydride derivatives, amplifying delivery risk for European and North American formulators dependent on Chinese feedstock. Supply concentrates in China, Germany, and Japan for polymer-grade maleic anhydride, while Saudi Arabia and India host emerging downstream formulation capacity. Raw material dependencies rest on crude oil derivatives, maleic anhydride monomer, and epoxidation catalysts. Single-source vulnerability concentrates among three Asian petrochemical complexes supplying 60% of regional feedstock. Distribution runs through direct tanker contracts for liquid grades and specialty chemical distributors for solid formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polyepoxysuccinic acid sits in early-cycle expansion as phosphorus-free mandates displace legacy phosphonate chemistries across municipal and industrial water treatment networks, with regulatory compliance timelines compressing adoption curves in previously resistant heavy industrial segments.
For Market Incumbents: Fortify feedstock security through backward integration into maleic anhydride production or long-term offtake agreements with Shandong-based suppliers, as crude oil derivative volatility threatens margin stability for non-integrated producers. Accelerate ISO 14001 certification timelines to capture municipal procurement frameworks that now embed environmental management requirements as qualification gates. Prioritize application laboratory investments in desalination and power generation segments where pilot validation compression is displacing incumbent phosphonate suppliers. For New Entrants and Emerging Players: Certification fast-track through USP and EP monograph compliance opens margin-differentiated pharmaceutical-grade channels where Evonik's dominance leaves room for specialized competitors. Target India's Jal Jeevan Mission infrastructure buildout, where biodegradable scale inhibitor specifications in new municipal treatment plants remain underpenetrated by established suppliers. Lead with technical service partnerships that close the field application engineering gap constraining customer transitions from phosphonate programs. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated producers with captive maleic anhydride supply and multi-year municipal procurement contracts, suggesting durable cash flow quality through commodity cycles. Over a five-to-ten-year horizon, acquisition targets should prioritize formulators with ISO 14001 certification and established dosing equipment retrofit protocols that lower customer switching costs. Monitor ECHA phosphorus restriction enforcement calendars as the inflection signal for accelerated substitution demand in European cooling tower retrofits.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Maleic Anhydride | Captive feedstock supply insulates margin stability from crude oil derivative volatility. |
| ISO 14001 Certification Acceleration | Environmental management qualification unlocks municipal procurement frameworks under tightening discharge standards. |
| Application Laboratory Expansion | Technical service density compresses pilot validation timelines for power plant and desalination conversions. |
| Pharmaceutical-Grade Purity Investment | USP and EP monograph compliance opens 3-4x pricing premiums in drug manufacturing supply chains. |
| Long-Term Municipal Supply Agreements | Contracted offtake structures convert spot-market exposure to recurring revenue streams. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, ECHA REACH registration databases, SEC 10-K filings, and China MEE discharge standard enforcement records. Interviews with water treatment plant managers, specialty chemical procurement leads, technical R&D directors at formulators, and distribution channel partners informed demand-side validation. Bottom-up triangulation across end-use industry consumption estimates converged with top-down supply-side capacity assessments.
Segmentation dimensions modeled include purity grade tier, product type formulation, end-use industry vertical, application function, and regional regulatory cluster. CAGRs were derived from regression analysis of historical consumption patterns and forward projection of regulatory compliance deadlines across jurisdictions. Forecast inputs incorporated desalination capacity expansion pipelines, power plant cooling tower retrofit schedules, and municipal water infrastructure investment programs.
Decision-makers should treat outputs as directional under assumptions of sustained phosphorus restriction enforcement and maleic anhydride supply continuity; material deviation in regulatory timelines or feedstock availability would warrant model refresh. Practitioners should keep alternative scenarios live as ECHA enforcement intensity and crude oil price volatility evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Global Antifreeze/Coolant Market
Industrial Chemicals
Trinitrotoluene (TNT) Market
Industrial Chemicals
Global Continuous Manufacturing Market
Industrial Chemicals
Enzymatically Hydrolyzed Carboxymethyl Cellulose Market
Industrial Chemicals
Global Industrial Oils Market
Industrial Chemicals
Tall Oil Fatty Acid Market
Industrial Chemicals
Industrial Cyclohexylamine Market
Industrial Chemicals
Explosive Chargers Market
Industrial Chemicals
Molecular Sieve for Air Separation Market
Industrial Chemicals
Fluidized Bed Reactors Market
Industrial Chemicals
Knitting Oils Market
Industrial Chemicals
FCCL Coating Machine Market
Industrial Chemicals
Non-PVC Waterstop Market
Industrial Chemicals
Blow Torch Market
Industrial Chemicals
Toluene Diisocyanates (TDI) Market
Industrial Chemicals
Monoethanol Amine Market