
 Formaldehyde Market | 2026-2036
Formaldehyde Market Size, Share, and Industry Trends Forecast 2026-2036
Formaldehyde Market Analysis
Market Context
The formaldehyde industry is pivoting on a widening split between low-emission specialty grades commanding formulation premiums and commodity resin volumes competing on methanol pass-through economics. BASF SE leverages captive methanol-to-formaldehyde integration across European sites to sustain margin capture in phenol-formaldehyde specialties. Hexion Inc. anchors North American supply for structural wood adhesives through controlled distribution to engineered lumber producers. Dynea Oy competes in Asian industrial binders with regional production footprints that navigate freight-cost volatility.
Technical Definition and Structural Segments
Formaldehyde is a reactive aldehyde gas (CH₂O) typically supplied as aqueous solutions (37–55% by weight with methanol stabilizer) or solid paraformaldehyde polymer for controlled release in resin synthesis, functioning primarily as a crosslinking agent in thermoset polymers and disinfectant chemistry. Phenol-formaldehyde resins dominate high-heat applications in automotive friction materials and electrical laminates where thermal stability commands durable margin pools. Urea-formaldehyde remains the volume leader in construction adhesives and insulation binders, though melamine-formaldehyde gains share in moisture-resistant furniture laminates and decorative surfaces.
Regulatory Framework and Outlook
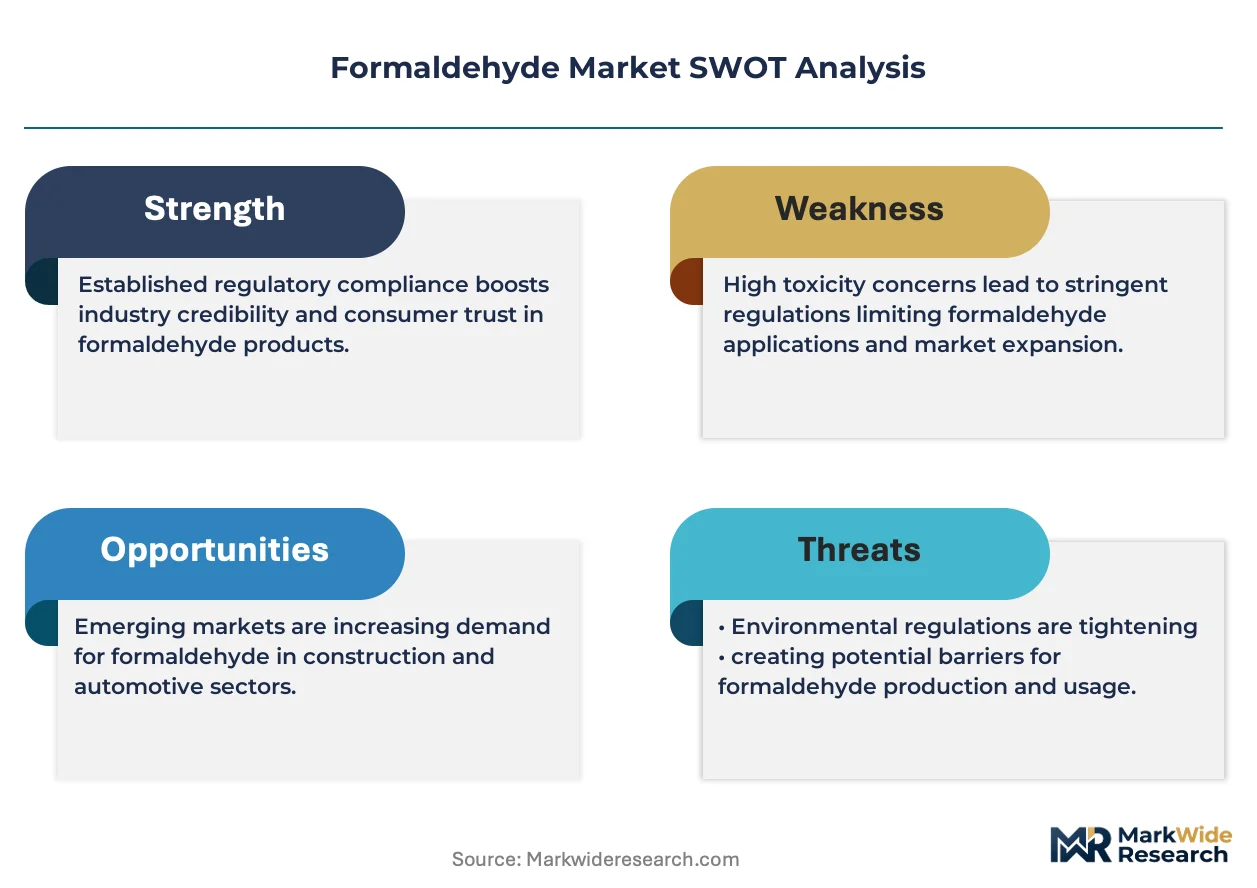
EPA TSCA Title VI sets composite wood formaldehyde emission limits in the United States, while REACH and the EU Green Deal drive substitution pressure toward bio-based aldehyde alternatives in European coatings. China's MEE enforces stricter air-quality standards on resin producers, forcing capital allocation toward scrubber retrofits and low-emitting formulations. Stakeholders must monitor regulatory divergence between emission caps and bio-based substitution mandates to align capacity investments with compliant product portfolios.
Market Dynamics
Formaldehyde market dynamics center on China's MEE emissions standards forcing a bifurcation between low-emission specialty grades and commodity resin volumes competing on methanol pass-through economics. This regulatory compression is redirecting capital toward scrubber retrofits and reformulated binders while squeezing marginal producers.
Growth Catalysts
- Construction adhesives demand:Engineered wood producers in North America and Europe are expanding consumption of phenol-formaldehyde resins for structural lumber applications. Residential retrofit programs and mass timber construction codes are amplifying order volumes.
- REACH substitution pressure:The EU Green Deal and ECHA bio-based mandates are creating premium pricing tiers for low-emitting formaldehyde formulations in coatings and laminates. Compliance differentiation now commands measurable margin capture.
- India furniture manufacturing:Uttar Pradesh and Gujarat industrial clusters are concentrating demand for urea-formaldehyde binders as export-oriented woodworking scales. Domestic resin production is expanding to match this pull.
Market Restraints
- Methanol cost volatility:Natural gas price swings and regional supply disruptions transmit directly into formaldehyde production economics. Producers without captive methanol integration face margin compression during feedstock spikes.
- EPA TSCA Title VI compliance:Composite wood emission caps in the United States require continuous testing and certification investments. Small-scale panel producers struggle with the fixed cost burden of third-party verification.
- Bio-based aldehyde substitution:Furfural and lignin-derived crosslinkers are capturing share in decorative surface applications where moisture resistance requirements are less stringent. European coatings formulators are piloting these alternatives.
Strategic Opportunities
- Southeast Asia construction:Vietnam and Indonesia building codes are formalizing engineered wood standards, creating virgin demand for structural adhesive formulations. Regional resin production capacity remains underdeveloped relative to projected needs.
- Automotive friction materials:Phenol-formaldehyde resins for brake pads and clutch facings are benefiting from electric vehicle weight increases requiring heavier-duty braking systems. Thermal stability specifications are tightening.
- China dual carbon alignment:Provincial carbon intensity targets are incentivizing formaldehyde producers to adopt methanol-to-formaldehyde process optimization and carbon capture retrofits. Early movers access preferential permitting.
Industry Challenges
- Process safety expertise:Formaldehyde's toxicity and flammability require specialized operational protocols that aging workforces in mature markets struggle to transfer. Training pipelines for chemical process operators are thinning.
- Multi-jurisdiction certification:Simultaneous compliance with EPA TSCA Title VI, REACH SVHC screening, and China's GB standards demands dedicated regulatory affairs capacity. Testing costs multiply for exporters serving multiple markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Formaldehyde Market |
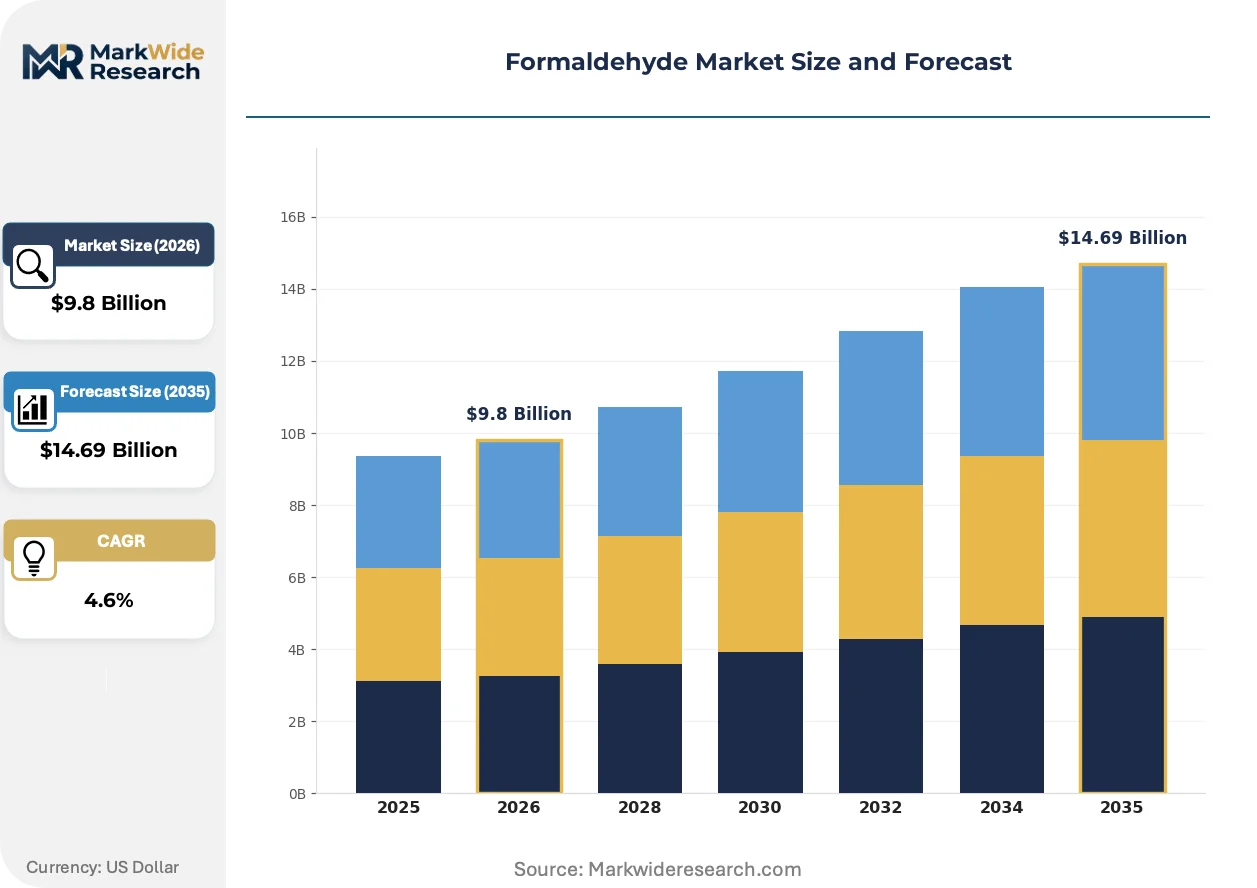
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $14.69 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Paraformaldehyde, Urea-Formaldehyde, Phenol-Formaldehyde, Melamine-Formaldehyde Application: Adhesives, Insulation, Coatings, Plastics End User: Construction, Automotive, Healthcare, Furniture Grade: Industrial, Pharmaceutical, Reagent, Technical |
| Companies Covered | Celanese Corporation, Foremark Performance Chemicals, BASF SE, Evonik Industries AG, Metafrax Chemicals, Hexion Inc., Dynea Oy, Ercros S.A., Georgia-Pacific Chemicals LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Formaldehyde Market Emerging Trajectories
Technology and regulatory forces are compressing the viable product spectrum toward lower-emission, higher-performance formulations while digital tools reshape how buyers evaluate and procure resin systems.
Paraformaldehyde solid polymer systems are integrating into automated resin synthesis lines to replace aqueous formaldehyde solutions in controlled-release applications. European engineered wood producers are adopting these systems to reduce storage hazards and improve batch consistency. This shift is integrating process safety improvements with formulation precision gains that aqueous logistics cannot match.
China's MEE Air Quality Action Plan is enforcing stricter volatile organic compound caps on formaldehyde resin manufacturing facilities. Producers in Shandong and Jiangsu provinces are installing regenerative thermal oxidizers and switching to low-methanol formulations. The construction adhesive segment is absorbing most compliance costs through reformulation investments rather than price pass-through.
Buyers in the furniture laminates sector are consolidating supplier relationships and demanding consolidated technical service bundled with resin supply. Large European and North American panel producers are reducing qualified vendor lists from dozens to handfuls. This concentration is most visible in Germany and Italy, where procurement teams now prioritize formulation support and regulatory documentation over unit pricing.
Formaldehyde Market Segmentation
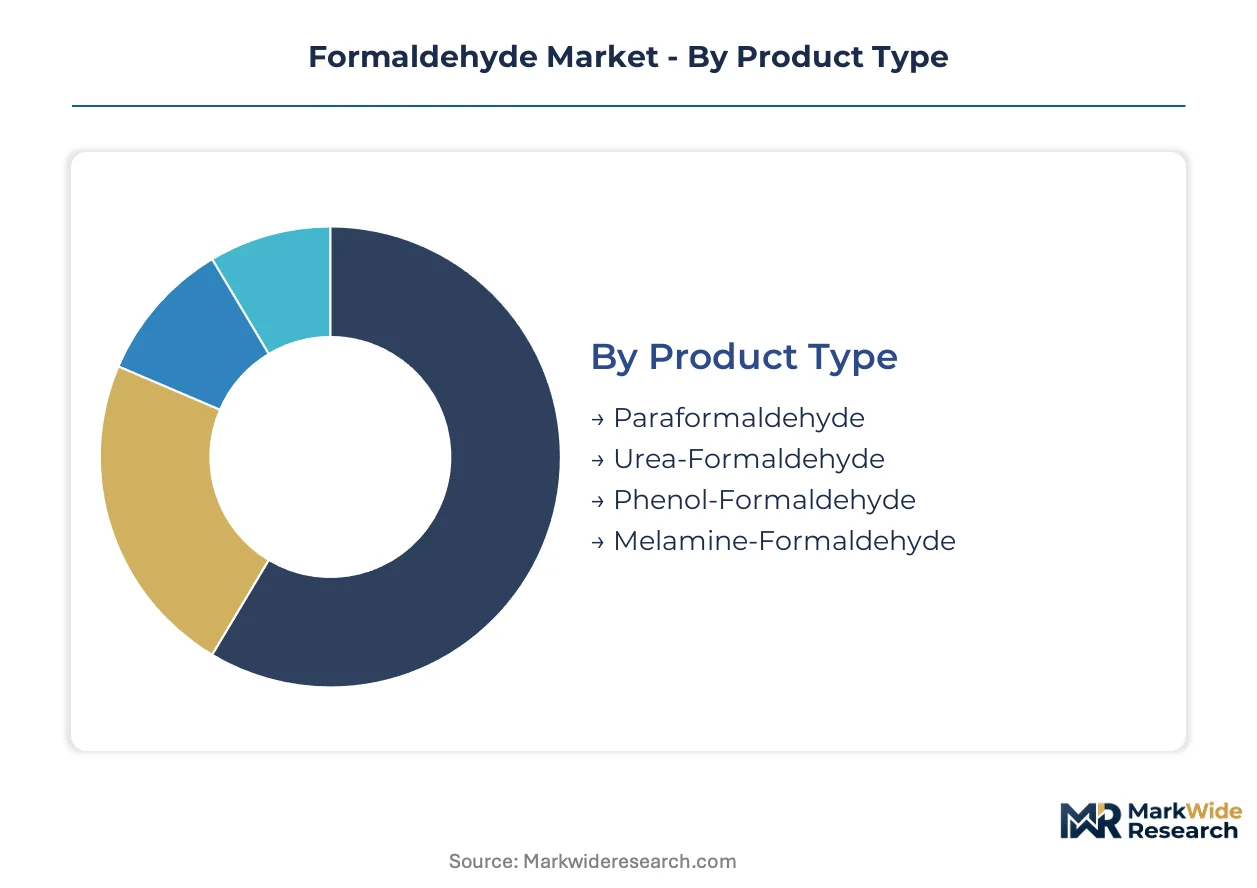
Formaldehyde market segmentation reveals how buyers trade off emission performance against methanol cost exposure. Product chemistry determines regulatory compliance pathways, while application specificity dictates formulation service requirements and pricing power.
Product Type:
Buyers select product chemistry based on thermal stability requirements and moisture resistance specifications in their end-use applications.
- Phenol-Formaldehyde:Thermosetting resins formed from phenol and formaldehyde condensation deliver superior heat resistance for automotive brake pads and electrical laminates. Demand concentrates in Germany and Japan where automotive friction material specifications are tightening for electric vehicle weight classes. Thermal stability requirements command durable margin pools despite higher raw material costs.
- Urea-Formaldehyde:The most cost-effective amino resin binds wood particles in particleboard and medium-density fiberboard through acid-catalyzed crosslinking. Construction adhesive demand in India and Vietnam absorbs volume production from Shandong province facilities navigating MEE emissions compliance. Cost sensitivity limits pricing power except in low-emission certified grades.
- Melamine-Formaldehyde:Decorative laminate binders offering improved moisture resistance for furniture surfaces and kitchen cabinetry.
- Paraformaldehyde:Solid polymer form enabling controlled-release formaldehyde in automated resin synthesis lines and pharmaceutical applications.
Volume sits with urea-formaldehyde; growth tilts toward phenol-formaldehyde.
Application:
Application selection tracks end-use durability requirements and regulatory exposure severity across building materials and industrial components.
- Adhesives:Structural wood bonding consumes the largest formaldehyde resin volumes through phenol-formaldehyde and urea-formaldehyde formulations. North American engineered lumber producers and European mass timber constructors specify emission-certified grades. Residential retrofit programs and cross-laminated timber building codes are amplifying order volumes for certified structural adhesives.
- Insulation:Urea-formaldehyde foams and binders stabilize fiberglass and mineral wool in building thermal barriers. Chinese building energy efficiency codes and European renovation wave targets are expanding specification requirements. Emission caps in Germany and France are pushing reformulation toward low-methanol binder systems.
- Coatings:Crosslinking agents for durable industrial finishes and automotive primers.
- Plastics:Molding compounds and thermoset components requiring formaldehyde-based resin matrices.
Adhesives capture the dominant share; insulation is expanding most quickly on building efficiency mandates.
End User:
End-user procurement patterns separate large-scale structural adhesive buyers from specialty pharmaceutical and medical device formulators.
- Construction:Engineered wood producers, insulation manufacturers, and decorative panel fabricators drive commodity resin volumes. Chinese mass timber projects and Indian furniture export clusters are concentrating demand geography. Procurement teams prioritize regulatory documentation and formulation support over unit pricing.
- Automotive:Friction material suppliers and electrical component manufacturers specify high-purity phenol-formaldehyde grades. Electric vehicle weight increases are requiring heavier-duty braking systems with tighter thermal stability specifications.
- Furniture:Laminate and decorative surface producers in Italy and Germany.
- Healthcare:Disinfectant and vaccine inactivant applications requiring pharmaceutical-grade specifications.
Construction anchors volume demand; automotive commands the steepest expansion trajectory on electrification trends.
Grade:
Grade differentiation separates methanol-stabilized industrial volumes from low-impurity pharmaceutical and analytical specifications.
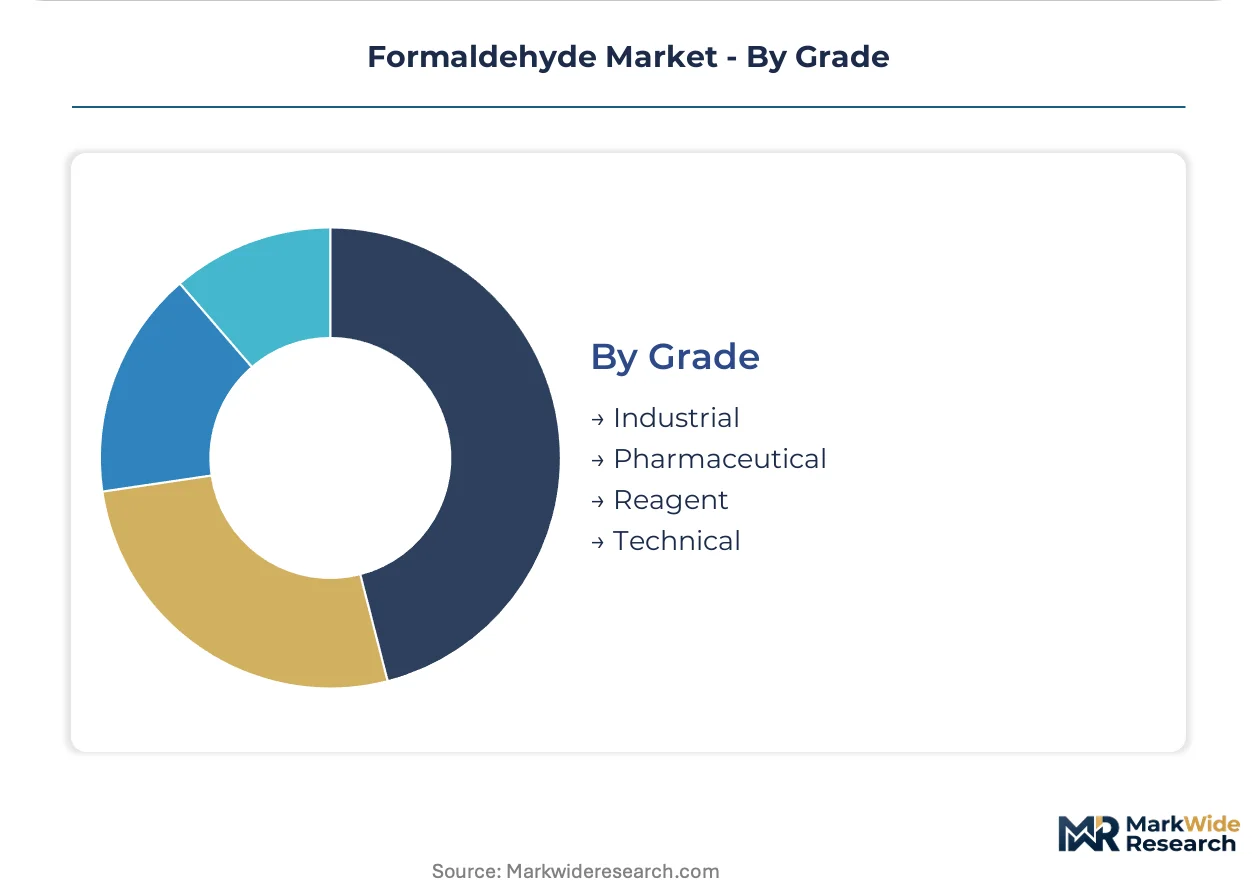
- Industrial:Aqueous solutions with methanol stabilizer for resin synthesis and general chemical manufacturing. Captive methanol integration at BASF Ludwigshafen and Hexion sites sustains margin capture against spot methanol volatility.
- Pharmaceutical:Low-methanol or methanol-free grades meeting pharmacopeial standards for vaccine production and medical disinfectants.
- Technical:Intermediate purity for specific industrial processes with controlled impurity limits.
- Reagent:High-purity analytical grade for laboratory and research applications.
Industrial grade dominates throughput; pharmaceutical grade is gaining share fastest on healthcare supply security priorities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shandong province anchors formaldehyde resin production capacity, with Jiangsu chemical clusters absorbing compliance investments under China's MEE Air Quality Action Plan. Regulatory divergence across major economies is fragmenting formulation standards and redirecting trade flows toward emission-certified grades.
China
MEE emissions standards are forcing Shandong and Jiangsu resin producers toward regenerative thermal oxidizer retrofits and low-methanol formulations. Provincial carbon intensity targets under dual carbon goals incentivize methanol-to-formaldehyde process optimization. Yangtze River Delta chemical parks are consolidating smaller facilities into larger compliant complexes.
United States
EPA TSCA Title VI composite wood emission limits drive continuous testing investments across particleboard and medium-density fiberboard producers. Engineered lumber demand concentrates in the Pacific Northwest and Southeast where mass timber building codes are formalizing. Georgia-Pacific Chemicals anchors regional supply through controlled distribution networks.
Germany
REACH SVHC screening and EU Green Deal bio-based mandates create premium pricing tiers for low-emitting formaldehyde formulations in coatings and laminates. Automotive friction material specifications are tightening for electric vehicle weight classes. Bavarian chemical sites leverage phenol-formaldehyde thermal stability expertise for brake pad applications.
India
Uttar Pradesh and Gujarat furniture manufacturing clusters concentrate demand for urea-formaldehyde binders as export-oriented woodworking scales. Domestic resin production is expanding to match import substitution priorities. BIS standards alignment with international emission benchmarks is accelerating certification investments among panel producers.
Japan
METI industrial standards enforce strict formaldehyde emission limits in construction materials, favoring melamine-formaldehyde moisture-resistant grades. Automotive electrical laminate demand from Nagoya-area suppliers supports high-purity phenol-formaldehyde consumption. Kanto region chemical producers maintain formulation precision advantages in pharmaceutical-grade specifications.
Formaldehyde Market Vendor Landscape
Premium-margin players sit above commodity-margin players across emission-certification and captive feedstock integration dimensions. The vendor base stratifies between integrated chemical conglomerates with methanol-to-formaldehyde control and regional resin specialists competing on freight-cost positioning. Three archetypes dominate: European integrated majors with specialty-grade focus, North American construction-adhesive anchors, and Asian industrial-binder competitors. Capacity expansion and low-emission formulation portfolios represent the dominant competitive moves.
Among integrated chemical conglomerates, BASF SE and Evonik Industries AG exemplify the premium-tier archetype through European site networks and specialty-grade positioning. Hexion Inc. occupies a distinct anchor position in North American structural wood adhesives. Dynea Oy represents the regional specialist model with Asian production footprints navigating freight-cost volatility.
| Leading Market Players |
|---|
| Celanese Corporation |
| Foremark Performance Chemicals |
| BASF SE |
| Evonik Industries AG |
| Metafrax Chemicals |
| Hexion Inc. |
| Dynea Oy |
| Ercros S.A. |
| Georgia-Pacific Chemicals LLC |
| Others |
Supply Flow & Price Mechanics
Engineered lumber producers in the Pacific Northwest and Southeast United States anchor demand concentration for structural adhesive formulations, locking pricing power with suppliers who bundle regulatory documentation and technical service. This buyer archetype's procurement consolidation from dozens to handfuls of qualified vendors has shifted negotiation leverage toward emission-certified grades with captive methanol integration.
Pricing Analysis
Value-based pricing anchored to thermal stability performance in automotive friction materials commands durable margin pools despite higher phenol input costs. Three-tier pricing structure across premium, standard, and economy levels separates low-emission certified grades from commodity resin volumes competing on methanol pass-through economics. Price differentiation rests on REACH SVHC screening compliance and EPA TSCA Title VI certification tier. Pricing pressure stems from methanol cost volatility transmitting directly into production economics for non-integrated producers. Small-scale panel producers exhibit highest price sensitivity due to fixed compliance cost burdens, while automotive OEMs demonstrate lowest sensitivity given thermal specification requirements.
Supply Chain Analysis
Certification gating through EPA TSCA Title VI, REACH SVHC screening, and China's GB standards fragments supplier qualification and extends onboarding timelines. Geographic supply concentrates in China, Germany, and the United States, with Shandong province and Jiangsu chemical parks anchoring Asian capacity. Raw material dependencies draw from methanol feedstock, phenol derivatives, and urea intermediates. Single-source vulnerability runs through concentrated methanol production clusters exposed to natural gas price swings. Distribution runs through controlled allocation networks to engineered wood producers, with technical service bundling replacing spot transactional procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The formaldehyde market sits in a technology-transition phase as paraformaldehyde solid polymer systems displace aqueous solutions in automated resin synthesis lines, integrating process safety with batch precision.
For Market Incumbents: Acquire regenerative thermal oxidizer assets and low-methanol formulation IP to preempt MEE compliance deadlines in Shandong and Jiangsu provinces. Consolidate distribution relationships with large European and North American panel producers who are reducing qualified vendor lists. Backward integration into captive methanol production anchors margin capture against feedstock volatility threatening commodity resin competitors. For New Entrants and Emerging Players: Capture white-space demand in Vietnam and Indonesia where building codes are formalizing engineered wood standards ahead of regional resin capacity expansion. Target automotive friction material suppliers serving electric vehicle weight-class braking systems with phenol-formaldehyde thermal stability specifications. Lead with formulation support and regulatory documentation bundled with resin supply rather than unit pricing. For Investors and Strategic Acquirers: The window for entry favors integrated chemical conglomerates with methanol-to-formaldehyde control and specialty-grade positioning. Long-term viability hinges on dual carbon alignment in China and bio-based substitution resilience in Europe. Watch provincial carbon intensity target enforcement as inflection indicator for preferential permitting access.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Methanol | BASF Ludwigshafen and Hexion sites sustain margin capture against spot volatility. |
| Low-Emission Formulation Portfolio | REACH and EPA TSCA Title VI compliance commands measurable premium pricing tiers. |
| Regenerative Thermal Oxidizer Retrofit | Shandong and Jiangsu producers access MEE compliance and preferential permitting. |
| Technical Service Bundling | German and Italian panel producers prioritize formulation support over unit pricing. |
| Southeast Asia Capacity Positioning | Vietnam and Indonesia building codes create virgin demand for structural adhesives. |
Methodological Framework
SEC 10-K filings, Cefic industry reports, and Chinese customs trade data formed the secondary backbone, cross-referenced with primary interviews conducted with plant managers at resin synthesis facilities, procurement leads at engineered wood OEMs, and technical R&D directors at adhesive formulators. Bottom-up capacity and consumption modeling triangulated against top-down macroeconomic indicators across the analysis window.
Historical trendline analysis of methanol-formaldehyde production economics and emission-standard adoption curves informed the analytical framework. Segmentation dimensions modeled include product chemistry tier, end-use industry vertical, certification grade level, and regional regulatory cluster. CAGRs were derived from slope analysis of volume trajectories adjusted for capacity utilization rates and compliance cost absorption patterns.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to MEE enforcement intensity in China and bio-based aldehyde substitution rates in European coatings. Forecasts reflect documented assumptions around methanol price stabilization and mass timber building code adoption. A model refresh is warranted upon material change in provincial carbon intensity target enforcement or EPA TSCA Title VI testing cost structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Food Grade Sodium Hypochlorite Market
Industrial Chemicals
VOC Concentrator Market
Industrial Chemicals
Europe Surface Treatment Chemicals Market
Industrial Chemicals
Fatty Amines Market
Industrial Chemicals
Asia-Pacific Activated Carbon Market
Industrial Chemicals
Wire Compound and Cable Compound Market
Industrial Chemicals
High Viscosity Mixer Market
Industrial Chemicals
Global Foundry Chemicals Market
Industrial Chemicals
Dewatering Aids Market
Industrial Chemicals
Global Ethylene Carbonate Market
Industrial Chemicals
Hydrogenated Bisphenol a Market
Industrial Chemicals
Perchloroethylene Market
Industrial Chemicals
Global Antifreeze/Coolant Market
Industrial Chemicals
Europe Isocyanates Market
Industrial Chemicals
India Precipitated Silica Market
Industrial Chemicals
Global Flow Chemistry Market