
 Molecular Sieve Desiccants Market | 2026-2036
Molecular Sieve Desiccants Market Size, Share, and Industry Trends Forecast 2026-2036
Molecular Sieve Desiccants Market Outlook
Asset-light leasing models for pressure-swing adsorption units is narrowing the capital barrier for mid-scale chemical processors, allowing regional operators to access molecular sieve capacity without full ownership burdens. Honeywell UOP leverages its integrated catalyst-adsorbant portfolio to bundle desiccant supply with process licensing. Zeochem AG anchors its position through Swiss manufacturing precision in specialty bead formulations for electronics-grade applications. Hengye Inc. competes aggressively on bulk 4A and 13X supply to Asian petrochemical complexes.
Molecular sieve desiccants are synthetic crystalline aluminosilicates with uniform pore apertures measured in angstroms, manufactured through hydrothermal crystallization of sodium aluminosilicate gels followed by ion exchange and calcination, engineered to adsorb water and polar molecules based on kinetic diameter and polarity. The 4A and 13X product types dominate volume flows into natural gas dehydration and air separation units where pore size selectivity determines process efficiency. Pharmaceutical applications command premium positioning due to FDA validation requirements for residual moisture control in active ingredient packaging. Bulk bag packaging for petrochemical customers generates scale economies, while sachet formats for electronics and food packaging capture higher per-unit margins through precision dosing.
The EPA enforces stringent volatile organic compound limits that mandate closed-loop regeneration systems, pushing refiners toward higher-performance 5A sieves with extended cycle life. China's MEE implements dual carbon targets that accelerate replacement of glycol-based dehydration with molecular sieve units in Sichuan and Xinjiang gas fields. ISO 9001 and ASTM D4464 standards govern particle size distribution and crush strength, creating compliance thresholds that filter out low-grade suppliers. Stakeholders must monitor regulatory tightening on regeneration emissions and the shifting cost calculus between captive sieve production and merchant supply as carbon border adjustments take shape.
Market Dynamics
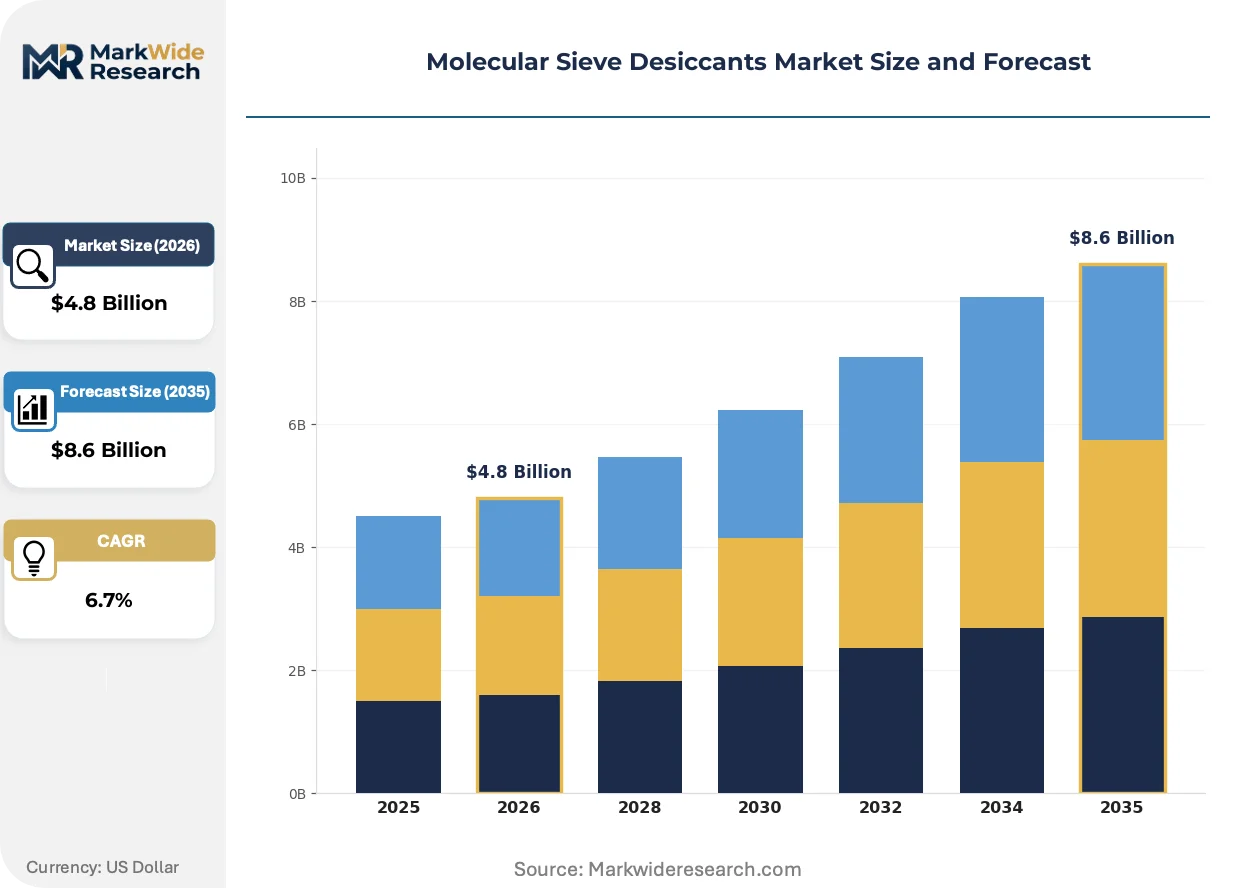
Refinery sulfur mandates and LNG export capacity buildouts are compressing replacement cycles for molecular sieve beds, forcing processors to prioritize adsorbent longevity over upfront cost minimization.
Growth Catalysts
- EPA Tier 3 gasoline sulfur limits:Petrochemical refiners on the US Gulf Coast are retrofitting catalytic reformer units with high-capacity 5A sieves to meet 10 ppm sulfur ceilings in finished gasoline.
- China's dual carbon targets:MEE enforcement is accelerating displacement of triethylene glycol dehydration with molecular sieve units in Sichuan shale gas fields and Xinjiang coalbed methane operations.
- Electronics-grade moisture control:Semiconductor fabs in Taiwan and South Korea are specifying sub-ppm residual moisture protocols for active pharmaceutical ingredient packaging, pulling premium 3A and 4A bead formulations.
Market Restraints
- Zeolite feedstock concentration:Synthetic sodium aluminosilicate gel supply clusters in Shandong Province and the US Mountain West, exposing processors to concentrated geopolitical and logistics risk.
- Energy-intensive calcination:Natural gas price volatility directly compresses margins for 13X powder manufacturers operating continuous rotary kilns.
- Glycol dehydration residual base:Triethylene glycol units retain installed cost advantages in remote gas fields with intermittent production profiles, slowing sieve penetration in marginal wells.
Strategic Opportunities
- India petrochemical expansion:Reliance Industries and Indian Oil are building ethylene crackers in Gujarat and Odisha with integrated adsorption trains, creating greenfield specification opportunities.
- Carbon capture pre-treatment:Amine-based CO2 capture units require ultra-dry feed gas, opening dedicated 4A sieve deployments ahead of liquefaction stages at US and Norwegian CCS hubs.
- Asset-light PSA leasing:Regional chemical processors are accessing molecular sieve capacity through operating leases rather than capital purchase, lowering barrier entry for mid-scale operators.
Industry Challenges
- FDA validation timelines:Pharmaceutical customers require 18-24 month stability documentation for new sieve lots, extending sales cycles and locking working capital in qualification inventories.
- Adsorbent regeneration expertise:Closed-loop thermal swing systems demand specialized technicians scarce outside major refining centers, constraining remote field deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Molecular Sieve Desiccants Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 4A, 5A, 13X, Molecular Sieve Beads Application: Petrochemical, Natural Gas, Air Drying, Pharmaceuticals End User: Food Packaging, Electronics, Chemical Manufacturing, Automotive Packaging Type: Bulk Bags, Pails, Drums, Sachets |
| Companies Covered | BASF SE, Honeywell UOP, Axens, Zeochem AG, CECA (Arkema), Clariant Produkte (Schweiz AG), W. R. Grace & Co., Tosoh Corporation, Hengye Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Molecular Sieve Desiccants Market Strategic Shifts
Process intensification and regulatory tightening are compressing the performance gap between commodity and specialty sieve grades, forcing suppliers to differentiate through integrated service bundles rather than bead specifications alone.
Structured adsorbent monoliths are migrating from laboratory-scale natural gas dehydration pilots to commercial ethylene cracker retrofits. Linde and Air Liquide are deploying honeycomb-form zeolite blocks in Texas and Louisiana olefins plants to cut pressure drop and vessel footprint. This format is migrating from niche cryogenic air separation applications toward mainstream petrochemical adsorption, threatening conventional pellet and bead suppliers with obsolescence in high-flow units.
REACH authorization requirements for synthetic zeolite precursors are tightening trace metal disclosure obligations for EU-based manufacturers. ECHA's 2024 updates to Annex XVII restricted substances lists now cover nickel and chromium residuals in desiccants destined for food-contact and medical packaging. German and Swiss pharmaceutical packagers are demanding batch-level ICP-MS certificates, compressing acceptable impurity thresholds by an order of magnitude versus industrial grades.
Buyers are consolidating molecular sieve procurement under single-source framework agreements with integrated process licensors. Mid-scale chemical processors in Southeast Asia are abandoning spot purchases from trading houses in favor of five-year tolling contracts tied to PSA unit performance guarantees. This concentration is most visible in Thailand and Vietnam, where Japanese engineering firms are bundling sieve supply with ethylene plant commissioning packages.
Molecular Sieve Desiccants Market Segmentation
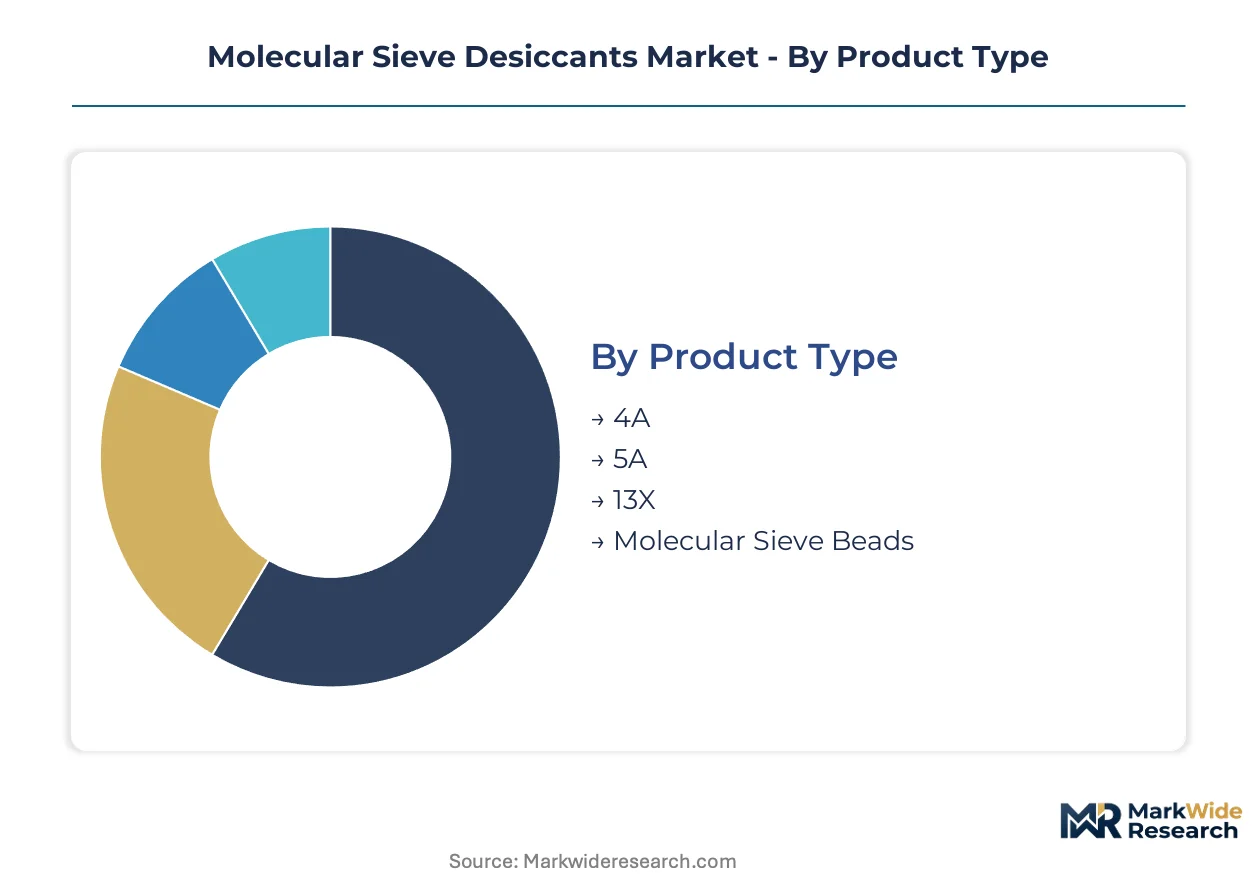
Molecular sieve desiccant procurement patterns diverge sharply across technical specifications and end-use requirements. Product type selection dictates regeneration frequency and capital recovery timelines. Packaging format choices reflect the tension between bulk logistics efficiency and precision dosing for moisture-sensitive applications.
Product Type:
After-sales service intensity escalates with pore size selectivity and regeneration complexity, driving differentiated support models across product grades.
- 4A:Potassium-exchanged zeolite with 4-angstrom pore apertures adsorbs water and ammonia while excluding larger hydrocarbons. Petrochemical crackers on the US Gulf Coast deploy 4A beds for ethylene feed gas dehydration, pressured by EPA Tier 3 sulfur mandates to minimize regeneration downtime.
- 13X:Sodium-exchanged faujasite structure with 10-angstrom pores captures mercaptans and aromatics alongside moisture. Natural gas processors in Sichuan and Xinjiang specify 13X for coalbed methane upgrading, displacing triethylene glycol under China's MEE dual carbon enforcement.
- 5A:Calcium-exchanged zeolite with 5-angstrom aperture separates linear from branched paraffins. Refinery catalytic reformer units specify 5A for n-paraffin recovery.
- Molecular Sieve Beads:Spherical bead formulations optimize packed bed pressure drop and attrition resistance. Electronics-grade bead production commands Swiss and German pharmaceutical packaging contracts.
By volume, 4A leads. By growth pace, 13X is ahead.
Application:
Cost tier stratification separates commodity dehydration from validated pharmaceutical moisture control, with certification requirements multiplying procurement complexity.
- Petrochemical:Catalytic reformer and ethylene cracker units consume high-tonnage 5A and 13X for hydrocarbon separation and sulfur reduction. Reliance Industries and Indian Oil specify molecular sieve trains for Gujarat and Odisha greenfield crackers.
- Natural Gas:LNG export terminals and shale gas processing deploy 4A and 13X for cryogenic feed gas dehydration. US Gulf Coast terminals require high-capacity beds to meet liquefaction moisture specifications.
- Air Drying:Cryogenic air separation units and instrument air systems specify 3A and 4A for dew point suppression. Steel and chemical plants in Japan and South Korea drive replacement demand.
- Pharmaceuticals:Active ingredient packaging demands FDA-validated 3A and 4A with batch-level residual moisture documentation. EMA and Swissmedic trace metal thresholds now require ICP-MS certification for EU and Swiss markets.
Petrochemical applications dominate tonnage. Pharmaceuticals expand most quickly on per-kilogram value metrics.
End User:
Customer type determines specification rigor, from bulk commodity procurement to validated batch documentation with 18-24 month qualification timelines.
- Food Packaging:Sachet-format 3A and 4A desiccants require EFSA and FDA food-contact compliance with migration testing. German and Swiss packagers enforce REACH Annex XVII nickel and chromium thresholds.
- Electronics:Semiconductor fabs in Taiwan and South Korea specify sub-ppm residual moisture protocols for wafer and component packaging. Honeycomb-form zeolite monoliths from Linde and Air Liquide are penetrating Texas and Louisiana olefins plants.
- Chemical Manufacturing:Mid-scale processors access molecular sieve capacity through asset-light PSA leasing rather than capital purchase. Thai and Vietnamese operators favor five-year tolling contracts with Japanese engineering firms.
- Automotive:Electric vehicle battery cell manufacturing requires ultra-dry assembly environments. South Korean and Japanese battery producers specify 3A for electrode drying operations.
Electronics commands premium pricing. Chemical manufacturing offers the steepest expansion trajectory through leasing model penetration.
Packaging Type:
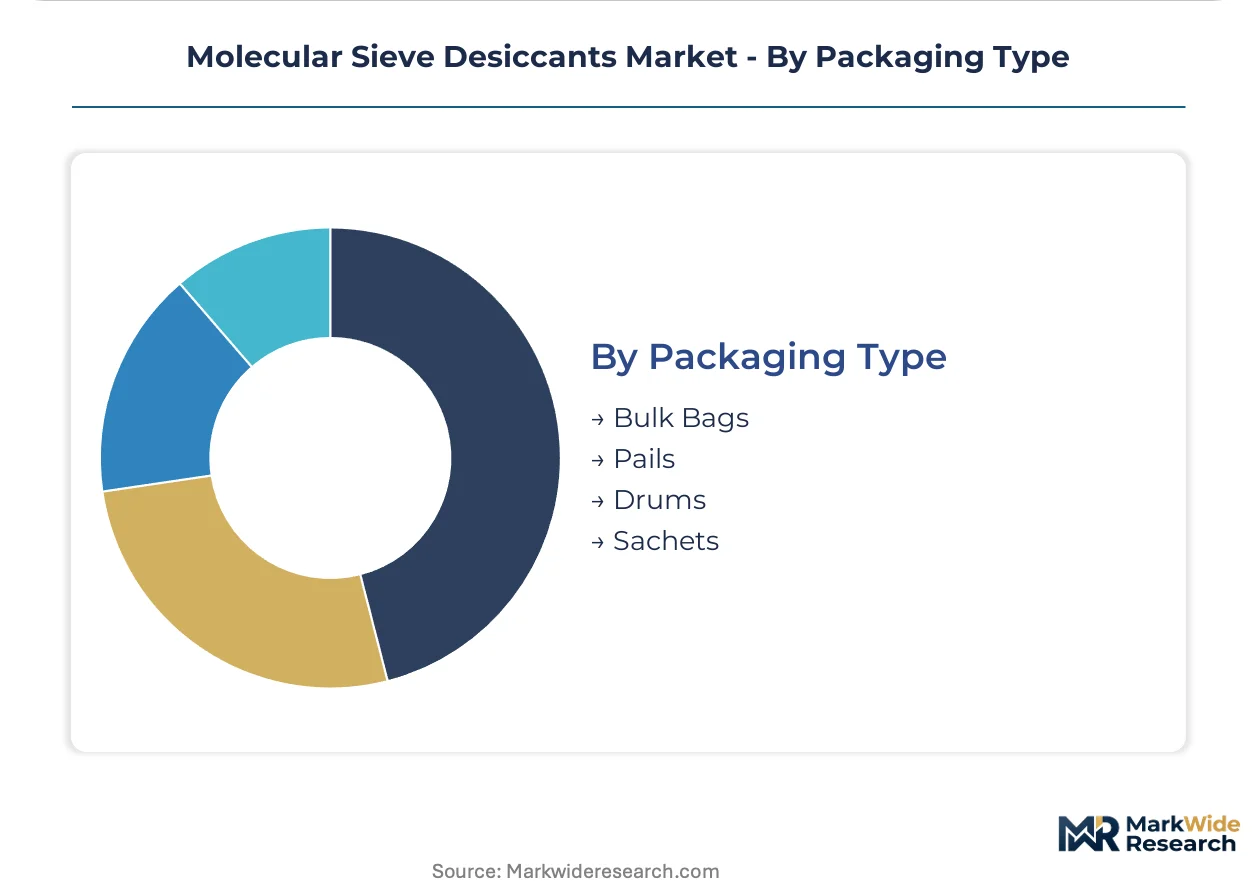
Volume scale and margin structure invert across packaging formats, with bulk logistics competing against precision dosing value capture.
- Bulk Bags:One-tonne flexible intermediate bulk containers serve petrochemical and natural gas dehydration with minimal handling cost. US Mountain West and Shandong Province production clusters supply Gulf Coast and Asian crackers.
- Sachets:Tyvek and composite film sachets deliver gram-precision dosing for electronics and pharmaceutical packaging. Swiss and German manufacturers capture 10-15x per-unit margin premiums over bulk formats.
- Pails:20-25kg steel or plastic pails suit mid-volume chemical processors and maintenance shops. Southeast Asian distributors stock pail formats for spot replacement demand.
- Drums:200-liter steel drums bridge bulk and precision packaging for regional chemical distributors. Indian and Brazilian importers favor drum formats for customs efficiency.
Bulk bags dominate tonnage throughput. Sachets gain share fastest on margin expansion and electronics demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA Tier 3 sulfur mandates and China's dual carbon enforcement are redrawing procurement patterns across molecular sieve desiccant markets. National regulators now dictate replacement cycles and product specifications with direct impact on regional demand distribution.
United States
Gulf Coast ethylene crackers and LNG export terminals consume high-capacity 5A and 13X sieves under EPA pressure to meet gasoline sulfur ceilings. FERC permitting for liquefaction trains in Texas and Louisiana accelerates dehydration unit deployments. Houston-Baytown corridor refiners prioritize adsorbent longevity over upfront cost minimization.
China
Shandong Province sodium aluminosilicate gel production clusters supply domestic petrochemical complexes while MEE enforcement displaces glycol dehydration in Sichuan shale fields. Dual carbon targets mandate molecular sieve upgrades in Xinjiang coalbed methane operations. Yangtze River Delta electronics manufacturers pull premium bead formulations for semiconductor packaging.
Germany
REACH Annex XVII trace metal restrictions now cover nickel and chromium residuals in desiccants for pharmaceutical and food-contact applications. ECHA disclosure obligations compress acceptable impurity thresholds below industrial-grade specifications. Bavarian and Swiss pharmaceutical packagers demand batch-level ICP-MS certification.
India
Reliance Industries and Indian Oil are commissioning ethylene crackers in Gujarat and Odisha with integrated molecular sieve adsorption trains. BIS standards for petrochemical equipment create specification pathways for greenfield installations. Mumbai-Pune industrial corridor distributors stock bulk bag formats for spot replacement demand.
Japan
METI efficiency standards for cryogenic air separation push steel and chemical plants toward 3A and 4A replacements with extended cycle life. Osaka-Kobe manufacturing belt instrument air systems specify sub-ppm dew point suppression. Chubu region engineering firms bundle sieve supply with PSA unit performance guarantees.
Molecular Sieve Desiccants Market Competitive Environment
Channel-controlling players compete with product-specialist players across a market structured around integrated process licensing versus standalone adsorbent supply. The vendor base clusters into three archetypes: multinational chemical conglomerates with catalyst-adsorbant portfolios, precision-focused Swiss and German specialists, and bulk-scale Asian manufacturers. Dominant competitive moves include bundling desiccant supply with engineering services and geographic expansion through tolling contracts with regional processors.
Within the multinational tier, BASF SE and Honeywell UOP represent integrated licensors that anchor market position through combined catalyst and adsorbent offerings. Zeochem AG exemplifies the precision-specialist archetype with Swiss manufacturing focus. Hengye Inc. occupies the scale-driven position serving Asian petrochemical corridors with bulk 4A and 13X supply.
| Leading Market Players |
|---|
| BASF SE |
| Honeywell UOP |
| Axens |
| Zeochem AG |
| CECA (Arkema) |
| Clariant Produkte (Schweiz AG) |
| W. R. Grace & Co. |
| Tosoh Corporation |
| Hengye Inc. |
| Others |
Value Chain & Pricing Dynamics
Shandong Province's sodium aluminosilicate gel production clusters feed downstream pricing power to Asian petrochemical processors, while US Mountain West calcination capacity anchors premium-grade supply to Gulf Coast refiners. Natural gas price volatility transmits directly into 13X powder manufacturing costs, compressing margins for rotary kiln operators and forcing tiered pricing stratification across industrial and electronics-grade segments.
Pricing Analysis
Certification level creates the primary spread between commodity and specialty grades, with FDA-validated 3A and 4A beads commanding 10-15x per-unit premiums over bulk bag formats. Three-tier pricing structure separates pharmaceutical-grade ICP-MS certified supply from standard industrial 4A/13X and economy glycol-alternative sieves. Pricing pressure stems from energy-intensive calcination costs and REACH Annex XVII trace metal disclosure burdens. Petrochemical crackers exhibit highest price sensitivity due to high-tonnage procurement, while semiconductor fabs prioritize moisture performance over unit cost.
Supply Chain Analysis
Synthetic zeolite precursor manufacturing draws from concentrated sodium aluminosilicate gel production in Shandong Province and the US Mountain West, with ion exchange chemicals sourced from German and Swiss specialty suppliers. Natural gas for calcination, potassium and calcium salts for ion exchange, and precision bead-forming equipment constitute critical input dependencies. Single-source vulnerability concentrates in Shandong's gel supply cluster, exposing processors to logistics disruption and geopolitical friction. Distribution runs through integrated process licensors like Honeywell UOP and Axens, which bundle sieve supply with PSA unit performance guarantees, displacing spot-market trading houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The molecular sieve desiccants market sits at an inflection point where EPA Tier 3 sulfur mandates and China's MEE dual carbon enforcement are compressing replacement cycles and elevating adsorbent longevity over upfront cost minimization. Structured adsorbent monoliths threaten conventional pellet and bead suppliers with obsolescence in high-flow ethylene cracker applications.
For Market Incumbents: Pre-empt monolith-format disruption by acquiring structured adsorbent technology or licensing honeycomb-form zeolite manufacturing from Linde and Air Liquide. Defend against Asian bulk-scale competitors by deepening certification investments for FDA and EMA pharmaceutical packaging contracts, locking in 18-24 month qualification timelines that freeze out low-grade suppliers.
For New Entrants and Emerging Players: India's Gujarat and Odisha petrochemical corridors offer greenfield specification opportunities as Reliance Industries and Indian Oil commission ethylene crackers with integrated adsorption trains. Carbon capture pre-treatment for amine-based CO2 capture units at US and Norwegian CCS hubs represents a second white-space target. Pursue asset-light PSA leasing models to bypass capital barriers for mid-scale chemical processors in Southeast Asia.
For Investors and Strategic Acquirers: Carve-out targets emerge from multinational chemical conglomerates seeking to divest non-core adsorbent portfolios amid catalyst-adsorbant integration pressures. Five-to-ten-year viability hinges on regulatory tightening trajectory for regeneration emissions and carbon border adjustment implementation. Monitor EPA enforcement patterns on closed-loop thermal swing systems and ECHA updates to REACH Annex XVII restricted substances lists as inflection signals.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Zeolite Precursor Supply | Captive sodium aluminosilicate gel production insulates margin from Shandong supply shocks. |
| Structured Adsorbent Monolith Commercialization | Honeycomb-form zeolite blocks cut pressure drop in Texas and Louisiana olefins plants. |
| FDA-Grade Certification Investment | Batch-level ICP-MS documentation secures Swiss and German pharmaceutical packaging contracts. |
| Asset-Light PSA Leasing Expansion | Operating lease models lower barrier entry for Thai and Vietnamese mid-scale chemical processors. |
| Carbon Capture Pre-Treatment Partnership | Dedicated 4A sieve deployments ahead of liquefaction stages at Norwegian CCS hubs anchor demand. |
Study Parameters
Operator-level perspectives from petrochemical plant managers, molecular sieve procurement leads at LNG terminals, PSA unit service technicians, and pharmaceutical packaging engineers anchored the qualitative base. Secondary validation drew from EPA enforcement documentation, ECHA REACH Annex XVII updates, SEC 10-K filings from listed chemical conglomerates, and customs data on zeolite precursor trade flows. Bottom-up capacity assessments across Shandong Province and US Mountain West production clusters were triangulated against top-down demand modeling from ethylene cracker and LNG export terminal deployment schedules.
Scenario-bracketing framed volume and value outputs across the analysis window, with CAGRs derived from regression against historical replacement cycle compression and regulatory mandate acceleration. Segmentation dimensions modeled include product type (4A, 5A, 13X, bead formulations), application tier (petrochemical, natural gas, pharmaceuticals, electronics), packaging format (bulk bags, sachets, pails, drums), and regional regulatory cluster (EPA Tier 3, MEE dual carbon, REACH Annex XVII). Forecast inputs incorporated natural gas price volatility for calcination cost modeling and FERC permitting velocity for LNG dehydration unit deployment timing.
The forecast holds incumbent behavior within observed patterns; aggressive moves by structured adsorbent technology licensors or carbon capture engineering consortia would shift outcomes beyond modeled ranges. Quarterly review of EPA enforcement actions on regeneration emissions, ECHA restricted substances list updates, and FERC liquefaction train permitting cadence is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Drying Technologies
Conical Vacuum Dryer Market
Drying Technologies
Sludge Dryer Machine Market
Drying Technologies
Membrane Air Dryers Market
Drying Technologies
Industrial Lyophilizer Market
Drying Technologies
Global Desiccant Wheel Market
Drying Technologies
Regenerative Thermal Oxidizer [RTO] Market
Drying Technologies
Freeze-Dried Powder Market
Drying Technologies
Paper Drying Systems Market
Drying Technologies
Brine Concentration Technology Market
Drying Technologies
Chemical Absorbent Pads Market
Drying Technologies
Global Absorbent Pads Market
Drying Technologies
Lyophilization Services Market
Drying Technologies
Filtration and Drying Equipment Market
Drying Technologies
Coke Dry Quenching Market
Drying Technologies
Dry Powder Refilling Machine Market