
 Zeolite 4A Market | 2026-2036
Zeolite 4A Market Size, Share, and Industry Trends Forecast 2026-2036
Zeolite 4A Market Analysis
ISO 9001 certification cycles for specialty chemical production is collapsing the supplier base to firms with verified quality management systems. BASF SE leverages its integrated petrochemical feedstock position to sustain cost-advantaged zeolite output across multiple continents. Clariant AG anchors its competitiveness through specialized adsorbent formulations for industrial gas purification. Tosoh Corporation dominates Asian supply through captive sodium silicate production and proximity to detergent manufacturers.
Zeolite 4A is a synthetic sodium aluminosilicate with a crystalline pore structure of approximately 4 angstroms, manufactured through hydrothermal crystallization of sodium aluminate and sodium silicate solutions at controlled temperature and pH. Its primary industrial purpose centers on ion exchange in phosphate-free detergents and selective adsorption in gas and liquid separation processes. Powder formulations lead volume shipments in detergent applications where dissolution kinetics matter most, while bead and pellet forms command premium positioning in fixed-bed adsorption systems for industrial end users. Catalytic conversion technology segments attract R&D investment as refiners seek FCC additives with enhanced selectivity.
EPA regulations on phosphate discharge limits shape detergent formulation standards across the United States, while REACH registration requirements in Europe govern chemical safety documentation and market access for imported zeolite products. China's MEE enforces wastewater treatment mandates that expand industrial adsorbent procurement. Stakeholders must monitor evolving regional carbon accounting rules that could restructure energy-intensive zeolite manufacturing economics and relocation decisions.
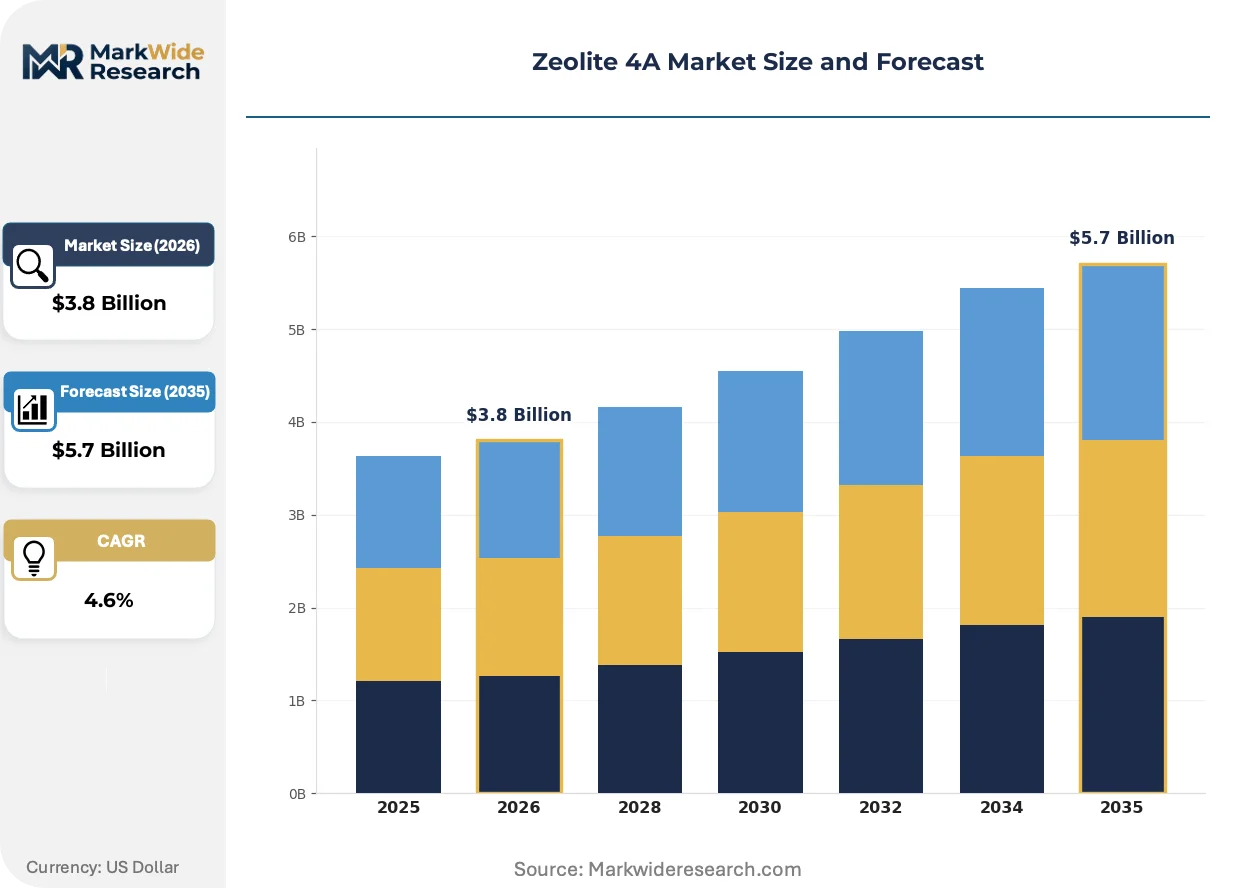
Market Dynamics
Phosphate-free detergent mandates across major economies are compressing formulation cycles and forcing rapid supplier qualification, with REACH compliance in Europe and China's GB standards tightening product specifications faster than incumbent capacity can adapt.
Growth Catalysts
- Regulatory phosphate bans:EPA discharge limits in the United States and parallel wastewater mandates from China's MEE are compelling detergent manufacturers to adopt ion-exchange zeolite builders.
- Industrial gas purification:Refinery FCC additive demand is accelerating as processors seek enhanced selectivity in catalytic cracking operations.
- India demand concentration:Household detergent consumption and municipal water treatment procurement are expanding simultaneously in this geography.
Market Restraints
- Sodium silicate supply concentration:Captive production in East Asia creates input cost volatility for non-integrated manufacturers elsewhere.
- Energy-intensive crystallization:Hydrothermal manufacturing processes face carbon accounting pressures that threaten facility economics.
- Synthetic zeolite substitution:Advanced metal-organic frameworks are encroaching on high-value adsorbent applications with superior pore tunability.
Strategic Opportunities
- Carbon capture applications:Post-combustion gas separation systems represent an emerging demand vertical for selective adsorbent formulations.
- EU Green Deal alignment:Circular economy incentives for recyclable detergent components create regulatory tailwinds for zeolite-based builders.
- Bead-to-powder conversion:Industrial end users are demanding customized particle geometries that optimize fixed-bed pressure drop.
Industry Challenges
- ISO 9001 certification timelines:Quality management system verification cycles are extending supplier onboarding beyond 18 months.
- Legacy formulation integration:Detergent manufacturers face technical complexity retrofitting zeolite builders into established production lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Zeolite 4A Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Detergents, Adsorbents, Catalysts, Water Treatment End User: Household, Industrial, Automotive, Agriculture Form: Powder, Granules, Beads, Pellets Technology: Ion Exchange, Adsorption, Catalytic Conversion, Membrane Separation |
| Companies Covered | BASF SE, Clariant AG, Honeywell International Inc., Tosoh Corporation, W. R. Grace & Co., Arkema Group, PQ Corporation, Albemarle Corporation, Zeochem AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Zeolite 4A Market Emerging Trajectories
Manufacturing process intensification and regulatory chemistry are converging to reshape competitive positioning, with crystallization efficiency and carbon footprint becoming simultaneous design constraints rather than sequential optimization targets.
Continuous-flow hydrothermal synthesis is supplanting batch crystallization in zeolite manufacturing. Specialty chemical producers in Germany and Japan are adopting this technology to reduce energy consumption per ton. The shift is compressing capital requirements for new entrants while raising barriers for legacy batch operators.
REACH registration requirements are tightening documentation burdens on imported zeolite products entering European markets. ECHA substance evaluation protocols now demand extensive ecotoxicological data that many non-EU suppliers cannot furnish. Detergent formulators are responding by consolidating procurement around REACH-registered sources with verified supply chain transparency.
Specification-driven procurement is replacing commodity spot purchasing among industrial adsorbent buyers. Refinery operators and gas processors now require certified adsorption kinetics data before contract award. This behavioral shift is most visible in South Korea and Saudi Arabia, where petrochemical complexes are unbundling zeolite supply from catalyst service agreements.
Zeolite 4A Market Segmentation
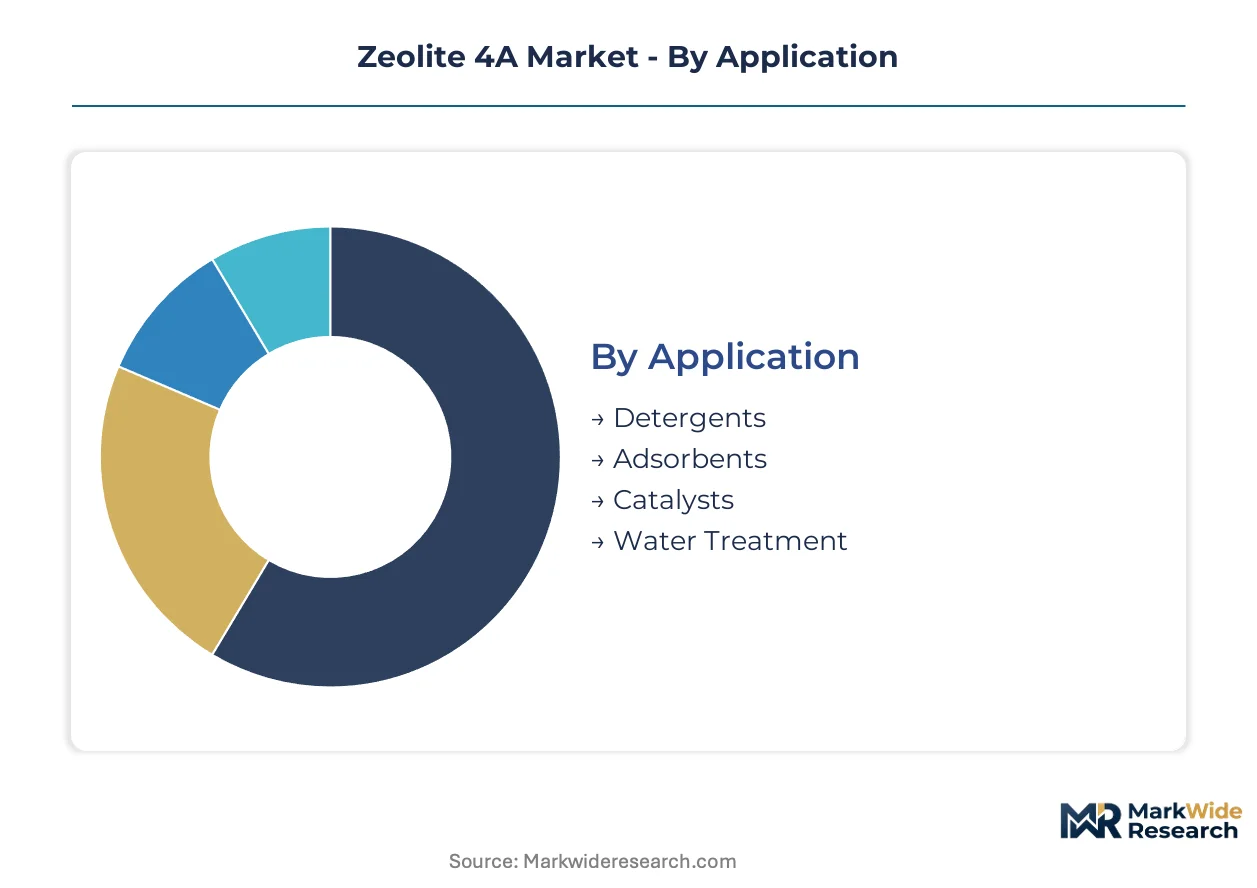
Segmentation in Zeolite 4A markets reveals how crystallization geometry and ion-exchange capacity map to divergent margin structures. Form and application categories operate on fundamentally different pricing architectures, with detergent-grade powders competing on volume while adsorbent beads extract premium through specification compliance.
Application:
Premium margin pools concentrate in catalytic conversion and specialized adsorbent formulations where refinery FCC additive specifications create technical barriers.
- Detergents:Phosphate-free laundry and dish formulations deploy sodium aluminosilicate builders for calcium and magnesium ion exchange. India's household detergent manufacturers drive procurement volume as municipal phosphate discharge regulations tighten across Maharashtra and Gujarat industrial corridors.
- Adsorbents:Industrial gas separation and dehydration applications demand certified adsorption kinetics data before contract award. Petrochemical processors in South Korea and Saudi Arabia now unbundle zeolite supply from catalyst service agreements, forcing standalone qualification protocols.
- Catalysts:FCC additives for enhanced selectivity in catalytic cracking operations.
- Water Treatment:Municipal and industrial wastewater purification systems.
Detergents hold installed capacity. Adsorbents is rotating up the share rankings.
End User:
Customer procurement sophistication varies sharply, with industrial buyers demanding ISO 9001-certified supply chains while household channels prioritize cost position.
- Industrial:Refinery operators, gas processors, and chemical manufacturers require documented adsorption performance under variable temperature and pressure conditions. REACH-registered suppliers with verified supply chain transparency capture procurement consolidation as ECHA substance evaluation protocols intensify documentation burdens.
- Household:Consumer detergent brands source ion-exchange builders through commodity-scale contracts.
- Automotive:Emission control and fuel dehydration applications.
- Agriculture:Soil amendment and feed additive formulations.
Industrial commands specification premiums. Household is gaining share fastest through volume scale.
Form:
Particle geometry directly determines pressure-drop performance in fixed-bed systems and dissolution kinetics in detergent applications.
- Powder:Fine particulate with rapid dissolution profiles dominates detergent manufacturing where builder integration speed affects formulation throughput. India's detergent producers favor powder grades for compatibility with legacy spray-drying equipment.
- Beads:Spherical morphology optimized for fixed-bed adsorption systems achieves lowest pressure drop per unit bed volume. German and Japanese specialty chemical producers command premium positioning through controlled sphericity and crush strength specifications.
- Granules:Intermediate particle size for fluidized bed applications.
- Pellets:Extruded cylindrical form for high-pressure gas processing units.
Beads holds installed capacity. Powder is rotating up the share rankings.
Technology:
Process intensification is collapsing the distinction between manufacturing method and end-use performance, with crystallization efficiency becoming simultaneous design constraint.
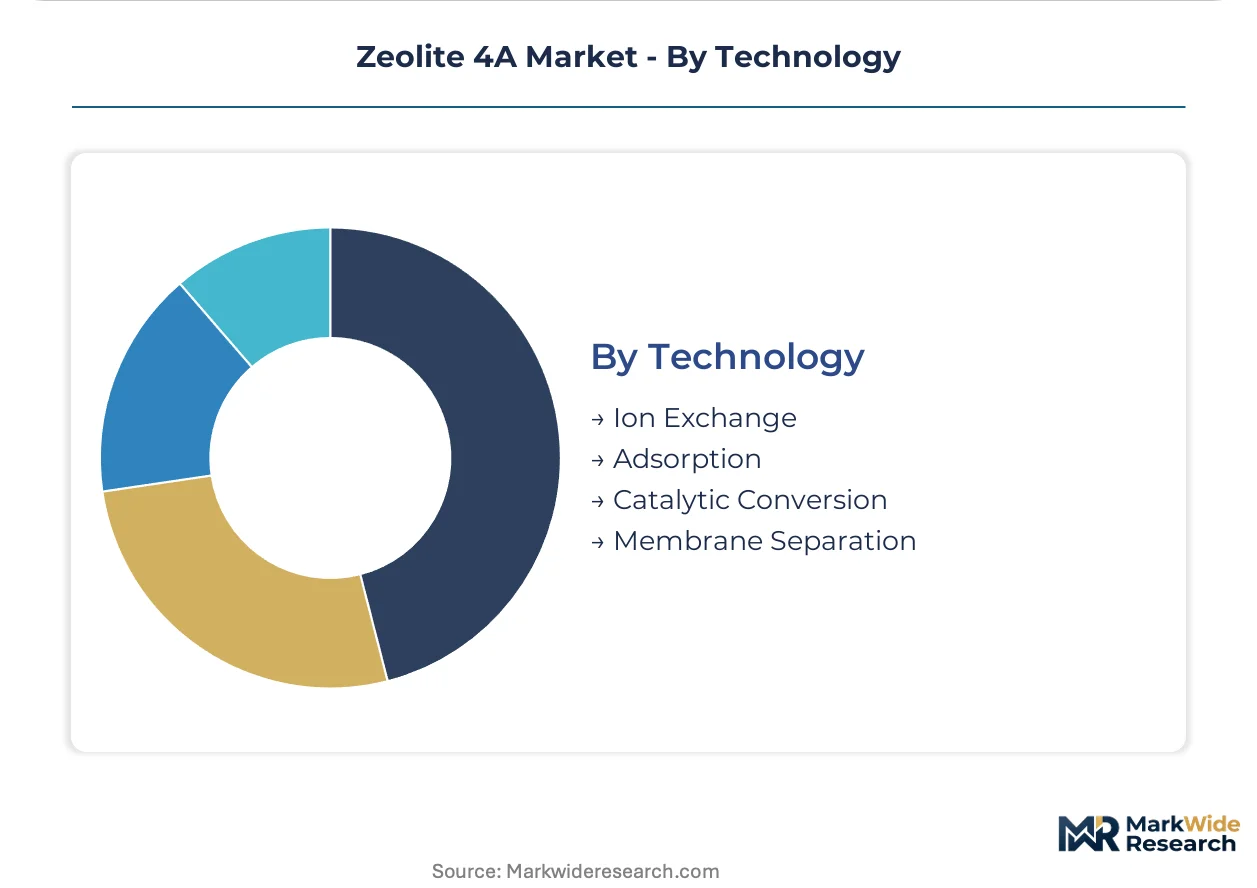
- Ion Exchange:Sodium aluminosilicate crystalline structure enables calcium and magnesium capture in detergent formulations. China's GB standards on environmental performance and India's BIS detergent builder specifications are compressing formulation cycles and forcing rapid supplier qualification.
- Adsorption:Selective molecular sieving based on 4-angstrom pore aperture separates gases and dehydrates liquids. Continuous-flow hydrothermal synthesis adoption in Germany and Japan reduces energy consumption per ton while raising barriers for legacy batch operators.
- Catalytic Conversion:Acid site modification for FCC additive selectivity enhancement.
- Membrane Separation:Emerging hybrid process configurations combining zeolite layers with polymeric supports.
Adsorption holds installed capacity. Ion Exchange is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH registration requirements in Europe and China's GB standards on environmental performance are compressing supplier qualification timelines across major manufacturing corridors. Detergent manufacturers in India and industrial gas processors in Germany and Japan are driving procurement volume as phosphate discharge regulations tighten wastewater treatment mandates.
China
Detergent manufacturers in the Yangtze River Delta and Pearl River Delta regions are expanding zeolite builder procurement as the Ministry of Ecology and Environment enforces municipal phosphate discharge limits. GB standards on environmental performance now require documented ecotoxicological data for imported chemical inputs. Zhejiang and Jiangsu province industrial clusters are retrofitting spray-drying equipment to accommodate powder-grade zeolite integration.
Germany
Specialty chemical producers in the Rhine-Ruhr and Bavaria regions are adopting continuous-flow hydrothermal synthesis to reduce energy consumption per ton of zeolite output. ECHA substance evaluation protocols under REACH registration requirements demand extensive supply chain transparency documentation. BASF SE's integrated petrochemical operations in Ludwigshafen sustain cost-advantaged zeolite production across multiple application segments.
India
Household detergent consumption in Maharashtra and Gujarat is rising alongside municipal water treatment procurement expansion. BIS detergent builder specifications are compressing formulation cycles and forcing rapid supplier qualification among domestic manufacturers. Mumbai and Ahmedabad industrial corridors are unbundling zeolite supply from legacy phosphate builder contracts.
Japan
Petrochemical processors in the Chubu and Kansai regions require certified adsorption kinetics data before contract award for industrial gas separation applications. METI industrial standards govern fixed-bed adsorption system specifications in refinery FCC additive procurement. Tosoh Corporation's captive sodium silicate production in the Osaka metropolitan area anchors Asian supply proximity to detergent manufacturers.
United States
Refinery operators in the Gulf Coast petrochemical corridor are demanding enhanced selectivity in catalytic cracking operations through FCC additive formulations. EPA discharge limits on phosphate runoff shape detergent formulation standards across consumer and industrial channels. Texas and Louisiana industrial clusters are consolidating procurement around REACH-registered suppliers with verified quality management systems.
Zeolite 4A Market Vendor Landscape
Player mix skews toward integrated petrochemical conglomerates and specialty chemical specialists with captive raw material positions. The supplier base is collapsing to firms with ISO 9001-certified quality management systems as certification cycles extend beyond eighteen months. Three archetypes dominate: integrated feedstock owners, adsorbent formulation specialists, and regional sodium silicate producers. Competitive moves center on backward integration into sodium silicate supply and continuous-flow manufacturing technology licensing.
Within the integrated conglomerate tier, BASF SE and Honeywell International Inc. occupy positions defined by petrochemical feedstock control and multi-continent manufacturing footprints. Among specialty adsorbent specialists, Clariant AG exemplifies competitive positioning through industrial gas purification formulation expertise. Tosoh Corporation anchors the East Asian supply vector through proximity advantages to detergent manufacturing clusters. PQ Corporation and Albemarle Corporation sit within the mid-tier specialist segment serving regional industrial procurement channels.
| Leading Market Players |
|---|
| BASF SE |
| Clariant AG |
| Honeywell International Inc. |
| Tosoh Corporation |
| W. R. Grace & Co. |
| Arkema Group |
| PQ Corporation |
| Albemarle Corporation |
| Zeochem AG |
| Others |
Supply Flow & Price Mechanics
Zeolite substitution for phosphate builders in Indian detergent formulations is simultaneously redrawing raw material procurement geography and compressing margin structures across non-integrated manufacturers. This input displacement concentrates purchasing power among sodium silicate producers in East Asia while forcing European and North American formulators to absorb logistics premiums or pursue captive supply investments.
Pricing Analysis
Certification level creates the primary spread between detergent-grade powder and adsorbent-grade bead specifications. Pricing stratifies across REACH-registered premium tiers, ISO 9001-verified standard tiers, and unregistered economy imports. Cost compression in powder grades is intensifying because India's BIS-mandated formulation cycles are shortening contract durations. Household detergent manufacturers exhibit highest price sensitivity, while refinery FCC additive buyers prioritize adsorption kinetics documentation over unit cost.
Supply Chain Analysis
Sodium silicate supply concentration in China, Japan, and South Korea anchors global zeolite manufacturing economics. Hydrothermal crystallization feeds from captive sodium aluminate production, sodium silicate solution, and controlled-temperature reactor capacity. Single-source vulnerability runs through East Asian sodium silicate producers who supply non-integrated Western manufacturers. Distribution runs through long-term offtake contracts to detergent formulators and spot purchasing for industrial adsorbent buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The detergent builder ecosystem is approaching a platform inflection where REACH-registered supply chains become the interoperability standard for accessing European and North American formulators. This certification-layer gating creates winner-take-most dynamics among qualified suppliers.
For Market Incumbents: Shield margin position by accelerating backward integration into sodium silicate supply and securing ISO 9001 certification ahead of competitor qualification cycles. Metal-organic framework substitution in high-value adsorbent applications demands R&D investment in pore tunability to defend technical differentiation. Capacity addition in India captures household detergent procurement expansion as phosphate bans tighten across Maharashtra and Gujarat industrial corridors. For New Entrants and Emerging Players: Anchor in carbon capture adsorbent formulations where specification standards remain unsettled and incumbent certification advantages are weakest. Municipal water treatment procurement in India offers the most penetrable volume segment given simultaneous BIS compliance pressure and supplier consolidation. A go-to-market angle emphasizing continuous-flow hydrothermal synthesis cost advantages can displace legacy batch operators in energy-conscious European markets. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed specialty chemical platforms lacking REACH registration depth or captive sodium silicate supply. Long-term viability across the analysis window hinges on regulatory compliance infrastructure rather than commodity scale. Watch ECHA substance evaluation protocol expansion as the inflection signal that collapses the supplier base to registered sources with verified supply chain transparency.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sodium Silicate | Captive raw material supply insulates margin structures from East Asian input cost volatility. |
| Continuous-Flow Hydrothermal Synthesis Licensing | German and Japanese technology adoption reduces energy consumption per ton while raising barriers for batch operators. |
| REACH Registration Completion | ECHA substance evaluation protocols now demand ecotoxicological data that unregistered suppliers cannot furnish. |
| Carbon Capture Adsorbent Formulation Development | Post-combustion gas separation systems represent emerging demand vertical with unsettled specification standards. |
| India Manufacturing Footprint Expansion | Maharashtra and Gujarat detergent producers are unbundling zeolite supply from legacy phosphate builder contracts. |
Methodological Framework
A spread of perspectives from detergent formulation chemists, refinery FCC procurement managers, sodium silicate plant operators, and specialty chemical distribution channel heads converged on the working assumptions driving this analysis. Primary interview insights were validated against customs and trade data, SEC filings from integrated petrochemical conglomerates, European Chemicals Agency registration databases, and Bureau of Indian Standards detergent specification documents. Bottom-up capacity and demand estimates were triangulated with top-down market sizing from trade flow analysis.
Segmentation dimensions modeled include crystallization form (powder, bead, granule, pellet), application category (detergents, adsorbents, catalysts, water treatment), end-user sophistication tier (industrial specification buyers versus household commodity purchasers), and regional regulatory cluster (REACH-registered Europe, GB-standard China, BIS-regulated India, EPA-governed United States). CAGRs were derived from regression analysis against phosphate ban implementation timelines and industrial gas purification capacity expansion announcements. Forecast inputs incorporated sodium silicate supply concentration indices and carbon accounting policy development trajectories.
Material uncertainties — including ECHA substance evaluation protocol expansion scope, China's dual carbon goals enforcement intensity, and metal-organic framework adsorbent commercialization pace — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory compliance timelines and crystallization technology adoption curves. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Relaxor Ferroelectric Ceramics Market
Ceramics
East Africa Ceramic Tiles Market
Ceramics
Barium Carbonate Powder Market
Ceramics
India Kaolin Market
Ceramics
Advanced Ceramic Additives Market
Ceramics
United States Ceramic Tiles Market
Ceramics
China Clay Market
Ceramics
Low Density Ceramic Proppant Market
Ceramics
High Temperature Ceramics Market
Ceramics
Tetra-N-Butyl Titanate Market
Ceramics
Taiwan Ceramic Tiles Market
Ceramics
Colloidal Alumina Market
Ceramics
Europe Activated Alumina Market
Ceramics
North America Barium Carbonate Market
Ceramics
Advanced Structural Ceramics Market
Ceramics
Global Ceramic Foams Market