
 Bulk Explosives Market | 2026-2036
Bulk Explosives Market Size, Share, and Industry Trends Forecast 2026-2036
Bulk Explosives Market Insights
Modular emulsion delivery systems is consolidating buyer preference across large-scale surface mining contracts. Orica Limited leverages its integrated blasting services model to anchor long-term supply agreements in Australian iron ore. MAXAM competes through its dense emulsion technology platform, while Dyno Nobel specializes in electronic blasting initiation paired with bulk explosive supply.
Bulk explosives denote free-flowing or pumpable energetic compositions—typically ammonium nitrate-fuel oil (ANFO) blends, water-gel emulsions, or slurry formulations—manufactured on-site or delivered in bulk for direct loading into blastholes ranging from 50 mm to 400 mm diameter. These materials fragment rock through controlled gas expansion and shock energy release, serving as the primary breakage method in open-pit and underground extraction. Emulsion explosives command the widest application footprint due to their water resistance and energy density advantages in wet drilling conditions. Mining applications dominate volume consumption, though civil engineering projects represent a concentrated margin pool where precision blasting specifications justify premium formulation pricing.
The US Bureau of Alcohol, Tobacco, Firearms and Explosives (ATF) and Australia's Work Health and Safety regulators enforce strict licensing, storage, and transport protocols that elevate compliance costs and favor established suppliers with integrated safety management systems. The EU REACH framework and China's GB standards on hazardous chemicals further constrain formulation flexibility and cross-border product mobility. Stakeholders must monitor evolving digital blasting integration requirements and on-site manufacturing automation as these capabilities increasingly determine contract eligibility and operational efficiency benchmarks.
Market Dynamics
Modular emulsion delivery systems are consolidating procurement decisions across large-scale surface mining contracts, concentrating volume with suppliers capable of integrating manufacturing, transport, and blasthole loading into unified service agreements.
Growth Catalysts
- Australian iron ore expansion:Surface mining operators in the Pilbara region are scaling emulsion-based bulk explosive consumption to match record production targets.
- China's MIIT safety mandates:Tightened ammonium nitrate storage and transport standards are accelerating replacement of outdated bulk handling infrastructure.
- Pumpable emulsion technology:Underground metal mines in Canada are adopting specialized formulations that perform in wet, high-pressure drilling conditions.
Market Restraints
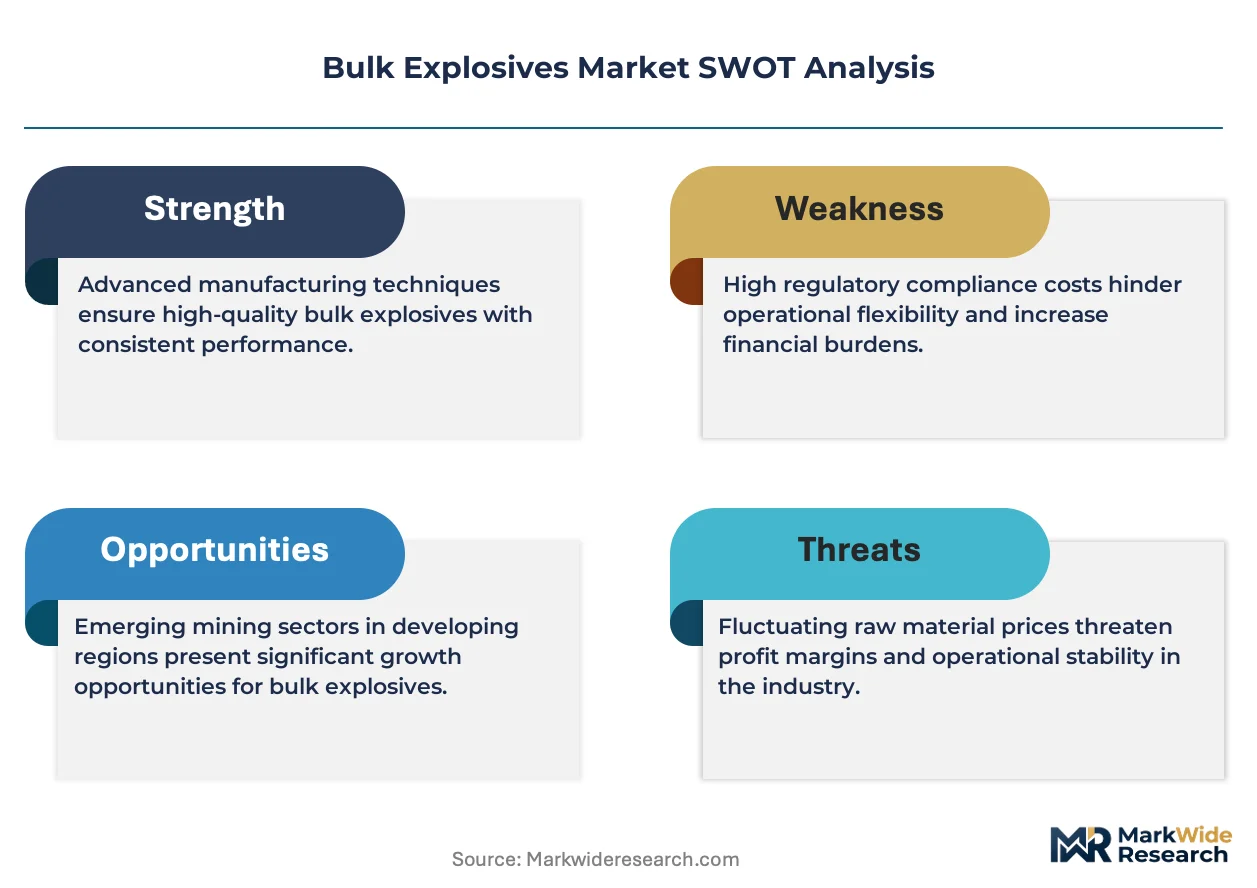
- Ammonium nitrate price volatility:Feedstock cost swings tied to natural gas and fertilizer market cycles compress formulation margins unpredictably.
- Supplier concentration in Australia:Three integrated blasting services providers control the majority of emulsion manufacturing and delivery capacity.
- REACH formulation constraints:The EU's chemical registration requirements limit cross-border mobility of certain water-gel sensitizers and emulsifiers.
Strategic Opportunities
- Canadian underground metal mining:Specialized pumpable explosive demand in nickel and copper operations remains underserved by standardized surface-mining formulations.
- Digital blasting integration:Convergence of electronic initiation systems with real-time blast optimization software creates premium service tiers.
- US ATF licensing barriers:Stringent explosives handler certification requirements favor established suppliers with integrated safety management systems.
Industry Challenges
- Blast engineer talent scarcity:Specialized expertise in electronic initiation timing and vibration control is concentrated among aging practitioner cohorts.
- On-site manufacturing capex:Mobile emulsion plants and bulk delivery vehicles require substantial capital deployment with long depreciation cycles.
- Legacy ANFO infrastructure:Existing powder magazines and pneumatic loading equipment resist cost-effective retrofit to emulsion handling systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bulk Explosives Market |
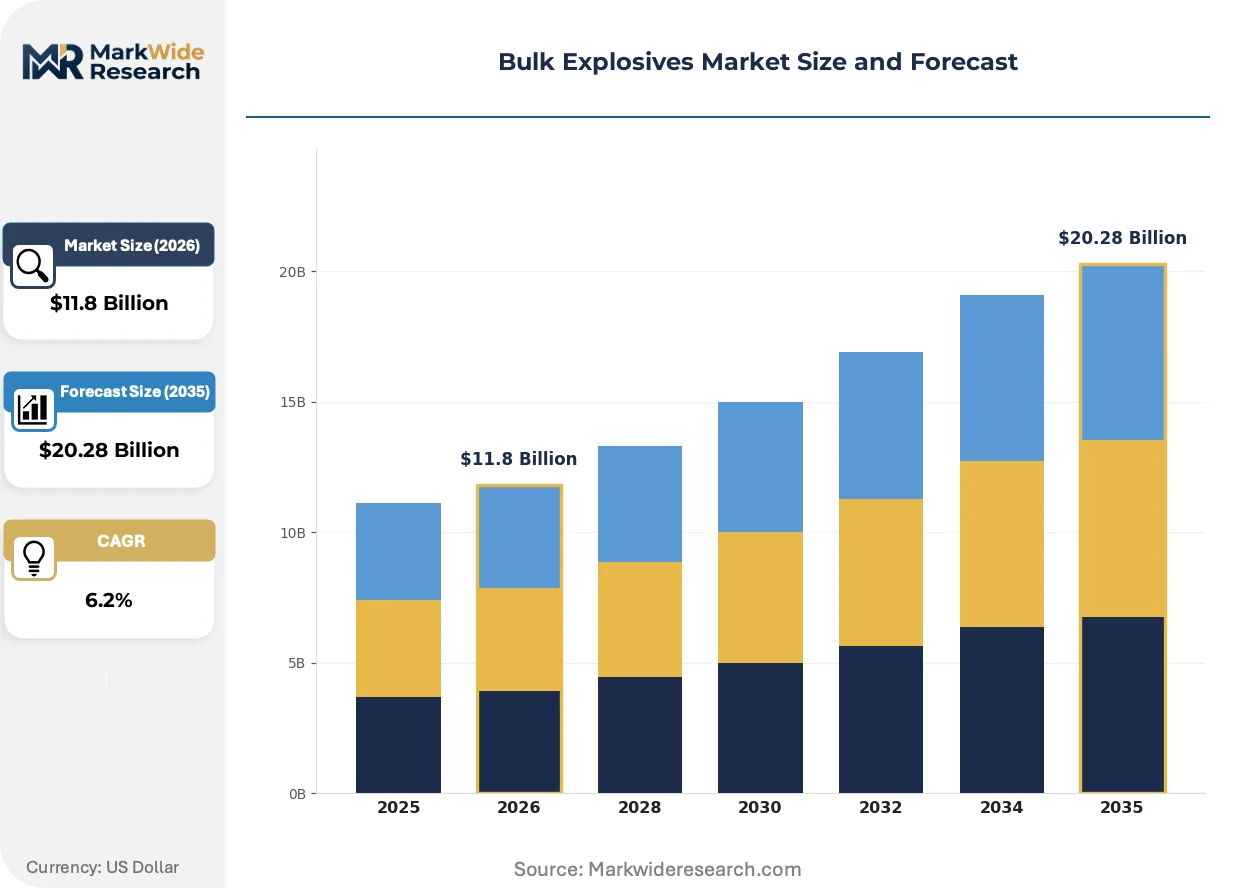
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $20.28 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: ANFO, Slurry Explosives, Emulsion Explosives, Dynamite, Cast Booster Application: Mining, Quarrying, Construction Demolition, Civil Engineering, Road Building End User: Mining Companies, Construction Firms, Oilfield Services, Cement Manufacturers, Aggregate Producers Distribution Channel: Direct Sales, Distributors, Dealers, Online Platforms, Tender Procurement |
| Companies Covered | Orica Limited, MAXAM, AEL Mining Services, Dyno Nobel, ENAEX, Sasol Limited, Austin Powder Company, EPC Groupe, Solar Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bulk Explosives Market Trends and Innovations
Digital integration is reshaping how bulk explosives are specified, delivered, and detonated, compressing the traditional separation between chemical supply and blast engineering services.
Emulsion explosives with built-in electronic detonator compatibility are overtaking conventional ANFO in wet blasthole applications. Australian iron ore miners are specifying these formulations in long-term supply agreements. The technology is compressing procurement timelines by bundling explosive chemistry with initiation hardware into single-vendor contracts.
REACH and China's parallel GB standards on hazardous chemicals are constraining formulation flexibility for cross-border suppliers. Manufacturers must maintain separate product registrations for EU and Asian markets. Underground mining operations in Canada face the tightest compliance burdens where dual certification for emulsion ingredients adds six to nine months to product launch cycles.
Buyer preference is consolidating around integrated blasting services rather than discrete explosive supply contracts. Mining operators in Australia are unbundling traditional procurement roles and awarding single-source agreements covering drilling, loading, and initiation. This pattern is most visible in iron ore and coal operations where blast optimization software ties explosive performance directly to crusher throughput metrics.
Bulk Explosives Market Segmentation
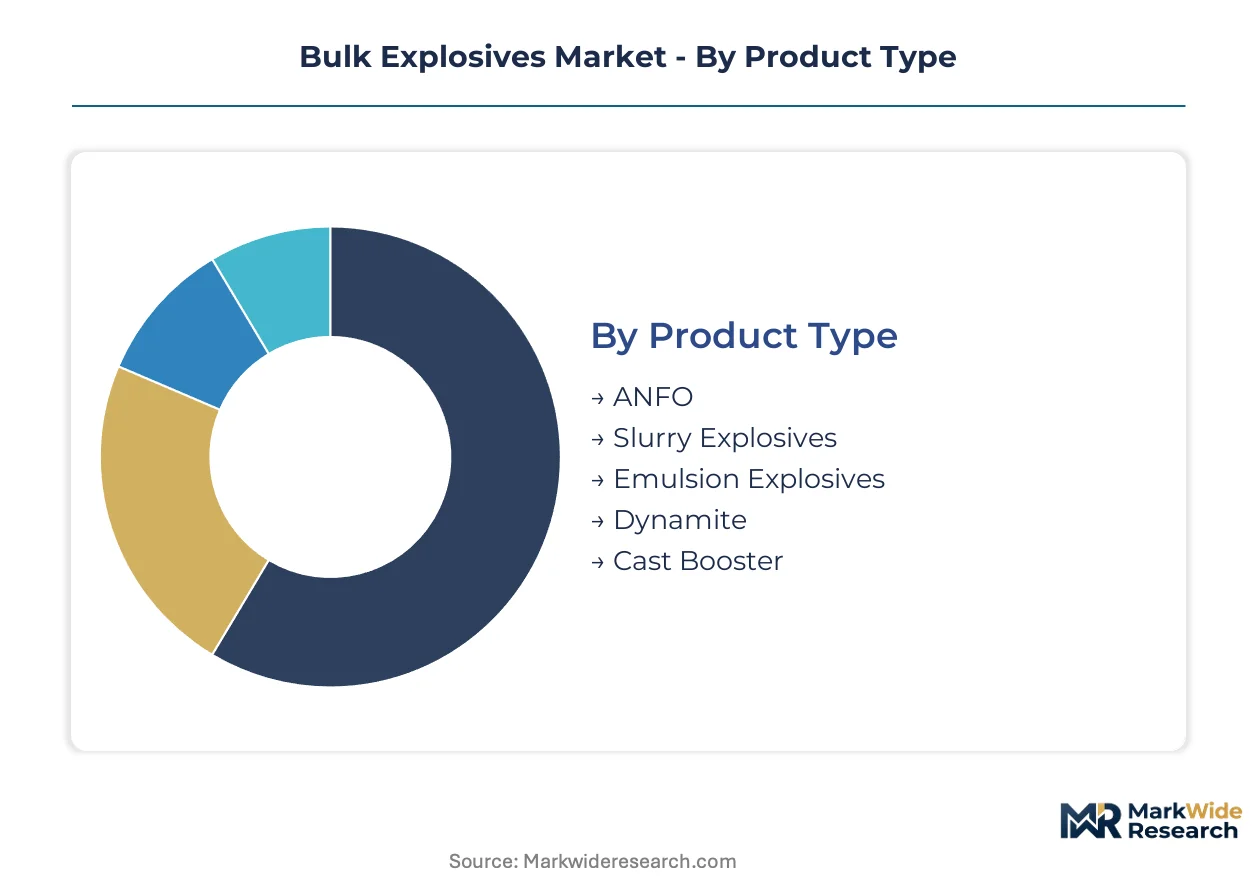
Explosive formulation chemistry and delivery method determine procurement economics across mining and civil engineering verticals. Buyers segment supply contracts by blasthole conditions, regulatory compliance burdens, and integration with electronic initiation systems.
Product Type:
Blasthole water presence and rock hardness drive formulation selection more than energy density specifications.
- Emulsion Explosives:Water-in-oil microemulsion matrices containing ammonium nitrate droplets suspended in hydrocarbon fuel phase deliver superior water resistance and detonation velocity control. Australian iron ore surface miners specify these formulations exclusively for wet drilling conditions above the water table. The chemistry commands premium pricing but eliminates blasthole dewatering costs.
- ANFO:Porous ammonium nitrate prills absorbed into fuel oil represent the lowest-cost bulk explosive option where dry conditions permit. Underground limestone operations in the United States and developing market quarries concentrate demand for this mature technology. Price volatility in fertilizer-grade ammonium nitrate feedstock compresses margins unpredictably.
- Slurry Explosives:Suspended oxidizer salts in aqueous gel matrices with aluminum powder sensitizers.
- Dynamite:Nitroglycerin-based cartridge explosives for specialized tunneling and perimeter blasting applications.
- Cast Booster:High-density pentolite or TNT-based cast units for initiating bulk explosive columns.
Emulsion explosives lead on scale; ANFO retains share in cost-sensitive dry applications.
Application:
Fragmentation requirements and environmental permitting intensity separate high-margin from commodity supply contracts.
- Mining:Open-pit metal and coal operations consume bulk explosives at volumes exceeding 100,000 tonnes annually per major site. Canadian underground nickel mines specify pumpable emulsion systems for mechanized loading in wet, high-pressure conditions. Integration with real-time blast optimization software is becoming a contract prerequisite.
- Construction Demolition:Urban implosion and precision rock removal demand specialized low-vibration formulations with electronic initiation timing. Projects in dense European and Middle Eastern cities command formulation premiums of 40-60% above mining baselines. ATF and local fire marshal permitting timelines extend project cycles substantially.
- Quarrying:Aggregate production for cement and road base materials.
- Civil Engineering:Tunneling, dam foundation excavation, and pipeline trenching.
- Road Building:Mountain highway cuts and borrow pit development.
Mining dominates absolute volume; construction demolition generates the steepest margin expansion.
End User:
Procurement sophistication and safety management system maturity determine supplier qualification thresholds.
- Mining Companies:Tier-one diversified miners operate captive explosive supply agreements spanning manufacturing, transport, and blasthole loading. Australian iron ore majors unbundle traditional procurement roles and award integrated blasting services contracts covering drilling through fragmentation analysis. Supplier concentration limits competitive tension in mature mining districts.
- Construction Firms:General contractors and specialized demolition operators purchase explosives through project-specific tender procurement with discrete volume commitments. US-based firms face ATF licensing barriers that favor established regional suppliers with demonstrated safety records. Digital blasting integration requirements are emerging in premium infrastructure segments.
- Oilfield Services:Perforating and well stimulation explosive applications.
- Cement Manufacturers:Captive limestone quarry operations with integrated explosive supply.
- Aggregate Producers:Regional quarry operators with variable technical specification capabilities.
Mining companies anchor contract value; construction firms represent the most contested expansion target.
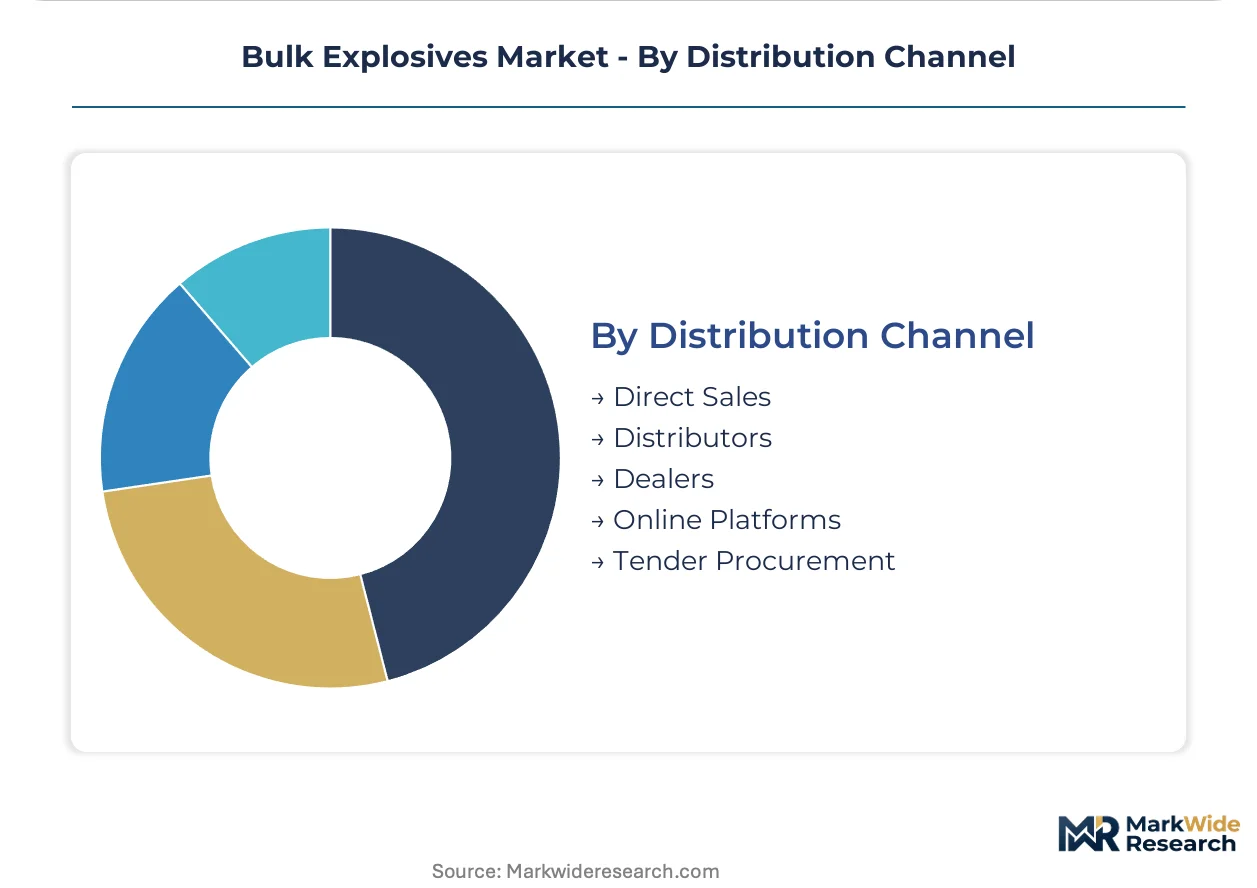
Distribution Channel:
Regulatory custody transfer points and on-site manufacturing economics shape channel selection.
- Direct Sales:Major mining houses negotiate long-term supply agreements with integrated service providers covering mobile emulsion plant deployment and dedicated bulk delivery fleets. Australian and Canadian operators favor this channel for security of supply and blast optimization service bundling. Capital deployment for on-site manufacturing infrastructure locks in multi-year relationships.
- Tender Procurement:Government infrastructure agencies and state-owned mining enterprises mandate competitive bidding with technical qualification gates. China's MIIT safety certification requirements and EU REACH registration documentation figure prominently in bid evaluation criteria. Award cycles extend 12-18 months for complex civil engineering projects.
- Distributors:Regional explosive product wholesalers serving mid-scale quarry and construction accounts.
- Dealers:Local agents with blasting contractor licensing for small-scale agricultural and specialty applications.
- Online Platforms:Emerging digital procurement for standardized initiation accessories and blasting supplies.
Direct sales capture the largest contract values; tender procurement channels are climbing fastest in state-backed infrastructure expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The bulk explosives industry traces its modern scale to 19th-century nitroglycerin manufacturing in Sweden and Germany, with contemporary production gravity shifting toward mineral-rich jurisdictions with intensive open-pit extraction.
Australia
Pilbara iron ore surface miners drive emulsion explosive consumption at volumes exceeding 100,000 tonnes annually per major site. Work Health and Safety regulators enforce strict licensing protocols that elevate compliance costs for new market entrants. Perth-based integrated blasting services providers anchor long-term supply agreements covering mobile manufacturing plant deployment.
China
Coal and rare earth surface mining operations sustain demand for water-gel emulsion formulations in Shanxi and Inner Mongolia. MIIT tightened ammonium nitrate storage and transport standards accelerate replacement of outdated bulk handling infrastructure. Yangtze River Delta chemical manufacturers face GB standards compliance burdens that constrain cross-border product mobility.
Canada
Underground nickel and copper mines in Ontario and Quebec specify pumpable emulsion systems for mechanized loading in wet, high-pressure drilling conditions. Health Canada and provincial regulators enforce dual certification requirements for emulsion ingredients that extend product launch cycles. Sudbury Basin metal mining operations concentrate specialized demand for formulations optimized for hard rock fragmentation.
United States
Surface coal operations in Wyoming and Appalachian limestone quarries sustain ANFO consumption where dry conditions permit. The ATF enforces stringent explosives handler certification requirements that favor established regional suppliers with demonstrated safety records. Texas and Louisiana oilfield services applications represent a concentrated margin pool for perforating explosive formulations.
South Africa
Platinum and gold reef mining operations in the Bushveld Complex and Witwatersrand Basin drive demand for specialized bulk explosive delivery systems. The country's national explosives regulator enforces strict transport and storage protocols for ammonium nitrate-based formulations. Johannesburg-centered mining houses operate captive supply agreements spanning manufacturing through blasthole loading.
Bulk Explosives Market Competitive Landscape
Premium-margin players sit above commodity-margin players across service integration depth, with the former bundling manufacturing, transport, and electronic initiation into unified contracts while the latter compete on feedstock cost and regional logistics. The vendor base clusters around three strategic archetypes: integrated blasting services providers with captive emulsion manufacturing, regional explosive product specialists with licensed distribution networks, and diversified chemical conglomerates with explosives divisions. Dominant competitive moves include backward integration into ammonium nitrate feedstock production and technology licensing partnerships for mobile emulsion plant deployment.
Within the integrated services tier, Orica Limited and Dyno Nobel exemplify the premium-position archetype through their Australian and North American market presence. MAXAM occupies a position bridging integrated services and technology specialization with its dense emulsion platform. Among regional specialists, AEL Mining Services and ENAEX represent the geographically concentrated distribution model, while Solar Industries anchors the emerging market expansion archetype from its Indian base. Austin Powder Company and Sasol Limited sit within diversified chemical conglomerate structures where explosives serve adjacent mining and energy verticals.
| Leading Market Players |
|---|
| Orica Limited |
| MAXAM |
| AEL Mining Services |
| Dyno Nobel |
| ENAEX |
| Sasol Limited |
| Austin Powder Company |
| EPC Groupe |
| Solar Industries |
| Others |
Pricing and Supply Chain Analysis
Ammonium nitrate feedstock costs cascade through formulation pricing tiers, with natural gas price volatility in fertilizer markets compressing margins for ANFO producers while emulsion manufacturers buffer through long-term offtake contracts with Australian iron ore majors.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates integrated blasting services from commodity bulk supply and spot-market ANFO. Price differentiation hinges on electronic initiation bundling and water-resistance certification grades. Cost compression in standard-tier emulsions is intensifying because Chinese MIIT safety mandates force infrastructure replacement. Construction demolition buyers show highest price sensitivity; mining houses with captive supply agreements demonstrate lowest.
Supply Chain Analysis
Domestic-content mandates in China's GB standards and India's explosives licensing regime are reshaping sourcing patterns for multinational suppliers. Manufacturing concentrates in Australia, China, and South Africa. The chain draws from natural gas-derived ammonium nitrate, hydrocarbon fuels, and specialized emulsifiers. Single-source vulnerability runs through concentrated ammonium nitrate production. Distribution runs through direct sales for mining majors and tender procurement for state infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bulk explosives market represents a late-cycle quality story as buyer preference consolidates around integrated blasting services with digital optimization capabilities rather than commodity chemistry supply.
For Market Incumbents: Hedge against margin erosion in standardized emulsion supply by deepening backward integration into ammonium nitrate feedstock production. Secure captive manufacturing infrastructure in Canadian underground mining districts where pumpable formulation expertise creates defensible positioning against emerging technology entrants.
For New Entrants and Emerging Players: Digital procurement platforms for standardized initiation accessories offer a channel route around established supplier relationships. Target civil engineering demolition segments in Middle Eastern urban centers where electronic blasting integration requirements remain underserved. Pursue technology licensing partnerships for mobile emulsion plant deployment rather than greenfield manufacturing investment.
For Investors and Strategic Acquirers: Consolidation pressure builds where fragmented regional distributors lack safety management system certification depth for ATF and REACH compliance. Five-to-ten-year viability favors integrated service providers with software-enabled blast optimization. Monitor electronic initiation adoption rates in Australian iron ore as the inflection signal for premium service tier expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ammonium Nitrate | Captive feedstock supply insulates Orica and Dyno Nobel from fertilizer market volatility cycles. |
| Mobile Emulsion Plant Deployment | On-site manufacturing reduces transport compliance burdens under China's tightened MIIT standards. |
| Electronic Initiation System Bundling | Software-hardware integration commands premium pricing from Australian Pilbara iron ore operators. |
| Dual Certification Investment | Parallel REACH and GB registration unlocks cross-border mobility for emulsion ingredient suppliers. |
| Blast Optimization Software Development | Real-time fragmentation analytics tie explosive performance directly to crusher throughput metrics. |
Research Methodology
Multiple input streams — structured interviews with blasting services directors, procurement leads at tier-one mining houses, explosives regulatory compliance officers, and mobile plant engineering specialists — were reconciled against customs trade data, Work Health and Safety licensing records, SEC 10-K explosives segment disclosures, and MIIT safety certification databases. Bottom-up volume modeling across formulation types and top-down value reconciliation anchored the analytical framework.
Data-stream reconciliation applied a segmented growth model across emulsion chemistry grades, application verticals, and end-user procurement sophistication tiers throughout the forecast period. CAGRs derived from historical volume trajectories in Australian surface mining and Canadian underground operations, adjusted for regulatory compliance cost escalations and digital integration adoption curves.
The model assumes a particular technology adoption path; alternative pathways for pumpable emulsion automation would alter the outlook if underground mechanization accelerates faster than projected. Forecasts reflect assumptions about ammonium nitrate price stability and REACH formulation continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Northern Europe Calcium Sulphate Market
Industrial Chemicals
Global Antifreeze Market
Industrial Chemicals
Global Low GWP Refrigerants Market
Industrial Chemicals
Europe and Middle East Lime Market
Industrial Chemicals
Trimethylolpropane (TMP) Market
Industrial Chemicals
Wood Vinegar Market
Industrial Chemicals
Acetylene Market
Industrial Chemicals
Global N-Methyl-2-Pyrrolidone (NMP) Market
Industrial Chemicals
Europe Starch Derivatives Market
Industrial Chemicals
Modified Bitumen Market
Industrial Chemicals
Permethrin Market
Industrial Chemicals
Shea Olein Market
Industrial Chemicals
Synthetic Gypsum Market
Industrial Chemicals
Cobalt Acetate Solution Market
Industrial Chemicals
South Africa Gypsum Plaster Market
Industrial Chemicals
Well Stimulation Materials Sales Market