
 Mining Chemicals Market | 2026-2036
Mining Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Mining Chemicals Market Intelligence
The integration of AI-driven process control systems for real-time dosage optimization is reconfiguring consumption patterns for specialty mining chemicals. This shift demands more consistent and high-purity formulations to work with automated sensors and feedback loops. BASF SE leverages its extensive R&D in polymer science to develop advanced flocculants for these systems. Solvay specializes in high-performance reagents for the solvent extraction of critical minerals, while Kemira Oyj competes with its comprehensive water treatment solutions for mine closure and reclamation.
Mining chemicals are specialty and commodity formulations used to improve the efficiency and yield of mineral extraction. These products function by altering the physicochemical properties of ores and slurries to facilitate the separation of valuable minerals from waste rock, or gangue. Flotation reagents and grinding aids constitute the largest product categories, essential for most mineral processing operations. Metal recovery remains the dominant application, with demand particularly strong for chemicals tailored to copper and gold extraction.
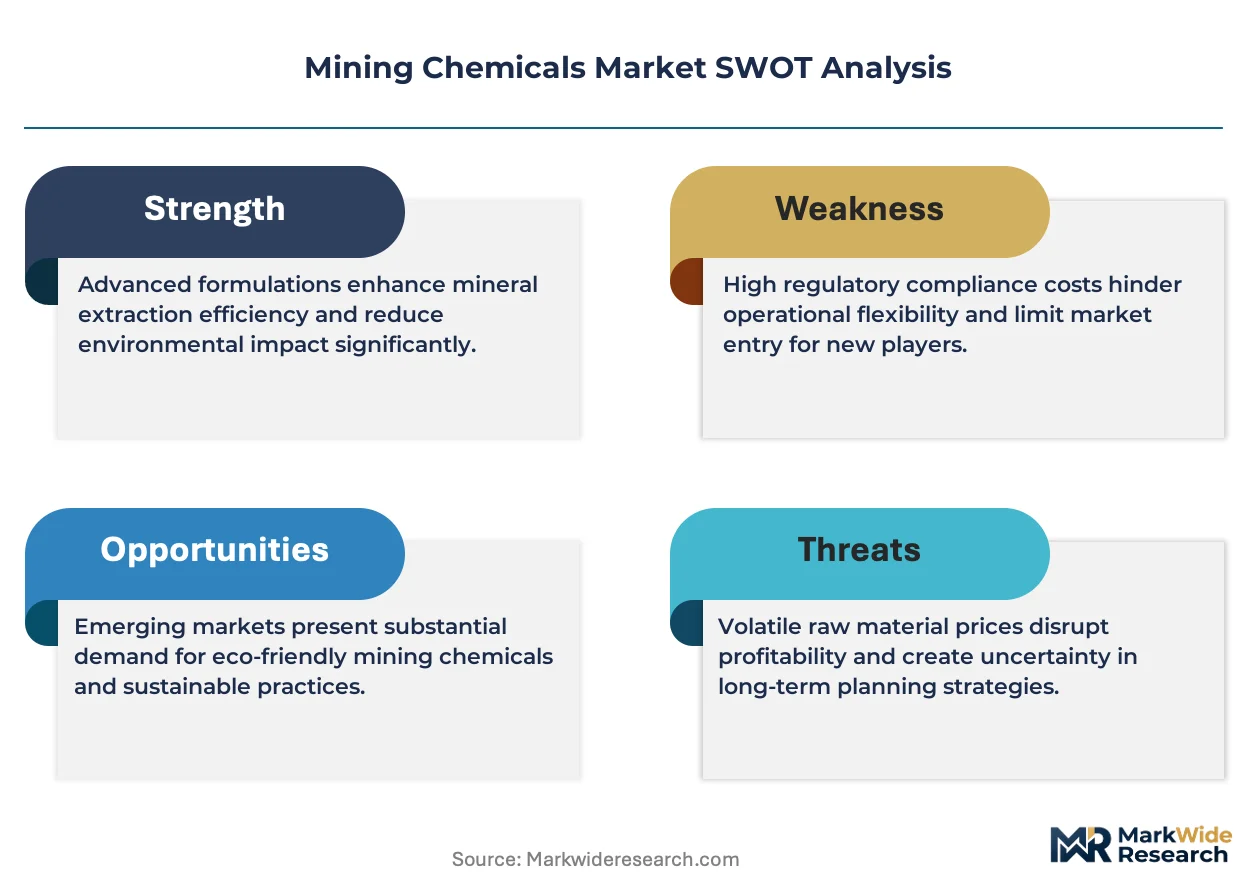
Regulatory frameworks such as the EU's REACH regulation, the US EPA's water quality standards, and China's MEE directives on industrial pollution are reshaping product development. These rules mandate lower toxicity and greater biodegradability, pushing manufacturers toward greener chemistry. For suppliers, the central challenge will be to innovate high-performance, eco-friendly formulations that still meet the mining industry's stringent cost-per-ton metrics.
Market Dynamics
The mining chemicals market is shaped by the fundamental tension between the economic necessity to process lower-grade ores and the mounting regulatory pressure for sustainable mining practices. This dynamic compels innovation in chemical formulations that can enhance mineral recovery efficiency while minimizing environmental impact and complying with stricter water and waste directives.
Growth Catalysts
- Advanced Bioleaching Technologies:The development of bio-hydrometallurgical processes, which use microorganisms to extract metals, is enabling the economic processing of low-grade sulfide ores and mine tailings that were previously unviable.
- Battery Material Demand:Surging production of electric vehicles and energy storage systems creates sustained demand for lithium, cobalt, and high-purity copper, directly boosting consumption of specialized solvent extraction reagents and flotation collectors.
- Major Mining Jurisdictions:Extensive copper and lithium operations in countries like Chile and Australia provide a concentrated and stable demand base for a wide range of processing chemicals, from grinding aids to flocculants.
Market Restraints
- Feedstock Price Volatility:The cost of many specialty chemicals, such as synthetic polymers used in flocculants, is directly tied to volatile petrochemical feedstock prices, creating margin pressure for manufacturers and budget uncertainty for mine operators.
- Stringent Water Regulations:Water quality standards, such as those mandated by the US EPA, impose strict limits on the concentration of residual chemicals in mine effluent, requiring costly water treatment steps or the use of more expensive, less-effective green alternatives.
- Performance of Eco-Friendly Formulations:A significant technical barrier is the difficulty in developing biodegradable reagents that can match the recovery efficiency and selectivity of traditional, often more toxic, chemistries under harsh operational conditions.
Strategic Opportunities
- Tailings Reprocessing:Developing chemical solutions specifically for re-mining and reprocessing historical tailings dams presents an opportunity to recover valuable metals while addressing environmental liabilities, creating a new service and chemical demand stream.
- Digital Service Integration:Suppliers can offer AI-driven dosage optimization software and remote monitoring platforms as a value-added service, creating recurring revenue streams and locking in customers beyond simple chemical sales.
- Emerging African Mining Belts:The copper and cobalt belts of the Democratic Republic of Congo and Zambia represent a significant growth frontier for reagent suppliers able to navigate the region's logistical and geopolitical complexities.
Industry Challenges
- Specialized Talent Scarcity:A persistent challenge is the shortage of metallurgists and chemical engineers who possess dual expertise in mineral processing science and the data analytics required to manage modern, automated reagent dosing systems.
- Remote Site Logistics:Ensuring a consistent and timely supply of chemicals to often remote and inaccessible mine sites involves significant logistical hurdles, including transportation infrastructure deficits and supply chain security risks.
- Legacy System Integration:Implementing advanced, high-purity chemical formulations is often hindered by the difficulty of integrating them with older processing plants and equipment that were not designed for such precise control.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mining Chemicals Market |
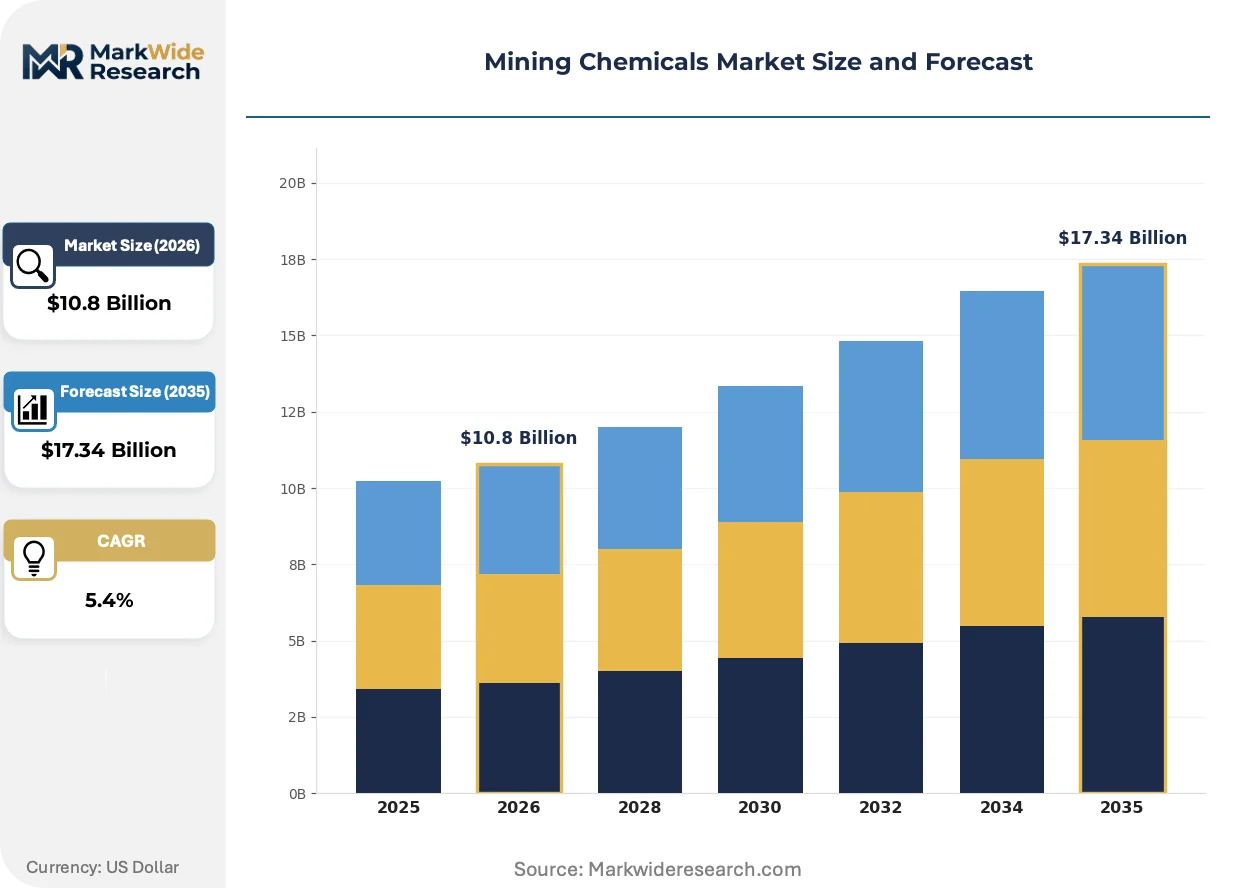
| Market Size in 2026 | $10.8 Billion |
| Market Size in 2035 | $17.34 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flotation Reagents, Leaching Agents, Grinding Aids, Flocculants, pH Modifiers Technology: Solvent Extraction, Ion Exchange, Bioleaching, Heap Leaching, Froth Flotation Application: Metal Recovery, Coal Processing, Mineral Processing, Water Treatment, Dust Suppression End User: Mining Operators, Mineral Processors, Metal Refiners, Equipment Suppliers |
| Companies Covered | Dow Chemical Company, Kemira Oyj, BASF SE, AECI, SNF Group, Clariant, Arkema, Chevron Phillips Chemical Company, Solvay, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mining Chemicals Market Strategic Shifts & Innovations
The convergence of digitalization and sustainability is fundamentally altering the criteria for chemical selection and application in mineral processing. Efficacy is no longer the sole metric; suppliers must now demonstrate environmental compliance, data transparency, and integration with automated control systems to maintain a competitive edge.
Digital twin technology, which creates a virtual replica of a mineral processing circuit, is gaining traction. Large-scale copper and gold miners are adopting this to simulate reagent performance and optimize process parameters without interrupting physical operations. The industry’s approach to chemical selection is migrating from reliance on physical, batch-based laboratory trials to a model based on continuous, predictive digital simulation.
Regulations like the EU's Corporate Sustainability Reporting Directive (CSRD) are increasing the burden of proof for environmental claims. This rule compels mining companies with significant European operations to disclose detailed, audited data on their chemical usage, water impact, and lifecycle management. The directive particularly affects suppliers to Scandinavian mining projects, who must now provide verifiable data on the biodegradability of their flotation agents and flocculants.
A notable shift in purchasing behavior involves the move from transactional, volume-based chemical sales to performance-oriented partnerships. This model replaces traditional cost-per-liter pricing with contracts based on shared metrics, such as cost-per-ton of mineral recovered or improvements in water quality. This trend is most visible in high-value gold and platinum group metal operations in South Africa and Australia, where process efficiency gains have a direct and substantial impact on profitability.
Mining Chemicals Market Segmentation
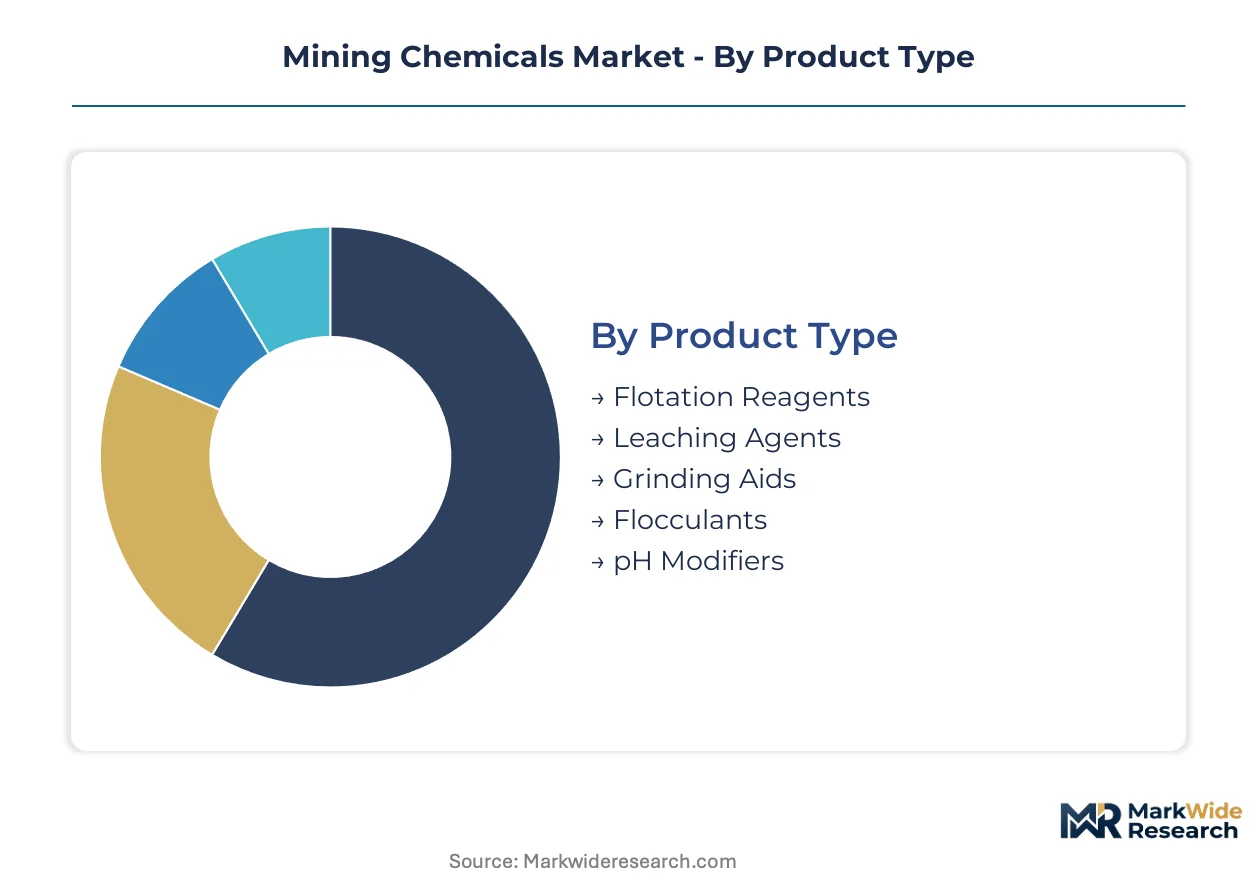
The mining chemicals market segmentation reflects the intricate interplay between diverse ore bodies, evolving extraction technologies, and stringent environmental mandates. Understanding these distinct segments is crucial for identifying targeted growth opportunities and navigating specialized product requirements.
Product Type:
The Product Type segment encompasses both mature chemical formulations and emerging specialized reagents designed for complex mineral matrices.
- Flotation Reagents:These chemicals selectively alter the surface properties of valuable minerals, enabling them to attach to air bubbles and separate from waste rock in froth flotation cells. Demand is particularly strong in copper and gold extraction operations across Australia and Chile due to their extensive mineral reserves.
- Flocculants:Polymers designed to aggregate fine particles in slurries, aiding solid-liquid separation and water clarification processes. Usage is increasing in mine dewatering and tailings management, driven by stricter water quality standards from the US EPA.
- Leaching Agents:Chemicals like acids or bases used to dissolve target metals from ore, particularly in hydrometallurgical processes.
- Grinding Aids:Additives that reduce energy consumption during ore comminution by preventing particle agglomeration.
- pH Modifiers:Acids or bases employed to control the acidity or alkalinity of process slurries, optimizing chemical reactions.
Flotation Reagents retain volume leadership; Flocculants hold the steepest expansion curve.
Technology:
Technology segmentation reflects the diverse methods employed to extract and purify minerals from ore bodies.
- Bioleaching:This technology utilizes microorganisms to solubilize metals from low-grade ores and mine tailings, offering an environmentally gentler extraction route. Bioleaching is gaining traction in processing complex sulfide ores found in regions like the Democratic Republic of Congo.
- Solvent Extraction:A hydrometallurgical process employing organic reagents to selectively separate and concentrate target metal ions from aqueous solutions. Demand for solvent extraction is high for critical battery materials like lithium and cobalt, especially in Chile.
- Ion Exchange:A purification process using resin beads to selectively remove or recover specific ions from solution.
- Heap Leaching:Involves percolating a chemical solution through a prepared pile of ore to dissolve and extract valuable metals.
- Froth Flotation:A physical-chemical separation process where valuable minerals are selectively attached to air bubbles and recovered in a froth layer.
Froth Flotation continues to deliver foundational processing efficiency; Bioleaching offers significant environmental and economic benefits for future resource recovery.
Application:
Application segmentation highlights where the largest volumes of mining chemicals are consumed, reflecting core industry needs.
- Metal Recovery:This primary application focuses on extracting valuable metals like copper, gold, and lithium from their ores. Metal recovery drives substantial demand for flotation reagents and leaching agents across major mining jurisdictions.
- Water Treatment:Involves chemical processes to purify mine wastewater and manage effluent, ensuring compliance with environmental regulations such as the US EPA's water quality standards. This is a critical area for sustainable mining practices.
- Coal Processing:Chemicals enhance the separation of coal from impurities and improve dewatering processes.
- Mineral Processing:Encompasses a broad range of operations to prepare ores for metal extraction, including comminution and separation.
- Dust Suppression:Chemicals are applied to control airborne particulate matter at mine sites, improving air quality and safety.
Metal Recovery dictates the bulk of chemical demand; Water Treatment applications are increasingly shaped by stringent regulatory frameworks.
End User:
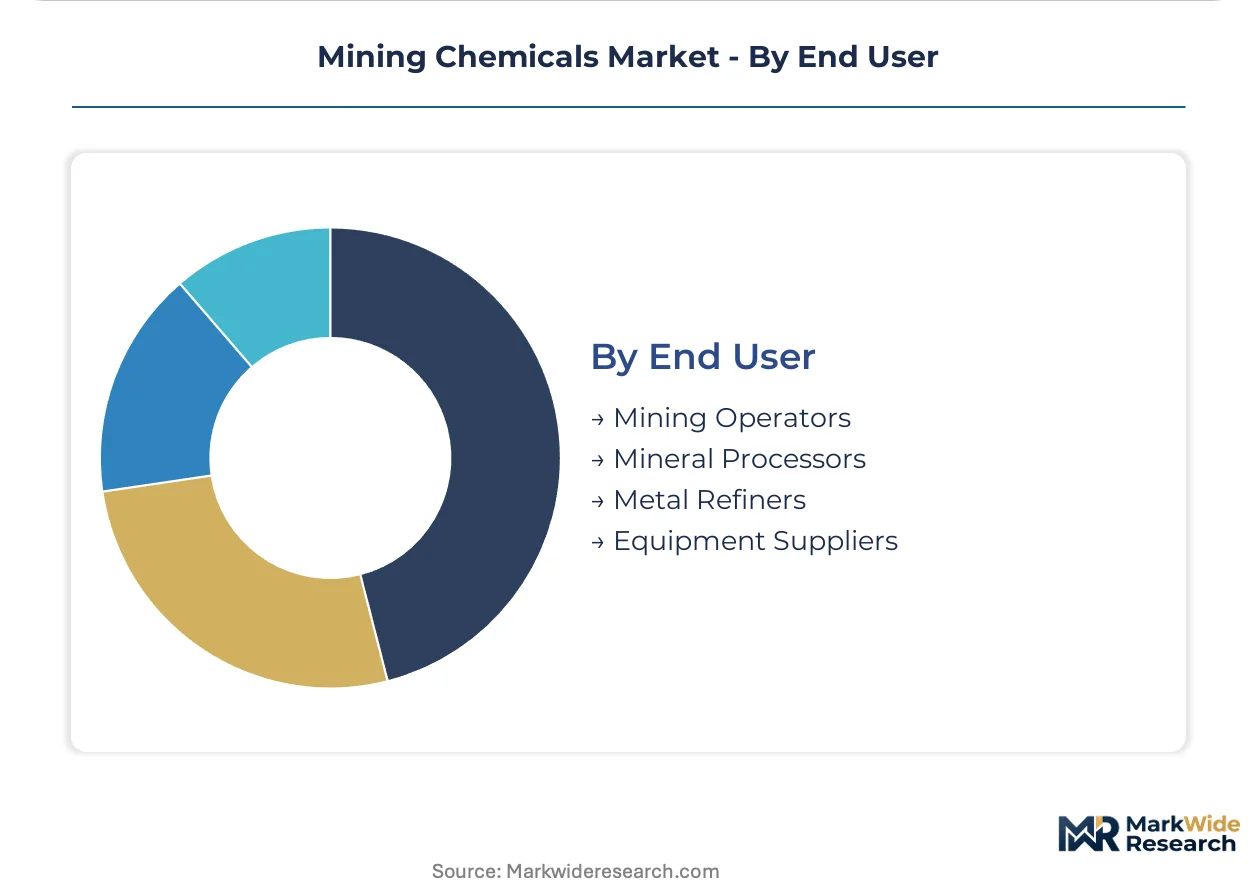
End User segmentation delineates the primary customer types procuring mining chemicals, each with distinct operational requirements.
- Mining Operators:Companies directly involved in extracting raw ore from the earth, utilizing chemicals for initial processing steps at the mine site. These entities drive demand for a broad spectrum of chemicals, from grinding aids to flocculants.
- Mineral Processors:Specialized facilities that take raw ore and concentrate valuable minerals through various physical and chemical separation techniques. They are significant consumers of flotation reagents and solvent extraction chemicals.
- Metal Refiners:Facilities that purify concentrated metals to high-purity standards, using specialized chemicals in their refining processes.
- Equipment Suppliers:Companies that provide machinery and systems to the mining industry, sometimes integrating chemicals into their offerings or recommending specific formulations.
Mining Operators represent the foundational demand base; Mineral Processors exert substantial influence over chemical selection for advanced separation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chemicals from European manufacturers frequently supply the extensive mining operations across South America and Australia. This global demand drives regional chemical consumption patterns, influenced by local mineral endowments and regulatory pressures.
Australia
Demand for flotation reagents and flocculants supports Australia's extensive iron ore and gold mining sectors. The TGA mandates strict environmental impact assessments for new mining projects. Western Australia's Pilbara region drives chemical consumption for mineral processing.
Chile
Chile's vast copper and lithium operations create strong demand for specialized solvent extraction reagents. The national environmental agency, SEA, enforces rigorous water quality standards for mine effluent. The Atacama Desert region sees concentrated demand for hydrometallurgical processes.
China
China's large-scale rare earth and base metal mining operations require diverse chemical formulations. The Ministry of Ecology and Environment (MEE) directives on industrial pollution drive demand for greener chemistry. Inner Mongolia and Xinjiang provinces represent significant hubs for mineral processing chemical consumption.
South Africa
South Africa's platinum group metals and gold mining sectors generate consistent demand for flotation reagents. The Department of Water and Sanitation implements stringent water use and discharge regulations for mining activities. The Bushveld Igneous Complex region concentrates significant chemical demand for beneficiation.
Brazil
Brazil's extensive iron ore and bauxite mining operations drive substantial chemical requirements. The Brazilian Institute of Environment and Renewable Natural Resources (IBAMA) oversees environmental licensing and compliance. Minas Gerais state is a primary center for mineral processing, consuming large volumes of flocculants.
Mining Chemicals Market Key Industry Players
On the supply side, the industry is characterized by a mix of large, diversified chemical manufacturers and specialized niche players. This creates a tiered competitive landscape where global chemical giants compete with focused reagent providers. Strategic archetypes include integrated chemical suppliers, dedicated mineral processing chemical specialists, and environmental solution providers. Companies pursue portfolio diversification and advanced R&D in greener chemistry to maintain market relevance.
Within the diversified chemical giants tier, BASF SE exemplifies extensive R&D capabilities, particularly in polymer science for advanced flocculants used in automated systems. Solvay, a global chemical company, occupies a strong position in high-performance reagents designed for the solvent extraction of critical battery materials. Kemira Oyj, with its comprehensive water treatment solutions, represents another key player, anchoring the environmental compliance segment for mine closure and reclamation. These companies leverage their global reach and innovation pipelines to serve diverse mining operations, focusing on both efficiency and sustainability.
| Leading Market Players |
|---|
| Dow Chemical Company |
| Kemira Oyj |
| BASF SE |
| AECI |
| SNF Group |
| Clariant |
| Arkema |
| Chevron Phillips Chemical Company |
| Solvay |
| Others |
Cost & Logistics Intelligence
Petrochemical feedstock price volatility from major oil-producing regions directly impacts the cost of synthetic polymers, influencing margin pools for specialty chemical manufacturers.
Pricing Analysis
The technology-generation pricing gap for advanced flocculants and solvent extraction reagents reflects their higher performance and R&D intensity compared to traditional chemistries. Contract-based long-term offtake agreements dominate for large-volume chemicals, while value-based pricing emerges for high-purity, digitally integrated formulations. Price differentiation stems from the quality grade required for automated systems and the depth of after-sales service integration. Pricing softness reflects the availability of lower-cost, less-effective green alternatives. Mining operators, focused on cost-per-ton metrics, represent the most price-sensitive segment.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities are common, reflecting the capital-intensive nature of mining operations and the need for consistent chemical supply. Geographic supply concentrates in China for rare earth processing chemicals and Europe for specialty reagents from companies like BASF SE and Solvay. The supply chain draws from critical raw material dependencies including petrochemical feedstocks and specific polymer precursors. Feedstock price volatility represents a structural risk. Distribution runs through direct sales channels for major mining groups and through regional distributors for smaller operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires a substitution defense, as bio-hydrometallurgical processes and advanced physical separation techniques threaten to displace traditional chemical-intensive methods.
For Market Incumbents:Harden core chemical offerings by investing heavily in greener chemistry R&D, particularly for biodegradable reagents that match performance. Integrate AI-driven process control systems as a value-added service, moving beyond simple chemical sales to performance-oriented partnerships. Secure long-term supply agreements for critical raw materials to mitigate feedstock price volatility. Pursue strategic acquisitions of niche technology providers specializing in bioleaching or digital twin solutions to counter emerging entrant archetypes.
For New Entrants and Emerging Players:Pursue white-space opportunities in tailings reprocessing, developing chemical solutions for recovering valuable metals from historical waste streams. Target emerging African mining belts like the Democratic Republic of Congo and Zambia, focusing on specialized reagents for complex sulfide ores. A go-to-market angle should emphasize verifiable environmental compliance and data transparency, leveraging regulatory frameworks like the EU's CSRD. Offer flexible, performance-based contracts to overcome initial adoption barriers with mining operators.
For Investors and Strategic Acquirers:Capital is best deployed toward specialized chemical providers with strong intellectual property in green chemistry and digital integration capabilities. The market's long-term viability, spanning a 5-10 year window, rests on sustained battery material demand and increasing regulatory pressure for sustainable mining. Identify acquisition targets that offer comprehensive water treatment solutions for mine closure and reclamation. A signal to watch is the increasing adoption rate of digital twin technology by major miners, indicating a shift towards integrated chemical and software solutions.
| Strategic Initiative | Industry Significance |
|---|---|
| Green Chemistry R&D Investment | Developing biodegradable reagents addresses stringent environmental regulations like REACH and CSRD. |
| Digital Service Platform Integration | Offering AI-driven dosage optimization enhances efficiency and creates recurring revenue streams for suppliers. |
| Targeted Bioleaching Reagent Development | Enables economic processing of low-grade ores, expanding the addressable market for chemical suppliers. |
| Tailings Reprocessing Solutions | Creates a new chemical demand stream while mitigating environmental liabilities for mining companies. |
| Strategic Partnerships in Emerging Markets | Secures early market share in high-growth regions like the African copper and cobalt belts. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with industry stakeholders and secondary validation from diverse sources. Primary insights were gathered from metallurgists, mine operators, chemical procurement leads, and R&D directors across major mining jurisdictions. Secondary data was sourced from industry association reports, regulatory filings from the US EPA and China's MEE, academic journals, and customs trade data. Bottom-up and top-down triangulation ensured data consistency.
Forecast inputs considered historical trends, current market dynamics, and future demand projections over the projection horizon. Segmentation dimensions modeled included product type, technology, application, end user, and regional demand patterns. Compound annual growth rates (CAGRs) were derived from a comprehensive analysis of these factors, projecting market expansion. Battery material production forecasts and bioleaching technology adoption rates served as key industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in global commodity prices or geopolitical stability would shift the trajectory. Forecasts reflect assumptions regarding regulatory stability and technological advancements within the mining sector. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Nitrogen Trifluoride (NF3) Market
Industrial Chemicals
Technical Enzymes Market
Industrial Chemicals
Glycidyl Ether Market
Industrial Chemicals
Pickling Chemicals Market
Industrial Chemicals
Sulfolane Market
Industrial Chemicals
Rodenticides Market
Industrial Chemicals
Global N-MDEA Market
Industrial Chemicals
North America Quicklime Market
Industrial Chemicals
Toluene Diisocyanates (TDI) Market
Industrial Chemicals
South Africa Gypsum Plaster Market
Industrial Chemicals
Silicates Market
Industrial Chemicals
Electro-Erosion Fluids Market
Industrial Chemicals
Draft Tube Baffle (DTB) Crystallizers Market
Industrial Chemicals
Mold Powders and Casting Fluxes Market
Industrial Chemicals
Caustic Calcined Magnesia Market
Industrial Chemicals
Global Acid Proof Lining Market