
 Africa Mining Chemicals Market | 2026-2036
Africa Mining Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Mining Chemicals Market Intelligence
Market Context
High-purity flotation reagent specifications are redrawing competitive boundaries across African mining corridors. BASF SE leverages its integrated polymer supply chain to dominate specialty flocculant deliveries in Southern Africa. AECI Mining Chemicals anchors its position through captive manufacturing in South Africa and direct rail links to Zambia's Copperbelt. Orica Limited differentiates via bulk emulsion and electronic blasting systems that reduce downstream chemical intensity.
Technical Definition and Segments
Africa mining chemicals encompass formulated reagents, solvents, and process aids with defined active-content thresholds, typically 85-98% purity for xanthate collectors and specified molecular-weight distributions for polyacrylamide flocculants, deployed to enhance mineral separation efficiency and wastewater compliance. Flocculants and coagulants lead product-type revenue due to universal deployment in tailings thickening across platinum and gold operations, while surfactants represent the fastest-growing category as bio-based formulations displace petroleum-derived alternatives. Mineral processing commands the largest application share through froth flotation and leaching circuits, though tailings management is deepening its margin pool as dam-safety regulations tighten.
Regulatory Framework
South Africa's Department of Mineral Resources and Energy, Zambia's Environmental Management Agency, and the Democratic Republic of Congo's national mining code collectively shape product standards through tailings-storage-facility audits and import-licensing requirements for cyanide and sulfuric acid. REACH-equivalent chemical-registration pressures in select African Economic Community zones are beginning to filter formulation choices for multinational suppliers. Stakeholders must monitor how the African Mining Vision's local-content mandates recalibrate procurement rules for reagent sourcing.
Market Dynamics
Ore-grade degradation across West African gold belts and the Copperbelt is intensifying reagent consumption per tonne of metal recovered, while South Africa's amended Mine Health and Safety Act tightens tailings-facility compliance burdens.
Growth Catalysts
- Copper-cobalt hydrometallurgical expansion:Solvent-extraction and electrowinning circuits in the Democratic Republic of Congo and Zambia are scaling sulfuric acid and organic-diluent demand as oxide-ore processing deepens.
- Platinum-group-metal tailings reprocessing:South Africa's Bushveld Complex operators are deploying advanced flocculant systems to extract residual value from historic tailings dams, driving specialty chemical volumes.
- African Mining Vision local-content mandates:Procurement rules in select regional economic communities are redirecting reagent sourcing toward domestic formulation facilities, stimulating captive manufacturing investments.
Market Restraints
- Caustic-soda and sulfuric-acid price volatility:Input costs for leaching and pH adjustment swing with energy prices and shipping rates, compressing margins for fixed-price supply contracts.
- Single-source import dependence:Xanthate collectors and specialty frothers often route through Durban or Dar es Salaam port corridors, creating concentration risk during logistics disruptions.
- Cyanide-transport licensing friction:Zambia's Environmental Management Agency and South Africa's Department of Mineral Resources and Energy impose divergent handling-certification requirements, complicating cross-border chemical movements.
Strategic Opportunities
- Bio-based surfactant formulation:Petroleum-derived frother chemistries face displacement from plant-derived alternatives as mining houses adopt Scope 3 emissions targets.
- Tailings-dam safety audits:South Africa's stricter facility-inspection mandates under amended mining law are expanding the addressable market for geotechnical-monitoring reagents and sealing polymers.
- Direct rail-to-mine distribution:Bulk-emulsion and flocculant deliveries via dedicated freight corridors to Zambia's Copperbelt bypass port congestion and reduce working-capital cycles.
Industry Challenges
- Process-chemistry talent scarcity:Qualified flotation and hydrometallurgical specialists are concentrated in South Africa and Australia, complicating operational scaling in West African greenfield sites.
- Legacy thickener integration:New high-performance flocculant chemistries require retrofitting of underflow pump capacities and rake drive systems at aging platinum and gold operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Mining Chemicals Market |
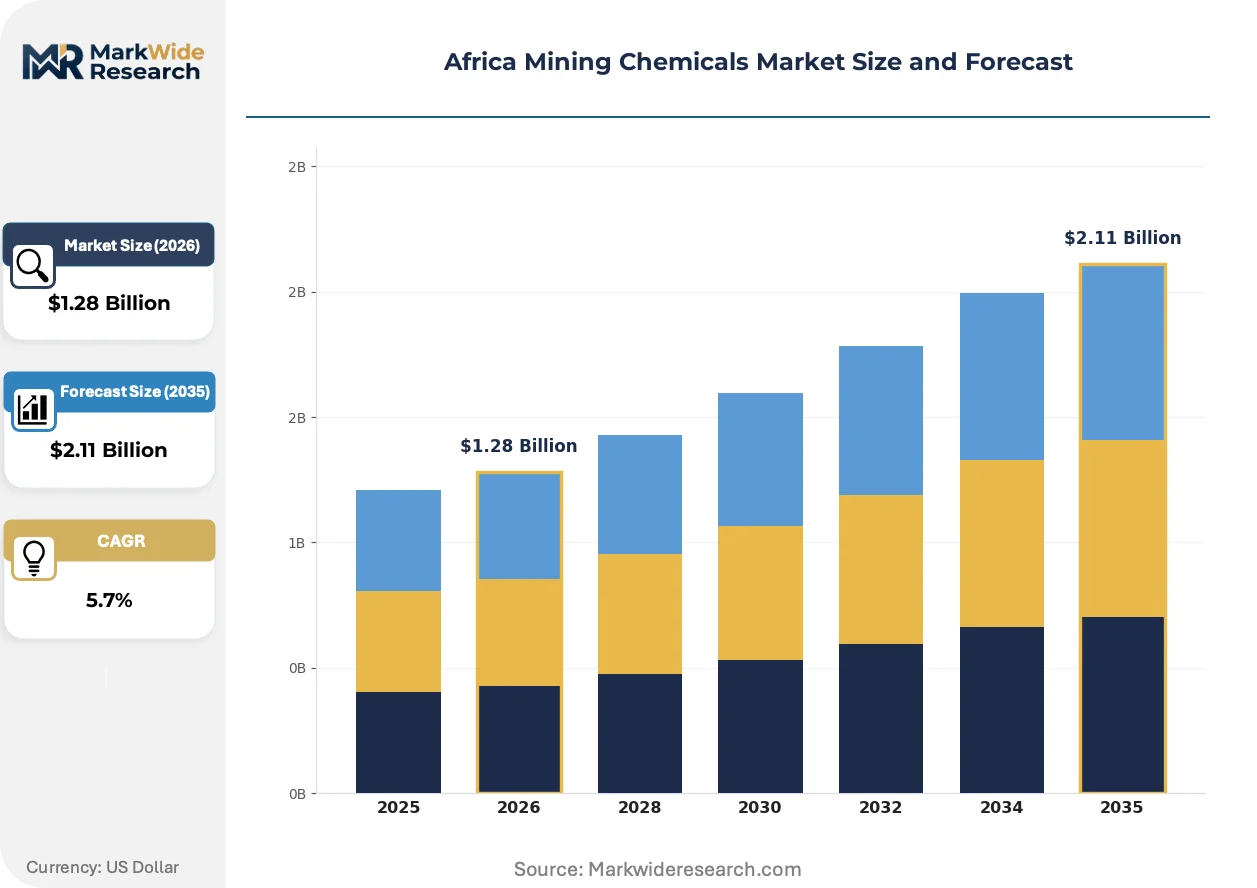
| Market Size in 2026 | $1.28 Billion |
| Market Size in 2035 | $2.11 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flocculants, Coagulants, Surfactants, Antiscalants Application: Mineral Processing, Water Treatment, Flotation, Tailings Management End User: Mining Companies, Mineral Processors, Contractors, OEMs Technology: Biotechnology, Chemical Synthesis, Physical Separation, Electrochemical |
| Companies Covered | BASF SE, Akzo Nobel N.V., Dow, Sasol, Clariant, Cytec Solvay Group, AECI Mining Chemicals, Orica Limited, Ashland, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Mining Chemicals Market Strategic Shifts & Innovations
Digital process-control systems and bio-based formulation chemistry are compressing reagent dosing precision and environmental footprint simultaneously across African extraction corridors.
Sensor-based flotation optimization is miniaturizing. Miniaturized online X-ray fluorescence and laser-induced breakdown spectroscopy units now embed directly into rougher-cell launders, enabling real-time grade-feedback loops. Gold and copper operators in Ghana and Zambia are piloting these systems to reduce collector overdosing. The technology is miniaturizing capital barriers for mid-tier miners who previously relied on centralized assay laboratories.
REACH-equivalent chemical-registration frameworks are emerging in select African Economic Community zones, compelling multinational suppliers to reformulate products or establish local registration entities. The industrial consequence is a bifurcation between registered-premium and unregistered-commodity reagent tiers. Flocculant and collector categories face the steepest compliance timelines, with suppliers accelerating dossier preparation for polyacrylamide molecular-weight specifications.
Consolidated procurement through mining-house central warehouses is displacing site-level chemical purchasing across West African operations. AngloGold Ashanti and Barrick Gold are unbundling reagent sourcing from individual mine contracts toward regional supply agreements with volume-tier pricing. This pattern is most visible in Ghana's Ashanti belt, where single-source flocculant and cyanide contracts now span multiple pits under unified logistics coordination.
Africa Mining Chemicals Market Segmentation
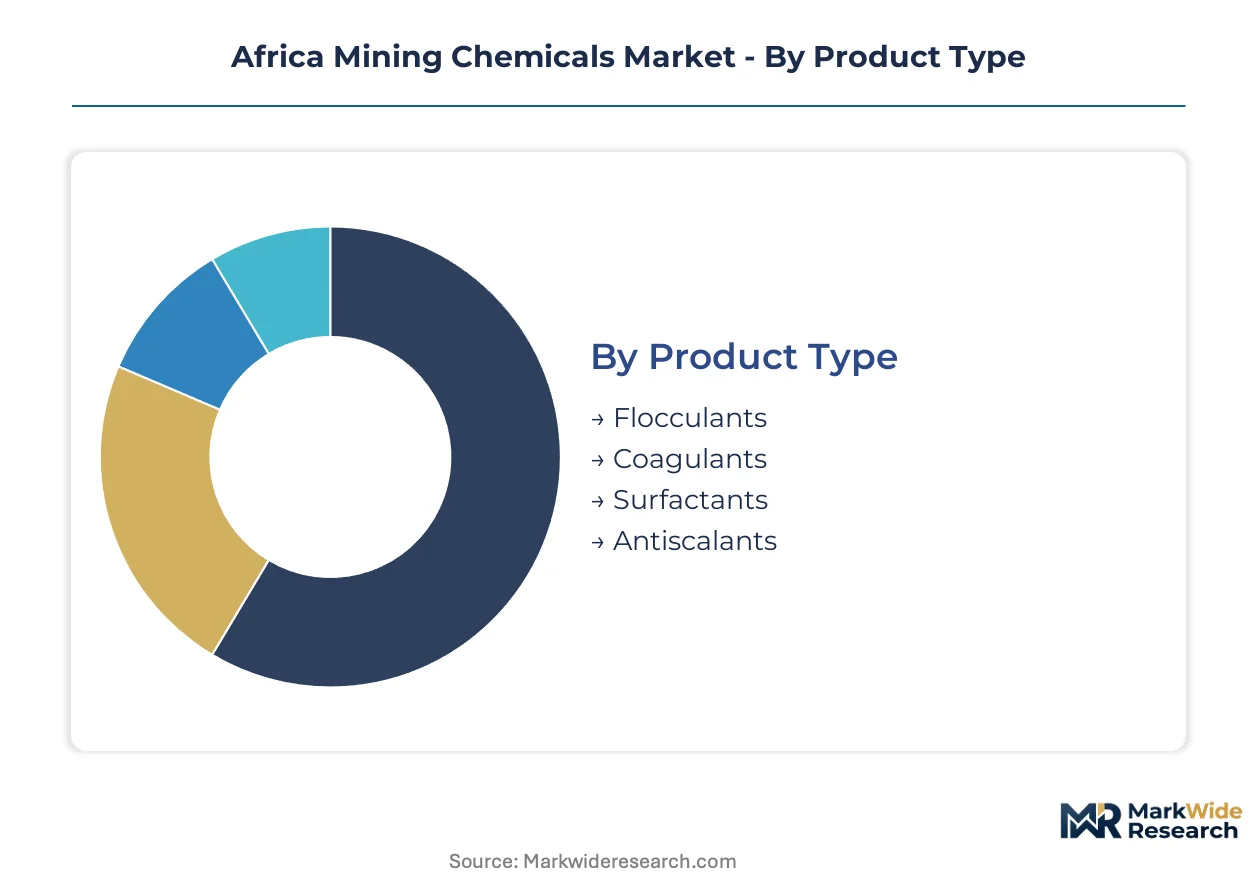
Mining chemical procurement in Africa channels through distinct technical and commercial pathways. Product specifications, application intensity, and end-user procurement power create tiered market structures that suppliers must navigate.
Product Type:
Flocculants and collectors move through direct manufacturer-to-mine contracts, while commodity solvents and pH modifiers route via regional distributors with inventory buffers at Durban and Dar es Salaam ports.
- Flocculants:High-molecular-weight polyacrylamide formulations (anionic and cationic variants) achieve 85-98% active content for tailings thickening. Demand concentrates in South Africa's Bushveld platinum operations and Zambia's Copperbelt, where dam-safety audits under South Africa's amended Mine Health and Safety Act mandate advanced dewatering performance.
- Coagulants:Inorganic aluminum and iron-based salts precipitate suspended solids in process water circuits. Ghana's Ashanti gold belt and the Democratic Republic of Congo's Kolwezi copper district are deepening consumption as freshwater scarcity intensifies closed-loop requirements.
- Surfactants:Petroleum-derived and emerging bio-based frother chemistries reduce surface tension in flotation cells.
- Antiscalants:Phosphonate and polymeric formulations inhibit mineral precipitation in reverse-osmosis and cooling systems.
Flocculants dominate installed base. Surfactants are where expansion concentrates.
Application:
Cost tiering separates high-margin specialty reagents for complex ore bodies from commodity chemicals for standard circuits, with hydrometallurgical applications commanding premium pricing over mechanical separation.
- Mineral Processing:Froth flotation and leaching circuits consume xanthate collectors, frothers, and cyanide for gold and copper recovery. The Copperbelt's solvent-extraction and electrowinning operations in Zambia and the Democratic Republic of Congo are scaling sulfuric acid and organic-diluent demand as oxide-ore processing deepens.
- Water Treatment:Process-water recycling and effluent neutralization deploy pH adjusters and heavy-metal precipitants. South Africa's Department of Mineral Resources and Energy enforces stricter discharge standards, compelling platinum and gold operators to upgrade treatment infrastructure.
- Flotation:Selective mineral separation relies on collector-frother-depressant combinations tailored to ore mineralogy.
- Tailings Management:Thickening, filtration, and dam-sealing applications use flocculant-coagulant blends and geotechnical polymers.
Mineral processing anchors volume. Tailings management is climbing the fastest.
End User:
Customer procurement power stratifies the market, with consolidated mining houses extracting volume-tier pricing that mid-tier processors and project contractors cannot match.
- Mining Companies:Integrated majors like AngloGold Ashanti and Barrick Gold centralize reagent sourcing across West African operations through regional supply agreements with unified logistics coordination.
- Mineral Processors:Toll-treatment facilities and concentrate traders purchase spot quantities with higher price elasticity.
- Contractors:Engineering-procurement-construction firms bundle chemical supply into turnkey plant contracts.
- OEMs:Equipment manufacturers specify reagent packages for flotation cells, thickeners, and filtration systems.
Mining companies dominate installed base. Mineral processors are where expansion concentrates.
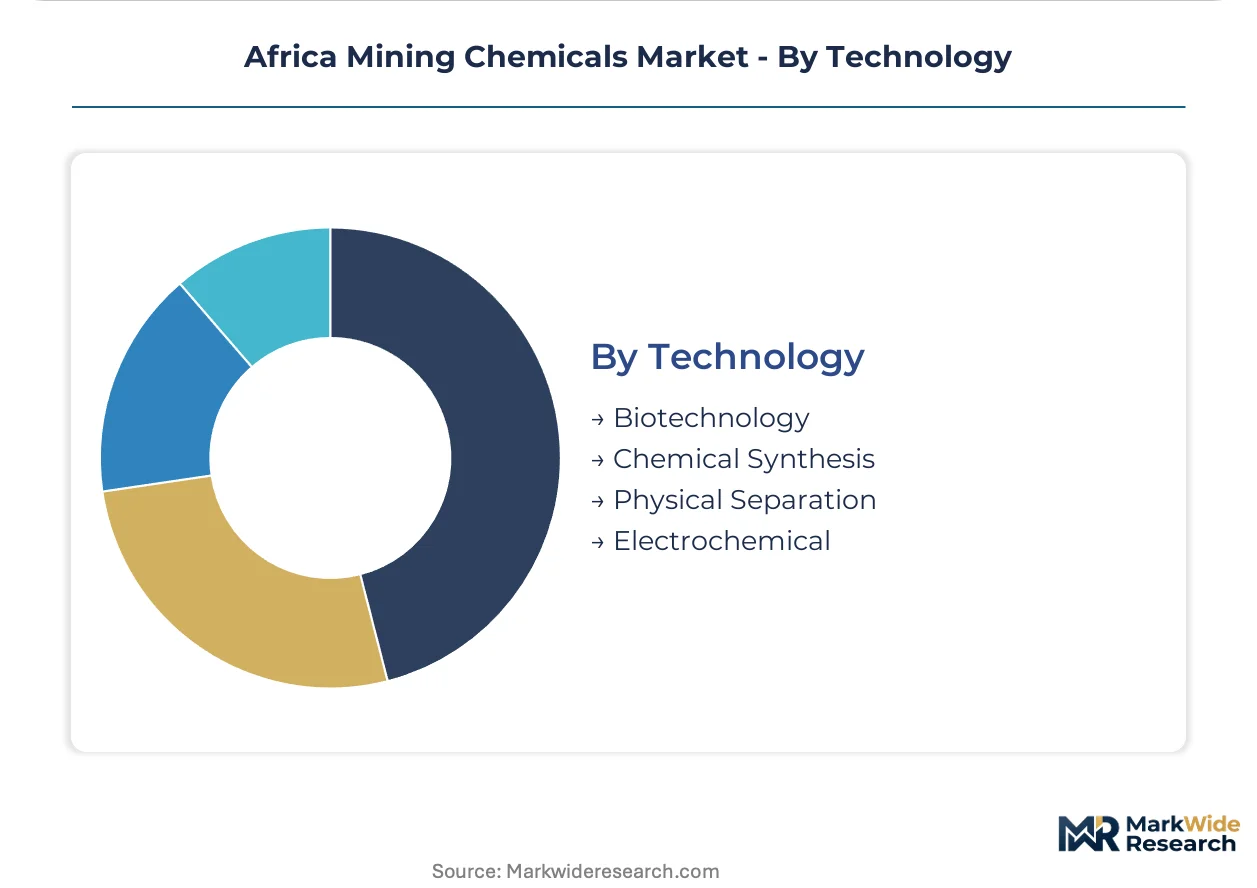
Technology:
Supply concentration favors chemical synthesis for volume commodities, while biotechnology and electrochemical methods occupy emerging niches with higher technical barriers.
- Biotechnology:Enzymatic and bio-surfactant formulations reduce environmental footprint. Plant-derived frother alternatives are gaining traction as mining houses adopt Scope 3 emissions targets.
- Chemical Synthesis:Conventional organic and inorganic manufacturing produces xanthates, cyanides, and polyacrylamides at scale. BASF SE and AECI Mining Chemicals anchor production in South Africa with captive manufacturing and direct rail links to Zambia's Copperbelt.
- Physical Separation:Gravity and magnetic concentration methods minimize chemical intensity.
- Electrochemical:Electrocoagulation and electro-oxidation treat recalcitrant effluents.
Chemical synthesis dominates installed base. Biotechnology is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Formulation capacity clusters in South Africa's industrial corridor, with rail spines extending reagent supply into Zambia's Copperbelt and Ghana's Ashanti gold belt. Port bottlenecks at Durban and Dar es Salaam concentrate import risk for specialty collectors and frothers.
South Africa
Platinum-group-metal tailings reprocessing in the Bushveld Complex drives flocculant consumption as operators extract residual value from historic dams. The Department of Mineral Resources and Energy enforces stricter tailings-facility standards under amended Mine Health and Safety Act provisions. Johannesburg-Pretoria manufacturing anchors regional supply, with AECI Mining Chemicals operating captive production and direct rail links northward.
Zambia
Copper-cobalt hydrometallurgical expansion in the Copperbelt intensifies sulfuric acid and organic-diluent demand as oxide-ore processing deepens. The Environmental Management Agency imposes divergent cyanide-transport licensing requirements that complicate cross-border chemical movements. Kitwe and Ndola concentrate processing infrastructure, with solvent-extraction and electrowinning circuits scaling reagent throughput.
Democratic Republic of Congo
Kolwezi copper-cobalt operations escalate hydrometallurgical chemical inputs as miners process lower-grade oxide deposits. The national mining code shapes product standards through import-licensing requirements for sulfuric acid and cyanide. Lualaba province hosts expanding SX-EW capacity, with Chinese-operated hubs deepening regional reagent demand.
Ghana
Gold extraction across the Ashanti belt expands reagent consumption as ore grades decline and operators process deeper sulfide zones. Consolidated procurement through AngloGold Ashanti and Barrick Gold regional supply agreements redirects sourcing toward unified logistics coordination. Obuasi and Ahafo mine clusters anchor consumption, with centralized warehousing displacing site-level chemical purchasing.
Africa Mining Chemicals Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Specialty flocculant and collector formulations command premium positioning, while bulk commodity acids and solvents compete on logistics efficiency and working-capital terms. Three archetypes dominate: integrated chemical majors with polymer supply chains, regional formulators with captive rail distribution, and explosives specialists bundling blasting systems with downstream chemical reduction. Capacity expansion into Zambian direct-rail corridors and portfolio diversification toward bio-based surfactants represent the dominant competitive vectors.
Within the integrated chemical tier, BASF SE anchors polymer supply chain control across Southern Africa. AECI Mining Chemicals exemplifies regional formulator positioning through South African manufacturing and Copperbelt rail penetration. Orica Limited occupies the explosives-chemical bundling archetype, with bulk emulsion systems reducing downstream reagent intensity for mining customers.
| Leading Market Players |
|---|
| BASF SE |
| Akzo Nobel N.V. |
| Dow |
| Sasol |
| Clariant |
| Cytec Solvay Group |
| AECI Mining Chemicals |
| Orica Limited |
| Ashland |
| Others |
Cost & Logistics Intelligence
Long-term offtake agreements with volume-tier pricing lock in supply access for copper-cobalt hydrometallurgical operators while fixing sulfuric acid and organic-diluent costs against energy-price swings. South Africa's Department of Mineral Resources and Energy tailings-facility audits and Zambia's Environmental Management Agency cyanide-licensing requirements embed compliance premiums into contract structures, binding price visibility to regulatory adherence across the Copperbelt and Bushveld Complex.
Pricing Analysis
South Africa's amended Mine Health and Safety Act dictates the pricing tier structure for flocculant and coagulant procurement, separating premium-grade polyacrylamide formulations for dam-safety-critical applications from standard-tier products for routine thickening. Three-tier pricing structure across premium, standard, and economy levels reflects active-content thresholds, molecular-weight specifications, and after-sales technical support bundling. Cost compression in commodity xanthate collectors is intensifying because caustic-soda input volatility and Durban port congestion erode fixed-contract margins. Mid-tier mineral processors exhibit the highest price sensitivity due to spot purchasing patterns, while integrated majors like AngloGold Ashanti extract least-cost positioning through centralized regional warehousing.
Supply Chain Analysis
Durban port congestion and Dar es Salaam customs delays constitute chokepoints that concentrate import risk for specialty collectors and frothers routed from Asian manufacturing hubs. Supply concentrates in South Africa's Johannesburg-Pretoria industrial corridor, China's sulfuric acid and xanthate production zones, and India's caustic-soda manufacturing belt. Raw material dependencies draw from petroleum-derived organic intermediates, phosphate rock for phosphonate antiscalants, and acrylamide monomer for polyacrylamide synthesis. Single-source vulnerability runs through concentrated xanthate collector import corridors. Distribution runs through direct rail-to-mine bulk deliveries for flocculants and emulsions, with regional distributors holding inventory buffers for commodity solvents and pH modifiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Africa mining chemicals market functions as a platform-economics inflection where consolidated procurement through mining-house central warehouses is displacing site-level purchasing, with interoperability across unified logistics coordination becoming the decisive competitive variable.
For Market Incumbents: Secure rail-spine distribution capacity into Zambia's Copperbelt before port congestion premiums erode margin structures, and accelerate bio-based surfactant formulation R&D to preempt Scope 3 emissions compliance mandates. BASF SE and AECI Mining Chemicals must defend against specialty chemical entrants by locking in molecular-weight specification patents for high-performance flocculants.
For New Entrants and Emerging Players: REACH-equivalent chemical-registration fast-tracks in select African Economic Community zones open white-space positioning for polyacrylamide and xanthate categories where dossier preparation lags among incumbents. Target Ghana's Ashanti gold belt toll-treatment facilities, where spot purchasing patterns and freshwater scarcity intensify closed-loop chemical demand. A technical-service-heavy go-to-market angle bypasses volume-tier pricing disadvantages against integrated majors.
For Investors and Strategic Acquirers: Capital is best deployed toward regional formulators with captive manufacturing and direct rail links, as these assets compound procurement-rule shifts under the African Mining Vision's local-content mandates. Long-term viability hinges on 5-10 year hydrometallurgical expansion trajectories in the Copperbelt and tailings-reprocessing economics in South Africa's Bushveld Complex. Watch for dam-safety audit enforcement intensity as the inflection signal for geotechnical-monitoring reagent demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylamide Monomer Production | South African captive manufacturing secures polyacrylamide supply chain against import volatility. |
| Direct Rail-to-Mine Distribution Expansion | Copperbelt freight corridors bypass Durban congestion and compress working-capital cycles. |
| Bio-Based Surfactant Formulation Development | Plant-derived frother alternatives align with mining house Scope 3 emissions targets. |
| Long-term Supply Agreement with Copperbelt SX-EW Operators | Sulfuric acid and organic-diluent offtake locks in volume against oxide-ore processing expansion. |
| Joint Venture for Regional Formulation Facilities | African Mining Vision local-content mandates redirect procurement toward domestic manufacturing. |
Research Approach
A standing panel of mine site procurement managers, hydrometallurgical process engineers, tailings-facility compliance officers, and regional chemical distribution channel heads provided ongoing calibration across primary interview rounds. Secondary validation drew from South African Department of Mineral Resources and Energy regulatory filings, Zambia Environmental Management Agency licensing records, customs and trade data for sulfuric acid and xanthate imports, and SEC 10-K disclosures from listed mining chemical suppliers. Bottom-up reagent consumption modeling triangulated against top-down market sizing from mining production forecasts.
Consistency checks against external benchmarks validated volume and value outputs across the analysis window. The analytical framework modeled product type, application intensity, end-user procurement power, and technology pathway as segmentation dimensions. CAGRs were derived from reagent consumption intensity curves tied to ore-grade degradation trajectories and hydrometallurgical circuit expansion in the Copperbelt.
Decision-makers should treat outputs as directional under base assumptions of continued copper-cobalt demand expansion and stable regulatory enforcement trajectories; material deviation in commodity price cycles or licensing friction would warrant model refresh. Practitioners should keep alternative scenarios live as African Economic Community REACH-equivalent framework implementation timelines and local-content mandate enforcement intensity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Guanidine Carbonate Market
Chemicals
Global Wood Preservative Chemicals and Coatings Active Ingredients Market
Chemicals
Global Glycine Market
Chemicals
Acetic Ether Market
Chemicals
Hydrazine Market
Chemicals
Silicone Textile Softeners Market
Chemicals
Heptaldehyde Market
Chemicals
Malic Acid Market
Chemicals
Calcium Borate Market
Chemicals
Methyl P-Hydroxybenzoate Market
Chemicals
Schneider's Insect Medium Market
Chemicals
Malaysia Construction Chemicals Market
Chemicals
South Korea Methanol Market
Chemicals
Electronic Grade Hydrofluoric Acid Market
Chemicals
Anhydrous Hydrogen Fluoride Market
Chemicals
Carcinogenic Chemical Alternatives Market