
 Electro-Erosion Fluids Market | 2026-2036
Electro-Erosion Fluids Market Size, Share, and Industry Trends Forecast 2026-2036
Electro-Erosion Fluids Market Analytics
Ultra-low-odor synthetic-grade formulations is unwinding legacy oil-based consumption patterns across precision machining centers. ExxonMobil leverages its integrated base oil and additive supply chain to dominate high-specification synthetic production. TotalEnergies anchors European demand through specialized distribution partnerships with aerospace tier-one suppliers. Eastern Petroleum competes on cost-optimized oil-based blends for mid-tier tool manufacturers across South and Southeast Asia.
Electro-erosion fluids are dielectric liquids engineered with precise electrical resistivity between 10^4 and 10^6 ohm-cm, formulated to flush debris and stabilize spark gaps during electrical discharge machining of hardened tool steels and conductive ceramics. Oil-based formulations retain the largest installed-base footprint among product types, though synthetic variants command the fastest replacement rate as shops modernize filtration systems. Aerospace application demand leads absolute volume, while electronics segment growth concentrates in micro-hole drilling for connector and semiconductor tooling where biodegradable fluids face emerging specification trials.
EPA discharge guidelines and ECHA REACH substance restrictions are reshaping formulation chemistry toward lower-aromatic, higher-biodegradability basestocks across both North American and European supply chains. Japan's METI energy-efficiency standards for manufacturing processes indirectly elevate fluid thermal stability requirements in precision machining. Stakeholders must weigh synthetic conversion costs against tightening multi-jurisdictional environmental compliance timelines when planning capacity investments or supplier qualification programs.
Market Dynamics
REACH substance restrictions across Europe are forcing accelerated synthetic fluid conversions, while aerospace tier-one suppliers consolidate procurement around qualified high-performance formulations.
Growth Catalysts
- Swiss Precision Machining Corridors:Tool steel manufacturers in Geneva and Solothurn are expanding EDM capacity for medical implant tooling, creating concentrated demand for ultra-pure dielectric fluids with sub-ppm sulfur specifications.
- ECHA REACH Annex XVII:Restrictions on polycyclic aromatic hydrocarbons in metalworking fluids are compelling German automotive tool shops to replace legacy mineral oil formulations before compliance deadlines.
- Micro-Hole Drilling Technology:Semiconductor connector manufacturers in Japan require fluids with enhanced debris-flush rates for 50-micron diameter drilling applications in tungsten carbide.
Market Restraints
- Group III Base Oil Supply Concentration:Synthetic formulation feedstock availability tightens around integrated refiners in Singapore and the US Gulf Coast, creating input cost volatility for independent blenders.
- Biodegradability-Performance Tradeoff:Vegetable-derived ester fluids meeting OECD 301B standards exhibit inferior oxidative stability above 70°C, limiting adoption in high-speed wire EDM applications.
- Japan METI Energy Standards:Thermal efficiency mandates for manufacturing processes indirectly raise fluid stability requirements, extending qualification timelines for new synthetic entrants.
Strategic Opportunities
- Indian Tool Manufacturing Clusters:Pune and Bangalore precision component producers remain underpenetrated by synthetic formulations, presenting first-mover positioning for REACH-compliant suppliers.
- Closed-Loop Filtration Convergence:Integration of advanced membrane filtration with dielectric fluid systems enables extended fluid life cycles, creating bundled service-revenue models.
- EU Green Deal Procurement Mandates:Public aerospace and defense contracts increasingly specify bio-based content thresholds, favoring suppliers with certified renewable feedstock supply chains.
Industry Challenges
- Fluid Analysis Technician Shortage:Precision machining shops lack personnel trained in dielectric resistivity monitoring and particle contamination assessment, delaying synthetic conversion decisions.
- Multi-Jurisdictional Qualification Overlap:Aerospace suppliers must simultaneously satisfy Boeing BAC specifications, Airbus AIMS standards, and Safran process approvals, multiplying compliance documentation burdens.
- Legacy Filtration System Retrofit Costs:Oil-based fluid infrastructure requires separator upgrades and tank modifications to handle synthetic formulations with different specific gravities and foam characteristics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electro-Erosion Fluids Market |
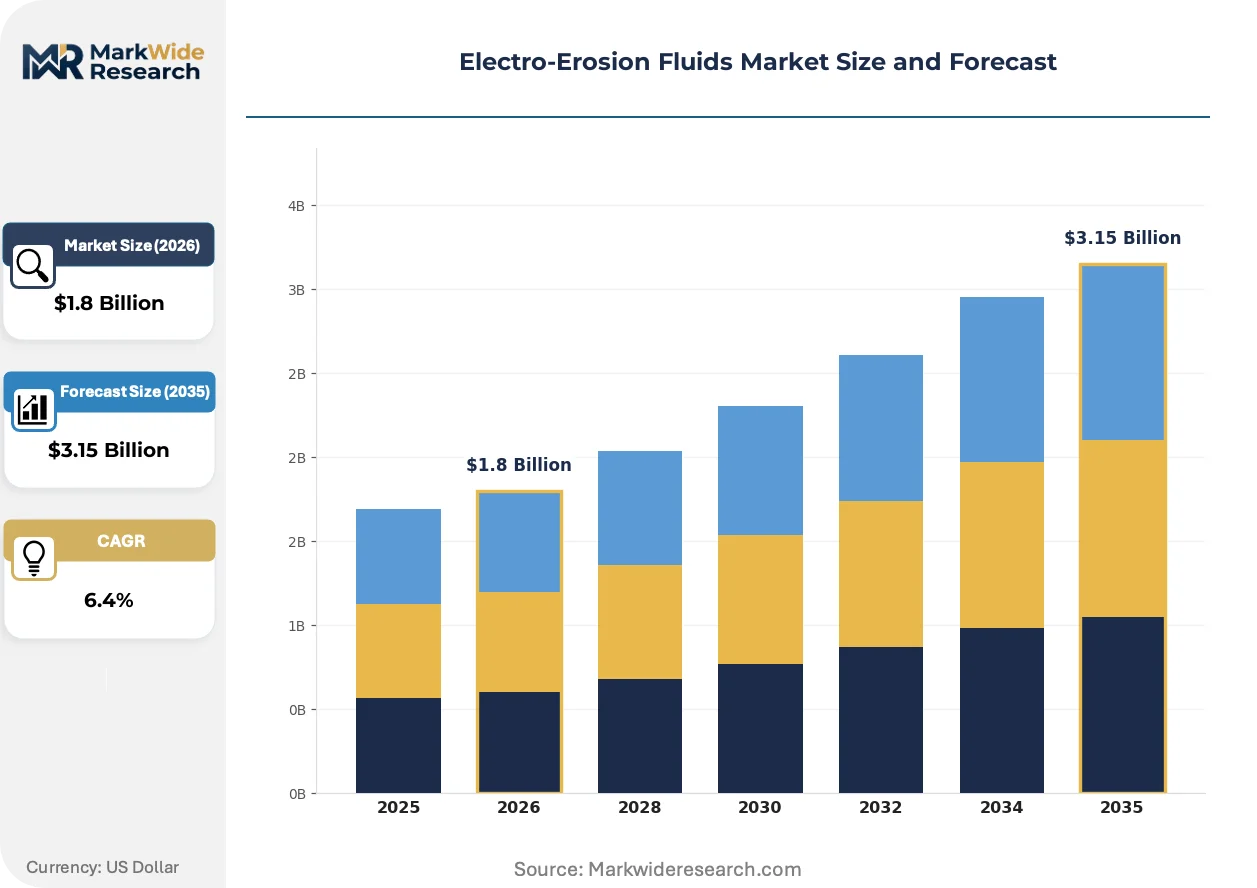
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-Soluble, Oil-Based, Synthetic, Biodegradable Application: Tool Manufacturing, Aerospace, Automotive, Electronics End User: Manufacturers, Research Institutions, Service Providers, OEMs Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | ExxonMobil Corporation, Shell, TotalEnergies, Chevron, BP, DNR Corporation, Eastern Petroleum, Gandhar Oil, Kocak Petroleum, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electro-Erosion Fluids Market Evolving Landscape
Synthetic dielectric chemistry is fragmenting into application-specific branches, while regulatory pressure and procurement consolidation reshape competitive requirements across precision manufacturing verticals.
Multi-additive synthetic formulations combining boron ester friction modifiers with hindered phenol antioxidants are bifurcating the product landscape. Swiss medical implant machinists are adopting these grades fastest, while general tool shops delay conversion due to capital constraints. This technology is compressing the viable market for conventional naphthenic mineral oils in high-specification applications.
EPA discharge guidelines for metalworking effluents are tightening permissible oil-in-water limits for facilities discharging to municipal treatment systems. Machine shop operators in Ohio and Michigan face capital decisions on wastewater pre-treatment equipment versus fluid formulation upgrades. The electronics segment, with its high-volume water-based wire EDM operations, is responding fastest through closed-loop system investments.
Consolidated procurement by aerospace tier-one suppliers is displacing fragmented distributor relationships across European supply chains. Safran and Rolls-Royce Power Systems now mandate direct supplier qualification for dielectric fluids used in turbine blade drilling operations. This concentration is most visible in southern Germany, where supplier reduction programs have halved approved fluid vendors since REACH implementation began.
Electro-Erosion Fluids Market Segmentation
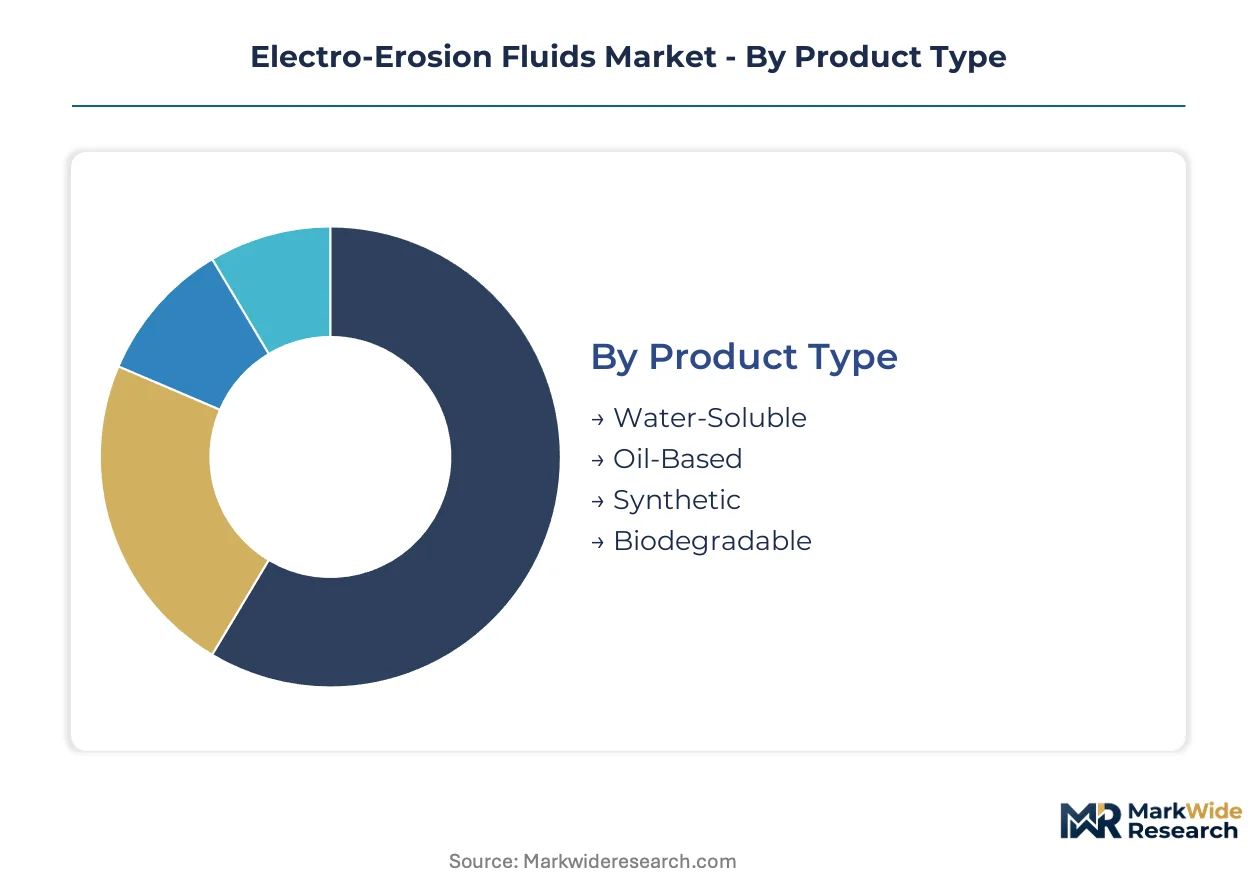
Electro-erosion fluid procurement patterns diverge sharply across product chemistries and end-use verticals, with aerospace qualification requirements and REACH compliance timelines creating divergent demand profiles. Understanding segment boundaries reveals where formulation investments concentrate versus where cost-optimized supply dominates.
Product Type:
Oil-based formulations anchor domestic consumption across established precision machining clusters, while synthetic grades drive export-led demand from REACH-regulated European supply chains.
- Oil-Based:Naphthenic mineral oil formulations with electrical resistivity calibrated between 10^4 and 10^5 ohm-cm retain dominance in legacy EDM installations across Japanese and Indian tool shops. German automotive suppliers face forced replacement timelines under ECHA REACH Annex XVII polycyclic aromatic hydrocarbon restrictions.
- Synthetic:Group III base oil formulations incorporating boron ester friction modifiers deliver thermal stability above 70°C for high-speed wire EDM applications. Swiss medical implant machinists in Geneva and Solothurn corridors specify ultra-pure grades with sub-ppm sulfur content for titanium drilling operations.
- Water-Soluble:Emulsified dielectric concentrates serve high-volume electronics manufacturing with simplified wastewater treatment requirements.
- Biodegradable:Vegetable-derived ester fluids meeting OECD 301B standards encounter adoption limits due to oxidative instability in sustained high-temperature operations.
Oil-based formulations hold the largest share; momentum sits with synthetic grades as multi-jurisdictional environmental compliance tightens.
Application:
Cost tier stratification separates aerospace premium qualification programs from electronics volume procurement and automotive mid-tier specification.
- Aerospace:Turbine blade drilling operations demand dielectric fluids qualified to Boeing BAC, Airbus AIMS, and Safran process standards simultaneously. Southern German suppliers have halved approved vendor lists since REACH implementation, consolidating procurement around direct manufacturer relationships.
- Electronics:Micro-hole drilling for semiconductor connectors requires enhanced debris-flush rates in 50-micron diameter tungsten carbide applications. Japanese manufacturers lead closed-loop system adoption to address EPA discharge guidelines for oil-in-water effluent limits.
- Tool Manufacturing:Hardened tool steel EDM in Swiss and German corridors specifies ultra-pure formulations for medical implant tooling.
- Automotive:Powertrain component machining balances performance requirements against capital constraints in legacy facility retrofits.
Aerospace commands premium pricing tiers; electronics exhibits the steepest expansion trajectory through micro-machining technology diffusion.
End User:
Customer type determines specification authority, with OEMs driving formulation standards that cascade through manufacturer and service provider tiers.
- Manufacturers:Precision machining shops in Pune and Bangalore clusters remain underpenetrated by synthetic formulations, presenting positioning opportunities for REACH-compliant suppliers.
- OEMs:Original equipment manufacturers specify dielectric fluids for captive EDM operations and bundled equipment-fluid supply contracts.
- Service Providers:Job shops face technician shortages in dielectric resistivity monitoring and particle contamination assessment, delaying synthetic conversion decisions.
- Research Institutions:Academic and national laboratory users trial biodegradable formulations for emerging specification development.
Manufacturers represent the volume anchor; OEMs concentrate specification control through consolidated procurement mandates.
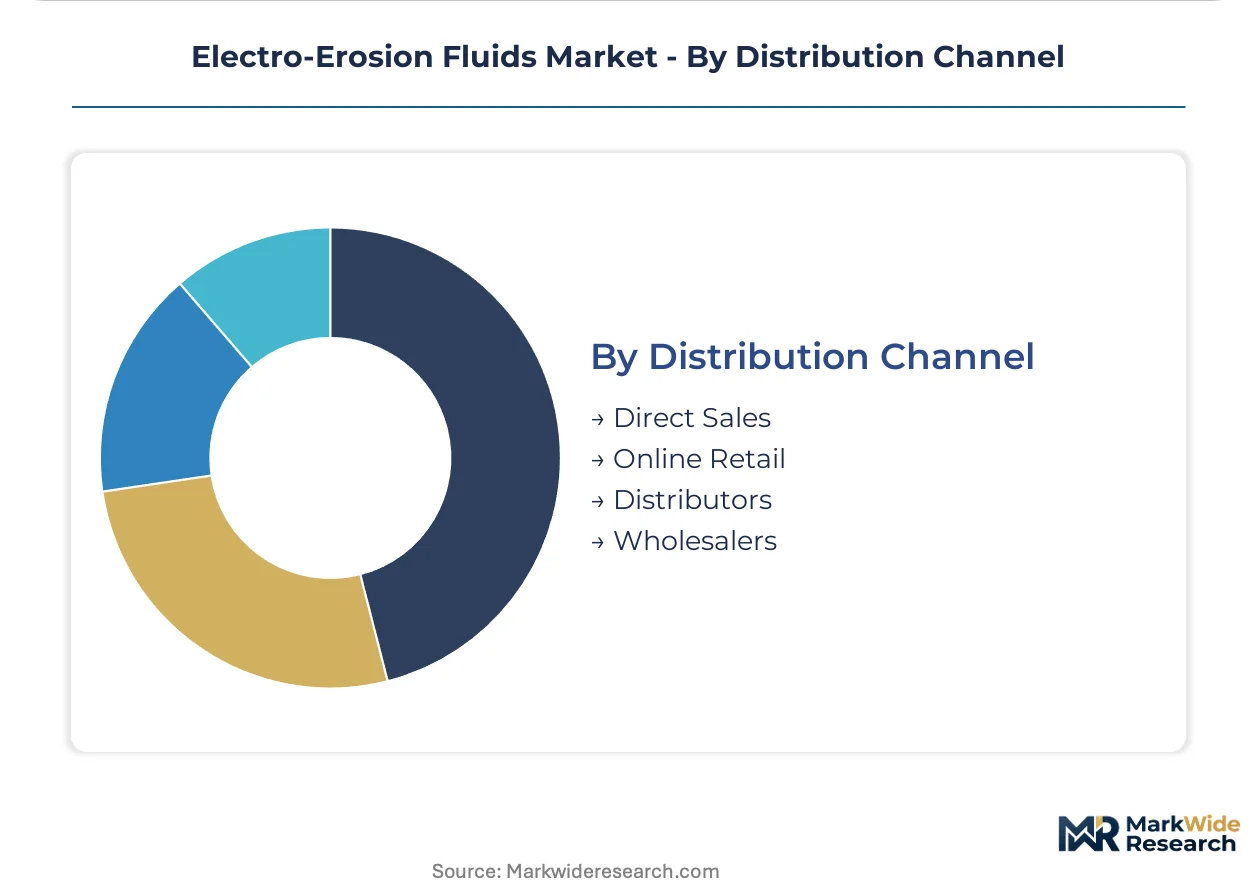
Distribution Channel:
Supply concentration favors integrated producers with captive base oil supply, while independent blenders compete through distributor relationships in cost-sensitive segments.
- Direct Sales:Aerospace tier-one suppliers mandate direct supplier qualification, displacing fragmented distributor relationships across European supply chains.
- Distributors:Specialized distribution partnerships anchor synthetic formulation access for mid-tier tool manufacturers lacking technical specification expertise.
- Online Retail:E-commerce channels serve small-batch replacement orders and emergency supply for job shops with limited inventory capacity.
- Wholesalers:Bulk supply aggregation supports high-volume electronics manufacturers with standardized water-soluble formulations.
Direct sales capture specification-critical segments; distributors retain relevance in geographically fragmented mid-tier markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-led synthetic formulation demand from REACH-regulated European supply chains contrasts with import-dependent consumption across South and Southeast Asian tool manufacturing clusters. Germany and Switzerland run structural trade surpluses in high-specification dielectric fluids. The United States and Japan balance domestic production with selective imports for aerospace qualification programs.
Germany
Automotive tool shops in Stuttgart and Munich corridors face forced replacement timelines for legacy mineral oil formulations under ECHA REACH Annex XVII polycyclic aromatic hydrocarbon restrictions. Southern German aerospace suppliers have halved approved fluid vendor lists since REACH implementation began. Turbine blade drilling operations in Bavaria now mandate direct supplier qualification bypassing traditional distribution channels.
Switzerland
Medical implant machinists in Geneva and Solothurn corridors specify ultra-pure synthetic grades with sub-ppm sulfur content for titanium drilling operations. Swissmedic maintains stringent process validation requirements that extend qualification timelines for new synthetic entrants. Precision machining capacity expansion in the Jura Arc creates concentrated demand for dielectric fluids with enhanced thermal stability above 70°C.
Japan
Semiconductor connector manufacturers require fluids with enhanced debris-flush rates for 50-micron diameter drilling applications in tungsten carbide. METI energy-efficiency standards for manufacturing processes indirectly elevate fluid thermal stability requirements in precision machining. Nagoya and Osaka industrial clusters lead closed-loop system adoption to address operational cost pressures.
United States
Machine shop operators in Ohio and Michigan face capital decisions on wastewater pre-treatment equipment versus fluid formulation upgrades under tightening EPA discharge guidelines. Aerospace tier-one suppliers consolidate procurement around qualified high-performance formulations for turbine component machining. The US Gulf Coast anchors Group III base oil supply concentration affecting synthetic formulation feedstock availability.
India
Pune and Bangalore precision component producers remain underpenetrated by synthetic formulations, presenting first-mover positioning opportunities for REACH-compliant suppliers. BIS standards for metalworking fluids create compliance documentation burdens for mid-tier tool manufacturers. Cost-optimized oil-based blends dominate domestic consumption across established machining clusters in western and southern states.
Electro-Erosion Fluids Market Competitive Landscape
Concentration sits with integrated petroleum majors possessing captive base oil supply chains and additive formulation capabilities. Three to four multinational energy companies control the high-specification synthetic segment through direct aerospace qualification programs. Strategic archetypes include integrated refiners with backward control over Group III feedstocks, regional blenders competing on cost-optimized oil-based formulations, and specialized distributors anchoring mid-tier access. Capacity expansion and portfolio diversification toward biodegradable ester chemistry represent the dominant competitive vectors.
Within the integrated petroleum major tier, ExxonMobil Corporation, TotalEnergies, and Shell exemplify archetypes defined by supply chain control and specification authority. ExxonMobil occupies a position reflecting integrated base oil and additive supply chain dominance. TotalEnergies anchors European demand positioning through specialized distribution partnerships. Shell represents scale-driven supply security for high-volume electronics manufacturing segments. Eastern Petroleum and Gandhar Oil sit within the regional blender archetype competing on cost-optimized formulations for price-sensitive South and Southeast Asian markets.
| Leading Market Players |
|---|
| ExxonMobil Corporation |
| Shell |
| TotalEnergies |
| Chevron |
| BP |
| DNR Corporation |
| Eastern Petroleum |
| Gandhar Oil |
| Kocak Petroleum |
| Others |
Value Network & Pricing Analysis
Synthetic-grade formulation substitution for legacy naphthenic mineral oils simultaneously redraws supply geography toward integrated Group III refiners in Singapore and the US Gulf Coast while compressing price premiums as REACH compliance deadlines force accelerated buyer conversion. Aerospace tier-one supplier consolidation around direct manufacturer relationships is amplifying pricing power asymmetries across European precision machining corridors.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels differentiated by sulfur purity grade and aerospace certification tier. Price differentiation stems from REACH compliance documentation burdens and volume scale commitments in long-term offtake contracts. Cost compression in mid-tier synthetic grades is intensifying because independent blenders face feedstock volatility from concentrated Group III base oil supply. Job shops and small-batch manufacturers exhibit highest price sensitivity, while Swiss medical implant machinists and aerospace tier-one suppliers demonstrate lowest sensitivity due to qualification lock-in effects.
Supply Chain Analysis
Singapore and the US Gulf Coast anchor Group III base oil production feeding synthetic formulation capacity, while Germany and Switzerland concentrate high-specification blending for aerospace qualification programs. Formulation chemistry draws from hindered phenol antioxidants, boron ester friction modifiers, and ultra-low-sulfur base oil feedstocks. Single-source vulnerability concentrates around integrated petroleum majors controlling captive additive supply chains. Distribution runs through direct sales channels for specification-critical aerospace segments and specialized distributor partnerships for mid-tier tool manufacturers lacking technical expertise.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated aerospace tier-one suppliers that have halved approved vendor lists since REACH implementation began, fragmenting pricing leverage among independent blenders and regional distributors.
For Market Incumbents: Consolidate specification authority through accelerated Boeing BAC and Airbus AIMS qualification investments before compliance deadlines harden vendor lock-in. Defend against emerging biodegradable ester entrants by anching distribution partnerships with Swiss medical implant machinists and German automotive tool shops facing forced replacement timelines. Prioritize backward integration into captive Group III base oil supply to insulate margin structures from Singapore and US Gulf Coast feedstock volatility. For New Entrants and Emerging Players: ECHA REACH Annex XVII fast-track certification creates positioning pathways into underpenetrated Indian precision machining clusters in Pune and Bangalore where cost-optimized oil-based blends still dominate. Target closed-loop filtration system bundling as a service-revenue wedge into electronics manufacturing segments responding to EPA discharge guidelines. Pursue white-space capture through biodegradable ester formulations meeting OECD 301B standards for EU Green Deal procurement mandates in public aerospace and defense contracts. For Investors and Strategic Acquirers: The market sits at a synthetic conversion acceleration phase that favors integrated petroleum majors with captive base oil and additive supply chains. Long-term viability over the next decade hinges on regulatory compliance depth rather than cost optimization alone. Acquisition focus should center on regional blenders possessing established aerospace qualification relationships. The signal to watch is ECHA REACH enforcement intensity against polycyclic aromatic hydrocarbon violations in German automotive supply chains.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Group III Base Oil Supply | Captive feedstock access insulates synthetic formulation margins from Singapore refinery concentration risk. |
| Aerospace Direct Supplier Qualification | Boeing BAC and Airbus AIMS certification locks in premium pricing tiers with tier-one turbine blade manufacturers. |
| Closed-Loop Filtration System Bundling | Service-revenue models extend fluid life cycles for Japanese semiconductor connector manufacturers facing METI efficiency standards. |
| Biodegradable Ester Formulation Development | OECD 301B-compliant chemistry addresses EU Green Deal procurement mandates in public aerospace contracts. |
| Indian Market Synthetic Conversion Partnerships | First-mover positioning in Pune and Bangalore clusters captures REACH-compliant supplier consolidation opportunities. |
Research Methodology
Cross-validation between primary interviews with EDM plant managers, aerospace procurement leads, dielectric fluid technical directors, and specialized distribution channel partners anchors the qualitative findings. Secondary validation draws from customs and trade data for electro-erosion fluid shipments, ECHA REACH substance restriction filings, SEC 10-K disclosures from integrated petroleum majors, and Swissmedic process validation records. Bottom-up demand modeling triangulates against top-down supply capacity assessments across Group III base oil production hubs.
Sensitivity analysis across the projection horizon tests forecast robustness against regulatory enforcement intensity variation and synthetic conversion pace assumptions. Segmentation dimensions include product chemistry tier, application vertical, end-user specification authority, and regional regulatory cluster. CAGRs derive from installed base replacement rate modeling and aerospace capacity expansion pipelines. Industry-specific inputs incorporate EDM machine tool shipment data and REACH compliance deadline phasing.
Underlying assumptions cover ECHA enforcement consistency and aerospace qualification timeline stability, with deviation risk concentrated in biodegradable ester performance breakthroughs and METI energy standard revisions. Recalibration cycles align with material shifts in REACH Annex XVII substance restriction expansions and EPA discharge guideline tightening.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Synthetic Gypsum Market
Industrial Chemicals
Mining Explosives Market
Industrial Chemicals
Biochemicals Control Market
Industrial Chemicals
General Industrial Oils Market
Industrial Chemicals
Global Dodecanedioic Acid Market
Industrial Chemicals
Powder Coating Guns Market
Industrial Chemicals
Proline Market
Industrial Chemicals
Molecular Sieves Market
Industrial Chemicals
Europe Hydrocarbon Refrigerants Market
Industrial Chemicals
Global Antifreeze/Coolant Market
Industrial Chemicals
Fischer-Tropsch (FT) Wax Market
Industrial Chemicals
Sulphur Recovery Technologies Market
Industrial Chemicals
Slimicides Market
Industrial Chemicals
Hydrogen Sulphide Market
Industrial Chemicals
Europe Antifreeze Coolant Market
Industrial Chemicals
India Precipitated Silica Market