
 Nitrogen Trifluoride (NF3) Market | 2026-2036
Nitrogen Trifluoride (NF3) Market Size, Share, and Industry Trends Forecast 2026-2036
Nitrogen Trifluoride (NF3) Market Analysis
Electronic-grade NF3 purity specifications above 99.99% is redrawing procurement standards across semiconductor fabrication. SK Materials leverages captive fluorine chemistry to sustain cost advantages in South Korea. Linde plc anchors European supply through on-site gas generation contracts with leading chipmakers. Foosung Co. Ltd dominates merchant supply to Chinese display panel manufacturers through specialized purification systems.
Nitrogen trifluoride is a colorless, non-flammable gas with a molar mass of 71 g/mol, manufactured primarily via electrolysis of ammonium fluoride-hydrogen fluoride melts for use as a fluorine source in plasma etching and chamber cleaning. The semiconductors product type occupies the largest value share due to relentless node shrinkage requiring more frequent chamber cleans. Chemical vapor deposition applications within the application dimension are expanding fastest as atomic layer deposition tools proliferate for 3D NAND fabrication. Direct sales channels control the distribution landscape because bulk NF3 requires cryogenic transport infrastructure and proximity storage.
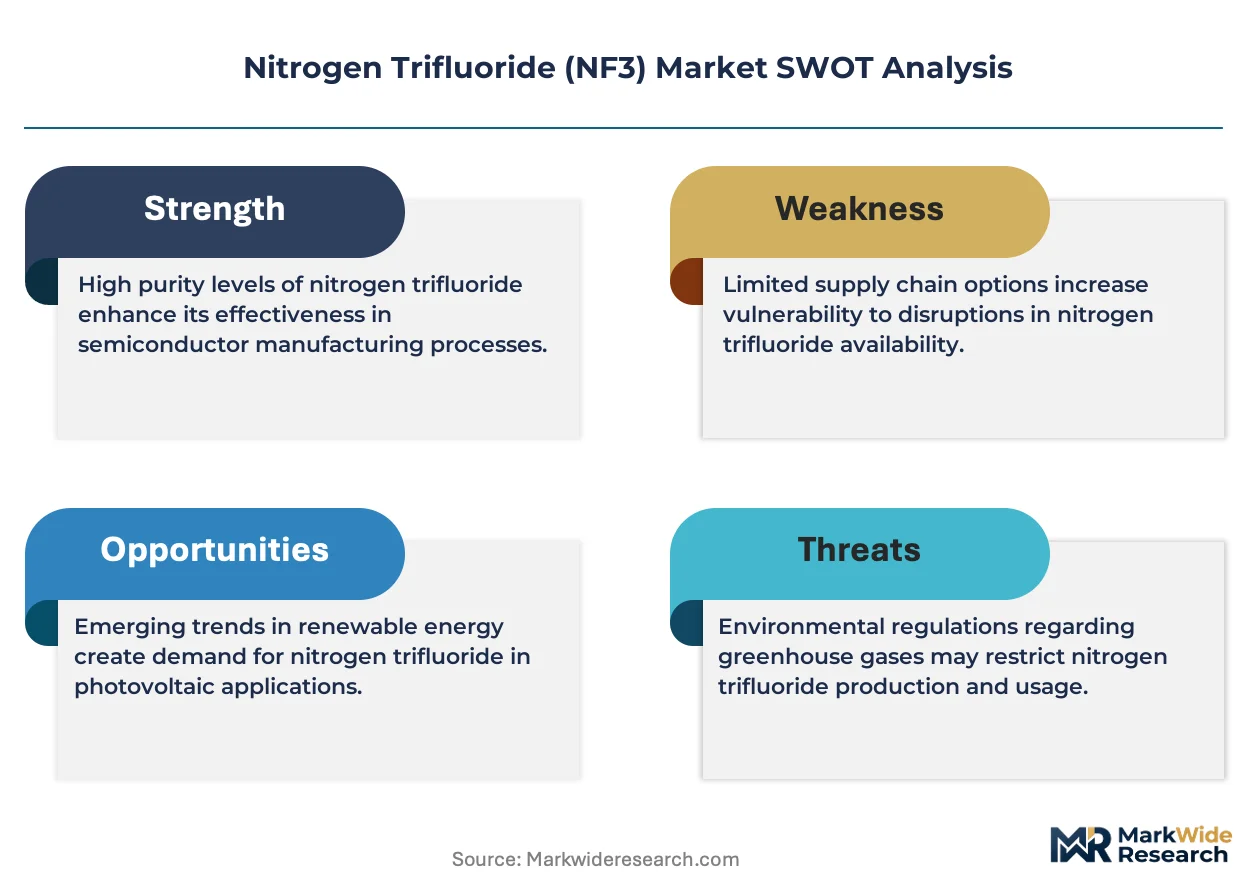
EPA fluorinated gas reporting mandates shape US market access by requiring granular emissions disclosure from electronics manufacturers. The EU F-Gas Regulation and REACH jointly restrict NF3 venting, compelling abatement technology co-investment. China's MEE enforces similar discharge limits under national carbon-neutrality frameworks. Stakeholders must monitor regulatory divergence between jurisdictions to optimize abatement capital deployment and avoid stranded supply commitments.
Market Dynamics
Advanced node migration below 3nm is intensifying chamber clean frequency requirements, compressing NF3 consumption cycles while simultaneously elevating purity thresholds. This structural tension between volume pull and specification escalation defines current market mechanics.
Growth Catalysts
- EU F-Gas Regulation Phase-Down:Mandated fluorinated gas emission reductions are accelerating abatement technology deployment, expanding serviceable equipment demand and captive NF3 generation contracts.
- Plasma Etching Intensification:Gate-all-around transistor architectures require more aggressive fluorine-based cleaning protocols, directly lifting NF3 throughput per wafer.
- Hsinchu-Pyeongtaek Corridor Concentration:Foundry clustering in Taiwan and South Korea creates localized demand density that justifies dedicated on-site gas generation infrastructure.
Market Restraints
- Fluorine Feedstock Volatility:Ammonium fluoride and hydrogen fluoride input costs fluctuate with phosphate fertilizer market dynamics, squeezing merchant supplier margins unpredictably.
- East Asian Supply Concentration:Overreliance on Korean and Taiwanese production clusters exposes buyers to concentrated geopolitical risk and single-source dependency.
- Carbon Tetrafluoride Substitution:Legacy C4F8 etchants retain cost advantages in mature node fabrication, limiting NF3 penetration in trailing-edge capacity expansions.
Strategic Opportunities
- Indian Semiconductor Mission Incentives:PLI scheme subsidies for domestic fab construction create first-mover advantage for NF3 suppliers establishing local abatement-integrated generation.
- Atomic Layer Deposition Tool Proliferation:ALD chamber cleaning protocols favor NF3 over alternative fluorine sources, opening incremental demand in 3D NAND manufacturing.
- Carbon-Neutral Certification Premiums:Scope 3 emissions accounting requirements are differentiating low-carbon-intensity NF3 production, enabling price stratification by environmental credential.
Industry Challenges
- Cryogenic Logistics Expertise Scarcity:Bulk NF3 transport requires specialized -129°C handling certification that exceeds standard industrial gas operator training.
- Multi-Jurisdiction Abatement Compliance:Divergent EPA, EU F-Gas, and China MEE reporting standards force redundant monitoring system investments without harmonized protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nitrogen Trifluoride (NF3) Market |
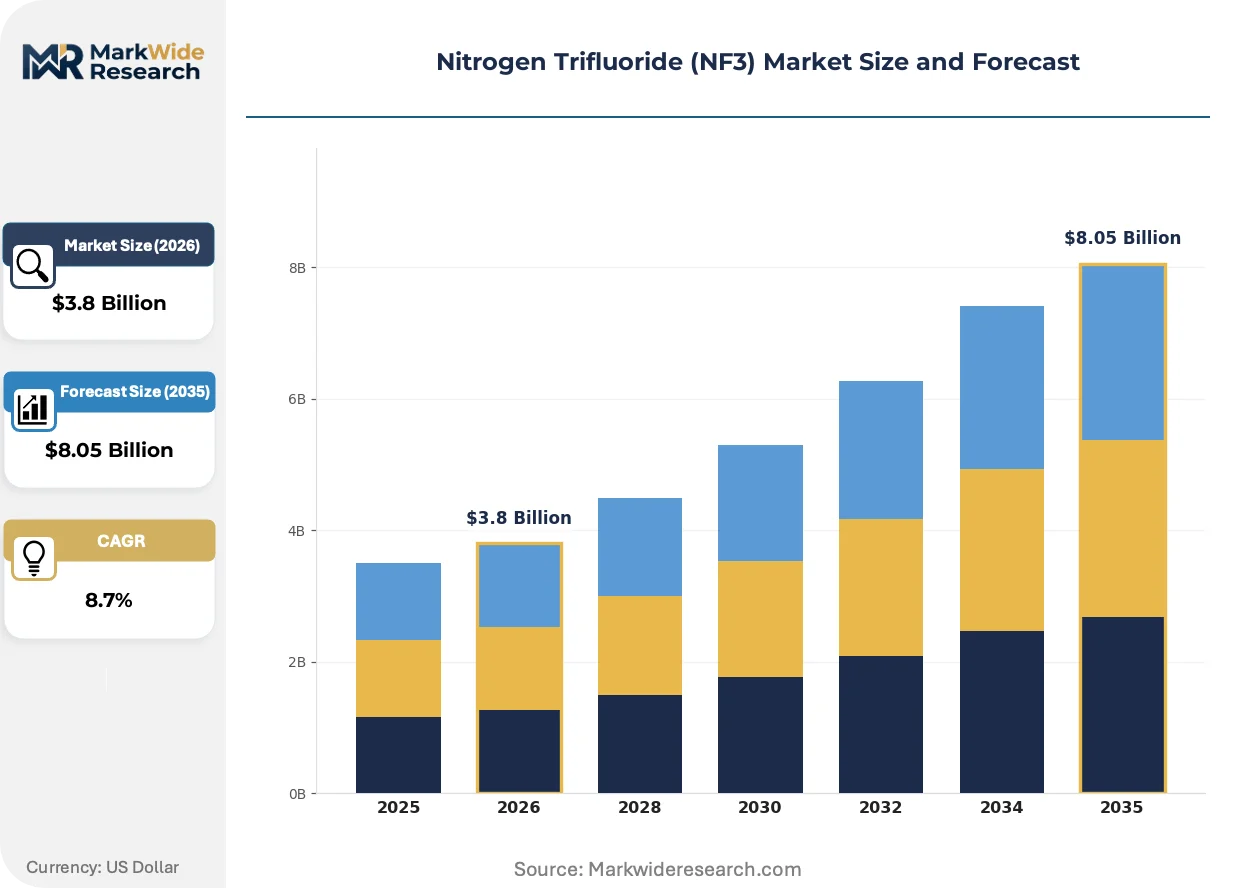
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Semiconductors, Solar Cells, LCD Displays, Cleaning Agents Application: Etching, Chemical Vapor Deposition, Surface Treatment, Electronics Manufacturing End User: Electronics, Aerospace, Automotive, Industrial Distribution Channel: Direct Sales, Distributors, Online Sales, Retail |
| Companies Covered | Foosung Co. Ltd, Linde plc, SK Materials, OCI Materials, Air Products & Chemicals, Kanto Denka Kogyo Co. Ltd, Hyosung, Showa Denko K.K., Central Glass Co. Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nitrogen Trifluoride (NF3) Market Emerging Trajectories
Plasma chemistry optimization and regulatory compliance architectures are converging to redefine NF3 value capture. Technology suppliers and gas producers are co-developing integrated abatement-generation systems that lock in long-term offtake arrangements.
Remote plasma cleaning systems are decomposing NF3 at point-of-use rather than venting unreacted fluorine, enabling semiconductor fabs to meet tightening emission limits without sacrificing throughput. TSMC and Samsung Foundry are deploying these systems at 5nm and 3nm lines. This decomposition architecture is compressing merchant gas demand while expanding abatement equipment and service revenue pools.
REACH and EU F-Gas Regulation amendments are mandating mandatory leak detection and repair programs for fluorinated gas handling equipment above threshold quantities. Industrial consequence includes mandatory infrared camera inspection protocols and quarterly reporting to national competent authorities. Display panel manufacturers in the Netherlands and Germany are responding by consolidating NF3 procurement through Linde's on-site generation contracts rather than merchant supply.
Direct long-term supply agreements are displacing spot market transactions as fabs seek price predictability amid volatility. Bulk consumers in South Korea are negotiating 7-10 year take-or-pay contracts with abatement co-investment clauses. This contracting pattern is most visible in Pyeongtaek's semiconductor cluster where SK Hynix and Samsung have locked in dedicated NF3 supply through 2032.
Nitrogen Trifluoride (NF3) Market Segmentation
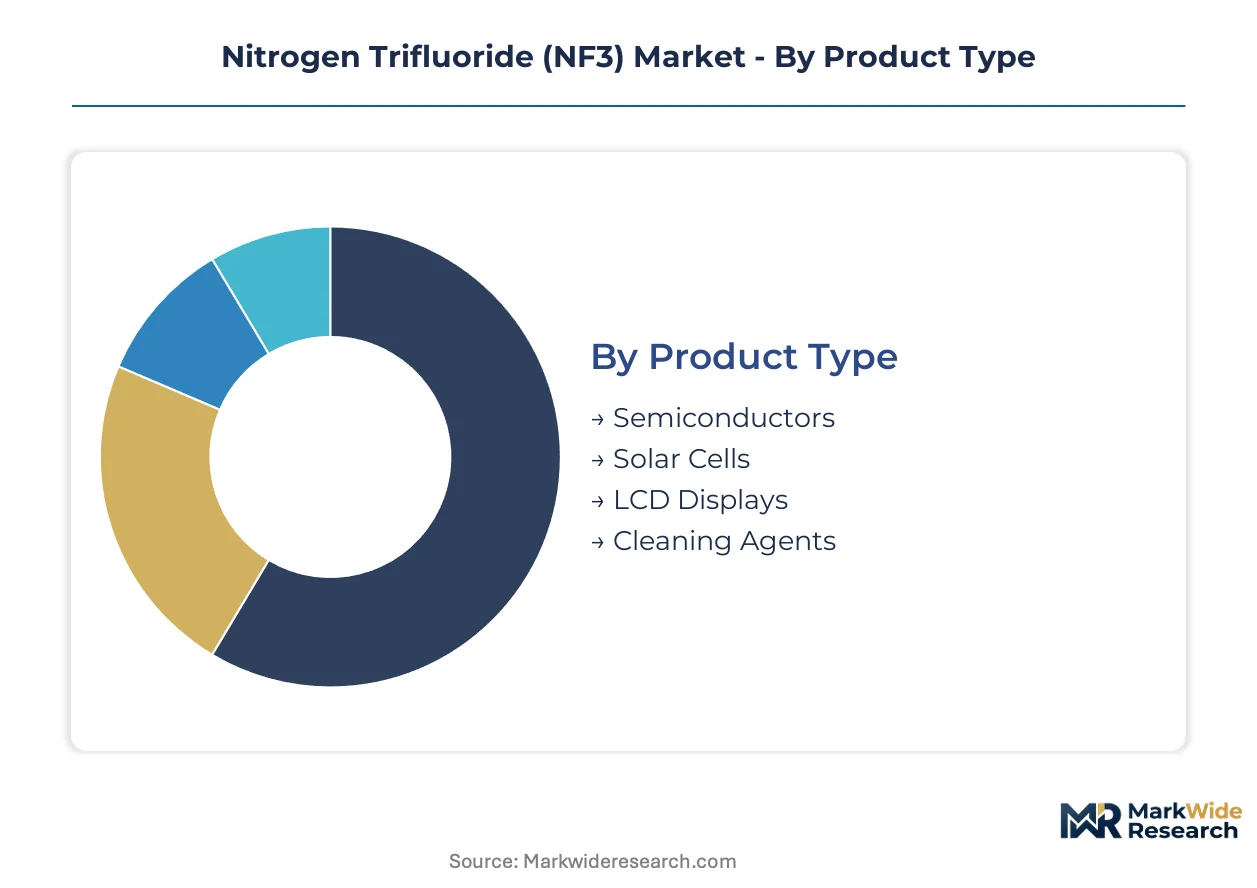
NF3 procurement patterns diverge sharply across end-use applications, with purity specifications and volume requirements creating distinct margin architectures. Understanding where value concentrates within each dimension enables suppliers to prioritize R&D investment and capacity allocation.
Product Type:
Margin pools concentrate in electronic-grade segments where 99.99%+ purity commands substantial premiums over industrial grades.
- Semiconductors:Electronic-grade NF3 with sub-ppm impurity tolerances dominates wafer fabrication for logic and memory chips. Foundries in Taiwan and South Korea absorb over half of global high-purity output, driven by relentless node shrinkage below 3nm that demands more aggressive chamber cleaning protocols.
- LCD Displays:TFT-LCD manufacturing requires mid-tier purity specifications for thin-film transistor etching. Chinese panel manufacturers in Shenzhen and Hefei represent the primary demand concentration, though OLED transition is compressing long-term volume trajectories.
- Solar Cells:Photovoltaic cell manufacturing utilizes NF3 for silicon wafer surface treatment and edge isolation. Passivated emitter and rear contact (PERC) cell expansion in Southeast Asia sustains steady offtake despite lower purity thresholds than semiconductor applications.
- Cleaning Agents:Industrial-grade NF3 serves specialized degreasing and surface preparation outside electronics. Chemical processing facilities in Germany and Japan represent concentrated demand for this lower-margin segment.
The dominant share belongs to Semiconductors, while Solar Cells is closing the gap fastest.
Application:
Volume throughput varies dramatically by process step, with chamber cleaning cycles consuming multiples of etching applications per wafer pass.
- Etching:Plasma etching of silicon dioxide and silicon nitride layers requires precise fluorine radical delivery. Gate-all-around transistor architectures at Samsung Foundry and TSMC are intensifying etch complexity, extending NF3 residence time in process chambers.
- Chemical Vapor Deposition:ALD and CVD chamber cleaning prevents cross-contamination between deposition cycles. 3D NAND fabrication with 200+ layer stacks is proliferating ALD tool counts, expanding point-of-use NF3 consumption faster than any other application.
- Surface Treatment:Silicon wafer surface activation and contamination removal precedes critical process steps. Solar cell manufacturers deploy this application for emitter diffusion preparation, though with less frequency than semiconductor fabs.
- Electronics Manufacturing:Broad category encompassing PCB cleaning and component surface preparation. Contract manufacturers in Vietnam and Mexico utilize NF3 for high-reliability aerospace and automotive electronics.
Etching retains the largest volume footprint, though Chemical Vapor Deposition is expanding most quickly as memory fabrication scales vertically.
End User:
Customer sophistication and contract structures separate premium electronics buyers from price-sensitive industrial purchasers.
- Electronics:Integrated device manufacturers and pure-play foundries negotiate long-term take-or-pay agreements with abatement co-investment clauses. Direct sales channels with on-site generation dominate, locking in supply security for multi-billion dollar fab investments.
- Aerospace:Satellite and avionics component manufacturers require NF3 for specialized coating removal and surface preparation. Lower volumes than electronics, but stringent traceability requirements support pricing premiums.
- Automotive:Power semiconductor and sensor fabrication for electric vehicles is emerging as a demand pocket. Infineon and STMicroelectronics are expanding silicon carbide capacity, incorporating NF3 into MOSFET manufacturing flows.
- Industrial:General chemical processing and metal treatment applications. Merchant gas supply through distributors predominates, with spot market pricing exposure and minimal service attachment.
Electronics commands the dominant revenue share, while Automotive is gaining share fastest on electrification-driven semiconductor content expansion.
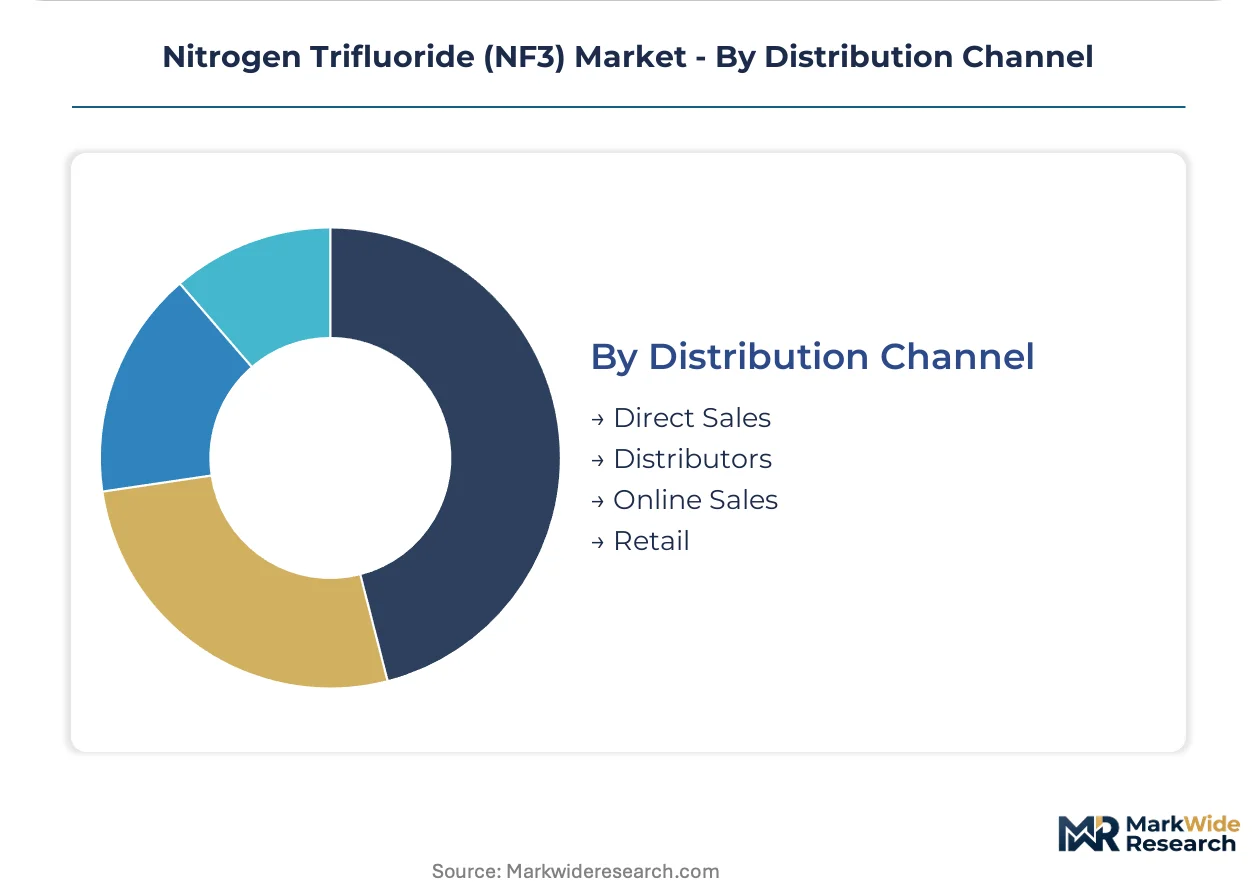
Distribution Channel:
Logistics complexity and safety requirements favor direct relationships for bulk consumers, fragmenting only at the long tail.
- Direct Sales:On-site gas generation and bulk liquid delivery via cryogenic transport infrastructure. SK Materials and Linde plc anchor this channel with dedicated pipelines to major fab clusters.
- Distributors:Regional gas specialists handling cylinder pack and small bulk quantities. Serve secondary electronics manufacturers and research institutions lacking volume for direct supply.
- Online Sales:Digital procurement platforms for specialty gas catalog ordering. Limited to standard cylinder sizes and industrial grades where specification variability is minimal.
- Retail:Minimal presence given NF3 hazardous material classification and transport restrictions. Laboratory supply houses in Japan represent the only meaningful retail footprint.
Direct Sales holds the dominant share, while Distributors are closing the gap fastest as mid-tier electronics manufacturing disperses geographically.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NF3 generation capacity clusters heavily in East Asian electronics manufacturing corridors, with South Korean and Taiwanese suppliers commanding dominant positions in high-purity output. This geographic concentration creates supply vulnerability for European and North American semiconductor fabs seeking qualified alternative sources.
South Korea
Advanced logic and memory fabrication at Samsung Foundry and SK Hynix drives relentless NF3 consumption for sub-3nm chamber cleaning cycles. The Ministry of Environment enforces fluorinated gas discharge limits under national carbon neutrality frameworks, compelling abatement co-investment. Pyeongtaek's semiconductor cluster anchors captive gas generation infrastructure with dedicated pipeline networks.
Taiwan
TSMC's dominance in contract chip manufacturing generates concentrated demand for electronic-grade NF3 with sub-ppm impurity tolerances. The Environmental Protection Administration mandates granular emissions reporting from electronics manufacturers under greenhouse gas inventory protocols. Hsinchu Science Park functions as the primary demand node, with suppliers locating generation assets within 50 kilometers of fab gates.
United States
Intel's domestic capacity expansion and emerging foundry investments by Samsung and TSMC in Arizona are reconstructing NF3 demand geography. EPA fluorinated gas reporting mandates shape market access through granular emissions disclosure requirements. The Southwest semiconductor corridor spanning Phoenix and Austin is attracting on-site gas generation investments from industrial gas majors.
China
Display panel manufacturing in Shenzhen and Hefei sustains merchant NF3 demand despite OLED transition pressures on long-term LCD volumes. The Ministry of Ecology and Environment enforces discharge limits under dual carbon goals, mirroring European regulatory stringency. Yangtze River Delta electronics clusters are consolidating procurement through localized purification and distribution networks.
Germany
Infineon and Bosch semiconductor operations require NF3 for power device and sensor fabrication serving automotive electrification. REACH and EU F-Gas Regulation jointly restrict NF3 venting, mandating infrared leak detection and quarterly reporting to competent authorities. Dresden's Silicon Saxony cluster represents the primary Central European demand concentration with dedicated abatement-integrated supply arrangements.
Nitrogen Trifluoride (NF3) Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Captive fluorine chemistry specialists leverage integrated ammonium fluoride supply chains to sustain margin advantages in high-volume markets. Merchant gas majors compete through on-site generation contracts and cryogenic logistics infrastructure. The dominant competitive moves involve abatement technology co-development partnerships and long-term take-or-pay contracting with foundry customers.
Among Korean suppliers, SK Materials and Hyosung exemplify the captive chemistry archetype, while Linde plc anchors the on-site generation model for European and North American fabs. Foosung Co. Ltd occupies a specialized position in merchant supply to Chinese display manufacturers. These three players represent distinct strategic postures: backward-integrated feedstock control, integrated abatement-service bundling, and regional purification specialization respectively.
| Leading Market Players |
|---|
| Foosung Co. Ltd |
| Linde plc |
| SK Materials |
| OCI Materials |
| Air Products & Chemicals |
| Kanto Denka Kogyo Co. Ltd |
| Hyosung |
| Showa Denko K.K. |
| Central Glass Co. Ltd |
| Others |
Supply Flow & Price Mechanics
Ninety-day inventory cycles for electronic-grade NF3 concentrate pricing power with backward-integrated Korean suppliers while compressing margins for merchant distributors dependent on spot ammonium fluoride procurement. This lead-time asymmetry between captive fluorine chemistry and external feedstock sourcing directly shapes contract negotiation leverage across the Hsinchu-Pyeongtaek corridor.
Pricing Analysis
EU F-Gas Regulation dictates the pricing tier structure across the NF3 market, separating abatement-integrated long-term contracts from merchant spot transactions. Three-tier pricing structure across premium electronic-grade, standard industrial-grade, and economy cleaning-agent levels reflects certification stringency and purity thresholds. Cost compression in standard grades is intensifying because Chinese display panel manufacturers are consolidating procurement through localized networks. Merchant distributors serving research institutions and secondary electronics manufacturers exhibit the highest price sensitivity, while foundries in Taiwan and South Korea prioritize supply security over unit economics.
Supply Chain Analysis
Taiwan and South Korea anchor wafer fabrication demand, drawing from concentrated ammonium fluoride and hydrogen fluoride feedstock networks in East Asian phosphate fertilizer corridors. Bulk NF3 distribution runs through cryogenic transport infrastructure requiring specialized -129°C handling certification, limiting qualified logistics providers. Single-source vulnerability concentrates in Korean fluorine chemistry supply chains, where SK Materials and Hyosung control captive production. Direct on-site generation contracts with abatement co-investment clauses dominate downstream relationships, displacing traditional merchant gas distribution for high-volume consumers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Semiconductor capital expenditure cycles position the NF3 market for recovery, with advanced node migration below 3nm driving chamber clean frequency expansion regardless of near-term foundry utilization rates.
For Market Incumbents: Fortify captive fluorine chemistry advantages through ammonium fluoride supply chain control and abatement technology co-development partnerships. Carbon tetrafluoride substitution in mature node fabrication threatens volume retention in trailing-edge segments, necessitating certification investment for EU F-Gas Regulation compliance. Capacity addition in the Indian semiconductor corridor offers geographic diversification against East Asian concentration risk. For New Entrants and Emerging Players: Anchor in the Indian Semiconductor Mission incentive zone, where PLI scheme subsidies for domestic fab construction create first-mover advantage for abatement-integrated generation assets. Atomic layer deposition tool proliferation in 3D NAND manufacturing represents the most penetrable application segment, with NF3 favorability over alternative fluorine sources. Joint venture structures with established cryogenic logistics operators accelerate market access without full infrastructure replication. For Investors and Strategic Acquirers: Carve-out targets emerge from industrial gas majors seeking to monetize non-core specialty gas divisions amid portfolio rationalization. Long-term viability hinges on abatement technology integration capabilities over the next decade as regulatory stringency tightens globally. Monitor EU F-Gas Regulation amendment trajectories as the critical inflection signal for accelerated consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ammonium Fluoride | SK Materials secures feedstock cost advantages against merchant competitors in Korean supply corridors. |
| Abatement Technology Co-Development | Linde plc locks in long-term offtake through integrated generation-service bundling with European foundries. |
| On-Site Generation Infrastructure Deployment | Direct pipeline connections to Pyeongtaek and Hsinchu clusters eliminate cryogenic transport cost premiums. |
| Carbon-Neutral Certification Program | Scope 3 emissions accounting differentiates low-carbon-intensity production for premium contract pricing. |
| Geographic Expansion into India | PLI scheme subsidies reduce capital intensity for first-mover abatement-integrated generation facilities. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with fluorine chemistry plant managers, semiconductor procurement leads at foundries, industrial gas distribution channel partners, and technical R&D directors; and secondary validation through customs and trade data, chemical industry association reports, and securities filings. Primary fieldwork captured operational realities of NF3 generation, purification, and abatement technology deployment. Secondary sources included EPA fluorinated gas reporting databases, EU F-Gas Regulation implementation guidance, and China MEE discharge limit documentation. Bottom-up capacity and consumption modeling triangulated against top-down market sizing from trade flow analysis.
Across the analysis window, the forecasting framework modeled segmentation dimensions including purity grade tier, end-use application, distribution channel structure, and regional regulatory cluster. CAGRs were derived from demand elasticity modeling against semiconductor node migration timelines and display panel manufacturing capacity expansion. Industry-specific inputs incorporated ALD tool proliferation rates in 3D NAND fabrication and EU F-Gas Regulation phase-down trajectories for fluorinated gas emission limits.
Material uncertainties — geopolitical disruption to East Asian supply corridors, regulatory divergence between EPA, EU F-Gas, and China MEE standards, and fluorine feedstock volatility tied to phosphate fertilizer markets — sit outside the modeled envelope. Forecasts reflect assumptions about abatement technology adoption rates and long-term contracting patterns without guarantee of realization. Recalibration cycles align with material shifts in semiconductor capital expenditure trajectories and regulatory amendment schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Nano-Bubble Generator Market
Industrial Chemicals
Wood Vinegar Market
Industrial Chemicals
Global Acid Proof Lining Market
Industrial Chemicals
Non-Corrosive Fluxes Market
Industrial Chemicals
Paraffin Inhibitors Market
Industrial Chemicals
2,3-Butanediol Market
Industrial Chemicals
1,4-Dioxane Market
Industrial Chemicals
Thermic Fluids Market
Industrial Chemicals
Food Grade Grease Market
Industrial Chemicals
Lignin Market
Industrial Chemicals
Liquid Electrolyte Market
Industrial Chemicals
Ethoxy Propanol Market
Industrial Chemicals
LAMEA Deoxidizer Market
Industrial Chemicals
Ultra-High-Purity Lithium Bis(fluorosulfonyl)imide (LiFSI) Electrolyte Salt Market
Industrial Chemicals
1,3-Propanediol (PDO) Market
Industrial Chemicals
India Thermic Fluid Market