
 Sage Extract Market | 2026-2036
Sage Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Sage Extract Market Analysis
Asset-light contract manufacturing and third-party extraction leasing is reshaping competitive entry in sage extract supply chains. Biolandes leverages backward integration into Mediterranean cultivation to secure raw material consistency. Mountain Rose Herbs sustains its position through certified organic channel control and direct-to-formulator distribution. McCormick and Company dominates food-grade extract procurement through longstanding spice and flavoring supply relationships with industrial buyers.
Sage extract comprises concentrated bioactive compounds—primarily rosmarinic acid, carnosic acid, and volatile terpenes—derived from Salvia officinalis through solvent extraction, steam distillation, or supercritical CO2 processing, serving antioxidant, antimicrobial, and flavoring functions across food, pharmaceutical, and cosmetic applications. Liquid extract and essential oil segments anchor current revenue pools due to established use in flavoring and aromatherapy applications, while powder extract formats are gaining traction in dietary supplement capsules and tablets where standardized dosing and shelf stability command premium positioning. The pharmaceutical application segment leads margin capture as clinicians seek evidence-backed botanical alternatives, though cosmetic preservative use is expanding as formulators replace synthetic antioxidants with plant-derived options.
EFSA novel food assessments and REACH substance registrations govern extract purity and import compliance across European markets, while FDA dietary supplement cGMPs and New Dietary Ingredient notifications shape product entry in the United States. Germany's Commission E monographs and the country's national pharmaceutical regulator maintain specific quality thresholds for sage preparations used in phytotherapy. Stakeholders must monitor evolving botanical identification requirements and adapt extraction documentation to satisfy divergent regional compliance frameworks.
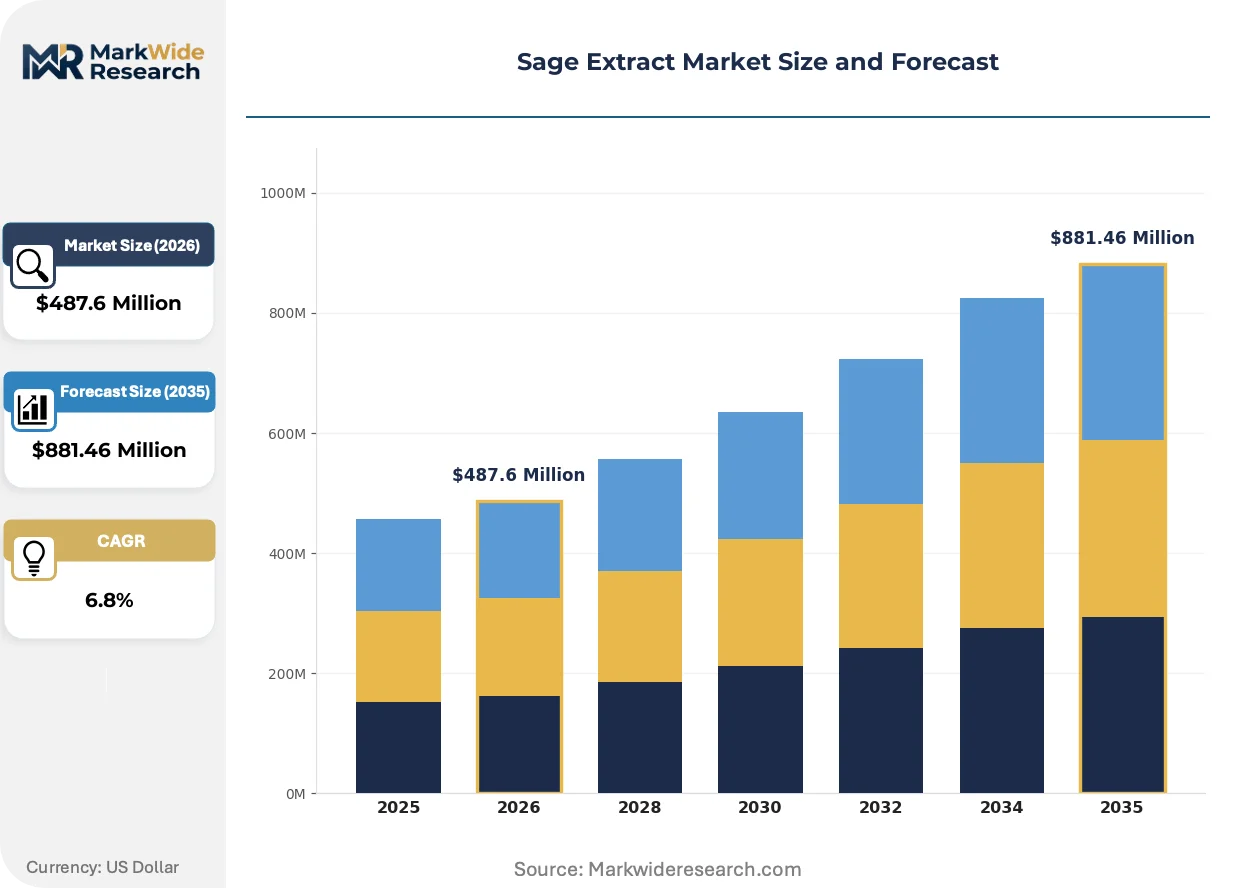
Market Dynamics
Pharmaceutical formulators are expanding sage extract incorporation into standardized herbal preparations, tightening purity thresholds across European supply chains while contract manufacturing reshapes competitive entry.
Growth Catalysts
- REACH substance registrations:ECHA mandates are elevating extract documentation standards, compelling suppliers to invest in chromatographic fingerprinting and batch traceability systems that command premium positioning.
- Phytotherapy demand in Germany:Commission E monographs sustain institutional procurement of sage preparations, anchoring volume commitments from hospital pharmacies and compounding facilities.
- Supercritical CO2 processing:This solvent-free extraction technology preserves volatile terpene profiles while eliminating residual solvent concerns, attracting clean-label cosmetic formulators.
Market Restraints
- Raw material concentration:Mediterranean cultivation clusters expose supply chains to climate volatility and harvest yield fluctuations that compress margin predictability.
- EFSA novel food assessments:Extended safety evaluation timelines delay market entry for innovative extract formats, freezing capital in regulatory limbo.
- Synthetic antioxidant substitution:Butylated hydroxytoluene and tertiary butylhydroquinone retain cost advantages in mass-market food preservation, capping sage extract penetration.
Strategic Opportunities
- Cosmetic preservative pivot:Formulators are replacing synthetic antioxidants with plant-derived options, opening shelf-space for rosmarinic acid standardized extracts in skincare emulsions.
- Dietary supplement capsules:Powder extract formats with verified actives are capturing premium positioning in direct-to-consumer wellness channels.
- EU Green Deal procurement:Sustainability-linked purchasing mandates favor botanical inputs with certified organic chain-of-custody documentation.
Industry Challenges
- Botanical identification expertise:Analytical chemists capable of distinguishing Salvia officinalis from adulterant species command scarce compensation premiums, constraining quality control scaling.
- Extraction equipment capex:Supercritical CO2 systems require seven-figure capital deployment with extended depreciation horizons, filtering mid-tier entrants toward leased capacity arrangements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sage Extract Market |
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Extract, Powder Extract, Essential Oil, Dried Sage Form: Capsule, Tablet, Tincture, Lotion End User: Food Industry, Pharmaceutical, Cosmetic, Dietary Supplements Application: Flavoring Agent, Medicinal Use, Aromatherapy, Preservative |
| Companies Covered | Aura Cacia, doTerra, Young Essential Oils, Aromatics International, Biolandes, Augusts Oil Ltd, Sibelius Natural Products, Mountain Rose Herbs, McCormick and Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sage Extract Market Emerging Trajectories
Extraction technology convergence with digital quality assurance systems is compressing batch-to-batch variability while regulatory documentation requirements intensify across multiple jurisdictions.
Supercritical CO2 extraction with inline near-infrared spectroscopy is digitizing real-time active compound monitoring during processing. Pharmaceutical contract manufacturers are adopting these integrated systems to satisfy FDA dietary supplement cGMP documentation requirements. The technology is digitizing quality control from post-hoc laboratory testing to continuous process verification, reducing release cycle times.
REACH botanical substance registrations are tightening purity thresholds for salvia-derived ingredients entering European markets. ECHA documentation requirements now mandate chromatographic fingerprinting and stable isotope ratio analysis for geographic origin verification. German phytomedicine manufacturers are responding by consolidating supplier relationships around backward-integrated Mediterranean cultivators with captive extraction capacity.
Direct-to-formulator distribution is displacing traditional ingredient broker networks in premium extract segments. Certified organic channel controllers are building proprietary procurement relationships with compounding pharmacies and boutique cosmetic houses. Germany anchors this channel compression, where phytotherapy traditions sustain willingness-to-pay premiums for documented provenance and batch-specific certificates of analysis.
Sage Extract Market Segmentation
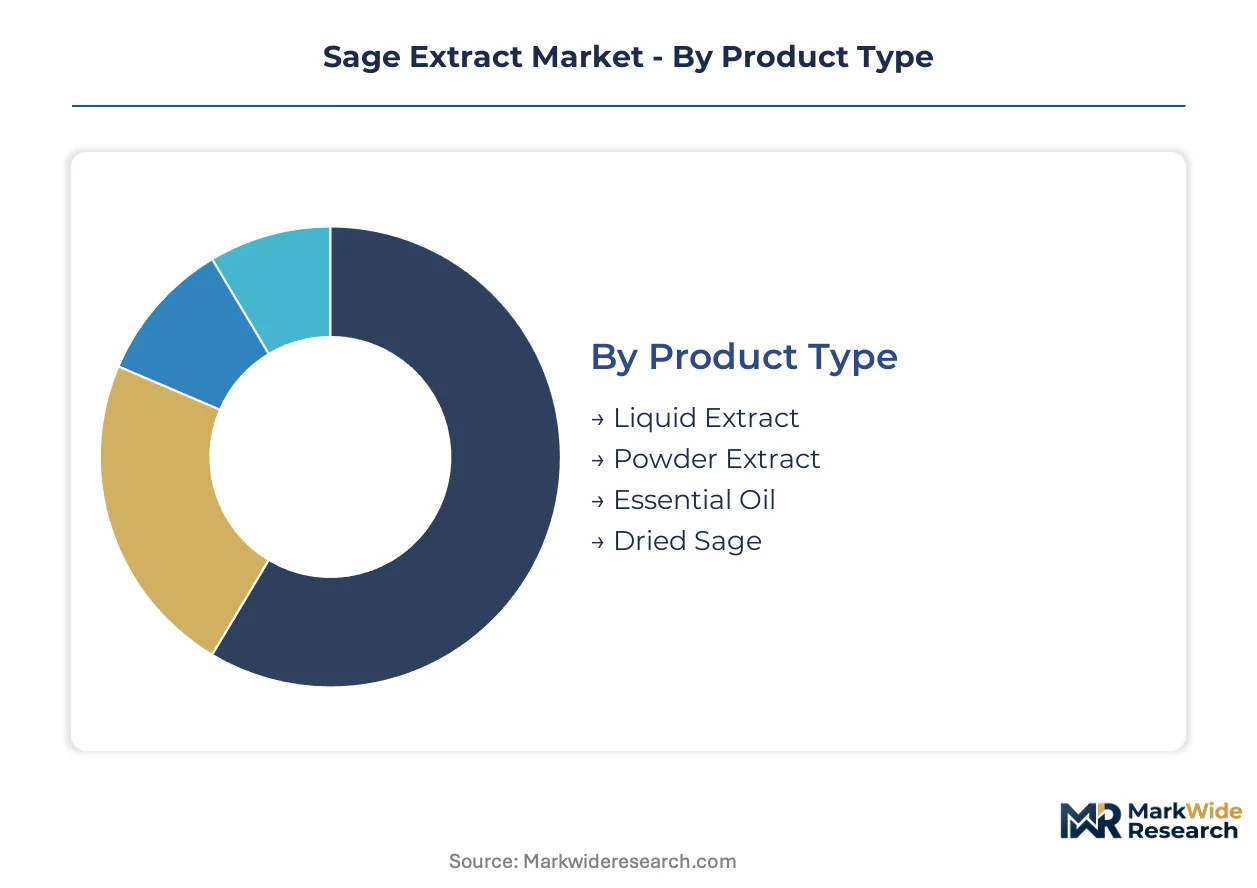
Sage extract segmentation reflects divergent technical requirements across pharmaceutical standardization, food-grade flavoring, and cosmetic preservation. Each product format and application carries distinct regulatory documentation burdens and margin structures that shape supplier specialization.
Product Type:
Liquid concentrates anchor flavoring and aromatherapy applications while powder formats capture pharmaceutical standardization premiums.
- Liquid Extract:Hydroalcoholic or glycerin-based solutions concentrate rosmarinic acid and volatile terpenes for rapid bioavailability. German phytotherapy manufacturers procure standardized tinctures for Commission E-compliant preparations, though aqueous stability limits shelf life in warm-climate distribution.
- Powder Extract:Spray-dried or vacuum-dried concentrates with verified active compound standardization enable precise dosing in solid dosage forms. Dietary supplement contract manufacturers in the United States favor these formats for FDA cGMP-compliant capsule production, where batch-to-batch consistency commands quality premiums.
- Essential Oil:Steam-distilled volatile fractions rich in thujone and cineole serve aromatherapy and topical applications.
- Dried Sage:Whole or cut leaf material retains culinary use in Mediterranean food processing and traditional medicine preparation.
Established volume favors Liquid Extract; emerging adoption favors Powder Extract.
Form:
Dosage format selection tracks end-use regulatory pathways and consumer convenience expectations across wellness channels.
- Capsule:Hard gelatin or vegetable cellulose shells encapsulate standardized powder extracts for precise unit dosing. Direct-to-consumer wellness brands in North American markets prioritize capsule formats for subscription-model compliance adherence, though excipient compatibility testing adds formulation development overhead.
- Tablet:Compressed powder matrices with binders and disintegrants suit high-volume pharmaceutical manufacturing. European compounding pharmacies specify tablet forms for hospital formulary inclusion, where dosage uniformity validation satisfies national pharmaceutical regulator requirements.
- Tincture:Alcohol-based liquid preparations retain traditional herbal medicine dispensing.
- Lotion:Emulsion-based topical delivery systems incorporate sage extract for cosmetic antioxidant claims.
Capsule formats climb the fastest in direct-to-consumer channels; tablet production retains institutional procurement dominance.
End User:
Customer segmentation reveals divergent purity specifications and documentation requirements across regulated industries.
- Pharmaceutical:Standardized extracts with chromatographic fingerprinting and heavy metal certification serve prescription and over-the-counter botanical drug development. German hospital pharmacies anchor procurement volume through Commission E monograph compliance, though EFSA novel food assessments delay innovative format entry.
- Cosmetic:Antioxidant and antimicrobial claims drive incorporation into natural preservation systems. Clean-label formulators in France and Switzerland specify rosmarinic acid standardized extracts to replace synthetic antioxidants in skincare emulsions, where EU Cosmetics Regulation safety dossiers mandate toxicological documentation.
- Food Industry:Flavoring-grade extracts and dried leaf serve seasoning and functional food applications.
- Dietary Supplements:Standardized extracts target wellness positioning in competitive retail channels.
Pharmaceutical procurement commands margin premiums; cosmetic adoption expands most quickly as synthetic replacement accelerates.
Application:
Functional use determines extraction method selection and regulatory classification across jurisdictions.
- Medicinal Use:Standardized preparations targeting throat irritation, digestive support, and cognitive claims require pharmaceutical-grade documentation. German phytotherapy traditions sustain volume through reimbursable prescription status, though clinical evidence requirements intensify for new indication expansion.
- Preservative:Rosmarinic acid and carnosic acid fractions replace synthetic antioxidants in clean-label food and cosmetic formulations. European cosmetic houses leverage plant-derived preservation to satisfy EU Green Deal procurement mandates, where organic certification chain-of-custody documentation qualifies for sustainability-linked purchasing.
- Flavoring Agent:Volatile terpene profiles enhance savory food and beverage applications.
- Aromatherapy:Essential oil diffusion and topical application serve wellness and stress management positioning.
Medicinal applications anchor value capture; preservative substitution gains share fastest across cosmetic and food segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal sustainability mandates are redirecting procurement toward certified organic sage extract supply chains, concentrating investment in Mediterranean cultivation zones with verified chain-of-custody documentation.
Germany
Commission E monographs sustain institutional procurement of standardized sage preparations through reimbursable phytotherapy prescriptions. The national pharmaceutical regulator enforces specific quality thresholds for hospital pharmacy and compounding facility supply. Bavaria anchors manufacturing concentration, where contract manufacturers serve domestic formulators with chromatographic fingerprinting documentation.
France
Clean-label cosmetic formulators specify rosmarinic acid standardized extracts to replace synthetic antioxidants in skincare emulsions. EU Cosmetics Regulation safety dossiers mandate toxicological documentation for preservative claims. The Provence-Alpes-Côte d'Azur region clusters boutique cosmetic houses demanding documented provenance and batch-specific certificates of analysis.
United States
FDA dietary supplement cGMPs and New Dietary Ingredient notifications shape product entry for standardized powder extracts in capsule formats. Direct-to-consumer wellness brands prioritize subscription-model compliance adherence. The Pacific Northwest concentrates certified organic channel controllers building proprietary procurement relationships with compounding pharmacies.
Switzerland
Swissmedic maintains stringent botanical drug quality standards that favor suppliers with supercritical CO2 processing capabilities. Premium cosmetic and pharmaceutical manufacturers demand solvent-free extraction documentation. The Basel region clusters precision formulators integrating sage extract into evidence-backed botanical preparations for export markets.
China
NMPA botanical ingredient registrations are tightening purity documentation requirements for imported salvia-derived materials entering domestic pharmaceutical and cosmetic manufacturing. Dual carbon goals accelerate sustainability-linked purchasing mandates. The Yangtze River Delta concentrates extraction equipment fabricators developing supercritical CO2 systems for regional contract manufacturers.
Sage Extract Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. The structure fragments between backward-integrated Mediterranean cultivators with captive extraction capacity and asset-light contract manufacturers leasing third-party processing. Three archetypes dominate: certified organic channel controllers, spice-and-flavoring conglomerates with industrial buyer relationships, and supercritical CO2 technology specialists. Competitive moves concentrate on supplier relationship consolidation around documented provenance and extraction equipment partnerships for capacity scaling.
Within the certified organic tier, Mountain Rose Herbs and Aura Cacia exemplify channel-control strategies through direct-to-formulator distribution and aromatherapy positioning. Biolandes anchors the backward-integrated archetype with Mediterranean cultivation control. McCormick and Company occupies the industrial-scale vector through longstanding spice and flavoring supply relationships. These three represent divergent competitive paths: proprietary procurement, upstream raw material security, and mass-market buyer lock-in.
| Leading Market Players |
|---|
| Aura Cacia |
| doTerra |
| Young Essential Oils |
| Aromatics International |
| Biolandes |
| Augusts Oil Ltd |
| Sibelius Natural Products |
| Mountain Rose Herbs |
| McCormick and Company |
| Others |
Supply Flow & Price Mechanics
Provence-Alpes-Côte d'Azur cultivation clusters anchor raw material availability for European cosmetic formulators, concentrating upstream capacity among backward-integrated Mediterranean growers who command premium positioning through certified organic documentation. This geographic concentration translates directly into pricing power for suppliers with verified chain-of-custody systems, while buyers without long-term offtake agreements face spot-market volatility during harvest compression periods.
Pricing Analysis
Certification level creates the primary spread between pharmaceutical-grade and food-grade sage extracts. Three-tier pricing structure across premium, standard, and economy levels reflects EFSA novel food compliance status, REACH substance registration completeness, and organic certification chain-of-custody documentation. Cost compression in standard-grade liquid extracts is intensifying because synthetic antioxidant substitutes retain cost advantages in mass-market food preservation. Pharmaceutical procurement teams demonstrate lowest price sensitivity due to Commission E monograph compliance requirements, while industrial flavoring buyers negotiate aggressively on volume contracts.
Supply Chain Analysis
Biolandes and Mountain Rose Herbs hold captive extraction capacity through backward-integrated Mediterranean cultivation or certified organic channel partnerships. Supply concentrates in France, Spain, and Germany, with raw material sourcing drawing from Dalmatian coast cultivation zones and Provencal organic cooperatives. Single-source vulnerability runs through climate-exposed harvest yields in Mediterranean growing regions. Distribution runs through direct-to-formulator relationships displacing traditional ingredient broker networks in premium segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sage extract procurement is shifting toward platform-economics coordination as EFSA and REACH documentation requirements force supplier consolidation around integrated quality assurance systems. Interoperability between chromatographic fingerprinting databases and regulatory submission portals is compressing formulator switching costs.
For Market Incumbents: Build regulatory documentation moats through REACH substance registration completion and EFSA novel food dossier pre-submission. Commission E monograph compliance anchors hospital pharmacy volume commitments that emerging suppliers cannot replicate without multi-year safety evaluation timelines. Biolandes demonstrates this defensive positioning through backward integration into Mediterranean cultivation securing raw material consistency against climate volatility threats. For New Entrants and Emerging Players: Mid-tier cosmetic contract manufacturers in Central Europe represent the most penetrable entry point for rosmarinic acid standardized powder extracts. Supercritical CO2 equipment leasing arrangements bypass seven-figure capital deployment barriers while satisfying Swissmedic solvent-free documentation requirements. Direct sampling to Provence-based boutique cosmetic houses bypasses established broker networks. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors supercritical CO2 processing specialists with integrated near-infrared spectroscopy quality systems. Long-term viability hinges on extraction technology convergence with digital batch traceability platforms. Acquisition target archetype: certified organic channel controllers with proprietary procurement relationships and documented provenance systems. The signal to watch is EFSA novel food assessment timeline compression indicating regulatory pathway predictability.| Strategic Initiative | Industry Significance |
|---|---|
| REACH Substance Registration Completion | ECHA documentation mandates elevate barrier to European market entry for unregistered suppliers. |
| Supercritical CO2 Capacity Expansion | Swissmedic solvent-free standards favor processors with clean-label extraction documentation. |
| Certified Organic Channel Partnership | EU Green Deal procurement mandates qualify sustainability-linked purchasing for documented provenance. |
| Direct-to-Formulator Distribution Buildout | German phytotherapy traditions sustain premium willingness-to-pay for batch-specific certificates of analysis. |
| Chromatographic Fingerprinting Investment | Commission E monograph compliance requires batch traceability systems commanding quality premiums. |
Methodological Framework
Operator-level perspectives from extraction equipment engineers, phytotherapy procurement managers at German hospital pharmacies, cosmetic formulation chemists, and certified organic cultivation cooperatives anchored the qualitative base. Primary interviews combined with secondary validation from EFSA novel food assessment databases, REACH substance registration filings, and EU organic certification body records. Bottom-up volume modeling across product type, application, and end-user segments triangulated against top-down trade flow analysis.
Scenario-bracketing framed demand projections across the analysis window, with segmentation modeling spanning liquid extract, powder extract, essential oil, and dried sage formats alongside pharmaceutical, cosmetic, food industry, and dietary supplement end-use applications. CAGRs derived from regression against historical volume trends and regulatory approval pathway timelines. Forecast inputs incorporated supercritical CO2 equipment deployment rates and EFSA assessment queue progression.
Macroeconomic conditions sit as an overlay; deviation in euro-zone pharmaceutical reimbursement policy and Mediterranean climate patterns would shift the trajectory. Forecasts reflect documented assumptions on regulatory timeline stability and harvest yield consistency. Quarterly review of EFSA novel food assessment publication rates and REACH registration completion volumes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Extracts
Cochineal Extract Market
Extracts
Organic Extracts Market
Extracts
Industrial Extractor Market
Extracts
Sandalwood Oil Market
Extracts
Citrus Powder Market
Extracts
Floral Extract Market
Extracts
Black Fungus Extract Market
Extracts
Peppermint Oil Market
Extracts
Global Azadirachtin Market
Extracts
Cassia Extract Market
Extracts
Myrrh Powder Market
Extracts
Marine Algae Polysaccharides Market
Extracts
Global Herbal Extract Market
Extracts
Orange Oil Market
Extracts
Nigella Sativa Extract Market
Extracts
Lemongrass Oil Market