
 Glycidyl Ether Market | 2026-2036
Glycidyl Ether Market Size, Share, and Industry Trends Forecast 2026-2036
Glycidyl Ether Market Analytics
A capital-intensity divergence between integrated petrochemical giants and specialty chemical firms is reorganizing competitive hierarchy in glycidyl ether supply. Hexion Inc. leverages its phenolic resin backbone to secure backward integration into bisphenol-A feedstocks. Huntsman Corporation anchors its position through dedicated epoxy intermediates manufacturing in North America and Europe. KUKDO Chemical competes on scale in Asia-Pacific merchant markets.
Glycidyl ethers constitute a class of epoxy reactive diluents and modifiers synthesized through epichlorohydrin condensation with alcohols or phenols, typically exhibiting molecular weights between 140 and 300 g/mol and epoxide equivalent weights of 140-290 g/eq. These compounds reduce viscosity in high-performance epoxy formulations while maintaining crosslink density for aerospace adhesives and marine coatings. Glycidyl Phenyl Ether dominates formulated coatings applications where thermal stability and chemical resistance command premium positioning. Composites application growth outpaces sealants adoption as wind turbine blade manufacturers specify longer-chain glycidyl ether tougheners. The construction end user segment sustains volume throughput through flooring and grouting compounds.
EPA regulates glycidyl ether emissions under Clean Air Act hazardous air pollutant standards for coating operations. ECHA classifies certain glycidyl ethers as skin sensitizers under REACH, restricting occupational exposure limits and labeling requirements. China's MEE enforces GB standards on epoxy resin production effluents containing epichlorohydrin residuals. Stakeholders must monitor regulatory divergence between jurisdictions when siting new production capacity or reformulating product lines for export qualification.
Market Dynamics
Epichlorohydrin feedstock concentration among integrated chlor-alkali producers is compressing merchant supply availability and forcing specialty formulators toward long-term offtake contracts or captive integration investments.
Growth Catalysts
- EU Green Deal VOC thresholds:REACH-compliant low-emission glycidyl ether formulations command premium positioning in European industrial coatings as manufacturers reformulate ahead of tightening emission caps.
- Wind turbine blade composites:Toughened epoxy systems incorporating longer-chain glycidyl ethers displace conventional amine curing agents in next-generation offshore turbine manufacturing.
- China's dual carbon goals:Domestic epoxy resin producers accelerate glycidyl ether adoption to meet GB standards on production efficiency and carbon intensity benchmarks.
Market Restraints
- Epichlorohydrin cost volatility:Propylene-chlorine integrated producers in the US Gulf Coast and Middle East exert pricing power over non-integrated glycidyl ether manufacturers.
- Skin sensitizer classification:ECHA REACH restrictions on glycidyl phenyl ether and related compounds impose occupational exposure limits that increase handling costs and workplace compliance burden.
- Bio-based epoxy diluents:Epoxidized vegetable oil derivatives from agricultural feedstocks threaten technical-grade glycidyl ether volumes in non-structural coating applications.
Strategic Opportunities
- India PLI scheme for advanced materials:Domestic epoxy formulation capacity expansion under production-linked incentives creates localized glycidyl ether demand as import substitution accelerates.
- UV-curable hybrid systems:Convergence of cationic photopolymerization with glycidyl ether-modified oligomers opens electronics encapsulation applications in semiconductor packaging.
- Direct-to-formulator digital channels:Specialty chemical marketplaces bypass traditional distributor markups for standardized glycidyl ether grades in mid-volume coating operations.
Industry Challenges
- Process safety engineering talent:Epichlorohydrin handling expertise and reactor safety management skills face scarcity as veteran chemical engineers retire from chlor-alkali operations.
- Multi-jurisdiction labeling compliance:Divergent hazard communication requirements between EPA, ECHA, and China's MEE create formulation versioning complexity for export-oriented producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glycidyl Ether Market |
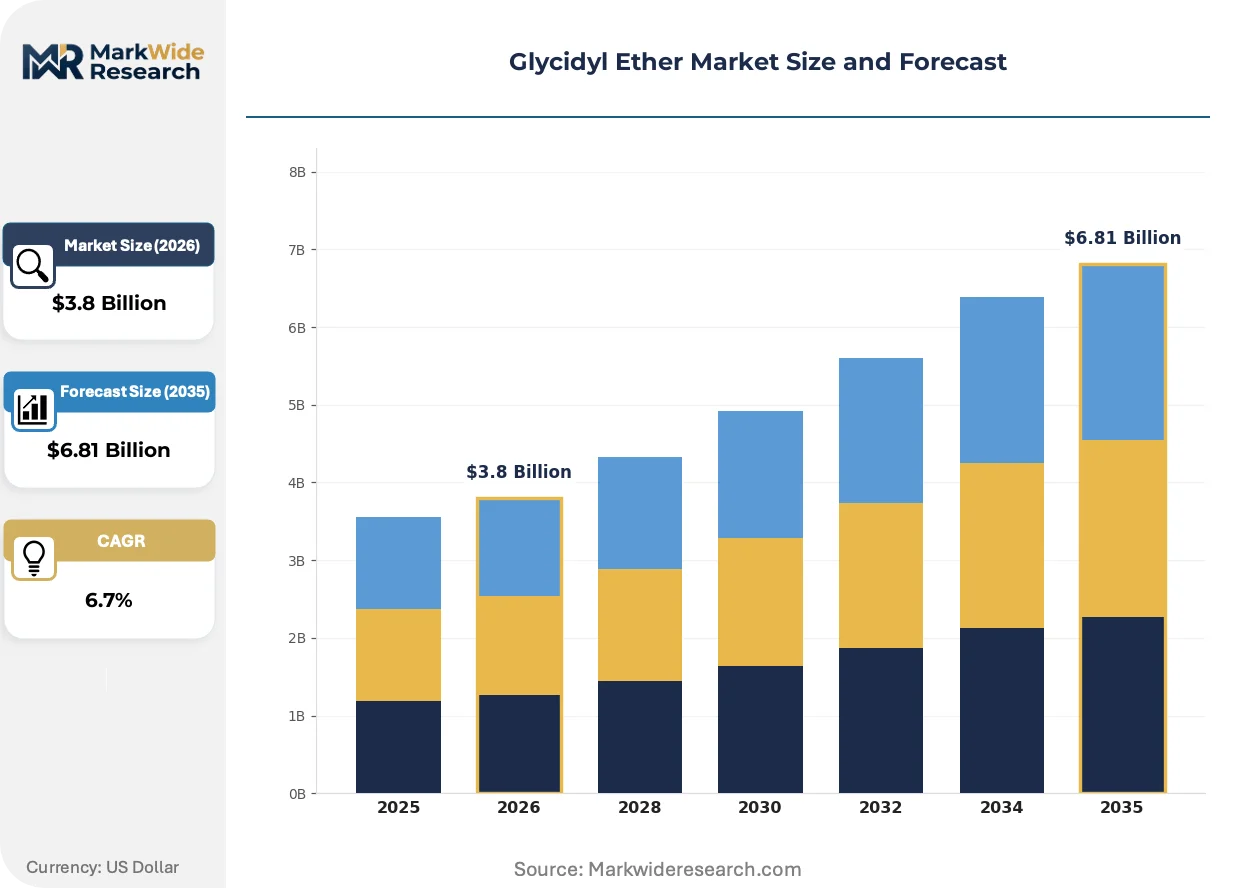
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glycidyl Phenyl Ether, Glycidyl Butyl Ether, Glycidyl Methacrylate, Glycidyl Allyl Ether Application: Adhesives, Coatings, Sealants, Composites End User: Aerospace, Automotive, Electronics, Construction Distribution Channel: Direct Sales, Distributors, Online Retailers, Wholesalers |
| Companies Covered | Hexion Inc., Huntsman Corporation, Olin Corporation, BASF SE, Evonik Industries AG, Cardolite Corporation, Atul Ltd., Aditya Birla Chemicals, KUKDO Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glycidyl Ether Market Evolving Landscape
Reactive diluent chemistry is fragmenting into performance-optimized and sustainability-driven development tracks, with formulation science advancing faster than standardization frameworks can codify.
Hybrid glycidyl ether-acrylate oligomers are bifurcating the radiation-curable coatings segment. Automotive OEM clearcoat formulators in Germany and Japan adopt these dual-cure systems to achieve solvent-free application with epoxy-grade chemical resistance. The technology is compressing conventional UV monomer demand while creating specification complexity for coating line operators.
REACH authorization procedures for Substances of Very High Concern are tightening supply security requirements for glycidyl ethers with residual epichlorohydrin content. Downstream aerospace adhesive manufacturers in France and the Netherlands now mandate third-party analytical certification for every batch. Suppliers with in-house gas chromatography capabilities capture preferential supplier status.
Specification-driven procurement now dominates high-performance epoxy purchasing. Wind energy OEMs in Denmark and Spain consolidate qualified material lists to three approved glycidyl ether sources per blade platform, displacing spot-market buying. Blade manufacturers with captive testing laboratories compress supplier onboarding timelines while raising technical barriers for merchant chemical distributors.
Glycidyl Ether Market Segmentation
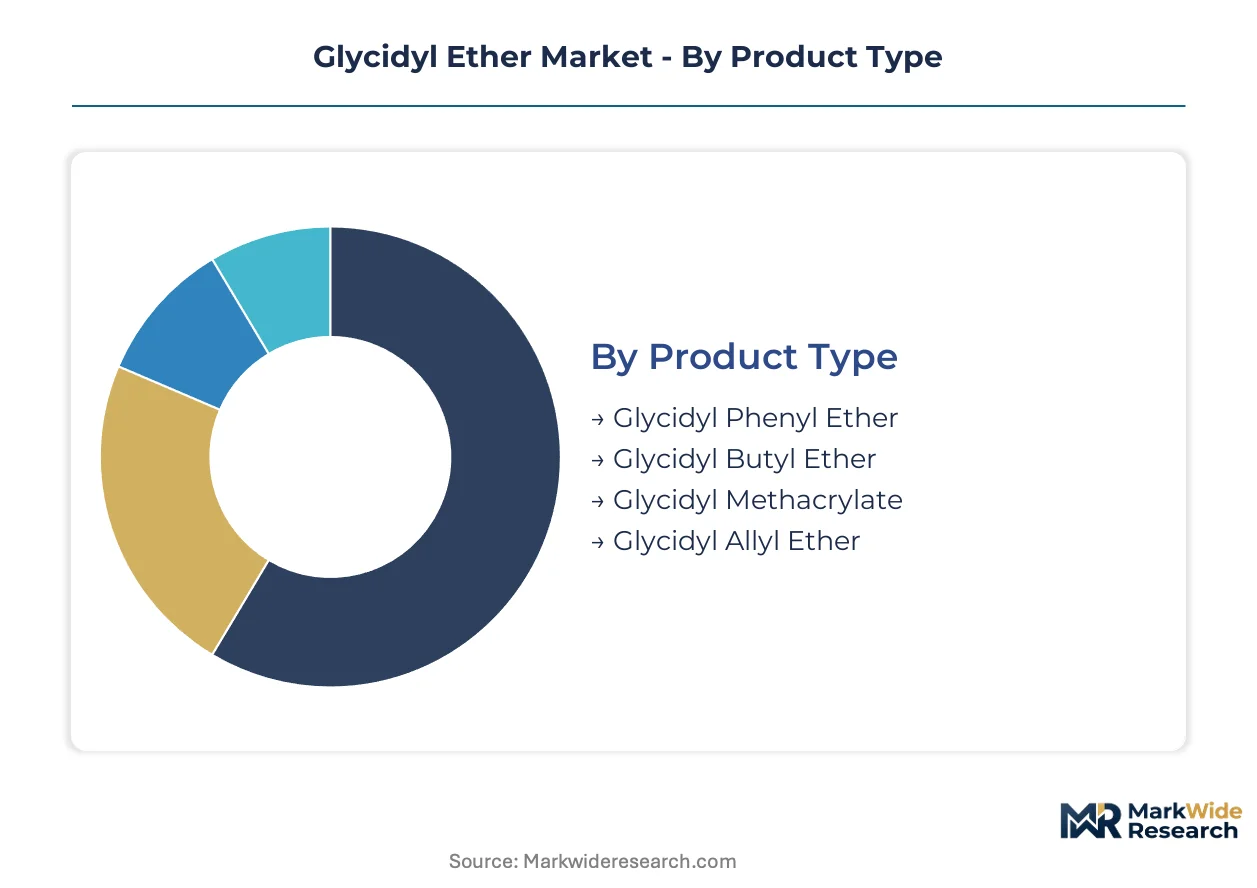
Segmentation in glycidyl ethers reveals how substitution pressures from bio-based diluents and regulatory constraints fragment demand across performance tiers. Formulators must match molecular architecture to end-use specifications or risk displacement by epoxidized vegetable oils in commodity coatings.
Product Type:
Glycidyl phenyl ether faces the most acute substitution threat from bio-based alternatives in non-structural applications, while specialized grades defend position through performance differentiation.
- Glycidyl Phenyl Ether:Aromatic structure delivers thermal stability above 150°C and chemical resistance for high-performance aerospace adhesives. Demand concentrates in Germany's industrial chemical corridor where REACH-compliant formulations command premium positioning ahead of tightening EU Green Deal VOC thresholds.
- Glycidyl Butyl Ether:Aliphatic backbone reduces viscosity in marine coatings and industrial flooring systems without compromising crosslink density. Construction formulators in Ludwigshafen and Leverkusen specify this grade for large-volume grouting compounds where cost efficiency competes with performance.
- Glycidyl Methacrylate:Dual functionality enables hybrid epoxy-acrylate systems for UV-curable electronics encapsulation.
- Glycidyl Allyl Ether:Unsaturated side chains support specialty composite tougheners in wind turbine blade manufacturing.
Glycidyl phenyl ether anchors the volume base while glycidyl methacrylate gains share at the steepest rate through hybrid curing applications.
Application:
Cost tier stratification separates specification-driven aerospace demand from price-sensitive construction volumes, with coating applications spanning both extremes.
- Adhesives:Structural bonding applications in aerospace manufacturing require low-viscosity glycidyl ether modifiers to maintain pot life while enabling high-shear strength. French and Dutch aerospace adhesive producers now mandate third-party analytical certification for every batch under REACH authorization procedures.
- Composites:Toughened epoxy systems incorporating longer-chain glycidyl ethers displace conventional amine curing agents in next-generation offshore wind turbine blade manufacturing. Denmark and Spain blade OEMs consolidate qualified material lists to three approved sources per platform.
- Coatings:Industrial protective and automotive clearcoat formulations balance VOC compliance with chemical resistance requirements.
- Sealants:Expansion joint and waterproofing applications favor lower-cost glycidyl butyl ether formulations in volume construction markets.
Coatings sustain the broadest volume footprint while composites climb the fastest through wind energy specification expansion.
End User:
Customer type fragmentation pits capital-intensive OEM qualification programs against merchant market spot buying, with procurement centralization reshaping supplier relationships.
- Aerospace:Lightweight composite structures in commercial aviation and defense applications specify glycidyl ether-modified epoxies for strength-to-weight optimization. Manufacturers expanding epoxy resin formulations drive specification tightening through captive testing laboratories.
- Construction:Flooring, grouting, and waterproofing systems consume standardized glycidyl ether grades through distributor channels with limited technical service requirements.
- Automotive:OEM clearcoat formulators in Germany and Japan adopt dual-cure hybrid systems to achieve solvent-free application with epoxy-grade chemical resistance.
- Electronics:Semiconductor packaging encapsulation demands ultra-low ionic content glycidyl ether grades with batch-level traceability.
Construction anchors volume throughput while aerospace expands most quickly through qualification-driven premium positioning.
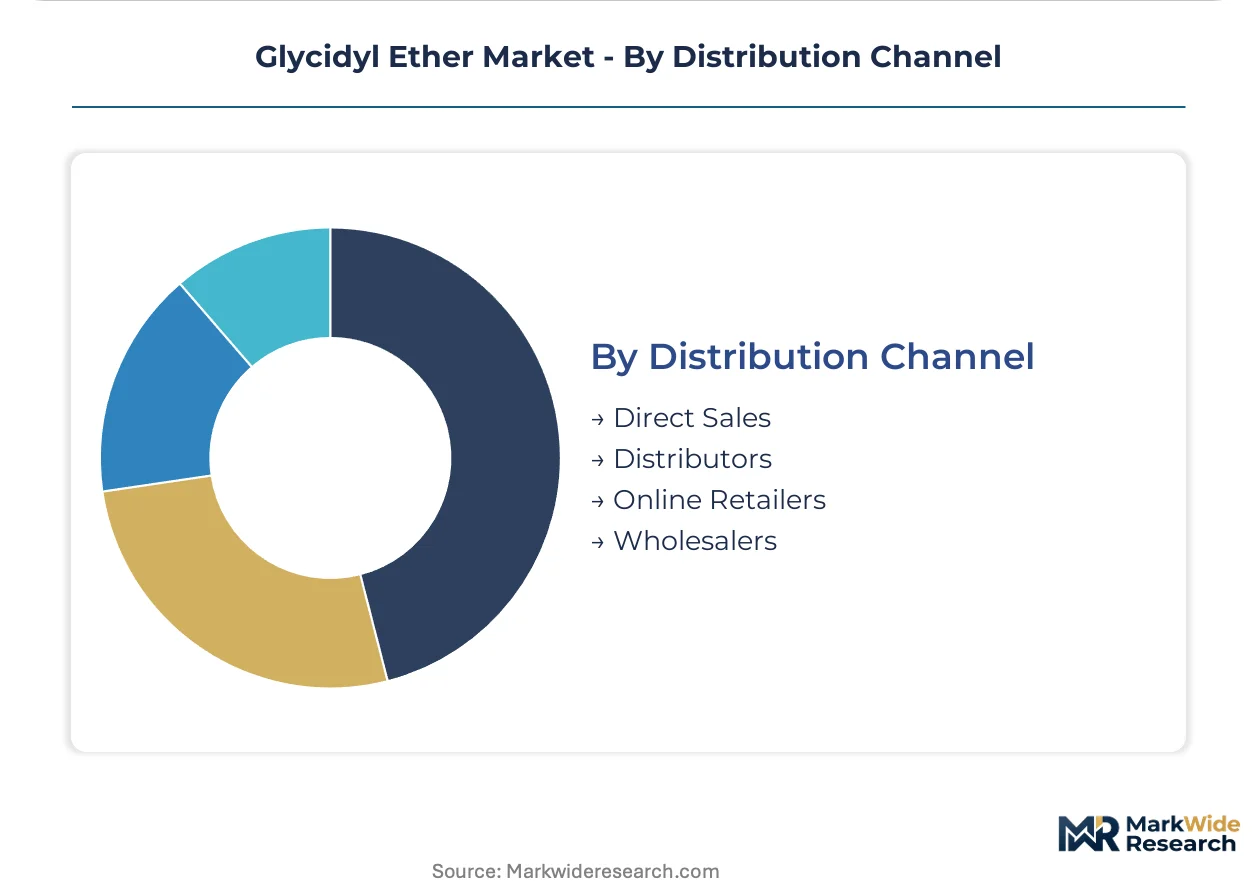
Distribution Channel:
Supply concentration among integrated chlor-alkali producers forces channel restructuring as specialty formulators seek security of supply through direct relationships.
- Direct Sales:Large-volume aerospace and wind energy OEMs negotiate long-term offtake contracts with glycidyl ether producers to secure epichlorohydrin supply chain continuity. Direct relationships enable batch certification and technical service integration required by specification-driven procurement.
- Distributors:Merchant chemical distributors face rising technical barriers as wind energy OEMs compress supplier onboarding timelines and consolidate qualified material lists.
- Online Retailers:Specialty chemical marketplaces bypass traditional distributor markups for standardized glycidyl ether grades in mid-volume coating operations.
- Wholesalers:Construction-focused volume channels serve price-sensitive flooring and grouting compound formulators with limited technical requirements.
Direct sales anchors the value base while online retailers gain traction fastest through marketplace disintermediation in standardized grades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. Germany and France prioritize REACH-compliant aerospace formulations with batch-level certification. China and India drive volume through construction-grade applications with less stringent traceability. The United States occupies a middle ground, balancing EPA-regulated industrial coatings with specification-driven wind energy demand.
Germany
Aerospace adhesive manufacturers in Hamburg and Munich specify glycidyl phenyl ether for structural bonding applications with thermal stability above 150°C. ECHA REACH authorization procedures for Substances of Very High Concern mandate third-party analytical certification for every batch. The industrial chemical corridor around Ludwigshafen and Leverkusen concentrates formulation capacity as manufacturers reformulate ahead of tightening EU Green Deal VOC thresholds.
China
Wind turbine blade producers in Jiangsu and Guangdong provinces accelerate adoption of toughened epoxy systems incorporating longer-chain glycidyl ether tougheners. MEE enforces GB standards on epoxy resin production effluents containing epichlorohydrin residuals. The Yangtze River Delta hosts integrated chlor-alkali producers that supply feedstock to domestic glycidyl ether manufacturers serving construction flooring markets.
United States
EPA regulates glycidyl ether emissions under Clean Air Act hazardous air pollutant standards for coating operations in automotive and marine applications. The US Gulf Coast propylene-chlorine integrated producers exert pricing power over non-integrated specialty formulators. Texas and Louisiana host merchant chemical distributors facing technical barriers as wind energy OEMs consolidate qualified material lists.
India
Domestic epoxy formulation capacity expansion under the PLI scheme for advanced materials creates localized glycidyl ether demand as import substitution accelerates. Maharashtra and Gujarat industrial zones attract construction chemical manufacturers specifying glycidyl butyl ether for large-volume grouting compounds. BIS standards on chemical intermediates drive quality upgrading among domestic producers.
France
Aerospace OEMs in Toulouse and Nantes mandate ultra-low ionic content glycidyl ether grades with batch-level traceability for composite structures. ECHA skin sensitizer classifications impose occupational exposure limits that increase handling costs in formulation facilities. The Provence-Alpes-Côte d'Azur region hosts specialty chemical distributors adapting to specification-driven procurement from wind energy blade manufacturers.
Glycidyl Ether Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in glycidyl ether supply. Integrated petrochemical giants control epichlorohydrin feedstock access through captive chlor-alkali operations. Specialty chemical firms compete on formulation expertise and batch certification capabilities. Strategic moves concentrate on backward integration into bisphenol-A feedstocks and long-term offtake contracting with wind energy OEMs.
Within the integrated chlor-alkali tier, Hexion Inc. and Huntsman Corporation exemplify producers leveraging phenolic resin backbones and dedicated epoxy intermediates manufacturing to secure supply chain continuity. KUKDO Chemical occupies a position among Asia-Pacific scale competitors serving merchant markets through volume-driven positioning. These three anchors illustrate how feedstock access and geographic specialization stratify competitive positioning across regional demand centers.
| Leading Market Players |
|---|
| Hexion Inc. |
| Huntsman Corporation |
| Olin Corporation |
| BASF SE |
| Evonik Industries AG |
| Cardolite Corporation |
| Atul Ltd. |
| Aditya Birla Chemicals |
| KUKDO Chemical |
| Others |
Value Network & Pricing Analysis
Sixty-to-ninety-day epichlorohydrin order lead times concentrate pricing power with integrated chlor-alkali producers in the US Gulf Coast and Middle East, forcing non-integrated glycidyl ether manufacturers toward long-term offtake contracts or margin compression.
Pricing Analysis
Long-term offtake contracts dominate aerospace and wind energy procurement, while spot purchases persist in construction-grade applications. Three-tier pricing structure across REACH-certified premium, standard industrial, and economy construction grades reflects batch certification costs and epichlorohydrin feedstock access. Cost compression in economy tiers intensifies because bio-based epoxy diluents from agricultural feedstocks threaten technical-grade volumes. Construction formulators exhibit highest price sensitivity; aerospace adhesive manufacturers accept premium positioning for thermal stability above 150°C.
Supply Chain Analysis
Strait of Hormuz transit routes underpin epichlorohydrin feedstock security for Middle Eastern integrated producers serving Asian merchant markets. Manufacturing concentrates in Germany, China, and the United States, with downstream formulation drawing from bisphenol-A, phenolic resins, and chlorine derivatives. Single-source vulnerability runs through propylene-chlorine integration at Ludwigshafen and Leverkusen chemical complexes. Distribution feeds from direct sales channels for qualified aerospace suppliers and specialty chemical marketplaces for standardized coating grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Reactive diluent chemistry fragmentation creates niche formation opportunities as formulation science advances faster than standardization frameworks can codify performance tiers.
For Market Incumbents: Compound captive epichlorohydrin supply through backward integration into chlor-alkai operations or long-term offtake contracting with Jiangsu and Guangdong wind blade manufacturers. Invest in in-house gas chromatography capabilities to capture preferential supplier status under REACH authorization procedures for Substances of Very High Concern. Bio-based diluent substitution in non-structural coatings demands defensive R&D into hybrid glycidyl ether-acrylate oligomers.
For New Entrants and Emerging Players: Anchor in India's PLI scheme for advanced materials to exploit import substitution acceleration in Maharashtra and Gujarat construction chemical zones. Target mid-volume coating operations through specialty chemical marketplace channels bypassing traditional distributor technical barriers. Electronics encapsulation for semiconductor packaging offers lowest qualification friction given ultra-low ionic content grade premiums.
For Investors and Strategic Acquirers: Carve-out targets emerge from integrated petrochemical parents seeking to divest non-core specialty chemical assets with stranded batch certification capabilities. Five-to-ten-year viability hinges on feedstock security and REACH compliance infrastructure rather than commodity scale. Monitor ECHA skin sensitizer classification expansion as inflection signal for occupational exposure limit cost escalation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chlor-Alkali | Hexion and Huntsman secure phenolic resin feedstock continuity against propylene volatility. |
| Long-term Supply Agreement with Wind OEMs | Denmark and Spain blade manufacturers consolidate qualified material lists to three approved sources per platform. |
| REACH Batch Certification Investment | French and Dutch aerospace adhesive producers mandate third-party analytical certification for every batch. |
| Hybrid Glycidyl Ether-Acrylate Development | German and Japanese automotive OEM clearcoat formulators adopt dual-cure systems for solvent-free application. |
| Specialty Chemical Marketplace Partnership | Digital channels bypass distributor markups for standardized grades in mid-volume coating operations. |
Research Methodology
A standing panel of epoxy formulation chemists, wind energy procurement directors, aerospace adhesive technical leads, and chlor-alkali plant managers provided ongoing calibration across primary interview cycles. Secondary validation drew from ECHA REACH authorization databases, US EPA Clean Air Act hazardous air pollutant standards, China MEE GB standards on epoxy resin effluents, and customs trade data for epichlorohydrin flows. Bottom-up volume modeling triangulated against top-down industry association benchmarks from ACC and Cefic.
Consistency checks validated segment-level outputs against external capacity announcements and qualified material list consolidations by Denmark and Spain wind OEMs. The analytical framework modeled product type, application, end user, and distribution channel dimensions across the projection horizon. CAGRs derived from elasticity-adjusted demand curves incorporating EU Green Deal VOC threshold implementation timelines and China's dual carbon goal compliance trajectories.
Decision-makers should treat outputs as directional under sustained epichlorohydrin feedstock concentration and REACH authorization timeline assumptions; material deviation in bio-based diluent substitution rates would warrant model refresh. Practitioners should keep alternative scenarios live as ECHA skin sensitizer classification scope and India PLI scheme disbursement pace evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Mining Explosives Consumables Market
Industrial Chemicals
Ultra-High-Purity Lithium Bis(fluorosulfonyl)imide (LiFSI) Electrolyte Salt Market
Industrial Chemicals
India Precipitated Silica Market
Industrial Chemicals
Blow Torch Market
Industrial Chemicals
General Industrial Oils Market
Industrial Chemicals
Enzymatic Acrylamide-Reduction Systems Market
Industrial Chemicals
Pesticide Inert Ingredients Market
Industrial Chemicals
Global Electronic Grade Sulfuric Acid Market
Industrial Chemicals
Quicklime Market
Industrial Chemicals
Fischer-Tropsch (FT) Wax Market
Industrial Chemicals
Liquid Electrolyte Market
Industrial Chemicals
Thermally Stable Antiscalant Market
Industrial Chemicals
Mass Transfer Trays Market
Industrial Chemicals
Wood Preservative Market
Industrial Chemicals
Ionophores Market
Industrial Chemicals
2,3-Butanediol Market