
 Global Acid Proof Lining Market | 2026-2036
Global Acid Proof Lining Market Size, Share, and Industry Trends Forecast 2026-2036
Global Acid Proof Lining Market Foresight
Specialized ceramic tile applicators and certified rubber lining technicians is redrawing competitive boundaries across the value chain. STEULER-KCH GmbH anchors German engineering dominance through captive installation crews and proprietary cast application protocols. Hempel A/S differentiates via fluoropolymer R&D intensity and marine-to-industrial technology transfer. Polycorp Ltd. occupies North American rubber lining specialization with backward integration into custom compound formulation.
Acid proof lining denotes corrosion-resistant barrier systems engineered from elastomeric sheets, thermoset resins, or fluoropolymer membranes bonded to steel or concrete substrates, typically achieving thicknesses of 3–10 mm and operating continuously at pH levels below 2.0. These systems shield chemical reactors, storage vessels, and effluent handling infrastructure from sulfuric acid, hydrochloric acid, and oxidizing media degradation. Epoxy coatings lead value contribution due to lower installed cost and versatile spray application across metal finishing and wastewater treatment infrastructure. Fluoropolymer linings represent the fastest-expanding material class as pharmaceutical producers and aggressive chemical processors specify PTFE and FEP barriers for temperatures exceeding 150°C. Rubber linings retain volume dominance in pulp and paper manufacturing where abrasion resistance and cost efficiency outweigh premium chemical performance requirements.
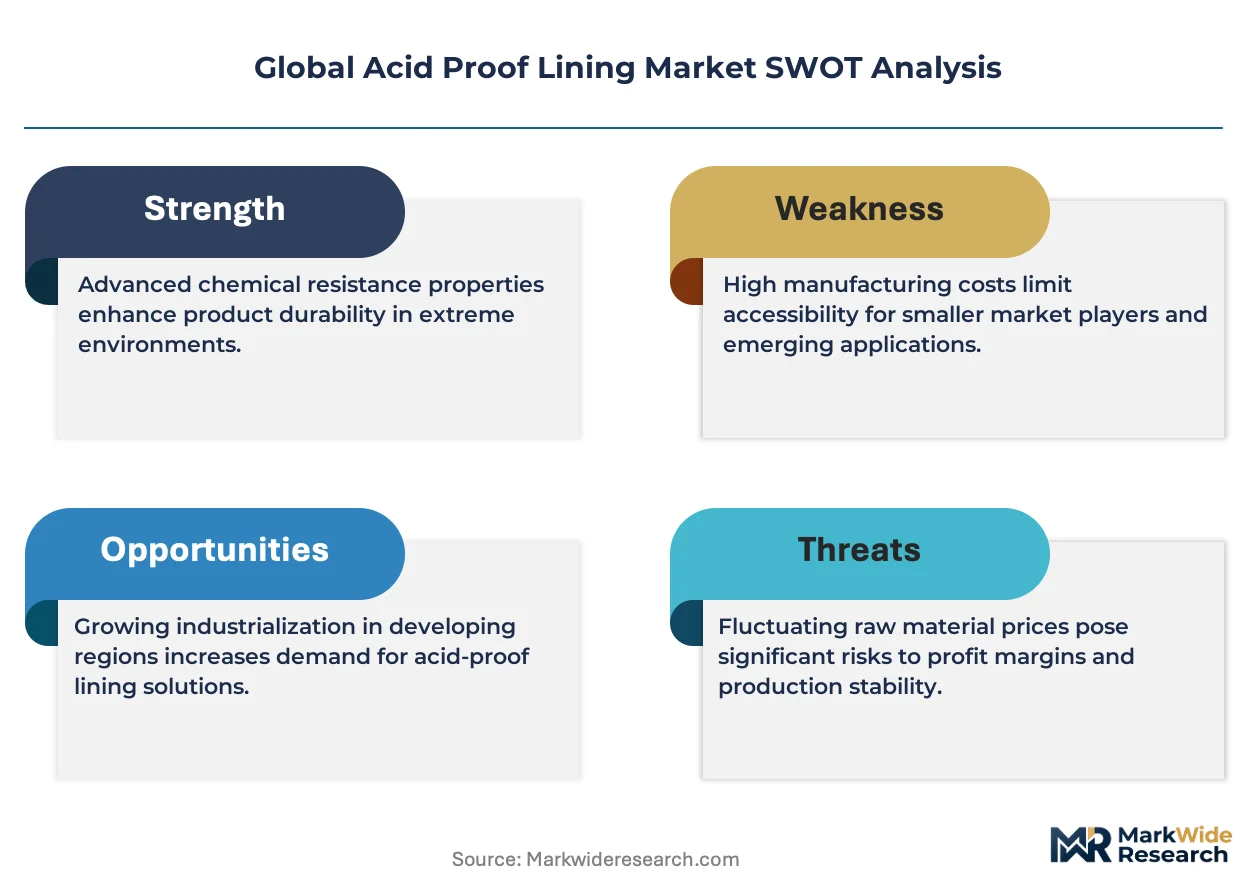
EPA effluent guidelines and OSHA process safety mandates tighten compliance thresholds for US chemical manufacturers and water treatment plants, directly elevating specification grades for lining replacement cycles. REACH restrictions on chromium-based pretreatments and the EU Green Deal industrial emissions framework push European steel fabricators toward epoxy and polyurethane systems with reduced volatile organic compound profiles. BIS corrosion protection standards and India's PLI scheme for chemical manufacturing infrastructure amplify domestic lining demand. Stakeholders must monitor evolving fluoropolymer raw material availability and regional installer certification scarcity as primary determinants of margin capture and project execution capacity.
Market Dynamics
Certified installer scarcity and captive application protocols are concentrating project execution capacity among vertically integrated specialists, compressing margins for material-only suppliers and reshaping competitive boundaries across the value chain.
Growth Catalysts
- EPA effluent guidelines:US chemical manufacturers and water treatment plants face tightened compliance thresholds, elevating specification grades for lining replacement cycles and accelerating demand for high-performance epoxy and polyurethane systems.
- India's PLI scheme:Domestic chemical manufacturing infrastructure incentives amplify lining demand as new plant construction requires corrosion protection for reactors, storage vessels, and effluent handling systems.
- Fluoropolymer membrane technology:Pharmaceutical producers and aggressive chemical processors specify PTFE and FEP barriers for continuous operation above 150°C, creating premium demand pull distinct from commodity rubber alternatives.
Market Restraints
- Fluoropolymer raw material concentration:PTFE and FEP resin supply concentrates among limited specialty chemical producers, exposing lining fabricators to feedstock availability shocks and price volatility.
- REACH chromium restrictions:European steel fabricators face elimination of hexavalent chromium pretreatments, forcing costly reformulation of surface preparation protocols and extending qualification timelines.
- Rubber lining abrasion limits:Pulp and paper manufacturers encounter performance ceilings in high-velocity slurry applications where ceramic tile systems offer superior wear resistance despite higher installed cost.
Strategic Opportunities
- Underpenetrated Saudi chemical infrastructure:Petrochemical expansion under Vision 2030 creates demand for acid proof lining in sulfuric acid alkylation units and phosphate fertilizer complexes with limited local installer presence.
- EU Green Deal industrial emissions framework:Carbon border adjustments and emissions trading scheme expansion push steel fabricators toward low-VOC epoxy systems, favoring suppliers with verified environmental product declarations.
- Digital twin integration:Convergence of IoT sensor networks with predictive maintenance platforms enables lining condition monitoring, opening subscription-based service revenue streams for installation specialists.
Industry Challenges
- Certified rubber lining technician shortage:Specialized applicators capable of hot vulcanization bonding and spark testing remain scarce relative to project pipeline, constraining execution capacity and extending lead times.
- Legacy concrete substrate compatibility:Aging chemical plant infrastructure presents surface preparation complexity where existing contamination and moisture intrusion compromise adhesion of modern thermoset resin systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Acid Proof Lining Market |
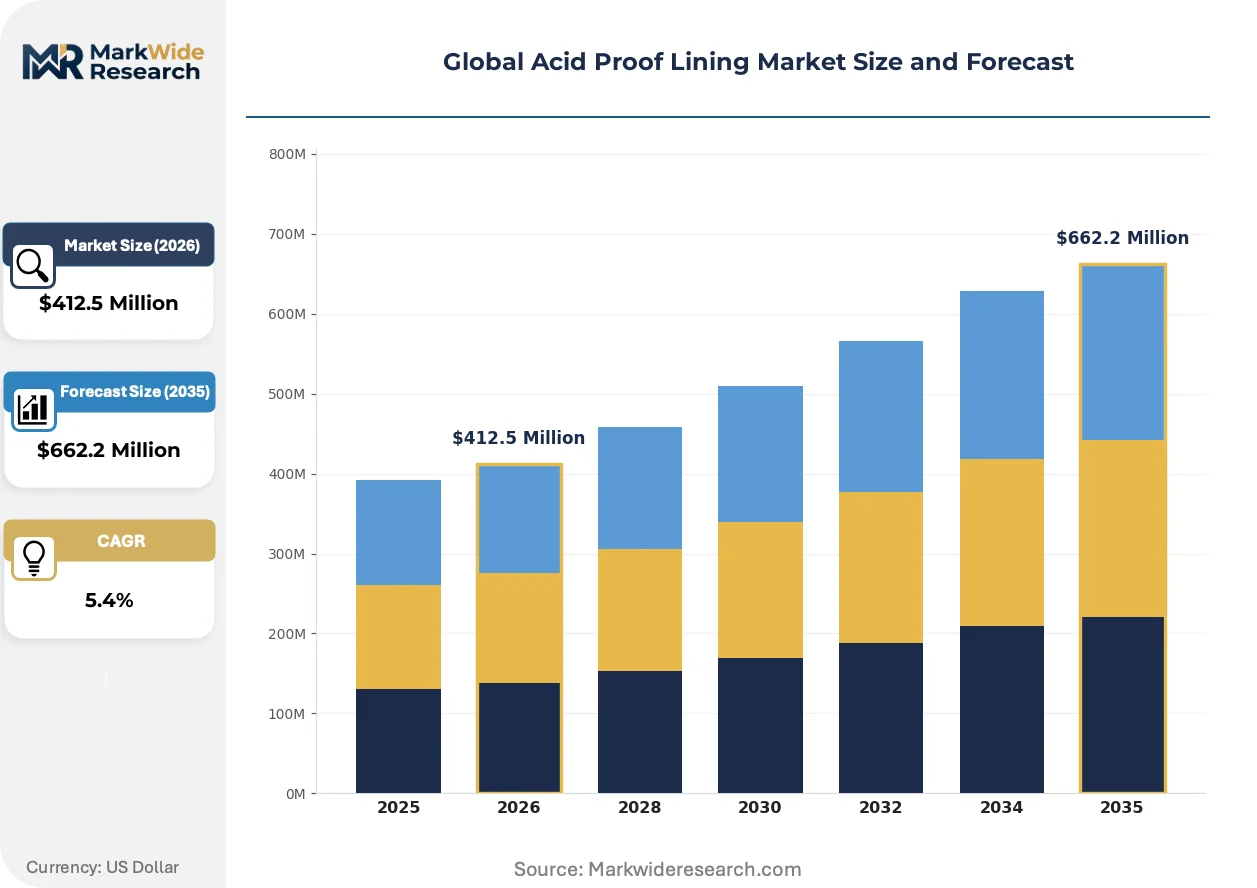
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $662.2 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Rubber Linings, Epoxy Coatings, Polyurethane Linings, PVC Linings, Fluoropolymer Linings Application: Chemical Processing, Wastewater Treatment, Pulp & Paper Manufacturing, Metal Finishing, Food & Beverage Production End User Industry: Chemical Manufacturers, Water Treatment Plants, Textile Mills, Steel Fabricators, Pharmaceutical Producers Installation Type: Spray Application, Brush Application, Roller Application, Cast Application, Dip Coating |
| Companies Covered | BASF SE, PPG Industries, The Sherwin-Williams Company, Axalta Coating Systems, Hempel A/S, Jotun A/S, STEULER-KCH GmbH, Polycorp Ltd., Koch Knight, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Acid Proof Lining Market Shifts & Advancements
Material science advances and regulatory chemistry restrictions are actively restructuring specification preferences across end-use verticals. The following developments capture the most consequential shifts in technology adoption and compliance architecture.
Fluoropolymer lining systems, specifically PTFE and FEP membranes bonded to fiberglass-reinforced plastic substrates, deliver superior chemical resistance across pH extremes and oxidizing media. Pharmaceutical batch reactor manufacturers and specialty chemical producers in Germany and Switzerland are specifying these systems for processes involving hot sulfuric acid and chlorine dioxide. This technology is supplanting traditional lead brick and carbon brick constructions in high-temperature, high-concentration applications where thermal cycling resistance proves critical.
REACH restrictions on chromium-based pretreatments and the EU Green Deal industrial emissions framework are eliminating hexavalent chromium conversion coatings from steel surface preparation protocols. European fabricators must qualify alternative phosphate and zirconium-based pretreatment systems that achieve comparable adhesion without hazardous substance classification. German steel fabrication shops and Dutch tank manufacturers face the steepest compliance curve given their export exposure to regulated markets requiring full material disclosure.
Asset owners in chemical processing and water treatment are compressing lining replacement cycles from reactive failure-based maintenance to predictive condition-based interventions. Third-party inspection contractors using ultrasonic thickness measurement and holiday detection are displacing traditional time-based maintenance contracts. This pattern is most pronounced in US Gulf Coast petrochemical complexes where OSHA process safety management audits mandate documented integrity management systems with quantitative remaining life calculations.
Global Acid Proof Lining Market Segmentation
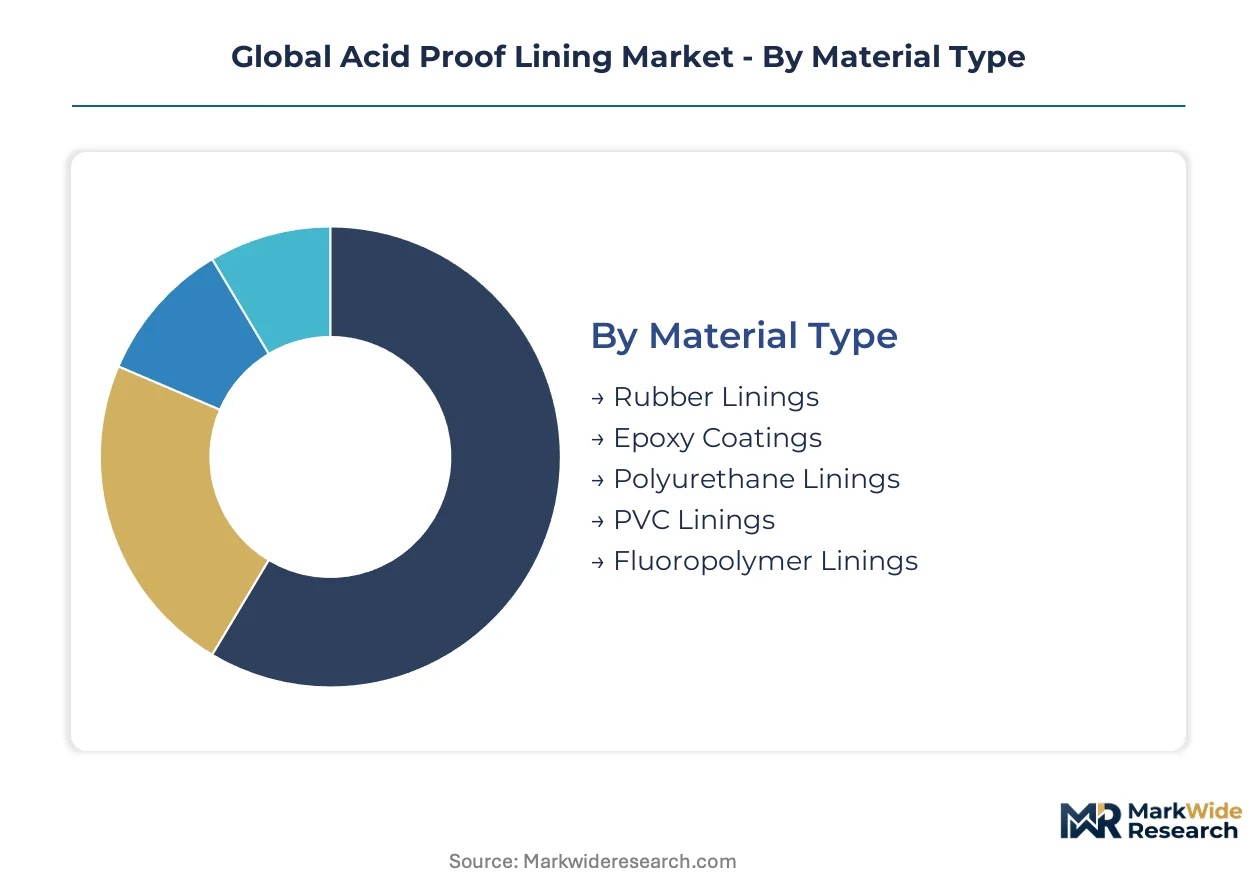
Material selection and application method determine project economics and regulatory compliance in acid proof lining procurement. Specification patterns diverge sharply between domestic maintenance cycles and export-oriented new construction, creating distinct margin tiers across each segment category.
Material Type:
Domestic chemical processors in India and Germany favor rubber and epoxy systems for cost-controlled maintenance, while fluoropolymer specifications concentrate in Swiss and US pharmaceutical export contracts demanding thermal performance documentation.
- Rubber Linings:Natural and synthetic elastomer sheets bonded through hot vulcanization deliver 3–8 mm barrier thickness against sulfuric and hydrochloric acid attack. Pulp and paper mills in the US Southeast specify these systems for abrasion resistance in lime slurry handling, though certified technician scarcity extends installation lead times.
- Epoxy Coatings:Two-part thermoset formulations achieve 500–2000 micron films through spray application with lower installed cost than sheet alternatives. German steel fabricators facing REACH chromium restrictions are qualifying low-VOC epoxy systems for tank and vessel construction under EU Green Deal emissions frameworks.
- Polyurethane Linings:Aliphatic and aromatic formulations balance chemical resistance with flexibility for concrete substrate applications.
- PVC Linings:Thermoplastic sheet systems serve secondary containment and lower-temperature effluent handling in cost-sensitive municipal installations.
- Fluoropolymer Linings:PTFE and FEP membranes bonded to FRP substrates enable continuous operation above 150°C in pharmaceutical batch reactors.
Rubber linings command the established base. The steepest expansion runs through fluoropolymer systems.
Application:
Volume concentration tracks industrial infrastructure age, with wastewater and metal finishing applications dominated by North American and European maintenance spend while chemical processing tilts toward Indian and Saudi new-build demand.
- Chemical Processing:Reactor vessels, storage tanks, and transfer piping in sulfuric acid alkylation and chlor-alkali operations require lining systems certified for pH below 2.0 and thermal cycling. Indian chemical manufacturers under PLI scheme expansion are driving specification upgrades for new reactor construction.
- Wastewater Treatment:Clarifier tanks, digesters, and effluent channels face accelerated lining replacement under tightened EPA effluent guidelines for US municipal and industrial treatment plants.
- Pulp & Paper Manufacturing:Digesters, bleach towers, and lime mud handling systems specify rubber-lined steel for abrasion resistance in kraft process operations.
- Metal Finishing:Plating tanks and rinse stations in automotive and electronics supply chains use PVC and epoxy systems for acid recovery containment.
- Food & Beverage Production:Clean-in-place vessels and acid-cleaned processing equipment require FDA-compliant lining materials with documented migration testing.
Chemical processing anchors revenue concentration. Wastewater treatment is climbing the fastest amid regulatory compliance acceleration.
End User Industry:
Procurement sophistication separates industries: pharmaceutical and steel fabricators demand certified installation protocols and material traceability, while textile and municipal water operators prioritize unit cost minimization.
- Chemical Manufacturers:Integrated petrochemical complexes and specialty chemical producers specify lining systems with quantitative remaining life calculations for OSHA process safety management compliance. US Gulf Coast operators are compressing replacement cycles from reactive failure to predictive condition-based interventions.
- Water Treatment Plants:Municipal and industrial facilities face lining degradation from chlorinated effluent and variable pH loading, with EPA consent decrees driving accelerated capital expenditure in legacy infrastructure.
- Textile Mills:Dyeing and finishing operations with acid-based color fixation require localized tank lining replacement rather than integrated system specifications.
- Steel Fabricators:Tank and vessel OEMs in Germany and the Netherlands are reformulating surface preparation protocols to eliminate hexavalent chromium pretreatments under REACH restrictions.
- Pharmaceutical Producers:Batch reactor manufacturers in Switzerland and Germany specify fluoropolymer barriers with full material disclosure for regulated export markets.
Chemical manufacturers command the established base. Pharmaceutical producers are gaining share fastest through premium specification pull.
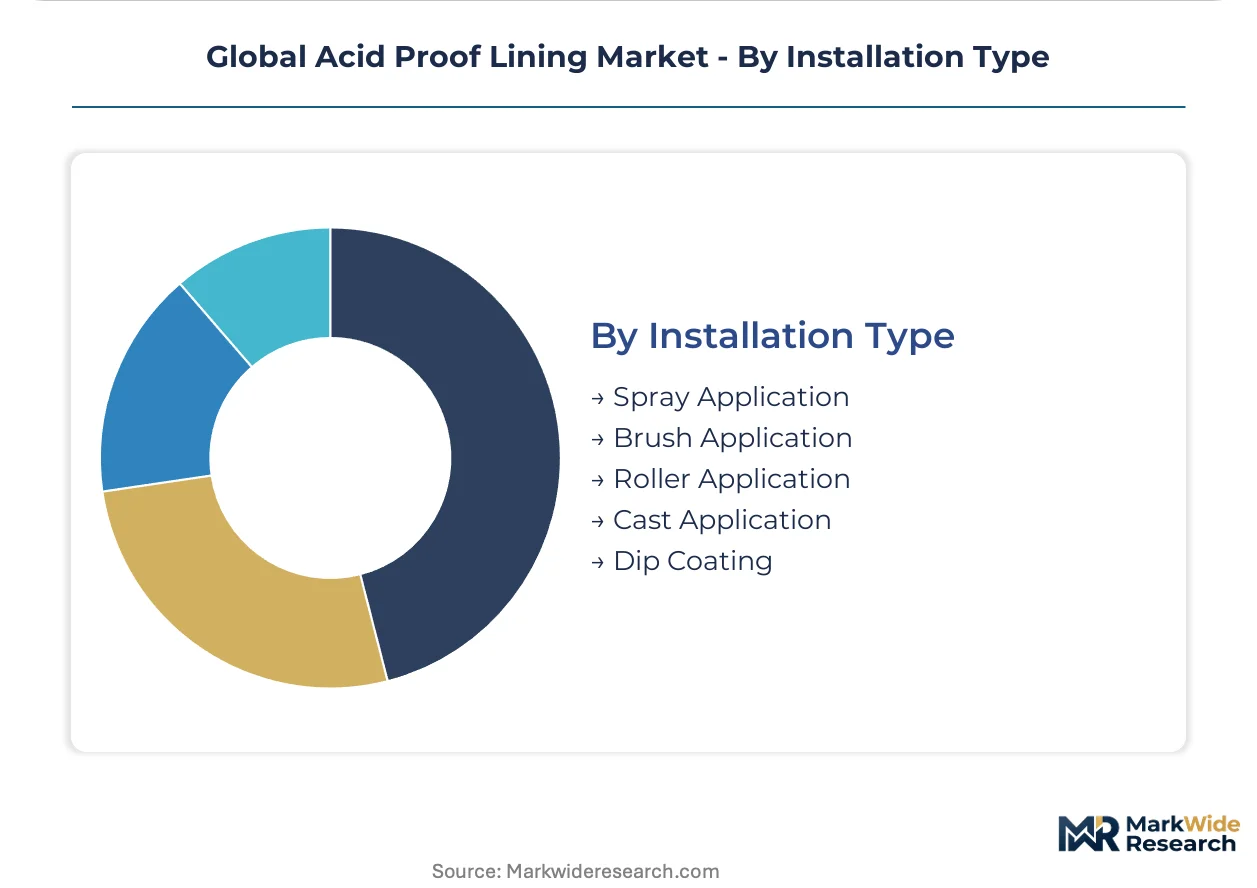
Installation Type:
Method selection determines project execution capacity: spray and cast application require captive crew certification, while brush and roller methods enable lower-tier contractor participation.
- Spray Application:Airless and plural-component spray equipment achieves rapid film buildup on large surface areas with consistent thickness control. Epoxy and polyurethane systems for wastewater treatment infrastructure in the US rely on certified applicators with EPA RRP credentials.
- Cast Application:Proprietary trowel and pour protocols for fluoropolymer and epoxy systems create monolithic barriers on complex geometries. German specialists STEULER-KCH maintain competitive differentiation through captive installation crews with proprietary technique certification.
- Brush Application:Manual coating for touch-up, repair, and small-diameter piping where equipment access limits spray deployment.
- Roller Application:Saturated fabric reinforcement with resin rolling for tank base and secondary containment areas.
- Dip Coating:Immersion application for small components and fittings with uniform coating distribution in controlled bath conditions.
Spray application commands the established base. Cast application is climbing the fastest through premium project capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography: German and Swiss pharmaceutical producers specify fluoropolymer membranes for thermal performance, while Indian and US operators prioritize rubber and epoxy systems for cost-controlled maintenance cycles.
United States
US Gulf Coast petrochemical complexes and municipal water treatment plants drive specification upgrades for lining replacement cycles. EPA effluent guidelines and OSHA process safety mandates tighten compliance thresholds, compressing maintenance intervals from reactive failure to predictive condition-based interventions.
Germany
Steel fabricators and tank OEMs in the Ruhr industrial basin face reformulation pressure from REACH chromium restrictions. The EU Green Deal industrial emissions framework eliminates hexavalent chromium pretreatments, forcing qualification of alternative phosphate and zirconium-based surface preparation protocols.
India
Chemical processing infrastructure expansion under the PLI scheme amplifies domestic lining demand for new reactor construction. Gujarat and Maharashtra industrial corridors see concentrated specification activity as specialty chemical producers build sulfuric acid alkylation and chlor-alkali capacity.
Saudi Arabia
Petrochemical expansion under Vision 2030 creates demand for acid proof lining in phosphate fertilizer complexes and alkylation units. The Eastern Province industrial cluster around Jubail presents execution challenges due to limited local certified installer presence relative to project pipeline.
Switzerland
Pharmaceutical batch reactor manufacturers in Basel and surrounding chemical clusters specify fluoropolymer barriers with full material documentation for regulated export markets. Swissmedic oversight and customer audit requirements elevate procurement sophistication beyond commodity specifications.
Global Acid Proof Lining Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the acid proof lining market. The upper tier commands project execution capacity through captive installation crews and proprietary application protocols, while mid-scale material suppliers face margin compression from certified technician scarcity. Two strategic archetypes dominate: German engineering specialists with backward integration into formulation and installation, and Nordic coating multinationals leveraging marine-to-industrial technology transfer. Competitive moves concentrate on vertical integration into application services and geographic expansion into underpenetrated chemical infrastructure markets.
Among German fabricators, STEULER-KCH GmbH anchors the integrated engineering archetype through captive crew certification and proprietary cast application protocols. Hempel A/S represents the coating multinational vector with fluoropolymer R&D intensity and cross-sector technology leverage. Polycorp Ltd. occupies the North American rubber lining specialization tier with in-house control over custom compound formulation. These three exemplify how execution capacity and material science depth separate premium-positioned operators from commodity material suppliers.
| Leading Market Players |
|---|
| BASF SE |
| PPG Industries |
| The Sherwin-Williams Company |
| Axalta Coating Systems |
| Hempel A/S |
| Jotun A/S |
| STEULER-KCH GmbH |
| Polycorp Ltd. |
| Koch Knight |
| Others |
Supply & Pricing Matrix
Twelve-to-sixteen-week lead times for certified rubber lining technicians in the US Gulf Coast and Western Europe concentrate project execution capacity among captive-crew specialists, compressing margins for material-only suppliers and amplifying pricing power for vertically integrated applicators with in-house bonding certification.
Pricing Analysis
Project-based contracting dominates acid proof lining procurement, with lump-sum engineering-procurement-construction agreements capturing 70-80 percent of chemical processing spend. Price differentiation hinges on installer certification tier and material traceability documentation. Cost compression in standard rubber and epoxy segments is intensifying as Indian PLI scheme expansion floods regional markets with qualified domestic applicators. Municipal water treatment operators exhibit highest price sensitivity, while Swiss pharmaceutical batch reactor manufacturers accept 40-60 percent premiums for fluoropolymer systems with full REACH-compliant material disclosure.
Supply Chain Analysis
Inventory cycles for PTFE and FEP resins stretch 90-120 days, exposing lining fabricators to feedstock availability shocks from limited specialty chemical producers in Germany, Japan, and the United States. Raw material sourcing draws from fluoropolymer resin synthesis, synthetic rubber compounding, and thermoset epoxy formulation. Single-source vulnerability concentrates in high-purity PTFE membrane supply. Distribution runs through direct project contracting for large chemical infrastructure, with regional distributor networks serving maintenance and repair segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fluoropolymer membrane technology is disrupting specification preferences across pharmaceutical and aggressive chemical processing, creating premium capture opportunities distinct from commodity rubber alternatives.
For Market Incumbents: Secure captive installer certification pipelines in India and Saudi Arabia before PLI scheme and Vision 2030 project peaks strain technician availability. Deepen backward integration into custom rubber compound formulation to defend margin position against material-only supplier commoditization. Prioritize digital twin integration investments to capture recurring service revenue from predictive maintenance platforms. For New Entrants and Emerging Players: Lead with certified cast application protocols for fluoropolymer systems in Swiss and German pharmaceutical export markets, where procurement sophistication exceeds commodity competition. Target Saudi Arabia's Eastern Province petrochemical cluster with mobile installation crews trained in hot vulcanization bonding. Differentiate through rapid-response maintenance contracts with documented spark testing capabilities. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because certified technician scarcity and proprietary application protocols are concentrating execution capacity among vertically integrated specialists. Acquisition targets include mid-scale German and Nordic coating specialists with captive crew certification and fluoropolymer R&D depth. Watch for REACH restriction enforcement tightening on chromium-based pretreatments as signal for epoxy system qualification surge.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Installer Certification | STEULER-KCH's proprietary cast protocols demonstrate how crew control captures premium project economics. |
| Fluoropolymer R&D Intensity | Hempel A/S leverages marine coating technology transfer to accelerate pharmaceutical barrier development. |
| Backward Integration into Compounding | Polycorp Ltd.'s in-house rubber formulation secures margin control against commodity resin volatility. |
| Digital Twin Platform Development | IoT sensor convergence enables subscription-based condition monitoring for US Gulf Coast petrochemical operators. |
| Geographic Expansion into Saudi Arabia | Vision 2030 petrochemical buildout creates demand with limited local certified installer presence. |
Research Methodology
Desk research of customs trade data, chemical industry association reports, and regulatory filing databases preceded structured interviews with plant engineers at chemical processing facilities, procurement leads at steel fabrication OEMs, certified rubber lining technicians, and technical R&D directors at coating multinationals. Primary fieldwork combined telephone and video interviews with secondary validation against SEC filings, BIS corrosion protection standards documentation, and EU Green Deal implementation guidance. Bottom-up project pipeline analysis triangulated against top-down material consumption estimates.
Variance decomposition across material type, application method, end-use industry, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs were derived from segmented growth rate aggregation. Key inputs included fluoropolymer resin capacity expansion announcements, certified installer training program graduation rates, and EPA effluent guideline enforcement timelines.
Forecasts assume regulatory continuity in EPA effluent guidelines, REACH chromium restrictions, and India's PLI scheme; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Liquid Electrolyte Market
Industrial Chemicals
Lime Manufacturing Market
Industrial Chemicals
Inorganic Coagulants Market
Industrial Chemicals
Aluminium Production Chemicals Market
Industrial Chemicals
Diphenyl Oxide (DPO) Market
Industrial Chemicals
India Thermic Fluid Market
Industrial Chemicals
Soil Treatment Chemicals Market
Industrial Chemicals
Fabric Starch Market
Industrial Chemicals
Calciner Market
Industrial Chemicals
Global Dodecanedioic Acid Market
Industrial Chemicals
Global Battery Grade Lithium Hydroxide Market
Industrial Chemicals
Europe Biocides Market
Industrial Chemicals
Pulp and Paper Enzymes Market
Industrial Chemicals
Hydrogen Sulfide Scavengers Market
Industrial Chemicals
Quenching Fluids and Salts Market
Industrial Chemicals
Molecular Sieves Market