
 Draft Tube Baffle (DTB) Crystallizers Market | 2026-2036
Draft Tube Baffle (DTB) Crystallizers Market Size, Share, and Industry Trends Forecast 2026-2036
Draft Tube Baffle (DTB) Crystallizers Market Insights
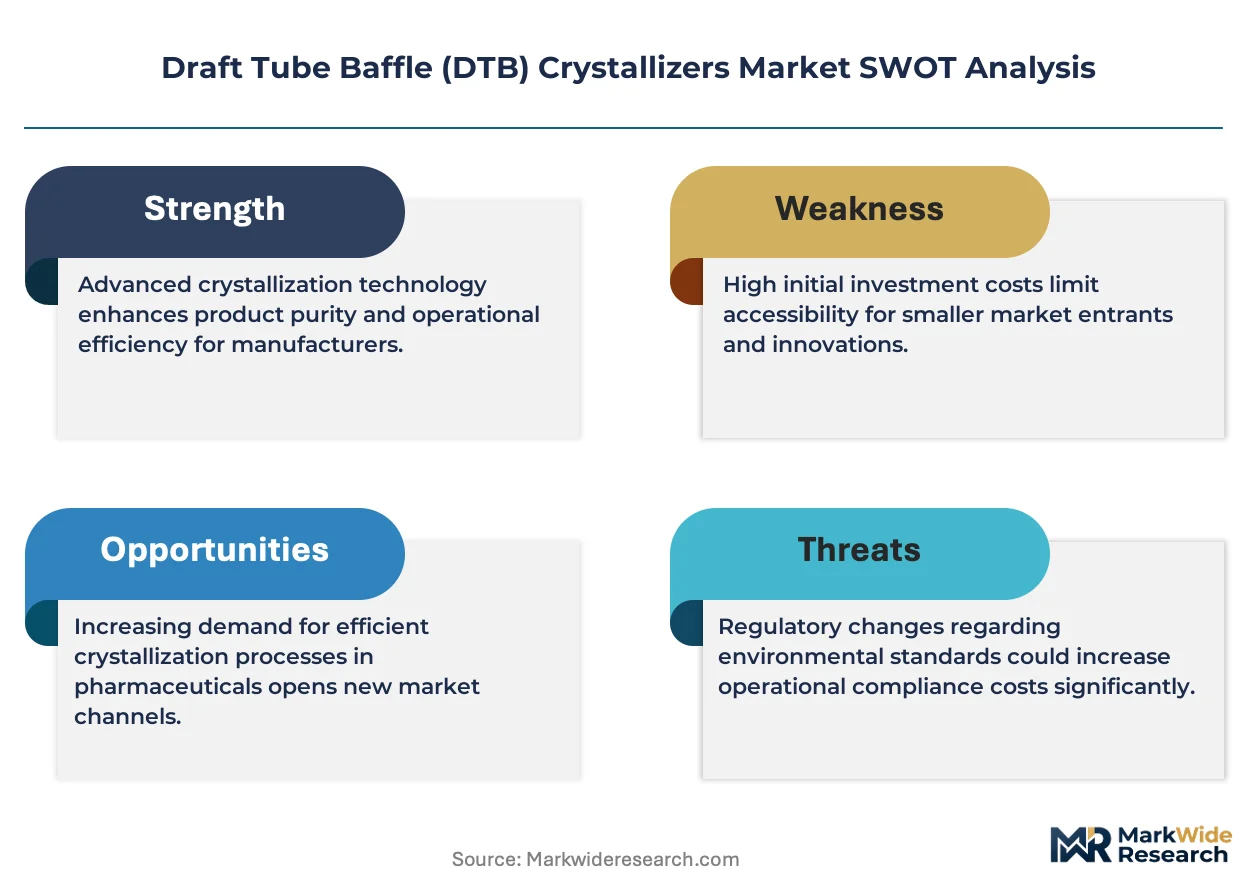
A shortage of process engineers trained in suspension crystallization hydrodynamics is unwinding project timelines across the DTB crystallizer sector. Swenson Technology leverages its century-long specialization in evaporation and crystallization equipment to anchor North American fertilizer and chemical markets. GEA Group sustains a broad geographic footprint through integrated process technology divisions that compete on thermal efficiency and modular system design.
The draft tube baffle crystallizer employs an internal circulation mechanism where a low-speed agitator directs slurry upward through a central draft tube while baffles create a classified suspension zone, enabling controlled crystal growth with narrow particle size distribution. Cylindrical draft tube configurations dominate installed capacity due to standardized pressure vessel fabrication and established scale-up protocols, though continuous crystallization technology is gaining traction in pharma formulator installations where batch-to-batch consistency requirements intensify. Cooling crystallization applications in food additive production occupy mature margin pools, while agricultural chemical processing drives replacement demand for corrosion-resistant alloy construction.
EPA effluent guidelines under the Clean Water Act shape material selection and wastewater handling specifications for DTB crystallizers deployed in US chemical processing facilities, while REACH compliance in Europe restricts certain heat transfer surface coatings and sealing compounds used in pharmaceutical synthesis equipment. India's BIS pressure vessel certification and the PLI scheme for specialty chemicals collectively determine import competitiveness versus domestic fabrication economics for agrochemical suppliers. Stakeholders must monitor evolving crystallization energy benchmarks as jurisdictions tighten carbon intensity rules for process industries.
Market Dynamics
China's GB standards on crystallization energy efficiency are tightening equipment specifications across the DTB crystallizer sector, forcing manufacturers to redesign thermal systems and recalibrate hydrodynamic performance benchmarks.
Growth Catalysts
- Specialty chemical procurement surge:Indian agrochemical formulators under the PLI scheme are expanding DTB crystallizer orders for fertilizer intermediate production.
- EPA effluent compliance:US chemical processors are replacing legacy crystallization systems to meet Clean Water Act wastewater handling specifications.
- Continuous crystallization adoption:Pharmaceutical manufacturers are installing classified suspension systems to achieve batch-to-batch consistency in active ingredient synthesis.
Market Restraints
- Alloy cost volatility:Nickel and molybdenum price swings are compressing margins on corrosion-resistant DTB crystallizer fabrication.
- Engineer scarcity:A shortage of process engineers trained in suspension crystallization hydrodynamics is extending project timelines.
- REACH coating restrictions:ECHA limitations on heat transfer surface coatings are constraining material options for European pharmaceutical equipment.
Strategic Opportunities
- Food additive cooling applications:Mature margin pools in sodium benzoate and citric acid crystallization await efficiency-focused equipment upgrades.
- Gujarat chemical corridor expansion:Domestic agrochemical production clusters are generating localized demand for modular DTB systems.
- Dual carbon alignment:China's MEE energy benchmarks are creating procurement pull for thermally optimized crystallization technology.
Industry Challenges
- Hydrodynamic modeling complexity:Scale-up from pilot to industrial DTB crystallizers requires computational fluid dynamics expertise that remains scarce.
- BIS certification timelines:Indian pressure vessel approval processes are delaying deployment schedules for domestic fabricators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Draft Tube Baffle (DTB) Crystallizers Market |
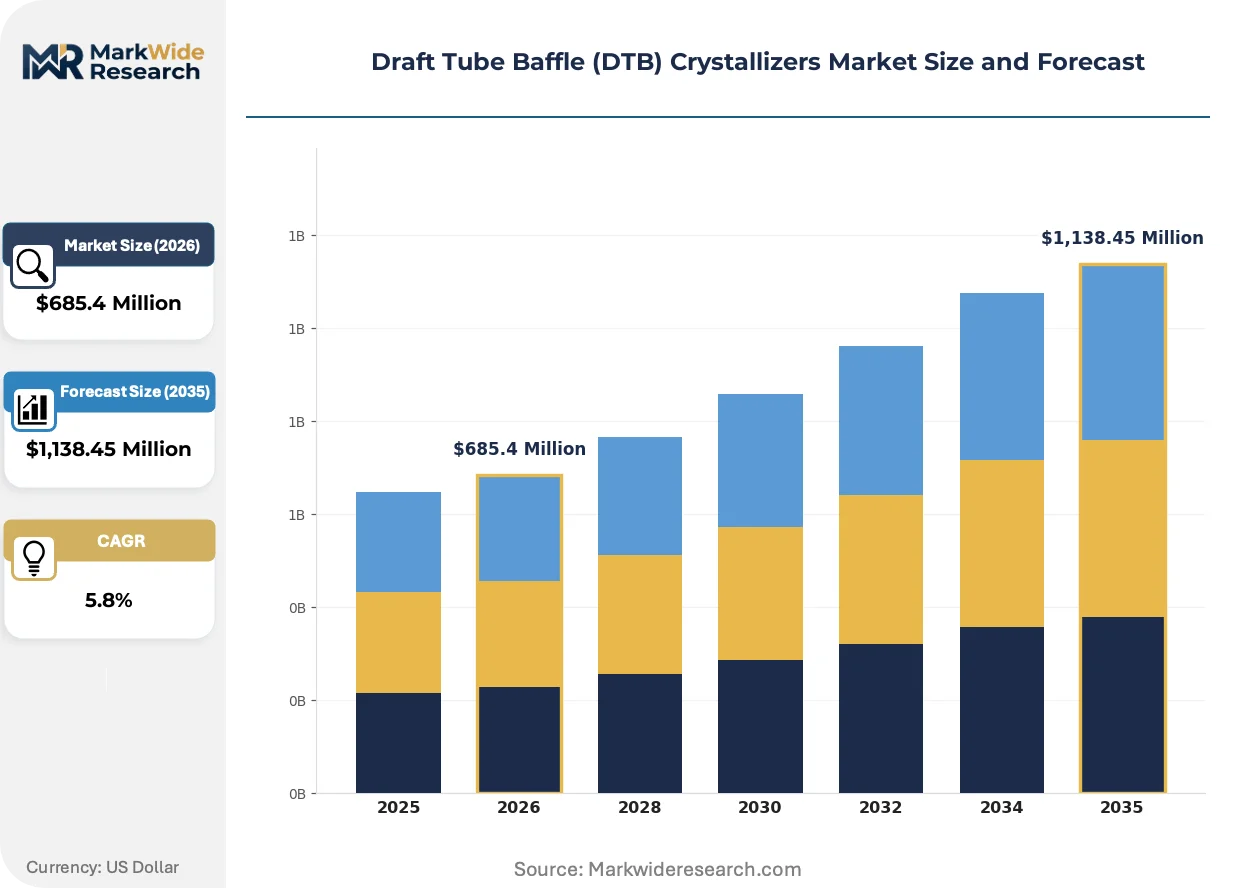
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,138.45 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cylindrical Draft Tube, Rectangular Draft Tube, Spiral Draft Tube, Helical Draft Tube Technology: Batch Crystallization, Continuous Crystallization, Suspension Crystallization, Cooling Crystallization Application: Chemical Processing, Food Additives, Pharmaceuticals Synthesis, Agricultural Chemicals End User: Specialty Chemical Manufacturers, Food Ingredient Producers, Pharma Formulators, Agrochemical Suppliers |
| Companies Covered | France Evaporation, Thermal Kinetics, Swenson Technology, Sulzer Ltd., Chem Process Systems, GEA Group, Ebner GmbH & Co. KG, SPX FLOW, Rosenblad Design Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Draft Tube Baffle (DTB) Crystallizers Market Trends and Innovations
Equipment manufacturers are reconfiguring DTB crystallizer architectures around energy intensity targets and digital process control integration. Three developments are restructuring competitive positioning.
Continuous crystallization technology with real-time particle size monitoring is supplanting batch configurations in pharmaceutical API manufacturing. Formulators seeking narrow crystal size distribution are adopting classified suspension zones with automated withdrawal systems. This shift is compressing demand for conventional batch DTB units in high-value synthesis applications.
REACH compliance in Europe is restricting certain heat transfer surface coatings and sealing compounds used in pharmaceutical synthesis equipment. Manufacturers are reformulating wetted surfaces with compliant alloys and ceramic alternatives. German and Swiss chemical processors are absorbing premium costs for certified construction to maintain EMA-aligned production.
Buyer concentration among specialty chemical multinationals is consolidating procurement authority into centralized engineering teams. Regional distributor networks are losing influence as direct OEM relationships govern large-capacity DTB crystallizer acquisitions. This pattern is most visible in India's agrochemical sector, where integrated producers are bypassing local intermediaries for Swenson and GEA system contracts.
Draft Tube Baffle (DTB) Crystallizers Market Segmentation
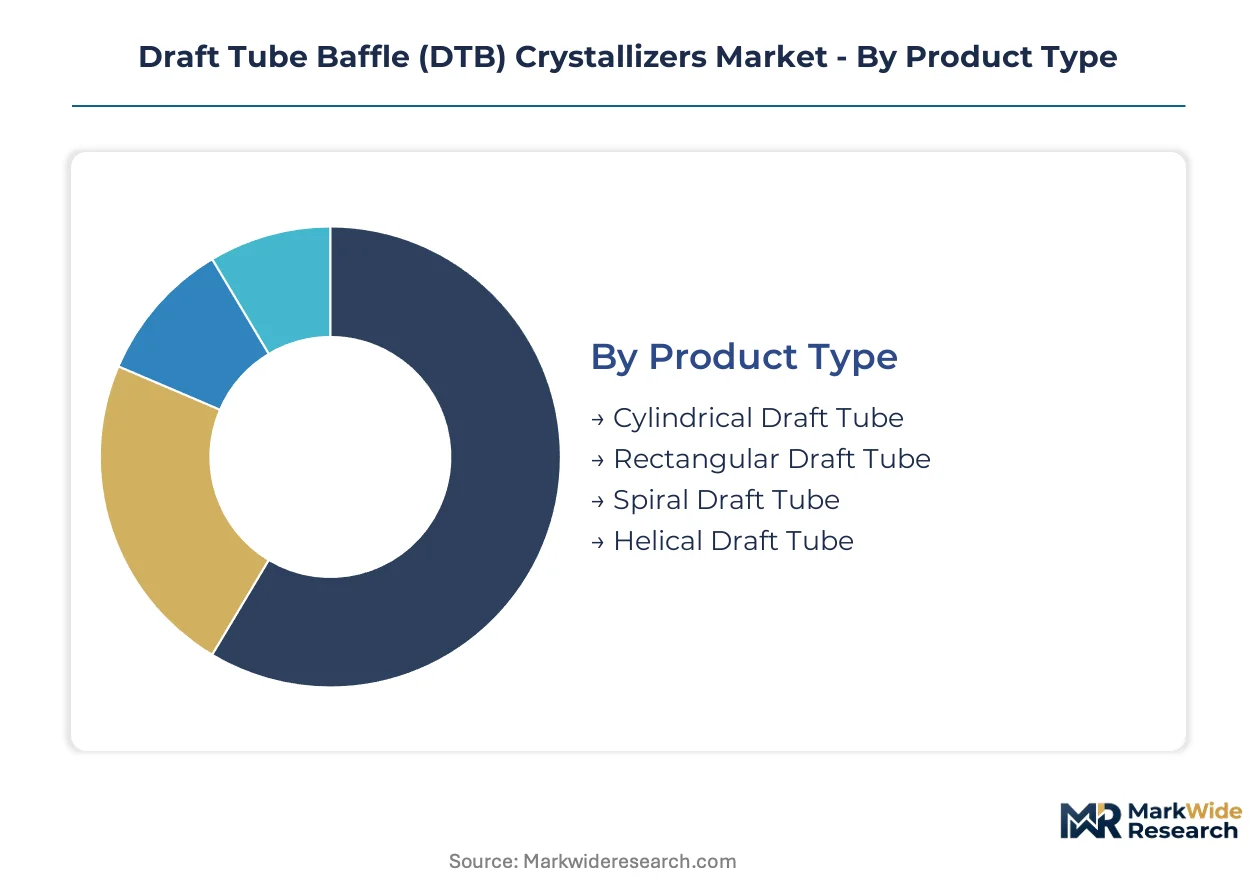
DTB crystallizer procurement patterns diverge sharply across product architectures and operational modes. Technology selection determines capital intensity and regulatory compliance pathways for end-users spanning agrochemical synthesis to pharmaceutical manufacturing.
Product Type:
Rectangular draft tube configurations face acute substitution pressure from cylindrical alternatives as fabricators exploit standardized pressure vessel codes and established scale-up protocols.
- Cylindrical Draft Tube:Circular cross-section geometry enables seamless integration with ASME and BIS pressure vessel certifications. Demand concentrates in Gujarat's chemical corridor where domestic agrochemical producers prioritize fabrication interoperability and maintenance standardization.
- Rectangular Draft Tube:Flat-walled construction suits constrained footprint installations in legacy chemical plants. Adoption remains constrained by non-standard weld inspection protocols and limited vendor qualification pools in India's specialty chemical sector.
- Spiral Draft Tube:Helical internal geometry enhances secondary nucleation control for narrow particle size distribution requirements.
- Helical Draft Tube:Advanced twist configurations serve pharmaceutical formulators demanding precise crystal habit manipulation in API synthesis.
Cylindrical draft tube retains volume leadership; helical draft tube holds the steepest expansion curve.
Technology:
Cost tier stratification separates high-automation continuous systems from capital-light batch configurations serving margin-constrained food additive producers.
- Continuous Crystallization:Steady-state operation with real-time particle size monitoring enables pharmaceutical manufacturers to achieve batch-to-batch consistency in active ingredient synthesis. FDA process analytical technology guidelines are accelerating adoption among US-based pharma formulators.
- Suspension Crystallization:Classified suspension zones with controlled magma density support agricultural chemical processing where corrosion-resistant alloy construction commands premium pricing. China's MEE energy benchmarks are reshaping thermal system specifications for domestic installations.
- Batch Crystallization:Cyclic operation remains dominant in sodium benzoate and citric acid food additive production.
- Cooling Crystallization:Temperature-driven supersaturation control serves mature margin pools in organic acid crystallization.
Batch crystallization dominates installed base; continuous crystallization is climbing the fastest.
Application:
Volume concentration in chemical processing creates procurement scale advantages that pharmaceutical synthesis cannot replicate despite superior margin profiles.
- Chemical Processing:Fertilizer intermediate and commodity chemical production drives replacement demand for corrosion-resistant DTB systems. EPA effluent guidelines under the Clean Water Act are forcing US processors to upgrade legacy crystallization infrastructure.
- Pharmaceuticals Synthesis:Active ingredient manufacturing demands narrow crystal size distribution achievable through classified suspension zone engineering. REACH compliance restrictions on heat transfer surface coatings are constraining European equipment specifications.
- Food Additives:Sodium benzoate and citric acid crystallization occupy mature efficiency-upgrade cycles.
- Agricultural Chemicals:Pesticide and herbicide intermediate production concentrates procurement authority among Indian PLI scheme beneficiaries.
Chemical processing commands volume leadership; pharmaceuticals synthesis holds the steepest expansion curve.
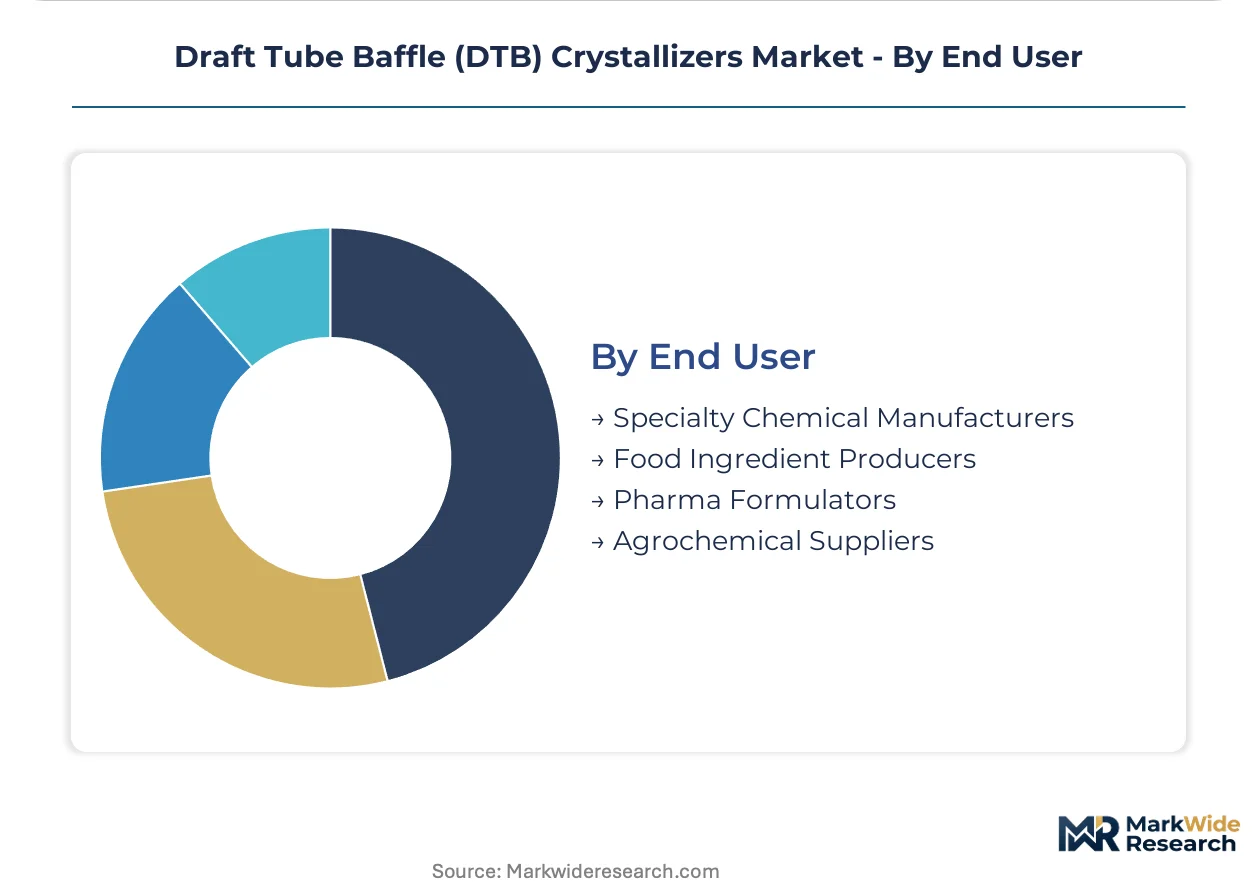
End User:
Customer type fragmentation separates integrated multinationals with centralized engineering teams from regional fabricators dependent on distributor networks.
- Specialty Chemical Manufacturers:Indian agrochemical formulators under the PLI scheme are expanding DTB crystallizer orders for fertilizer intermediate production. Procurement authority is consolidating into direct OEM relationships with Swenson and GEA.
- Pharma Formulators:Multinational drug manufacturers are bypassing regional distributors for certified construction meeting EMA-aligned production standards.
- Food Ingredient Producers:Sodium benzoate specialists prioritize thermal efficiency upgrades in mature margin environments.
- Agrochemical Suppliers:Domestic Indian producers are absorbing BIS certification timeline delays to secure localized fabrication economics.
Specialty chemical manufacturers retain volume leadership; pharma formulators are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MEE energy benchmarks are tightening crystallization equipment specifications across the DTB sector, while India's PLI scheme for specialty chemicals accelerates procurement in Gujarat's chemical corridor.
China
Dual carbon alignment policies are reshaping thermal system specifications for fertilizer intermediate producers. GB standards on crystallization energy efficiency are forcing equipment redesigns and hydrodynamic recalibration. Procurement concentrates in Shandong Peninsula chemical clusters where domestic fabricators absorb MEE compliance costs.
India
Specialty chemical manufacturers under the PLI scheme are scaling DTB crystallizer orders for agrochemical production. BIS pressure vessel certification timelines are delaying deployment schedules for domestic fabricators. Demand clusters in Gujarat's chemical corridor where integrated producers prioritize localized fabrication economics.
United States
EPA effluent guidelines under the Clean Water Act are forcing chemical processors to replace legacy crystallization infrastructure. Wastewater handling specifications are reshaping material selection and equipment configurations. Upgrades concentrate in Gulf Coast petrochemical corridors where corrosion-resistant alloy construction commands premium pricing.
Germany
REACH compliance restrictions on heat transfer surface coatings are constraining pharmaceutical equipment specifications. EMA-aligned production standards are absorbing premium costs for certified construction. Demand localizes in Bavaria's chemical processing belt where formulators seek narrow crystal size distribution systems.
Japan
METI industrial efficiency targets are accelerating thermal optimization investments in chemical processing facilities. JIS standards pressure vessel codes enable seamless fabrication interoperability for domestic suppliers. Procurement clusters in Chubu-Nagoya industrial zones where continuous crystallization technology gains traction among API manufacturers.
Draft Tube Baffle (DTB) Crystallizers Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the DTB crystallizer sector. The vendor base separates into integrated process technology conglomerates, century-specialized evaporation equipment firms, and regional pressure vessel fabricators. Two dominant competitive moves are reshaping positioning: direct OEM relationship consolidation bypassing distributor networks, and thermal system redesign to meet tightening energy efficiency benchmarks.
Among North American specialists, Swenson Technology exemplifies the century-established evaporation and crystallization archetype, while Thermal Kinetics occupies a position within the integrated process solutions tier. European fabricators include Sulzer Ltd. and GEA Group, which represent the diversified industrial technology conglomerate model competing on modular system design and geographic footprint breadth.
| Leading Market Players |
|---|
| France Evaporation |
| Thermal Kinetics |
| Swenson Technology |
| Sulzer Ltd. |
| Chem Process Systems |
| GEA Group |
| Ebner GmbH & Co. KG |
| SPX FLOW |
| Rosenblad Design Group |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at Chinese pressure vessel fabricators shapes price floors across the DTB crystallizer sector, concentrating procurement leverage among domestic agrochemical producers while forcing international suppliers to absorb alloy cost volatility through margin compression.
Pricing Analysis
Geographic price spreads between Indian domestic fabrication and European import alternatives exceed thirty percent for equivalent ASME-certified cylindrical draft tube configurations. Three-tier pricing structure across premium, standard, and economy levels separates corrosion-resistant alloy construction from carbon steel alternatives and refurbished legacy systems. Cost compression in standard-tier equipment is intensifying because nickel and molybdenum price swings compress fabricator margins. Specialty chemical manufacturers in Gujarat exhibit highest price sensitivity, while pharmaceutical formulators seeking EMA-aligned production absorb premium costs for certified construction with minimal negotiation leverage.
Supply Chain Analysis
Extended lead times for BIS pressure vessel certification are stretching procurement cycles for Indian domestic fabricators, creating inventory buffers among integrated agrochemical producers. Manufacturing concentration rests on China, India, and Germany, with Shandong Peninsula clusters feeding Asian demand and Bavarian fabricators serving European pharmaceutical specifications. Nickel alloy plate, precision agitation drives, and ceramic heat transfer coatings constitute critical input dependencies. Single-source vulnerability around engineered agitator assemblies from German suppliers exposes project timelines to disruption. Distribution runs through direct OEM relationships with Swenson and GEA, bypassing regional distributor networks as procurement authority consolidates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
DTB crystallizer adoption sits in early-cycle expansion as continuous crystallization technology displaces batch configurations in pharmaceutical API manufacturing, creating penetration headroom for thermally optimized systems.
For Market Incumbents: Shield market position by deepening backward integration into corrosion-resistant alloy supply chains, capturing margin currently lost to nickel price volatility. Secure BIS pre-certification capacity in Gujarat to compress deployment timelines against domestic fabricator competition. Prioritize hydrodynamic modeling software development to offset engineer scarcity extending project timelines. For New Entrants and Emerging Players: Aftermarket service coverage gaps in India's chemical corridor present white-space entry points where Swenson and GEA maintain limited localized technical support presence. Target food additive cooling crystallization upgrades in mature efficiency cycles where incumbents underinvest. Pursue joint development agreements with Gujarat-based agrochemical formulators seeking modular system standardization. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized hydrodynamic engineering firms with captive CFD capabilities and established pharmaceutical validation track records. Long-term viability hinges on continuous crystallization technology portfolios rather than batch system legacy revenue. Monitor China's MEE energy benchmark enforcement intensity as inflection signal for thermally optimized equipment procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Supply | Captive nickel and molybdenum sourcing insulates margins from commodity volatility affecting corrosion-resistant fabrication. |
| Continuous Crystallization Platform Launch | Real-time particle size monitoring capabilities capture pharmaceutical formulator demand for batch-to-batch consistency. |
| BIS Pre-Certification Investment | Compressed deployment timelines in Gujarat's chemical corridor secure procurement preference among PLI scheme beneficiaries. |
| Hydrodynamic Modeling Software Development | Computational fluid dynamics expertise scarcity creates differentiation against competitors dependent on external engineering resources. |
| Pharmaceutical Validation Partnership | FDA process analytical technology alignment opens high-margin API synthesis equipment procurement channels. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs, incorporating plant engineers at Indian agrochemical facilities, procurement leads at specialty chemical multinationals, aftermarket service heads at regional fabricators, and technical R&D directors at crystallization equipment OEMs. Secondary validation drew from BIS certification databases, SEC 10-K filings of listed process technology conglomerates, customs trade data on pressure vessel imports, and ACC industry reports. Bottom-up unit economics triangulated against top-down market sizing from installed base estimates.
Across the analysis window, the forecast framework modeled volume and value outputs through segmentation across product architecture, operational technology, end-use application, and customer type. CAGRs were derived from regression analysis against historical procurement patterns and forward-looking regulatory enforcement timelines. Alloy cost indices, BIS certification throughput rates, and pharmaceutical facility capital expenditure cycles served as industry-specific forecast inputs.
Material uncertainties — regulatory enforcement intensity, alloy commodity price trajectories, and process engineer labor market tightness — sit outside the modeled envelope and could compress or extend projected expansion rates. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Screw Separators Market
Industrial Chemicals
Monoethanol Amine Market
Industrial Chemicals
Electro-Erosion Fluids Market
Industrial Chemicals
Chemical Reactors Market
Industrial Chemicals
Global Bio Based Isoprene Market
Industrial Chemicals
Fabric Starch Market
Industrial Chemicals
Europe Surface Treatment Chemicals Market
Industrial Chemicals
Middle-East and Africa Surface Treatment Chemicals Market
Industrial Chemicals
Gypsum-Based Products Market
Industrial Chemicals
Cryogenic Column Market
Industrial Chemicals
Hydrogen Silicone Fluid Market
Industrial Chemicals
Chemical Process Mixers Market
Industrial Chemicals
1,3-Propanediol (PDO) Market
Industrial Chemicals
Global Alkylated Naphthalene Market
Industrial Chemicals
Proline Market
Industrial Chemicals
Deoxidant Market