
 Pickling Chemicals Market | 2026-2036
Pickling Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Pickling Chemicals Market Analytics
Phosphoric acid formulations is hardening as the preferred substitute for hydrochloric acid in precision metal finishing, reducing hydrogen embrittlement risks while maintaining oxide removal efficiency. BASF SE leverages its integrated phosphate chemistry portfolio to supply buffered pickling solutions for automotive OEMs. Solvay S.A. anchors European supply through specialized acid blends tailored to aerospace-grade titanium processing. PVS Chemicals, Inc. dominates North American bulk distribution with captive rail logistics and regional blending facilities.
Pickling chemicals are acidic formulations designed to remove surface oxides, scale, and corrosion products from metals, typically operating at concentrations between 5-25% and temperatures ranging from ambient to 90°C depending on substrate and acid selection. The metal surface treatment application leads volume consumption as steel mills and coil processors require continuous descaling ahead of cold rolling and galvanizing. Hydrochloric acid occupies the largest product type share due to its aggressive oxide dissolution kinetics and lower cost per treated ton, though citric acid represents the fastest-growing category as biodegradable formulations gain favor in food-contact equipment and precision electronics cleaning where residue sensitivity is paramount.
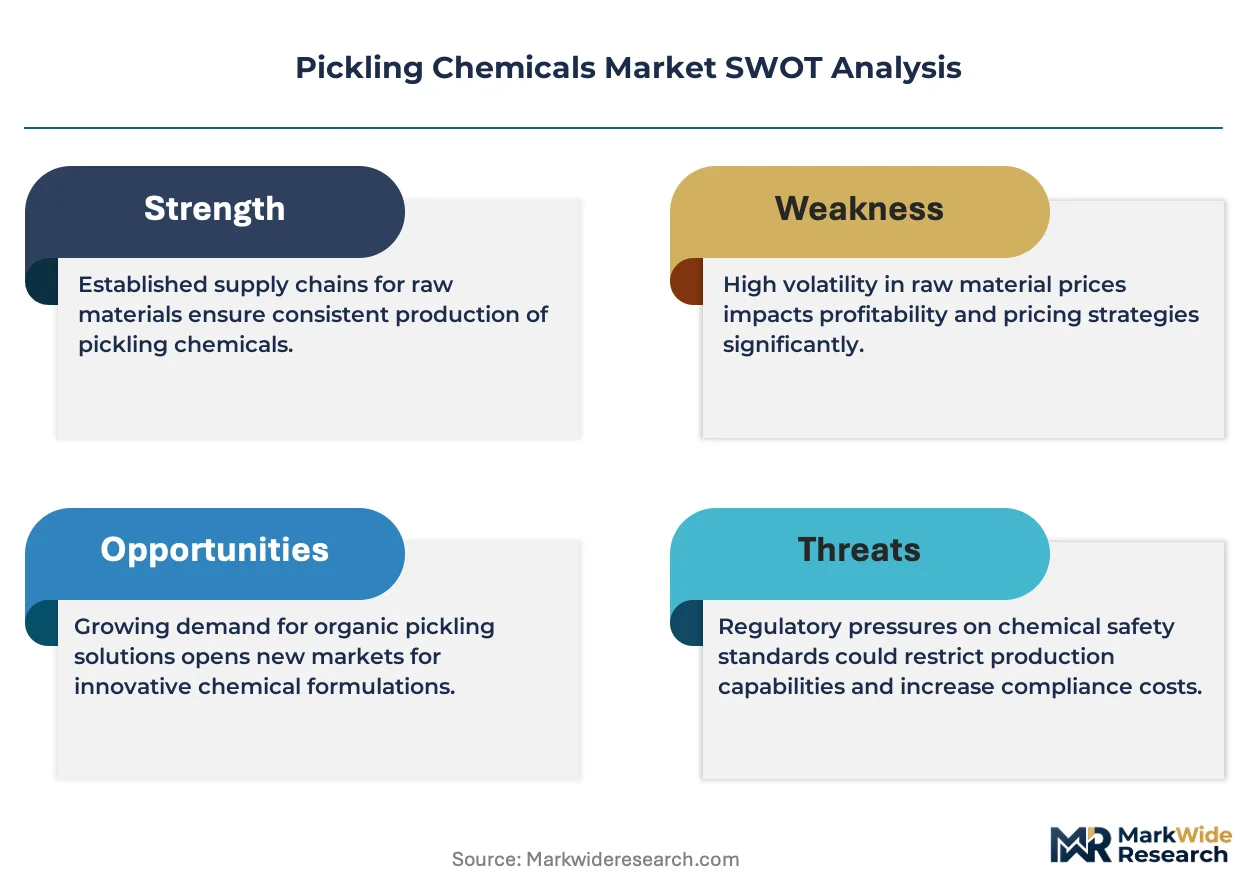
The EPA regulates spent pickle liquor under the Resource Conservation and Recovery Act, forcing processors to invest in acid regeneration or neutralization infrastructure that raises operating costs but creates demand for longer-bath-life formulations. REACH registration requirements in Europe constrain novel acid introductions while favoring established suppliers with complete substance dossiers. OSHA permissible exposure limits for hydrogen chloride vapor shape workplace engineering controls and drive substitution toward lower-fuming alternatives. Stakeholders must monitor evolving state-level restrictions on hexavalent chromium co-treatments and assess whether emerging nitric-free pickling protocols will disrupt existing supply relationships.
Market Dynamics
EPA emission standards on spent pickle liquor disposal are forcing stainless steel fabricators toward acid regeneration systems and longer-bath-life formulations, restructuring cost economics across metal surface preparation operations.
Growth Catalysts
- Automotive lightweighting mandates:OEMs require precision descaling of high-strength steel alloys for chassis and powertrain components, sustaining acid consumption volumes at tier-1 suppliers.
- REACH registration dossiers:Established European suppliers with complete substance documentation capture share as novel acid introductions face regulatory friction and extended approval timelines.
- China steel output dominance:Continuous expansion of hot-rolled coil capacity in Hebei and Jiangsu provinces sustains regional demand for hydrochloric acid-based pickling lines.
Market Restraints
- Input cost volatility:Sulfuric acid and hydrochloric acid prices track energy markets and chlorine-alkali capacity utilization, compressing processor margins during feedstock spikes.
- Geographic supply concentration:Bulk acid production clusters along the US Gulf Coast and Rhine-Ruhr corridor expose buyers to logistics disruptions from hurricane or riverine flooding events.
- Substitution threat from laser cleaning:Dry ablation systems eliminate wastewater disposal burdens for precision components in aerospace maintenance, though capital costs limit penetration.
Strategic Opportunities
- India specialty steel expansion:PLI scheme incentives for stainless steel and electrical steel production create virgin demand for phosphoric and nitric acid formulations at greenfield mills.
- Biodegradable citric acid protocols:Food-contact equipment manufacturers adopt residue-neutral cleaning to satisfy FDA sanitation requirements without neutralization infrastructure.
- Acid regeneration technology convergence:Integration of membrane electrolysis with thermal spray roasting enables closed-loop operations that extend bath life threefold.
Industry Challenges
- Process engineer scarcity:Deep expertise in acid concentration management and hydrogen embrittlement prevention has concentrated among retiring specialists at legacy steel mills.
- Legacy system integration friction:Continuous pickling lines built in the 1980s require custom retrofitting to accommodate lower-fuming acid blends and vapor capture hoods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pickling Chemicals Market |
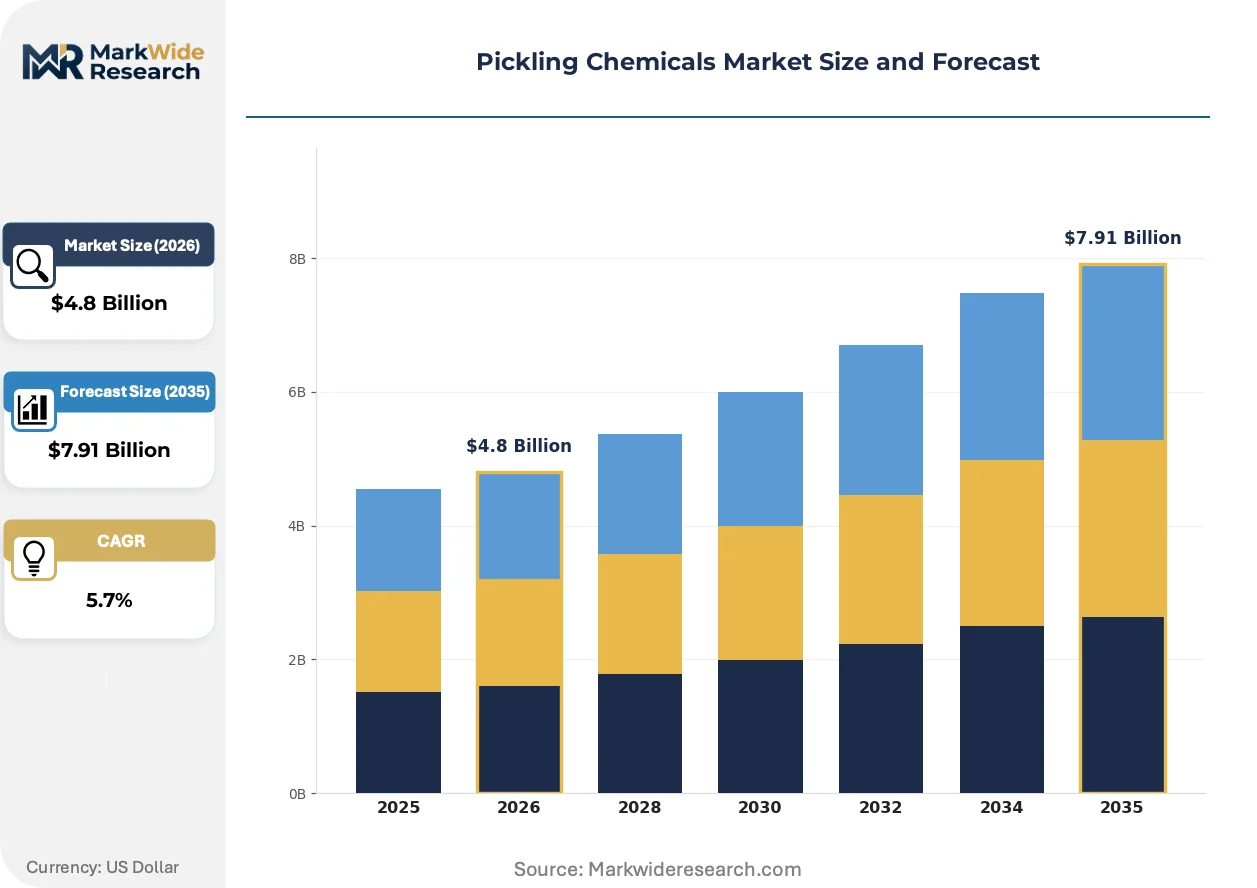
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Citric Acid, Phosphoric Acid, Hydrochloric Acid, Sulfuric Acid Application: Metal Surface Treatment, Textile Industry, Food Processing, Oil & Gas End User: Manufacturers, Service Providers, Construction, Automotive Distribution Channel: Direct Sales, Distributors, Online Sales, Retail |
| Companies Covered | Solvay S.A., Dow Inc., BASF SE, PVS Chemicals, Inc., Kemira Oyj, Henkel AG & Co. KGaA, Quaker Houghton, Chemetall GmbH, The Sherwin-Williams Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pickling Chemicals Market Evolving Landscape
Formulation chemistry and disposal economics are converging to reshape competitive positioning, with biodegradable alternatives and closed-loop regeneration systems displacing conventional single-use acid baths.
Electrolytic pickling is unifying oxide removal and surface passivation in a single-stage process for stainless steel strip. German coil processors have adopted this technology for precision automotive-grade material, eliminating separate neutralization tanks. The process compresses line footprint by forty percent while reducing acid consumption, unifying environmental compliance with capital efficiency targets.
REACH authorization requirements for chromium trioxide in passivation layers have forced European suppliers to accelerate nitric-free pickling protocols. The restriction affects aerospace-grade titanium processors most severely, who must validate alternative surface activation methods without hexavalent chromium conversion coatings. German KBA certification timelines for automotive safety components have extended eighteen months as a result.
Steel service centers are consolidating procurement through annual framework contracts with acid regeneration service providers rather than spot purchases of virgin chemicals. This model transfers bath maintenance liability to specialized operators who monitor concentration and metal saturation remotely. The shift is most visible in the US Great Lakes region where toll processors serve fragmented automotive stampers.
Pickling Chemicals Market Segmentation
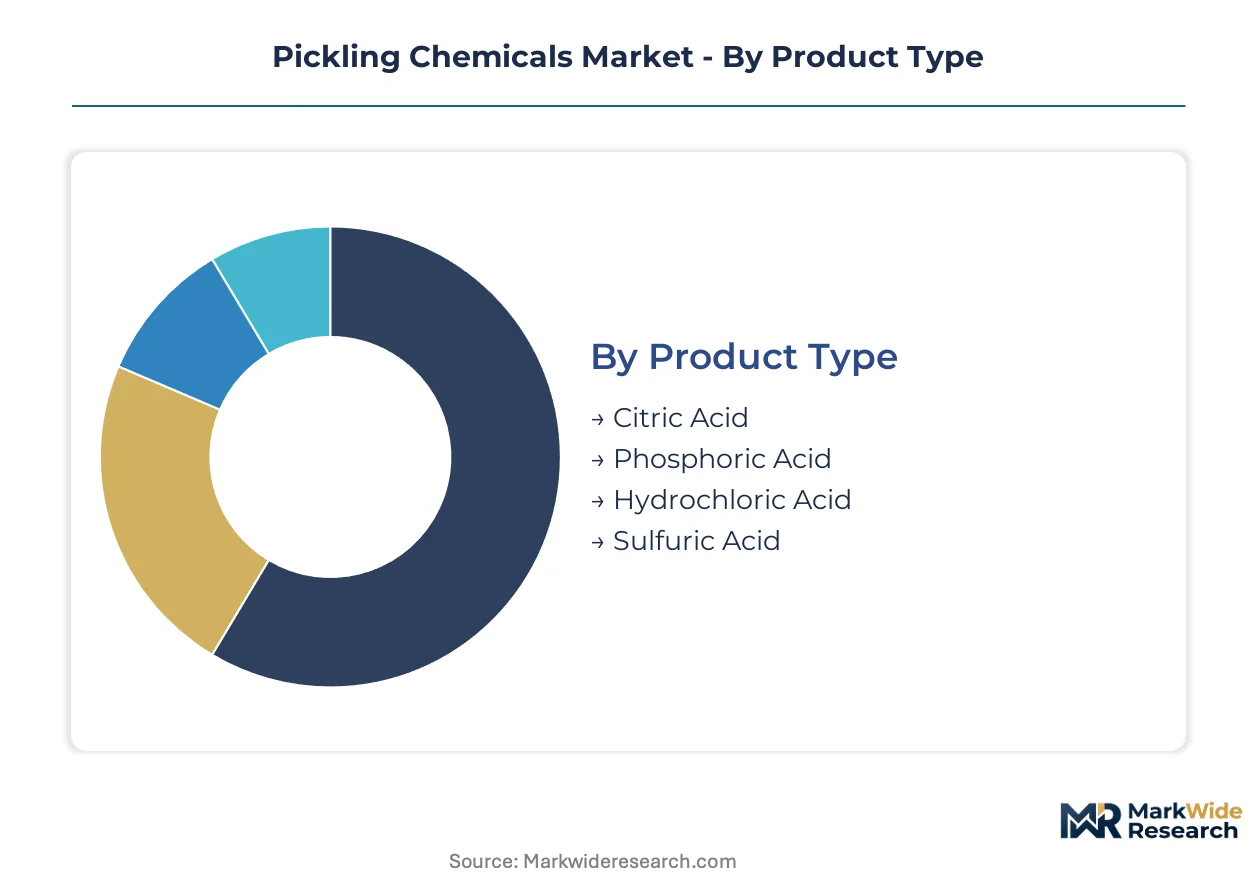
Pickling chemical buyers navigate distinct compliance landscapes depending on acid chemistry and end-use exposure. Segmentation reveals where REACH dossier completeness, FDA food-contact approvals, and OSHA exposure limits concentrate procurement decisions among qualified suppliers.
Product Type:
Certification burdens cluster around acid volatility and residue toxicity, with REACH-registered formulations commanding premium positioning in European automotive supply chains.
- Hydrochloric Acid:Formulations operate at 5-25% concentration with aggressive oxide dissolution kinetics for continuous steel mill descaling. Demand concentrates in Hebei province steel clusters where hot-rolled coil capacity expansion sustains bulk consumption despite hydrogen chloride vapor exposure controls mandated by OSHA and China's MEE.
- Citric Acid:Biodegradable formulations eliminate neutralization infrastructure for food-contact equipment and precision electronics cleaning. FDA sanitation requirements and residue sensitivity in Swiss pharmaceutical packaging equipment are accelerating substitution away from mineral acids where wastewater disposal costs dominate.
- Phosphoric Acid:Buffered solutions reduce hydrogen embrittlement risks in high-strength automotive steel alloys. BASF SE leverages integrated phosphate chemistry for OEM supply.
- Sulfuric Acid:Lower-cost alternative for heavy scale removal in construction steel and rail infrastructure, constrained by sulfur dioxide emission regulations.
Hydrochloric acid sits at the top of the volume ranking, with citric acid climbing the fastest.
Application:
Cost tier stratification separates continuous industrial processing from batch specialty operations, with capital intensity determining acid selection and service model.
- Metal Surface Treatment:Continuous pickling lines at steel mills and coil processors represent the highest-volume consumption tier. Acid regeneration service contracts dominate the US Great Lakes automotive stamping corridor, transferring bath maintenance liability to specialized operators.
- Food Processing:Equipment sanitization protocols favor citric acid formulations to satisfy FDA residue limits without neutralization infrastructure. Swiss and German dairy equipment manufacturers specify biodegradable cleaning to align with EU Green Deal wastewater targets.
- Oil & Gas:Pipeline descaling and wellbore cleanup operations in the US Permian Basin and Saudi Aramco fields require acid blends compatible with high-pressure pumping systems.
- Textile Industry:Yarn and fabric preparation uses dilute acid baths for pH adjustment and impurity removal, concentrated in India's Tiruppur cluster and Bangladesh's Dhaka export zones.
Metal surface treatment commands the highest volume tier, with food processing gaining share fastest on regulatory tailwinds.
End User:
Customer type determines procurement sophistication, with integrated manufacturers capturing cost advantages through captive regeneration versus fragmented service providers dependent on spot markets.
- Automotive:Tier-1 chassis and powertrain suppliers require precision descaling of high-strength steel alloys under German KBA certification timelines. OEM lightweighting mandates sustain acid consumption volumes despite laser cleaning substitution threats for precision components.
- Manufacturers:Integrated steel mills and coil processors with continuous pickling lines built in the 1980s face retrofit friction for lower-fuming acid blends and vapor capture hoods.
- Service Providers:Toll processors and metal finishing job shops in fragmented markets depend on distributor relationships and spot acid purchases without regeneration infrastructure.
- Construction:Structural steel fabricators for commercial and infrastructure projects use lower-specification acid baths with minimal environmental controls in emerging markets.
Automotive end users anchor the premium tier, with service providers expanding most quickly as toll processing models proliferate.
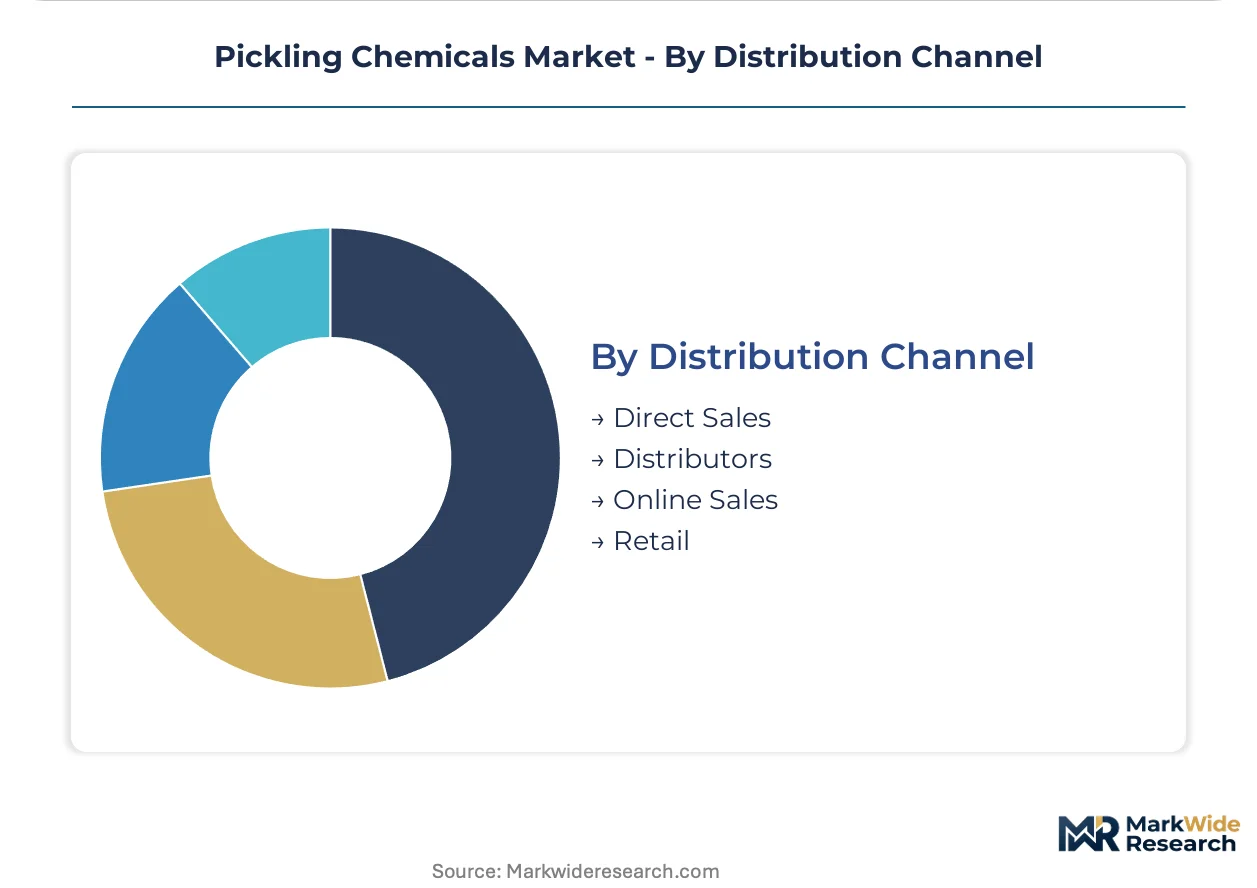
Distribution Channel:
Supply concentration along the US Gulf Coast and Rhine-Ruhr corridor shapes logistics economics, with rail-served bulk terminals commanding regional market control.
- Distributors:PVS Chemicals dominates North American bulk distribution through captive rail logistics and regional blending facilities. Regional distributors capture fragmented automotive stamper demand in the US Midwest.
- Direct Sales:BASF SE and Solvay S.A. supply automotive OEMs and aerospace-grade titanium processors through long-term framework contracts with embedded technical service.
- Online Sales:Specialty citric acid formulations and smaller-volume precision cleaning chemicals reach food-contact equipment manufacturers and electronics assemblers.
- Retail:Consumer-grade pickling products for hobbyist metalworkers and small maintenance operations represent minimal volume.
Distributors control the highest volume flows, with direct sales climbing fastest as annual framework contracts consolidate procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hebei province steel clusters anchor global pickling chemical consumption, with continuous hot-rolled coil expansion sustaining acid demand across multiple geographies.
United States
Automotive chassis suppliers in Michigan and Ohio sustain hydrochloric acid volumes through precision descaling contracts. EPA enforcement of spent pickle liquor disposal under RCRA forces acid regeneration investments at legacy mills. Great Lakes toll processors consolidate procurement through annual framework agreements with specialized bath maintenance operators.
Germany
KBA certification timelines for automotive safety components extend eighteen months as nitric-free protocols replace hexavalent chromium passivation. REACH authorization requirements for chromium trioxide disrupt aerospace-grade titanium processing. Coil processors in North Rhine-Westphalia adopt electrolytic pickling to compress line footprint by forty percent.
China
MEE emission standards tighten around hydrogen chloride vapor exposure at steel facilities in Jiangsu province. Dual carbon goals accelerate acid regeneration technology deployment at state-owned mills. Hot-rolled coil capacity expansion in Tangshan sustains bulk hydrochloric acid consumption despite environmental compliance costs.
India
PLI scheme incentives for stainless steel and electrical steel production create virgin demand for phosphoric formulations at greenfield specialty mills. FSSAI sanitation requirements drive citric acid adoption in dairy equipment manufacturing. Tiruppur textile clusters use dilute acid baths for yarn preparation pH adjustment.
Japan
METI industrial efficiency targets push precision electronics manufacturers toward residue-neutral citric acid cleaning. JIS standards constrain novel acid introductions while favoring established suppliers with complete documentation. Kansai region metal finishers retrofit 1980s continuous lines for lower-fuming acid blends and vapor capture hoods.
Pickling Chemicals Market Competitive Landscape
Global majors compete with regional champions across formulation chemistry and logistics infrastructure. The vendor base separates into integrated phosphate chemistry suppliers, bulk acid distributors with captive rail networks, and specialized blenders serving aerospace-grade requirements. Three archetypes dominate: diversified chemical conglomerates with acid portfolios, regional distributors controlling terminal access, and toll processors embedding technical service into procurement contracts. Competitive moves center on acid regeneration service partnerships and backward integration into phosphate rock or chlorine-alkali feedstocks.
Among diversified chemical conglomerates, BASF SE and Solvay S.A. exemplify integrated phosphate chemistry positioning, while PVS Chemicals, Inc. anchors North American bulk distribution through regional blending facilities. These three occupy distinct competitive spaces: one leverages captive phosphate chemistry for automotive OEM supply, another supplies specialized acid blends for aerospace-grade titanium processing, and the third dominates rail-served terminal logistics across the US Midwest.
| Leading Market Players |
|---|
| Solvay S.A. |
| Dow Inc. |
| BASF SE |
| PVS Chemicals, Inc. |
| Kemira Oyj |
| Henkel AG & Co. KGaA |
| Quaker Houghton |
| Chemetall GmbH |
| The Sherwin-Williams Company |
| Others |
Value Network & Pricing Analysis
Chlor-alkali capacity utilization indices and sulfur-based feedstock benchmarks cascade through hydrochloric acid and sulfuric acid production economics, compressing processor margins during energy market spikes while rewarding buyers with captive regeneration infrastructure. Contract structures stratify across acid regeneration service providers, spot bulk purchasers, and integrated steel mills with in-house bath management, with pricing power concentrating among rail-served terminal operators.
Pricing Analysis
Input cost pass-through from chlorine-alkali and phosphate rock feedstocks governs contract negotiations, with hydrochloric acid formulations tracking energy market volatility more tightly than buffered phosphoric alternatives. Three-tier pricing structure across premium, standard, and economy levels separates REACH-registered specialty blends from commodity bulk acid and unregistered regional supply, with certification completeness and vapor capture compatibility as primary differentiation drivers. Pricing pressure stems from sulfuric acid spot market softness in construction steel applications. Automotive OEM procurement teams exhibit lowest price sensitivity due to KBA certification lock-in, while textile processors in South Asia operate at highest cost elasticity.
Supply Chain Analysis
Regional distribution centers along the US Gulf Coast and Rhine-Ruhr corridor anchor hub-and-spoke bulk acid logistics, with PVS Chemicals' captive rail networks commanding Midwest automotive corridor access. Bulk production clusters in China, Germany, and the United States feed global supply, drawing from chlorine-alkali capacity, phosphate rock mining, and sulfur recovery operations. Single-source vulnerability concentrates around hurricane exposure at Gulf Coast terminals and riverine flooding risk at Rhine-Ruhr blending facilities. Distribution runs through annual framework contracts with regeneration service providers rather than spot purchasing, transferring bath maintenance liability to specialized operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage opportunities crystallize around acid regeneration infrastructure gaps, with EPA enforcement costs in the United States running substantially above MEE compliance burdens in China for equivalent steel output volumes.
For Market Incumbents: Hedge exposure to hydrochloric acid feedstock volatility through backward integration into chlorine-alkali capacity or phosphate rock mining, while accelerating citric acid formulation R&D to capture food-contact equipment substitution demand. Laser cleaning technology threatens precision component descaling revenue streams. Defend automotive OEM relationships through embedded technical service contracts that extend KBA certification support. For New Entrants and Emerging Players: PLI scheme incentives in India open a window for phosphoric acid supply partnerships at greenfield stainless steel mills, bypassing entrenched European and Chinese supplier relationships. Citric acid protocols for Swiss pharmaceutical packaging equipment represent the most penetrable white-space target, with biodegradable residue profiles satisfying EU Green Deal wastewater targets without neutralization capital. Go-to-market positioning should emphasize FDA sanitation compliance bundled with remote bath monitoring services. For Investors and Strategic Acquirers: Asymmetric upside sits with acid regeneration technology specialists possessing membrane electrolysis and thermal spray roasting integration capabilities, as steel service centers consolidate procurement through toll processing models. Five-to-ten year viability hinges on closed-loop chemistry adoption rates. Acquisition targets should demonstrate captive rail terminal access or complete REACH dossier portfolios. Watch for MEE emission standard tightening in Jiangsu province as inflection indicator for Chinese state-owned mill regeneration investment velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphate Rock Mining | BASF SE secures captive phosphate chemistry feedstock for automotive OEM buffered formulations. |
| Acid Regeneration Technology Convergence | Membrane electrolysis integration extends bath life threefold at US Great Lakes toll processors. |
| Biodegradable Citric Acid Protocol Expansion | Swiss dairy equipment manufacturers adopt residue-neutral cleaning to satisfy FDA sanitation requirements. |
| Long-term Framework Contract Consolidation | Steel service centers transfer bath maintenance liability to specialized operators with remote monitoring. |
| Joint Venture for Greenfield Specialty Mill Supply | PLI scheme incentives in India create virgin demand for phosphoric formulations at electrical steel facilities. |
Research Methodology
Bottom-up steel mill and coil processor consumption modeling reconciled against top-down chlorine-alkali capacity tracking forms the analytical core of this study. Primary interviews with plant managers at continuous pickling lines, procurement leads at automotive Tier 1 suppliers, acid regeneration service operators, and technical R&D directors at formulation specialists were combined with secondary validation from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings from diversified chemical conglomerates, and EPA enforcement action databases. Triangulation across these sources calibrated volume estimates and price elasticity assumptions.
Input-output matrices mapped acid consumption intensity per ton of hot-rolled and cold-rolled steel output across product type, application, end user, and regional production hub segmentation dimensions. CAGRs were derived from regression analysis of historical capacity expansion announcements, regulatory compliance cost trajectories, and substitution threat penetration curves. Industry-specific forecast inputs included KBA certification timeline extensions for nitric-free protocols and MEE emission standard implementation schedules at Chinese state-owned mills.
Revisions become necessary when REACH authorization requirements accelerate, acid regeneration technology cost curves shift, or laser cleaning capital costs decline below threshold penetration levels for aerospace maintenance applications. Forecasts reflect assumptions about regulatory enforcement consistency and feedstock energy market correlation. Stakeholders should weight assumptions against their own operating context and captive infrastructure positions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
FCCL Coating Machine Market
Industrial Chemicals
Carbon Molecular Sieves Market
Industrial Chemicals
Global Antifreeze Market
Industrial Chemicals
Propylene Oxide Market
Industrial Chemicals
2,3-Butanediol Market
Industrial Chemicals
Technical Enzymes Market
Industrial Chemicals
Quicklime Market
Industrial Chemicals
Diisononyl Phthalate (DINP) Market
Industrial Chemicals
Tall Oil Fatty Acid Market
Industrial Chemicals
Global Industrial Anti Scaling Chemical Market
Industrial Chemicals
Froth Flotation Chemicals Market
Industrial Chemicals
Food Grade Grease Market
Industrial Chemicals
Gypsum Market
Industrial Chemicals
Methylene Diphenyl Di-Isocyanate (MDI) Market
Industrial Chemicals
Global Bio Based Isoprene Market
Industrial Chemicals
Diisobutylaluminum Chloride Market