
 Toluene Diisocyanates (TDI) Market | 2026-2036
Toluene Diisocyanates (TDI) Market Size, Share, and Industry Trends Forecast 2026-2036
Toluene Diisocyanates (TDI) Market Analytics
Technical service contracts for formulation optimization is broadening what TDI suppliers monetize beyond commodity volumes. Covestro AG leverages its polyurethane application laboratories to anchor long-term supply agreements with automotive seating manufacturers. Wanhua Chemical Group Co., Ltd sustains cost leadership through backward integration into nitric acid and aniline production at its Ningbo complex. BASF SE differentiates via specialty TDI grades for high-performance coatings.
Toluene diisocyanates are aromatic diisocyanates produced through nitration of toluene followed by phosgenation, yielding isomer mixtures typically containing 80% 2,4-TDI and 20% 2,6-TDI with functionality critical for polyurethane polymerization. The compound serves primarily as a reactive monomer for flexible polyurethane foams, coatings, and elastomer systems requiring controlled cross-linking density. Foam applications command the largest volume share within the application dimension, driven by bedding and automotive seating demand, while specialty TDI commands premium pricing due to low-volume custom formulations for industrial coatings. The end use industry dimension shows furniture outpacing construction in growth velocity as residential renovation cycles accelerate in emerging economies.
REACH registration requirements in Europe mandate comprehensive toxicological dossiers that constrain market entry for non-integrated producers, while China's MEE enforces stricter emissions controls at TDI manufacturing facilities. The EPA's TSCA framework in the United States influences product stewardship protocols and downstream handling standards. Buyers should monitor regulatory divergence between jurisdictions as it reshapes cost structures and supplier qualification requirements.
Market Dynamics
Technical service contracts for formulation optimization are broadening what TDI suppliers monetize beyond commodity volumes, anchoring long-term supply agreements through embedded application expertise rather than spot pricing alone.
Growth Catalysts
- REACH registration dossiers:Comprehensive toxicological requirements in Europe constrain market entry for non-integrated producers, consolidating volume with established registrants who capture displaced demand.
- Furniture sector procurement:Polyurethane foam producers are expanding volumes for bedding and seating applications as residential renovation cycles accelerate in emerging economies.
- Shanghai chemical corridor concentration:Manufacturing clusters around the Yangtze River Delta benefit from integrated logistics and feedstock access, lowering delivered costs for regional converters.
Market Restraints
- Toluene feedstock volatility:Crude-linked aromatic pricing transmits cost instability to TDI producers lacking captive naphtha cracking or refinery integration.
- Supplier concentration risk:Backward-integrated producers in East Asia control nitric acid and aniline supply chains, creating dependency for non-integrated compounders in other regions.
- Aliphatic diisocyanate substitution:HDI and IPDI grades penetrate high-performance coatings where UV stability and color retention outweigh TDI cost advantages.
Strategic Opportunities
- India construction chemicals:Underpenetrated rigid foam and coating applications in commercial building insulation offer volume expansion as urbanization intensifies.
- GB standard compliance services:China's tightening chemical emissions frameworks create paid advisory revenue streams for suppliers with in-house regulatory affairs capabilities.
- Automotive lightweighting convergence:Integration of TDI-based elastomers with composite structural components enables seating and interior module weight reduction programs.
Industry Challenges
- Phosgene handling certification:Specialized safety training and equipment maintenance requirements extend commissioning timelines for new production assets.
- Legacy formulation integration:Custom polyurethane systems developed for specific TDI isomer ratios resist rapid substitution when supply disruptions force grade switching.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Toluene Diisocyanates (TDI) Market |
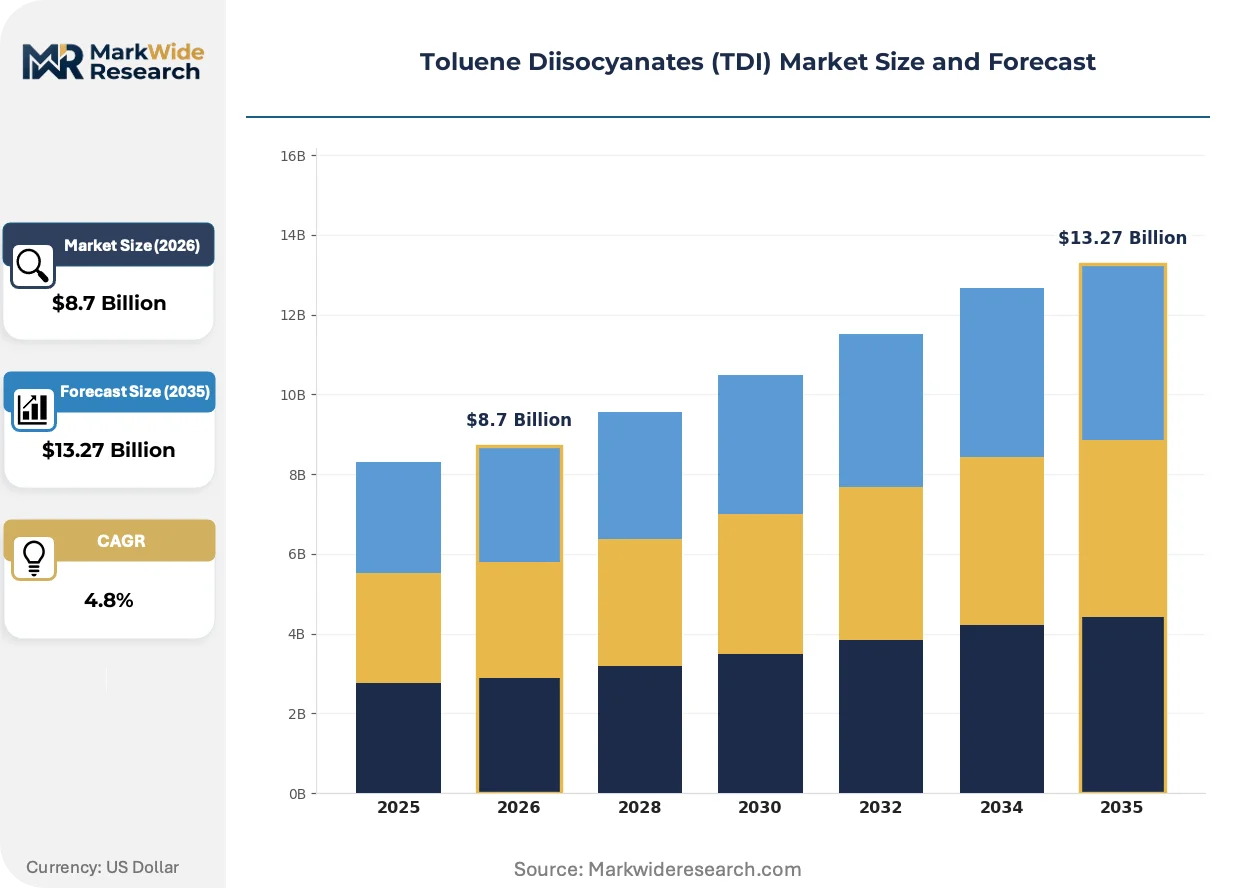
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.27 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
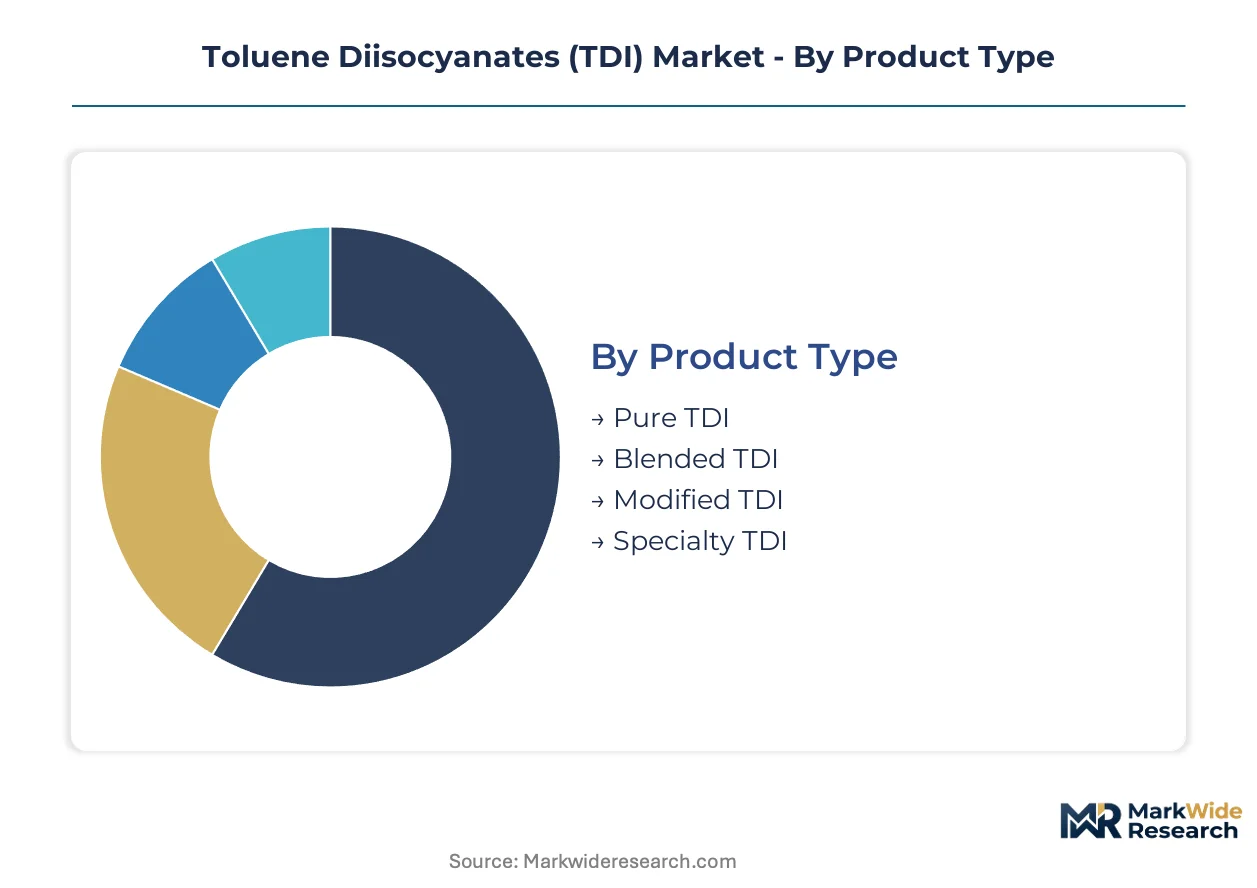
| Segmentation | Product Type: Pure TDI, Blended TDI, Modified TDI, Specialty TDI End Use Industry: Automotive, Construction, Furniture, Footwear Application: Coatings, Adhesives, Elastomers, Foam Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesalers |
| Companies Covered | Dow, Evonik, Covestro AG, Mitsui Chemicals, Inc., Tosoh, BASF SE, SABIC, Cangzhou Dahua Group, Wanhua Chemical Group Co., Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Toluene Diisocyanates (TDI) Market Evolving Landscape
Reformulation toward lower-emission polyurethane systems is compressing the viable window for conventional TDI grades while elevating demand for purified isomer variants and application-optimized blends.
Prepolymer technology is overtaking conventional TDI polyol blending in automotive seating manufacturing. Tier-1 suppliers are adopting quasi-prepolymer systems to reduce free monomer content and stabilize viscosity profiles. This shift is overtaking traditional batch processing lines and forcing compounders to retool mixing equipment for narrower molecular weight distributions.
China's MEE emissions enforcement at TDI manufacturing facilities is tightening vent gas treatment and wastewater discharge parameters. Facilities must install catalytic oxidation units and closed-loop scrubbing systems to maintain operating permits. Specialty TDI grades for coatings applications face the steepest compliance cost escalation due to smaller batch sizes and higher solvent handling intensity.
Converter procurement is consolidating through direct mill agreements that bypass traditional distributor networks. Large furniture manufacturers in East Asia are negotiating frame contracts with TDI producers for quarterly volume commitments with price collars. This concentration is most visible in the Yangtze River Delta, where bedding OEMs have absorbed regional distributor functions to secure allocation during supply tightness.
Toluene Diisocyanates (TDI) Market Segmentation
TDI procurement decisions hinge on isomer purity requirements, formulation compatibility, and regulatory compliance thresholds that vary sharply across end-use applications. Buyers evaluate segments through the lens of processing consistency, emission profiles during curing, and long-term supply security rather than commodity pricing alone.
Product Type:
Cost tier determines supplier qualification and contract structure more than any other product dimension.
- Blended TDI:Standard 80/20 isomer mixtures (2,4-TDI/2,6-TDI) dominate flexible foam production for mattress and automotive seating manufacturers seeking predictable reactivity profiles. Procurement concentrates with furniture OEMs in the Yangtze River Delta who negotiate quarterly frame contracts with price collars to secure allocation during supply tightness.
- Specialty TDI:Purified isomer variants and low-acid grades command premium positioning for high-performance coatings where color stability and hydrolytic resistance outweigh raw material cost considerations. Demand clusters with industrial coating formulators serving automotive refinish and marine protection segments in Germany and Japan.
- Pure TDI:Unmodified 2,4-TDI serves laboratory-scale polymer research and specialty elastomer synthesis requiring precise stoichiometric control.
- Modified TDI:Pre-reacted variants with reduced free monomer content address workplace exposure limits in European manufacturing environments governed by REACH dossier requirements.
Blended TDI leads on scale; Specialty TDI leads on momentum.
End Use Industry:
Application maturity separates volume buyers from specification-driven niche purchasers.
- Furniture:Bedding and upholstered seating manufacturers consume the largest TDI volumes globally, with procurement expanding as residential renovation cycles accelerate across emerging economies. Chinese foam producers around Shanghai dominate converter consolidation through direct mill agreements that bypass traditional distribution.
- Automotive:Seating, interior trim, and acoustic insulation applications demand consistent isomer ratios for reproducible foam density and compression set properties. Tier-1 suppliers are adopting quasi-prepolymer systems to reduce free monomer content and stabilize viscosity profiles during high-speed production lines.
- Construction:Rigid foam insulation and spray-applied coatings represent underpenetrated volume opportunity as commercial building energy codes tighten across India and Southeast Asia.
- Footwear:Microcellular polyurethane midsoles and outsoles require low-density TDI formulations with specific hydroxyl number ranges for controlled cell structure formation.
Furniture commands absolute volume; Automotive offers the steepest expansion trajectory through lightweighting convergence.
Application:
Processing method dictates isomer specification and handling protocols more than final product performance alone.
- Foam:Flexible polyurethane systems for cushioning and packaging represent the foundational TDI application, with formulation optimization services anchoring long-term supply agreements. Technical service contracts embed application expertise that extends supplier monetization beyond commodity volumes.
- Coatings:Two-component polyurethane finishes for industrial and automotive refinish applications require low-color, low-acid TDI grades with precise functionality control. China's GB standards on chemical emissions are tightening formulation requirements and elevating compliance service revenue for qualified suppliers.
- Elastomers:Castable and thermoplastic polyurethane systems serve rollers, wheels, and industrial components where abrasion resistance and load-bearing capacity drive material selection.
- Adhesives:Reactive hot-melt and solvent-based systems for flexible packaging and footwear assembly utilize TDI prepolymers with tailored molecular weight distributions.
Foam dominates manufacturing throughput; Coatings generate the highest margin per kilogram through formulation complexity.
Distribution Channel:
Customer scale and technical support requirements determine channel selection and pricing architecture.
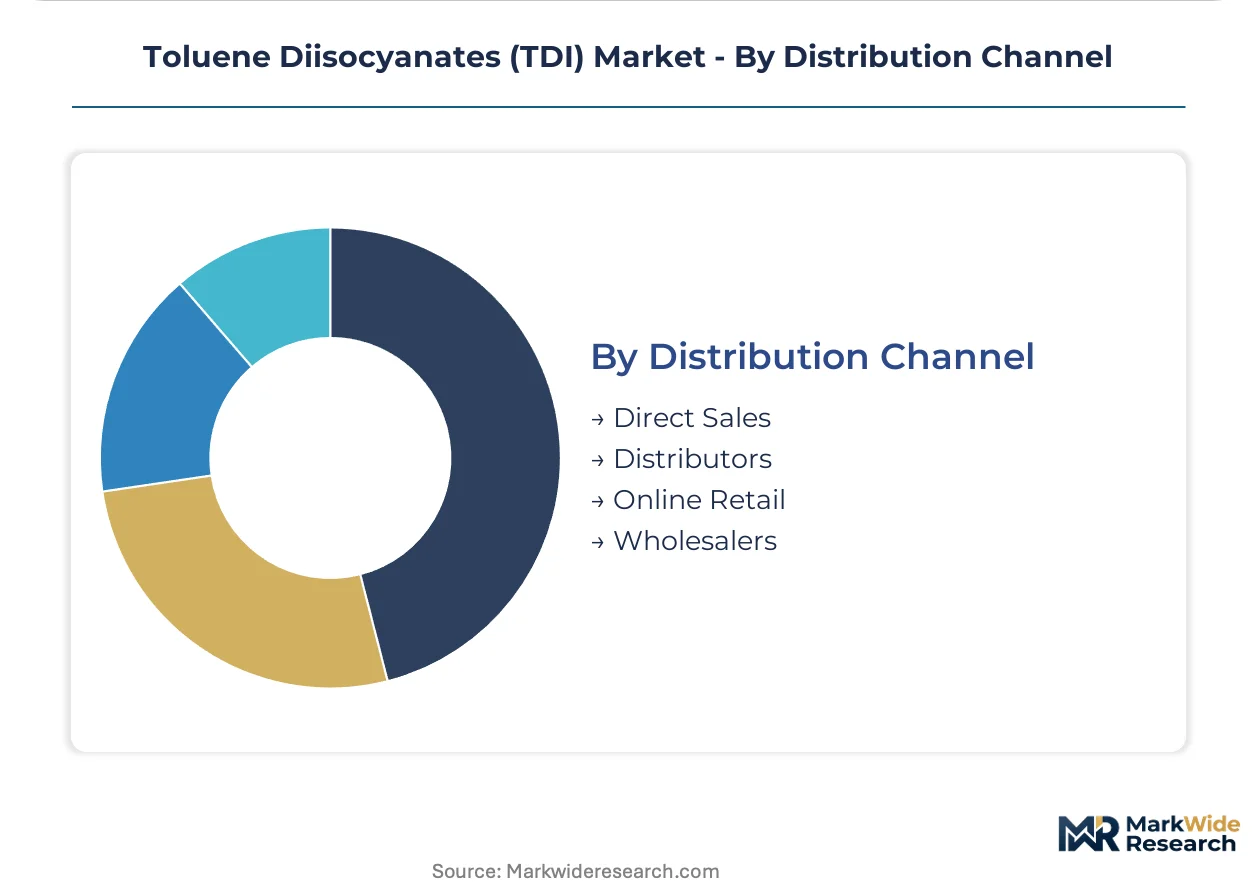
- Direct Sales:Large-volume converters with in-house formulation capabilities negotiate frame contracts directly with TDI producers, particularly visible in East Asian manufacturing clusters where bedding OEMs have absorbed regional distributor functions. These agreements typically include embedded technical service for process optimization.
- Distributors:Regional compounders and mid-tier foam producers rely on stocked inventory and local logistics support, though their role is compressing as procurement consolidates through mill-direct relationships.
- Wholesalers:Smaller converters and specialty chemical blenders access TDI through bulk-breaking intermediaries with limited technical support capabilities.
- Online Retail:Laboratory-scale and sample quantities for R&D procurement represent a nascent channel with minimal commercial significance in this market.
Direct Sales captures the largest contract values; Distributors retain relevance in fragmented regional markets lacking integrated logistics infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and China present contrasting regulatory intensities, with the former enforcing REACH dossier compliance and the latter tightening MEE emissions standards. Both jurisdictions reshape supplier qualification requirements and cost structures for TDI procurement.
China
Furniture OEMs in the Yangtze River Delta dominate procurement volumes for bedding and seating applications. The MEE enforces catalytic oxidation and closed-loop scrubbing mandates at manufacturing facilities. Shanghai chemical corridor producers absorb regional distributor functions through direct mill agreements.
Germany
Automotive seating manufacturers demand consistent isomer ratios for reproducible foam density. ECHA REACH registration requirements constrain market entry for non-integrated producers. Industrial coating formulators in the Rhine-Ruhr region serve automotive refinish segments with low-color TDI grades.
United States
EPA TSCA frameworks influence product stewardship protocols for downstream polyurethane converters. Construction chemicals distributors in the Gulf Coast petrochemical corridor manage inventory for spray-applied insulation contractors. Texas-based compounders face phosgene handling certification requirements that extend commissioning timelines.
Japan
Marine protection and industrial coating segments in the Osaka-Kobe manufacturing zone require hydrolytic-resistant TDI variants. METI oversees chemical emissions frameworks that elevate compliance service revenue for qualified suppliers. Nagoya-area automotive suppliers adopt quasi-prepolymer systems for reduced free monomer content.
India
Commercial building insulation applications represent underpenetrated volume opportunity as urbanization intensifies. BIS standards govern product safety specifications for imported chemical feedstocks. Maharashtra-based construction chemicals distributors expand technical service capabilities for rigid foam system houses.
Toluene Diisocyanates (TDI) Market Competitive Landscape
Top-tier vendors anchor long-term supply agreements through embedded formulation expertise, while mid-tier compounders compete on regional logistics and stocked inventory availability. The vendor base stratifies across integrated producers with captive aniline supply, application-optimized specialists, and regional distributors. Three archetypes dominate: backward-integrated chemical conglomerates, polyurethane system houses with technical service capabilities, and specialty distributors serving fragmented converter markets. Capacity expansion and direct mill contracting constitute the primary competitive moves reshaping channel structures.
Within the integrated producer tier, Covestro AG and Wanhua Chemical Group Co., Ltd exemplify divergent geographic anchoring strategies. Covestro AG occupies a position emphasizing application laboratory networks for automotive seating partnerships. Wanhua Chemical Group Co., Ltd sits within the cost leadership archetype through its Ningbo complex integration. BASF SE represents the specialty-grade vector with differentiated product positioning for high-performance coatings. These three entities collectively illustrate how supplier monetization extends beyond commodity volumes toward technical service and regulatory compliance capabilities.
| Leading Market Players |
|---|
| Dow |
| Evonik |
| Covestro AG |
| Mitsui Chemicals, Inc. |
| Tosoh |
| BASF SE |
| SABIC |
| Cangzhou Dahua Group |
| Wanhua Chemical Group Co., Ltd |
| Others |
Value Network & Pricing Analysis
Premium-modified versus commodity-blended grade bifurcation separates automotive seating contracts from furniture spot purchases, embedding REACH certification costs into German supply agreements while compressing margins on Yangtze River Delta bulk deliveries through direct mill contracting.
Pricing Analysis
Capacity additions in China's Ningbo chemical corridor are reshaping price floors for standard 80/20 isomer blends, forcing European producers to defend specialty-grade premiums through embedded formulation services. Three-tier pricing stratification across purified isomer, low-acid modified, and standard blended grades tracks certification burden and volume scale. Cost compression in commodity furniture foam intensifies as procurement consolidates through quarterly frame contracts with price collars. Tier-1 automotive seating manufacturers exhibit lowest price sensitivity due to specification lock-in, while mid-tier Chinese bedding OEMs drive aggressive spot-market negotiation.
Supply Chain Analysis
Domestic-content mandates in India's construction chemicals sector are reshaping sourcing patterns for rigid foam system houses, redirecting procurement away from established East Asian suppliers toward regional compounders with BIS certification. Production gravity centers on China, Germany, and the United States, with nitric acid and aniline feedstock dependencies anchoring cost structures to refinery integration depth. Single-source vulnerability concentrates in phosgene-handling assets along the Yangtze River Delta, where MEE emissions enforcement constrains rapid capacity response. Distribution runs through direct mill agreements for large converters, with regional distributors retaining relevance only in fragmented Indian and Southeast Asian markets lacking integrated logistics infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
TDI procurement has shifted toward late-cycle quality specifications as automotive lightweighting programs demand quasi-prepolymer systems with sub-ppm free monomer thresholds, elevating technical service contracts over commodity volume plays.
For Market Incumbents: Anchor long-term supply security through backward integration into aniline and nitric acid production, mirroring Wanhua Chemical's Ningbo complex model. Defend against aliphatic diisocyanate substitution in high-performance coatings by embedding application laboratories with automotive OEMs. Prioritize REACH dossier maintenance and MEE emissions compliance as qualification barriers against non-integrated entrants. For New Entrants and Emerging Players: Enter via India's underpenetrated commercial building insulation segment, where BIS certification requirements remain less stringent than REACH or GB standard enforcement. Target Maharashtra-based construction chemicals distributors lacking captive TDI supply for technical partnership structures. Pursue rigid foam system house alliances rather than direct converter competition against established Yangtze River Delta producers. For Investors and Strategic Acquirers: Consolidation pressure builds where phosgene-handling certification requirements extend commissioning timelines beyond typical private equity holding periods, favoring strategic acquirers with operational expertise. Mid-tier regional distributors in fragmented Southeast Asian markets represent viable targets as procurement shifts toward direct mill contracting. Monitor MEE enforcement intensity as inflection signal for Chinese capacity discipline and import opportunity windows.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aniline | Captive nitric acid supply at Ningbo and Ludwigshafen complexes insulates margin structures from toluene volatility. |
| Prepolymer Technology Adoption | Quasi-prepolymer systems for Toyota and Volkswagen seating programs reduce workplace exposure liability. |
| GB Standard Compliance Services | Paid advisory revenue from Shanghai furniture OEMs offsets commodity pricing pressure through regulatory expertise monetization. |
| Direct Mill Agreement Expansion | Frame contracts with Yangtze River Delta bedding manufacturers disintermediate regional distributors and secure allocation priority. |
| Catalytic Oxidation Asset Installation | MEE-mandated vent gas treatment at Chinese facilities preserves operating permits against emissions enforcement. |
Research Methodology
Direct dialogue with polyurethane plant managers, automotive Tier-1 procurement leads, furniture OEM technical directors, and specialty chemical distribution partners grounded qualitative assessment in operational reality. Secondary validation drew from customs trade databases, Cefic sector reports, SEC 10-K chemical segment disclosures, and China MEE emissions filings. Bottom-up volume modeling across isomer grades and end-use applications triangulated against top-down macroeconomic demand drivers.
Bottom-up segment analysis tracked grade tier, end-use industry, and regional production hub dimensions across the projection horizon. CAGRs were derived from production capacity utilization trajectories and downstream demand elasticity estimates. Industry-specific forecast inputs included automotive seating content-per-vehicle trends and residential renovation cycle intensity in emerging economies.
Inputs from regulatory filing databases and trade statistics were available through the study window; gaps in real-time inventory positioning at Chinese manufacturing facilities introduce uncertainty bands around short-term pricing trajectory assumptions. Forecasts reflect documented demand elasticity and capacity response assumptions, with revision risk concentrated in MEE enforcement timing and toluene feedstock volatility. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Calcium Fluoride Market
Industrial Chemicals
Lime Market
Industrial Chemicals
Chlorine Trifluoride Market
Industrial Chemicals
Soil Hardening Agent Market
Industrial Chemicals
Middle East Refrigerants Market
Industrial Chemicals
Heat Treating Market
Industrial Chemicals
Molecular Sieve for Air Separation Market
Industrial Chemicals
Non-Corrosive Fluxes Market
Industrial Chemicals
Nonylphenol Ethoxylate Market
Industrial Chemicals
Rust Preventive Oil Market
Industrial Chemicals
Global Specialty Oils Market
Industrial Chemicals
Draft Tube Baffle (DTB) Crystallizers Market
Industrial Chemicals
Global N-MDEA Market
Industrial Chemicals
Cryolite Market
Industrial Chemicals
Tallow Fatty Acid Market
Industrial Chemicals
Pentane Plus Market