
 North America Quicklime Market | 2026-2036
North America Quicklime Market Size, Share, and Industry Trends Forecast 2026-2036
North America Quicklime Market Analytics
Mexico's expanding steel and construction sectors are reshaping import flows and capacity planning across the North American quicklime trade corridor. Graymont leverages its integrated quarry-to-kiln network across the Canadian provinces to sustain cost advantages in high-purity lime supply. Lhoist North America anchors its position through deep vertical control over Mississippi River distribution channels, while Carmeuse competes aggressively on specialty grades for environmental applications.
Quicklime, or calcium oxide, is produced by calcining limestone at temperatures exceeding 900 degrees Celsius in rotary or vertical kilns, yielding a highly reactive alkaline material with typical calcium oxide content ranging from 90 to 95 percent. Its primary industrial purpose centers on pH regulation, slag formation in metallurgy, and flue gas desulfurization across heavy manufacturing. The steel manufacturing end-use segment dominates volume offtake due to persistent flux demand from integrated mills and electric arc furnace operators, while water treatment applications represent the fastest-expanding margin pool as municipalities upgrade aging infrastructure. Powder and granular forms together occupy the bulk of commercial transactions, though slurry delivery is gaining share among large industrial buyers seeking handling efficiency.
The US EPA enforces National Ambient Air Quality Standards that directly constrain kiln emissions and drive capital spending on scrubber retrofits, while OSHA's permissible exposure limits for crystalline silica shape workplace handling protocols and product packaging requirements. State-level regulators in Texas and Louisiana impose additional monitoring obligations on calcination facilities near populated areas, tightening operational compliance burdens. Stakeholders must monitor how impending revisions to federal mercury and air toxics standards will redirect capital toward pollution control upgrades versus greenfield capacity.
Market Dynamics
Steelmakers along the Great Lakes and Gulf Coast are pulling high-calcium quicklime volumes upward while EPA mercury standards force kiln operators into multi-million-dollar scrubber investments. This tension between demand expansion and compliance burden defines current market structure.
Growth Catalysts
- US EPA Air Toxics Standards:Tightening mercury and particulate limits are accelerating scrubber retrofits at calcination facilities, sustaining replacement demand for high-reactivity lime in flue gas treatment systems.
- Texas-Louisiana Petrochemical Corridor:Dense concentrations of ethylene crackers and refineries are expanding sulfur recovery and pH neutralization applications, pulling granular quicklime volumes from regional suppliers.
- Electric Arc Furnace Expansion:EAF operators across the US Midwest are consuming more flux-grade quicklime per ton of crude steel as scrap quality degrades and slag chemistry requirements tighten.
Market Restraints
- Natural Gas Price Volatility:Calcination requires sustained temperatures above 900°C, making kiln economics hostage to Henry Hub spot movements and regional pipeline constraints.
- Quarry Reserve Depletion:High-calcium limestone deposits with sub-3% magnesium content are concentrating in fewer permitted sites across Ontario and Pennsylvania, tightening long-term feedstock security.
- Slag Cement Substitution:Ground granulated blast-furnace slag from steelmaking is displacing quicklime in some soil stabilization and masonry applications, capping volume growth in construction-grade segments.
Strategic Opportunities
- Mexico Infrastructure Pipeline:Pemex refinery upgrades and Dos Bocas petrochemical complex development are creating import demand for US Gulf Coast quicklime suppliers with barge access.
- Lithium Processing Applications:Spodumene calcination and lithium hydroxide production are emerging as high-specification quicklime consumers as North American battery material plants commission.
- Carbon Capture Retrofits:Direct air capture and post-combustion carbon capture facilities are testing quicklime-based sorbent loops, opening potential demand from climate-tech developers.
Industry Challenges
- Kiln Operator Shortage:Experienced rotary kiln technicians and process engineers are aging out of the workforce faster than vocational programs in Alabama and Texas can replace them.
- Silica Compliance Burden:OSHA's crystalline silica permissible exposure limits are forcing packaging line automation investments and respiratory protection program overhauls at distribution terminals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Quicklime Market |
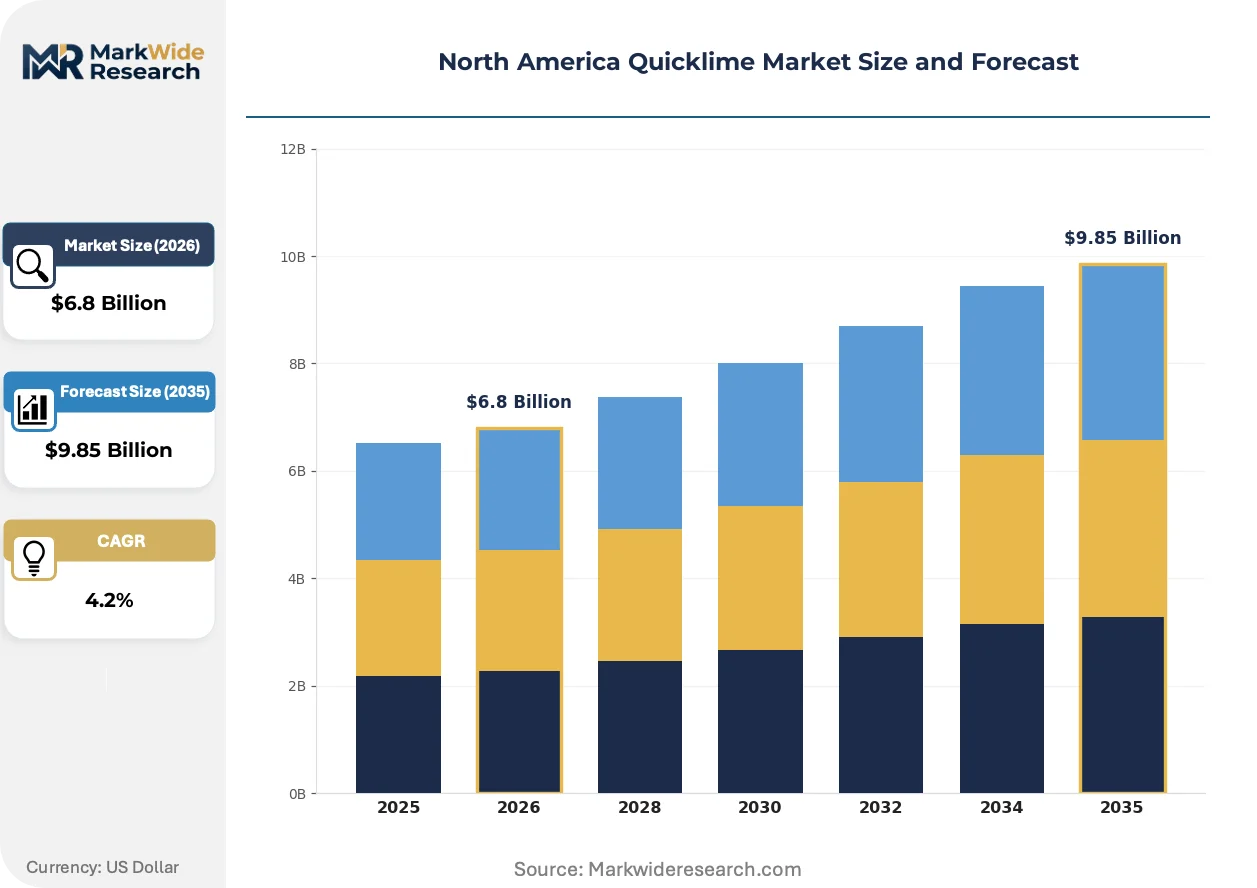
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $9.85 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrated Lime, Quicklime, Calcium Carbonate, Quicklime Slurry End Use Industry: Construction, Steel Manufacturing, Water Treatment, Mining Form: Powder, Granular, Paste, Slurry Distribution Channel: Direct Sales, Online, Distributors, Retail |
| Companies Covered | Graymont, Lhoist North America, Carmeuse, United States Lime & Minerals, Mississippi Lime Company, Cheney Lime & Cement Company, Pete Lien & Sons, Arcosa Specialty Materials, Martin Marietta Materials, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Quicklime Market Evolving Landscape
Calcination technology and logistics models are compressing cost structures while regulatory pressure accelerates environmental performance requirements. These forces are redrawing competitive boundaries across the North American quicklime trade.
Maerz vertical shaft kilns with parallel flow regenerative design are collapsing energy consumption benchmarks for high-calcium quicklime production. Steelmakers in Indiana and Ohio are specifying PFR-kiln material for flux applications where thermal efficiency translates directly to delivered cost advantages. The technology is collapsing the historical gap between rotary kiln output volumes and vertical kiln energy economics, reshaping supplier investment priorities.
US EPA's pending revisions to the National Emission Standards for Hazardous Air Pollutants for lime manufacturing are tightening mercury and hydrogen chloride limits. Kiln operators in Texas and Louisiana face scrubber upgrade timelines that compress capital deployment windows through 2027. The standards are forcing integrated producers to choose between pollution control investments at aging facilities and greenfield capacity with embedded compliance.
Large industrial buyers are consolidating procurement through long-term tolling arrangements rather than spot market purchases. Chemical processors along the Houston Ship Channel are locking in dedicated kiln output through take-or-pay contracts that transfer price risk to suppliers. This concentration is most visible in water treatment applications, where municipal utilities are aggregating demand through regional purchasing cooperatives.
North America Quicklime Market Segmentation
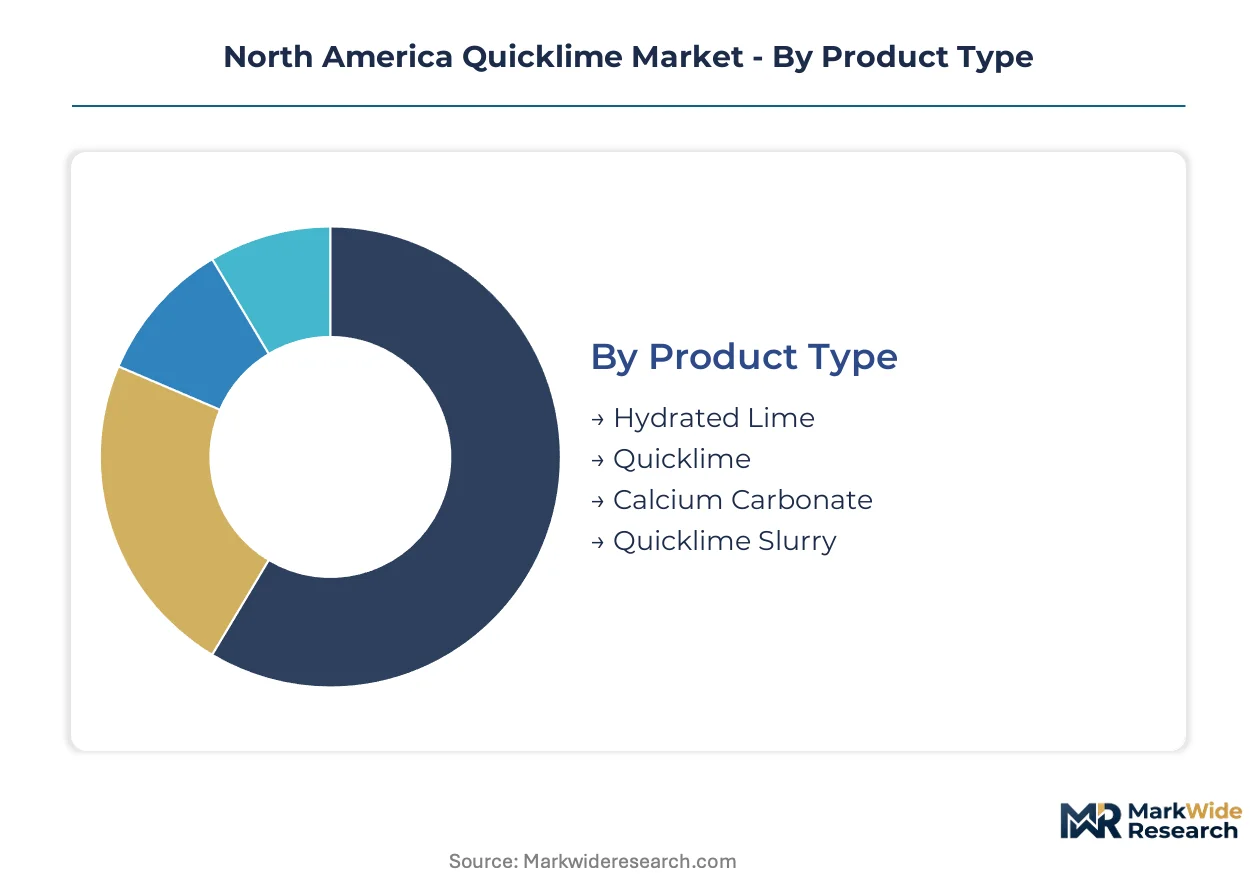
Quicklime segmentation in North America reflects divergent technical requirements across steel fluxing, environmental compliance, and chemical processing. Each dimension—product chemistry, industrial application, physical form, and procurement channel—carries distinct margin structures and capital intensity profiles that reshape supplier strategy.
Product Type:
Mature commodity grades dominate volume, while slurry and specialty derivatives capture expanding share in automated handling systems.
- Quicklime:Calcium oxide produced via limestone calcination above 900°C, typically 90-95% CaO content. Steel mills across Indiana and Ohio specify high-calcium grades for slag formation where thermal reactivity determines flux efficiency.
- Quicklime Slurry:Pre-hydrated aqueous suspension delivering 20-40% solids content for pipeline injection. Water treatment utilities in Texas and Louisiana are standardizing on slurry delivery to eliminate dust handling and reduce OSHA silica exposure compliance costs.
- Hydrated Lime:Calcium hydroxide formed through controlled slaking of quicklime, offering safer handling and precise pH control for municipal wastewater applications.
- Calcium Carbonate:Ground limestone product serving as lower-reactivity filler in construction and agriculture, positioned downstream of calcination economics.
Quicklime handles the majority of throughput; quicklime slurry is the fastest mover on share.
End Use Industry:
Volume concentrates in heavy manufacturing, though environmental applications are climbing fastest on regulatory tailwinds.
- Steel Manufacturing:Integrated mills and electric arc furnace operators consume flux-grade material for slag chemistry control. EAF expansion across the US Midwest is pulling additional volumes as scrap quality degradation tightens slag basicity requirements.
- Water Treatment:Municipal utilities deploy high-reactivity lime for pH adjustment, softening, and phosphorus removal. Regional purchasing cooperatives in the Great Lakes states are aggregating demand through long-term tolling arrangements.
- Construction:Soil stabilization and masonry applications face substitution pressure from ground granulated blast-furnace slag, capping volume growth in traditional building-grade segments.
- Mining:Gold and copper heap leaching operations utilize lime for pH control in cyanide and sulfuric acid circuits, with Nevada and Arizona deposits driving regional consumption patterns.
Steel manufacturing commands the dominant volume position; water treatment is expanding most quickly on infrastructure replacement cycles.
Form:
Physical presentation dictates logistics economics and end-use handling infrastructure across the value chain.
- Powder:Fine-ground material below 75 microns, standard for steel fluxing and chemical processing where rapid reactivity is essential. Powder dominates Great Lakes steel corridor deliveries.
- Granular:Pebble or pellet form optimized for controlled reactivity in water treatment and mining leaching circuits, reducing dust generation versus powder alternatives.
- Slurry:Pumpable aqueous suspension eliminating dust exposure and enabling automated injection systems, gaining preference among large industrial buyers with dedicated storage infrastructure.
- Paste:High-density hydrated lime product for specialized construction grouting and soil mixing applications requiring minimal water addition.
Powder and granular forms together anchor commercial transactions; slurry is gaining share fastest among buyers seeking handling efficiency.
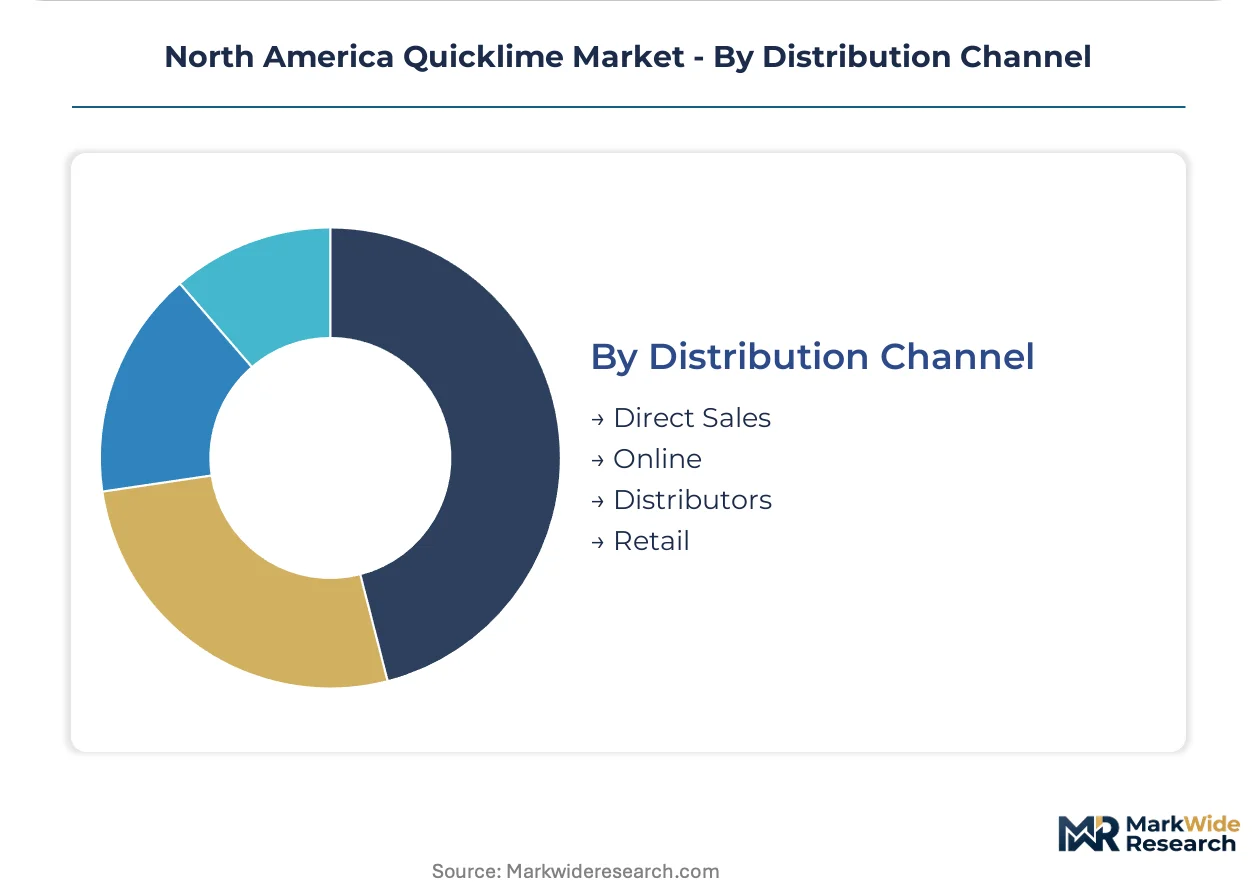
Distribution Channel:
Procurement patterns are bifurcating between direct supply relationships and consolidated intermediary networks.
- Direct Sales:Producer-to-consumer contracts governing large-volume steel, chemical, and utility accounts. Texas-Louisiana petrochemical processors are locking in dedicated kiln output through take-or-pay structures that transfer price risk to suppliers.
- Distributors:Regional intermediaries serving construction contractors, small municipalities, and agricultural users with fragmented demand and high service requirements.
- Online:Emerging platform procurement for standardized grades, currently limited to small-volume buyers without established supplier relationships.
- Retail:Bagged product for agricultural and residential applications, representing minimal revenue share in the industrial-focused North American market.
Direct sales channels capture the dominant value flow; distributor networks are consolidating fastest as mid-size buyers seek procurement efficiency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA enforcement of National Ambient Air Quality Standards shapes capacity decisions across the United States, while Canadian and Mexican industrial expansion redirects trade flows throughout the continent.
United States
Steel manufacturers in Indiana and Ohio consume high-calcium quicklime for electric arc furnace fluxing as scrap quality degradation tightens slag chemistry requirements. EPA mercury and air toxics standards are forcing multi-million-dollar scrubber investments at calcination facilities in Texas and Louisiana. The Houston Ship Channel petrochemical corridor anchors sulfur recovery and pH neutralization demand, with processors locking in dedicated kiln output through long-term tolling arrangements.
Canada
Ontario's high-calcium limestone deposits with sub-3% magnesium content are concentrating in fewer permitted sites, tightening long-term feedstock security for Great Lakes steel suppliers. Environment Canada enforces parallel air quality standards that align with US EPA thresholds, simplifying cross-border compliance for integrated producers. Quebec's integrated quarry-to-kiln networks sustain cost advantages in high-purity lime supply to northeastern US markets.
Mexico
Pemex refinery upgrades and Dos Bocas petrochemical complex development are creating import demand for US Gulf Coast quicklime suppliers with barge access. Mexican steel and construction sectors are expanding consumption faster than domestic calcination capacity can match. The Mexico City metropolitan area and Nuevo León industrial corridor represent concentrated demand nodes for environmental and metallurgical applications.
Texas-Louisiana Gulf Coast
Ethylene crackers and refineries across this sub-regional corridor expand sulfur recovery and pH neutralization applications, pulling granular quicklime volumes from regional suppliers. State-level regulators impose additional monitoring obligations on calcination facilities near populated areas, tightening operational compliance burdens. Dense petrochemical and construction activity sustains the continent's most concentrated quicklime demand cluster outside the Great Lakes steel belt.
North America Quicklime Market Competitive Landscape
Capability concentration sits with integrated quarry-to-kiln operators; scale advantage sits with diversified materials conglomerates with captive limestone reserves. The North American quicklime market structures around three archetypes: vertically integrated specialists controlling full value chains from mining to distribution, regional producers serving single-state or single-industry demand pools, and diversified construction materials players for whom lime represents a portfolio segment alongside aggregates and cement. Competitive moves center on scrubber retrofit investments at aging facilities versus greenfield capacity with embedded environmental compliance, and long-term tolling arrangements that transfer price risk from industrial buyers to suppliers.
Among integrated specialists, Graymont and Lhoist North America exemplify the vertically integrated archetype, each leveraging captive quarry networks and controlled distribution channels to sustain cost positions in high-purity supply. Carmeuse occupies a position emphasizing specialty grades for environmental applications, representing the diversification-focused tier within the specialist segment. United States Lime & Minerals and Mississippi Lime Company sit within the regional producer category, anchoring supply relationships with steelmakers and chemical processors across their respective geographic footprints. Arcosa Specialty Materials and Martin Marietta Materials exemplify the diversified construction materials conglomerate archetype, where quicklime operations integrate with broader aggregate and specialty materials portfolios rather than standing as standalone strategic priorities.
| Leading Market Players |
|---|
| Graymont |
| Lhoist North America |
| Carmeuse |
| United States Lime & Minerals |
| Mississippi Lime Company |
| Cheney Lime & Cement Company |
| Pete Lien & Sons |
| Arcosa Specialty Materials |
| Martin Marietta Materials |
| Others |
Value Network & Pricing Analysis
Ontario's high-calcium limestone deposits with sub-3% magnesium content concentrate in fewer permitted sites, anchoring margin pools downstream with integrated quarry-to-kiln operators who control feedstock security. This upstream concentration translates directly into pricing power for steel flux and environmental-grade supply.
Pricing Analysis
Price spreads between Great Lakes and Gulf Coast delivery points reflect natural gas differentials and barge freight economics. Three-tier pricing structure across high-purity flux grades, standard chemical grades, and construction-grade material captures quality and certification premiums. Cost compression in construction-grade segments stems from ground granulated blast-furnace slag substitution. Municipal utilities demonstrate highest price sensitivity due to budget constraints, while petrochemical processors accept premium positioning for guaranteed supply security.
Supply Chain Analysis
Long-term tolling arrangements concentrate calcination capacity with Graymont, Lhoist North America, and Carmeuse across Ontario, Quebec, Pennsylvania, and Alabama. The supply chain draws from high-calcium limestone reserves, natural gas feedstock, and specialized refractory linings. Single-source vulnerability runs through Mississippi River barge channels where flooding or lock maintenance disrupts bulk deliveries. Distribution runs through direct producer-to-consumer contracts for large industrial accounts, with regional distributors handling fragmented construction and agricultural demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ground granulated blast-furnace slag from steelmaking is displacing quicklime in soil stabilization and masonry applications, forcing incumbents to defend metallurgical and environmental-grade positions where substitution economics fail.
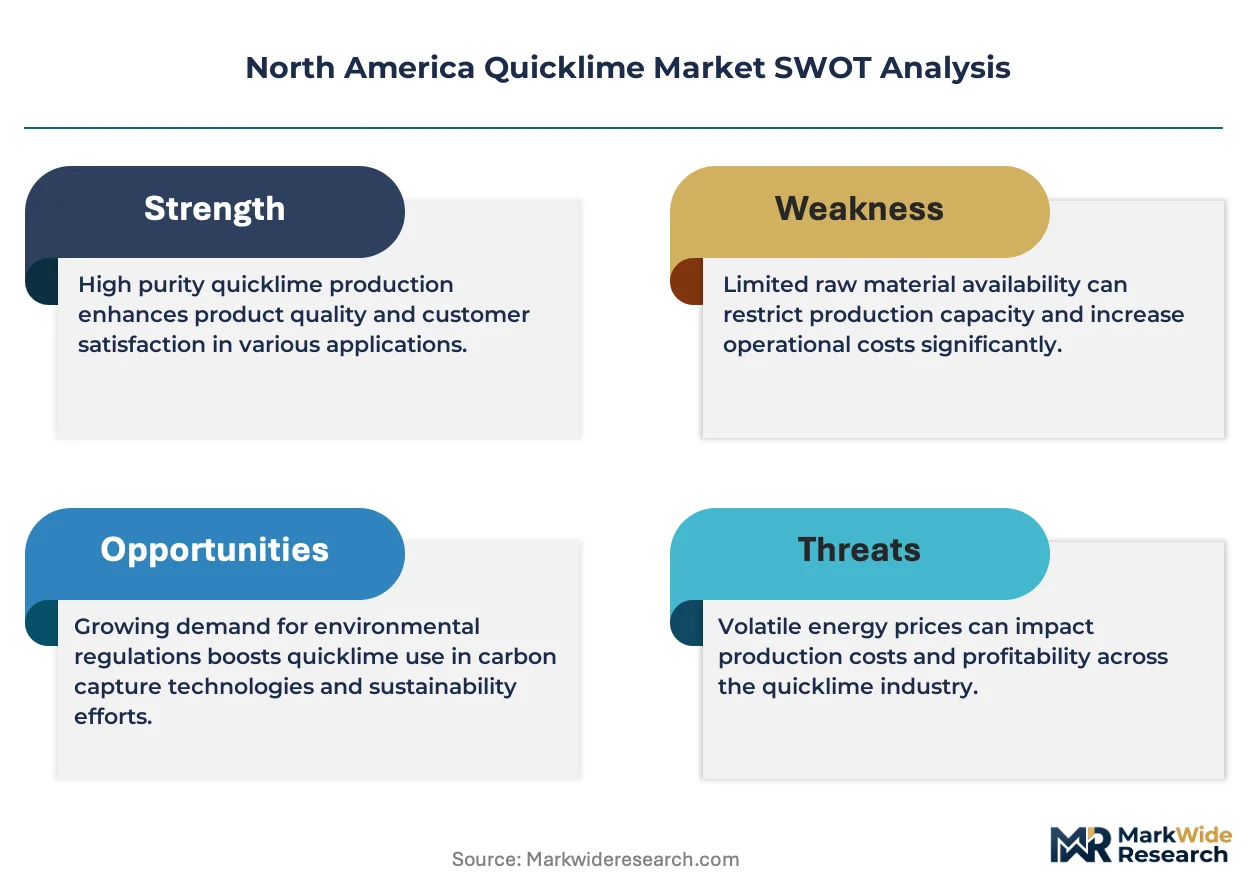
For Market Incumbents: Build captive quarry reserves as the primary moat against feedstock depletion in Ontario and Pennsylvania. Secure long-term tolling arrangements with Texas-Louisiana petrochemical processors to lock in volume commitments before greenfield capacity emerges. Invest in Maerz PFR kiln retrofits to collapse energy costs and defend margin position against natural gas volatility. For New Entrants and Emerging Players: Mexico's Dos Bocas petrochemical complex and Pemex refinery upgrades represent the most penetrable entry point for US Gulf Coast suppliers with existing barge infrastructure. Lithium processing applications in Nevada and Arizona offer white-space demand as battery material plants commission. Pursue slurry delivery specialization to bypass established powder and granular incumbents in water treatment procurement. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional producers holding single-state quarry positions in Alabama and Texas. The five-to-ten year viability window favors integrated operators with captive limestone reserves and scrubber-compliant kilns. Watch EPA mercury standard enforcement timelines as the signal for forced consolidation versus greenfield investment inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Quarry Reserves | Captive limestone supply in Ontario and Pennsylvania secures feedstock against permitted site concentration. |
| Scrubber Retrofit Investment | EPA mercury compliance at Texas-Louisiana kilns sustains operating permits through tightening air toxics standards. |
| Long-term Tolling Arrangement | Take-or-pay contracts with Houston Ship Channel processors transfer natural gas price risk to suppliers. |
| Slurry Delivery Infrastructure | Pipeline injection systems for Texas and Louisiana utilities eliminate dust handling and reduce OSHA compliance costs. |
| Maerz PFR Kiln Conversion | Parallel flow regenerative design collapses energy consumption benchmarks for Indiana and Ohio steel flux supply. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with kiln operators, steel procurement managers, water treatment utility engineers, and petrochemical process engineers; and secondary validation through USGS mineral commodity summaries, EPA enforcement databases, SEC 10-K filings from listed lime producers, and US EIA natural gas price series. Bottom-up capacity modeling triangulated against top-down end-use consumption estimates across steel, chemical, and environmental applications.
Forecast inputs include calcination capacity by kiln type, EPA regulatory compliance timelines, natural gas price scenarios, and steel production forecasts by furnace technology. Segmentation dimensions span product chemistry grade, end-use industry, physical form, and procurement channel structure. CAGRs were derived from trend extrapolation of historical consumption patterns adjusted for regulatory-driven replacement cycles and infrastructure investment pipelines.
Practitioners should monitor EPA National Emission Standards revision schedules and Henry Hub forward curves for early signals of margin compression or capacity rationalization. Cross-checking against USGS mineral yearbook limestone reserve depletion rates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Middle East Refrigerants Market
Industrial Chemicals
Electro-Erosion Fluids Market
Industrial Chemicals
1,3-Propanediol (PDO) Market
Industrial Chemicals
Heat Shrink Tubes Market
Industrial Chemicals
Metal Forming Fluids Market
Industrial Chemicals
Cryogenic Column Market
Industrial Chemicals
Industrial Closures Market
Industrial Chemicals
India Thermic Fluid Market
Industrial Chemicals
Carbon Molecular Sieves Market
Industrial Chemicals
Fischer-Tropsch (FT) Wax Market
Industrial Chemicals
Metal Removal Fluids Market
Industrial Chemicals
Chrome Plating Market
Industrial Chemicals
6-KT Mother Liquor Market
Industrial Chemicals
Rotomolding Powder Market
Industrial Chemicals
Bulk Explosives Market
Industrial Chemicals
Food Grade Grease Market