
 Silicates Market | 2026-2036
Silicates Market Size, Share, and Industry Trends Forecast 2026-2036
Silicates Market Analytics
Direct sales channels serving large-volume detergent and glass manufacturers is tilting toward distributor networks that can bundle technical service with logistics. PQ Corporation leverages its captive sodium silicate capacity to sustain pricing leverage across North American construction accounts. Evonik Industries AG differentiates through specialty precipitated silicas for tire and electronics grades, while Solvay anchors European supply through its integrated alkali-silica operations.
Silicates are inorganic compounds built from silicon-oxygen tetrahedra, typically manufactured by fusing silica sand with alkali or alkaline-earth carbonates at temperatures exceeding 1,100°C to produce water-soluble glasses or insoluble mineral forms. Sodium silicate dominates volume flows, with its 2.0-3.3 SiO2/Na2O ratio range determining solubility and binding strength for detergents, adhesives, and foundry molds. Calcium silicate occupies the fastest-growing structural position, as thermal insulation boards gain share in passive fire protection and high-temperature industrial linings where low thermal conductivity below 0.06 W/m·K is specified. Potassium silicate carves a premium niche in specialty coatings and welding electrodes, where its higher water resistance and lower efflorescence justify cost premiums over sodium grades.
REACH registration requirements in Europe and EPA Toxic Substances Control Act reporting in the United States impose compositional disclosure burdens that favor producers with dedicated regulatory affairs functions and standardized analytical protocols. China's GB standards for industrial sodium silicate and the EU F-Gas Regulation's indirect pressure on fluorinated alternatives both expand addressable demand for inorganic silicate substitutes in insulation and refrigeration applications. Stakeholders must monitor how carbon border adjustment mechanisms and evolving green procurement criteria reweight total cost of ownership calculations across regional supply bases.
Market Dynamics
REACH compliance deadlines and China's dual carbon goals are compressing formulation timelines across construction and detergent applications, forcing producers to revalidate water-based silicate systems ahead of regulatory enforcement waves.
Growth Catalysts
- Passive fire protection mandates:Germany's updated building codes specify calcium silicate boards for high-rise facades, expanding thermal insulation specifications across EU-27 member states.
- REACH registration:ECHA's 2023 dossier updates for sodium silicate grades have clarified compositional thresholds, reducing formulation uncertainty for detergent manufacturers seeking supply security.
- Foundry binder substitution:Sodium silicate cold-box systems are displacing phenolic resins in Chinese automotive casting operations, driven by VOC reduction targets under MEE air quality directives.
Market Restraints
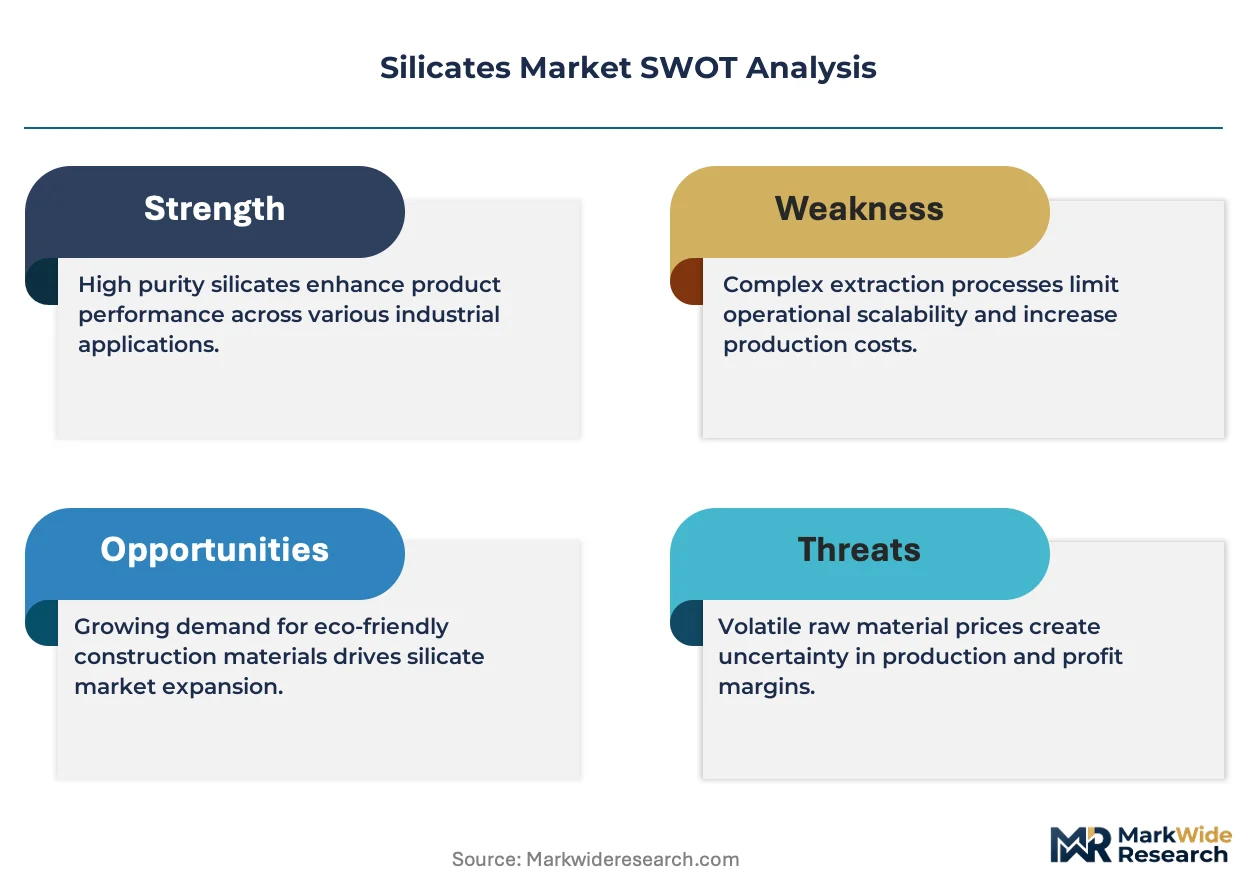
- Energy cost volatility:Soda ash and silica sand fusion requires sustained temperatures above 1,100°C, exposing producers to European natural gas price spikes that compress margin structures.
- Supply concentration:Captive sodium silicate capacity at PQ Corporation and Solvay limits spot market liquidity, constraining mid-volume buyers seeking flexible procurement terms.
- Technical ceiling in thin-film electronics:Precipitated silica particle size distribution constraints prevent penetration into next-generation semiconductor packaging below 50nm feature sizes.
Strategic Opportunities
- India construction chemicals:BIS certification requirements for fire-rated building materials create first-mover advantage for calcium silicate board producers establishing local compounding operations.
- EU F-Gas Regulation:Phasedown of hydrofluorocarbon blowing agents redirects refrigeration insulation demand toward inorganic silicate foam systems with zero global warming potential.
- Digital formulation platforms:Cloud-based rheology modeling is compressing silicate binder development cycles from 18 months to 8 weeks for specialty coating applications.
Industry Challenges
- High-temperature process engineering talent:Fusion furnace operation and energy optimization expertise is concentrating at retiring technician cohorts, constraining capacity expansion timelines.
- Legacy analytical protocol integration:X-ray fluorescence and titration methods for SiO2/Na2O ratio verification resist automation, delaying real-time quality control deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Silicates Market |
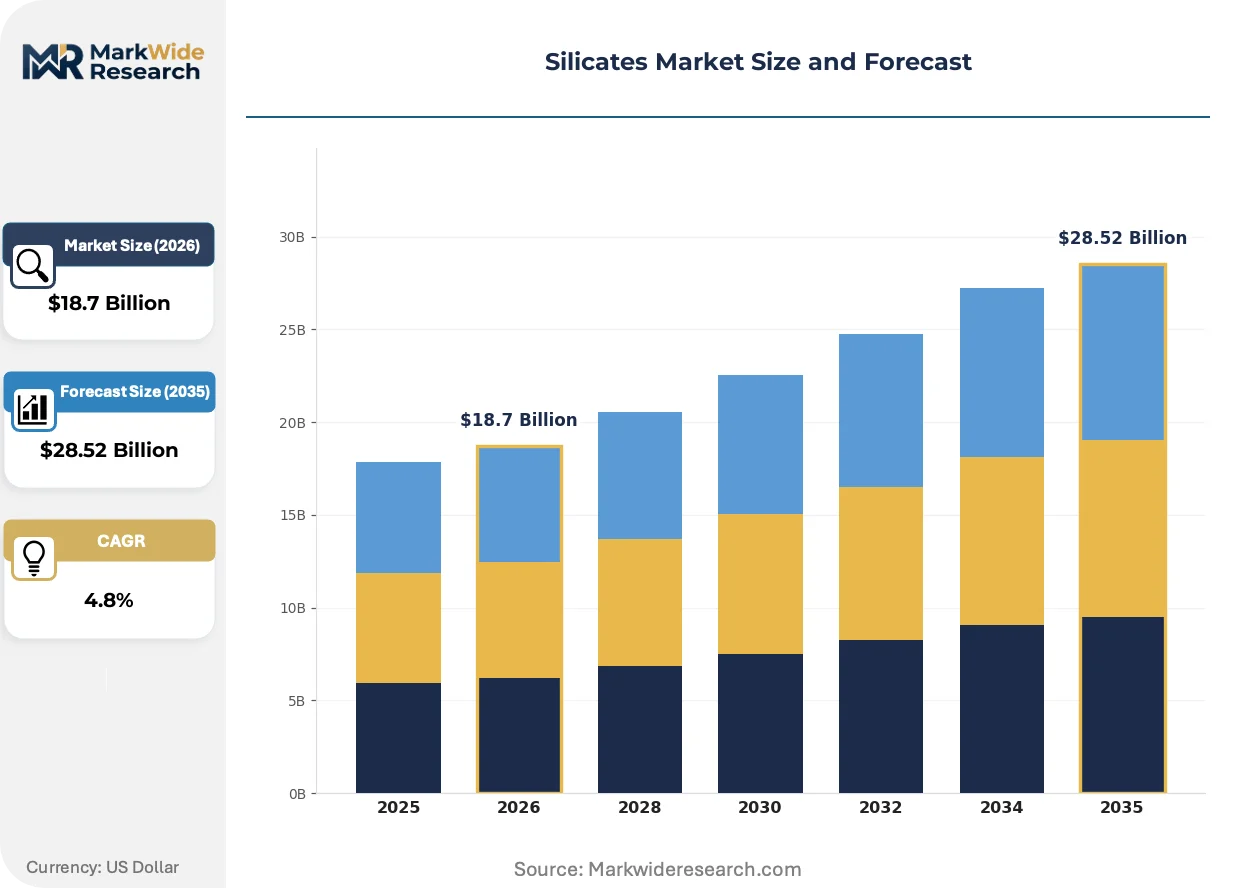
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sodium Silicate, Potassium Silicate, Calcium Silicate, Magnesium Silicate Application: Construction, Detergents, Glass Manufacturing, Agriculture End Use Industry: Automotive, Electronics, Pharmaceuticals, Food Processing Distribution Channel: Direct Sales, Online Retail, Wholesale, Distributors |
| Companies Covered | Evonik Industries AG, PQ Corporation, PPG Industries, Qemetica, W.R. Grace & Co., Huber Engineered Materials, Solvay, Occidental Petroleum Corporation, Oriental Silicas Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Silicates Market Evolving Landscape
Digital twin technology and predictive analytics are virtualizing silicate product development, compressing laboratory-to-production timelines while regulatory pressure accelerates substitution away from organic binders.
Colloidal silica sol-gel processing is virtualizing surface modification protocols for tire tread applications. Continental and Michelin procurement teams are qualifying these grades for silica-silane coupling efficiency gains. The technology is virtualizing traditional precipitated silica capacity planning by enabling just-in-time surface treatment without dedicated reactor assets.
ECHA's 2024 update to REACH Annex XVII restricted substance listings has tightened disclosure thresholds for crystalline silica impurities. Industrial sodium silicate producers must now implement laser diffraction particle sizing below 10 micrometers for regulatory dossier compliance. Detergent and foundry segments in Poland and Czechia are absorbing elevated testing costs through supplier qualification surcharges.
Glass manufacturers in Shandong Province are consolidating sodium silicate procurement through integrated supplier platforms that bundle logistics, technical service, and inventory management. These arrangements displace fragmented distributor networks that previously served small and mid-volume accounts. The shift is most visible in container glass operations supplying export markets, where supply security outweighs spot price optimization.
Silicates Market Segmentation
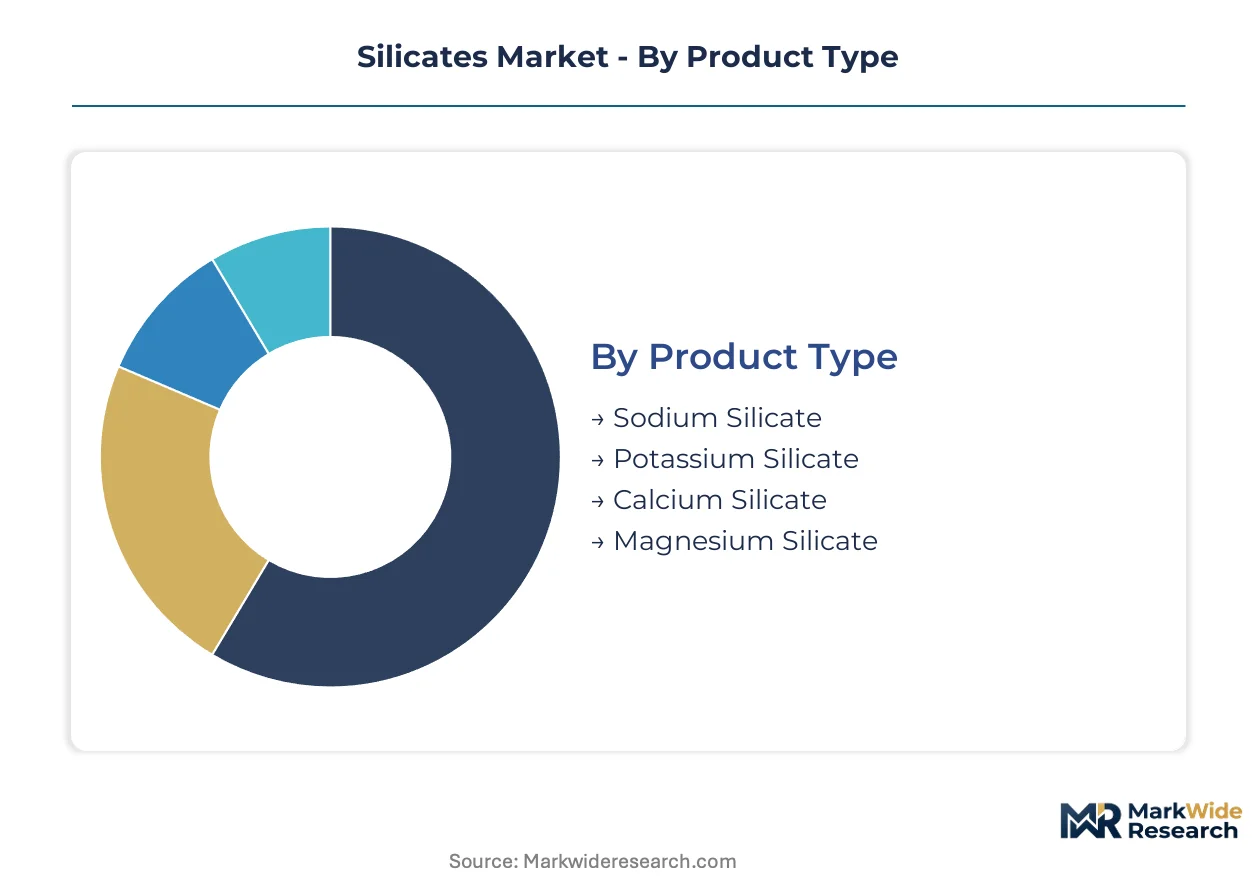
Silicate chemistry spans soluble glasses and insoluble minerals with divergent processing requirements and end-use specifications. Segmentation reveals how product type, application focus, and channel structure determine margin profiles and competitive positioning across the value chain.
Product Type:
The use-case spectrum runs from commodity binders in detergents to engineered thermal insulation boards demanding sub-0.06 W/m·K conductivity.
- Sodium Silicate:Manufactured by fusing silica sand with soda ash above 1,100°C, this water-soluble glass dominates detergent and foundry binder applications. Demand concentrates in China where glass manufacturing and MEE-compliant foundry operations consume substantial volumes for cold-box systems displacing phenolic resins.
- Calcium Silicate:Low thermal conductivity mineral boards serve passive fire protection mandates in German high-rise codes and high-temperature industrial linings. Adoption accelerates fastest across EU-27 member states updating building envelope specifications.
- Potassium Silicate:Higher water resistance and reduced efflorescence justify cost premiums in specialty welding electrodes and protective coatings.
- Magnesium Silicate:Talc and serpentine-derived grades filter pharmaceuticals and reinforce polymer compounds.
Established volume favors sodium silicate; emerging adoption favors calcium silicate.
Application:
Cost tier separation distinguishes specification-grade construction materials from commodity detergent builders.
- Construction:Calcium silicate boards and sodium silicate adhesives face tightening VOC regulations redirecting specification toward water-based systems. Germany's updated facade codes and India's BIS fire-rating certification are expanding thermal insulation demand.
- Detergents:Sodium silicate builders with 2.0-3.3 SiO2/Na2O ratios provide alkalinity and anti-redeposition in powder formulations. REACH registration clarity from ECHA's dossier updates has reduced supply uncertainty for European manufacturers.
- Glass Manufacturing:Container and flat glass operations in Shandong Province consolidate procurement through integrated supplier platforms bundling logistics and inventory management.
- Agriculture:Silicate soil amendments and foliar fertilizers address silicon deficiency in rice and sugarcane cultivation.
Construction commands specification premiums; detergents anchor baseline volume.
End Use Industry:
Customer type fragmentation separates automotive procurement teams seeking foundry binder security from electronics buyers demanding particle size precision.
- Automotive:Chinese casting operations adopt sodium silicate cold-box systems under MEE air quality directives, displacing resin-bonded sand molds.
- Electronics:Precipitated silica for semiconductor packaging faces technical ceilings below 50nm feature sizes, constraining penetration into advanced packaging.
- Pharmaceuticals:Magnesium silicate excipients and colloidal silica anti-caking agents require pharmacopeial compliance.
- Food Processing:Sodium silicate functions as a corrosion inhibitor in can coatings and egg preservation.
Automotive drives foundry substitution; electronics demands sub-micron particle engineering.
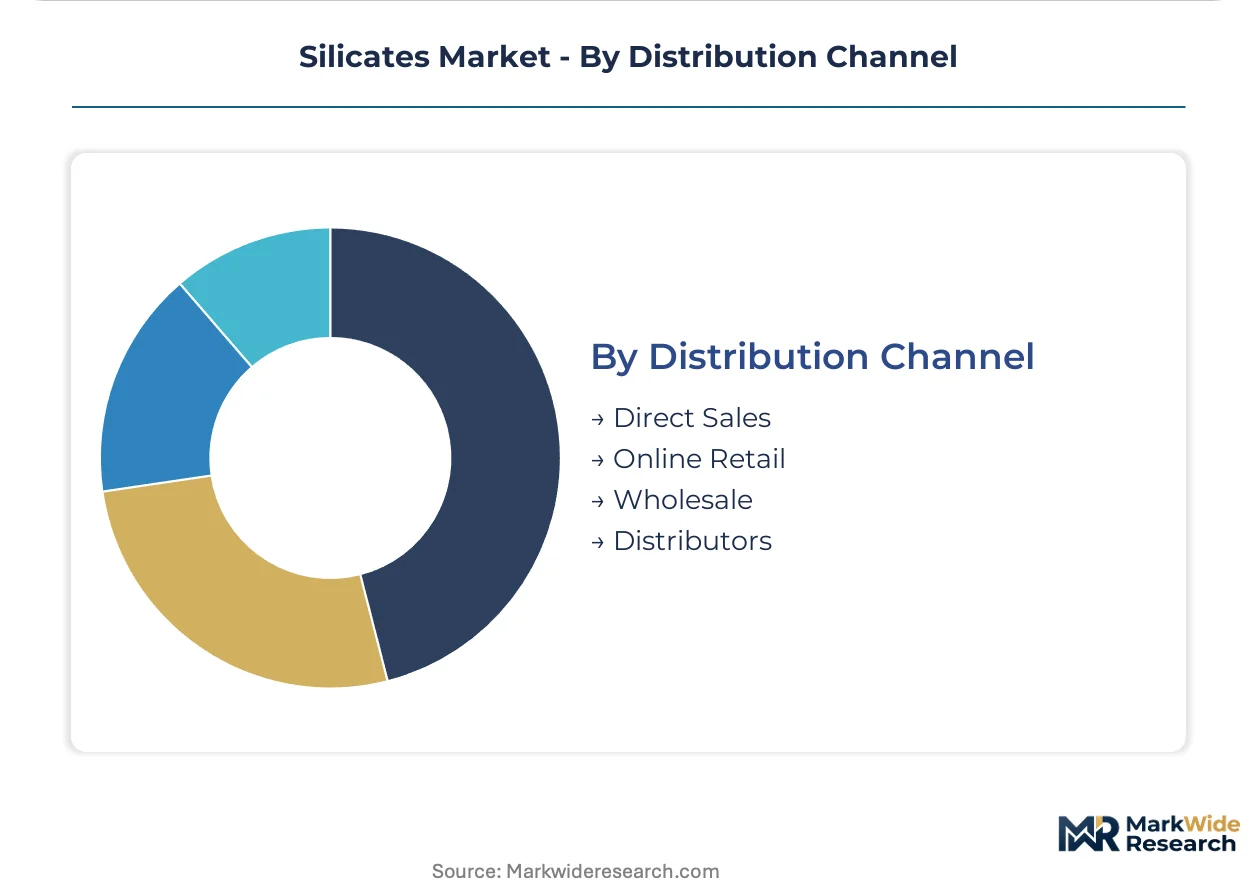
Distribution Channel:
Supply concentration shapes channel economics, with captive producer capacity limiting spot market liquidity for mid-volume buyers.
- Direct Sales:Large-volume detergent and glass manufacturers negotiate frame contracts with PQ Corporation and Solvay, securing technical service integration.
- Distributors:Regional networks bundle logistics with formulation support for construction chemicals and foundry supply, gaining share as procurement consolidates.
- Wholesale:Bulk sodium silicate solutions move through tanker-fed depots serving mid-tier adhesive and sealant compounders.
- Online Retail:Specialty potassium silicate coatings and small-batch colloidal silica sols reach coating formulators through technical chemical marketplaces.
Direct sales defend large-account relationships; distributor networks capture technical service premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main-Danube waterway and Rotterdam-Antwerp pipeline corridors sustain European silicate feedstock flows. Asian port infrastructure at Ningbo-Zhoushan and Qingdao handles bulk soda ash imports for Chinese glass manufacturing clusters. North American rail networks connecting Wyoming trona deposits to Midwest soda ash plants underpin regional supply security.
China
Shandong Province container glass manufacturers consolidate sodium silicate procurement through integrated supplier platforms bundling logistics and inventory management. MEE air quality directives accelerate foundry binder substitution toward sodium silicate cold-box systems displacing phenolic resins. Qingdao and Weifang industrial zones concentrate detergent-grade silicate production serving domestic and export markets.
Germany
Updated building codes specify calcium silicate boards for high-rise facades, expanding thermal insulation demand across EU-27 member states. REACH registration deadlines from ECHA compress formulation timelines for water-based silicate systems in construction adhesives. The Rhine-Ruhr industrial corridor anchors specialty precipitated silica production for automotive and electronics grades.
United States
EPA Toxic Substances Control Act reporting requirements impose compositional disclosure burdens favoring producers with dedicated regulatory affairs functions. Natural gas price volatility at Gulf Coast fusion plants compresses margin structures for soda ash-silica glass production. Texas and Louisiana chemical corridors concentrate sodium silicate capacity serving detergent and foundry markets.
India
BIS certification requirements for fire-rated building materials create first-mover advantage for calcium silicate board producers establishing local compounding operations. Construction chemical demand concentrates in Maharashtra and Gujarat where infrastructure investment accelerates passive fire protection specification. The Delhi-Mumbai Industrial Corridor attracts silicate adhesive formulators seeking proximity to building materials distribution networks.
Japan
METI efficiency standards for industrial insulation redirect specification toward low-thermal-conductivity calcium silicate systems below 0.06 W/m·K. JIS standards for precipitated silica in tire manufacturing maintain quality thresholds that filter supplier qualification. The Kansai industrial region around Osaka sustains specialty potassium silicate production for welding electrode and coating applications.
Silicates Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream. The silicates market structures around three tiers: multinational alkali-silica conglomerates with captive fusion capacity, regional precipitated silica compounders serving tire and electronics grades, and construction chemical distributors bundling technical service with logistics. Strategic moves concentrate on backward integration into soda ash supply and geographic expansion into Indian and Southeast Asian construction markets.
Among Germany-based chemical conglomerates, Evonik Industries AG exemplifies specialty precipitated silica positioning. PQ Corporation represents North American captive capacity leverage across construction accounts. Solvay anchors European supply through integrated alkali-silica operations. These three occupy positions that illustrate how regulatory compliance scale and fusion furnace asset control determine competitive access to large-volume detergent and glass manufacturing procurement.
| Leading Market Players |
|---|
| Evonik Industries AG |
| PQ Corporation |
| PPG Industries |
| Qemetica |
| W.R. Grace & Co. |
| Huber Engineered Materials |
| Solvay |
| Occidental Petroleum Corporation |
| Oriental Silicas Corporation |
| Others |
Value Network & Pricing Analysis
Wyoming trona deposits feeding North American soda ash production concentrate upstream margin capture among alkali-silica conglomerates with captive fusion capacity. This concentration cascades downstream into tiered pricing power across detergent and glass manufacturing accounts.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates specification-grade precipitated silicas from commodity sodium silicate solutions. Price differentiation hinges on SiO2/Na2O ratio precision and REACH registration status. Cost compression in standard-grade detergent builders is intensifying because European natural gas price spikes squeeze fusion furnace economics. Mid-volume foundry operations exhibit highest price sensitivity; tire-grade precipitated silica buyers show lowest.
Supply Chain Analysis
Extended payment terms from integrated supplier platforms in Shandong Province are restructuring working capital flows for container glass manufacturers. Supply concentrates in China, Germany, and the United States, drawing from Wyoming trona, Nordic quartz deposits, and synthetic soda ash streams. Single-source vulnerability sits with European natural gas dependency for fusion energy. Distribution runs through tanker-fed depots serving adhesive compounders and regional construction chemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fusion furnace operation expertise is retiring faster than technical training programs replace it, compressing expansion timelines for producers seeking capacity additions. This capability gap favors incumbents with established technician cohorts.
For Market Incumbents: Build regulatory affairs scale by expanding ECHA dossier maintenance teams and GB standards compliance infrastructure. Sodium silicate cold-box substitution threatens phenolic resin incumbents in Chinese automotive casting; defend through backward integration into Qingdao industrial zone logistics platforms and captive soda ash supply arrangements.
For New Entrants and Emerging Players: Pursue BIS certification-first entry into Maharashtra calcium silicate board compounding before established European suppliers localize production. India's Delhi-Mumbai Industrial Corridor offers the most penetrable geography; anchor go-to-market through construction chemical distributors bundling fire-rating technical service.
For Investors and Strategic Acquirers: Capital is best deployed toward specialty precipitated silica compounders with tire and electronics grade qualifications and cloud-based rheology modeling capabilities. Long-term viability favors assets with digital formulation platform integration and regional regulatory affairs scale. Watch for ECHA Annex XVII crystalline silica threshold tightening as inflection signal for testing cost absorption capacity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Soda Ash Supply | Wyoming trona access insulates PQ Corporation and Solvay from energy-driven feedstock volatility. |
| Digital Formulation Platform Deployment | Cloud-based rheology modeling compresses silicate binder development cycles for Continental and Michelin procurement teams. |
| REACH Registration Scale Investment | ECHA dossier maintenance capabilities secure detergent manufacturer supply security and reduce qualification uncertainty. |
| Local Compounding Operations in India | Maharashtra and Gujarat facilities capture BIS fire-rating certification premiums ahead of European incumbent entry. |
| Colloidal Silica Sol-Gel Capacity | Just-in-time surface treatment technology virtualizes traditional precipitated silica reactor assets for tire tread applications. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across plant managers at fusion furnace facilities, procurement leads at detergent and glass manufacturers, distribution channel partners in construction chemicals, and technical R&D directors specializing in precipitated silica grades. Secondary validation drew from customs and trade data, Cefic sector reports, SEC 10-K filings from alkali-silica conglomerates, and ECHA registration dossiers. Bottom-up volume modeling and top-down value triangulation were cross-referenced for consistency.
Calibration against historical capacity utilization rates and regional energy cost differentials anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include silicate chemistry type, end-use industry concentration, regional production hub clustering, and SiO2/Na2O ratio specification tier. CAGRs were derived from slope analysis of disclosed capacity expansions and procurement consolidation trends. Forecast inputs incorporated MEE air quality directive enforcement timelines and EU F-Gas Regulation phasedown schedules.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-backed alkali producers or rapid European green hydrogen adoption for fusion energy would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Europe Surface Treatment Chemicals Market
Industrial Chemicals
Quicklime Market
Industrial Chemicals
Global Isocyanate Market
Industrial Chemicals
Carbamate Insecticides Market
Industrial Chemicals
Europe Isocyanates Market
Industrial Chemicals
Mining Explosives Consumables Market
Industrial Chemicals
Ceramic Corona Discharge Ozone Generator Market
Industrial Chemicals
Non-Corrosive Fluxes Market
Industrial Chemicals
Asia Neopentyl Glycol (NPG) Market
Industrial Chemicals
Thermic Fluids Market
Industrial Chemicals
Global N-Methyl-2-Pyrrolidone (NMP) Market
Industrial Chemicals
Nano-Bubble Generator Market
Industrial Chemicals
Asia-Pacific Molecular Sieve Market
Industrial Chemicals
Modified Bitumen Market
Industrial Chemicals
Lignin Market
Industrial Chemicals
Blow Torch Market