

Mold Powders and Casting Fluxes Market Size, Share, and Industry Trends Forecast 2026-2036
Mold Powders and Casting Fluxes Market Insights
Alumina-carbon composite formulations with engineered slag chemistry is reconfiguring how mold powders deliver thermal insulation and lubrication in high-speed continuous casting. Vesuvius leverages its integrated refractory platform to sustain R&D intensity across Europe and Asia. RHI Magnesita anchors global supply through captive raw material positions in magnesia-rich deposits. Shinagawa Refractories competes on specialized powder blends for ultra-low carbon steel grades.
Mold powders and casting fluxes are synthetic slag compositions—typically silica-calcium-alumina systems with carbonaceous additives and fluoride-bearing minerals—engineered to control heat transfer, prevent steel oxidation, and enable defect-free strand solidification in continuous casting operations. Granular powder dominates volume due to its ease of pneumatic feeding and consistent bed formation atop the molten meniscus. Steel casting applications absorb the majority of value, while aluminum foundries represent a faster-growing niche as automotive lightweighting intensifies demand for precision flux chemistry.
EU Green Deal carbon border adjustments and REACH restrictions on fluoride emissions are tightening product formulation standards across European steel corridors. Japan's METI energy efficiency benchmarks and China's GB standards on industrial emissions collectively push suppliers toward lower-carbon manufacturing routes and reduced volatile content. Stakeholders must monitor how regional decarbonization timelines reshape raw material qualification criteria and foundry procurement specifications.
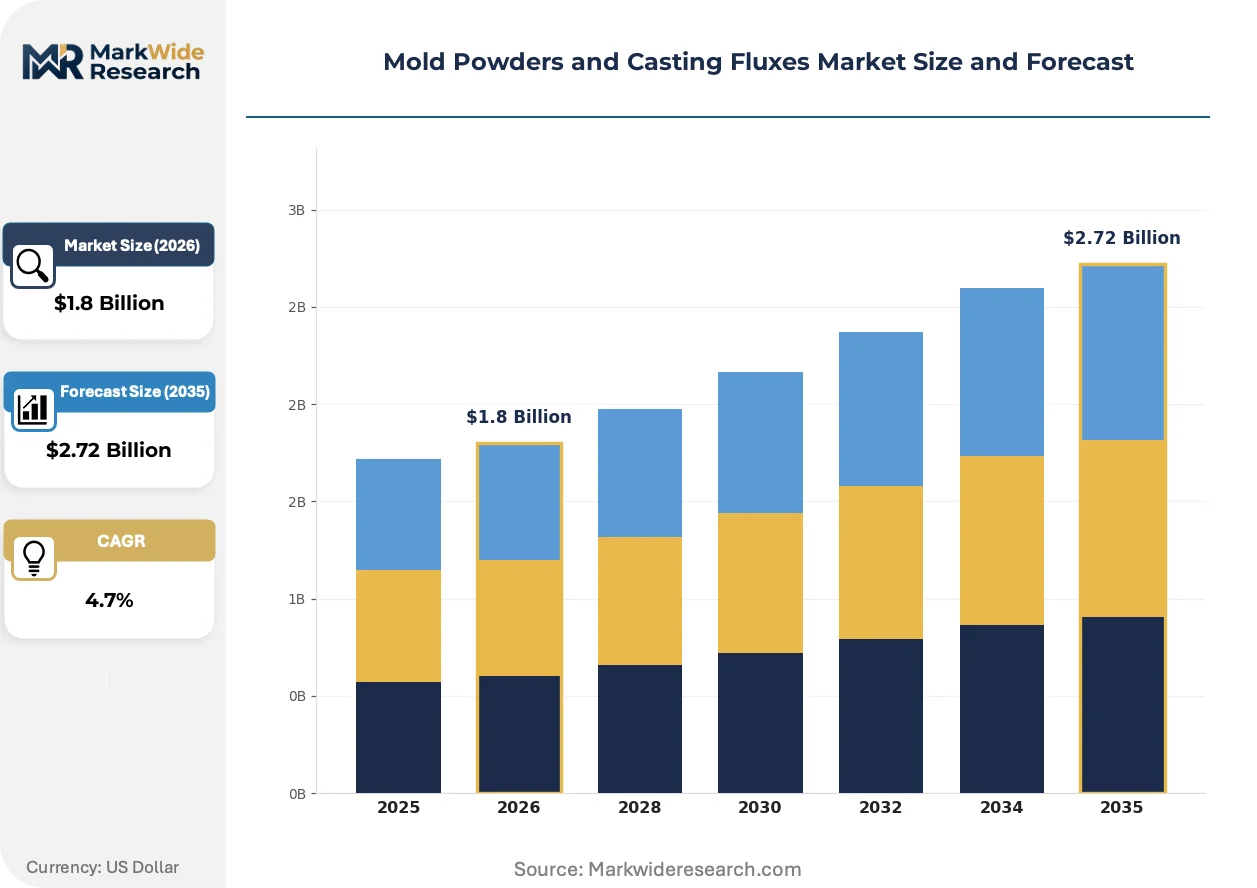
Market Dynamics
EU Green Deal carbon border adjustments and REACH restrictions on fluoride emissions are tightening product formulation standards across European steel corridors, forcing suppliers toward lower-carbon manufacturing routes and reduced volatile content. This regulatory compression is reconfiguring raw material qualification criteria and foundry procurement specifications simultaneously.
Growth Catalysts
- EU Green Deal compliance:German steel casting plants are expanding procurement of low-carbon mold powders as carbon border adjustments phase in, creating immediate demand pull for reformulated products.
- Japanese METI efficiency standards:Steel producers in Japan face tightening energy efficiency benchmarks that favor advanced mold powder chemistries optimizing heat transfer and reducing energy intensity per ton cast.
- Automotive lightweighting:Aluminum foundries serving electric vehicle battery housings and structural components are absorbing specialized flux formulations at accelerating rates.
Market Restraints
- Fluoride mineral supply concentration:Cryolite and fluorite deposits cluster in China and Mexico, exposing formulators to geopolitical supply interruptions and export quota volatility.
- REACH regulatory friction:European Chemicals Agency restrictions on fluoride emissions are forcing costly reformulation of established product lines without immediate performance guarantees.
- Magnesia price volatility:Refractory-grade magnesia from captive deposits faces periodic export restrictions from major producing regions, compressing margin predictability for integrated suppliers.
Strategic Opportunities
- India's PLI scheme for specialty steel:Production-linked incentives for high-grade automotive and electrical steel are expanding continuous casting capacity requiring qualified mold powder supply.
- Silica-calcium-alumina system convergence:Engineered slag chemistry integrating alumina-carbon composites is opening premium positioning for thermal insulation performance in high-speed casting lines.
- South Korean battery materials corridor:Gwangyang and Pohang steel complexes serving cathode precursor producers are generating demand for ultra-low carbon steel grades requiring specialized powder blends.
Industry Challenges
- Slag chemistry expertise gap:Formulators struggle to recruit metallurgists capable of optimizing silica-calcium-alumina systems for simultaneous thermal insulation, lubrication, and oxidation control.
- Legacy pneumatic feeding system integration:Foundries with established granular powder infrastructure face capital-intensive retrofits to accommodate next-generation engineered formulations.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mold Powders and Casting Fluxes Market Trends and Innovations
Alumina-carbon composite formulations with engineered slag chemistry are reconfiguring how mold powders deliver thermal insulation and lubrication in high-speed continuous casting operations. Three interconnected developments are compressing product lifecycles and reshaping supplier-buyer relationships.
Sensor-embedded mold powder beds are digitizing real-time thermal profile monitoring across the meniscus region. Integrated steel mills in Japan and South Korea are deploying these systems at commercial scale. This capability is digitizing quality assurance workflows and compressing defect response times from hours to minutes.
REACH restrictions on fluoride emissions are forcing systematic substitution of cryolite-bearing minerals in European formulations. The industrial consequence is accelerated R&D into fluoride-free flux chemistries maintaining comparable thermal insulation properties. Steel casting corridors in Germany and Italy are most affected, with suppliers front-loading compliance investments ahead of 2027 enforcement milestones.
Buyer consolidation among East Asian integrated steel mills is compressing supplier qualification timelines and unbundling technical service contracts from material supply agreements. Tier-one mills in China and Japan now demand dedicated formulation support embedded within procurement relationships. This pattern is most visible in the automotive steel supply chain serving battery electric vehicle platform production.
Mold Powders and Casting Fluxes Market Segmentation
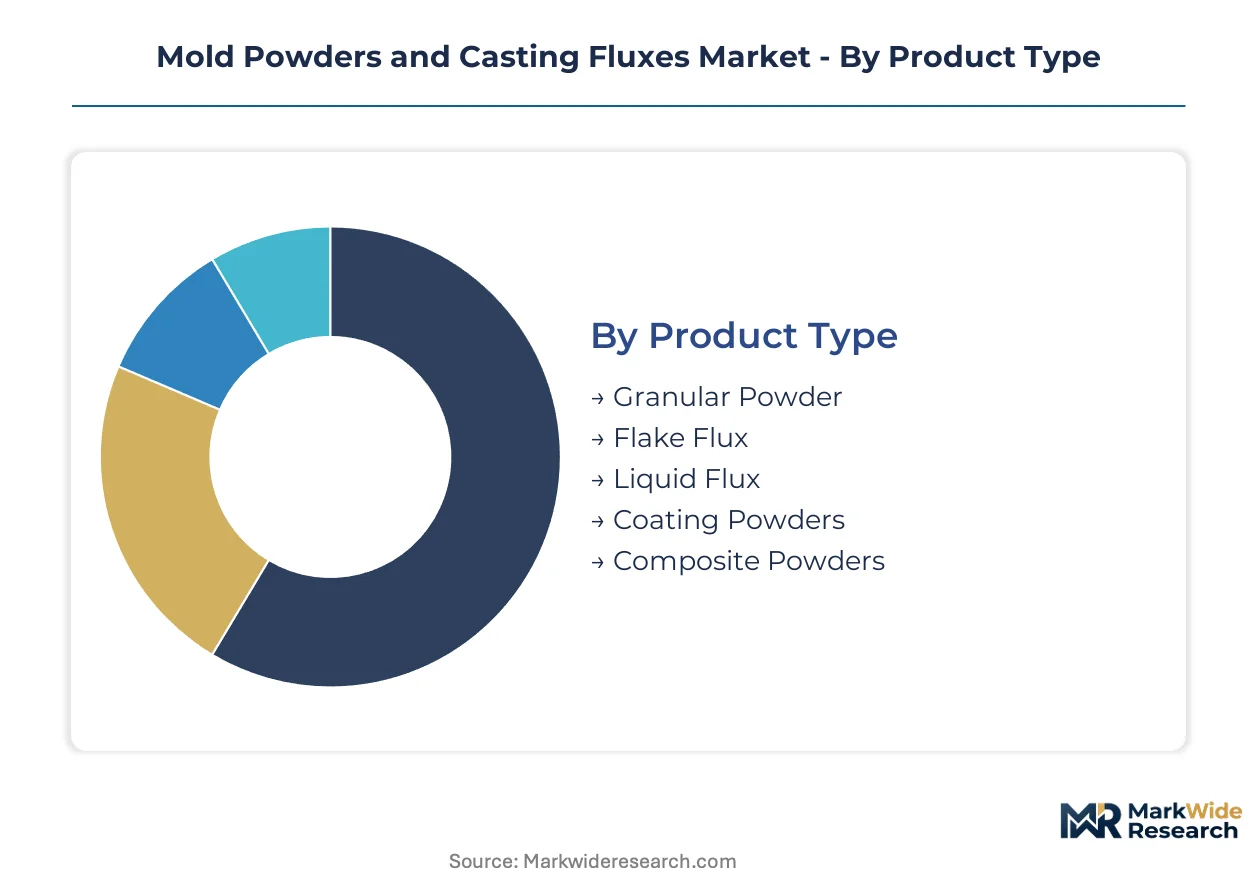
Mold powders and casting fluxes serve distinct thermal and chemical functions across casting speeds, metal chemistries, and automation levels. Segmentation reveals how formulation complexity and delivery mechanisms align with end-use requirements and regulatory constraints.
Product Type:
Granular powder dominates pneumatic feeding systems across high-speed continuous casting lines, while engineered alternatives address specialized thermal profiles.
- Granular Powder:Silica-calcium-alumina systems with carbonaceous additives enable consistent bed formation atop molten steel meniscus. East Asian integrated mills absorb the majority of volume as high-speed slab casting intensifies.
- Flake Flux:Thin-layer geometries optimize dissolution rates in aluminum foundries serving electric vehicle battery housings. German automotive suppliers favor flake formulations for precision flux chemistry in structural component casting.
- Liquid Flux:Pre-melted slag compositions reduce volatile emissions during application. Japanese METI efficiency benchmarks accelerate adoption at energy-intensive steel corridors.
- Coating Powders:Surface-applied formulations protect against oxidation in magnesium foundries. South Korean battery materials corridors generate emerging demand for ultra-low carbon grade compatibility.
- Composite Powders:Alumina-carbon hybrid systems integrate engineered slag chemistry for thermal insulation optimization. REACH fluoride restrictions in Germany and Italy force reformulation investments ahead of enforcement milestones.
Established volume favors granular powder; emerging adoption favors composite powders.
Application:
Steel casting absorbs value concentration, while non-ferrous segments climb fastest on automotive lightweighting and battery supply chain expansion.
- Steel Casting:Continuous slab, bloom, and billet casting operations require synthetic slag control of heat transfer and solidification defects. China's GB standards on industrial emissions reshape procurement specifications across state-owned mills.
- Aluminum Foundries:Specialized flux chemistry enables precision casting of thin-wall battery housings and crash structures. India's PLI scheme for specialty steel indirectly expands aluminum foundry capacity serving component suppliers.
- Copper Production:Fire refining and continuous casting operations demand sulfur-controlled flux systems. Japanese wire rod producers prioritize oxidation prevention in high-conductivity applications.
- Zinc Casting:Galvanizing fluxes manage dross formation and surface quality in coating operations. German automotive steel corridors sustain steady demand from corrosion-resistant component specifications.
- Magnesium Foundries:Ignition-resistant formulations address handling hazards in lightweight structural casting. South Korean cathode precursor supply chains stimulate interest in ultra-low carbon steel grades requiring compatible mold powder systems.
Steel casting anchors revenue concentration; aluminum foundries gain share fastest on electric vehicle platform proliferation.
End User:
Procurement sophistication varies from commodity volume buyers to specification-intensive defense contractors.
- Foundry Shops:Independent operations serving regional metalworking demand standardized granular powder grades. Price sensitivity dominates supplier selection.
- Metal Casting Plants:Integrated continuous casting facilities require dedicated formulation support embedded within procurement relationships. Japanese and South Korean mills compress qualification timelines.
- Heavy Engineering:Large forging and casting operations for power generation and mining equipment absorb specialized flux for thick-section solidification control.
- Shipbuilding Units:Classification society specifications dictate defect tolerance thresholds for marine steel grades. Korean yards at Gwangyang and Pohang anchor regional demand.
- Defense Manufacturers:Ultrasonic testing requirements for armor and ordnance steels impose premium formulation standards with full batch traceability.
Metal casting plants command formulation partnership terms; defense manufacturers extract maximum specification compliance.
Packaging Type:
Handling automation and moisture sensitivity drive packaging selection across climatic and logistical conditions.
- Bulk Bags:One-ton flexible intermediate bulk containers serve high-volume continuous casting plants with pneumatic unloading infrastructure. German and Japanese mills favor bulk delivery for cost efficiency.
- Paper Bags:Multi-wall kraft constructions protect against humidity in moderate climates. Foundry shops in India and Southeast Asia rely on manual handling compatibility.
- Plastic Drums:Sealed containment preserves hygroscopic liquid flux and specialized coating powders. REACH-compliant distributors in Europe prefer drum formats for hazardous material protocols.
- Fiber Drums:Lightweight rigidity suits flake flux and composite powder shipments requiring stacking strength. Japanese logistics networks optimize for fiber drum dimensions.
- Cartons:Small-format packaging serves trial quantities and maintenance-repair-operations inventory. Defense manufacturers specify cartons for controlled access storage.
Bulk bags dominate tonnage throughput; plastic drums capture premium formulation value.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated steel mills in Germany and Japan anchor procurement sophistication, while Chinese state-owned enterprises concentrate volume demand. East Asian foundries absorb premium formulations for high-speed continuous casting, and India's specialty steel incentives reshape supplier qualification timelines.
China
State-owned steel mills in Tangshan and Baoshan drive granular powder consumption for high-speed slab casting. GB standards on industrial emissions reshape procurement specifications across Hebei and Jiangsu provinces. The Yangtze River Delta cluster concentrates reformulation investments as MEE enforcement intensifies.
Germany
ThyssenKrupp and Salzgitter expand low-carbon mold powder procurement as EU Green Deal carbon border adjustments phase in. REACH restrictions on fluoride emissions force cryolite substitution in formulations from ECHA compliance deadlines. The Ruhr industrial corridor anchors reformulation R&D for 2027 enforcement milestones.
Japan
Nippon Steel and JFE Steel optimize heat transfer chemistries under METI energy efficiency benchmarks. JIS standards on continuous casting quality compress supplier qualification timelines at Kawasaki and Chiba mills. The Chubu region around Nagoya concentrates sensor-embedded powder bed deployments.
South Korea
POSCO and Hyundai Steel generate demand for ultra-low carbon steel grades serving cathode precursor producers. MFDS-aligned industrial emissions protocols reshape flux chemistry specifications at Gwangyang and Pohang complexes. The battery materials corridor drives specialized coating powder adoption for magnesium foundry compatibility.
India
Tata Steel and JSW Steel expand continuous casting capacity under PLI scheme incentives for automotive and electrical grades. BIS certification requirements tighten raw material qualification for specialty steel production. The Jharkhand-Odisha belt concentrates new mold powder supply agreements as integrated mills scale output.
Mold Powders and Casting Fluxes Market Competitive Landscape
Channel-controlling players compete with product-specialist players across formulation complexity tiers. The market structures around three archetypes: integrated refractory platforms with captive raw material positions, regional specialists in engineered slag chemistry, and commodity formulators serving price-sensitive foundry shops. M&A activity concentrates in magnesia-rich deposit access, while strategic partnerships embed technical service within procurement relationships at tier-one steel mills.
Among integrated refractory platforms, Vesuvius and RHI Magnesita exemplify the scale-driven archetype with backward integration into mineral supply. Shinagawa Refractories occupies a position within the specialist tier, representing Japanese precision in ultra-low carbon grade formulations. These three anchors illustrate how geographic origin and company structure correlate with competitive positioning: the Belgian-UK combination of Vesuvius, the Austrian-German structure of RHI Magnesita, and the Japanese Co., Ltd. format of Shinagawa each sit within distinct capability clusters.
| Leading Market Players |
|---|
| Vesuvius |
| Calderys |
| RHI Magnesita |
| Shinagawa Refractories |
| Krosaki Harima |
| Puyang Refractories Group |
| Saint-Gobain SEFPRO |
| IFGL Refractories |
| Dalmia Bharat Refractories |
| Others |
Pricing and Supply Chain Analysis
Overcapacity signals from Chinese magnesia processing corridors are compressing supplier pricing power while simultaneously forcing consolidation among formulators dependent on captive mineral positions. This utilization dynamic tightens margin structures for integrated refractory platforms and regional specialists alike, reshaping procurement negotiations at East Asian steel mills.
Pricing Analysis
Cost-plus contracts with quarterly magnesia and fluorite indexation dominate procurement agreements between formulators and integrated steel mills. Three-tier pricing structure across premium, standard, and economy levels separates REACH-compliant composite powders from commodity granular grades and unbundled technical service offerings. Cost compression in standard-grade formulations is intensifying because Chinese state-owned mills are consolidating supplier panels and demanding volume rebates. Foundry shops serving regional metalworking exhibit highest price sensitivity, while Japanese automotive steel corridors absorb premium positioning for defect-free strand solidification guarantees.
Supply Chain Analysis
Extended payment terms stretching to 90 days and supply-chain finance facilities anchored in Austrian and German banking networks are becoming standard for tier-one mill procurement. Raw material dependencies center on magnesia-rich deposits in Austria and China, fluorite concentrates from Mexico and China, and engineered alumina feedstocks from Australian bauxite corridors. Single-source vulnerability concentrates in cryolite-bearing mineral supply from Chinese export quota regimes. Distribution runs through regional blending facilities co-located with steel complexes in Germany, Japan, and South Korea, with bulk pneumatic delivery to mill stockyards.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment creates durable barriers: REACH compliance investments and JIS certification timelines lock in qualified suppliers and extend replacement cycles beyond five years.
For Market Incumbents: Harden formulation IP positions through captive R&D partnerships with Nagoya-area sensor-embedded powder bed deployers. Deepen backward integration into magnesia-rich deposit access ahead of export restriction volatility from major producing regions. Prioritize certification investment for EU Green Deal carbon border adjustment readiness at German steel corridors. For New Entrants and Emerging Players: Build out flake flux capabilities serving aluminum foundries supplying South Korean battery materials corridors, where precision flux chemistry commands specification premiums and incumbent coverage remains thin. Target India's Jharkhand-Odisha belt for granular powder supply agreements as PLI scheme incentives expand continuous casting capacity. Lead with technical service embedding rather than price undercutting to differentiate from commodity formulators. For Investors and Strategic Acquirers: Capital is best deployed toward regional specialists with proven slag chemistry expertise and existing JIS or BIS certification pathways, positioned for consolidation as buyer concentration among East Asian mills squeezes standalone formulators. Long-term viability hinges on regulatory compliance capability rather than scale alone. Watch for REACH enforcement milestone acceleration as an inflection signal for fluoride-free formulation premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Magnesia Supply | Captive Austrian deposit access insulates RHI Magnesita from Chinese export quota volatility. |
| REACH-Compliant Fluoride-Free Reformulation | Anticipated ECHA enforcement milestones in Germany and Italy front-load R&D recovery timelines. |
| Sensor-Embedded Powder Bed Deployment | Japanese METI efficiency benchmarks accelerate digitized quality assurance adoption at Chubu mills. |
| Technical Service Contract Embedding | Tier-one mills in South Korea now demand dedicated formulation support within procurement relationships. |
| India PLI Scheme Capacity Alignment | Specialty steel incentives at Tata Steel and JSW Steel reshape supplier qualification timelines. |
Research Methodology
A standing panel of continuous casting plant managers, refractory procurement leads at integrated steel mills, technical R&D directors at formulators, and channel distribution partners provided ongoing calibration across primary fieldwork. Secondary validation drew from SEC 10-K filings of listed refractory platforms, ECHA REACH registration databases, Japanese METI energy efficiency benchmark disclosures, and customs trade data for fluorite and magnesia concentrate flows. Bottom-up volume modeling triangulated against top-down value estimates from identified supplier revenue disclosures.
Scenario-bracketing framed low, base, and high cases across the projection horizon without assuming linear progression. Segmentation dimensions modeled included product type tier, application chemistry, end-user procurement sophistication, and regional regulatory cluster intensity. CAGRs derived from slope analysis of segment-specific growth trajectories, cross-referenced against steel production capacity expansion schedules and automotive lightweighting penetration curves for aluminum foundry demand.
Practitioners should monitor ECHA enforcement acceleration, Chinese magnesia export license tightening, and METI benchmark revision cycles for early signals of forecast deviation. Macroeconomic steel demand contraction, regulatory timeline compression, or breakthrough fluoride-free thermal insulation performance would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.