
 Anionic Flocculants Market | 2026-2036
Anionic Flocculants Market Size, Share, and Industry Trends Forecast 2026-2036
Anionic Flocculants Market Analysis
Direct supply contracts between polymer manufacturers and municipal water authorities is tilting procurement away from distributor intermediaries. SNF Floerger leverages its backward integration into acrylamide monomer production to control raw material costs across European utilities. Kemira OYJ anchors its position through captive R&D facilities in Finland that tailor molecular weight distributions to regional sludge characteristics. Solenis competes by embedding technical service teams directly at pulp and paper mill sites, converting product sales into performance-based contracts.
Anionic flocculants are water-soluble polymers carrying negatively charged functional groups, typically sulfonate or carboxylate moieties grafted onto polyacrylamide backbones with molecular weights ranging from 10 to 20 million Daltons, designed to neutralize and bridge positively charged suspended particles in aqueous systems. Polyacrylamide formulations dominate value capture due to their tunable charge density and shear stability under high-throughput clarifier operations. Powder and emulsion forms command premium positioning in mining tailings dewatering where rapid dissolution kinetics reduce basin retention times. Wastewater treatment applications now outpace water treatment in growth velocity as industrial discharge standards tighten across manufacturing-intensive basins.
EPA effluent guidelines under the Clean Water Act and REACH registration requirements for acrylamide monomer content shape product formulation thresholds and import compliance costs for suppliers serving North American and European utilities. China's MEE wastewater discharge standards and India's Central Pollution Control Board mandates for textile cluster effluent are forcing reformulation toward lower-toxicity polymer architectures. Stakeholders must monitor evolving polymer registration dossiers under REACH and state-level precursor chemical controls to anticipate reformulation timelines and regional supply reallocations.
Market Dynamics
EPA National Pollutant Discharge Elimination System permit tightening is compressing municipal procurement cycles and forcing utilities toward direct polymer manufacturer relationships, bypassing traditional chemical distribution networks.
Growth Catalysts
- MEE wastewater discharge standards:China's Ministry of Ecology and Environment rules are redirecting industrial procurement toward high-charge-density polyacrylamide formulations in coastal manufacturing zones.
- Textile cluster effluent mandates:India's Central Pollution Control Board requirements are accelerating polymer consumption in dyeing and finishing operations across Tamil Nadu and Gujarat.
- Electronics fabrication effluent:Semiconductor wafer fabrication plants in South Korea and Taiwan are expanding anionic flocculant dosing for heavy metal precipitation and suspended solids removal.
Market Restraints
- Acrylamide monomer price volatility:Propylene feedstock cost swings and acrylonitrile supply tightness transmit directly to polymer manufacturing economics.
- REACH registration requirements:ECHA dossier maintenance costs and monomer content thresholds create compliance friction for suppliers serving European utilities.
- Natural flocculant substitution:Chitosan and starch-based alternatives are capturing niche applications in food-processing and cosmetic wastewater streams.
Strategic Opportunities
- Indonesia industrial corridor expansion:Batang integrated chemical parks and Morowali nickel processing zones lack established polymer supply infrastructure.
- Performance-based contracting:Municipal utilities in Germany and the Netherlands are piloting sludge dewatering efficiency guarantees tied to polymer dosage optimization.
- Dual carbon goals procurement:China's state-owned enterprises must source lower-carbon-intensity polymer production methods to meet Scope 3 reduction targets.
Industry Challenges
- Polymer characterization expertise shortage:Molecular weight distribution analysis and charge density titration require specialized analytical chemists scarce in regional water authorities.
- Legacy clarifier retrofit complexity:Aging circular basin infrastructure in US Rust Belt municipalities cannot accommodate high-molecular-weight polymer feed systems without mechanical upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anionic Flocculants Market |
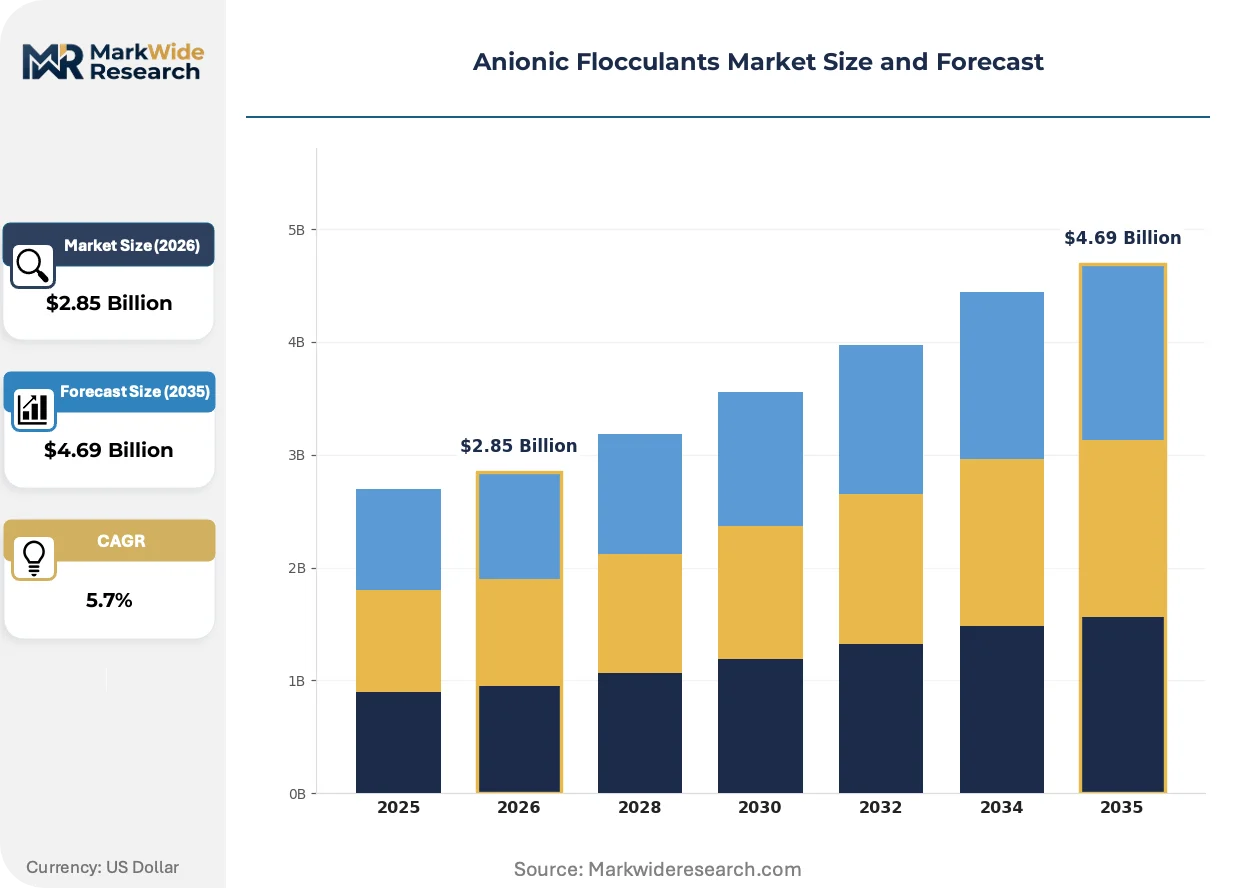
| Market Size in 2026 | $2.85 Billion |
| Market Size in 2035 | $4.69 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyacrylamide, Starch, Cellulose, Synthetic Polymers Application: Water Treatment, Wastewater Treatment, Mineral Processing, Papermaking Form: Granular, Powder, Liquid, Emulsion End User: Municipal, Industrial, Mining, Oil & Gas |
| Companies Covered | Ecolab Inc., Feralco AB, SNF Floerger, Buckman Laboratories, Solvay, Kemira OYJ, Solenis LLC, Kurita Water Industries Ltd., BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anionic Flocculants Market Emerging Trajectories
Digital dosing control systems and molecular architecture customization are compressing the gap between laboratory formulation and field performance validation.
Automated polymer make-down systems with real-time viscosity feedback are virtualizing the traditional field-trial process. Mining tailings operators in Chile and Australia are deploying these units to eliminate manual batch preparation. The technology is virtualizing distributor technical service roles by embedding optimization algorithms directly at customer sites.
REACH authorization timelines for acrylamide monomer are extending reformulation lead times for European suppliers. Polymer manufacturers are accelerating low-toxicity backbone development to preempt regulatory restriction. Water utilities in France and Germany are demanding pre-registered polymer grades to de-risk procurement continuity.
Direct manufacturer-to-utility contracting is displacing regional chemical distribution networks. Municipal procurement departments in Texas and California are negotiating multi-year supply agreements with volume-flexibility clauses. This pattern is most visible in US Sun Belt states where population growth is straining existing water treatment capacity.
Anionic Flocculants Market Segmentation
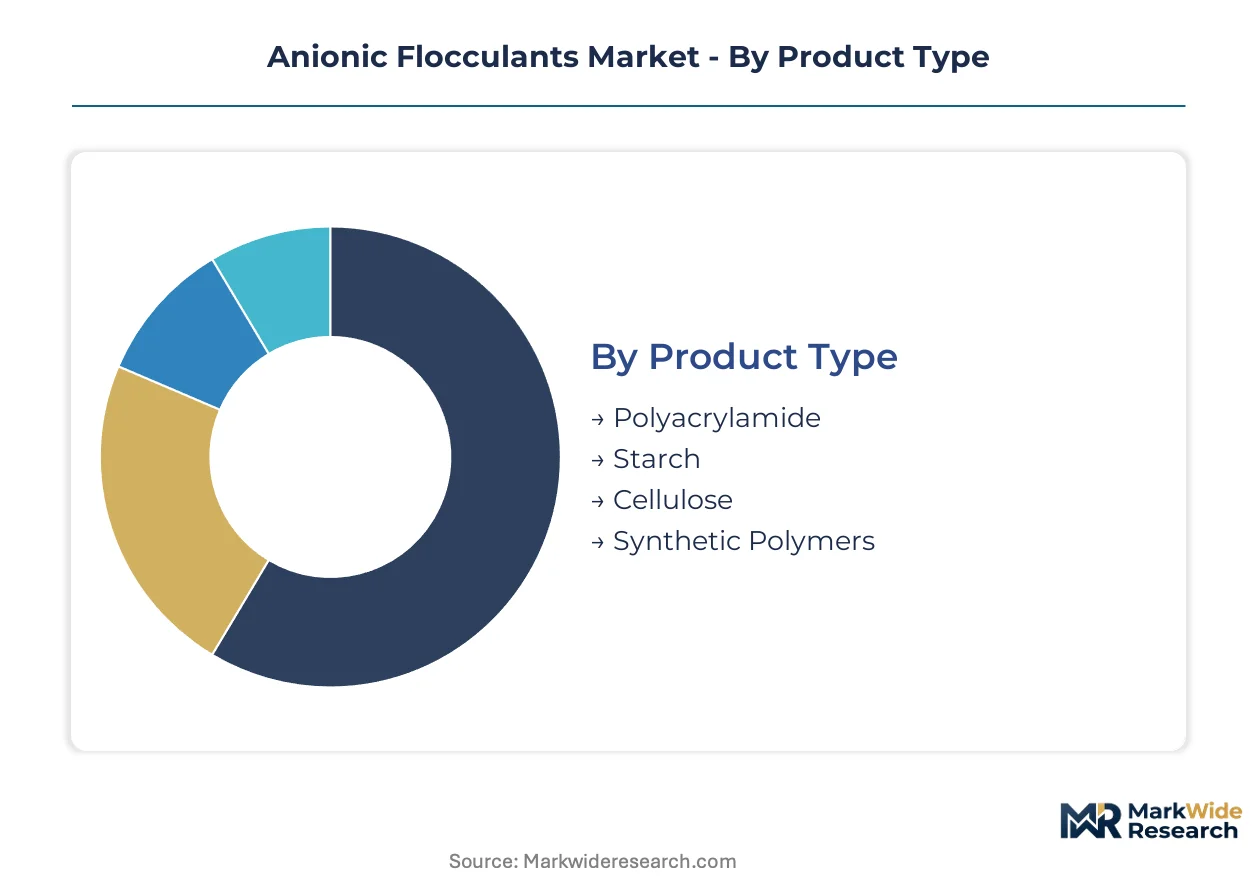
Segmentation in anionic flocculants reveals how polymer architecture, application intensity, and end-user procurement sophistication create distinct competitive arenas. Manufacturers configure product portfolios across these dimensions to match technical service capabilities with customer operational complexity.
Product Type:
Polyacrylamide formulations dominate mature industrial applications while bio-based alternatives carve emerging niches in food-contact and cosmetic wastewater streams.
- Polyacrylamide:Synthetic polymers with tunable charge density and molecular weight distributions from 10 to 20 million Daltons anchor municipal water treatment and mining tailings dewatering. China's MEE wastewater discharge standards are redirecting procurement toward high-charge-density formulations in coastal manufacturing zones.
- Starch:Bio-derived polysaccharide flocculants from corn and potato feedstocks serve food-processing effluent where synthetic polymer residues face regulatory scrutiny. India's Central Pollution Control Board mandates for textile cluster effluent are accelerating adoption in Tamil Nadu dyeing operations.
- Cellulose:Modified cellulose ethers from wood pulp derivatives offer moderate charge density for papermaking white water clarification.
- Synthetic Polymers:Polyacrylic acid and polyethyleneimine alternatives provide specialized performance in electronics fabrication heavy metal precipitation.
Polyacrylamide retains volume leadership; starch holds the steepest expansion curve.
Application:
Application segmentation tracks the shift from clean water production toward contaminated stream remediation as discharge standards tighten across manufacturing-intensive basins.
- Wastewater Treatment:Industrial effluent clarification and sludge dewatering now outpace water treatment in growth velocity. Semiconductor wafer fabrication plants in South Korea and Taiwan are expanding dosing for suspended solids removal and heavy metal precipitation.
- Water Treatment:Municipal raw water clarification for potable supply remains the volume foundation. US utilities under EPA National Pollutant Discharge Elimination System permit tightening are compressing procurement cycles toward direct manufacturer relationships.
- Mineral Processing:Mining tailings thickening and fines recovery demand rapid-dissolution kinetics to reduce basin retention times in Chilean copper and Australian iron ore operations.
- Papermaking:White water clarification and fiber retention in integrated pulp and paper mills require shear-stable molecular architectures.
Water treatment commands installed base dominance; wastewater treatment is climbing the fastest.
Form:
Physical form selection balances dissolution kinetics against handling economics and automated system compatibility.
- Emulsion:Liquid polymer dispersions with rapid inversion characteristics command premium positioning in mining tailings dewatering where manual batch preparation is being eliminated. Chilean and Australian operators deploy automated make-down systems with real-time viscosity feedback.
- Powder:Spray-dried granular grades offer lowest unit cost for high-volume municipal utilities with established dry-feed infrastructure. Aging circular basin infrastructure in US Rust Belt municipalities cannot accommodate high-molecular-weight powder feed systems without mechanical upgrades.
- Liquid:Pre-hydrolyzed solutions suit small-scale industrial users lacking polymer make-down expertise.
- Granular:Coarse-grade particulates bridge powder economy with emulsion handling convenience for mid-scale papermaking operations.
Powder retains cost-driven volume leadership; emulsion holds the steepest expansion curve.
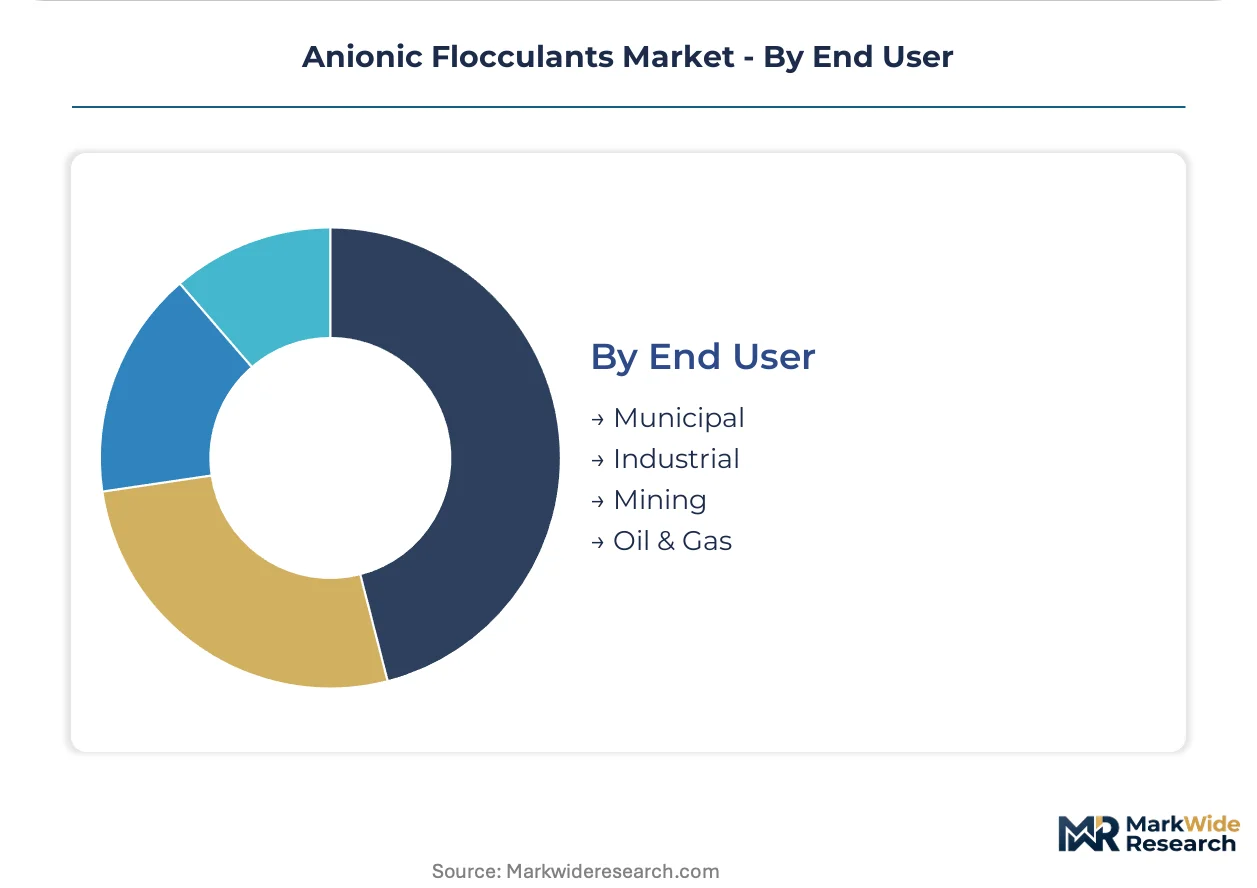
End User:
End-user segmentation exposes divergent procurement sophistication between municipal utilities and resource extraction operators.
- Municipal:Water and wastewater authorities in Texas and California are negotiating multi-year direct supply agreements with volume-flexibility clauses. Population growth in US Sun Belt states is straining existing treatment capacity and accelerating polymer consumption.
- Industrial:Manufacturing facilities across China's coastal chemical parks face dual carbon goals procurement requirements for lower-carbon-intensity polymer production methods. State-owned enterprises must meet Scope 3 reduction targets.
- Mining:Tailings dewatering operators demand performance-based contracting with sludge dryness guarantees. Indonesian Batang integrated chemical parks and Morowali nickel processing zones lack established polymer supply infrastructure.
- Oil & Gas:Produced water treatment in unconventional extraction requires salt-tolerant polymer architectures for high-TDS brine clarification.
Municipal captures volume leadership; industrial is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta's integrated chemical port infrastructure underwrites China's dominance in polymer feedstock logistics and coastal manufacturing effluent treatment capacity.
United States
Texas and California municipal utilities negotiate multi-year direct supply agreements with volume-flexibility clauses as population growth strains Sun Belt water treatment infrastructure. EPA National Pollutant Discharge Elimination System permit tightening compresses procurement cycles toward manufacturer-direct relationships. Rust Belt municipalities face legacy clarifier retrofit complexity that blocks high-molecular-weight polymer adoption without mechanical upgrades.
China
MEE wastewater discharge standards redirect industrial procurement toward high-charge-density polyacrylamide formulations across coastal manufacturing zones. Dual carbon goals procurement requirements force state-owned enterprises to source lower-carbon-intensity polymer production methods for Scope 3 reduction compliance. Yangtze River Delta textile dyeing and electronics fabrication clusters concentrate demand for heavy metal precipitation and suspended solids removal applications.
Germany
REACH registration requirements for acrylamide monomer content create compliance friction that extends reformulation lead times for European suppliers. Municipal utilities in the Netherlands and Germany pilot performance-based contracting with sludge dewatering efficiency guarantees tied to polymer dosage optimization. ECHA dossier maintenance costs drive water utilities toward pre-registered polymer grades to de-risk procurement continuity.
India
Central Pollution Control Board mandates for textile cluster effluent accelerate polymer consumption across Tamil Nadu and Gujarat dyeing operations. Food-processing wastewater streams in Punjab and Maharashtra adopt starch-based bio-flocculants where synthetic polymer residues face regulatory scrutiny. National clean river missions under Namami Gange expand municipal dosing capacity in upstream industrial corridors.
Indonesia
Batang integrated chemical parks and Morowali nickel processing zones lack established polymer supply infrastructure, creating greenfield procurement opportunities. Mining tailings operators demand rapid-dissolution emulsion formulations to reduce basin retention times in nickel-cobalt extraction circuits. Domestic manufacturing capacity gaps force reliance on Singapore and Malaysian distributor networks for technical service support.
Anionic Flocculants Market Vendor Landscape
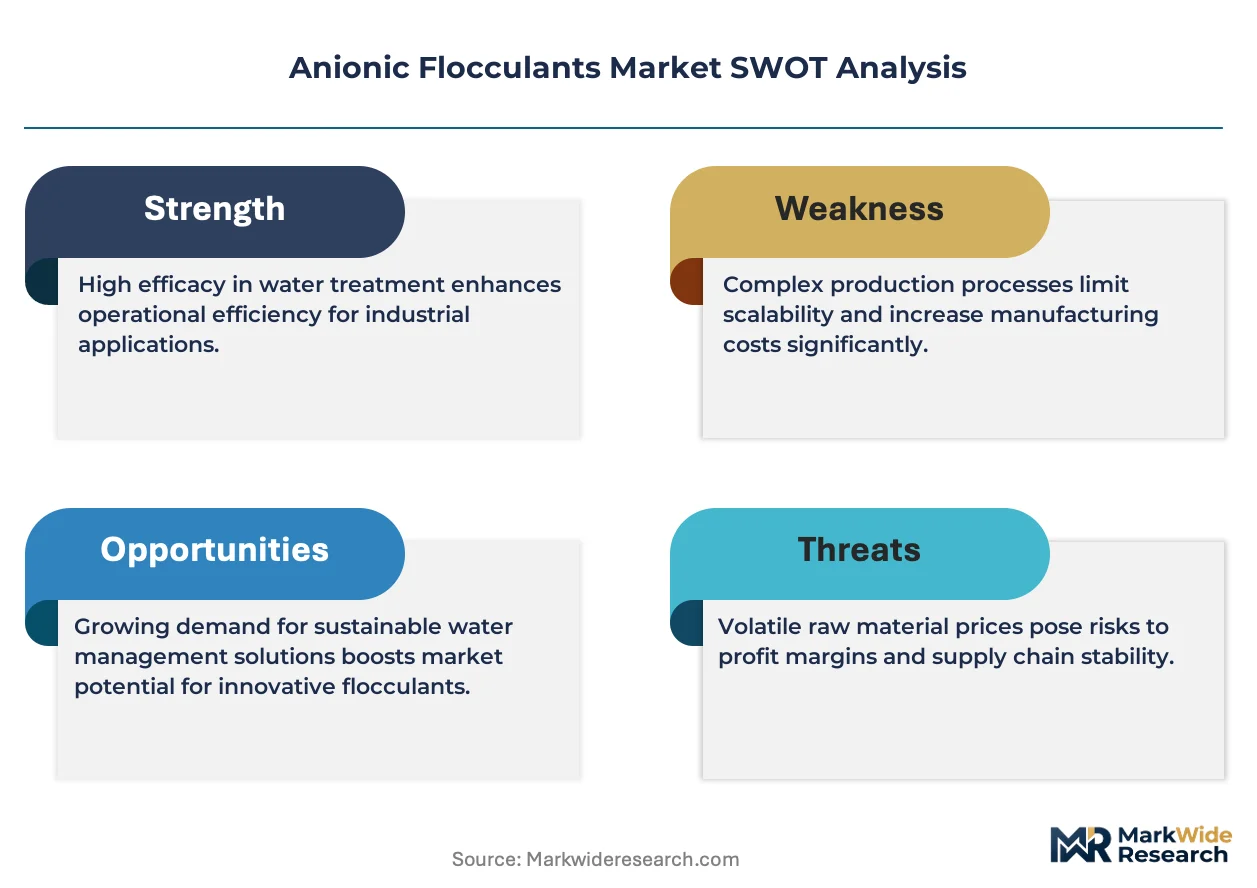
On the supply side, the industry is consolidating around backward-integrated acrylamide producers and technical service-embedded specialists. Three strategic archetypes dominate: monomer-integrated polymer manufacturers with feedstock cost control, application-engineered solution providers with captive R&D facilities, and distributor-dependent regional blenders with formulation flexibility. Competitive moves concentrate on direct manufacturer-to-utility contracting displacement of distribution networks and performance-based sludge dewatering guarantees.
Within the monomer-integrated tier, SNF Floerger and BASF SE exemplify upstream control strategies that anchor polymer manufacturing economics against propylene feedstock volatility. Kemira OYJ and Solenis LLC occupy positions as application-engineered specialists, embedding technical service capabilities directly at industrial customer sites to convert product sales into outcome-based contracts. Ecolab Inc. represents the diversified water treatment platform archetype, leveraging cross-selling infrastructure across municipal and industrial verticals.
| Leading Market Players |
|---|
| Ecolab Inc. |
| Feralco AB |
| SNF Floerger |
| Buckman Laboratories |
| Solvay |
| Kemira OYJ |
| Solenis LLC |
| Kurita Water Industries Ltd. |
| BASF SE |
| Others |
Supply Flow & Price Mechanics
Acrylamide monomer production concentration in China and Western Europe funnels margin capture toward backward-integrated polymer manufacturers with captive feedstock supply. Municipal utilities and mining operators downstream face asymmetric negotiating leverage against these integrated suppliers.
Pricing Analysis
Volume-discount tiering separates municipal utilities with multi-year offtake commitments from spot-buying industrial facilities and premium-priced emulsion grades for mining tailings applications. Pricing stratifies across premium, standard, and economy tiers based on molecular weight distribution precision and charge density certification. Cost compression in standard-grade powder formulations is intensifying because propylene feedstock volatility transmits directly through acrylonitrile supply chains. Municipal procurement departments exhibit highest price sensitivity due to budget-constrained capital cycles, while mining tailings operators prioritize dewatering performance guarantees over unit cost.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from integrated manufacturers are locking in municipal utility relationships against distributor intermediaries. Manufacturing concentration rests on China, France, and the United States for polyacrylamide backbone production, drawing from acrylonitrile feedstocks anchored in Gulf Coast petrochemical complexes and Chinese coal-to-chemicals corridors. Single-source vulnerability around acrylamide monomer supply creates exposure to REACH authorization delays and MEE environmental enforcement actions. Distribution runs through direct manufacturer-to-utility contracting in North America and Europe, while Asian markets retain layered distributor networks for technical service localization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Municipal utility procurement consolidation into direct manufacturer relationships is shifting buyer power toward volume-aggregated water authorities and away from fragmented regional distributors.
For Market Incumbents: Insulate position by deepening captive acrylamide production capacity in low-carbon-intensity manufacturing hubs to preempt China's dual carbon goals procurement requirements. Secure multi-year performance-based contracts with sludge dewatering efficiency guarantees to lock out distributor competitors from technical service relationships. For New Entrants and Emerging Players: Indonesia's Batang integrated chemical parks and Morowali nickel processing zones present greenfield supply infrastructure gaps where established polymer distributors lack technical service presence. Target rapid-dissolution emulsion formulations for mining tailings operators demanding automated make-down systems with real-time viscosity feedback. For Investors and Strategic Acquirers: Capital is best deployed toward application-engineered specialists with embedded R&D facilities capable of tailoring molecular weight distributions to regional sludge characteristics. Monitor REACH authorization timeline extensions for acrylamide monomer as an inflection signal for low-toxicity backbone development acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylamide Monomer | SNF Floerger's captive feedstock supply anchors polymer manufacturing economics against propylene volatility. |
| Performance-Based Contracting | German and Dutch municipal utilities pilot sludge dewatering efficiency guarantees tied to polymer dosage optimization. |
| Green Manufacturing Transition | China's state-owned enterprises must source lower-carbon-intensity polymer production methods for Scope 3 compliance. |
| Long-term Supply Agreement | Texas and California utilities negotiate multi-year direct supply agreements with volume-flexibility clauses. |
| Joint Venture | Indonesian Batang chemical parks lack established polymer supply infrastructure, creating partnership opportunities. |
Methodological Framework
Operator-level perspectives from municipal procurement officers, mining tailings engineers, pulp and paper mill technical directors, and polymer R&D chemists anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation against customs trade data, EPA NPDES permit filings, MEE wastewater discharge records, and SEC 10-K disclosures from listed chemical manufacturers. Bottom-up demand modeling across end-use segments triangulated against top-down supply-side capacity assessments.
Scenario-bracketing around regulatory enforcement intensity and feedstock price volatility framed the analytical approach across the projection horizon. Segmentation dimensions modeled include product form, charge density tier, application intensity, and regional manufacturing cluster. CAGRs derived from installed base expansion rates, replacement demand cycles, and penetration assumptions for automated dosing systems. Industry-specific inputs encompassed acrylamide monomer registration dossier timelines and municipal capital expenditure forecasts.
Practitioners should monitor REACH authorization progression, MEE enforcement actions against coastal chemical parks, and propylene-acrylonitrile spread compression for early signals of supply disruption or pricing inflection. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water & Sludge Treatment
North America Membrane Water and Wastewater Treatment (WWT) Market
Water & Sludge Treatment
Internal Boiler Treatment Chemicals Market
Water & Sludge Treatment
Ballast Water Treatment Market
Water & Sludge Treatment
Global Industrial Sludge Treatment Chemicals Market
Water & Sludge Treatment
Low-Dosage Hydrate Inhibitors (Ldhis) Market
Water & Sludge Treatment
Water Purification Systems Market
Water & Sludge Treatment
Industrial Wastewater Real-Time Toxicity Monitoring Test Systems Market
Water & Sludge Treatment
Liquid Waste Container Market
Water & Sludge Treatment
United States Water Treatment Chemicals Market
Water & Sludge Treatment
Mexico Water Treatment Chemicals Market
Water & Sludge Treatment
Produced Water Treatment Market
Water & Sludge Treatment
Industrial Water Treatment Chemicals Market
Water & Sludge Treatment
China Water Treatment Chemicals Market
Water & Sludge Treatment
Europe Water Treatment Chemicals Market
Water & Sludge Treatment
Global Turbidity Meters Market
Water & Sludge Treatment
Global Wet Waste Management Market