
 Rodenticides Market | 2026-2036
Rodenticides Market Size, Share, and Industry Trends Forecast 2026-2036
Rodenticides Market Analysis
The capital-intensity divergence between integrated formulators and commodity blenders is collapsing as active-ingredient synthesis costs rise and registration timelines lengthen. Bayer AG leverages captive a.i. production to sustain margin structures across European agricultural channels. BASF SE anchors its position through R&D intensity in second-generation anticoagulant chemistry. Syngenta AG competes by controlling distribution networks in Asia-Pacific grain belts.
Rodenticides are toxic chemical or biological formulations designed to control rodent populations through lethal or sub-lethal mechanisms, with anticoagulant variants typically containing coumarin or indandione derivatives that disrupt vitamin K-dependent clotting factors over multiple feeding cycles. These products serve agricultural, commercial, and residential sectors by protecting stored commodities, structural assets, and public health infrastructure from gnawing damage and zoonotic disease vectors. Anticoagulants occupy the largest value share due to established efficacy and regulatory familiarity, while natural rodenticides represent the fastest-expanding category as organic certification standards tighten across food-handling facilities. Bait stations command premium positioning within formulation types because they reduce non-target exposure and satisfy integrated pest management audit requirements.
The EPA governs rodenticide registration and label restrictions in the United States, while the EU Biocidal Products Regulation mandates comprehensive active-substance approval cycles that extend market access timelines. India's Central Insecticides Board enforces import and formulation standards that shape competitive entry for foreign manufacturers. Stakeholders must monitor evolving resistance profiles and substitution pressures as regulatory bodies weigh ecological risk against food-security imperatives.
Market Dynamics
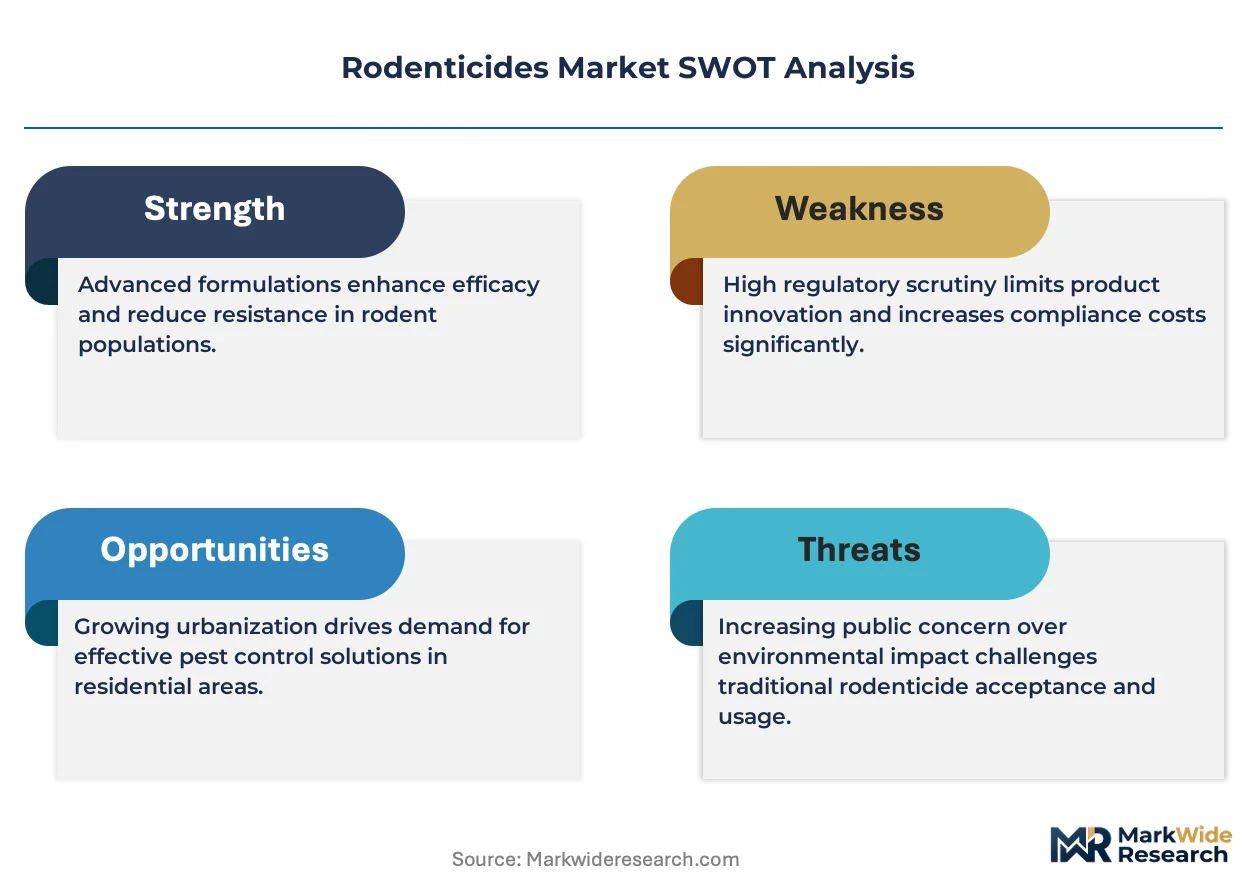
Anticoagulant resistance profiles are forcing formulation innovation cycles to compress across agricultural and urban pest management channels. EPA label restrictions on second-generation compounds have triggered a supply-side pivot toward alternative chemistries and delivery mechanisms.
Growth Catalysts
- FSSAI residue limit tightening:Indian agricultural warehousing operators face mandatory compliance deadlines for stored grain protection, accelerating certified anticoagulant procurement.
- State-backed silo modernization:China's grain-producing provinces require documented rodent management protocols, creating structured demand for bait station systems.
- Integrated pest management audit adoption:Food-handling facilities across North America and Europe now mandate bait station deployment for organic certification maintenance.
Market Restraints
- Active ingredient synthesis cost escalation:Coumarin and indandione derivative production faces feedstock volatility from specialty chemical suppliers concentrated in China and India.
- EU Biocidal Products Regulation timeline extension:Comprehensive active-substance approval cycles now stretch market access timelines for novel formulations.
- Biological substitute emergence:Natural rodenticides leveraging cholecalciferol and essential oil formulations capture share in premium organic segments.
Strategic Opportunities
- Underpenetrated African grain belt:Post-harvest storage infrastructure expansion in Nigeria and Kenya lacks standardized rodent management, creating first-mover positioning for certified suppliers.
- Smart bait station integration:Convergence of IoT sensors with mechanical delivery systems enables remote monitoring for commercial property management portfolios.
- India PLI scheme alignment:Domestic formulation manufacturing incentives support import substitution for foreign active ingredient dependencies.
Industry Challenges
- Toxicology specialist scarcity:Registration dossier preparation requires expertise in ecotoxicology and mammalian toxicology that outpaces academic pipeline output.
- Manufacturing facility reconfiguration:EPA risk mitigation decision compliance demands capital allocation toward containment infrastructure and non-target exposure prevention systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rodenticides Market |
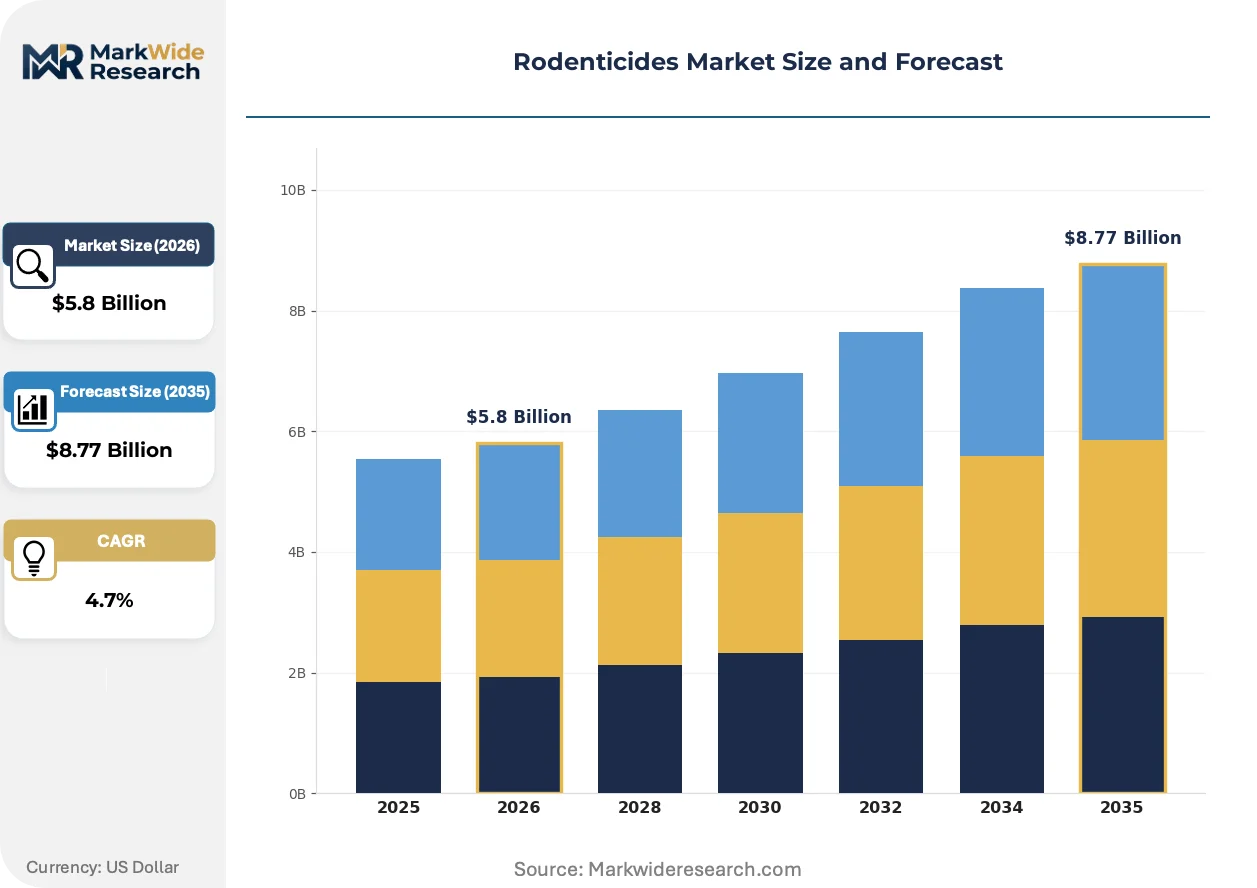
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $8.77 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anticoagulants, Non-Anticoagulants, Natural Rodenticides, Combination Rodenticides Application: Agricultural, Residential, Commercial, Industrial Formulation: Granular, Bait Stations, Soluble Powders, Pellets Distribution Channel: Online Retail, Offline Retail, Wholesale, Direct Sales |
| Companies Covered | Bayer AG, BASF SE, Syngenta AG, UPL Limited, Rentokil Initial plc, Liphatech, Bell Laboratories, Neogen Corporation, PelGar International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rodenticides Market Emerging Trajectories
Formulation chemistry and delivery hardware are diverging from legacy anticoagulant dominance toward precision-targeted systems and resistance-aware active ingredient portfolios. This shift reconfigures competitive advantage around regulatory navigation capability rather than manufacturing scale alone.
Micro-encapsulated bait technologies are fragmenting the traditional pellet and block formulation segments by enabling moisture-stable deployment in tropical storage environments. Large-scale grain elevator operators in Brazil and Southeast Asia are adopting these systems for monsoon-season protection. The technology is fragmenting procurement patterns away from commodity bulk purchases toward specification-driven vendor relationships with technical support obligations.
REACH authorization requirements for anticoagulant actives are compressing the viable product portfolio for European agricultural applications. Formulators must now submit comprehensive substitution plans and comparative efficacy data for continued market access. Grain storage cooperatives in Germany and France are accelerating transition timelines to avoid supply discontinuity during reauthorization windows.
Facility managers are unbundling rodenticide supply from integrated pest management service contracts, creating direct procurement relationships with certified product distributors. Food manufacturing plants in the United States are driving this pattern through vendor consolidation initiatives that separate chemical sourcing from application labor. The shift concentrates buying power among technical specification teams rather than outsourced service providers.
Rodenticides Market Segmentation
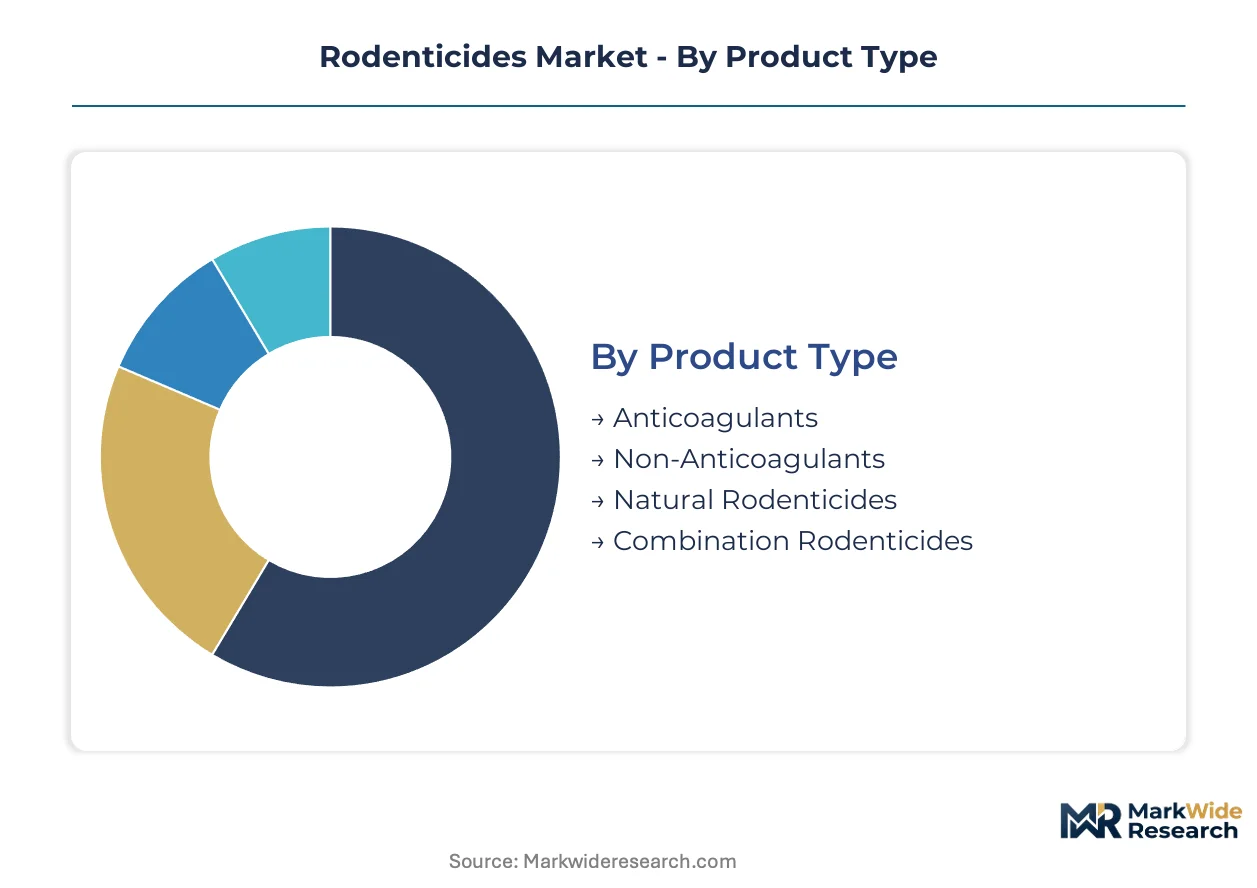
Rodenticide procurement patterns diverge sharply across end-use contexts, with agricultural buyers prioritizing bulk formulation economics while food-handling facilities demand certified bait station systems. Channel configuration directly shapes which product formats gain traction in each vertical.
Product Type:
Agricultural distributors push anticoagulant volumes through wholesale channels, while natural formulations command premium positioning in direct-to-facility supply contracts.
- Anticoagulants:Coumarin and indandione derivatives disrupt vitamin K-dependent clotting factors through multi-feed mechanisms. India's FSSAI-compliant warehousing sector drives procurement concentration as residue limit enforcement tightens on stored grains.
- Natural Rodenticides:Cholecalciferol and essential oil formulations target organic-certified facilities. North American food manufacturing plants mandate these for audit compliance, displacing synthetic alternatives in premium segments.
- Non-Anticoagulants:Acute toxicants including bromethalin and zinc phosphide serve resistance-management rotations.
- Combination Rodenticides:Multi-mechanism blends address heterogeneous rodent populations in tropical storage environments.
By volume, anticoagulants lead. By growth pace, natural rodenticides are expanding most quickly.
Application:
Cost tier stratification separates commodity agricultural procurement from specification-driven commercial contracts requiring technical support obligations.
- Agricultural:Grain elevator operators in Brazil and Southeast Asia specify moisture-stable micro-encapsulated systems for monsoon-season protection. China's state-backed silo modernization programs mandate documented rodent management protocols, creating structured demand for certified suppliers.
- Commercial:Food-handling facilities unbundle chemical sourcing from application labor, concentrating buying power among technical specification teams. Bait station deployment satisfies integrated pest management audit requirements.
- Residential:Home improvement retailers dominate channel access for homeowner-grade pellet and block formulations.
- Industrial:Manufacturing plants require perimeter defense systems with non-target exposure mitigation.
Agricultural applications command the largest shipment volumes. Commercial segments generate the steepest margin expansion.
Formulation:
Volume concentration favors granular and pellet formats, while margin accrues to precision-delivery systems with remote monitoring capability.
- Bait Stations:Tamper-resistant enclosures reduce non-target exposure and satisfy regulatory audit trails. Facility managers in North America and Europe mandate these for organic certification maintenance, fragmenting procurement toward specification-driven vendor relationships.
- Granular:Broadcast-applied grains serve agricultural perimeter treatments with lower unit economics. Brazilian soybean storage cooperatives favor these for cost-sensitive large-scale deployment.
- Pellets:Extruded formulations balance stability with palatability for residential and light commercial use.
- Soluble Powders:Concentrated active ingredients enable custom dilution for specialized application equipment.
Granular formulations move the highest tonnage. Bait stations are gaining share fastest in value terms.
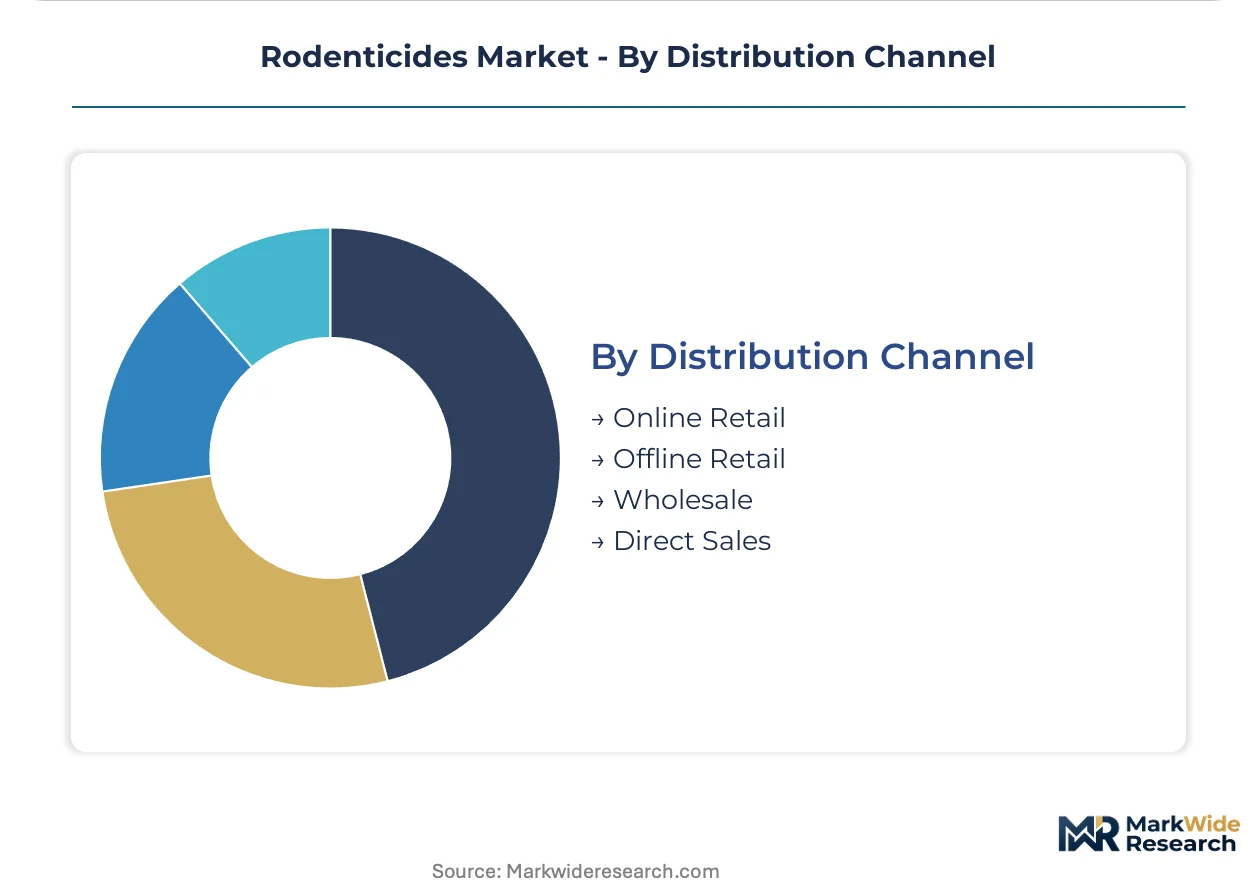
Distribution Channel:
Customer type determines channel selection, with wholesale dominating agricultural volume and direct sales capturing facility-level specification authority.
- Direct Sales:Technical specification teams at food manufacturing plants consolidate vendor relationships, bypassing outsourced service providers. Formulators with captive R&D capability anchor these accounts through efficacy documentation and regulatory dossier support.
- Wholesale:Agricultural supply cooperatives aggregate demand across grain-producing regions, concentrating procurement leverage. Indian domestic manufacturers leverage PLI scheme incentives to displace import dependencies in this channel.
- Offline Retail:Agricultural input stores and pest control distributors serve professional applicator segments.
- Online Retail:E-commerce platforms penetrate residential segments with homeowner-grade products and subscription replenishment models.
Wholesale channels handle the greatest product volume. Direct sales are climbing the fastest as facility managers consolidate specification authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in European formulators facing REACH authorization pressures, while procurement volume aggregates in Chinese state grain reserves and Indian agricultural warehousing where residue compliance deadlines accelerate certified product uptake.
United States
EPA label restrictions on second-generation anticoagulants compress formulation portfolios while elevating bait station specifications. Food manufacturing plants in the Midwest and Southeast consolidate vendor relationships through direct procurement channels. Chicago-area grain elevator operators specify moisture-stable micro-encapsulated systems for monsoon-season protection.
Germany
REACH authorization requirements for anticoagulant actives force comprehensive substitution plans from grain storage cooperatives. ECHA compliance timelines compress product transition windows. Bavarian agricultural distributors aggregate demand across Central European grain-producing regions.
China
State-backed silo modernization programs in Henan and Shandong provinces mandate documented rodent management protocols. SAMR certification requirements structure procurement toward approved suppliers. Yangtze River Delta chemical manufacturers supply active ingredient intermediates amid feedstock volatility.
India
FSSAI residue limit tightening on stored grains accelerates certified anticoagulant procurement by agricultural warehousing operators. PLI scheme incentives support domestic formulation manufacturing. Maharashtra and Gujarat-based grain processors face mandatory compliance deadlines.
Brazil
Soybean storage cooperatives in Mato Grosso and Rio Grande do Sul favor cost-sensitive granular formulations for large-scale deployment. ANVISA registration requirements shape competitive entry for foreign manufacturers. São Paulo-based distributors serve professional applicator segments through wholesale channels.
Rodenticides Market Vendor Landscape
Concentration sits with integrated agrochemical conglomerates possessing captive active ingredient synthesis and regulatory dossier capabilities. Mid-tier formulators compete through regional registration expertise and technical support relationships. Three archetypes dominate: vertically integrated multinational conglomerates, specialist toxicology houses with focused anticoagulant portfolios, and regional blenders serving price-sensitive agricultural channels. Competitive moves center on M&A for registration asset accumulation and capacity expansion in tropical formulation facilities.
Among European-based conglomerates, Bayer AG and BASF SE exemplify integrated archetypes with captive production structures. Syngenta AG occupies a position emphasizing distribution network control. Specialist houses including Liphatech and Bell Laboratories represent focused toxicology expertise. UPL Limited anchors the India-facing formulation tier. Rentokil Initial plc exemplifies service-led channel integration.
| Leading Market Players |
|---|
| Bayer AG |
| BASF SE |
| Syngenta AG |
| UPL Limited |
| Rentokil Initial plc |
| Liphatech |
| Bell Laboratories |
| Neogen Corporation |
| PelGar International |
| Others |
Supply Flow & Price Mechanics
Cholecalciferol substitution for legacy anticoagulant actives simultaneously redraws supply geography toward vitamin D feedstock producers and compresses pricing economics for coumarin-dependent formulators facing feedstock volatility from Chinese and Indian specialty chemical suppliers.
Pricing Analysis
The customization-premium spread separates specification-driven bait station procurement for organic-certified food facilities from commodity pellet pricing in agricultural wholesale channels. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and technical support bundling. Price erosion runs through standard-grade anticoagulant formulations as Indian PLI scheme incentives expand domestic manufacturing capacity. Agricultural distributors exhibit highest price sensitivity, while commercial facility managers prioritize audit compliance over unit cost.
Supply Chain Analysis
Inventory lead times for anticoagulant active ingredients have extended amid REACH authorization uncertainty and EPA risk mitigation decision compliance requirements. Supply concentrates in China for coumarin and indandione derivative intermediates, in India for formulation manufacturing, and in Germany for precision delivery system components. Raw material dependencies include naphthalene feedstocks, vitamin D3 precursors, and tamper-resistant polymer resins. Single-source vulnerability characterizes Chinese intermediate supply for European formulators. Distribution runs through agricultural supply cooperatives for bulk volume and direct technical sales for certified commercial accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The rodenticides market is entering a cyclical recovery phase as post-pandemic food security investments and silo modernization programs across grain-producing regions drive replacement demand for certified rodent management systems.
For Market Incumbents: Fortify registration asset portfolios through accelerated dossier preparation for EU Biocidal Products Regulation reauthorization windows. Captive production of anticoagulant actives insulates margin structures against Chinese feedstock volatility. Prioritize technical support infrastructure expansion in India's FSSAI-compliant warehousing sector to anchor long-term supply contracts. For New Entrants and Emerging Players: Differentiate on smart bait station integration with IoT-enabled remote monitoring capabilities for commercial property management portfolios. White-space opportunities concentrate in Nigeria and Kenya's underpenetrated grain belt storage infrastructure. Pursue direct procurement relationships with North American food manufacturing plants unbundling chemical sourcing from integrated pest management service contracts. For Investors and Strategic Acquirers: Capital is best deployed toward specialist toxicology houses possessing focused anticoagulant portfolios and established regulatory dossier capabilities. Long-term viability hinges on substitution chemistry expertise as resistance profiles evolve and natural rodenticide segments expand. Watch EPA registration timeline compression for second-generation compound alternatives as the inflection signal for portfolio reconfiguration urgency.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Active Ingredient Synthesis | Bayer AG's captive production sustains margin structures amid Chinese feedstock volatility. |
| Smart Bait Station Development | IoT sensor convergence enables remote monitoring for commercial property management portfolios. |
| EU Biocidal Products Regulation Dossier Expansion | Comprehensive substitution plans secure continued market access during reauthorization windows. |
| India PLI Scheme Alignment | Domestic formulation manufacturing incentives support import substitution for foreign dependencies. |
| African Grain Belt Market Entry | First-mover positioning in Nigeria and Kenya leverages post-harvest storage infrastructure expansion. |
Methodological Framework
Desk research of regulatory filings, customs trade databases, and agricultural commodity storage reports preceded structured interviews with agricultural warehousing procurement managers, pest control distributor technical directors, food manufacturing facility managers, and regulatory affairs specialists at formulator companies. Secondary validation drew from EPA registration databases, ECHA authorization timelines, FSSAI compliance circulars, and grain storage cooperative procurement records. Bottom-up demand aggregation across end-use segments was cross-checked against top-down market sizing from active ingredient production volumes.
Variance decomposition across product type, application vertical, formulation format, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth trajectory modeling. Industry-specific forecast inputs included FSSAI compliance deadline schedules, Chinese state grain reserve procurement cycles, and REACH authorization timeline assumptions.
The analysis sits within stated boundaries; outcomes outside sustained agricultural commodity price stability and regulatory enforcement continuity would require recalibration. Forecasts reflect documented assumptions regarding resistance profile evolution and substitution chemistry adoption curves. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Global Substrate Market
Industrial Chemicals
Mass Finishing Consumables Market
Industrial Chemicals
Food Grade Grease Market
Industrial Chemicals
Global Battery Grade Lithium Hydroxide Market
Industrial Chemicals
Diphenyl Oxide (DPO) Market
Industrial Chemicals
Bio Derived Enzymes for Detergents Market
Industrial Chemicals
Mold Powders and Casting Fluxes Market
Industrial Chemicals
Global Foundry Chemicals Market
Industrial Chemicals
Industrial Phosphate Market
Industrial Chemicals
Aluminium Production Chemicals Market
Industrial Chemicals
Global Alkylated Naphthalene Market
Industrial Chemicals
Nonylphenol Ethoxylate Market
Industrial Chemicals
Knitting Oils Market
Industrial Chemicals
Synthetic Gypsum Market
Industrial Chemicals
Global Continuous Stirred Tank Reactors Market
Industrial Chemicals
Global Antifreeze Market