
 Platinum Group Metals Market | 2026-2036
Platinum Group Metals Market Size, Share, and Industry Trends Forecast 2026-2036
Platinum Group Metals Market Intelligence
Streaming and royalty financing is rewriting capital access for junior platinum group metals developers, allowing asset-light entry into a capital-intensive sector. Anglo American Platinum leverages its integrated Bushveld operations to sustain mine-to-market margins. Norilsk Nickel anchors Russian palladium supply through its Norilsk-Talnakh deposits. Impala Platinum Holdings Limited specializes in mechanized extraction across its Rustenburg and Marikana shafts.
Platinum group metals comprise six transition elements—platinum, palladium, rhodium, ruthenium, iridium, and osmium—with platinum exhibiting a melting point of 1,768.3°C and exceptional catalytic surface activity for oxidation reactions. These metals serve primarily as heterogeneous catalysts in automotive exhaust treatment, petrochemical refining, and electrochemical energy conversion. Palladium commands the largest revenue share within the product type dimension, reflecting its dominance in gasoline catalytic converter formulations, while rhodium generates the highest unit margins due to extreme supply scarcity. The automotive end use industry remains structurally mature in light-duty applications but is pivoting toward platinum-intensive hydrogen fuel cell stacks.
The EPA tailpipe emission standards and the EU F-Gas Regulation shape catalyst loadings and substitution patterns across the automotive supply chain. South Africa's Department of Mineral Resources and Energy, alongside the country's Mining Charter, influences investment timelines and local beneficiation requirements for PGM producers. Stakeholders must monitor how hydrogen infrastructure build-out and battery-electric vehicle penetration rates alter the relative demand intensity for platinum versus palladium across transport applications.
Market Dynamics
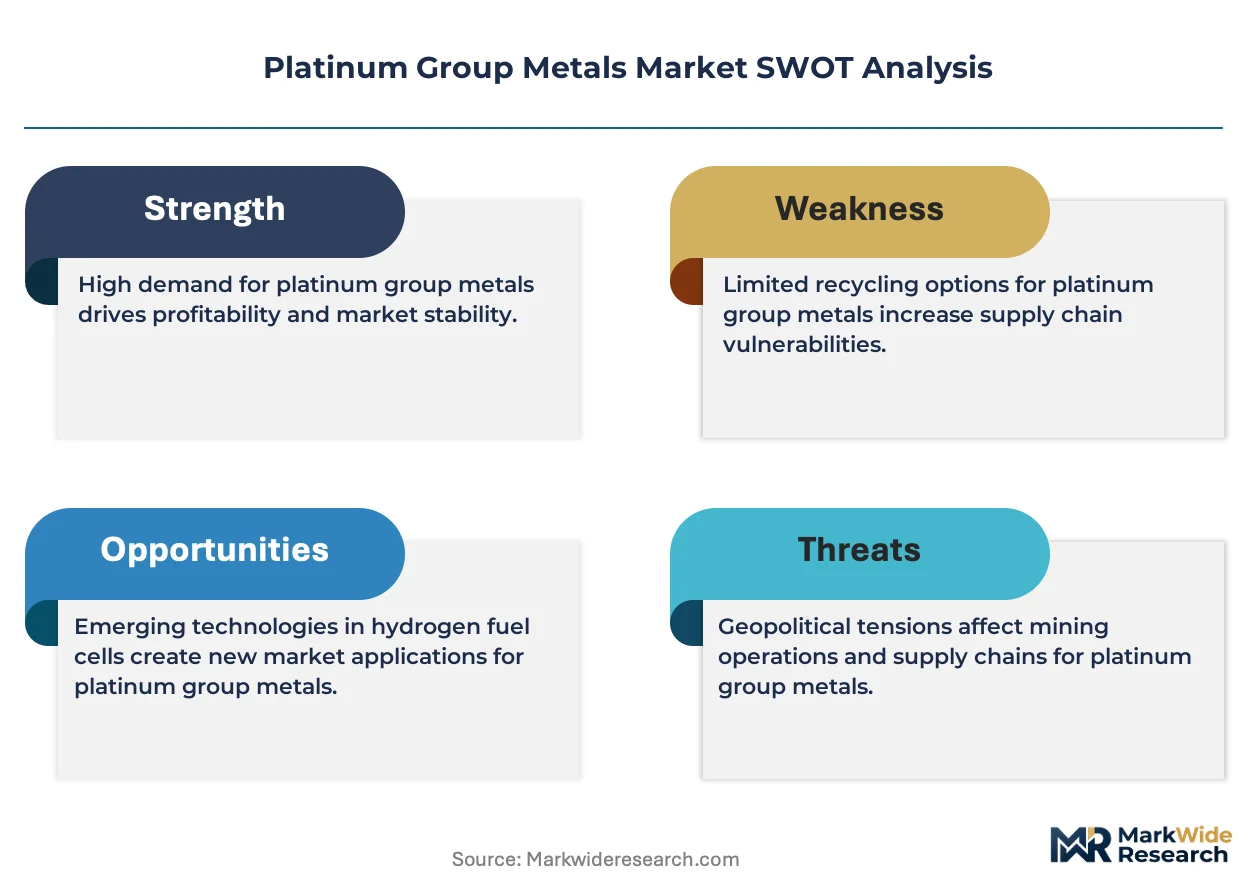
Hydrogen fuel cell stack technology is compressing the traditional palladium-gasoline catalytic converter nexus while South Africa's Bushveld supply concentration amplifies geopolitical exposure for automotive and industrial buyers.
Growth Catalysts
- EU Green Deal emission benchmarks:Tighter automotive catalyst specifications across member states are expanding platinum loadings in heavy-duty exhaust systems.
- Hydrogen fuel cell transport:Heavy-duty trucking and bus fleets are deploying platinum-intensive proton exchange membrane stacks for zero-emission logistics corridors.
- Streaming and royalty financing:Capital-light structures are unlocking development capital for junior PGM explorers in South Africa's Bushveld Complex.
Market Restraints
- Supply concentration risk:South Africa's Bushveld Complex hosts over 70% of primary platinum reserves, concentrating geopolitical and labor disruption exposure.
- Substitution threat:Battery-electric vehicle powertrains are displacing internal combustion engines and their palladium-loaded catalytic converters in light-duty segments.
- Input cost volatility:Diesel fuel and electricity price swings in South African mining operations compress all-in sustaining margins for underground extraction.
Strategic Opportunities
- Electrolyzer manufacturing scale-up:Proton exchange membrane electrolyzers for green hydrogen production represent a nascent platinum offtake channel outside automotive applications.
- US Inflation Reduction Act hydrogen incentives:Production tax credits for clean hydrogen are accelerating domestic electrolyzer deployment and platinum catalyst procurement.
- Recycling circuit expansion:Spent automotive catalyst recovery infrastructure in Germany and Japan is capturing above-ground platinum stocks as a secondary supply source.
Industry Challenges
- Deep-level mining automation:Mechanized extraction at depths exceeding 1,000 meters demands scarce mining engineers and robotics integration specialists.
- Beneficiation compliance timelines:South Africa's Mining Charter local content requirements extend project approval cycles for new concentrator investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Platinum Group Metals Market |
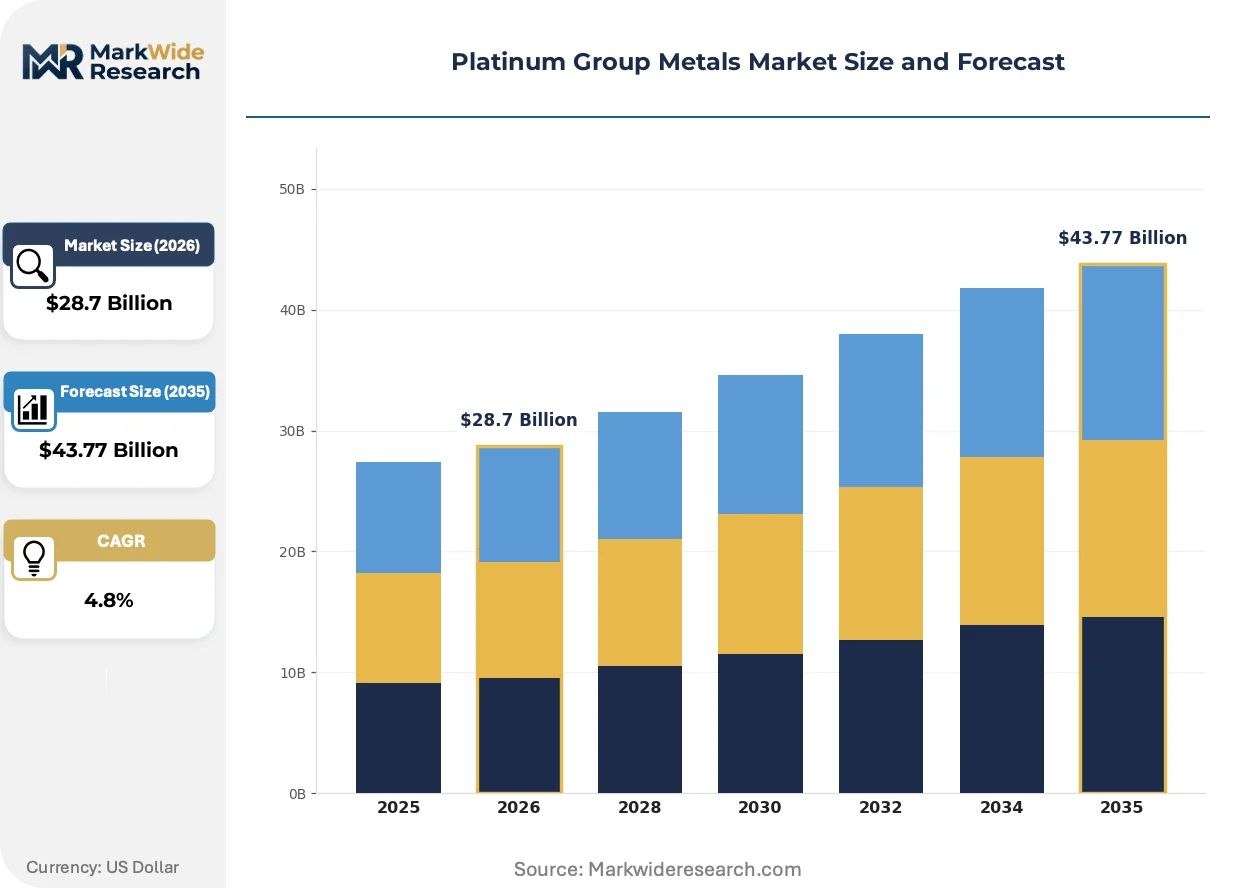
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $43.77 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Platinum, Palladium, Rhodium, Iridium End Use Industry: Automotive, Electronics, Jewelry, Chemical Application: Catalytic Converters, Electronics Manufacturing, Dental Alloys, Chemical Reactions Form: Granules, Powder, Sheet, Wire |
| Companies Covered | Anglo American Platinum, Norilsk Nickel, Impala Platinum Holdings Limited, Sibanye-Stillwater, Northam Platinum Holdings Limited, Glencore, African Rainbow Minerals Limited, Platinum Group Metals Limited, Johnson Matthey, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Platinum Group Metals Market Strategic Shifts & Innovations
Platinum group metals applications are bifurcating between declining gasoline catalyst demand and ascending hydrogen energy vectors, with processing technology and regulatory chemistry specifications evolving in parallel.
Proton exchange membrane fuel cell stacks are migrating from demonstration fleets to commercial heavy-duty transport contracts. Logistics operators in California and the Netherlands are deploying platinum-loaded fuel cell trucks for port-to-warehouse corridors. This technology migration is compressing the timeline for platinum demand displacement of palladium in transport applications.
The EPA tailpipe emission standards are tightening nitrogen oxide limits for diesel powertrains. Engine manufacturers are responding with higher platinum-rhodium loadings in selective catalytic reduction systems. Heavy-duty truck OEMs in the US and EU are reformulating catalyst substrates to meet the new compliance thresholds.
Buyers are consolidating procurement contracts around long-term offtake agreements with South African concentrate producers. Tier-1 automotive suppliers are bypassing traditional merchant metal markets to secure direct smelter allocations. This concentration pattern is most visible in German and Japanese catalyst manufacturing clusters where volume commitments now span five-year horizons.
Platinum Group Metals Market Segmentation
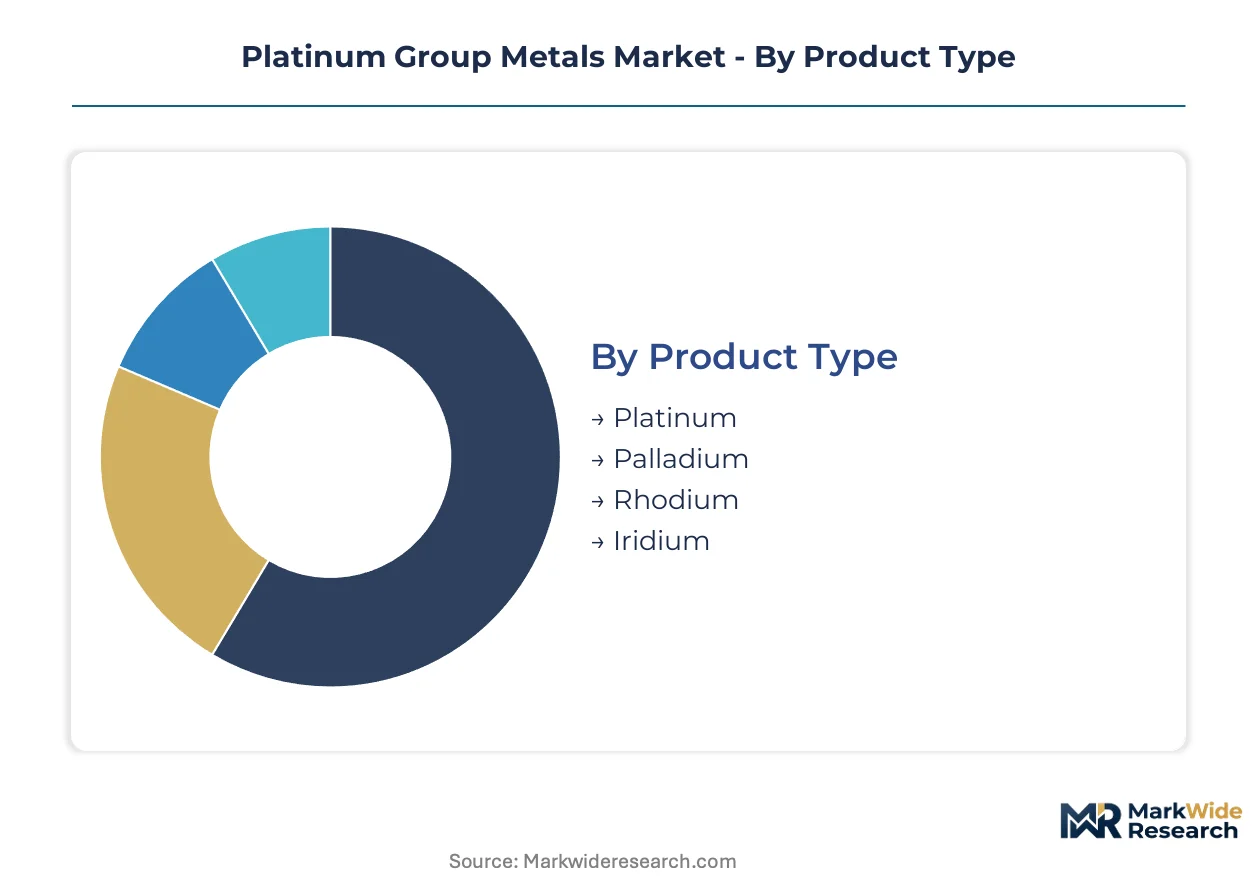
Platinum group metals exhibit divergent demand profiles across elemental, industrial, and physical form dimensions. Segmentation reveals how palladium's gasoline catalyst dominance contrasts with platinum's hydrogen energy pivot, while form factors determine processing economics for downstream fabricators.
Product Type:
Elemental composition defines pricing volatility, supply security, and substitution elasticity across industrial procurement strategies.
- Palladium:A silvery-white metal with density of 12.02 g/cm³ and exceptional hydrogen absorption capacity. Gasoline catalytic converter loadings in German and Japanese automotive plants consume the majority of primary offtake, though battery-electric vehicle penetration in California and Norway is compressing long-term demand trajectories.
- Platinum:Dense, malleable, and corrosion-resistant with catalytic surface activity optimized for oxidation reactions. Heavy-duty diesel catalyst specifications from the EPA and proton exchange membrane fuel cell deployments in the Netherlands and California are redirecting procurement volumes toward this element.
- Rhodium:Rarest of the primary PGMs with reflectivity exceeding 80% across visible spectrum. Nitrogen oxide reduction chemistry in EU-compliant automotive systems drives concentrated demand from catalyst manufacturers in Stuttgart and Toyota City.
- Iridium:Highest density stable element with extreme hardness and oxidation resistance above 2,000°C. Spark plug electrodes and crucibles for single-crystal silicon growth in Japanese semiconductor foundries anchor niche offtake channels.
Palladium commands the established base. The steepest expansion runs through platinum.
End Use Industry:
Application maturity varies sharply across sectors, with automotive incumbent dominance yielding to emerging hydrogen and electronics vectors.
- Automotive:Exhaust aftertreatment systems consume the majority of palladium and rhodium units, while platinum loadings rise in heavy-duty diesel compliance hardware. The EU F-Gas Regulation and EPA Tier 3 standards are reformulating catalyst substrate specifications across powertrain categories.
- Chemical:Platinum-ruthenium catalysts facilitate nitric acid production and silicone polymerization. Petrochemical crackers along the US Gulf Coast and Rotterdam harbor complexes maintain steady offtake for process optimization.
- Electronics:Ruthenium barrier layers in copper interconnects and iridium electrodes in capacitors serve semiconductor miniaturization. South Korean and Taiwanese fabrication facilities drive precision metal sourcing requirements.
- Jewelry:Platinum's hypoallergenic properties and tarnish resistance sustain premium positioning in Chinese and Indian consumer markets. Fabrication demand tracks discretionary spending cycles in Shanghai and Mumbai retail corridors.
Automotive absorbs the volume concentration. Chemical applications are climbing the fastest.
Application:
Functional deployment determines metal specification, purity requirements, and recycling recovery rates across value chain nodes.
- Catalytic Converters:Honeycomb substrates coated with platinum-group washcoats transform toxic exhaust constituents into benign emissions. Three-way catalyst formulations in gasoline engines and selective catalytic reduction systems in diesel powertrains define the dominant demand architecture.
- Chemical Reactions:Heterogeneous catalysts accelerate hydrogenation, dehydrogenation, and oxidation processes in pharmaceutical and petrochemical synthesis. Batch reactor configurations in Basel and Ludwigshafen chemical complexes specify high-surface-area platinum and ruthenium preparations.
- Electronics Manufacturing:Sputtering targets, plating baths, and conductive pastes incorporate ruthenium, iridium, and osmium for thin-film deposition. Hard disk drive media and chip packaging applications in Japanese and South Korean facilities drive ultra-high-purity sourcing.
- Dental Alloys:Platinum-palladium-gold mixtures provide biocompatibility and mechanical durability for crowns and bridges. German and Swiss dental laboratories specify certified alloy compositions for prosthetic fabrication.
Catalytic converters retain the incumbent position. Chemical reactions are gaining share fastest.
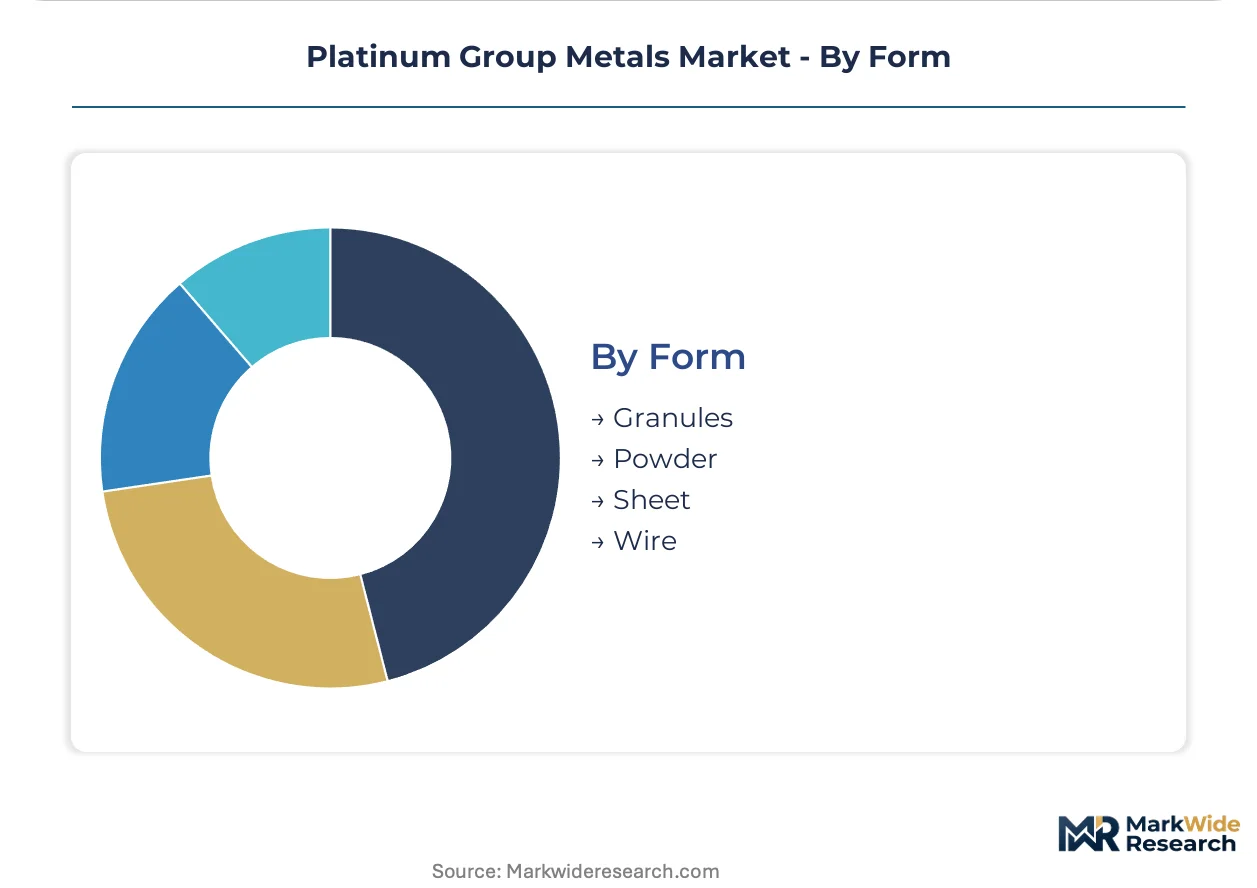
Form:
Physical configuration dictates downstream processing economics, transportation logistics, and inventory carrying costs for fabricators and refiners.
- Powder:Finely divided metal particles with high surface-area-to-mass ratios enable catalyst ink formulation and powder metallurgy compaction. Fuel cell membrane electrode assembly manufacturers in California and Bavaria specify platinum black and carbon-supported platinum nanoparticles.
- Granules:Cast droplets with controlled particle size distribution facilitate melting and alloying operations. Jewelry manufacturers and dental alloy producers in Milan and Shenzhen prefer this form for batch furnace charging.
- Sheet:Rolled plate and foil configurations serve electrochemical cell electrodes and laboratory apparatus. Electrolyzer stack assemblers in Denmark and Canada procure platinum-coated titanium sheet for proton exchange membrane hardware.
- Wire:Drawn filament with precise diameter tolerance enables spark plug electrodes, thermocouples, and electrical contacts. Automotive ignition system suppliers in Nagoya and Detroit specify iridium and platinum wire for high-voltage durability.
Granules dominate established fabrication channels. Powder is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Inflation Reduction Act's hydrogen production tax credits and the EU Green Deal's emission benchmarks are redirecting platinum procurement toward electrolyzer manufacturing and heavy-duty fuel cell deployment across North America and Europe.
United States
California's zero-emission truck mandates and the Department of Energy's hydrogen hub program are accelerating proton exchange membrane electrolyzer procurement. The EPA tailpipe emission standards tighten nitrogen oxide limits for diesel powertrains, forcing higher platinum-rhodium loadings in selective catalytic reduction systems. Houston's petrochemical corridor and Detroit's automotive catalyst manufacturing clusters are consolidating long-term offtake agreements with South African concentrate producers.
Germany
The EU F-Gas Regulation and national hydrogen strategy are expanding electrolyzer manufacturing capacity for export markets. Stuttgart's automotive catalyst fabricators are reformulating substrates to meet tightened EU emission benchmarks for heavy-duty diesel compliance. The country's national chemical regulator enforces REACH compliance for catalyst precursors, extending approval cycles for new platinum-based formulations.
Japan
METI's hydrogen roadmap and fuel cell vehicle deployment targets are sustaining platinum demand for automotive and stationary power applications. Toyota City's catalyst manufacturing facilities are pivoting toward platinum-intensive membrane electrode assemblies for heavy-duty transport. The country's national industrial standards body certifies ultra-high-purity metal specifications for semiconductor and electronics applications.
South Africa
The Department of Mineral Resources and Energy's Mining Charter mandates local beneficiation requirements for platinum group metals producers. Rustenburg and Marikana mining shafts in the Bushveld Complex concentrate over 70% of global primary platinum reserves, amplifying geopolitical exposure for international buyers. Labor disruption risks and electricity supply volatility compress all-in sustaining margins for deep-level mechanized extraction.
China
The Ministry of Industry and Information Technology's dual carbon goals and hydrogen energy development plans are expanding electrolyzer deployment for industrial decarbonization. Yangtze River Delta manufacturing clusters are scaling proton exchange membrane stack production for domestic heavy-duty transport markets. The national market regulator enforces GB standards for fuel cell system safety and performance certification.
Platinum Group Metals Market Key Industry Players
On the supply side, the industry is consolidated around a handful of integrated mining majors with captive smelting capacity and long-dated reserve positions in South Africa's Bushveld Complex. Strategic archetypes include vertically integrated Bushveld operators, Russian palladium-dominant producers, and mid-tier mechanized specialists. Dominant competitive moves center on streaming and royalty financing structures for capital-light expansion, alongside direct offtake contracting that bypasses traditional merchant metal markets.
Among South Africa-based integrated producers, Anglo American Platinum exemplifies the vertically integrated archetype through its mine-to-market Bushveld operations. Norilsk Nickel anchors the palladium-dominant supply position through its Russian deposit base. Impala Platinum Holdings Limited occupies a position within the mechanized extraction tier, specializing in shaft operations across the Rustenburg and Marikana complexes. These three entities collectively represent the supply-side concentration that defines procurement risk for automotive and industrial buyers.
| Leading Market Players |
|---|
| Anglo American Platinum |
| Norilsk Nickel |
| Impala Platinum Holdings Limited |
| Sibanye-Stillwater |
| Northam Platinum Holdings Limited |
| Glencore |
| African Rainbow Minerals Limited |
| Platinum Group Metals Limited |
| Johnson Matthey |
| Others |
Cost & Logistics Intelligence
Undercapacity in South Africa's Bushveld smelting infrastructure is amplifying concentrate treatment premiums while compressing mine-gate returns for junior producers. This utilization squeeze simultaneously tightens term contract availability for automotive buyers and elevates spot market volatility for merchant metal procurement.
Pricing Analysis
Metal purity certification level creates the primary spread between investment-grade bar and industrial catalyst precursor pricing. Long-term offtake contracts dominate procurement, with five-year tenors locking in premiums above spot benchmarks for automotive catalyst fabricators in Germany and Japan. Cost compression in palladium-loaded gasoline formulations is intensifying because battery-electric vehicle substitution erodes volume commitments. Tier-1 automotive suppliers exhibit the lowest price sensitivity due to regulatory compliance mandates, while jewelry fabricators in India and China face acute margin pressure from metal price swings.
Supply Chain Analysis
Upstream concentrate feedstock draws from South Africa, Russia, and Zimbabwe for primary platinum group metals supply. Mining inputs rest on diesel fuel, electricity, and specialized mechanized equipment for deep-level extraction. Single-source vulnerability concentrates in South Africa's Bushveld Complex, where labor disruptions and grid instability propagate through downstream smelter allocations. Distribution runs through integrated mining majors with captive refining capacity, bypassing traditional merchant metal exchanges for volume automotive contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The platinum group metals sector rewards operators who control scarce deep-level mining engineering talent and captive smelter throughput. Capability gaps in mechanized extraction automation and hydrogen catalyst formulation expertise are widening competitive moats between integrated majors and junior developers.
For Market Incumbents: Pre-empt substitution threats by accelerating platinum-intensive proton exchange membrane catalyst partnerships with electrolyzer manufacturers in Denmark and Canada. Secure backward integration into spent automotive catalyst recycling infrastructure in Germany and Japan to capture above-ground metal stocks. Deepen shaft mechanization at Rustenburg and Marikana complexes to compress all-in sustaining costs below junior producer breakevens. For New Entrants and Emerging Players: Hydrogen fuel cell membrane electrode assembly supply in California and the Netherlands represents the most penetrable entry point for non-integrated catalyst fabricators. Streaming and royalty financing structures on Bushveld exploration tenements offer asset-light exposure to metal price upside without operational risk. Target direct offtake contracting with proton exchange membrane electrolyzer assemblers rather than competing for automotive catalyst market share. For Investors and Strategic Acquirers: Capital is best deployed toward mechanized extraction specialists with demonstrated sub-1,000-meter shaft automation capabilities and compliant Mining Charter beneficiation track records. Long-term viability hinges on hydrogen infrastructure build-out sustaining platinum demand displacement of palladium across transport applications. Watch for US Inflation Reduction Act hydrogen hub deployment announcements as the inflection signal for electrolyzer manufacturing capacity expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Direct smelter allocations from Anglo American Platinum bypass volatile merchant metal exchanges for German automotive catalyst fabricators. |
| Backward Integration | Captive recycling infrastructure in Japan captures spent catalyst above-ground stocks as secondary palladium and rhodium supply. |
| Capacity Expansion | Mechanized shaft deepening at Bushveld Complex operations extends reserve life beyond competing Russian palladium deposits. |
| Joint Venture | Proton exchange membrane electrolyzer partnerships with California hydrogen hub operators secure platinum offtake outside automotive applications. |
| Green Manufacturing Transition | Renewable-powered smelter operations in South Africa align with EU Green Deal carbon border adjustments for European automotive buyers. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with mining engineers, automotive catalyst procurement managers, hydrogen fuel cell system integrators, and precious metals trading desks. Secondary validation drew from South African Department of Mineral Resources and Energy production statistics, USGS mineral commodity summaries, EPA emission standard filings, and EU F-Gas Regulation implementation reports. Bottom-up concentrate production estimates and top-down automotive catalyst loading requirements were triangulated to reconcile supply-demand balances.
Calibration against historical price volatility periods and regulatory implementation timelines anchored projection parameters across the analysis window. Segmentation modeling incorporated elemental composition, end-use industry, physical form, and regional regulatory cluster dimensions. CAGRs were derived from elasticity-adjusted demand curves for hydrogen infrastructure deployment and battery-electric vehicle substitution rates. Forecast inputs included Bushveld mining cost inflation trajectories and electrolyzer manufacturing capacity announcements.
Practitioners should monitor South African electricity supply stability, hydrogen hub deployment acceleration, and palladium substitution thresholds in gasoline catalyst formulations for early signals of forecast revision. Cross-checking against London Metal Exchange spot price series and automotive OEM powertrain mix disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Crude Steel Market
Metals
Titanium Market
Metals
Metal Powder Market
Metals
Global Flat Carbon Steel Market
Metals
Brazil Aluminum Market
Metals
Aluminum Powders Pastes and Flakes Market
Metals
Potassium Platinochloride Market
Metals
Global Flat Steel Market
Metals
Brazing Strips Market
Metals
Tungsten Metal Powder Market
Metals
Zinc Plating Market
Metals
Nickel Oxide Target Market
Metals
High Purity Base Metals Market
Metals
Lanthanum Market
Metals
Silver Sulphate Market
Metals
Palladium Market