
 South Africa Gypsum Plaster Market | 2026-2036
South Africa Gypsum Plaster Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Gypsum Plaster Market Intelligence
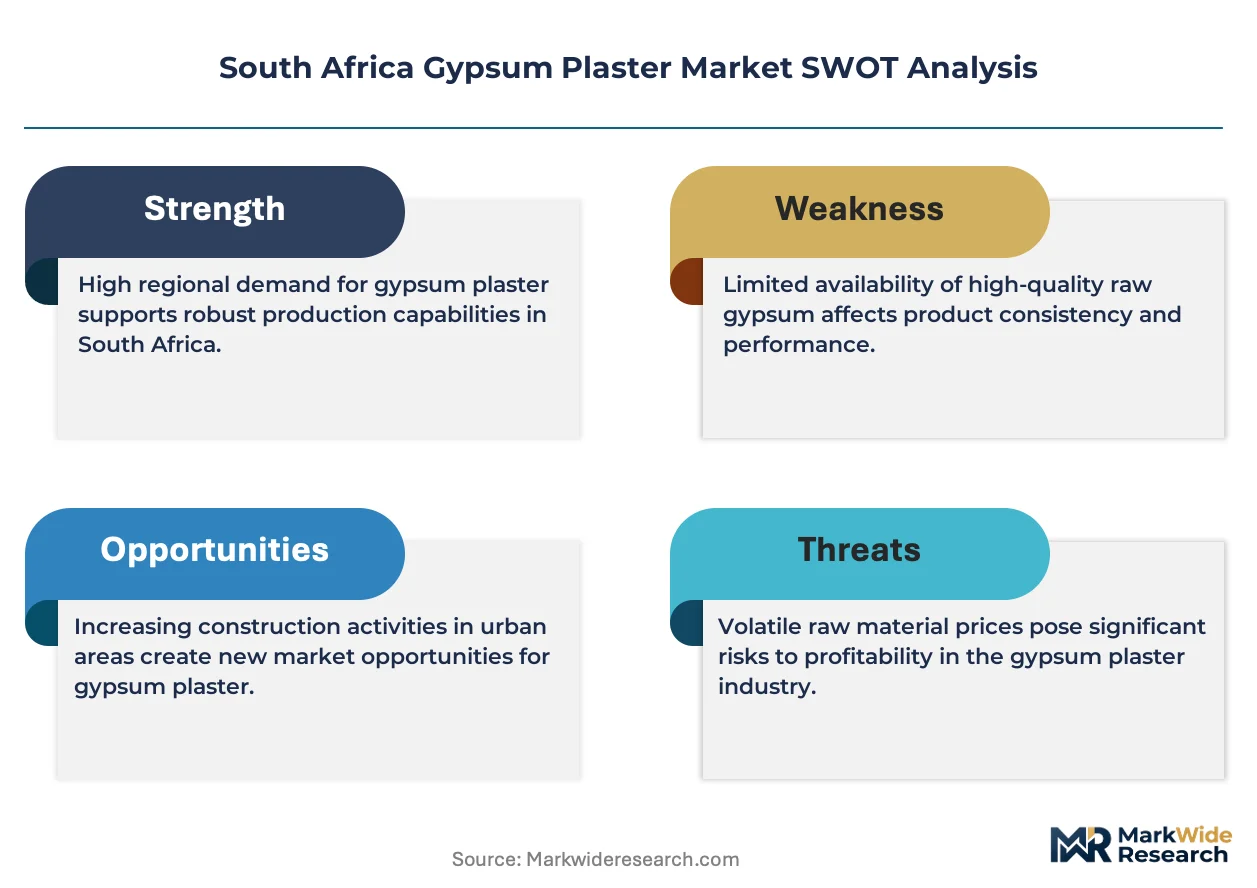
Artisan plastering skills is redrawing competitive dynamics as certified applicators become scarce across South Africa's major metros. Knauf leverages its training academy network to lock in specification loyalty among contractors. Gyproc SA anchors its position through captive gypsum board-to-plaster systems that simplify jobsite logistics. Saint-Gobain competes on specification depth, offering SABS-compliant acoustic and fire-rated plaster solutions for premium commercial builds.
South Africa gypsum plaster comprises calcined gypsum (calcium sulfate hemihydrate) blended with retarders, aggregates, and additives, rehydrating to gypsum dihydrate upon water addition to form a hard, dimensionally stable finish surface. The material serves primarily as an interior wall and ceiling finishing system, providing smooth substrates for paint or wallpaper while contributing fire resistance and acoustic dampening. Standard gypsum plaster occupies the volume base across mass housing and routine commercial fit-outs, yet lightweight formulations are capturing share in high-rise construction where dead-load reduction yields structural savings. Water-resistant gypsum plaster remains a niche premium segment, confined to wet-area applications in hospitality and healthcare builds where SABS durability standards apply.
South Africa's National Regulator for Compulsory Specifications enforces SABS standards for gypsum-based building materials, while the National Home Builders Registration Council mandates quality benchmarks that filter product eligibility for warranty-backed residential projects. The Department of Trade, Industry and Competition's local content preferences in public infrastructure tenders are steering specification toward domestic manufacturing footprints. Stakeholders must monitor evolving SABS test protocols and local-content thresholds to preserve specification access across public and private project pipelines.
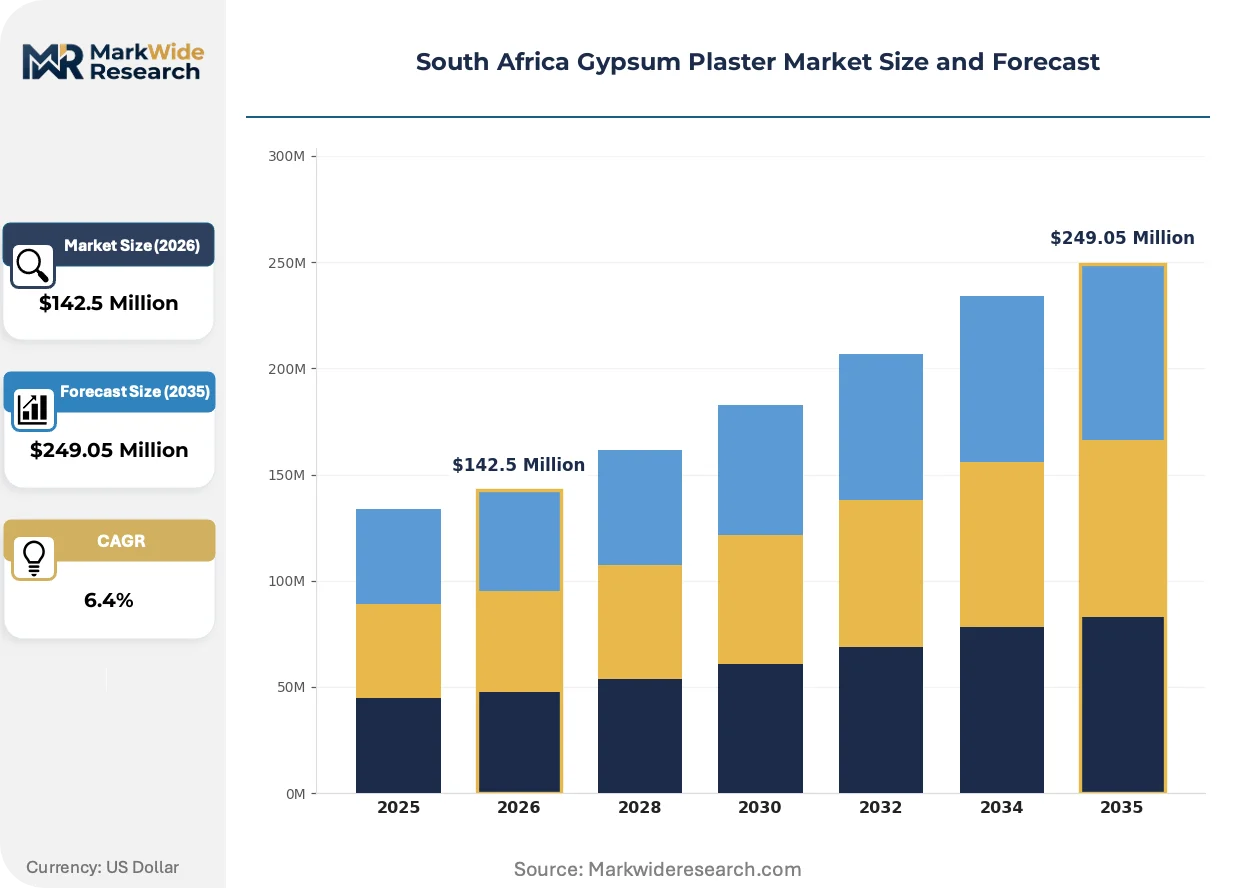
Market Dynamics
Certified artisan scarcity across Johannesburg, Cape Town, and Durban is compressing project timelines and forcing specification loyalty toward manufacturers with captive training infrastructure. This talent bottleneck is restructuring competitive advantage around workforce development rather than raw material cost.
Growth Catalysts
- SABS fire-rated standards:Tightening National Building Regulations are mandating enhanced fire resistance in commercial high-rises, pulling specification toward certified gypsum plaster systems that demonstrate tested performance.
- Housing backlog concentration:Gauteng and Western Cape residential construction pipelines are absorbing volume as government housing programs and private developers address persistent undersupply in urban cores.
- Lightweight formulation uptake:Dead-load reduction requirements in high-rise structural design are accelerating specification of low-density gypsum plaster variants that yield concrete and steel savings.
Market Restraints
- Retarder import dependency:Chemical additives for set-time control are concentrated in limited offshore supply channels, exposing margin structures to freight and currency volatility.
- Substitute finish systems:Cement-based skim coats and pre-finished drywall are capturing share in cost-sensitive mass housing where SABS compliance is not contractually mandated.
- Calcination energy costs:Natural gas and electricity inputs for gypsum hemihydrate production are structurally elevated, compressing domestic manufacturer competitiveness against imported board products.
Strategic Opportunities
- Eastern Cape underpenetration:Port Elizabeth and East London construction activity is accelerating without matching plaster manufacturing footprint, creating logistics-advantaged entry potential for regional distributors.
- Green building certification tailwinds:Green Star SA and EDGE certification growth in commercial retrofits is creating specification pull for low-embodied-carbon plaster systems with verified environmental product declarations.
- Wet-area premium expansion:Water-resistant gypsum plaster for hospitality and healthcare builds remains supply-constrained, offering margin expansion for SABS durability-certified product lines.
Industry Challenges
- Artisan certification bottlenecks:Applicator training programs are failing to match retirement outflows, forcing contractors to absorb premium labor costs or risk quality defects and warranty exposure.
- Jobsite logistics coordination:Just-in-time plaster delivery is colliding with inconsistent site readiness, generating waste and rework where substrate preparation lags behind material arrival.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Gypsum Plaster Market |
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $249.05 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Gypsum Plaster, Lightweight Gypsum Plaster, Water-Resistant Gypsum Plaster, High-Strength Gypsum Plaster End User: Residential Construction, Commercial Construction, Industrial Facilities, Infrastructure Projects Application: Interior Walls, Ceiling Finishing, Decorative Moldings, Repair Work Distribution Channel: Direct Sales, Wholesale Distributors, Online Retail, Building Material Suppliers |
| Companies Covered | Knauf, USG Boral, Gyproc SA, CSR Limited, National Gypsum Company, Mega Crete, Etex Group, Holcim Group, Saint-Gobain, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Gypsum Plaster Market Strategic Shifts & Innovations
Material science advances and procurement model compression are simultaneously reshaping product specifications and channel economics. Three forces are actively restructuring how value is captured across the South African gypsum plaster value chain.
Lightweight gypsum plaster incorporating expanded perlite and hollow glass microspheres is decomposing the traditional density-performance tradeoff. High-rise developers in Johannesburg and Cape Town are specifying these formulations to reduce structural dead loads by fifteen to twenty percent compared to standard plaster. This density reduction is decomposing the historical premium pricing of lightweight systems and compressing the addressable market for conventional high-density alternatives.
SABS standards evolution for acoustic and fire-rated systems is tightening test protocols and documentation requirements. Manufacturers must now submit extended performance data to maintain specification eligibility in NHBRC-warranty residential projects. Premium commercial builds in Sandton and Century City are responding by demanding certified chain-of-custody documentation that traces raw gypsum source through final application.
Buyer consolidation among national retail contractors is compressing distributor margins and consolidating specification authority. Large-fitout specialists are bypassing traditional merchant channels to negotiate direct supply agreements with Knauf and Gyproc SA. This channel disintermediation is most visible in Durban's commercial retrofit pipeline, where project-scale procurement is displacing branch-level purchasing decisions.
South Africa Gypsum Plaster Market Segmentation
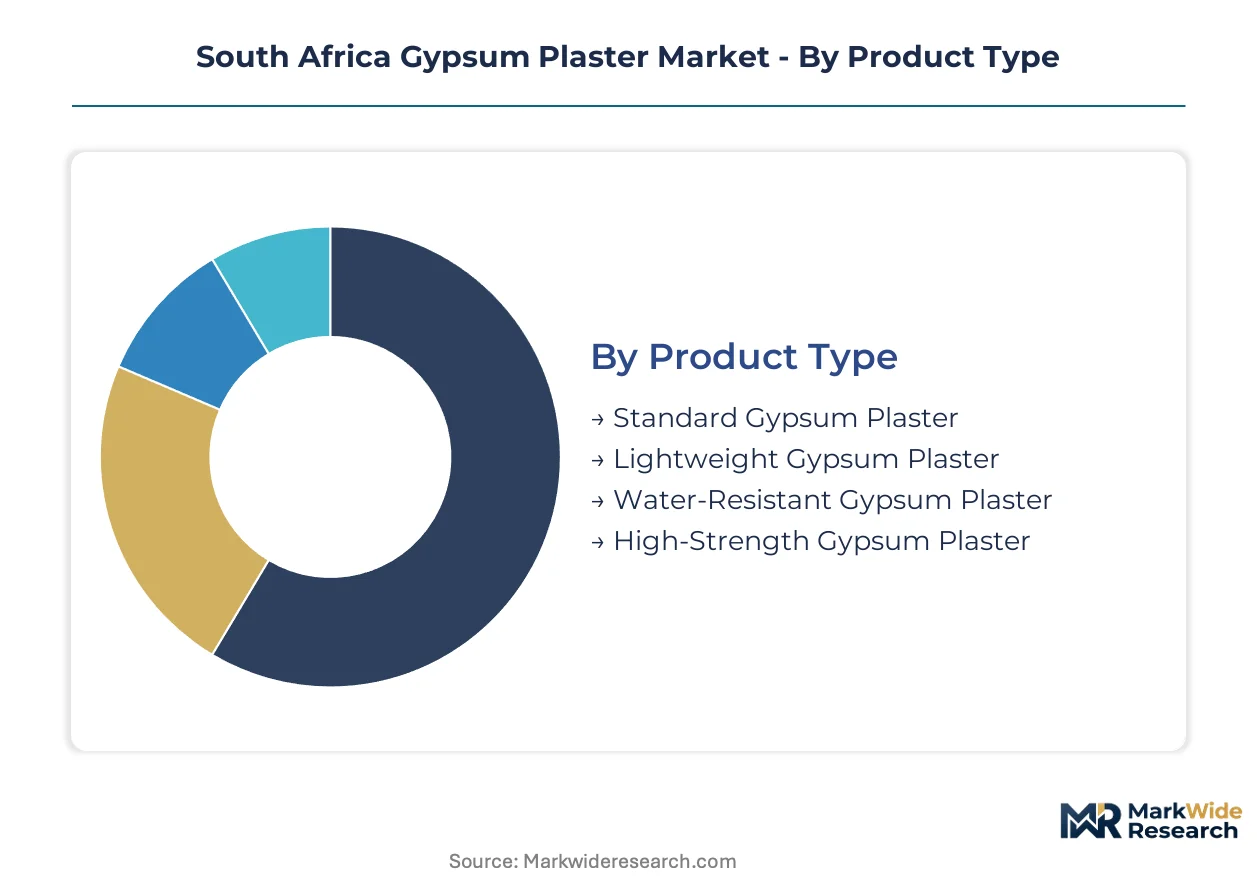
Segmentation in South Africa's gypsum plaster market reveals how SABS certification tiers, structural load requirements, and channel economics partition value capture. Manufacturers configure product portfolios around these fault lines to defend specification access across divergent construction verticals.
Product Type:
SABS fire-rated and acoustic standards create divergent compliance burdens across density grades, compressing margin structures for uncertified alternatives while rewarding tested systems with specification lock-in.
- Standard Gypsum Plaster:Composed of calcined calcium sulfate hemihydrate with mineral retarders and fine aggregates, this formulation delivers the baseline fire resistance and surface finish required for NHBRC-warranty residential projects. Mass housing programs in Gauteng absorb the majority of volume, though cement-based skim coats erode share where SABS compliance is not contractually mandated.
- Lightweight Gypsum Plaster:Incorporating expanded perlite or hollow glass microspheres to achieve fifteen to twenty percent density reduction versus standard grades. High-rise developers in Johannesburg and Cape Town specify these systems to yield concrete and steel savings in structural dead-load calculations, with Green Star SA certification reinforcing specification pull.
- Water-Resistant Gypsum Plaster:Silicone-treated or polymer-modified formulations meeting SABS durability standards for wet-area applications. Hospitality and healthcare builds in Durban and Sandton concentrate demand, though domestic manufacturing capacity remains supply-constrained relative to specification growth.
- High-Strength Gypsum Plaster:Dense hemihydrate blends with enhanced surface hardness for high-traffic commercial interiors. Premium office fit-outs in Century City and Rosebank represent the primary addressable base.
Established volume favors Standard Gypsum Plaster; emerging adoption favors Lightweight Gypsum Plaster.
End User:
Procurement authority concentrates differently across customer types, with national retail contractors consolidating specification decisions while government housing programs fragment purchasing across regional developers.
- Residential Construction:Government housing backlogs in Gauteng and the Western Cape drive volume absorption, with NHBRC quality benchmarks filtering product eligibility for warranty-backed projects. Private developers in Johannesburg's northern suburbs are accelerating lightweight specification for estate housing.
- Commercial Construction:Green building certification growth in Sandton and Century City retrofits is pulling specification toward low-embodied-carbon systems with verified environmental product declarations. Large-fitout specialists are consolidating procurement authority through direct manufacturer agreements.
- Industrial Facilities:Manufacturing and logistics warehousing in Port Elizabeth and East London generate episodic demand for high-strength finishes, though specification frequency trails commercial verticals.
- Infrastructure Projects:Department of Trade, Industry and Competition local-content preferences steer public infrastructure tenders toward domestic manufacturing footprints, compressing import participation.
Residential Construction absorbs the dominant volume share; Commercial Construction is climbing the fastest on green certification tailwinds.
Application:
Substrate preparation requirements and finish durability specifications partition application economics, with ceiling systems demanding superior sag resistance and wall applications prioritizing surface hardness.
- Interior Walls:The foundational application across all construction verticals, requiring smooth substrates for paint or wallpaper adhesion. Mass housing programs in Gauteng concentrate volume demand for standard-grade systems.
- Ceiling Finishing:Lightweight formulations are gaining share fastest here, as sag resistance and dead-load reduction compound in high-rise structural design. Cape Town commercial towers are specifying expanded perlite systems.
- Decorative Moldings:Niche premium segment requiring high-strength hemihydrate with extended working time for ornate cornice and architrave fabrication. Heritage restoration projects in Durban's colonial-era buildings sustain demand.
- Repair Work:Patch and renovation activity across Johannesburg's aging commercial stock, with rapid-setting formulations addressing compressed maintenance windows.
Interior Walls represents the mature volume base; Ceiling Finishing is expanding most quickly on high-rise construction density.
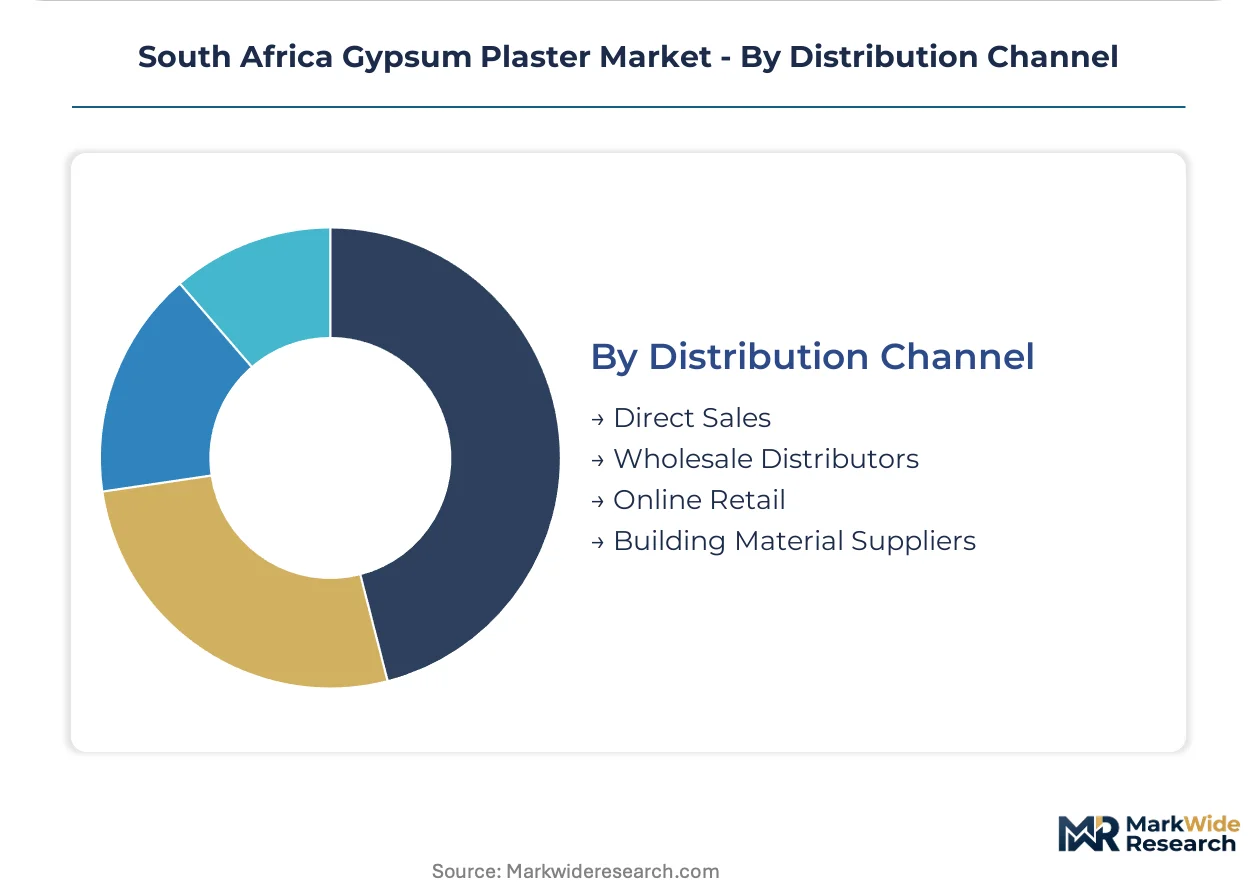
Distribution Channel:
Channel disintermediation is restructuring margin capture, with project-scale procurement bypassing traditional merchant networks in favor of direct supply relationships.
- Direct Sales:National retail contractors and large-fitout specialists in Durban's commercial retrofit pipeline are negotiating direct agreements with manufacturers, consolidating specification authority and compressing distributor margins.
- Wholesale Distributors:Regional merchant networks remain dominant in mass housing and smaller commercial projects where fragmented purchasing resists consolidation. Branch-level inventory buffers jobsite logistics coordination challenges.
- Online Retail:Emerging channel for repair-work quantities and small-project contractors, though bulk plaster logistics limit penetration relative to packaged building materials.
- Building Material Suppliers:Integrated construction supply houses in Johannesburg and Cape Town bundle plaster with complementary substrates, capturing specification through convenience rather than price.
Wholesale Distributors retain the volume concentration; Direct Sales is gaining share fastest on contractor consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gauteng and the Western Cape absorb the majority of South African gypsum plaster consumption through divergent demand profiles. Gauteng concentrates mass housing volume, while the Western Cape drives lightweight specification in high-rise commercial towers. Eastern Cape construction activity accelerates without matching manufacturing footprint, creating logistics fragmentation.
Gauteng
Johannesburg and Pretoria anchor residential construction volume through government housing backlogs and private estate development. The National Home Builders Registration Council mandates NHBRC quality benchmarks that filter product eligibility for warranty-backed projects. Sandton commercial retrofits are consolidating procurement authority through direct manufacturer agreements, bypassing traditional distributor channels.
Western Cape
Cape Town high-rise developers specify expanded perlite lightweight systems to yield concrete and steel savings in structural dead-load calculations. Green Star SA certification growth in Century City commercial builds pulls specification toward low-embodied-carbon plaster systems. The provincial construction pipeline absorbs premium-grade volume for hospitality and healthcare wet-area applications.
KwaZulu-Natal
Durban's commercial retrofit pipeline exhibits the most visible channel disintermediation, with large-fitout specialists negotiating direct supply agreements. SABS fire-rated standards tighten test protocols for acoustic and fire-rated systems in premium office builds. The city's colonial-era heritage restoration projects sustain niche demand for high-strength decorative molding plaster.
Eastern Cape
Port Elizabeth and East London construction activity accelerates without matching plaster manufacturing footprint, generating logistics-advantaged entry potential for regional distributors. The Department of Trade, Industry and Competition's local content preferences steer public infrastructure tenders toward domestic manufacturing. Industrial facilities in the Coega Special Economic Zone generate episodic demand for high-strength finishes.
North West and Free State
Mining belt construction in Rustenburg and Welkom generates maintenance-driven repair work demand for rapid-setting formulations. Substrate preparation inconsistencies collide with just-in-time delivery schedules, generating waste and rework. Branch-level distributor inventory buffers jobsite logistics coordination challenges in these secondary markets.
South Africa Gypsum Plaster Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in South Africa's gypsum plaster market. The upper tier captures specification authority through captive training infrastructure and certified system portfolios. The specialist tier competes on regional logistics and wet-area premium segments. Three archetypes dominate: multinational building materials conglomerates with SABS-compliant system depth, domestic manufacturers with local-content advantages for public tenders, and regional distributors exploiting Eastern Cape underpenetration. Competitive moves concentrate on workforce development investments and direct contractor relationships that disintermediate traditional merchant channels.
Within the multinational tier, Knauf leverages its training academy network to lock in specification loyalty among contractors facing certified artisan scarcity. Gyproc SA anchors position through captive gypsum board-to-plaster systems that simplify jobsite logistics. Saint-Gobain competes on specification depth, offering SABS-compliant acoustic and fire-rated plaster solutions for premium commercial builds in Sandton and Century City. These three represent the dominant competitive positioning vectors: training infrastructure, system integration, and certified performance depth.
| Leading Market Players |
|---|
| Knauf |
| USG Boral |
| Gyproc SA |
| CSR Limited |
| National Gypsum Company |
| Mega Crete |
| Etex Group |
| Holcim Group |
| Saint-Gobain |
| Others |
Cost & Logistics Intelligence
Long-term offtake agreements between Johannesburg commercial contractors and Knauf's South African operations lock in supply access while providing price visibility across multi-year retrofit pipelines. These contractual structures insulate volume buyers from calcination energy cost volatility while compressing spot-market participation for smaller distributors.
Pricing Analysis
Project-based pricing dominates commercial specifications in Sandton and Century City, where Green Star SA certification tiers separate premium low-embodied-carbon systems from standard NHBRC-compliant grades. Price differentiation rests on SABS fire-rated documentation depth and artisan training bundling. Cost compression in standard-grade segments intensifies as cement-based skim coats capture mass housing share. Government housing programs in Gauteng exhibit the highest price sensitivity, while hospitality developers in Durban's wet-area premium segment show the least.
Supply Chain Analysis
Inventory buffers at Port Elizabeth distributor branches stretch lead times for Eastern Cape projects lacking local manufacturing footprint. Gypsum ore draws from South African mining belts in the North West and Limpopo, while chemical retarders hinge on concentrated Indian and Chinese import channels. Single-source vulnerability in offshore additive supply exposes margin structures to freight and currency volatility. Distribution runs through wholesale merchant networks in mass housing, though direct manufacturer agreements are consolidating procurement authority among national retail contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The South African gypsum plaster market rewards stakeholders who control certified artisan pipelines, as applicator scarcity constrains project execution more than raw material access. Firms that capture training infrastructure lock in specification loyalty ahead of competitors dependent on spot labor markets.
For Market Incumbents: Compound specification authority by expanding captive training academy capacity to outpace artisan retirement outflows. Cement-based skim coat erosion in cost-sensitive housing segments demands defensive pricing coordination with wholesale distributors. Backward integration into retarder formulation buffers margin exposure to import volatility. For New Entrants and Emerging Players: Anchor in Eastern Cape logistics gaps where Port Elizabeth and East London construction activity accelerates without matching plaster manufacturing footprint. Regional distribution partnerships with Coega Special Economic Zone industrial facilities offer the most penetrable entry vector. Lead with rapid-setting repair formulations targeting mining belt maintenance demand in Rustenburg and Welkom. For Investors and Strategic Acquirers: Regional distributors with established Eastern Cape branch networks and SABS certification relationships represent the most attractive acquisition archetype. Long-term viability over the coming decade rests on local-content compliance for public infrastructure tender participation. Monitor Department of Trade, Industry and Competition local-content threshold adjustments as the critical inflection signal for import-dependent business model stress.| Strategic Initiative | Industry Significance |
|---|---|
| Artisan Training Academy Expansion | Captures scarce certified applicator capacity ahead of competitor workforce development programs. |
| Retarder Formulation Backward Integration | Reduces import dependency exposure for set-time control chemical additives. |
| Eastern Cape Distribution Footprint Buildout | Exploits logistics fragmentation in Port Elizabeth and East London construction corridors. |
| Green Star SA Certification Investment | Unlocks premium specification access in Century City and Sandton commercial retrofits. |
| Direct Contractor Supply Agreements | Bypasses wholesale margin compression from national retail contractor consolidation. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with commercial contractors, artisan training coordinators, NHBRC quality auditors, and wholesale distributor branch managers. Secondary validation drew from SABS standard documentation, Department of Trade, Industry and Competition tender records, National Home Builders Registration Council warranty filings, and Green Building Council South Africa certification databases. Bottom-up volume estimates from regional construction pipeline tracking were triangulated against top-down gypsum ore production and calcination capacity assessments.
Across the analysis window, the forecasting framework modeled product type segmentation by density grade and certification tier, end user verticals by construction category, application by substrate requirements, and distribution channel by procurement authority concentration. CAGRs were derived from construction pipeline absorption rates and specification substitution dynamics. Key inputs included housing backlog data from provincial human settlements departments and commercial retrofit permit flows from metropolitan municipalities.
Material uncertainties — retarder supply disruption, SABS protocol revision, artisan training program scale, and local-content threshold adjustment — sit outside the modeled envelope. Forecasts reflect assumptions about continued National Building Regulations enforcement trajectory and green building certification adoption velocity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Pentane Plus Market
Industrial Chemicals
Tall Oil Fatty Acid Market
Industrial Chemicals
Chemical Process Mixers Market
Industrial Chemicals
Global Alkylated Naphthalene Market
Industrial Chemicals
Global Foundry Chemicals Market
Industrial Chemicals
Asia Neopentyl Glycol (NPG) Market
Industrial Chemicals
Global Silica Gel Market
Industrial Chemicals
Vacuum Degreasers Market
Industrial Chemicals
Heat Shrink Tubes Market
Industrial Chemicals
Global Itaconic Acid Market
Industrial Chemicals
Hydrogen Sulfide Scavengers Market
Industrial Chemicals
Paraffin Inhibitors Market
Industrial Chemicals
Hydrogen Silicone Fluid Market
Industrial Chemicals
Global High Throughput Process Development Market
Industrial Chemicals
Global Odor Control Systems Market
Industrial Chemicals
Shea Olein Market