
 Bauxite Mining Market | 2026-2036
Bauxite Mining Market Size, Share, and Industry Trends Forecast 2026-2036
Bauxite Mining Market Analysis
The EU Green Deal's carbon border adjustment mechanism is decoupling European aluminum demand from high-carbon bauxite sources. Rio Tinto leverages its Weipa and Gove operations in Australia to sustain low-carbon ore output for European smelters. South32 anchors its portfolio through the Worsley Alumina integrated chain in Western Australia, while Emirates Global Aluminium PJSC competes via captive bauxite supply from Guinea's CBG and CBK mines.
Bauxite mining extracts aluminum-bearing ore, typically containing gibbsite, boehmite, or diaspore with alumina content ranging from 30% to 60%, through surface stripping or underground methods for refining into alumina via the Bayer process. The primary commercial purpose is feeding alumina refineries that produce smelter-grade oxide for aluminum metal production or non-metallurgical grades for abrasives, chemicals, and proppants. Open-pit extraction dominates volume due to lower stripping ratios in lateritic deposits, while metallurgical-grade product commands the largest revenue pool tied to primary aluminum output. Non-metallurgical grade bauxite occupies a narrower but higher-margin niche in refractory and cement applications where calcined material specifications tighten.
China's MEE enforces dual carbon goals that cap energy intensity per ton of alumina refined, indirectly constraining bauxite import quality and origin requirements. Australia's EPA and Guinea's national mining code jointly shape environmental permitting timelines that delay greenfield project approvals. Brazil's ANM and India's Ministry of Mines each administer royalty frameworks that alter mine economics across the Atlantic and Indian Ocean supply corridors. Stakeholders must track how carbon border adjustments in Europe and Asia redefine acceptable ore provenance before committing to long-dated offtake structures.
Market Dynamics
China's dual carbon goals are compressing allowable emission intensity across the bauxite-to-alumina value chain, forcing import origin diversification and quality upgrading across Asian smelter networks.
Growth Catalysts
- Aerospace-grade alumina demand:Commercial aircraft manufacturers are expanding superalloy content in next-generation engines, pulling high-purity metallurgical bauxite through dedicated offtake channels.
- MEE emission caps:China's Ministry of Ecology and Environment enforces binding carbon intensity thresholds per ton of alumina refined, indirectly filtering bauxite import specifications toward lower-embedded-carbon sources.
- Guinean belt expansion:Chinese mining firms are locking long-dated supply agreements across the Boké-Kimbo corridor, securing volume commitments that underpin greenfield refinery investments.
Market Restraints
- Energy cost volatility:Diesel and heavy fuel oil price swings directly alter open-pit stripping economics, particularly for Australian lateritic deposits with elevated overburden ratios.
- Guinean supply concentration:Over half of seaborne bauxite export capacity routes through Conakry-Boké infrastructure, creating single-point vulnerability to port congestion or political disruption.
- High-carbon ore exclusion:The EU Green Deal's carbon border adjustment mechanism is structurally disqualifying Indonesian and some Australian high-emission bauxite from European smelter procurement.
Strategic Opportunities
- Saudi Arabian downstream integration:Ma'aden's Ras Al Khair complex is expanding alumina refining capacity, creating captive bauxite demand that regional miners can anchor long-term contracts against.
- Non-metallurgical refractory grades:Calcined bauxite specifications for cement kiln linings and proppant applications command 40-60% price premiums over metallurgical grades with lower volume volatility.
- EU Green Deal compliance services:Third-party carbon accounting and origin certification providers can capture value from European smelters scrambling to document supply chain emissions ahead of CBAM phase-in.
Industry Challenges
- Geotechnical engineering talent scarcity:Lateritic deposit modeling and slope stability analysis for high-rainfall open-pit operations require specialized skills concentrated in Australian and Brazilian consultancies.
- Bayer process residue disposal capex:New refinery-linked mining projects face billion-dollar tailings dam construction and rehabilitation bonding requirements that extend payback periods.
- Cross-border environmental permitting:Guinea's national mining code mandates multi-year environmental and social impact assessments that delay project sanctioning beyond typical investment committee horizons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bauxite Mining Market |
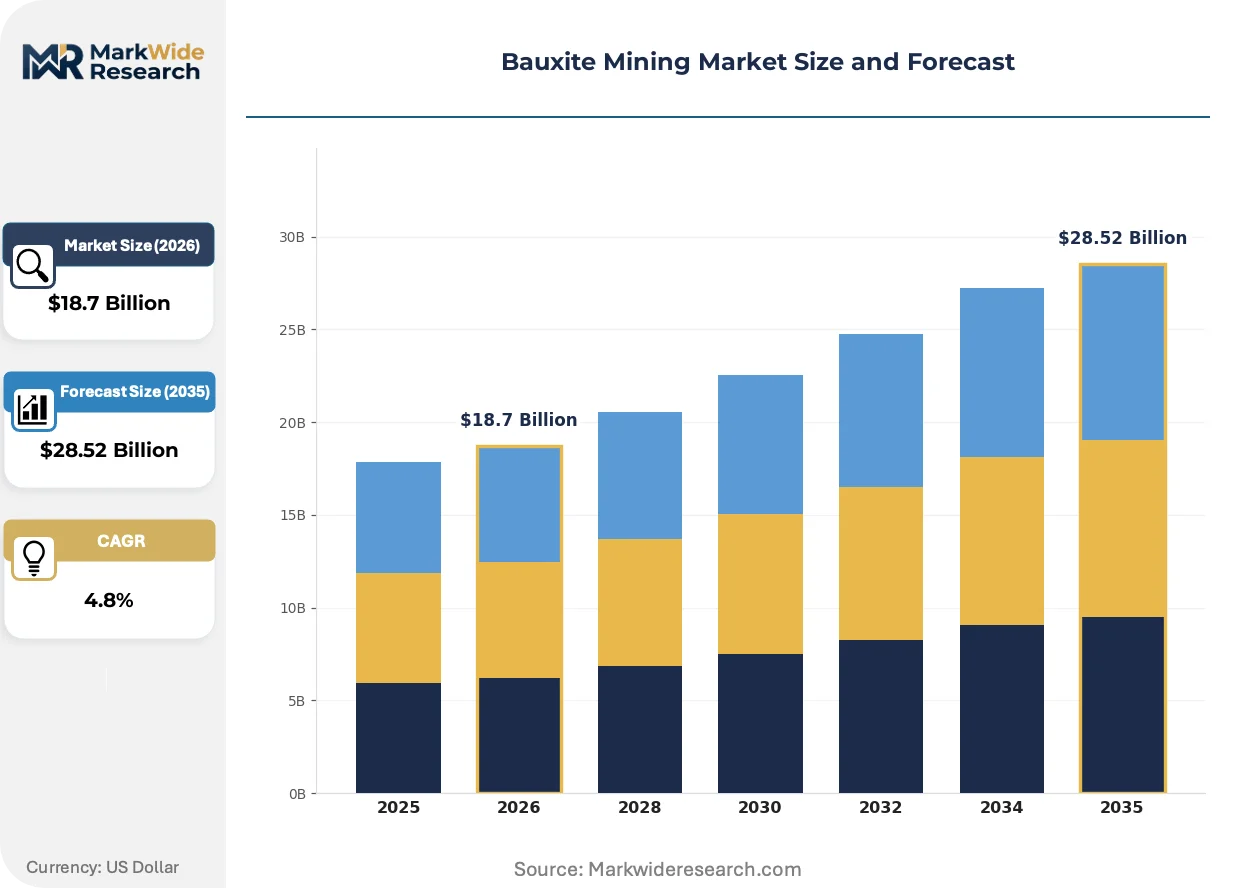
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Extraction Method: Open-Pit, Underground, Dredging, Hydraulic Product Type: Alumina, Metallurgical Grade, Non-Metallurgical Grade, Calcined End User: Aerospace, Construction, Automotive, Packaging Geological Setting: Lateritic, Karst, Sedimentary, Others |
| Companies Covered | Aluminum Corporation of China Limited, South32, Rio Tinto, Glencore, Emirates Global Aluminium PJSC, Alcoa Corporation, Norsk Hydro ASA, RusAL, Winning International Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bauxite Mining Market Emerging Trajectories
Dry beneficiation technologies and sensor-based ore sorting are displacing water-intensive washing circuits, while carbon border compliance tools reshape procurement specifications across Atlantic and Pacific supply corridors.
Sensor-based ore sorting is absorbing capital allocation across Australian and Guinean greenfield developments. Rio Tinto's Weipa operations pilot X-ray transmission sorters that reject sub-grade material before wet processing, cutting water consumption per ton of export ore by roughly one-third. The technology is absorbing engineering resources that previously flowed into conventional dense media separation plants, compressing capital intensity for new mine builds.
The EU Green Deal's carbon border adjustment mechanism is redefining acceptable ore provenance for European smelters. CBAM requires documented emissions from bauxite extraction through alumina refining, effectively penalizing high-carbon Indonesian and some Australian sources while advantaging Guinean and certain Brazilian low-carbon belts. German and French aluminum producers are accelerating supplier audits and dual-sourcing strategies to lock compliant supply ahead of full mechanism activation.
Buyer concentration among Chinese state-linked smelters is compressing contract negotiation cycles and standardizing quality specifications. Chalco and Hongqiao now demand consistent gibbsite content and reactive silica ratios across annual offtake agreements, displacing the spot-market variability that historically characterized Atlantic basin trade. This consolidation is most visible in Guinea's Boké region, where Chinese mining ventures have vertically integrated into captive alumina refineries.
Bauxite Mining Market Segmentation
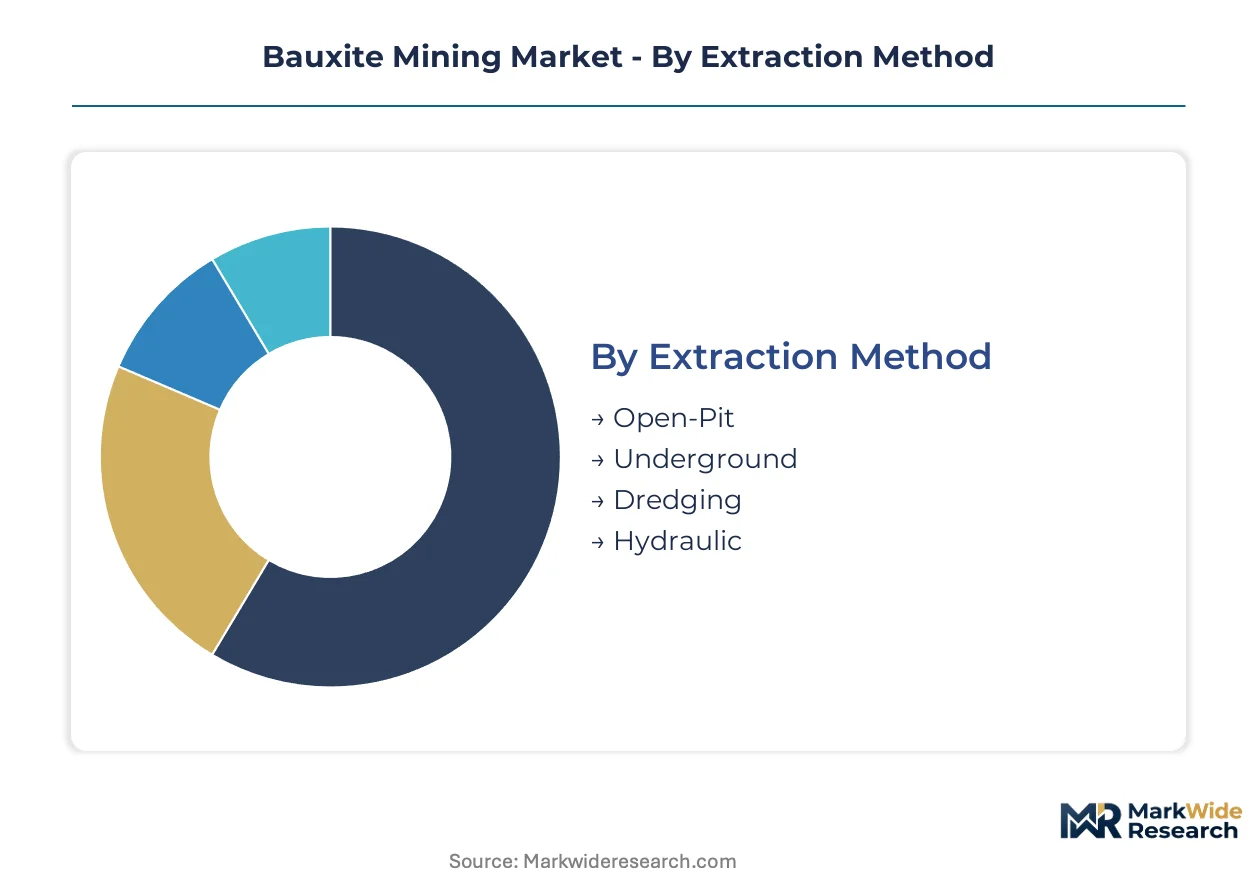
Bauxite mining segmentation reveals how ore quality, extraction economics, and end-use specifications fragment supply chains. Each dimension carries distinct capital intensity and margin profiles that shape investment allocation across the value chain.
Extraction Method:
Standardization dominates surface operations while specialized techniques serve niche deposits with unique geotechnical constraints.
- Open-Pit:Surface stripping of lateritic deposits with overburden removal ratios of 2:1 to 5:1. Australian Weipa and Guinean Boké operations concentrate here, driven by China's MEE emission caps favoring low-carbon seaborne ore.
- Underground:Room-and-pillar or longwall methods for steeply dipping karst bauxite. Limited to Chinese Guizhou and Hungarian deposits where surface exhaustion forces vertical expansion.
- Dredging:Floating cutter suction for submerged alluvial deposits. Jamaican St. Ann operations employ this method where water table proximity precludes dry excavation.
- Hydraulic:High-pressure water jet mining for friable laterite. Brazilian Paragominas uses this technique to reduce diesel dependency in remote Amazonian terrain.
Most installed capacity flows through Open-Pit. Expansion is steepest in Dredging as coastal deposits face exhaustion pressures.
Product Type:
Margin stratification separates commodity alumina feedstock from premium calcined grades serving specialized industrial applications.
- Alumina:Smelter-grade oxide output from Bayer process refining. Guinea's CBG and CBK mines anchor Atlantic supply to European smelters navigating EU Green Deal carbon border adjustments.
- Metallurgical Grade:High-gibbsite ore with reactive silica below 5% for primary aluminum production. Chinese Chalco and Hongqiao procurement concentrates here, standardizing specifications across annual offtake agreements.
- Non-Metallurgical Grade:Lower-purity ore for abrasives, chemicals, and proppants. Refractory applications in cement kiln linings command 40-60% price premiums over metallurgical equivalents.
- Calcined:Rotary kiln-fired bauxite at 1600-1800°C for refractory and proppant markets. Saudi Ma'aden's Ras Al Khair complex drives captive demand for high-density calcined material.
Metallurgical Grade absorbs the largest volume share. Calcined gains share fastest as refractory specifications tighten.
End User:
Application-driven purity requirements split supply between aerospace superalloy feedstock and mass-market aluminum semis.
- Aerospace:Superalloy-grade alumina for turbine blade coatings and structural alloys. Commercial engine manufacturers pull high-purity metallurgical bauxite through dedicated offtake channels.
- Construction:Structural aluminum for facades, window frames, and infrastructure. Building codes in Germany and France increasingly require documented low-carbon ore provenance.
- Automotive:Lightweight body sheet and cast components. Electric vehicle platform expansion drives demand for high-strength aluminum extrusions.
- Packaging:Can sheet and foil for food and beverage containers. Recyclability mandates in EU packaging regulations sustain steady bauxite-to-alumina throughput.
Construction commands the largest volume off take. Aerospace posts the steepest specification escalation.
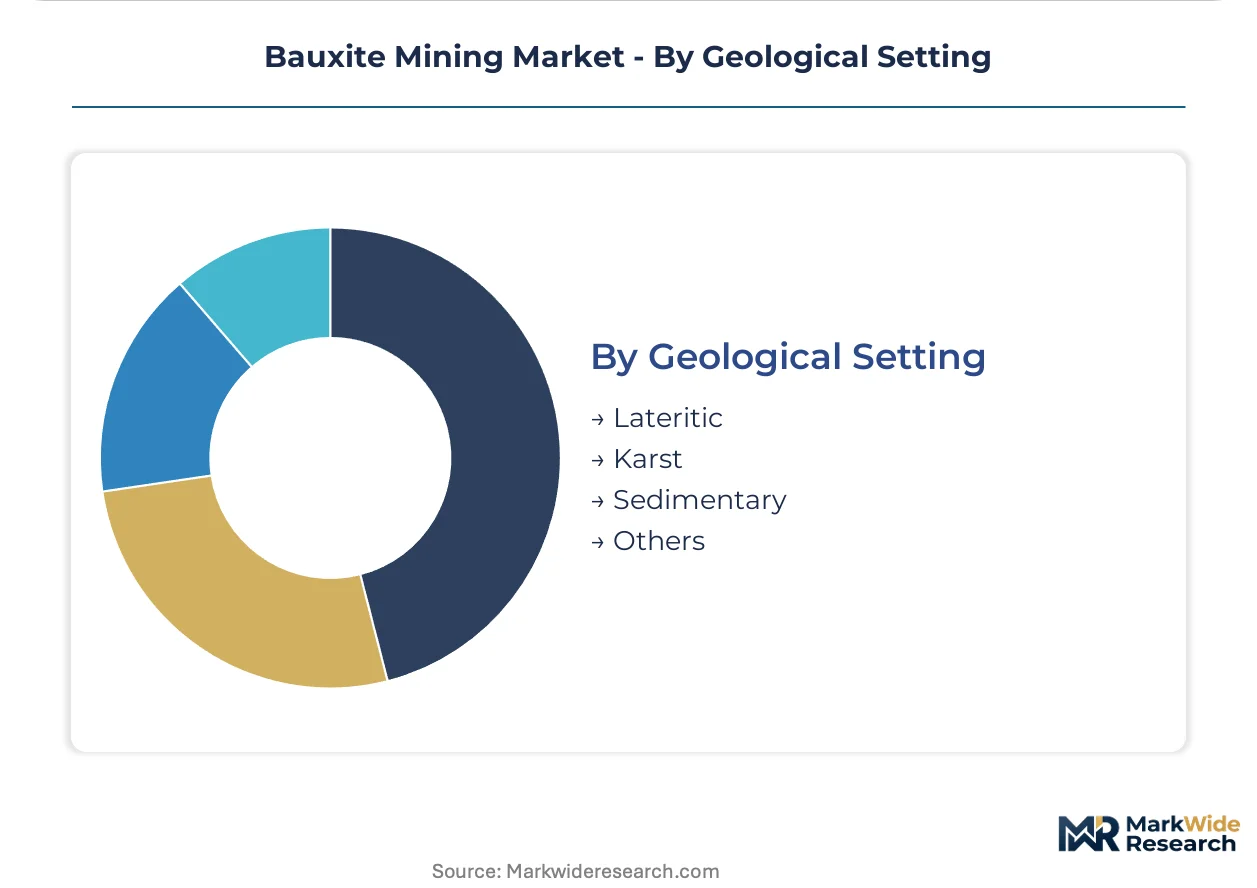
Geological Setting:
Deposit chemistry and stripping economics concentrate investment in lateritic belts while karst and sedimentary sources serve regional niches.
- Lateritic:Tropical weathering profiles yielding gibbsite-rich ore at 45-60% alumina. Guinea's Boké-Kimbo corridor and Australian Weipa-Gove districts dominate seaborne trade.
- Karst:Residual accumulation in limestone cavities, typically boehmite-dominant with higher silica. Chinese Guizhou and Vietnamese deposits supply regional smelters.
- Sedimentary:Stratiform deposits in coastal plains or lake beds. Jamaica's St. Ann and Russia's Severouralsk operations serve Atlantic and Eurasian markets respectively.
- Others:Minor occurrence types including tuffaceous and glauconitic bauxite. Limited commercial significance outside localized supply arrangements.
Lateritic deposits host the bulk of installed capacity. Karst expansion accelerates as Chinese domestic supply priorities shift.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bauxite mining scaled from Caribbean and Mediterranean origins in the early twentieth century to today's lateritic belt dominance across tropical Australia, West Africa, and South America. Modern supply chains trace directly to these geological endowments.
Guinea
Chinese offtake agreements with CBG and CBK mines drive volume growth through the Boké-Kimbo corridor. The national mining code mandates multi-year environmental impact assessments that delay greenfield approvals. Boké port infrastructure handles over half of seaborne export capacity, creating congestion vulnerability during peak loading seasons.
Australia
Rio Tinto's Weipa and Gove operations supply low-carbon ore to European smelters navigating EU Green Deal carbon border adjustments. The EPA enforces rehabilitation bonding requirements that extend project payback periods. Western Australia's Worsley Alumina integrated chain anchors South32's metallurgical-grade output for Asian buyers.
Brazil
Paragominas operations employ hydraulic mining to reduce diesel dependency in remote Amazonian terrain. ANM royalty frameworks alter mine economics across the Atlantic supply corridor. The northern Carajás mineral province hosts expanding lateritic deposits with gibbsite content favoring Bayer process efficiency.
China
Domestic Guizhou karst deposits supply regional smelters as import dependence rises. MEE emission caps per ton of alumina refined filter bauxite import specifications toward lower-embedded-carbon sources. Shandong and Henan provinces concentrate refinery capacity that pulls Guinean and Australian seaborne ore.
Saudi Arabia
Ma'aden's Ras Al Khair complex expands alumina refining capacity, creating captive bauxite demand for regional contract structures. The national industrial strategy prioritizes downstream integration over raw ore export. The Eastern Province hosts the kingdom's primary aluminum smelting and refining cluster.
Bauxite Mining Market Vendor Landscape
Capital-heavy integrated miners compete with trading-house intermediaries for offtake control across the bauxite-to-alumina value chain. The structure concentrates around three strategic tiers: diversified majors with captive refining, pure-play miners dependent on spot or contract sales, and state-linked Chinese ventures securing supply for domestic smelter networks. Dominant competitive moves include backward integration into captive alumina refining and geographic expansion into Guinean greenfield belts.
Among diversified majors, Rio Tinto and South32 exemplify the integrated archetype with Australian-based low-carbon ore output. Emirates Global Aluminium PJSC occupies a position bridging mining and smelting through Guinean captive supply. Aluminum Corporation of China Limited anchors the state-linked tier, representing buyer concentration that compresses contract negotiation cycles across Atlantic basin trade.
| Leading Market Players |
|---|
| Aluminum Corporation of China Limited |
| South32 |
| Rio Tinto |
| Glencore |
| Emirates Global Aluminium PJSC |
| Alcoa Corporation |
| Norsk Hydro ASA |
| RusAL |
| Winning International Group |
| Others |
Supply Flow & Price Mechanics
EU Green Deal carbon border adjustment mechanisms gate qualified supply access for European smelters while compressing premium-tier pricing premiums for compliant Guinean and Australian ore. This regulatory filter forces bifurcation between certified low-carbon supply channels and discounted high-carbon alternatives excluded from Atlantic basin procurement.
Pricing Analysis
Long-dated offtake contracting dominates metallurgical-grade bauxite trade, with pricing stratifying across premium, standard, and economy tiers based on carbon certification status and reactive silica content. Price differentiation rests on MEE compliance documentation for Chinese buyers and EU CBAM carbon intensity scores for European procurement. Cost compression in standard-tier Australian supply is intensifying because diesel stripping economics face persistent fuel volatility. Chinese state-linked smelters exhibit lowest price sensitivity due to captive refining margins, while European traders show highest sensitivity to carbon-adjusted delivered costs.
Supply Chain Analysis
Geotechnical engineering talent scarcity in Australian and Brazilian consultancies constrains expansion velocity for new open-pit developments. Supply concentrates in Guinea, Australia, and Brazil, with extraction drawing from diesel fuel, ammonium nitrate explosives, and specialized haul truck fleets. Single-source vulnerability runs through Conakry-Boké port infrastructure handling over half of seaborne export capacity. Distribution runs through integrated miner-to-refiner pipelines and trading-house intermediaries serving spot-market consumers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bauxite mining operates as a geographic-arbitrage play where Guinean low-carbon ore commands Atlantic basin premiums against Australian high-carbon discounts under EU CBAM enforcement.
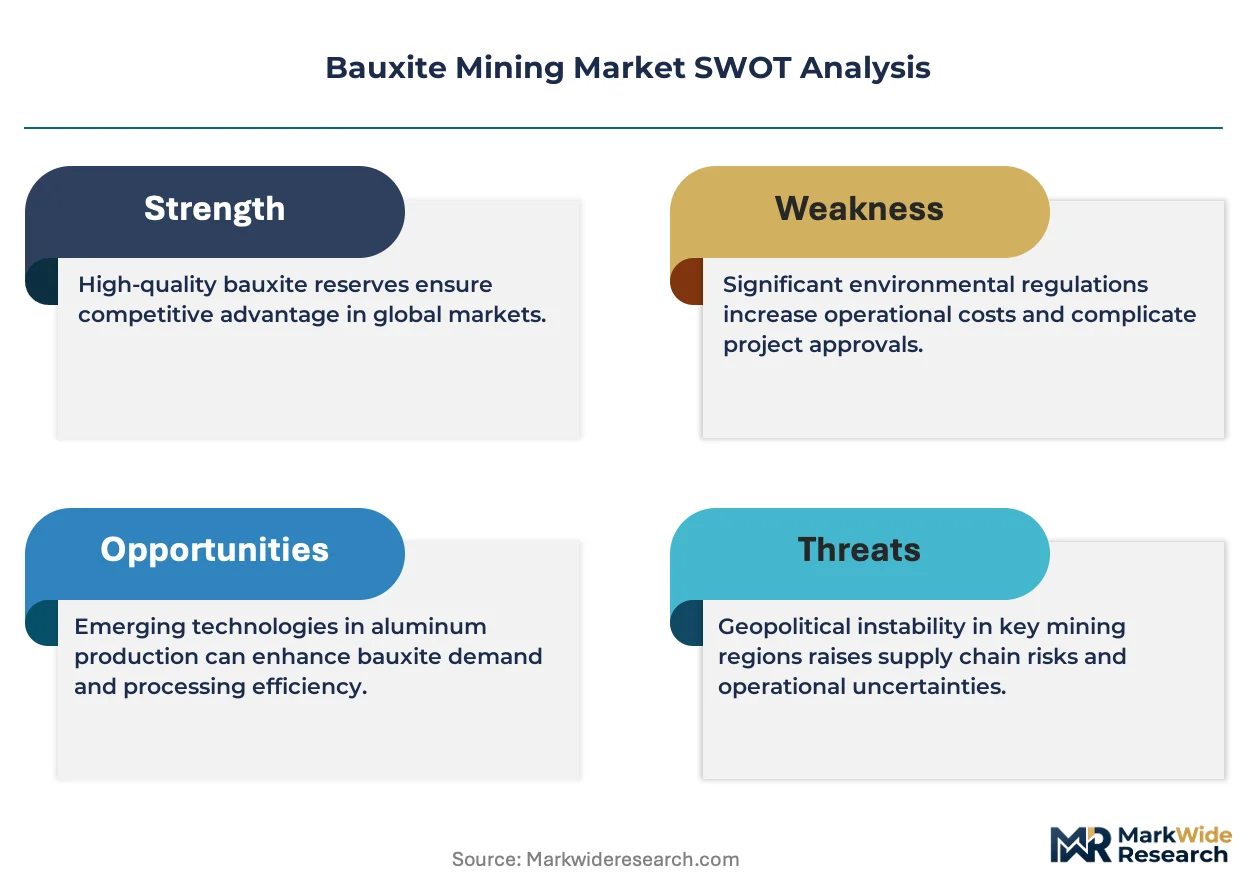
For Market Incumbents: Cement backward integration into captive alumina refining to lock margin capture against trading-house disintermediation. Prioritize carbon certification investment for European offtake retention as CBAM phase-in accelerates supplier audits. For New Entrants and Emerging Players: Launch via non-metallurgical refractory grade specialization targeting Saudi Ma'aden Ras Al Khair captive demand. The calcined bauxite segment offers penetrable white-space with 40-60% price premiums and lower buyer concentration risk than metallurgical supply. For Investors and Strategic Acquirers: Roll-up economics work for mid-tier Guinean pure-play miners because Chinese state-linked offtake concentration creates exit demand for compliant volume. Target assets with documented low-carbon extraction profiles and active environmental permits. Watch MEE emission cap tightening as inflection indicator for accelerated import origin shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alumina Refining | Captures margin upstream from Bayer process operations and reduces offtake price volatility. |
| Carbon Certification Program | Secures EU CBAM-compliant supply status for European smelter procurement under Green Deal enforcement. |
| Long-term Supply Agreement | Locks volume commitments with Chinese state-linked smelters navigating MEE emission intensity caps. |
| Non-metallurgical Grade Specialization | Accesses refractory and proppant markets commanding price premiums over metallurgical feedstock. |
| Greenfield Expansion in Guinean Belt | Positions output within lowest-carbon seaborne supply corridor favored by Atlantic basin buyers. |
Methodological Framework
Multiple input streams — mine operations data, refinery procurement records, and customs trade documentation — were reconciled across primary interviews with mining engineers, alumina refinery procurement managers, and dry bulk shipping operators. Secondary validation drew from Guinea national mining code filings, Australian EPA environmental assessments, Chinese MEE emission disclosures, and SEC 10-K extracts from listed diversified miners. Bottom-up project-level capacity builds and top-down regional demand aggregates were triangulated for convergence.
Data-stream reconciliation across extraction method, product grade, and end-use application dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level volume trajectories and value-per-ton realizations. Forecast inputs incorporated Bayer process residue disposal capex cycles and carbon border adjustment mechanism phase-in schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Guinean political disruption or MEE emission cap acceleration. Projections reflect assumptions on Chinese import dependence growth and EU Green Deal enforcement stringency. Material deviation in diesel fuel cost volatility or Boké port congestion warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals & Minerals
Pyroxenite Market
Metals & Minerals
Pre-Painted Galvanised Iron (PPGI) Market
Metals & Minerals
Global Antimony Market
Metals & Minerals
Titanium Ore Market
Metals & Minerals
Mineral Ingredients Market
Metals & Minerals
Iron Ore Pellets Market
Metals & Minerals
Recycled Scrap Metal Market
Metals & Minerals
Colored Gemstones Market
Metals & Minerals
Testing Inspection and Certification TIC for the Metals and Minerals Market
Metals & Minerals
Moissanite Market
Metals & Minerals
Rare Earth Elements Market
Metals & Minerals
Manganese Mining Market
Metals & Minerals
Cobalt Carbonate Market
Metals & Minerals
Nickel Nano Powder Market
Metals & Minerals
Frac Sand Market
Metals & Minerals
Mexico Mining Market