
 Lithium Bromide Market | 2026-2036
Lithium Bromide Market Size, Share, and Industry Trends Forecast 2026-2036
Lithium Bromide Market Outlook
The split between battery-grade and industrial-grade specifications is realigning procurement patterns across the lithium bromide value chain. ICL IP leverages its Dead Sea brine access to sustain cost leadership in industrial-grade volumes. The Chemours Company differentiates through fluorochemical-bromine integration, while FMC Corporation anchors North American supply with vertically controlled lithium sourcing.
Lithium bromide is an ionic salt with the formula LiBr, typically manufactured through neutralization of lithium hydroxide or lithium carbonate with hydrobromic acid, forming hygroscopic crystals used primarily as a desiccant and refrigerant in absorption refrigeration systems. Battery-grade lithium bromide commands premium qualification protocols as cathode precursor demand tightens purity requirements. HVAC systems represent the most mature application segment, while lithium extraction applications are expanding fastest as direct-extraction technologies commercialize. Chemical synthesis retains concentrated margin pools in pharmaceutical intermediates where reagent-grade specifications apply.
China's MIIT enforces GB standards on industrial salt purity, while the EPA regulates bromine discharge under the Clean Water Act in U.S. manufacturing zones. REACH registration requirements in Europe constrain non-EU suppliers seeking market access. Stakeholders must monitor evolving battery-grade certification thresholds and regional carbon-border adjustments that will reshape cost-competitive sourcing.
Market Dynamics
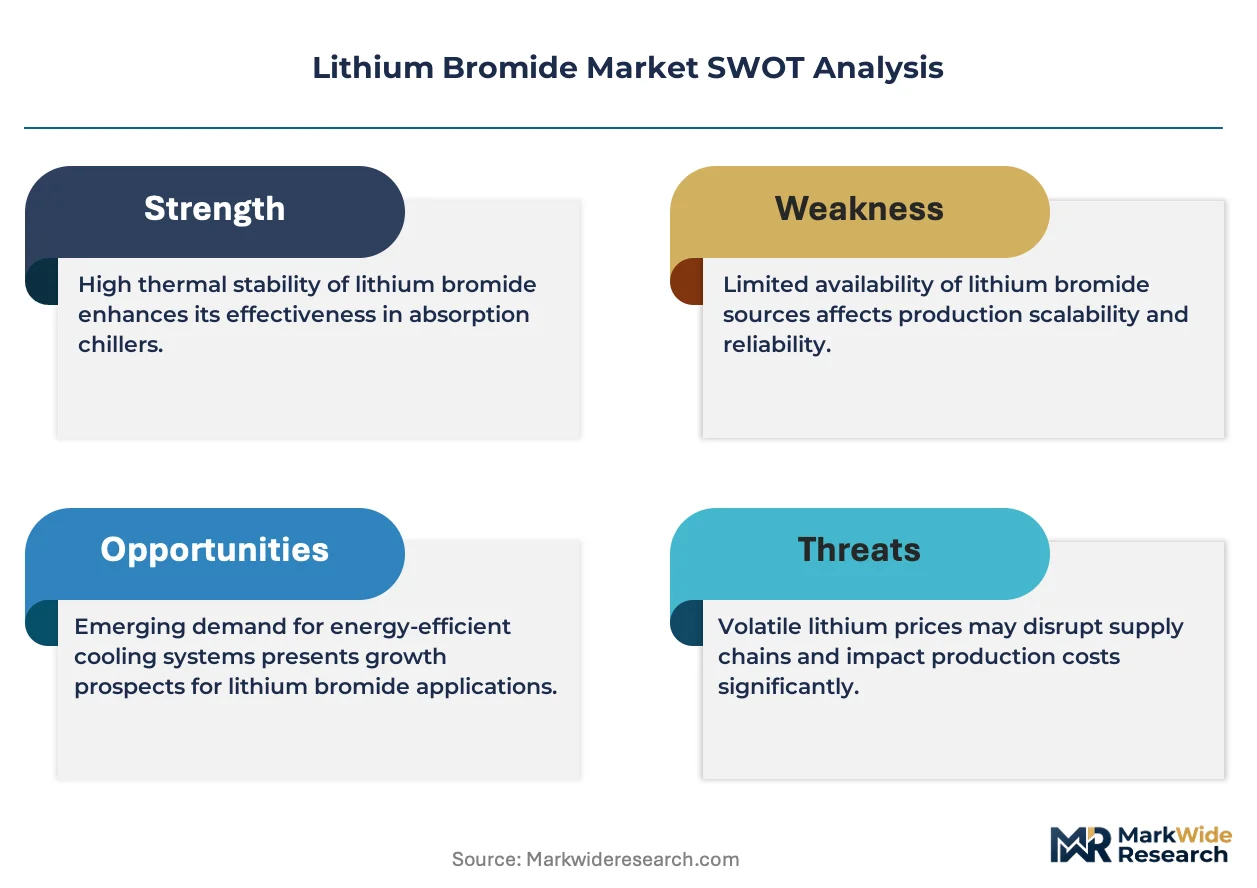
China's dual carbon goals and the EU F-Gas Regulation are forcing rapid refrigerant phase-outs, pulling absorption chiller adoption into commercial HVAC retrofits and tightening purity thresholds across the lithium bromide value chain.
Growth Catalysts
- Building energy codes:Stricter efficiency mandates in California, Germany, and Japan are accelerating replacement of vapor-compression systems with absorption cooling in district networks and large commercial facilities.
- Direct lithium extraction:Selective sorbent technologies commercializing in Chile and Argentina are expanding lithium bromide demand as a reagent in DLE brine processing circuits.
- REACH registration:European chemical compliance requirements are filtering non-EU suppliers and consolidating procurement toward qualified industrial-grade producers with established ECHA dossiers.
Market Restraints
- Bromine supply concentration:Over 70% of elemental bromine originates from Dead Sea and Arkansas brine operations, creating vulnerability to geopolitical or climatic disruption.
- Lithium carbonate volatility:Battery-grade lithium chemical price swings transmit directly into lithium bromide production economics, compressing margin predictability for compounders.
- Membrane desiccant substitution:Solid-state dehumidification technologies are displacing lithium bromide liquid desiccant systems in certain HVAC sub-segments.
Strategic Opportunities
- India building stock expansion:Commercial construction in Mumbai, Delhi, and Bangalore is outpacing grid capacity, creating absorption chiller penetration potential before vapor-compression lock-in.
- Pharmaceutical synthesis demand:Reagent-grade specifications for Grignard and organometallic chemistry are tightening, opening premium margin pools for qualified suppliers.
- Carbon border adjustments:The EU CBAM is incentivizing low-carbon lithium sourcing, rewarding producers with integrated brine-to-salt operations and renewable energy inputs.
Industry Challenges
- Battery-grade qualification timelines:Cathode precursor certification protocols require 18-24 month validation cycles, delaying revenue recognition for new entrants.
- Legacy chiller integration:Absorption system retrofits into existing building management infrastructure demand custom engineering, extending sales cycles and inflating project costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lithium Bromide Market |
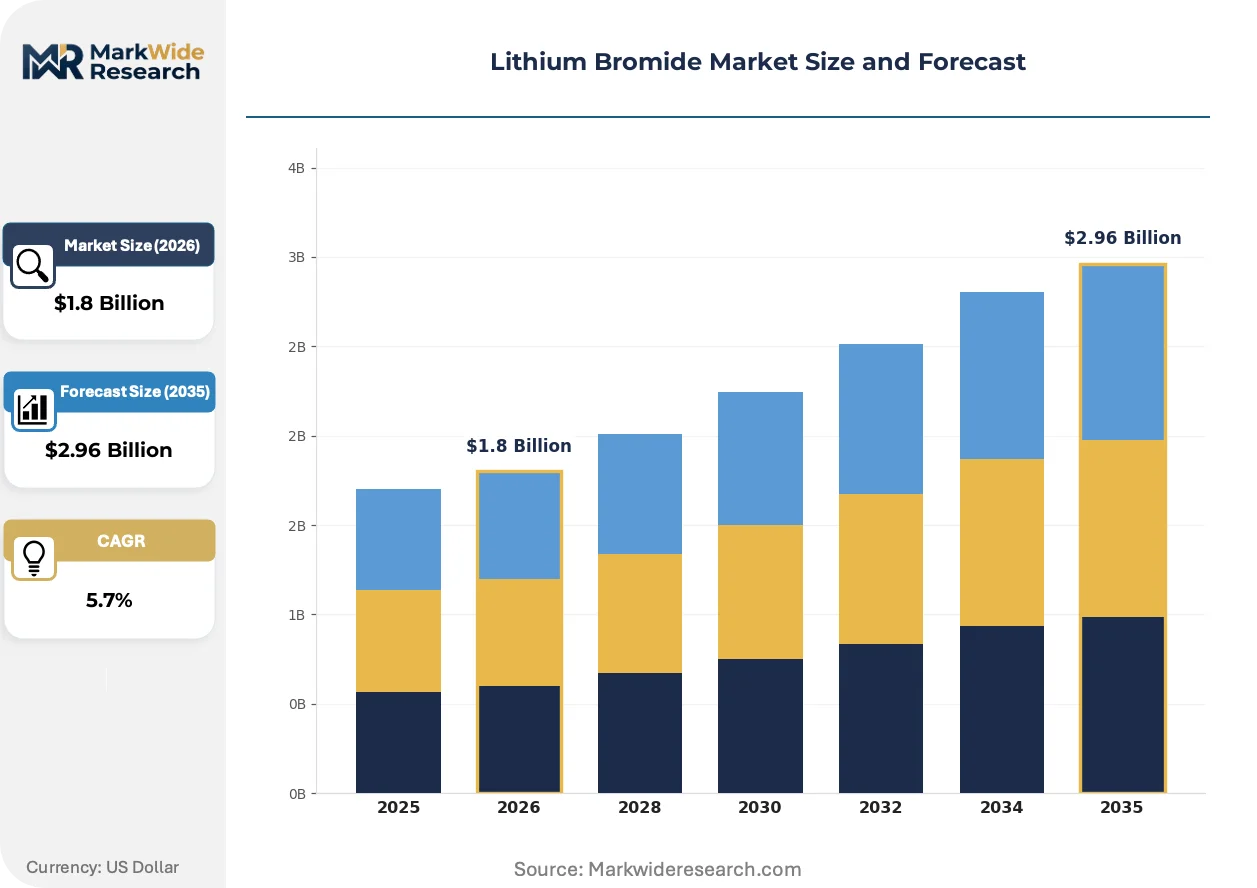
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Battery Grade, Pharmaceutical Grade, Reagent Grade End User: Chemical Manufacturers, Pharmaceutical Companies, Research Institutions, HVAC Systems Application: Chemical Synthesis, Air Conditioning, Lithium Extraction, Laboratory Reactions Distribution Channel: Direct Sales, Online Sales, Distributors, Retail Outlets |
| Companies Covered | ICL IP, The Chemours Company, Rockwood Lithium, Daikin, Arkema, FMC Corporation, Honeywell International Inc., Shreenivas Chemicals, Leverton Clarke, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lithium Bromide Market Strategic Shifts
Process intensification in lithium chemical production and regulatory pressure on synthetic refrigerants are rewriting competitive requirements for purity, energy intensity, and supply chain traceability.
Membrane-based lithium extraction is rewriting the economics of brine processing. Sorbent technologies from Lilac Solutions and Controlled Thermal Resources are reducing evaporation pond footprints by 90%. Chilean and Argentine operators are piloting these systems at commercial scale. The technology is compressing traditional solar evaporation timelines and enabling faster lithium bromide reagent supply expansion.
The EU F-Gas Regulation mandates 79% HFC phase-down by 2030. Industrial cooling in Germany, France, and the Netherlands faces forced technology transitions. Absorption chiller manufacturers are qualifying lithium bromide working fluids under revised safety standards. The regulation is accelerating R-134a displacement in district cooling networks.
Long-term offtake contracting is displacing spot market procurement for battery-grade lithium chemicals. Korean and Japanese cathode producers are securing five-year supply agreements with minimum purity guarantees. This behavior concentrates procurement power among integrated compounders with proven qualification histories. The shift is most visible in supply negotiations for Jiangsu and Shandong manufacturing clusters.
Lithium Bromide Market Segmentation
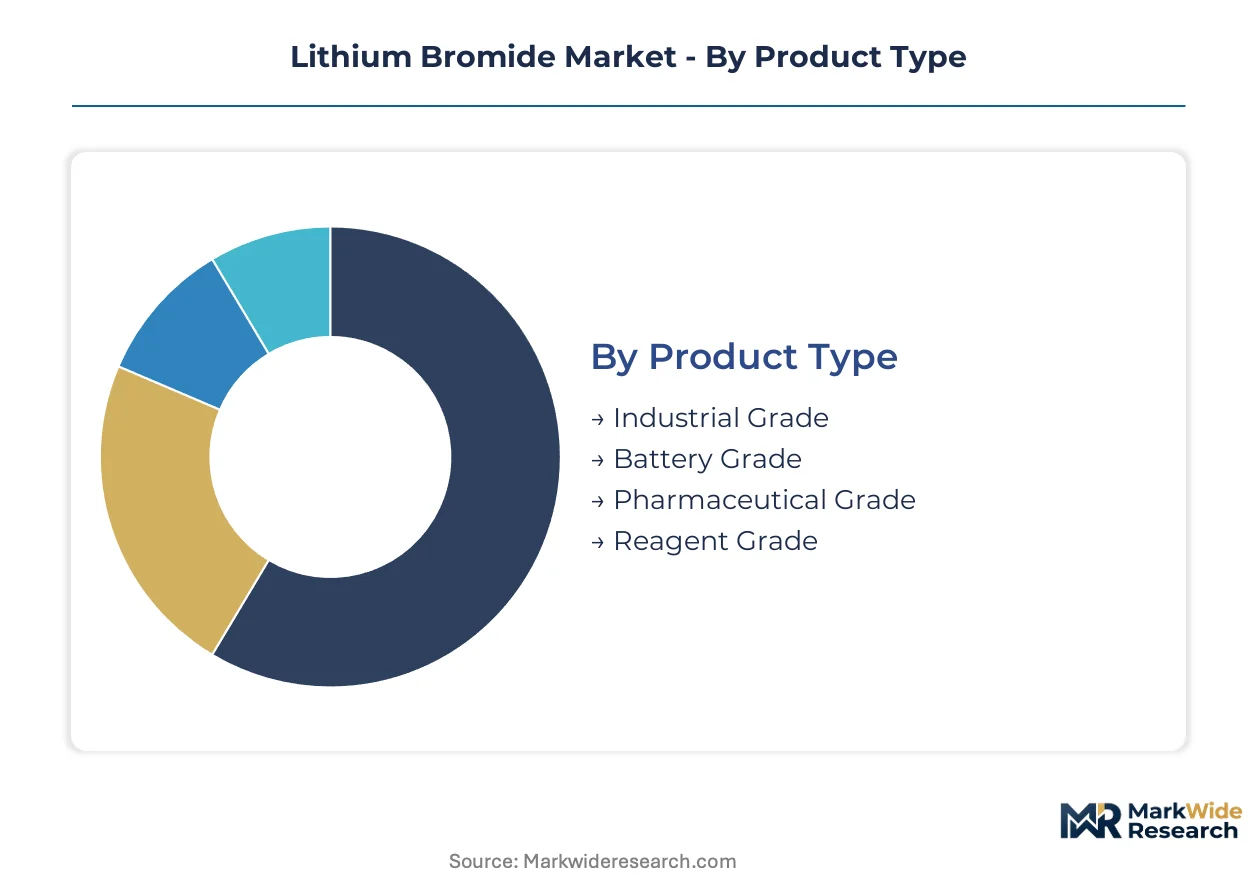
Grade specifications, end-use requirements, and procurement channels each impose distinct technical and commercial constraints on lithium bromide suppliers. Buyers in HVAC systems prioritize hygroscopic stability and bulk logistics, while battery-grade purchasers demand sub-ppm impurity thresholds and multi-year qualification timelines.
Product Type:
Cost tiers separate commodity chemical buyers from premium-grade purchasers with stringent certification requirements.
- Industrial Grade:Hygroscopic crystals with 99-99.5% purity serve absorption refrigeration and dehumidification systems. Demand concentrates in Jiangsu and Shandong manufacturing clusters where HVAC OEMs source bulk volumes under annual contracts.
- Battery Grade:Sub-50 ppm metallic impurity specifications qualify material for cathode precursor synthesis. Korean and Japanese cathode producers enforce 18-24 month validation cycles, concentrating procurement among integrated compounders with proven ECHA dossiers and renewable energy inputs.
- Pharmaceutical Grade:USP/EP-compliant material for drug formulation and parenteral applications.
- Reagent Grade:ACS-certified specifications for analytical chemistry and research protocols.
Industrial grade leads volumes today; battery grade is gaining share fastest.
End User:
Application maturity and margin structure divide procurement patterns across customer categories.
- HVAC Systems:District cooling networks and commercial absorption chiller OEMs specify lithium bromide working fluids for F-Gas-compliant installations. German and Dutch district operators are accelerating R-134a displacement under EU mandates.
- Chemical Manufacturers:Grignard reagent production and organometallic synthesis consume reagent-grade volumes with concentrated margin pools.
- Pharmaceutical Companies:API synthesis and formulation operations require GMP-compliant supply chains with full batch traceability.
- Research Institutions:Laboratory-scale procurement of high-purity material for experimental protocols.
HVAC systems anchor current demand; pharmaceutical companies deliver the steepest margin expansion.
Application:
Technology substitution risk and regulatory pressure reshape competitive intensity across use cases.
- Air Conditioning:Absorption chillers in commercial buildings and industrial facilities utilize lithium bromide-water solution pairs. California Title 24 and Japan's Top Runner standards are accelerating vapor-compression displacement in large facilities.
- Lithium Extraction:Direct extraction technologies from Lilac Solutions and Controlled Thermal Resources deploy lithium bromide as selective sorbent reagent in Chilean and Argentine brine processing circuits.
- Chemical Synthesis:Pharmaceutical intermediates and specialty chemical production employ reagent-grade material.
- Laboratory Reactions:Academic and industrial R&D operations utilize analytical-grade specifications.
Air conditioning dominates installed base; lithium extraction shows the most rapid demand acceleration.
Distribution Channel:
Volume scale and technical service requirements determine channel selection across buyer segments.
- Direct Sales:Integrated producers supply battery-grade and industrial-grade volumes under long-term offtake agreements with cathode manufacturers and HVAC OEMs. Korean and Japanese buyers are consolidating procurement toward five-year contracts with minimum purity guarantees.
- Distributors:Regional chemical distributors serve mid-volume pharmaceutical and research customers with technical support and just-in-time delivery.
- Online Sales:E-procurement platforms handle small-laboratory and research-grade orders with standardized specifications.
- Retail Outlets:Limited presence for consumer-grade desiccant applications.
Direct sales capture the majority of value; distributor relationships are expanding most quickly in emerging markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands the largest installed absorption chiller base, while Germany drives regulatory displacement of synthetic refrigerants under EU mandates. Both markets concentrate procurement among integrated compounders with proven qualification histories.
China
Jiangsu and Shandong provinces host scaled lithium chemical processing corridors serving HVAC OEMs and cathode manufacturers. MIIT enforces GB standards on industrial salt purity, tightening thresholds for battery-grade qualification. Qingdao and Changzhou clusters absorb bulk industrial-grade volumes under annual procurement contracts.
Germany
District cooling networks in Frankfurt and Hamburg accelerate R-134a displacement through absorption chiller retrofits. The EU F-Gas Regulation mandates 79% HFC phase-down by 2030, forcing technology transitions in commercial HVAC. BASF and Lanxess chemical corridors in Ludwigshafen and Leverkusen concentrate reagent-grade demand for pharmaceutical synthesis.
United States
Arkansas brine operations supply elemental bromine feedstock for domestic lithium bromide production. EPA regulates bromine discharge under the Clean Water Act in manufacturing zones around Magnolia and El Dorado. Texas and California commercial construction absorbs industrial-grade volumes for absorption cooling in data centers and healthcare facilities.
Japan
Tokyo and Osaka metropolitan districts deploy absorption chillers under METI energy efficiency directives and Top Runner standards. Cathode producers in Kansai enforce 18-24 month battery-grade qualification protocols, consolidating procurement toward integrated suppliers. Nagoya automotive and electronics corridors drive reagent-grade consumption for precision chemical synthesis.
India
Mumbai, Delhi, and Bangalore commercial construction outpaces grid capacity, creating absorption chiller penetration potential before vapor-compression lock-in. BIS certification requirements filter non-domestic suppliers in bulk chemical procurement. Gujarat chemical corridors near Ahmedabad and Vadodara scale lithium salt processing for domestic HVAC OEM supply.
Lithium Bromide Market Competitive Environment
Top-tier vendors anchor integrated brine-to-salt operations, while specialized compounders occupy qualification-dependent niches. The structure concentrates procurement power among producers with captive bromine access and renewable energy inputs. Two archetypes dominate: Dead Sea and Arkansas brine operators with backward integration into elemental bromine, and Asian compounders with scaled lithium hydroxide neutralization capacity. Competitive moves center on long-term offtake contracting and carbon-border positioning under EU CBAM.
Within the brine-integrated tier, ICL IP exemplifies cost leadership through Dead Sea access, while The Chemours Company occupies fluorochemical-bromine integration positioning. FMC Corporation anchors North American supply with vertically controlled lithium sourcing. These three represent distinct geographic and feedstock archetypes rather than interchangeable competitors.
| Leading Market Players |
|---|
| ICL IP |
| The Chemours Company |
| Rockwood Lithium |
| Daikin |
| Arkema |
| FMC Corporation |
| Honeywell International Inc. |
| Shreenivas Chemicals |
| Leverton Clarke |
| Others |
Value Chain & Pricing Dynamics
Process chemist concentrations in Jiangsu and Shandong provinces anchor lithium bromide manufacturing, with labor-cost differentials between these eastern China clusters and inland alternatives widening spreads between battery-grade and industrial-grade pricing tiers. The EU F-Gas Regulation and China's dual carbon goals are tightening qualification protocols, forcing buyers to absorb premium certification costs or downgrade to unqualified supply.
Pricing Analysis
Bundled technical service contracts command substantial premiums over unbundled commodity transactions. Long-term offtake agreements with cathode manufacturers stratify across premium, standard, and economy tiers based on purity guarantees and renewable energy verification. Cost compression in industrial-grade volumes is intensifying because Dead Sea brine operators leverage captive bromine supply. HVAC OEMs in Jiangsu exhibit highest price sensitivity, while Korean cathode producers accept premium qualification timelines for battery-grade security.
Supply Chain Analysis
Workforce availability constraints in Jiangsu and Shandong chemical corridors are elevating wage pressure for qualified process engineers. Supply concentrates in China, Israel, and the United States, with elemental bromine feedstock anchored in Dead Sea and Arkansas brine operations. Production draws from lithium hydroxide, hydrobromic acid, and energy inputs, with single-source vulnerability concentrated in bromine extraction. Distribution runs through direct sales to integrated compounders and regional distributors serving pharmaceutical intermediates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU F-Gas mandates and China's dual carbon goals are forcing refrigerant phase-outs and accelerating absorption chiller retrofits. The regulatory tailwind concentrates procurement power among qualified producers with established ECHA dossiers.
For Market Incumbents: Cement backward integration into captive bromine supply through Dead Sea or Arkansas brine access, insulating margin from elemental feedstock volatility. Lock in five-year offtake agreements with Korean and Japanese cathode producers before battery-grade qualification timelines extend further. Defend against membrane desiccant substitution by embedding lithium bromide into district cooling engineering specifications under EU mandates.
For New Entrants and Emerging Players: The price-point gap between premium battery-grade and economy industrial-grade specifications exceeds viable entry thresholds for unqualified compounders. Target India's absorption chiller market before vapor-compression lock-in, leveraging BIS certification gaps against established EU and Chinese suppliers. Pursue reagent-grade pharmaceutical synthesis niches where ACS certification requirements filter commodity competitors and sustain margin pools.
For Investors and Strategic Acquirers: HVAC OEMs with absorption chiller portfolios are the most active acquirer in this space, seeking captive lithium bromide supply for F-Gas-compliant product lines. Five-to-ten-year viability hinges on direct lithium extraction scale-up in Chile and Argentina, where sorbent technology commercialization is compressing traditional evaporation economics. Monitor EU CBAM implementation as the inflection signal for low-carbon lithium sourcing premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bromine Supply | Dead Sea and Arkansas brine access insulates compounders from elemental feedstock concentration risk. |
| Battery-Grade Qualification Investment | ECHA dossier completion opens Korean and Japanese cathode procurement to five-year offtake contracting. |
| Direct Lithium Extraction Partnership | Lilac Solutions and Controlled Thermal Resources sorbent deployments expand reagent demand in Chilean brine circuits. |
| EU CBAM Carbon Border Positioning | Renewable energy inputs in Jiangsu and Shandong production qualify low-carbon lithium for premium European procurement. |
| India Distribution Channel Expansion | Mumbai and Delhi commercial construction outpaces grid capacity, creating absorption chiller penetration before vapor-compression lock-in. |
Study Parameters
Coverage spans East Asia, Europe, North America, and South America, with primary inputs from each region combined with secondary validation. Interviews with plant managers at lithium chemical facilities, procurement leads at HVAC OEMs, technical R&D directors at cathode manufacturers, and distribution channel partners informed supply-side dynamics. Secondary sources include customs and trade data, SEC filings from integrated chemical producers, ECHA registration databases, and MIIT GB standard documentation. Bottom-up volume modeling and top-down market sizing were triangulated against producer capacity disclosures.
Granularity was maintained at the grade-tier, end-use industry, and regional production hub levels across the projection horizon. Segment-level CAGRs were derived from installation rates of absorption chillers under EU F-Gas mandates, direct lithium extraction commercialization timelines in Chile and Argentina, and battery-grade qualification protocol evolution. Industry-specific inputs incorporated bromine supply concentration from Dead Sea and Arkansas operations, lithium carbonate price transmission elasticities, and REACH registration completion rates among Asian compounders.
Caveats apply where bromine supply disruption, lithium carbonate volatility, or membrane desiccant substitution could materially shift the outlook. Forecasts reflect assumptions regarding regulatory enforcement consistency, DLE technology scale-up rates, and carbon border adjustment implementation scope. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Ethylene Oxide Market
Bulk Chemicals
Middle East and Africa Ferric Chloride Market
Bulk Chemicals
Ethyleneamines Market
Bulk Chemicals
Ethylbenzene Market
Bulk Chemicals
Global Crude Sulfate Turpentine Market
Bulk Chemicals
Europe Lipids Market
Bulk Chemicals
Aerospace and Defense Chemical Distribution Market
Bulk Chemicals
4-Diisopropylbenzene Market
Bulk Chemicals
Nahcolite Market
Bulk Chemicals
Hydrochloric Acid Market
Bulk Chemicals
Global Dicyandiamide Market
Bulk Chemicals
Battery Grade Lithium Chloride Market
Bulk Chemicals
Global Ammonium Sulphate Market
Bulk Chemicals
Ammonium Bicarbonate Market
Bulk Chemicals
North America Hydrochloric Acid Market
Bulk Chemicals
Asia-Pacific Caustic Soda Market