
 Caustic Calcined Magnesia Market | 2026-2036
Caustic Calcined Magnesia Market Size, Share, and Industry Trends Forecast 2026-2036
Caustic Calcined Magnesia Market Intelligence
Buyer concentration among steel mills is pivoting toward integrated blast furnace operators in China and India that now contract directly for refractory-grade caustic calcined magnesia rather than purchasing through trading intermediaries. Sibelco leverages its European logistics network to supply specialty grades to glass manufacturers requiring low-iron content. Nedmag anchors its position through backward integration into Dutch salt brine operations, securing synthetic magnesia feedstock independent of mined ore volatility. Grecian Magnesite specializes in high-purity caustic calcined grades from its Greek deposits, competing on consistency for pharmaceutical and chemical applications.
Caustic calcined magnesia refers to magnesium oxide produced by calcining magnesite or magnesium hydroxide at temperatures between 700°C and 1000°C, yielding a reactive, finely divided powder with specific surface areas typically exceeding 30 m²/g and magnesium oxide content ranging from 80% to 95% depending on feedstock purity. Its primary industrial purpose centers on chemical reactivity applications including wastewater neutralization, agricultural soil amendment, and as a precursor in refractory brick bonding systems. Hard burned magnesia commands mature volume pools in environmental protection where municipal wastewater treatment plants standardize on bulk neutralization chemicals. Lightly burned magnesia represents the fastest-growing product category as fertilizer producers adopt micronutrient delivery systems requiring high reactivity. The refractory materials application segment concentrates margin pools at the premium end where steel mills specify low-calcium grades for extended ladle lining life.
China's MEE enforces stricter particulate emissions limits on magnesia calciners in Liaoning, forcing facility upgrades that favor larger producers with capital access. REACH registration requirements in Europe constrain import volumes of unregistered caustic calcined magnesia grades, shaping competitive access for Turkish and Greek suppliers. ISO 9001 quality certification and BIS standards in India increasingly filter market entry for construction-grade and agricultural applications. Stakeholders must monitor how carbon border adjustment mechanisms and evolving emissions trading systems reshape cost structures for energy-intensive calcination operations across competing supply bases.
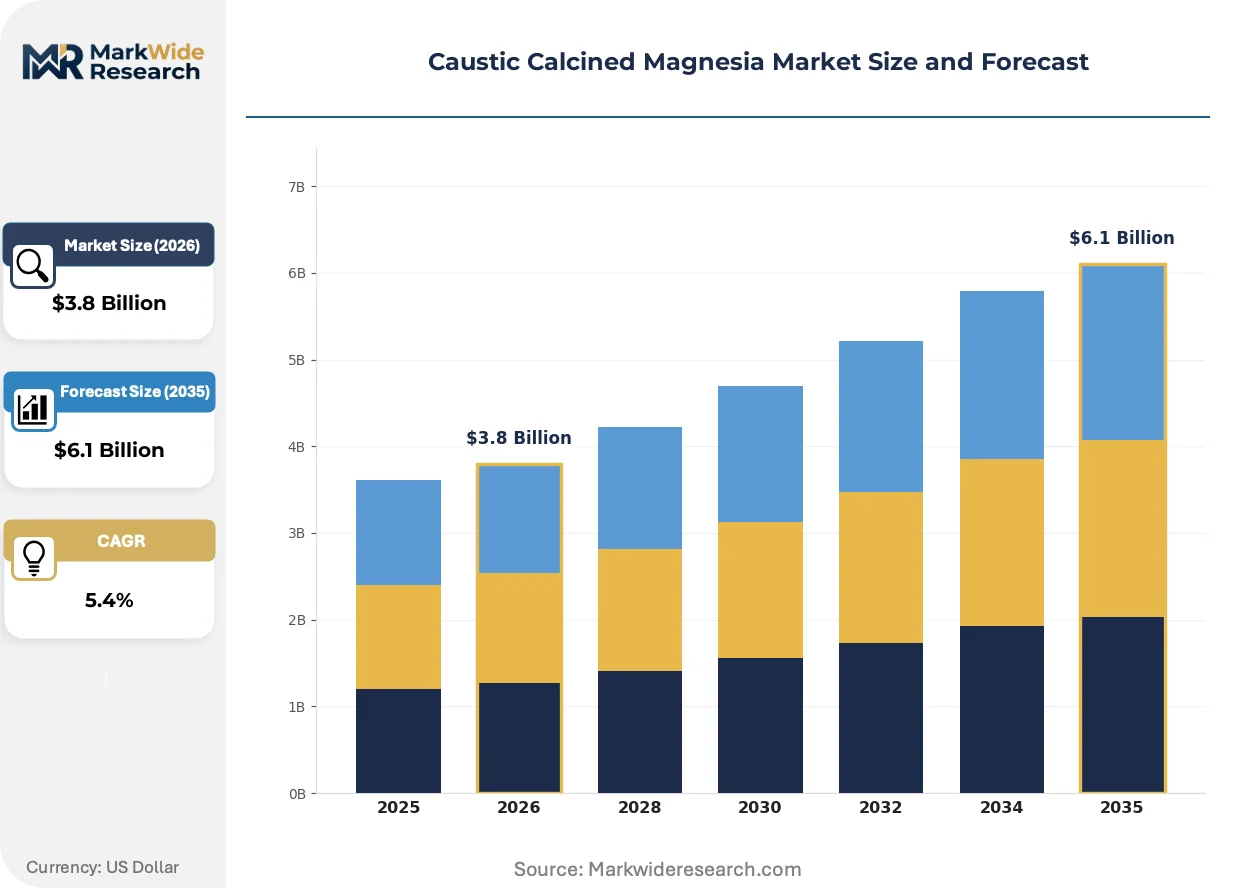
Market Dynamics
Blast furnace relining cycles are compressing across Asian steel mills, forcing direct procurement relationships with caustic calcined magnesia suppliers and bypassing traditional trading intermediaries. This structural compression in refractory consumption patterns is concentrating volume with integrated furnace operators who now specify low-calcium, high-reactivity grades for extended ladle lining performance.
Growth Catalysts
- Dual carbon goals:China's MEE emissions standards are accelerating calcination technology upgrades, favoring producers with capital access for cleaner production assets.
- Micronutrient delivery systems:Fertilizer producers are adopting lightly burned magnesia for high-reactivity soil amendment applications.
- Liaoning Province concentration:Captive magnesite reserves give Chinese processors sustained feedstock cost advantages over import-dependent competitors.
Market Restraints
- Energy cost volatility:Natural gas and electricity prices for calcination operations fluctuate with regional grid constraints.
- REACH registration friction:Unregistered caustic calcined magnesia grades face constrained import volumes into European markets.
- Synthetic magnesia substitution:Dutch salt brine-derived synthetic magnesia offers feedstock independence from mined ore quality variation.
Strategic Opportunities
- Pharmaceutical grade expansion:High-purity caustic calcined magnesia from Greek deposits commands premium positioning in chemical synthesis applications.
- Direct mill contracting:Indian integrated steel producers are eliminating intermediaries for refractory-grade supply security.
- Carbon border adjustment preparation:Energy-intensive calciners can secure competitive positioning through emissions monitoring infrastructure ahead of mechanism implementation.
Industry Challenges
- ISO 9001 certification timelines:Construction-grade and agricultural application entry requires extended quality system implementation.
- Particulate control capex:Liaoning facility upgrades demand substantial capital for MEE-compliant emissions capture technology.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Caustic Calcined Magnesia Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.1 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lightly Burned Magnesia, Hard Burned Magnesia, Dead Burned Magnesia, Caustic Magnesia Application: Refractory Materials, Agriculture, Environmental Protection, Chemical Industry, Pharmaceuticals End User: Steel Mills, Glass Manufacturers, Wastewater Treatment Plants, Fertilizer Producers Packaging Type: Bulk Bags, Paper Bags, Woven Sacks, Drums |
| Companies Covered | Sibelco, Kumas, Nedmag, Erzkontor Group, Star Grace Mining, Grecian Magnesite, TERNA MAG, Queensland Magnesia, Magnezit Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Caustic Calcined Magnesia Market Strategic Shifts & Innovations
Calcination technology and supply chain configuration are converging to reshape competitive positioning in caustic calcined magnesia. Three active developments are compressing traditional procurement patterns while elevating quality differentiation.
Flash calcination systems are integrating into new production facilities, replacing rotary kilns with rapid thermal processing that yields more uniform particle size distribution. Steel mills in India and China are specifying flash-calcined material for refractory applications where batch consistency directly impacts ladle lining life. This technology is integrating quality control upstream, compressing the role of post-production blending and third-party certification.
REACH registration requirements are tightening import pathways for unregistered magnesia grades, constraining competitive access for Turkish and non-EU Mediterranean suppliers. ECHA compliance timelines are extending lead times for new market entrants, while registered incumbent suppliers consolidate shelf space with glass and chemical manufacturers. Specialty low-iron grades for optical glass production face the most acute registration-driven supply concentration.
Integrated steel mills are consolidating procurement through direct long-term contracts with calcination operators, displacing spot-market purchasing through trading houses. This channel compression is most visible across Chinese and Indian blast furnace operators seeking supply security amid tightening Liaoning export availability. Trading intermediaries are pivoting toward smaller agricultural and construction-grade accounts where volume fragmentation sustains intermediary relevance.
Caustic Calcined Magnesia Market Segmentation
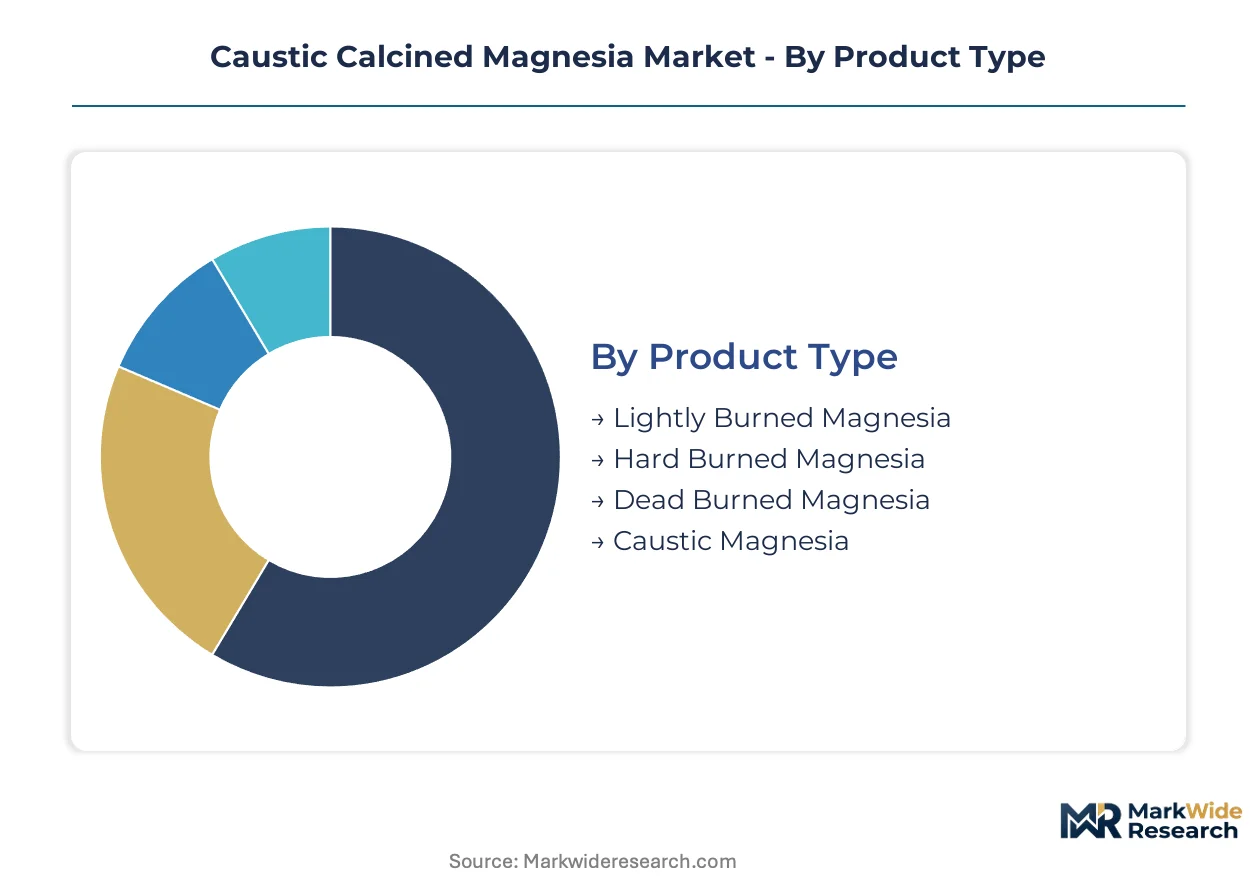
Caustic calcined magnesia serves divergent performance requirements across refractory bonding, chemical reactivity, and soil amendment applications. Segmentation reveals where margin pools concentrate versus where volume commoditization dominates procurement patterns.
Product Type:
Integration depth varies sharply: lightly burned grades embed directly into reactive chemical systems, while dead burned variants function as standalone refractory aggregates.
- Lightly Burned Magnesia:Produced at 700-1000°C with specific surface areas exceeding 30 m²/g, this grade delivers maximum reactivity for agricultural micronutrient delivery and wastewater neutralization. Fertilizer producers in India specify this grade for high-efficiency soil amendment where rapid magnesium ion release improves crop uptake rates.
- Hard Burned Magnesia:Intermediate calcination temperatures yield moderate reactivity with improved density for environmental protection bulk chemicals. Municipal wastewater treatment plants across China standardize procurement on this grade for pH neutralization operations where cost efficiency outweighs reactivity maximization.
- Dead Burned Magnesia:Sintered above 1500°C for refractory aggregate applications requiring minimal hydration reactivity.
- Caustic Magnesia:General-purpose designation encompassing variable reactivity grades for construction and industrial bonding systems.
Volume placements concentrate in hard burned magnesia for environmental bulk chemicals; the faster expansion belongs to lightly burned grades for precision agriculture.
Application:
Cost tier stratification separates premium specification markets from commodity bulk procurement, with certification requirements acting as the primary filtering mechanism.
- Refractory Materials:Low-calcium, high-purity grades specified for steel ladle and blast furnace lining applications where thermal shock resistance extends campaign life. Integrated mills in China and India contract directly for these grades, bypassing intermediaries to secure supply continuity amid Liaoning export constraints.
- Agriculture:Micronutrient fertilizer applications require consistent particle sizing and controlled reactivity for soil amendment efficacy. European REACH registration requirements constrain import pathways for unregistered agricultural grades, favoring incumbent suppliers with established ECHA compliance.
- Environmental Protection:Bulk neutralization chemicals for municipal and industrial wastewater treatment, standardized on cost-per-ton efficiency metrics.
- Chemical Industry:Intermediate reactivity grades for magnesium salt production and industrial synthesis applications.
- Pharmaceuticals:Ultra-high-purity grades with stringent heavy metal limits for active pharmaceutical ingredient synthesis and excipient applications.
Margin concentration sits with refractory and pharmaceutical specifications; agricultural volumes are climbing fastest as micronutrient adoption spreads.
End User:
Customer type determines procurement sophistication, with integrated industrial operators demanding direct supplier relationships versus fragmented agricultural buyers sustaining intermediary channels.
- Steel Mills:Blast furnace and ladle lining operators specify low-calcium caustic calcined magnesia for refractory brick bonding systems. Relining cycle compression across Asian integrated producers is forcing direct long-term contracts with calcination operators, eliminating traditional trading house intermediaries.
- Glass Manufacturers:Optical and specialty glass producers require ultra-low-iron content grades where trace impurities compromise optical clarity. REACH-registered European suppliers command shelf space with this segment due to ECHA compliance barriers for new entrants.
- Wastewater Treatment Plants:Municipal operators prioritize bulk cost efficiency over reactivity precision, standardizing on hard burned grades through distributor channels.
- Fertilizer Producers:Compound fertilizer manufacturers incorporate lightly burned magnesia for magnesium micronutrient delivery, with procurement fragmented across regional blending operations.
Contract value concentrates with steel mills; fertilizer producers are expanding procurement most rapidly.
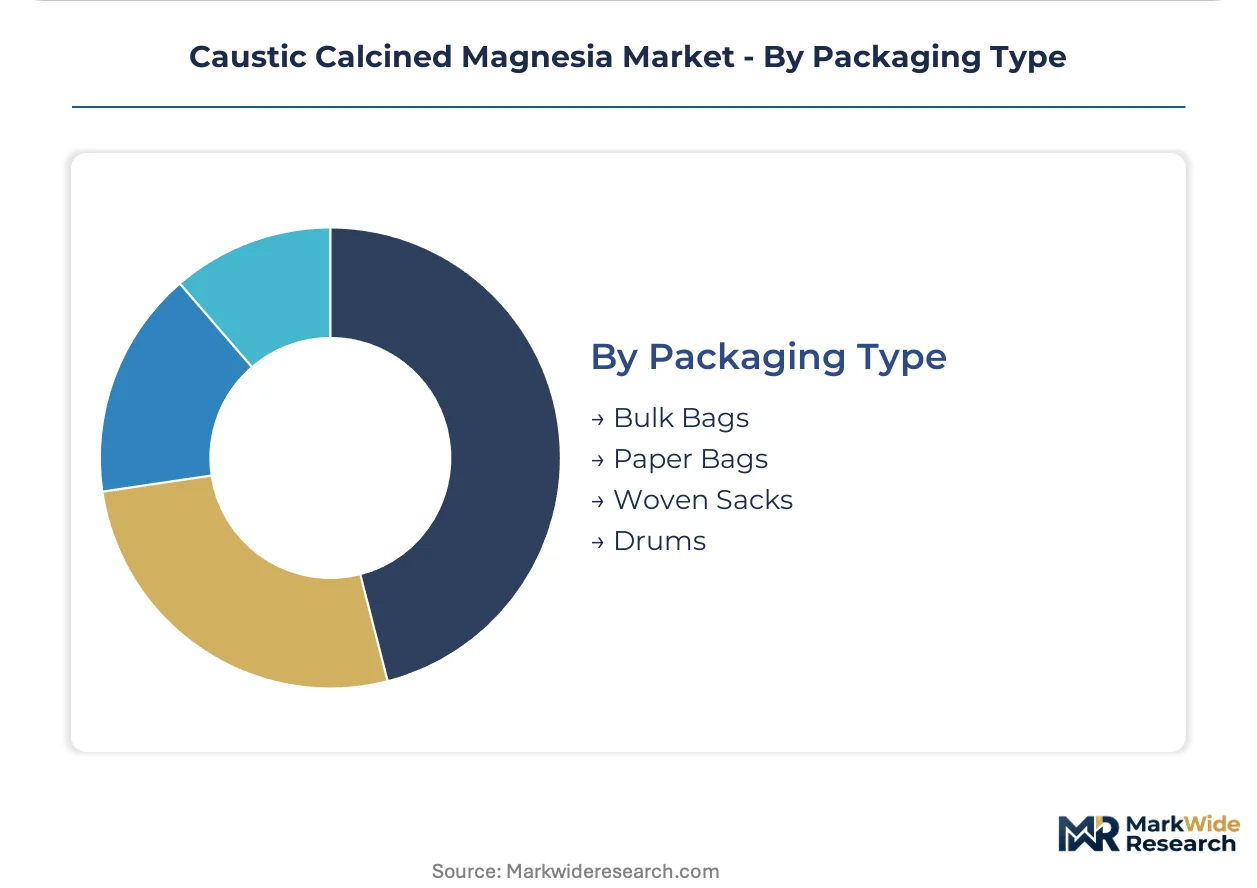
Packaging Type:
Supply chain configuration and handling infrastructure dictate packaging selection, with bulk systems favored at scale and unitized packaging serving fragmented end points.
- Bulk Bags:One-ton flexible intermediate bulk containers dominate refractory and agricultural volume shipments to integrated mills and fertilizer blending plants with mechanized handling systems.
- Paper Bags:Multi-wall kraft construction for 25-50 kg pharmaceutical and specialty chemical shipments requiring moisture protection and clean handling.
- Woven Sacks:Polypropylene construction for construction-grade and general industrial applications where cost minimization precedes barrier properties.
- Drums:Steel or fiber containers for high-reactivity lightly burned grades requiring airtight storage to prevent premature hydration.
Shipment volumes cluster in bulk bags for integrated end users; drum packaging is gaining fastest for high-reactivity specialty grades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Steel mill procurement concentrates demand in China and India, while European environmental regulations and North American refractory specifications fragment supply access across distinct compliance zones.
China
Blast furnace relining cycles compress across Hebei and Jiangsu provinces, forcing direct contracts with Liaoning-based calciners. MEE emissions standards tighten particulate limits on magnesia processors, accelerating technology upgrades among larger producers. Dalian and Yingkou clusters concentrate calcination capacity where captive magnesite reserves sustain feedstock cost advantages.
India
Integrated steel producers in Odisha and Chhattisgarh eliminate trading intermediaries for refractory-grade supply security. BIS standards increasingly filter market entry for construction-grade and agricultural applications. Jamshedpur and Rourkela industrial belts anchor procurement concentration as Tata Steel and JSW specify low-calcium grades for extended ladle lining life.
Germany
REACH registration requirements constrain import volumes of unregistered caustic calcined magnesia grades, shaping competitive access for Turkish and Greek suppliers. ECHA compliance timelines extend lead times for new market entrants. Ruhr industrial region glass manufacturers demand ultra-low-iron specialty grades where trace impurities compromise optical clarity.
United States
Environmental protection applications standardize on hard burned magnesia for municipal wastewater neutralization operations. EPA discharge standards drive bulk chemical procurement patterns across Great Lakes and Gulf Coast treatment facilities. Ohio River Valley refractory consumers specify consistent reactivity grades for steel foundry bonding systems.
Brazil
Agricultural micronutrient adoption expands fertilizer blender demand for lightly burned magnesia with controlled particle sizing. ANVISA pharmaceutical regulations constrain high-purity grade import pathways for chemical synthesis applications. São Paulo state compound fertilizer manufacturers incorporate reactive magnesia for magnesium-deficient tropical soils.
Caustic Calcined Magnesia Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue specialty certification pathways. Market structure consolidates around integrated miners with captive magnesite reserves and synthetic feedstock operators with brine-derived independence. Three archetypes dominate: Liaoning-based miners with backward integration into ore bodies, European specialists with REACH-registered shelf space, and synthetic producers with salt brine feedstock security. Capacity expansion and emissions compliance technology licensing represent the dominant competitive moves.
Within the European specialty tier, Sibelco leverages logistics networks for glass manufacturer supply, while Grecian Magnesite exemplifies high-purity deposit-based positioning. Nedmag anchors the synthetic feedstock archetype through Dutch salt brine operations. These three represent distinct strategic vectors: logistics-integrated distribution, geological purity premiums, and feedstock independence from mined ore volatility.
| Leading Market Players |
|---|
| Sibelco |
| Kumas |
| Nedmag |
| Erzkontor Group |
| Star Grace Mining |
| Grecian Magnesite |
| TERNA MAG |
| Queensland Magnesia |
| Magnezit Group |
| Others |
Cost & Logistics Intelligence
Integrated steel mill procurement consolidation across Hebei and Jiangsu provinces forces calcination operators to absorb emissions compliance costs while maintaining contract pricing, compressing margins on standard refractory grades and widening spreads for certified low-calcium specifications.
Pricing Analysis
Volume commoditization dominates hard burned magnesia for wastewater neutralization, while premium margin pools concentrate in lightly burned grades for precision agriculture and ultra-low-iron specifications for optical glass. Price differentiation separates REACH-registered European suppliers from unregistered import competition, with certification tier and captive magnesite feedstock acting as the primary drivers. Pricing pressure stems from MEE-mandated particulate control investments in Liaoning, forcing facility upgrade costs onto producers without full pass-through to contract buyers. Municipal wastewater treatment plants exhibit highest price sensitivity, while pharmaceutical manufacturers prioritize heavy metal consistency over per-ton cost.
Supply Chain Analysis
China's tightening domestic-content preferences for state-backed infrastructure projects reshape sourcing patterns, favoring Liaoning-based calciners with captive ore reserves over import-dependent processors. Geographic supply concentration centers on China, Greece, and the Netherlands, with raw material dependencies on magnesite ore quality, natural gas for calcination energy, and salt brine chemistry for synthetic routes. Single-source vulnerability runs through Liaoning's cluster dominance, where export constraints from environmental compliance create supply discontinuity risks. Distribution runs through direct long-term contracts to integrated steel mills, with trading intermediaries relegated to fragmented agricultural and construction-grade accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market structure favors consolidation as MEE emissions standards and REACH registration barriers eliminate capital-constrained calciners, concentrating supply with integrated miners and synthetic feedstock operators possessing compliance infrastructure.
For Market Incumbents: Extend backward integration into captive magnesite reserves or salt brine feedstock to secure cost position against ore quality volatility. Invest in flash calcination technology to meet steel mill consistency specifications, while leveraging existing REACH registrations to defend shelf space against Turkish and non-EU Mediterranean entrants seeking European glass manufacturer supply relationships. For New Entrants and Emerging Players: BIS standards in India open a window for domestic calciners serving Odisha and Chhattisgarh steel belts with construction-grade and agricultural specifications. Target micronutrient fertilizer applications in São Paulo state compound blending operations, where controlled-reactivity lightly burned magnesia faces less entrenched incumbent supply. Pursue joint venture structures with Liaoning processors seeking technology licensing partnerships for MEE-compliant emissions capture. For Investors and Strategic Acquirers: Re-rating potential sits with synthetic feedstock operators given carbon border adjustment mechanism preparation and feedstock independence from mined ore volatility. Focus acquisition screening on Dutch salt brine-derived producers and Greek high-purity deposit operators with pharmaceutical grade certification. Watch for inflection in European carbon border adjustment implementation timelines, which would accelerate cost advantage shifts toward low-emissions calcination assets.| Strategic Initiative | Industry Significance |
|---|---|
| Flash Calcination Technology Deployment | Steel mills in India and China specify flash-calcined material for ladle lining consistency. |
| REACH Registration Completion | ECHA compliance secures shelf space with German Ruhr region optical glass manufacturers. |
| Backward Integration into Captive Reserves | Liaoning magnesite ore bodies sustain feedstock cost advantages over import-dependent competitors. |
| Carbon Border Adjustment Infrastructure | Emissions monitoring systems position calciners for competitive cost structures under EU mechanisms. |
| Direct Mill Contracting Relationships | Long-term offtake agreements with Tata Steel and JSW eliminate trading intermediary margin extraction. |
Research Approach
Trade databases, MEE emissions filings, and ECHA registration records formed the secondary backbone, cross-referenced with primary interviews involving Liaoning plant managers, European glass manufacturer procurement leads, and Indian fertilizer blending operators. Bottom-up volume modeling from calcination capacity utilization rates was triangulated against top-down steel refractory consumption estimates across the analysis window.
Historical trendline analysis of blast furnace relining cycle compression and micronutrient adoption curves informed the projection framework. Segmentation dimensions included calcination intensity tier, end-use application, geographic production hub, and certification status. CAGRs were derived from elasticity modeling of steel output and fertilizer formulation shifts, with flash calcination penetration rates and REACH compliance timelines as industry-specific forecast inputs.
The model assumes a particular technology adoption path for emissions-compliant calcination; alternative pathways for particulate capture retrofits would alter the outlook for Liaoning facility economics. Forecasts reflect assumptions regarding MEE enforcement intensity and carbon border adjustment implementation scope, with supply disruption from environmental compliance timelines representing a specific revision risk. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Industrial Phenol Market
Industrial Chemicals
Commercial Electronic Detonator Market
Industrial Chemicals
Pyrethrin Market
Industrial Chemicals
Isononanol (INA) Market
Industrial Chemicals
Gypsum-Free Cement Market
Industrial Chemicals
Heat Shrink Tubes Market
Industrial Chemicals
Methylene Diphenyl Di-Isocyanate (MDI) Market
Industrial Chemicals
Activated Carbon for Sugar Decolorization Market
Industrial Chemicals
Vacuum Degreasers Market
Industrial Chemicals
Hazardous Chemicals Packaging Market
Industrial Chemicals
Profenofos Market
Industrial Chemicals
Asia-Pacific Activated Carbon Market
Industrial Chemicals
Soil Hardening Agent Market
Industrial Chemicals
Asia-Pacific Molecular Sieve Market
Industrial Chemicals
Powder Coating Guns Market
Industrial Chemicals
High Viscosity Mixer Market