
 Global N-MDEA Market | 2026-2036
Global N-MDEA Market Size, Share, and Industry Trends Forecast 2026-2036
Global N-MDEA Market Foresight
The specialized amine chemist labor pool is collapsing across North America and Western Europe, constraining process optimization and new plant commissioning timelines for N-MDEA producers. Huntsman Corporation leverages its integrated ethylene oxide and amine manufacturing footprint in the US Gulf Coast to sustain captive feedstock security. BASF SE anchors European supply through its Ludwigshafen Verbund complex, where backward integration into ethylene oxide secures cost discipline. Mitsubishi Chemical Corporation dominates technical-grade N-MDEA output for Asian gas treatment markets through dedicated reactor trains at its Yokkaichi site.
N-methyldiethanolamine is a tertiary alkanolamine with the molecular formula CH3N(C2H4OH)2, manufactured via the reductive amination of diethanolamine with formaldehyde and hydrogen over a nickel catalyst, and functions primarily as a selective absorbent for hydrogen sulfide and carbon dioxide in acid gas removal systems. Gas sweetening applications occupy the dominant value share due to irreversible demand from sour gas processing and LNG pretreatment trains, while chemical intermediates for surfactant synthesis represent the fastest-expanding segment as Asian personal care formulators shift toward milder emulsifier chemistries. Water treatment applications sustain steady offtake through municipal and industrial boiler feedwater conditioning, though margin pools remain thinner relative to oilfield-specification product grades.
EPA New Source Performance Standards under 40 CFR Part 60 Subpart OOOOa mandate leak detection and repair protocols that elevate demand for high-efficiency amine circulation systems in US gas processing. REACH registration requirements and the EU F-Gas Regulation constrain market access for non-compliant Asian exporters while rewarding ECHA-registered European producers with preferential offtake from integrated energy majors. Stakeholders must monitor carbon capture retrofit announcements at coal and gas-fired power stations, as post-combustion capture solvent specifications will determine whether N-MDEA formulations displace conventional monoethanolamine in next-generation scrubbing systems.
Market Dynamics
Permian Basin gas processing expansions and Gulf Coast refinery upgrades are concentrating demand for high-purity N-MDEA formulations, while REACH compliance and MEE sulfur protocols are fragmenting supply qualifications across Atlantic and Pacific trade lanes.
Growth Catalysts
- EPA Subpart OOOOa mandates:Leak detection and repair protocols in US gas processing elevate demand for high-efficiency amine circulation systems and precision-engineered solvent formulations.
- Carbon capture retrofits:Post-combustion capture specifications at coal and gas-fired power stations open pathways for N-MDEA to displace monoethanolamine in next-generation scrubbing architectures.
- LNG pretreatment trains:Sour gas processing infrastructure across North American export terminals sustains irreversible offtake for selective hydrogen sulfide absorbents.
Market Restraints
- Ethylene oxide feedstock volatility:Captive supply advantages for integrated producers lock out merchant buyers during ethylene cracker turnaround cycles.
- Specialized amine chemist scarcity:Collapsing technical labor pools across North America and Western Europe constrain process optimization and new plant commissioning timelines.
- EU F-Gas Regulation barriers:Non-compliant Asian exporters face market access constraints while ECHA-registered European producers capture preferential offtake from integrated energy majors.
Strategic Opportunities
- Asian personal care formulators:Shifting emulsifier preferences toward milder surfactant chemistries expand chemical intermediate demand for technical-grade N-MDEA beyond traditional gas treatment applications.
- Municipal boiler feedwater conditioning:Water treatment specifications in industrial corridors create steady offtake channels with lower certification barriers than oilfield-grade product tiers.
- Dual carbon goals in China:MEE tightening of sulfur emission protocols accelerates amine system replacement cycles at state-owned refinery complexes.
Industry Challenges
- Amine synthesis expertise gap:Retiring workforce cohorts in tertiary alkanolamine production limit knowledge transfer for reductive amination process control.
- REACH registration timeline compression:Extended dossier preparation periods for new market entrants delay commercial launch windows.
- Legacy monoethanolamine infrastructure:Existing scrubbing system designs require costly reconfiguration to accommodate N-MDEA's distinct viscosity and thermal degradation profiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global N-MDEA Market |
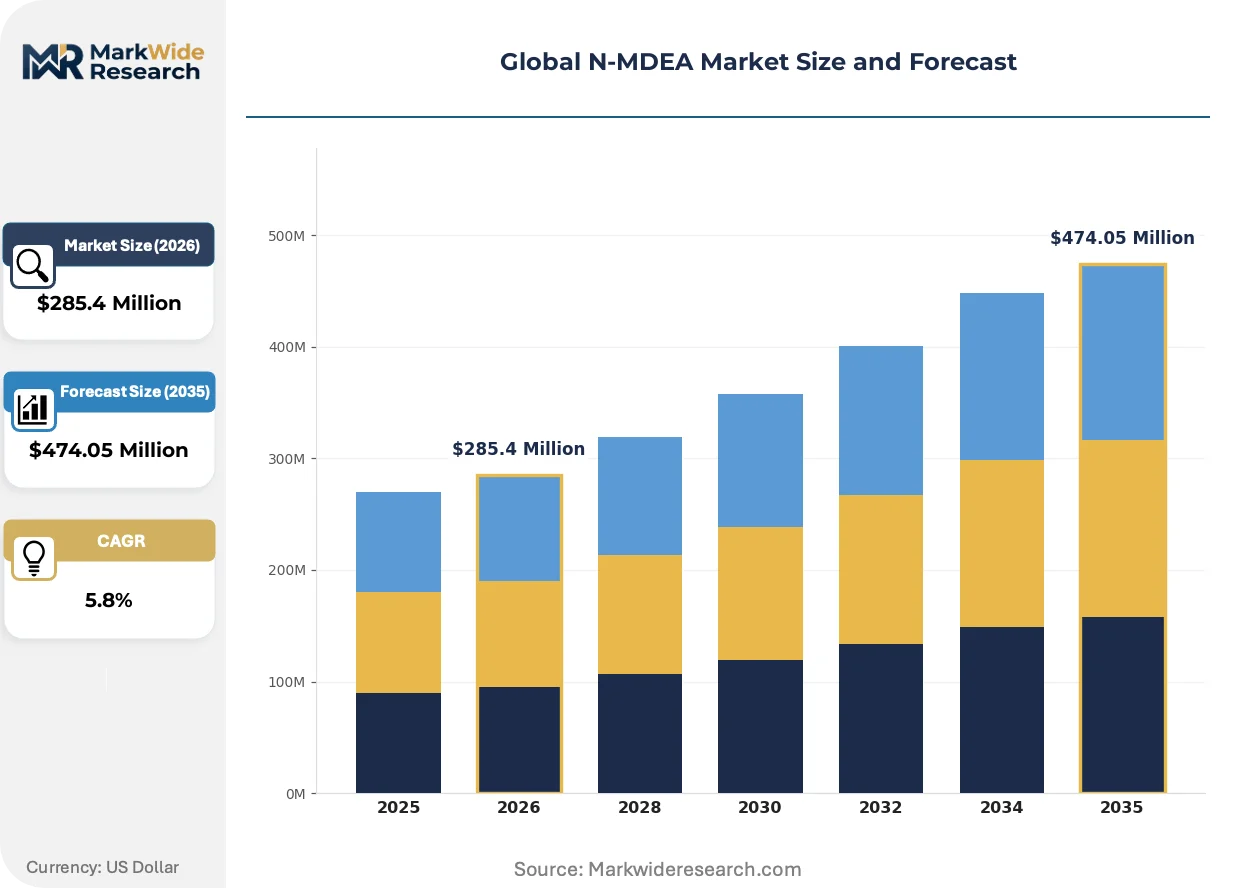
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $474.05 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
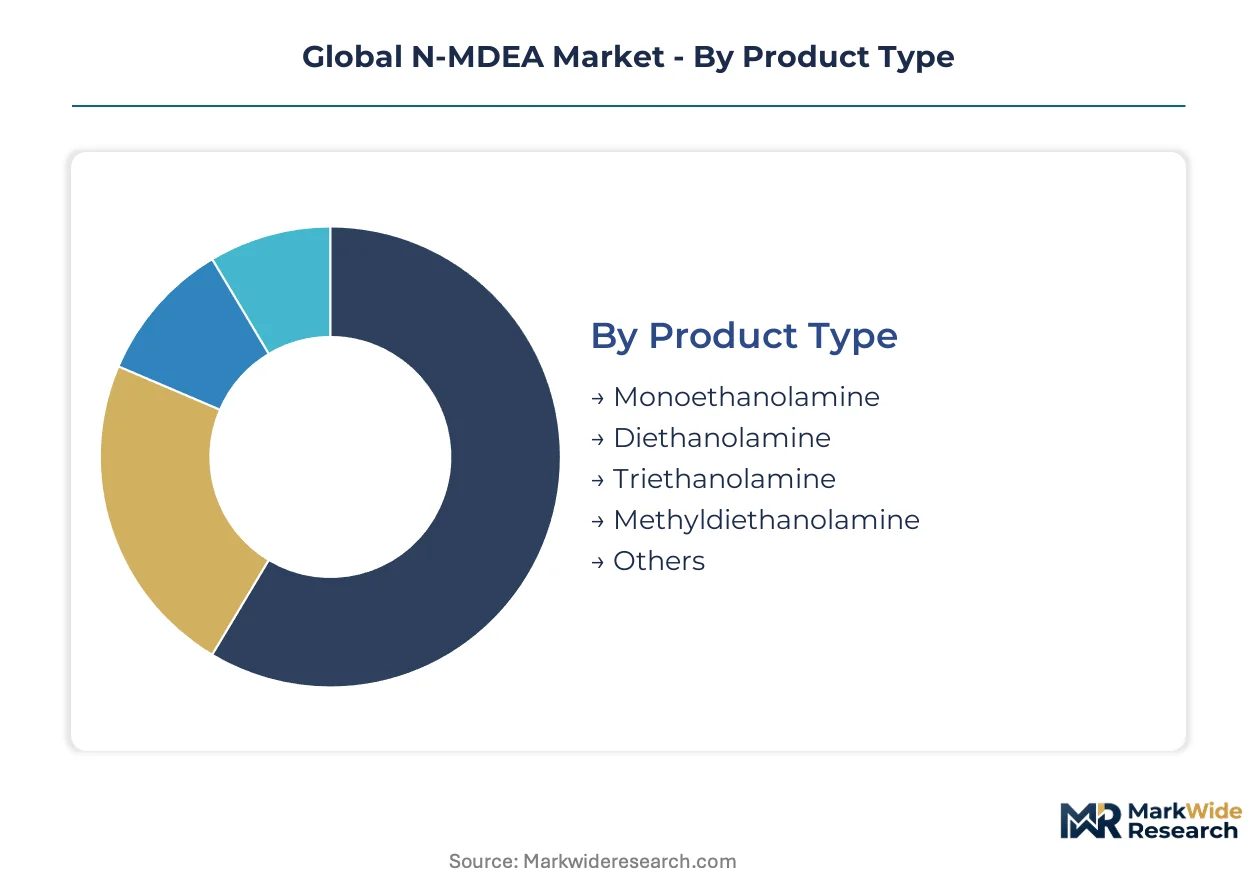
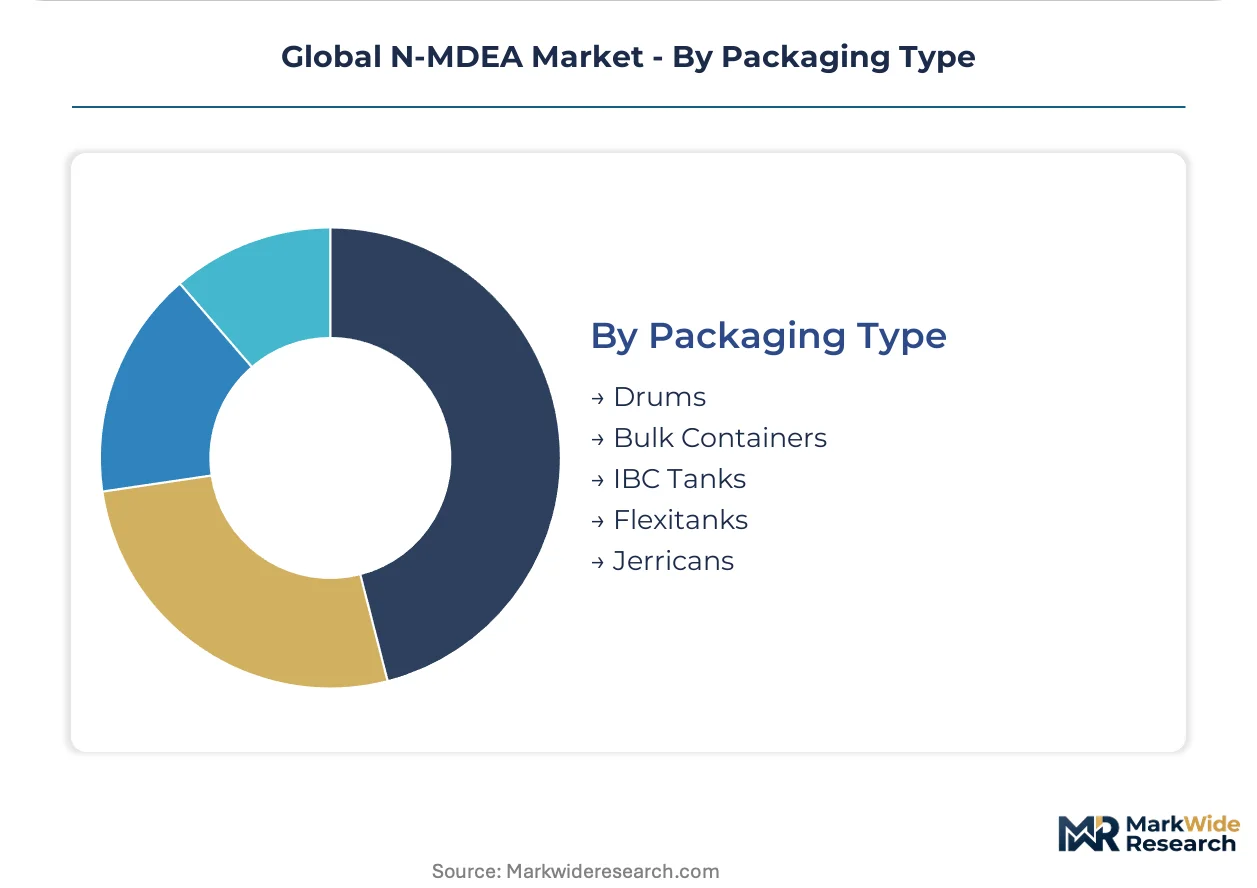
| Segmentation | Product Type: Monoethanolamine, Diethanolamine, Triethanolamine, Methyldiethanolamine, Others Application: Gas Sweetening, Chemical Intermediates, Personal Care Products, Water Treatment, Agri Chemicals End User Industry: Oil & Gas Refineries, Agrochemical Manufacturers, Pharmaceutical Producers, Water Treatment Facilities, Cosmetic Manufacturers Packaging Type: Drums, Bulk Containers, IBC Tanks, Flexitanks, Jerricans |
| Companies Covered | Huntsman Corporation, SABIC, BASF SE, Amines & Plasticizers Ltd., Mitsubishi Chemical Corporation, Eastman Chemical Company, INEOS Group Holdings S.A., Nippon Nyukazai Co., Ltd., Dow Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global N-MDEA Market Shifts & Advancements
Formulation science and regulatory chemistry are converging to redefine solvent performance benchmarks, with selective absorption efficiency and environmental persistence emerging as the decisive technical battlegrounds.
Hybrid amine blends incorporating N-MDEA with sterically hindered amines are displacing conventional monoethanolamine formulations in high-pressure natural gas treatment applications. US Gulf Coast processors operating supercritical CO2 injection projects have accelerated adoption curves by eighteen to twenty-four months. This displacement is compressing margin pools for single-component solvent suppliers while rewarding formulation houses with proprietary blending IP.
REACH registration requirements and the EU F-Gas Regulation are constraining import pathways for non-ECHA-registered Asian producers. European integrated energy majors now mandate full substance registration documentation for amine procurement tenders. German and Dutch gas treatment operators have responded by consolidating supplier panels around Ludwigshafen and Antwerp-based producers with verified Verbund integration.
Specification-driven procurement now dominates amine sourcing for international LNG projects, with buyers unbundling technical service contracts from product supply agreements. Engineering procurement contractors in Qatar and Australia are replacing bundled solvent-plus-service models with discrete chemical tenders and separate process optimization consultancies. This unbundling is most visible in Australian LNG pretreatment expansions, where operators now engage third-party amine specialists independent of incumbent solvent suppliers.
Global N-MDEA Market Segmentation
N-MDEA market segmentation reflects divergent purity specifications across regulatory jurisdictions, with EPA, REACH, and MEE protocols creating distinct product tiers that reshape procurement patterns for gas treatment versus chemical synthesis applications.
Product Type:
Regulatory differentiation separates pharmaceutical-grade specifications from industrial bulk supply, with purity thresholds determining market access rather than functional performance alone.
- Methyldiethanolamine:Tertiary alkanolamine manufactured via reductive amination of diethanolamine with formaldehyde and hydrogen. US Gulf Coast gas processors and Permian Basin treatment facilities specify this grade for selective hydrogen sulfide absorption in high-pressure sour gas streams.
- Monoethanolamine:Primary alkanolamine with higher regeneration energy requirements. Legacy carbon capture installations at coal-fired power stations in the United States continue specifying this chemistry, though N-MDEA blends are displacing conventional formulations in new scrubbing architectures.
- Diethanolamine:Secondary amine intermediate serving as feedstock for N-MDEA synthesis and direct use in refinery gas treating.
- Triethanolamine:Tertiary amine with emulsification properties, consumed primarily in concrete admixtures and metalworking fluids.
- Others:Sterically hindered amines and proprietary blends developed for hybrid solvent systems in supercritical CO2 injection projects.
Methyldiethanolamine handles the majority of throughput; chemical intermediates for surfactant synthesis are expanding most quickly on share.
Application:
Cost tier separation between oilfield-specification products and technical-grade alternatives determines margin architecture, with certification burden concentrated in upstream energy applications.
- Gas Sweetening:Acid gas removal systems in natural gas processing and LNG pretreatment trains. US export terminals and Qatari production facilities specify high-purity N-MDEA for irreversible hydrogen sulfide absorption duty.
- Chemical Intermediates:Feedstock for surfactant and emulsifier synthesis. Asian personal care formulators in South Korea and Japan are shifting toward milder tertiary alkanolamine chemistries for cosmetic applications.
- Personal Care Products:Direct incorporation into pH adjusters and conditioning agents for hair and skin formulations.
- Water Treatment:Boiler feedwater conditioning and pH control in municipal and industrial systems.
- Agri Chemicals:Intermediate for herbicide and pesticide synthesis with lower purity requirements than pharmaceutical applications.
Gas Sweetening commands the dominant value position; Chemical Intermediates for surfactant synthesis show the steepest expansion trajectory.
End User Industry:
Customer type fragmentation splits procurement between integrated energy majors with captive technical service capabilities and merchant buyers dependent on formulation houses.
- Oil & Gas Refineries:Sour gas processing infrastructure requiring continuous amine circulation. Gulf Coast upgrades and Permian Basin expansions sustain concentrated offtake for high-purity formulations.
- Cosmetic Manufacturers:Personal care formulators in South Korea and Japan specifying technical-grade N-MDEA for mild surfactant emulsifiers.
- Agrochemical Manufacturers:Pesticide and herbicide producers with volume-driven procurement and reduced certification requirements.
- Pharmaceutical Producers:cGMP-compliant manufacturers requiring documented supply chain traceability.
- Water Treatment Facilities:Municipal and industrial boiler operators with steady but thinner margin demand.
Oil & Gas Refineries anchor volume absorption; Cosmetic Manufacturers are gaining share fastest as Asian formulators shift emulsifier preferences.
Packaging Type:
Supply concentration in bulk logistics favors integrated producers with dedicated terminal infrastructure, while specialty packaging commands premium positioning for remote or small-volume deliveries.
- Bulk Containers:Rail and vessel shipments for refinery and gas processing facilities with direct unloading infrastructure.
- IBC Tanks:Intermediate bulk packaging for chemical intermediate producers and water treatment operations.
- Drums:Standard 200-liter containers for agrochemical and pharmaceutical manufacturers with moderate volume requirements.
- Flexitanks:Single-use liquid bulk containers for international chemical trade and remote site deliveries.
- Jerricans:Small-volume packaging for laboratory and specialty chemical distributors.
Bulk Containers handle the majority of throughput; IBC Tanks are climbing the fastest on share as mid-scale chemical intermediate demand expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. US gas processors favor high-purity formulations for Permian Basin sour gas treatment. Asian buyers concentrate procurement on technical-grade material for surfactant intermediates. European purchasers prioritize REACH-registered supply chains above unit cost optimization.
United States
Permian Basin gas processing expansions and Gulf Coast refinery upgrades drive concentrated offtake for oilfield-specification N-MDEA. EPA Subpart OOOOa mandates elevate demand for high-efficiency amine circulation systems with leak detection protocols. Houston and Beaumont industrial corridors host integrated ethylene oxide and amine manufacturing complexes serving domestic gas treatment infrastructure.
China
State-owned refinery complexes accelerate amine system replacement cycles under MEE sulfur emission tightening. Dual carbon goals compress procurement timelines for carbon capture solvent specifications. Yangtze River Delta chemical clusters concentrate technical-grade N-MDEA output for both domestic gas sweetening and surfactant intermediate export.
Germany
Ludwigshafen Verbund complexes anchor European supply through backward integration into ethylene oxide feedstock. REACH registration requirements and EU F-Gas Regulation constrain import pathways for non-ECHA-registered producers. Antwerp-Rotterdam chemical corridor operators consolidate supplier panels around verified Verbund-integrated producers.
Japan
Yokkaichi site reactor trains dominate technical-grade output for Asian gas treatment markets. METI energy transition roadmaps prioritize amine-based carbon capture retrofits at coal and gas-fired power stations. Osaka-Kobe industrial zone personal care formulators shift procurement toward milder tertiary alkanolamine emulsifier chemistries.
Saudi Arabia
Integrated energy majors mandate full substance registration documentation for amine procurement tenders in LNG pretreatment expansions. SABIC petrochemical complexes leverage captive ethylene oxide supply for regional N-MDEA formulation. Jubail Industrial City hosts gas treatment chemical clusters serving Gulf sour gas processing infrastructure.
Global N-MDEA Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive ethylene oxide supply separating margin sustainability from feedstock vulnerability. The structure rewards backward integration into ethylene oxide and penalizes merchant buyers during cracker turnaround cycles. Three archetypes dominate: integrated petrochemical majors with Verbund manufacturing, regional amine specialists with formulation IP, and Asian technical-grade producers serving surfactant intermediate demand. Capacity expansion and strategic partnerships constitute the dominant competitive moves, as producers seek to lock in terminal infrastructure and long-term offtake agreements.
Among integrated petrochemical majors, Huntsman Corporation and BASF SE exemplify the captive-feedstock archetype, with US Gulf Coast and Ludwigshafen Verbund positioning respectively. Mitsubishi Chemical Corporation occupies a specialist position in Asian technical-grade supply. These three anchors illustrate how geographic clustering around ethylene oxide production shapes competitive sustainability in amine manufacturing.
| Leading Market Players |
|---|
| Huntsman Corporation |
| SABIC |
| BASF SE |
| Amines & Plasticizers Ltd. |
| Mitsubishi Chemical Corporation |
| Eastman Chemical Company |
| INEOS Group Holdings S.A. |
| Nippon Nyukazai Co., Ltd. |
| Dow Chemical Company |
| Others |
Supply & Pricing Matrix
Hybrid amine formulations displacing conventional monoethanolamine in US Gulf Coast supercritical CO2 projects simultaneously concentrate supply geography around ethylene oxide-integrated producers and compress pricing premiums for single-component solvent tiers. This substitution dynamic rewards backward-integrated manufacturers with captive feedstock security while exposing merchant buyers to margin volatility during cracker turnaround cycles.
Pricing Analysis
Long-term offtake agreements dominate procurement for oilfield-grade N-MDEA, with Permian Basin gas processors and Gulf Coast refiners locking in multi-year supply contracts to secure high-purity formulations against ethylene oxide feedstock volatility. Price differentiation separates REACH-registered European supply from technical-grade Asian material, with certification burden and documented supply chain traceability commanding substantial premiums over merchant spot alternatives. Cost compression in standard-grade tiers intensifies as Yangtze River Delta producers expand technical-grade output for surfactant intermediate demand. Merchant buyers without captive ethylene oxide supply exhibit highest price sensitivity, while integrated energy majors with dedicated terminal infrastructure prioritize security of supply over unit cost optimization.
Supply Chain Analysis
The United States and Germany anchor N-MDEA manufacturing through Huntsman's Gulf Coast complexes and BASF's Ludwigshafen Verbund operations, with China concentrating technical-grade output in Yangtze River Delta chemical clusters. Feedstock dependencies center on ethylene oxide from steam cracker operations, formaldehyde supply from methanol oxidation units, and hydrogen from reformer or electrolysis sources. Single-source vulnerability concentrates around ethylene oxide supply interruptions during planned and unplanned cracker maintenance cycles. Distribution runs through dedicated rail and vessel terminals for bulk refinery deliveries, with IBC tank and drum packaging serving mid-scale chemical intermediate and personal care formulator channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
N-MDEA procurement is shifting toward unbundled chemical tenders and separate process optimization consultancies, creating platform-economics dynamics where formulation IP and technical service capabilities decouple from commodity solvent supply. This interoperability inflection rewards suppliers with standalone optimization expertise alongside manufacturing scale.
For Market Incumbents: Compound captive ethylene oxide advantages through capacity additions in US Gulf Coast and Antwerp-Rotterdam corridors, while investing in REACH dossier maintenance and ECHA registration extensions to defend against Asian technical-grade entrants. Threats from hybrid amine blend displacement require accelerated R&D in sterically hindered amine co-formulations. Certification investment in carbon capture solvent specifications represents the critical lever for next-generation scrubbing system adoption. For New Entrants and Emerging Players: Differentiate on formulation science capabilities for carbon capture retrofits at coal and gas-fired power stations, where post-combustion capture solvent specifications remain unsettled and incumbent relationships are less entrenched. Municipal boiler feedwater conditioning offers the most penetrable segment, with lower certification barriers and steady offtake from industrial corridor operators. A technical service-led go-to-market approach, pairing solvent supply with amine system optimization consulting, bypasses incumbent bundled-service advantages. For Investors and Strategic Acquirers: The market sits at a substitution-phase inflection that favors backward-integrated producers with verified Verbund positioning over merchant formulation houses. Long-term viability across the analysis window hinges on ethylene oxide supply security and regulatory registration depth rather than scale alone. Acquisition targets should demonstrate captive feedstock integration or proprietary blending IP for hybrid solvent systems. The signal to watch is carbon capture retrofit announcement velocity at power stations, which will determine whether N-MDEA formulations achieve meaningful displacement of monoethanolamine in post-combustion capture architectures.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethylene Oxide | Captive feedstock security insulates margin stability during cracker turnaround cycles at US Gulf Coast and Ludwigshafen complexes. |
| REACH Dossier Extension and ECHA Maintenance | Registration depth preserves European market access against tightening F-Gas Regulation constraints on non-compliant Asian exporters. |
| Hybrid Amine Formulation R&D | Sterically hindered amine blending IP addresses supercritical CO2 injection project specifications displacing conventional solvent architectures. |
| Carbon Capture Solvent Certification | Post-combustion capture validation at coal and gas-fired power stations opens pathway for N-MDEA displacement of monoethanolamine. |
| Technical Service Capability Buildout | Standalone process optimization consulting captures value from unbundled procurement models in Australian and Qatari LNG pretreatment expansions. |
Research Methodology
Initial hypotheses were tested against primary input from plant managers at integrated petrochemical complexes, procurement leads at downstream gas processing facilities, distribution channel partners in Antwerp-Rotterdam and Houston-Beaumont corridors, and technical R&D directors specializing in amine synthesis. These perspectives were refined against secondary validation from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings from listed chemical producers, and EPA regulatory filings under Subpart OOOOa. Bottom-up capacity and demand estimates were triangulated with top-down market sizing derived from ethylene oxide consumption patterns and gas processing infrastructure expansion announcements.
Variance decomposition across the projection horizon isolates drivers by grade tier, end-use industry, packaging format, and regional production hub. Segmentation dimensions modeled include pharmaceutical-grade versus industrial bulk specifications, gas sweetening versus chemical intermediate applications, and oilfield versus personal care end-user industries. CAGRs were derived from elasticity-adjusted demand projections tied to Permian Basin gas processing capacity additions, MEE sulfur protocol implementation timelines, and carbon capture retrofit announcement flows. Industry-specific forecast inputs incorporate ethylene cracker operating rates, REACH registration renewal schedules, and LNG pretreatment train commissioning calendars.
Material uncertainties — ethylene oxide supply disruptions, REACH dossier evaluation delays, and carbon capture solvent specification shifts — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory enforcement consistency and feedstock price stability that could require revision if MEE protocols accelerate or EPA mandates expand beyond leak detection protocols. Recalibration cycles align with material shifts in carbon capture policy, ethylene cracker maintenance schedules, and hybrid amine blend adoption curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Caustic Calcined Magnesia Market
Industrial Chemicals
Continuous Reactors Market
Industrial Chemicals
Anhydrous Ammonia Storage Tank Market
Industrial Chemicals
Blown Oils Market
Industrial Chemicals
Calcium Fluoride Market
Industrial Chemicals
Diesel Exhaust Fluid Market
Industrial Chemicals
Acetylene Market
Industrial Chemicals
Trimethylolpropane (TMP) Market
Industrial Chemicals
VOC Concentrator Market
Industrial Chemicals
Global Chemical Mechanical Planarization Market
Industrial Chemicals
Heat Treating Market
Industrial Chemicals
North America Paper Machine Oil Market
Industrial Chemicals
Electronic Grade Trimethylindium Market
Industrial Chemicals
Global Isocyanate Market
Industrial Chemicals
Screw Separators Market
Industrial Chemicals
Fluorine-Based Plasma Surface Treatment Machine for Leather Market