
 Technical Enzymes Market | 2026-2036
Technical Enzymes Market Size, Share, and Industry Trends Forecast 2026-2036
Technical Enzymes Market Outlook
Enzyme-as-a-service subscription models for bioprocess optimization is pivoting how industrial buyers procure catalytic capacity rather than owning enzyme inventories outright. Novozymes leverages its platform-based fermentation services to lock in multi-year biofuel contracts. BASF anchors European detergent enzyme supply through backward integration into proprietary strain development. DuPont competes on thermostability IP, sustaining premium positioning in textile desizing applications.
Technical enzymes are protein-based biocatalysts, typically operating at 30-70°C and pH 4-9, that accelerate specific biochemical reactions without being consumed in the process. Manufacturers produce them via submerged fermentation of genetically modified microbial hosts, followed by downstream recovery and formulation into liquid or granulated preparations for industrial deployment. Proteases dominate detergent and leather processing volumes, while cellulases capture expanding margin pools in second-generation biofuel pre-treatment. Lipases show the fastest trajectory within food processing, where cold-active variants reduce energy inputs for dairy fat modification. Amylases remain mature in starch liquefaction, with pricing power concentrated among suppliers controlling high-temperature alpha-amylase strains.
EPA biofuel mandates under the Renewable Fuel Standard and REACH registration requirements in Europe shape product development roadmaps by enforcing lifecycle toxicity assessments for industrial enzyme formulations. China's SAMR enforces GB standards for food-grade enzyme safety, creating separate compliance tracks for export versus domestic supply. FDA GRAS notifications govern pharmaceutical and food processing applications in the United States, adding documentation burdens that favor established suppliers with regulatory affairs infrastructure. Stakeholders must monitor how carbon border adjustments and biomanufacturing subsidies redraw competitive boundaries between regional supply bases.
Market Dynamics
Enzyme-as-a-service subscription models are compressing capital deployment cycles for industrial buyers, shifting procurement from inventory ownership to contracted catalytic capacity with embedded bioprocess optimization.
Growth Catalysts
- EPA Renewable Fuel Standard mandates:Cellulosic ethanol quotas in the United States accelerate enzyme consumption for agricultural residue pre-treatment, locking in multi-year offtake agreements with fermentation service providers.
- Textile processing belt expansion:China's Zhejiang and Jiangsu provinces concentrate desizing and bio-polishing operations, sustaining cellulase and pectinase demand from integrated dyeing-finishing clusters.
- Cold-active lipase engineering:Dairy fat modification applications in Scandinavia and New Zealand adopt low-temperature biocatalysts to reduce energy inputs in butterfat fractionation.
Market Restraints
- Fermentation feedstock volatility:Corn steep liquor and molasses price swings destabilize production economics for submerged culture enzyme manufacturers.
- Strain development concentration:Proprietary high-temperature alpha-amylase IP remains captive to three dominant suppliers, constraining pricing negotiation leverage for downstream formulators.
- REACH registration timelines:ECHA's extended substance evaluation periods for industrial-grade enzyme formulations delay new product commercialization across European detergent and leather processing channels.
Strategic Opportunities
- India's pharmaceutical enzyme clusters:Hyderabad and Bengaluru contract manufacturing organizations seek localized protease and lipase supply to reduce import dependency for active pharmaceutical ingredient synthesis.
- EU Green Deal biomanufacturing subsidies:Horizon Europe funding streams for cell factory engineering create capital access for second-generation biocatalyst startups targeting bio-based chemical intermediates.
- Digital bioprocess twin integration:Convergence of AI-driven fermentation modeling with real-time metabolite sensing enables predictive enzyme dosing optimization for biofuel pre-treatment facilities.
Industry Challenges
- Regulatory affairs capability scarcity:Multi-jurisdictional GRAS notification, REACH dossier preparation, and SAMR registration expertise concentrates among established suppliers, raising barriers for mid-scale entrants.
- Downstream recovery capex intensity:Ultrafiltration membrane trains and spray-drying infrastructure for granulated formulations require substantial capital deployment before revenue generation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Technical Enzymes Market |
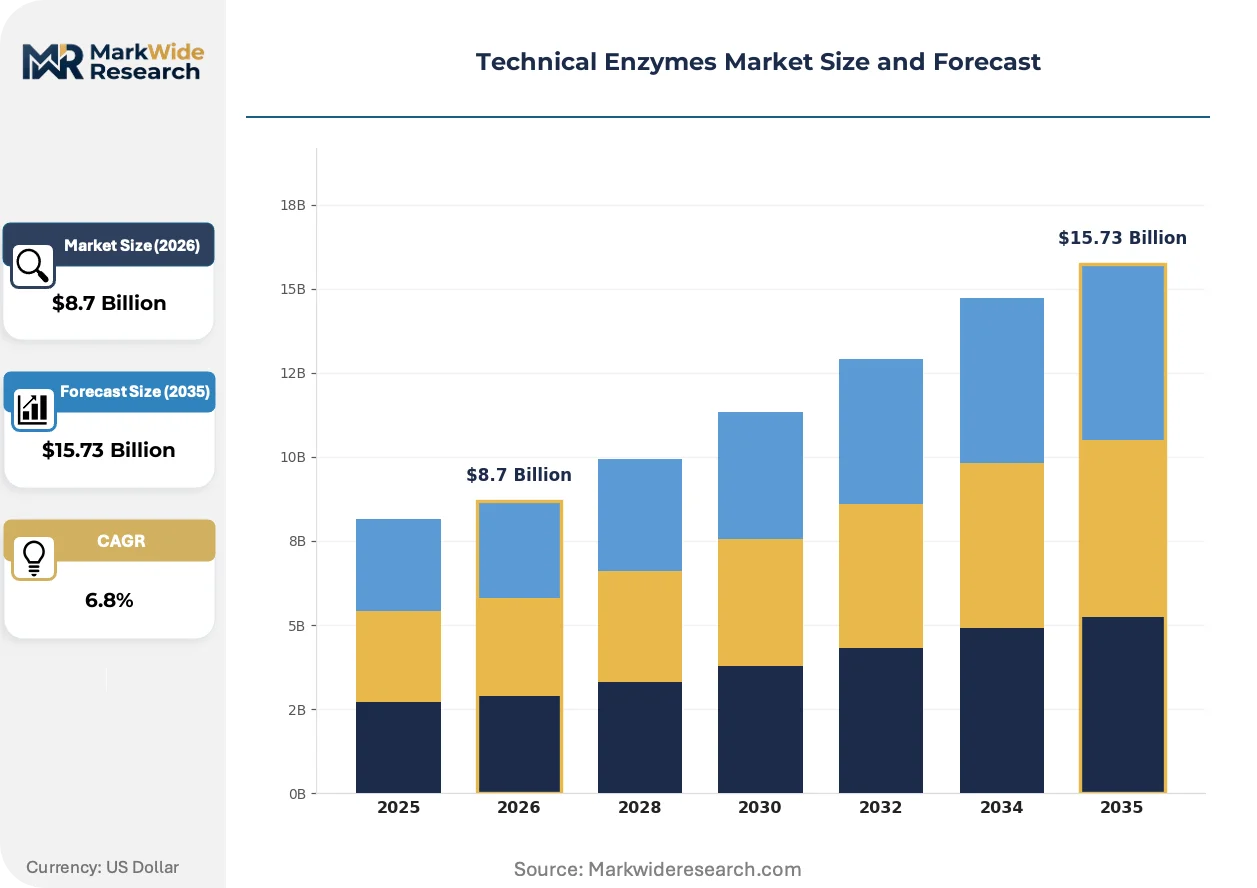
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Proteases, Amylases, Lipases, Cellulases Application: Textile, Biofuels, Detergents, Food Processing End User: Manufacturing, Agriculture, Pharmaceuticals, Food & Beverage Distribution Channel: Online, Direct Sales, Distributors, Retail |
| Companies Covered | BASF, DuPont, Associated British Foods, Novozymes, DSM, Dyadic International, Advanced Enzyme Technologies, Maps Enzymes, EPYGEN LABS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Technical Enzymes Market Strategic Shifts
Continuous processing architectures and in-line quality analytics are displacing batch fermentation paradigms, compressing cycle times while tightening purity specifications for industrial-grade enzyme outputs.
Automated high-throughput screening platforms coupled with machine learning-directed protein engineering is automating strain optimization for thermostability and pH tolerance. Specialty chemical manufacturers in Germany and Japan deploy these systems to compress development timelines for detergent protease variants. The technology is automating what previously required iterative wet-lab evolution, collapsing the competitive moat of legacy strain libraries.
REACH authorization requirements for Substances of Very High Concern extend to residual protein impurities in technical enzyme formulations, forcing reformulation investments across European supply chains. Industrial cleaning product manufacturers face downstream liability exposure from legacy surfactant-enzyme combinations. The regulation drives substitution toward granular encapsulation technologies that isolate enzyme activity from incompatible chemical matrices.
Subscription-based catalytic capacity contracts displace spot purchasing for biofuel pre-treatment operations, embedding technical service and dosing optimization into multi-year agreements. Brazilian cellulosic ethanol producers pioneered this structure, and US Midwest refineries now replicate the model. The shift transfers operational risk from plant operators to enzyme suppliers while locking in volume commitments that justify dedicated fermentation capacity investments.
Technical Enzymes Market Segmentation
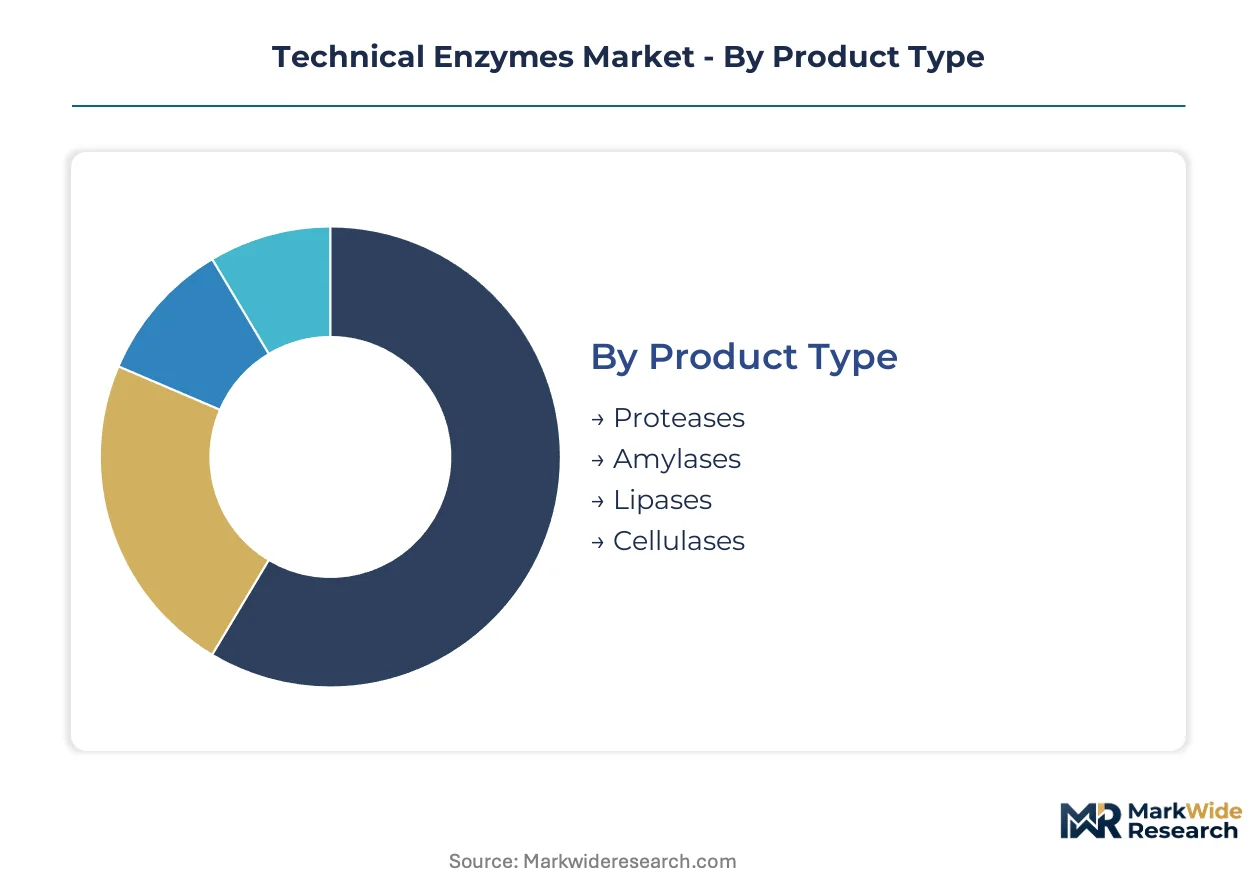
Technical enzyme procurement patterns diverge sharply across industrial verticals, with biofuel processors contracting multi-year catalytic capacity while textile formulators negotiate spot pricing for desizing formulations. Segmentation clarity exposes where margin pools concentrate and which application vectors justify dedicated strain development investments.
Product Type:
Supply concentration for proprietary high-performance strains tilts competitive leverage toward developers controlling thermostable alpha-amylase and cold-active lipase IP libraries.
- Proteases:Serine and metallo-protease formulations hydrolyze peptide bonds at alkaline pH, enabling stain removal in detergent matrices and hair removal in leather bating. Detergent manufacturers in Germany and the United States lock in multi-year supply agreements for subtilisin variants with granulated encapsulation to prevent dust exposure.
- Cellulases:Endoglucanase-exoglucanase cocktails depolymerize crystalline cellulose into fermentable sugars, requiring strain optimization for tolerance to pretreatment inhibitors. Brazilian biofuel producers in São Paulo state and US Midwest refineries drive demand for cellulase complexes with enhanced beta-glucosidase activity to complete saccharification.
- Amylases:High-temperature alpha-amylase variants liquefy starch slurries at 95°C, reducing viscosity before saccharification. Corn wet millers in Iowa and Illinois specify thermostable formulations for continuous liquefaction trains.
- Lipases:Cold-active variants from Antarctic microbial sources catalyze butterfat interesterification at 20°C, slashing energy inputs. Scandinavian dairy processors adopt these biocatalysts for spreadable fat fractionation.
Today's leader: Proteases. Tomorrow's challenger: Cellulases.
Application:
Cost tier stratification separates premium-priced pharmaceutical-grade formulations from commodity industrial grades, with biofuel applications occupying a mid-tier value band.
- Biofuels:Cellulosic ethanol pre-treatment consumes enzyme loads of 10-30 mg protein per gram cellulose, with process economics hinging on enzyme cost per liter ethanol produced. Brazilian producers in Minas Gerais and Goiás states optimize enzyme dosing through real-time cellulose conversion monitoring.
- Textile:Bio-polishing and desizing operations in China's Zhejiang province specify acid cellulases for cotton surface fiber removal, with pectinase cocktails for scouring bast fibers. Water recycling mandates tighten purity specifications for effluent-compatible formulations.
- Detergents:Protease-amylase-lipase ternary systems target protein, starch, and lipid soils across wash temperatures. European formulators navigate REACH authorization requirements for residual protein content.
- Food Processing:GRAS-notified amylases and lipases modify starch viscosity and fat crystallinity. US bakery manufacturers specify fungal alpha-amylase for anti-staling applications.
Biofuels command the steepest volume expansion trajectory. Textile applications defend the densest margin concentration.
End User:
Customer type fragmentation separates contract manufacturing organizations seeking localized supply from integrated multinationals with captive fermentation infrastructure.
- Manufacturing:Textile dyeing-finishing clusters and leather tanneries procure bulk liquid enzymes in IBC totes, with just-in-time delivery contracts tied to production schedules. India's Tamil Nadu textile belt sources acid cellulases from domestic toll manufacturers.
- Food & Beverage:Dairy and brewing operations specify food-grade enzyme preparations with kosher and halal certification. New Zealand butterfat processors import cold-active lipases for premium spread production.
- Pharmaceuticals:Active pharmaceutical ingredient synthesis employs immobilized lipases for stereoselective acylation. Hyderabad contract manufacturers seek localized protease supply to reduce import lead times.
- Agriculture:Silage inoculants and feed enzymes improve fiber digestibility in ruminant nutrition. US dairy operations in Wisconsin specify fibrolytic enzyme additives for corn silage.
Manufacturing anchors current procurement volumes. Pharmaceuticals represent the fastest-climbing value tier.
Distribution Channel:
Geography of demand clusters determines channel economics, with concentrated manufacturing corridors favoring direct technical service relationships over distributor markups.
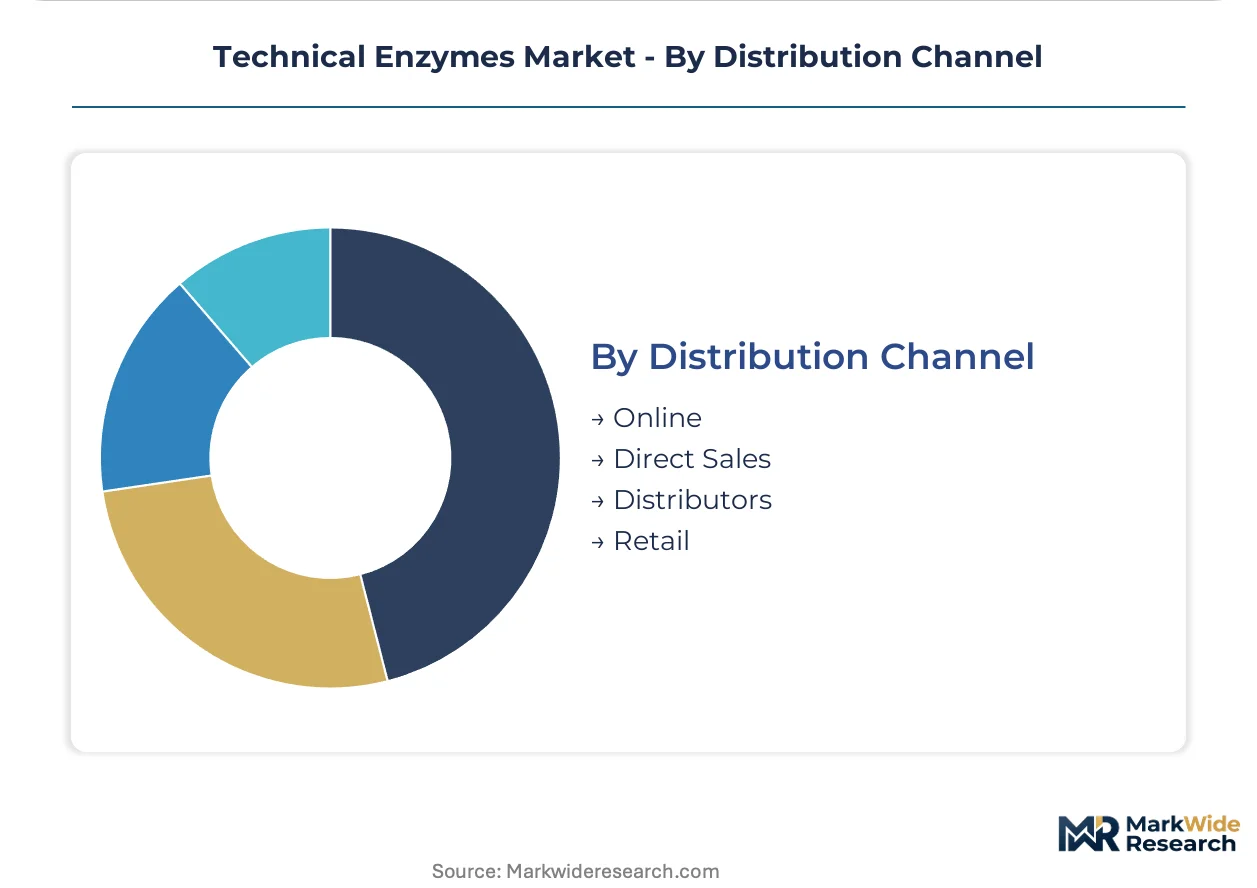
- Direct Sales:Fermentation service providers embed technical staff at biofuel pre-treatment facilities for real-time dosing optimization. Novozymes and DuPont deploy dedicated account teams at Brazilian and US Midwest refineries.
- Distributors:Regional chemical distributors stock liquid and granulated formulations for fragmented textile and detergent formulators. India's Gujarat and Maharashtra industrial corridors rely on distributor networks for small-batch procurement.
- Online:Research-grade enzyme preparations and assay kits flow through specialized biochemical supply portals. Academic and startup synthetic biology labs procure engineered variants through digital catalogs.
- Retail:Consumer-facing laundry additives and dietary supplements reach mass market through supermarket and pharmacy chains. European retail channels emphasize eco-label certification for enzyme-containing products.
Direct sales capture the highest-value contracts. Distributor channels penetrate the broadest geographic footprint.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil and the United States diverge in enzyme deployment intensity, with Brazilian biofuel processors running higher cellulase loadings per liter while US refineries optimize for thermostability under colder operational conditions.
United States
Cellulosic ethanol mandates under the EPA Renewable Fuel Standard lock in multi-year enzyme offtake agreements across Iowa and Illinois corn wet milling corridors. FDA GRAS notification requirements govern food-grade amylase and lipase deployments in bakery and dairy processing. Midwest refineries in Minnesota and Nebraska specify high-temperature alpha-amylase variants for continuous liquefaction trains.
Brazil
São Paulo state biofuel producers pioneered enzyme-as-a-service subscription contracts, transferring operational risk to fermentation service providers. ANVISA enforces residual protein thresholds for industrial enzyme formulations entering food-contact applications. Minas Gerais and Goiás states optimize cellulase dosing through real-time cellulose conversion monitoring at cellulosic ethanol pre-treatment facilities.
China
Zhejiang and Jiangsu provinces concentrate textile desizing and bio-polishing operations, sustaining acid cellulase and pectinase demand from integrated dyeing-finishing clusters. SAMR enforces evolving GB standards for food-grade enzyme safety, creating separate compliance tracks for export versus domestic supply. Shanghai and Guangzhou pharmaceutical manufacturers import immobilized lipases for active pharmaceutical ingredient synthesis.
Germany
Detergent manufacturers in North Rhine-Westphalia lock in multi-year protease supply agreements with granulated encapsulation specifications. ECHA REACH registration timelines extend substance evaluation periods for industrial-grade enzyme formulations, delaying new product commercialization. Bavaria-based specialty chemical producers deploy automated high-throughput screening platforms for detergent protease variant development.
India
Hyderabad and Bengaluru contract manufacturing organizations seek localized protease and lipase supply to reduce import dependency for pharmaceutical synthesis. FSSAI and BIS enforce dual certification requirements for food-grade and industrial-grade enzyme formulations. Tamil Nadu textile belts source acid cellulases from domestic toll manufacturers for cotton surface fiber removal operations.
Technical Enzymes Market Competitive Environment
Top-tier vendors anchor multi-year fermentation service contracts, while mid-scale formulators compete on regional toll manufacturing and distributor channel penetration. The vendor base stratifies between integrated strain developers with captive IP libraries and downstream formulators reliant on licensed biocatalysts. Three archetypes dominate: platform-based fermentation service providers, backward-integrated strain developers, and regional toll manufacturers. Competitive moves concentrate on strategic partnerships for bioprocess optimization and capacity expansion into high-growth manufacturing corridors.
Within the platform-based service tier, Novozymes and DuPont occupy positions embedding technical staff at biofuel pre-treatment facilities for real-time dosing optimization. BASF anchors the European detergent enzyme supply vector through proprietary strain development. DSM represents the specialty nutrition and pharmaceutical enzyme archetype with dual food-grade and industrial-grade formulation capabilities.
| Leading Market Players |
|---|
| BASF |
| DuPont |
| Associated British Foods |
| Novozymes |
| DSM |
| Dyadic International |
| Advanced Enzyme Technologies |
| Maps Enzymes |
| EPYGEN LABS |
| Others |
Value Chain & Pricing Dynamics
Fermentation strain engineers concentrated in Denmark and the Netherlands command wage premiums that compress margin spreads between economy-grade commodity enzymes and premium thermostable formulations. This labor-cost differential propagates through pricing tiers as contract manufacturers in India and Brazil compete on toll-processing rates while European developers capture value through proprietary IP licensing.
Pricing Analysis
Capacity additions in Brazil are reshaping price floors for cellulase complexes used in cellulosic ethanol pre-treatment. Three-tier pricing structure across premium, standard, and economy levels separates REACH-registered formulations from industrial-grade spot supply and unregistered toll-manufactured volumes. Cost compression in economy tiers is intensifying because Brazilian producers optimize enzyme dosing through real-time monitoring, reducing per-liter consumption rates. Biofuel processors show highest price sensitivity due to enzyme cost per ethanol liter economics, while pharmaceutical formulators accept premium positioning for immobilized lipase stereoselectivity.
Supply Chain Analysis
GB standards compliance and REACH registration gating concentrate supply qualification burdens on established strain developers with regulatory affairs infrastructure. Manufacturing gravity centers on China, Denmark, and the United States, with downstream formulation tethered to corn wet milling corridors in Iowa and Illinois and textile processing belts in Zhejiang. Raw material dependencies include corn steep liquor, molasses feedstocks, and ultrafiltration membrane trains for downstream recovery. Single-source vulnerability runs through proprietary high-temperature alpha-amylase IP held by three dominant suppliers. Distribution runs through direct technical service relationships for biofuel contracts and regional chemical distributors for fragmented textile formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Technical Enzymes Market reads as a late-cycle quality story as biofuel processors shift procurement toward subscription-based catalytic capacity with embedded bioprocess optimization rather than spot purchasing of commodity formulations.
For Market Incumbents: Anticipate margin compression from automated high-throughput screening platforms that collapse development timelines for detergent protease variants. Lock in multi-year fermentation service contracts with Brazilian and US Midwest biofuel refineries to secure dedicated capacity utilization. Deepen backward integration into proprietary strain development to defend pricing power in thermostable alpha-amylase supply.
For New Entrants and Emerging Players: The premium-economy price-point gap in pharmaceutical-grade lipase supply creates white-space opportunity for Hyderabad and Bengaluru contract manufacturing organizations seeking localized sourcing. Target India's Tamil Nadu textile belt with acid cellulase toll manufacturing to reduce import lead times for cotton bio-polishing operations. Pursue EU Green Deal biomanufacturing subsidies through Horizon Europe funding streams for cell factory engineering capabilities.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional toll manufacturers with distributor channel penetration but lacking proprietary strain IP. Five-to-ten year viability hinges on regulatory affairs capability scarcity concentrating among established suppliers. Watch for carbon border adjustment implementation as inflection indicator that redraws competitive boundaries between regional supply bases.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Strain Development | BASF anchors European detergent supply through captive proprietary biocatalyst IP libraries. |
| Long-term Supply Agreement | Novozymes locks in multi-year biofuel contracts via platform-based fermentation service embedding. |
| Geographic Expansion | DuPont deploys dedicated account teams at Brazilian and US Midwest refineries for dosing optimization. |
| Green Manufacturing Transition | Cold-active lipase engineering reduces energy inputs for Scandinavian dairy fat fractionation applications. |
| Joint Venture | Indian pharmaceutical clusters partner for localized protease supply to reduce API synthesis import dependency. |
Study Parameters
Direct dialogue with fermentation service directors, textile procurement leads at Zhejiang dyeing-finishing clusters, biofuel plant operators in São Paulo state, and regulatory affairs managers at enzyme formulators grounded qualitative findings. Secondary validation drew from EPA Renewable Fuel Standard filings, ECHA REACH registration databases, SAMR GB standards disclosures, and customs trade data on industrial enzyme imports. Bottom-up volume estimates from application-level consumption rates triangulated against top-down market sizing from supplier capacity disclosures.
Segmentation-level outputs across product type, application vertical, end-user category, and distribution channel fed into growth rate derivation over the projection horizon. Modeled dimensions included thermostability performance tier, pH tolerance range, and regional regulatory compliance cluster. CAGRs were computed from year-over-year expansion rates applied to base-period consumption volumes, with cellulosic ethanol mandate trajectories and textile belt capacity additions as primary forecast inputs.
Caveats apply where ECHA substance evaluation timeline extensions, SAMR GB standard revisions, or carbon border adjustment implementations could materially shift the outlook. Forecasts reflect stated policy assumptions and technology adoption curves. A model refresh is warranted upon material change in EPA biofuel mandate stringency or REACH authorization scope expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Diphenyl Oxide (DPO) Market
Industrial Chemicals
Deoxidant Market
Industrial Chemicals
Cooling Tower Chemicals Market
Industrial Chemicals
Plant-Based Hydraulic Oil Market
Industrial Chemicals
Global Industrial Anti Scaling Chemical Market
Industrial Chemicals
Global Specialty Oils Market
Industrial Chemicals
Perchloroethylene Market
Industrial Chemicals
Global Industrial Separators Market
Industrial Chemicals
Biobased Degreaser Market
Industrial Chemicals
Non-Corrosive Fluxes Market
Industrial Chemicals
Global Microencapsulated Pesticides Market
Industrial Chemicals
Volatile Organic Compounds (VOC) Concentrator Market
Industrial Chemicals
Heat Treating Market
Industrial Chemicals
Calcium Fluoride Market
Industrial Chemicals
Dynamite Market
Industrial Chemicals
Gypsum Market