
 Military Wearable Medical Device Market | 2026-2036
Military Wearable Medical Device Market Size, Share, and Industry Trends Forecast 2026-2036
Military Wearable Medical Device Market Intelligence
Defense-oriented leasing and performance-based contracting is tilting procurement toward firms with scalable manufacturing and regulatory track records. Medtronic leverages its FDA-cleared cardiac monitoring portfolio to anchor military telemedicine contracts. Garmin sustains competitive positioning through ruggedized GPS-integrated wearables purpose-built for austere environments. Bittium specializes in encrypted short-range communications that harden wireless sensor networks against electronic warfare threats.
Military wearable medical devices encompass body-worn biosensors, transdermal monitors, and networked telemetry systems engineered to ISO 81001-5-1 electromagnetic resilience standards, continuously tracking vital signs, metabolic indicators, and environmental exposure in operational theaters. Pulse oximetry and ECG monitoring segments lead current procurement volumes due to their established role in triage and aeromedical evacuation protocols. Bluetooth Technology and Wireless Sensors compete for platform integration, with infrared-based non-contact modalities gaining traction for mass-casualty screening scenarios where skin contact risks contamination or time constraints prohibit individual device donning.
FDA 510(k) premarket notification and the EU Medical Device Regulation shape transatlantic product entry requirements, while NATO Standardization Agreement 4559 governs interoperability of soldier-worn health data networks. The US Defense Health Agency and Army Medical Research and Development Command coordinate validation protocols that compress fielding timelines for expeditionary platforms. Stakeholders must monitor evolving electromagnetic spectrum allocation rules and counter-signature requirements that determine whether commercial fitness-derived architectures survive hardening for contested logistics environments.
Market Dynamics
The convergence of NATO Standardization Agreement 4559 interoperability mandates with FDA 510(k) clearance compression is restructuring procurement toward dual-use platforms that bridge commercial health tech with hardened military specifications.
Growth Catalysts
- Expeditionary Medical Modernization:US Army Futures Command and SOCOM coordinate next-generation soldier health programs that embed continuous physiological monitoring into standard kit configurations.
- ISO 81001-5-1 Electromagnetic Resilience Certification:Hardening standards for body-worn biosensors against electronic warfare threats accelerate replacement cycles for legacy unhardened devices.
- Short-Range Encrypted Telemetry:Bittium's communications architecture demonstrates that wireless sensor networks hardened against jamming and interception satisfy contested logistics requirements.
Market Restraints
- Miniaturized Biosensor Fabrication Costs:Semiconductor foundry capacity constraints and specialized MEMS packaging inflate unit economics for transdermal monitors below deployable price points.
- Single-Source Wireless Module Dependencies:Bluetooth and proprietary low-power radio chipsets concentrate in East Asian fabrication facilities, exposing supply chains to geopolitical disruption.
- EU Medical Device Regulation Transition Friction:MDR recertification timelines for existing CE-marked devices delay transatlantic product entry and compress available vendor pools.
Strategic Opportunities
- Mass-Casualty Screening Modalities:Infrared-based non-contact vital sign monitoring addresses contamination risks and time constraints in chemical, biological, radiological, and nuclear response scenarios.
- Performance-Based Contracting Structures:Defense-oriented leasing models tilt procurement toward firms with scalable manufacturing and established regulatory track records for multi-year platform sustainment.
- Aeromedical Evacuation Telemetry Integration:Pulse oximetry and ECG monitoring segments extend into en-route care networks linking point-of-injury sensors with theater hospital systems.
Industry Challenges
- Cross-Domain Certification Expertise Scarcity:Engineers fluent in both FDA medical device pathways and MIL-STD-810G environmental testing command premium compensation and extend development timelines.
- Legacy Health Data Network Integration:NATO member states operate incompatible soldier-worn health data architectures that fragment procurement and complicate joint force interoperability.
- Electromagnetic Spectrum Allocation Uncertainty:Evolving military frequency assignments and civilian 5G encroachment threaten operational availability of unlicensed bands for wireless sensor networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Military Wearable Medical Device Market |
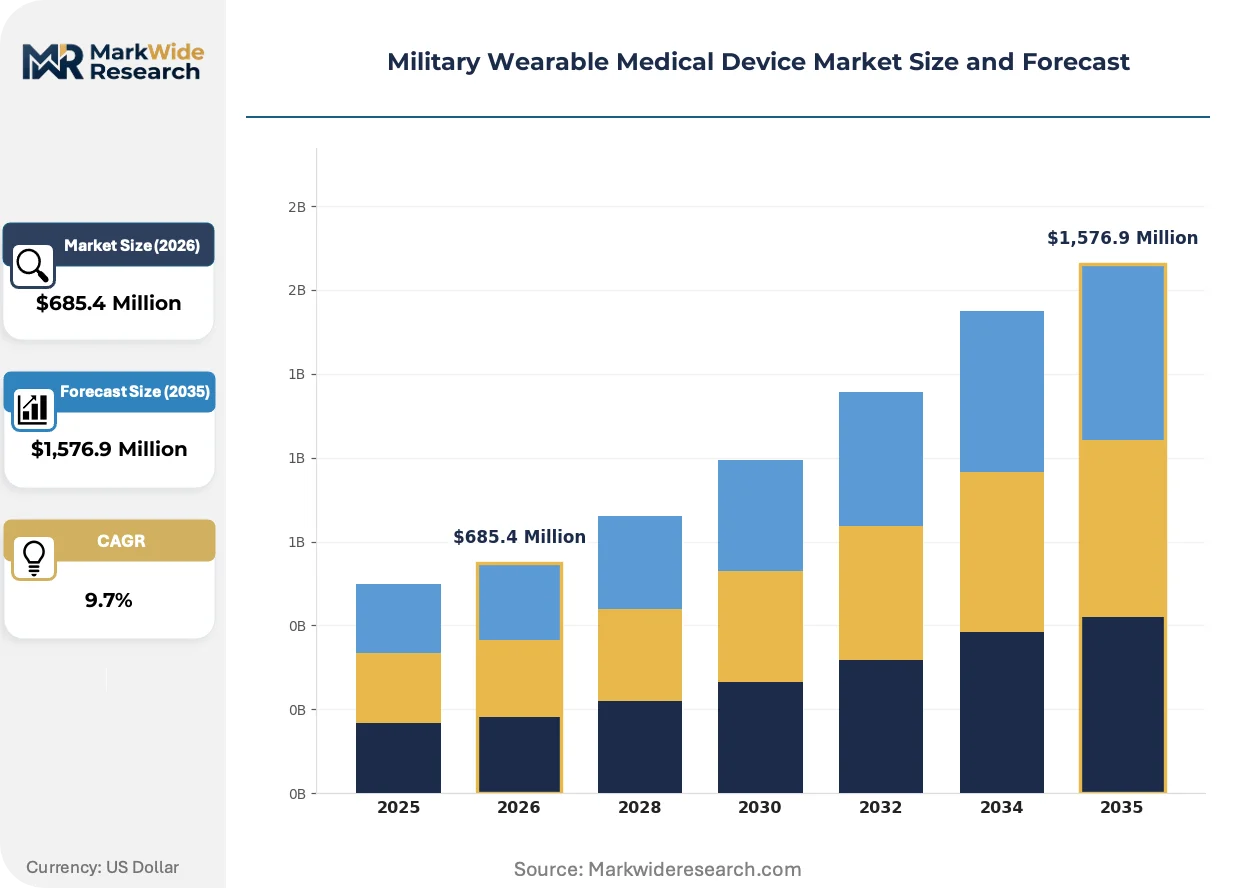
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,576.9 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heart Rate Monitors, Blood Glucose Monitors, Pulse Oximeters, ECG Monitors Technology: Wireless Sensors, Bluetooth Technology, Infrared Sensors, NFC Devices Application: Health Monitoring, Performance Tracking, Emergency Response, Telemedicine End User: Active Duty Personnel, Veterans, Military Support Staff, Medical Personnel |
| Companies Covered | Fitbit, NeuroMetrix, Garmin, Honeywell, Oura, Bittium, Zephyr Technology Corporation, Medtronic, Polar Electro, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Military Wearable Medical Device Market Strategic Shifts & Innovations
Continuous physiological monitoring architectures are migrating from reactive triage tools toward predictive health analytics platforms that anticipate combat effectiveness degradation before symptomatic presentation.
Non-contact infrared thermography paired with computer-vision pulse detection is virtualizing the physical patient-device interface, eliminating skin contact requirements that delay mass-casualty triage in contaminated environments. Special operations medical teams in NATO expeditionary units are piloting these systems for rapid throughput screening. The technology is virtualizing traditional wired monitoring infrastructure by collapsing multiple vital sign capture modalities into single optical sensor packages.
FDA's Digital Health Center of Excellence has streamlined 510(k) premarket notification pathways for software-as-a-medical-device components embedded in expeditionary platforms. This regulatory compression enables commercial health tech firms to pivot dual-use architectures toward military procurement channels with reduced validation overhead. Cardiac monitoring and metabolic indicator segments are responding fastest, with multiple vendors pursuing parallel civilian-military clearance strategies.
Defense health agencies are unbundling after-sales service from hardware procurement, awarding separate sustainment contracts to third-party logistics providers with theater repair capabilities. This disintermediation of original equipment manufacturer service networks disrupts traditional vendor lock-in models and compresses switching costs between platform generations. United States Army Medical Research and Development Command validation protocols exhibit the most aggressive unbundling, with field repair certifications now transferable across qualified contractors.
Military Wearable Medical Device Market Segmentation
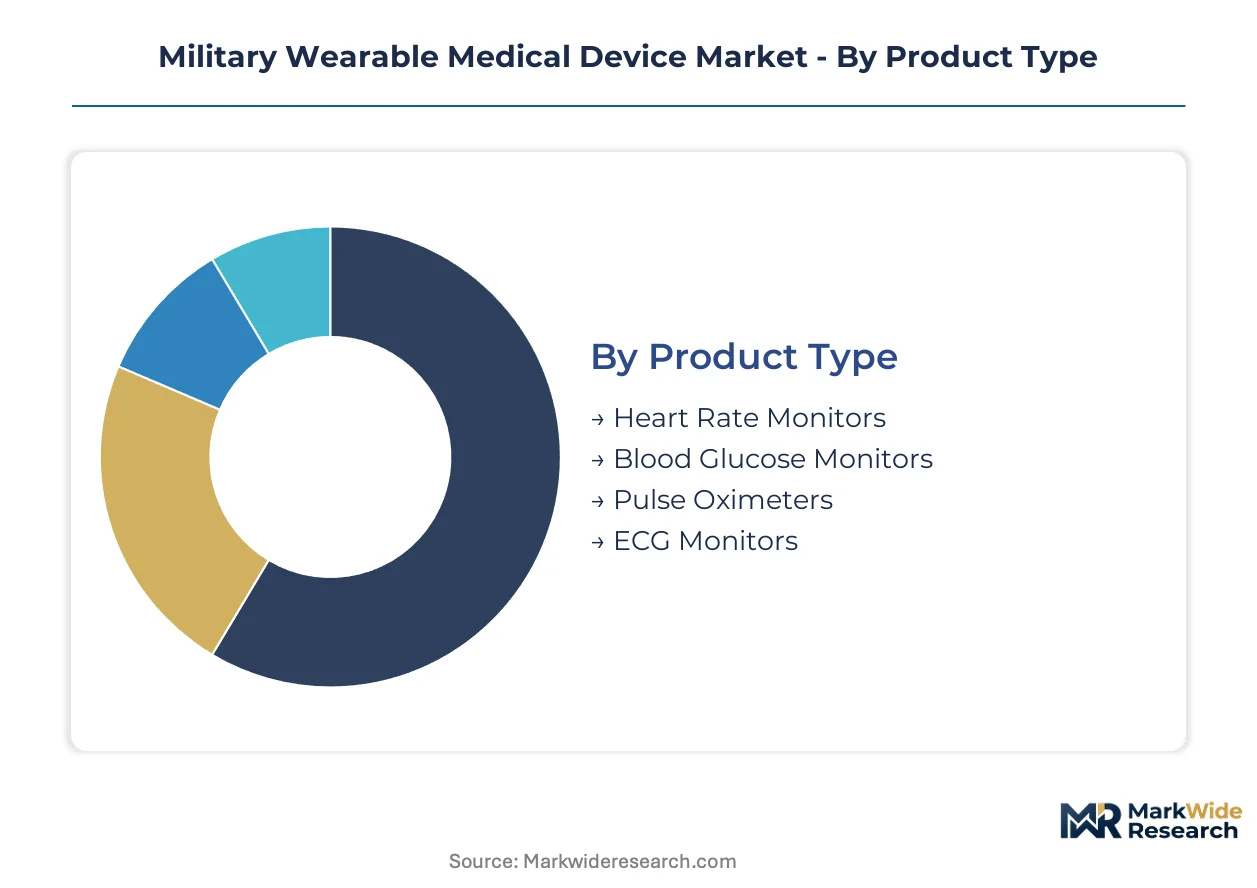
Military wearable medical devices fragment across physiological domains, connectivity protocols, and operational use cases. Procurement patterns diverge sharply between continuous monitoring platforms for forward-deployed units and episodic screening tools for rear-echelon medical facilities.
Product Type:
Cardiopulmonary monitoring dominates current kit configurations across NATO expeditionary forces.
- Pulse Oximeters:Transmissive and reflectance SpO2 sensors engineered to ISO 81001-5-1 electromagnetic resilience standards. US Army aeromedical evacuation protocols mandate fingertip and earlobe variants for en-route patient monitoring from point-of-injury to theater hospitals.
- ECG Monitors:Multi-lead dry-electrode arrays with embedded arrhythmia detection algorithms. Special operations forces in United States and United Kingdom drive demand for Holter-equivalent continuous cardiac surveillance during extended missions.
- Heart Rate Monitors:Photoplethysmography-based wrist and chest strap configurations for fitness-derived performance baselining.
- Blood Glucose Monitors:Continuous interstitial glucose sensors with factory-calibrated algorithms reducing fingerstick dependencies in sustained operations.
Established volume favors pulse oximeters; emerging adoption favors ECG monitors with predictive analytics integration.
Technology:
Platform selection hinges on contested logistics requirements and electronic warfare threat profiles.
- Wireless Sensors:Proprietary low-power radio architectures operating in allocated military spectrum bands. Bittium's encrypted short-range telemetry demonstrates hardened network resilience against jamming in NATO joint exercises.
- Bluetooth Technology:Bluetooth Low Energy 5.3 modules with frequency-hopping spread spectrum for unlicensed band reliability. Garmin integrates these into ruggedized GPS-wearable platforms for austere environment durability.
- Infrared Sensors:Non-contact thermography and computer-vision pulse detection eliminating skin contact requirements. Mass-casualty screening in chemical, biological, radiological, and nuclear response scenarios drives pilot programs.
- NFC Devices:Near-field pairing and patient identification tags for triage tag synchronization with electronic health records.
Bluetooth Technology captures widest installed base; infrared sensors gain share fastest in special operations medical modernization programs.
Application:
Use-case migration shifts from reactive triage toward predictive combat effectiveness analytics.
- Health Monitoring:Continuous vital sign surveillance with automated threshold alerting for commanders. FDA 510(k) clearance compression accelerates fielding of expeditionary physiological monitoring platforms.
- Telemedicine:Real-time data streaming from soldier-worn sensors to remote trauma specialists. US Defense Health Agency validation protocols prioritize low-latency telemetry for contested bandwidth environments.
- Performance Tracking:Baseline fitness metrics and load carriage strain quantification for training optimization.
- Emergency Response:Rapid triage categorization and medical asset allocation in mass-casualty incidents.
Health Monitoring anchors procurement budgets; telemedicine exhibits steepest expansion trajectory as NATO Standardization Agreement 4559 interoperability mandates mature.
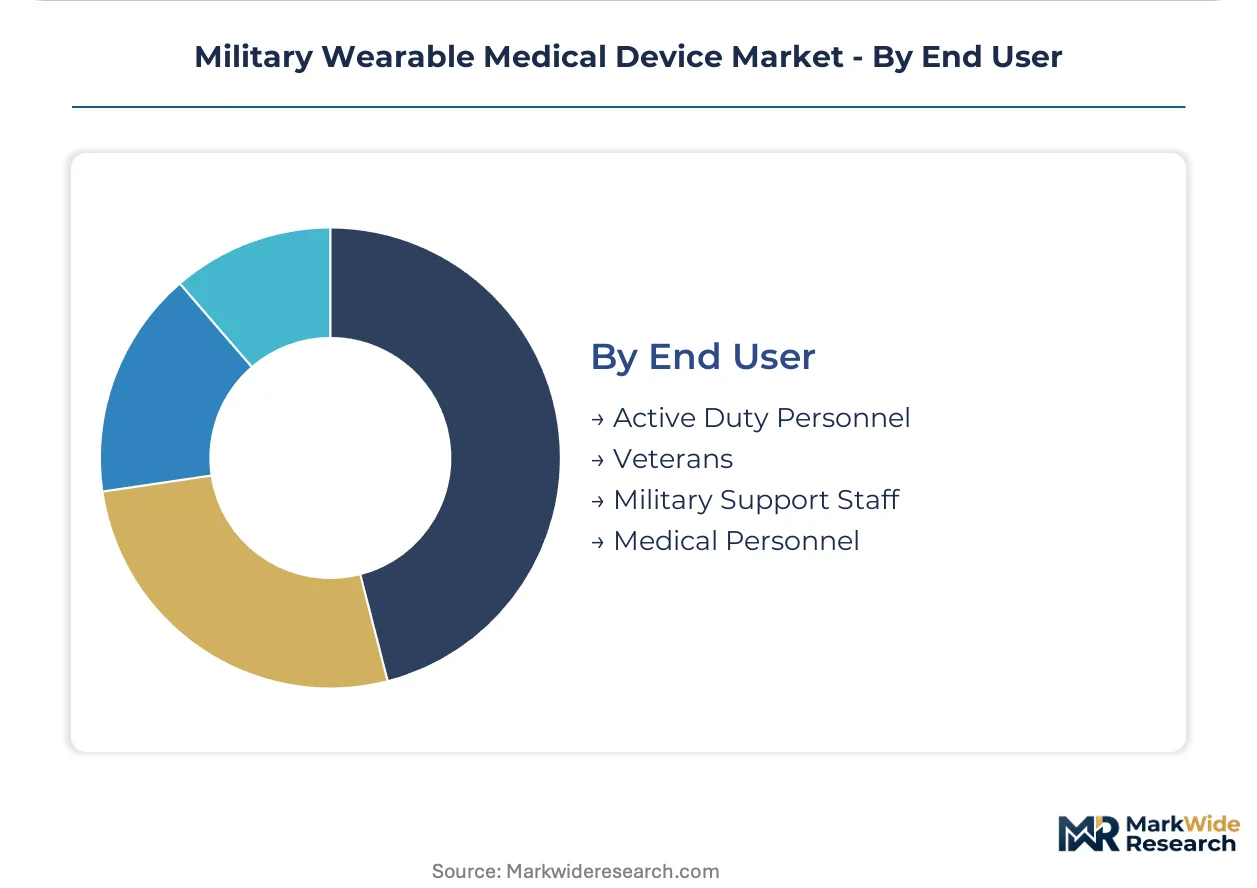
End User:
User categories reflect divergent physiological baselines and operational exposure profiles.
- Active Duty Personnel:Forward-deployed combat arms units requiring hardened, continuous monitoring under MIL-STD-810G environmental stress. Army Futures Command and SOCOM coordinate next-generation soldier health programs embedding biosensors into standard kit.
- Medical Personnel:Combat medics and physician assistants using wearable telemetry for patient handoff documentation and treatment prioritization. Theater hospital systems integrate these feeds into electronic health record architectures.
- Veterans:Post-service remote patient monitoring for service-connected disability management and chronic condition surveillance.
- Military Support Staff:Logistics and administrative personnel in garrison environments with commercial-grade fitness tracking requirements.
Active duty personnel concentrate platform development investment; medical personnel drive interoperability specification refinement for joint force operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows of hardened biosensor components originate predominantly from East Asian semiconductor foundries, while finished military-grade wearables concentrate in North American and European defense procurement channels. Import dependencies for specialized MEMS packaging create vulnerability in transatlantic supply security.
United States
Army Futures Command and SOCOM coordinate next-generation soldier health programs embedding continuous physiological monitoring into standard kit configurations. FDA 510(k) premarket notification pathways compress fielding timelines for expeditionary platforms. Boston and San Diego anchor dual-use medical technology clusters where commercial cardiac monitoring firms pivot toward military telemedicine contracts.
Germany
Bundeswehr medical modernization programs drive procurement of ISO 81001-5-1 certified electromagnetic resilience systems for electronic warfare environments. EU Medical Device Regulation recertification timelines delay transatlantic product entry for legacy CE-marked devices. Munich and Stuttgart concentrate precision sensor fabrication capabilities serving NATO Standardization Agreement 4559 interoperability mandates.
United Kingdom
Special operations forces demand Holter-equivalent continuous cardiac surveillance during extended missions in contested logistics environments. Ministry of Defence validation protocols prioritize low-latency telemetry for bandwidth-constrained operational theaters. Bristol and Cambridge host encrypted communications specialists hardening wireless sensor networks against jamming threats.
Israel
Defense export controls shape dual-use medical device trade flows toward allied NATO procurement channels. National pharmaceutical regulator frameworks accommodate accelerated military clearance pathways for expeditionary physiological monitoring platforms. Tel Aviv and Haifa anchor battlefield telemedicine innovation clusters integrating predictive health analytics into combat effectiveness systems.
South Korea
MFDS certification requirements intersect with military frequency allocation rules for wireless sensor network deployment. Domestic semiconductor fabrication capacity supports specialized MEMS packaging for transdermal glucose monitors in sustained operations. Seoul and Suwon concentrate biosensor foundry capabilities reducing single-source dependencies on East Asian supply chains.
Military Wearable Medical Device Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream supplying hardened telemetry modules and encrypted communications architectures. Market structure exhibits moderate consolidation around firms possessing dual FDA-military clearance expertise and scalable expeditionary manufacturing. Three archetypes dominate: diversified medical technology conglomerates with cardiac monitoring portfolios, ruggedized GPS-telemetry specialists, and encrypted short-range communications pure-plays. Competitive dynamics center on strategic partnerships bridging commercial health tech with MIL-STD-810G environmental testing capabilities, plus vertical integration into specialized MEMS fabrication to secure supply continuity.
Among North American platform integrators, Medtronic and Garmin occupy positions anchoring the premium system tier, while Bittium exemplifies the encrypted communications specialization archetype. Medtronic represents the diversified medical technology model leveraging FDA-cleared cardiac monitoring portfolios for military telemedicine contract capture. Garmin sits within the ruggedized wearable segment integrating GPS-telemetry for austere environment durability. Bittium anchors European encrypted short-range communications capabilities hardening wireless sensor networks against electronic warfare threats in NATO joint exercises.
| Leading Market Players |
|---|
| Fitbit |
| NeuroMetrix |
| Garmin |
| Honeywell |
| Oura |
| Bittium |
| Zephyr Technology Corporation |
| Medtronic |
| Polar Electro |
| Others |
Cost & Logistics Intelligence
Semiconductor foundry undercapacity in East Asian fabrication nodes is compressing supplier margins while amplifying pricing power for firms with captive MEMS packaging capabilities. Military procurement officers face extended lead times for ISO 81001-5-1 certified transdermal monitors as capacity constraints ripple through specialized biosensor supply chains.
Pricing Analysis
Defense procurement agencies anchor three-tier pricing structure across premium, standard, and economy levels differentiated by electromagnetic resilience certification grade and after-sales service bundling. Price differentiation hinges on FDA 510(k) clearance status and MIL-STD-810G environmental testing completeness. Cost compression in standard-tier unhardened commercial derivatives is intensifying because defense health agencies are unbundling sustainment contracts from hardware procurement. Special operations units demonstrate least price sensitivity due to mission-critical reliability requirements, while garrison support staff procurement exhibits highest elasticity.
Supply Chain Analysis
US export controls on advanced semiconductor manufacturing equipment and EU dual-use technology restrictions are fragmenting transdermal biosensor component flows. Geographic supply concentration centers on Taiwan for Bluetooth Low Energy chipsets, South Korea for specialized MEMS glucose sensor packaging, and Germany for precision ECG electrode arrays. Raw material dependencies draw from gallium arsenide substrates, medical-grade silicone membranes, and rare-earth magnet materials for miniaturized pulse oximetry. Single-source vulnerability in East Asian foundry capacity represents the dominant structural risk. Distribution runs through defense logistics agency prime vendors with theater repair certifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The intersection of FDA medical device pathways and MIL-STD-810G environmental testing expertise represents a contracting talent pool that constrains platform development velocity. Firms possessing both regulatory fluencies command premium positioning in military telemedicine contract competitions.
For Market Incumbents: Harden supply chain resilience through backward integration into specialized MEMS fabrication or exclusive foundry partnerships in South Korea and Taiwan. Accelerate ISO 81001-5-1 certification pipelines for next-generation wireless sensor architectures before EU MDR recertification timelines compress vendor pools. Electronic warfare threat evolution and contested logistics requirements represent the primary displacement risks requiring proactive electromagnetic resilience investment. For New Entrants and Emerging Players: Mass-casualty screening modalities using infrared-based non-contact vital sign monitoring represent the most penetrable entry point given contamination-risk protocols and time-constrained triage requirements. NATO Standardization Agreement 4559 interoperability gaps in legacy soldier-worn health data networks create white-space for encrypted short-range telemetry specialists. Pursue software-as-a-medical-device FDA 510(k) pathways through the Digital Health Center of Excellence to compress validation overhead before hardware integration. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across electromagnetic resilience certification and miniaturized biosensor fabrication sub-segments as semiconductor foundry constraints persist. Long-term viability over the projection horizon favors acquisition targets with dual FDA-military clearance track records and scalable expeditionary manufacturing footprints. Monitor NATO joint exercise procurement awards and SOCOM technology demonstration contracts as early signals of platform adoption inflection.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Premarket Notification | Compresses fielding timelines for expeditionary physiological monitoring platforms through streamlined software-as-medical-device pathways. |
| ISO 81001-5-1 Electromagnetic Resilience Certification | Enables replacement cycles for legacy unhardened devices in electronic warfare threat environments across NATO forces. |
| Defense Logistics Agency Prime Vendor Partnership | Secures theater repair capabilities and sustainment contract access independent of original equipment manufacturer service networks. |
| Encrypted Short-Range Telemetry Development | Hardens wireless sensor networks against jamming and interception in contested logistics environments per Bittium architecture demonstrations. |
| EU MDR Recertification Pathway | Maintains transatlantic product entry access as legacy CE-marked device timelines compress available vendor pools. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with defense procurement officers, biomedical engineers at Army Medical Research and Development Command, GPO contracts managers, and special operations medical teams; and secondary validation against FDA 510(k) filings, NATO Standardization Agreement documentation, EU MDR recertification databases, and defense health agency budget justifications. Bottom-up unit economics modeling triangulated against top-down expenditure allocation patterns across Army Futures Command and SOCOM program lines.
Forecast inputs span product type segmentation across pulse oximetry, ECG monitoring, and continuous glucose sensing; technology platforms including Bluetooth Low Energy, proprietary low-power radio, and infrared non-contact modalities; and end-user categories from forward-deployed active duty personnel to theater hospital medical staff. CAGRs were derived from expenditure trajectory analysis across the projection horizon. Key inputs include electromagnetic spectrum allocation rule changes, semiconductor foundry capacity utilization rates, and FDA Digital Health Center of Excellence pathway expansion.
Practitioners should monitor NATO Standardization Agreement 4559 implementation maturity, East Asian foundry capacity expansion announcements, and EU MDR enforcement discretion for early signals of forecast revision. Material shifts in defense health agency unbundling policies or export control regime expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Europe Smart Bed Market
Medical Devices
Artificial Respirator Market
Medical Devices
Europe Intraocular Lens Market
Medical Devices
Hydrogen Inhalers Market
Medical Devices
Global Thrombectomy Devices Market
Medical Devices
Global Nerve Monitoring System Market
Medical Devices
India Artificial Organs and Bionics Market
Medical Devices
Global Active Implantable Medical Devices Market
Medical Devices
North America Pen Needles Market
Medical Devices
Australia Insulin Delivery Devices Market
Medical Devices
Clot Management Devices Market
Medical Devices
Global Medical Device Labeling Market
Medical Devices
Europe Smart Medical Devices Market
Medical Devices
Spinal Access Systems Market
Medical Devices
Endoluminal Device Systems Market
Medical Devices
Global Cardiac Reader System Market