
 Global Medical Device Labeling Market | 2026-2036
Global Medical Device Labeling Market Size, Share, and Industry Trends Forecast 2026-2036
Global Medical Device Labeling Market Intelligence
European specialty adhesive producers is expanding cleanroom-grade label substrate capacity to serve sterile device packaging requirements. Avery Dennison Corporation leverages its polymer science expertise to dominate high-performance pressure-sensitive adhesive portfolios for implantable devices. Huhtamaki Oyj anchors its position through advanced coating technologies that sustain autoclave and gamma sterilization compatibility.
Medical device labeling encompasses printed, embossed, or digitally marked substrates affixed to instruments, implants, and diagnostic equipment to convey identification, traceability, sterilization status, and regulatory compliance data; these labels must withstand chemical exposure, temperature extremes, and repeated handling without degradation of human-readable or machine-scannable information. Thermal transfer labels lead volume consumption due to their balance of durability and cost efficiency in high-throughput hospital environments. RFID labels represent the fastest-expanding technology segment as automated inventory management and operating room workflow optimization concentrate demand among integrated delivery networks seeking real-time device tracking.
FDA UDI rules, EU MDR Annex I general safety and performance requirements, and ISO 15223-1 symbol standards collectively dictate minimum label content, format, and permanence thresholds that manufacturers must satisfy for market access. Japan's PMDA and China's NMPA impose additional localization requirements that fragment compliance architectures for multinational device portfolios. Stakeholders must monitor harmonization gaps between regional traceability mandates to optimize label platform standardization versus market-specific customization investments.
Market Dynamics
Regulatory traceability mandates are compressing label upgrade cycles as manufacturers reconcile FDA UDI serialization with EU MDR symbol requirements across product portfolios. This dual-compliance pressure is forcing substrate and adhesive specification resets that ripple through sterile packaging supply chains.
Growth Catalysts
- EU MDR Annex I:General safety and performance requirements now mandate machine-readable label elements, accelerating demand for thermal transfer and laser-etched substrates in sterile barrier systems.
- Surgical robotics:Precision instrument tracking requirements in operating rooms are pulling RFID-enabled labels into high-value implantable device kits.
- Japan:PMDA localization rules for imported devices are creating dedicated label production capacity investments by foreign manufacturers seeking direct market access.
Market Restraints
- Specialty adhesive concentration:Cleanroom-grade pressure-sensitive adhesive supply concentrates among European polymer science specialists, exposing label converters to input bottlenecks.
- Gamma sterilization incompatibility:Standard thermal transfer ribbons degrade under cobalt-60 exposure, limiting substrate options for terminal sterilization workflows.
- China NMPA:In-country testing requirements for label adhesives create six-to-nine-month approval timelines that fragment global platform standardization efforts.
Strategic Opportunities
- India:CDSCO medical device rules expansion is opening import substitution opportunities for domestic label converters with sterilization-compatible coating capabilities.
- Blockchain-UDI convergence:Distributed ledger integration with unique device identifiers offers immutable chain-of-custody records for high-risk implantable traceability.
- Direct-to-hospital digital printing:On-demand label production at integrated delivery network distribution centers reduces SKU proliferation and obsolescence risk.
Industry Challenges
- Polymer science talent scarcity:Formulation chemists with sterile packaging adhesion expertise command premium compensation, constraining mid-tier converter expansion.
- ISO 15223-1 harmonization gaps:Symbol interpretation disputes between notified bodies create certification iteration cycles that delay product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Medical Device Labeling Market |
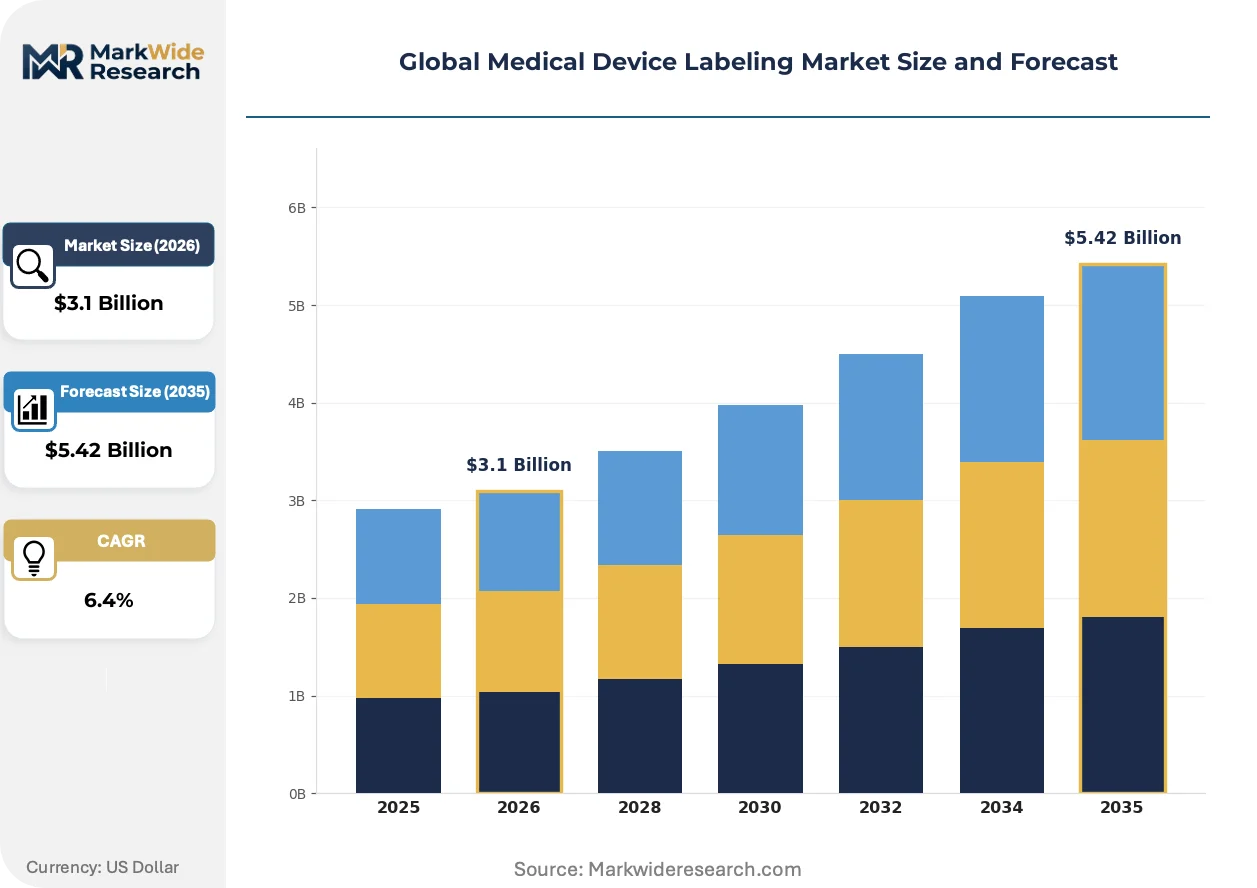
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $5.42 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
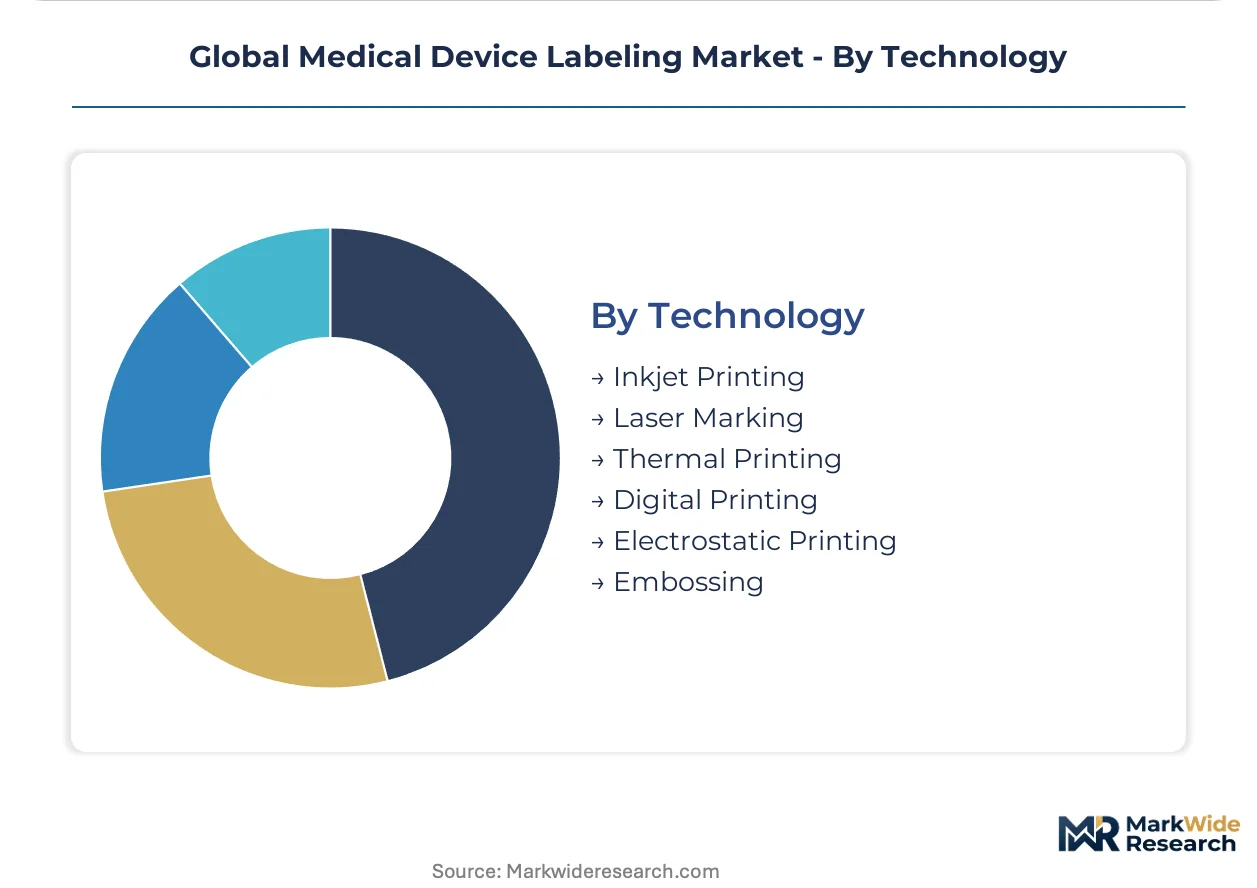
| Segmentation | Product Type: Barcode Labels, RFID Labels, Thermal Transfer Labels, Pressure-Sensitive Labels, Film Labels, Tag Labels Application: Diagnostic Equipment, Surgical Instruments, Implantable Devices, Monitoring Systems, Dental Devices, Rehabilitation Equipment End User: Hospitals, Ambulatory Surgical Centers, Diagnostic Laboratories, Home Healthcare Providers, Research Institutes, Elder Care Facilities Technology: Inkjet Printing, Laser Marking, Thermal Printing, Digital Printing, Electrostatic Printing, Embossing |
| Companies Covered | Avery Dennison Corporation, Huhtamaki Oyj, 3M, CCL Industries, UPM Raflatac, Amcor, Lintec Corporation, Schreiner Group, Mondi Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Medical Device Labeling Market Strategic Shifts & Innovations
Digital marking technologies are compressing the gap between regulatory data requirements and physical label real estate, enabling dynamic content without substrate format changes. This shift is redistributing value from conventional printing equipment toward software-defined compliance architectures.
RFID inlay integration with thermal transfer substrates is decentralizing inventory authentication from centralized warehouse scanners to point-of-use readers in operating suites. Ambulatory surgical centers and hospital sterile processing departments are adopting these hybrid labels fastest. The technology is decentralizing traceability infrastructure investment away from distributor-controlled systems toward provider-owned networks.
EU MDR's economic operator liability provisions are tightening label permanence standards for implantable devices, forcing adhesive specification upgrades. Manufacturers now face downstream legal exposure for label degradation in vivo. Cardiovascular and orthopedic implant suppliers in Germany and Ireland are accelerating qualification of gamma-stable, solvent-resistant substrate-adhesive combinations.
Hospital procurement consolidation into integrated delivery networks is compressing supplier qualification timelines while expanding compliance documentation requirements. Group purchasing organizations now mandate UDI verification at receipt, not just at shipment. This pattern is most pronounced in United States metropolitan hospital systems with centralized sterile processing operations.
Global Medical Device Labeling Market Segmentation

Medical device labeling segmentation reflects divergent performance requirements across sterilization workflows, traceability mandates, and point-of-use environments. Procurement specifications vary sharply between implantable device manufacturers seeking gamma-stable substrates and diagnostic OEMs prioritizing cost-efficient thermal transfer solutions.
Product Type:
Material specification decisions pivot on sterilization compatibility and information permanence thresholds.
- Thermal Transfer Labels:Wax-resin or full-resin ribbons bond to polyester or polyimide substrates, delivering smudge-resistant barcodes that survive autoclave cycles. Hospital central sterile processing departments in the United States and Germany specify these for instrument tracking trays due to FDA UDI and EU MDR scan reliability mandates.
- RFID Labels:UHF inlays embedded between adhesive layers and printable facestocks enable non-line-of-sight inventory authentication. Integrated delivery networks in Japan and the United States are deploying these for operating room kit verification, though inlay cost premiums constrain adoption outside high-value implantable kits.
- Barcode Labels:Direct thermal or thermal transfer substrates carrying linear or 2D symbologies remain the default for low-risk devices.
- Pressure-Sensitive Labels:Acrylic or silicone adhesives formulated for low-energy surfaces dominate disposable device packaging.
- Film Labels:Polyolefin or fluoropolymer facestocks serve devices requiring solvent resistance.
- Tag Labels:Cardstock or synthetic tags attach to non-adhesive-compatible device surfaces.
Thermal Transfer Labels lead on scale; RFID Labels lead on momentum.
Application:
Regulatory liability exposure and in-vivo permanence requirements stratify substrate selection across device classes.
- Implantable Devices:Cardiovascular stents, orthopedic screws, and pacemakers demand gamma-stable, solvent-resistant adhesive combinations that resist degradation during cobalt-60 terminal sterilization and long-term tissue contact. German and Irish manufacturers face EU MDR economic operator liability provisions that mandate adhesive qualification beyond prior industry standards.
- Surgical Instruments:Precision laparoscopic and robotic tools require laser-etched or thermal transfer markings that withstand repeated autoclave exposure without information loss. United States hospital systems with centralized sterile processing operations specify these for tray-level UDI compliance.
- Diagnostic Equipment:Imaging and laboratory instruments use standard pressure-sensitive labels for asset tracking.
- Monitoring Systems:Patient-worn devices prioritize skin-contact-safe adhesives.
- Dental Devices:Implant drill guides and prosthetics follow sterilization protocols similar to surgical instruments.
- Rehabilitation Equipment:Mobility aids and orthotics employ basic identification labels with limited durability requirements.
Surgical Instruments dominates procurement volume; Implantable Devices commands the steepest specification escalation.
End User:
Workflow automation intensity and compliance documentation burden determine technology adoption readiness.
- Hospitals:Integrated delivery networks with centralized distribution centers mandate UDI verification at receipt, pulling RFID-hybrid labels into replenishment workflows. United States metropolitan systems with group purchasing organization contracts are compressing supplier qualification timelines while expanding traceability documentation requirements.
- Ambulatory Surgical Centers:Smaller sterile processing footprints and lean inventory models favor thermal transfer labels with pre-printed sterilization indicators. These facilities in Japan and the United States are adopting RFID-enabled kits fastest as surgical robotics penetration rises.
- Diagnostic Laboratories:High-throughput specimen tracking relies on cost-optimized barcode labels.
- Home Healthcare Providers:Patient-administered devices require simplified instruction labels.
- Research Institutes:Pre-market device studies use variable-data digital printing for small batches.
- Elder Care Facilities:Durable medical equipment labeling follows basic identification standards.
Hospitals anchor absolute demand; Ambulatory Surgical Centers shows the fastest technology upgrade trajectory.
Technology:
Print method selection trades capital equipment investment against per-unit cost and content flexibility.
- Thermal Printing:Direct thermal and thermal transfer systems dominate high-volume hospital environments due to equipment ubiquity and ribbon supply security. German and Japanese converters maintain dedicated cleanroom production lines for sterile barrier label output.
- Laser Marking:Fiber and CO2 systems etch permanent identifiers directly onto metal instruments and polymer housings, eliminating adhesive degradation risks entirely. This technology is climbing fastest among orthopedic and cardiovascular implant suppliers facing EU MDR permanence scrutiny.
- Inkjet Printing:Piezoelectric drop-on-demand systems serve short-run pharmaceutical-device combination products.
- Digital Printing:Toner and inkjet presses enable on-demand production for clinical trial materials.
- Electrostatic Printing:Specialized applications in cleanroom environments with solvent restrictions.
- Embossing:Legacy method for metal instrument identification with limited information density.
Thermal Printing retains installed base dominance; Laser Marking gains share fastest on implantable device qualification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage in medical device labeling favors jurisdictions with harmonized traceability standards and established sterile packaging infrastructure. Manufacturers migrate production toward countries where FDA UDI and EU MDR compliance costs are offset by proximity to end markets and polymer science talent pools.
United States
Integrated delivery networks in metropolitan hospital systems drive RFID-hybrid label demand for operating room kit verification. FDA UDI mandates at the point of receipt compress supplier qualification timelines. The Greater Boston and Minneapolis-Saint Paul clusters concentrate sterile barrier label converters serving orthopedic and cardiovascular implant OEMs.
Germany
EU MDR economic operator liability provisions force adhesive specification upgrades for implantable device manufacturers. German notified bodies lead ISO 15223-1 symbol interpretation disputes that create certification iteration cycles. The Rhine-Main and Bavarian medical technology corridors host specialty adhesive producers expanding cleanroom-grade substrate capacity.
Japan
PMDA localization rules for imported devices create dedicated label production capacity investments by foreign manufacturers. Surgical robotics penetration in Tokyo and Osaka metropolitan hospitals pulls RFID-enabled labels into high-value implantable kits. Chubu region converters maintain cleanroom production lines for sterile barrier output.
China
NMPA in-country testing requirements for label adhesives fragment global platform standardization efforts with six-to-nine-month approval timelines. Domestic converters in Jiangsu and Zhejiang provinces develop sterilization-compatible coating capabilities for import substitution. Yangtze River Delta medical device OEMs demand gamma-stable thermal transfer substrates.
India
CDSCO medical device rules expansion opens import substitution opportunities for domestic label converters. Maharashtra and Gujarat-based manufacturers invest in autoclave-compatible coating technologies to serve surgical instrument tracking demand. Mumbai-Pune pharmaceutical-device combination product clusters require short-run digital printing capabilities.
Global Medical Device Labeling Market Key Industry Players
North American producers anchor the premium adhesive tier; European specialists hold sterile packaging certification density. The vendor base stratifies across polymer science formulators, cleanroom converters, and integrated packaging conglomerates. Three archetypes dominate: specialty adhesive innovators, sterile barrier system integrators, and diversified materials conglomerates. Competitive moves concentrate on M&A for coating technology access and geographic expansion toward Asia-Pacific regulatory markets.
Within the specialty adhesive tier, Avery Dennison Corporation and Huhtamaki Oyj exemplify divergent approaches to sterilization compatibility. Avery Dennison occupies a position anchored in polymer science expertise for high-performance pressure-sensitive portfolios. Huhtamaki sits within the advanced coating technology segment sustaining autoclave and gamma sterilization compatibility. 3M represents the diversified conglomerate archetype with cross-industrial materials science capabilities applicable to medical device traceability requirements.
| Leading Market Players |
|---|
| Avery Dennison Corporation |
| Huhtamaki Oyj |
| 3M |
| CCL Industries |
| UPM Raflatac |
| Amcor |
| Lintec Corporation |
| Schreiner Group |
| Mondi Group |
| Others |
Cost & Logistics Intelligence
Specialty adhesive resin costs cascade through three pricing tiers as cleanroom-grade pressure-sensitive formulations move from European polymer science specialists to sterile barrier converters serving implantable device OEMs. FDA UDI and EU MDR compliance premiums concentrate at the premium tier, while diagnostic equipment labels compete on thermal transfer ribbon efficiency.
Pricing Analysis
Distributor margins compress most acutely in the standard tier, where thermal transfer label converters face ribbon supply security premiums and hospital procurement consolidation. Three-tier pricing structure across premium, standard, and economy levels separates gamma-stable implantable substrates from autoclave-compatible instrument labels and basic barcode solutions. Pricing pressure stems from specialty adhesive concentration among German and Swiss polymer formulators. Ambulatory surgical centers exhibit highest price sensitivity due to lean inventory models, while integrated delivery networks absorb RFID-hybrid premiums for operating room workflow optimization.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from United States metropolitan hospital systems and German implantable device manufacturers, bypassing distributor markups for sterile barrier label contracts. Geographic supply concentrates in Germany, Japan, and the United States, where cleanroom production lines and polymer science talent clusters align with regulatory enforcement intensity. Raw material dependencies span medical-grade acrylic adhesives, polyester facestocks, and UHF RFID inlays. Single-source vulnerability sits with European specialty adhesive producers qualified for gamma sterilization compatibility. Distribution runs through group purchasing organizations and regional sterile packaging distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The medical device labeling market functions as a regulatory compounder, where EU MDR economic operator liability provisions and FDA UDI mandates continuously escalate substrate permanence requirements and traceability investments.
For Market Incumbents: Extend cleanroom-grade adhesive formulation capabilities through backward integration into polymer science talent acquisition, countering specialty resin supply bottlenecks. Deepen certification density with notified bodies for ISO 15223-1 symbol interpretation to accelerate product launch timelines. Acquire regional converters in Japan and China to bypass PMDA localization delays and NMPA in-country testing barriers.
For New Entrants and Emerging Players: Begin with autoclave-compatible coating technologies for surgical instrument tracking in India's CDSCO-expanding market, where import substitution policies favor domestic production. Target ambulatory surgical centers in Japan and the United States with RFID-enabled kit verification solutions as surgical robotics penetration rises. Pursue hospital system partnerships through direct-to-hospital digital printing capabilities that reduce SKU proliferation.
For Investors and Strategic Acquirers: Roll-up economics work for sterile barrier system integrators because EU MDR liability fragmentation forces mid-tier converters toward scale or exit. Long-term viability centers on platforms with gamma-stable substrate-adhesive qualification and multi-regulatory certification architectures. Watch blockchain-UDI convergence pilots as the inflection signal for immutable traceability infrastructure investment.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR Annex I compliance accelerates machine-readable label adoption across sterile barrier systems. |
| Hospital System Partnership | Integrated delivery network contracts compress supplier qualification while expanding UDI verification requirements. |
| Backward Integration into Adhesive Formulation | Captive polymer science capabilities insulate against European specialty resin supply concentration. |
| RFID Inlay Integration | Hybrid thermal transfer-RFID substrates enable point-of-use authentication in operating suites. |
| Reimbursement Strategy | Traceability infrastructure investments align with CMS Medicare device tracking mandates. |
Research Approach
Coverage spans the United States, Germany, Japan, China, and India, with primary inputs from each market cluster combining interviews with biomedical engineers, hospital purchasing committees, GPO contracts managers, and sterile processing directors with secondary validation. Secondary sources include FDA UDI database filings, EU MDR notified body certification records, hospital procurement databases, and customs trade data for adhesive resin imports. Bottom-up volume modeling triangulates against top-down regulatory mandate impact assessments.
Granularity extends to product type, application class, end-user workflow intensity, and print technology across the analysis window. Segmentation dimensions capture sterilization compatibility thresholds, regulatory compliance tier, and point-of-use environment. CAGRs derive from installed base replacement cycles, surgical volume trajectories, and traceability mandate phase-in schedules. Forecast inputs incorporate RFID adoption curves in integrated delivery networks and laser marking penetration among implantable device suppliers.
Several conditions sit outside the modeled scope, including geopolitical trade restrictions on medical-grade polymers, sudden harmonization of ISO 15223-1 symbol interpretation across notified bodies, and breakthrough sterilization technologies displacing gamma and autoclave protocols. Forecasts reflect assumptions about regulatory enforcement consistency and hospital capital expenditure continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Tumor Tracking Systems Market
Medical Devices
Remote Magnetic Catheter Systems Market
Medical Devices
Global Assistive Listening Device Market
Medical Devices
South Africa Neurology Devices Market
Medical Devices
Intravenous Transportation System Market
Medical Devices
Neonatal & Preterm Infant Enteral Feeding Devices Market
Medical Devices
Japan Ultrasound Devices Market
Medical Devices
Global Glaucoma Surgery Devices Market
Medical Devices
Global Hemorrhoid Treatment Devices Market
Medical Devices
US Anti-Snoring Devices and Snoring Surgery Market
Medical Devices
Urethral Bulking System Market
Medical Devices
Neuro Medical Devices Market
Medical Devices
Autorefractor Keratometer Market
Medical Devices
Global Thrombectomy Devices Market
Medical Devices
Massage Equipment Market
Medical Devices
Europe Spinal Fusion Devices Market