
 India Artificial Organs and Bionics Market | 2026-2036
India Artificial Organs and Bionics Market Size, Share, and Industry Trends Forecast 2026-2036
India Artificial Organs and Bionics Market Foresight
Biomechanical integration with sensor-enabled feedback systems is tilting the technology stack toward closed-loop control architectures. Medtronic leverages its cardiac rhythm management expertise to anchor premium implantable device portfolios across Indian metros. Cochlear Limited differentiates through specialized auditory rehabilitation ecosystems that extend beyond hardware into therapy networks. Ossur competes on advanced prosthetic limb geometries optimized for tropical climate durability.
Artificial organs and bionics comprise electromechanical and biological substitutes engineered to restore or augment physiological functions, incorporating biocompatible alloys, polymer matrices, and microprocessor-controlled actuation with operational lifespans measured in years. These systems serve patients with organ failure, sensory deprivation, or motor impairment across clinical and ambulatory settings. Cardiac devices dominate current revenue pools given the burden of cardiovascular disease, while 3D printing emerges as the fastest-growing technology segment by enabling patient-specific anatomical matching at reduced tooling cost. Robotics applications in neurology and orthopedics concentrate margin pools where precision motor control commands premium reimbursement.
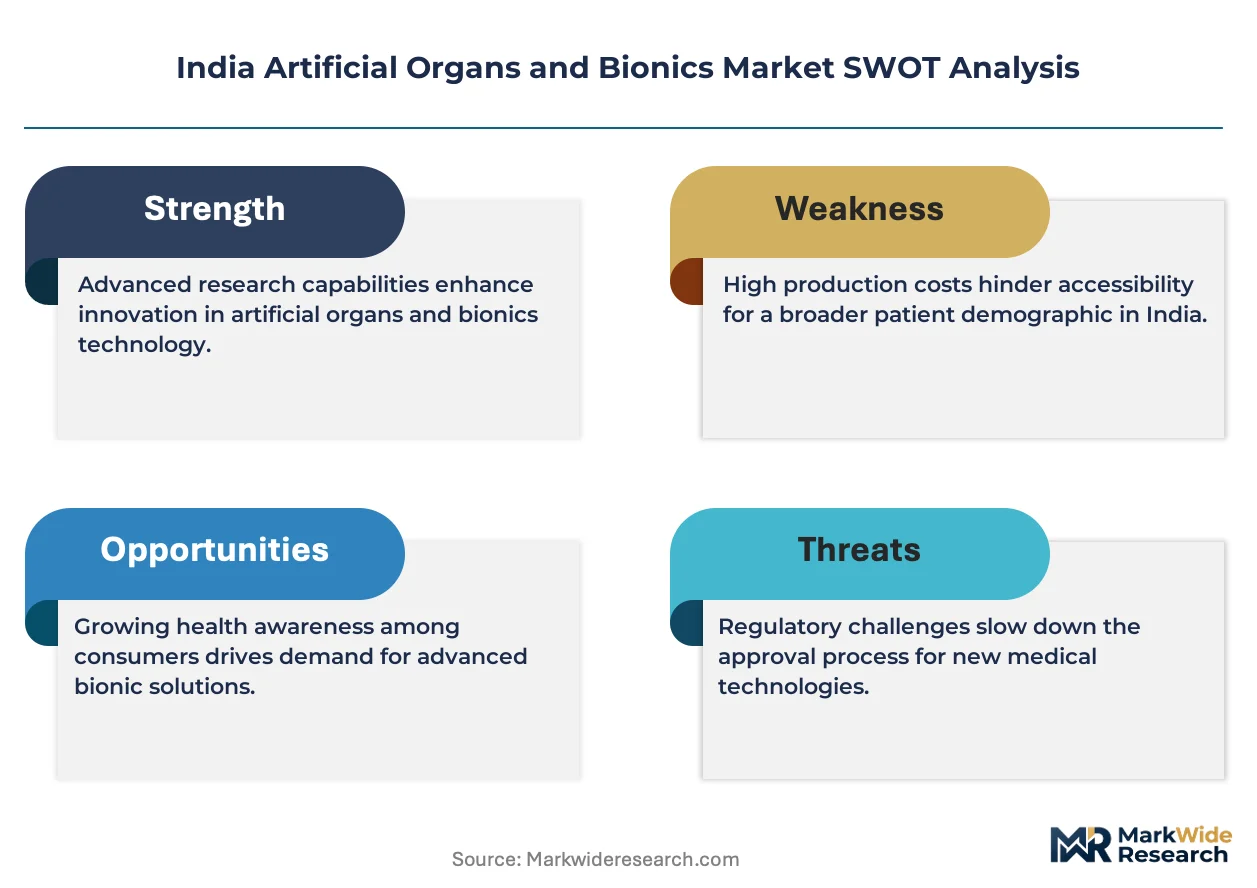
CDSCO governs product registration and clinical trial protocols under the Medical Device Rules, while BIS certification mandates electrical safety and electromagnetic compatibility standards for active implantables. The PLI scheme for medical devices shapes demand by incentivizing domestic manufacturing scale, reducing import dependency for critical components. Stakeholders must monitor how state-level health procurement policies align with central regulatory harmonization to capture reimbursement-accessible volume.
Market Dynamics
CDSCO's streamlined approval pathways under the Medical Device Rules are compressing time-to-market for active implantables, while the PLI scheme redirects manufacturing gravity toward domestic production clusters in Maharashtra and Tamil Nadu.
Growth Catalysts
- PLI scheme incentives:Production-linked incentives for medical devices are accelerating local manufacturing scale for cardiac rhythm management devices and prosthetic components, reducing import dependency for critical sub-assemblies.
- Tertiary care expansion:Hospital chains in Mumbai, Chennai, and Delhi are scaling procurement of sensor-enabled bionic limbs and implantable cardiac devices to address cardiovascular disease burden.
- 3D printing adoption:Patient-specific anatomical matching through additive manufacturing is lowering tooling costs for custom prosthetic geometries optimized to tropical climate conditions.
Market Restraints
- Biocompatible alloy supply concentration:Titanium and cobalt-chromium feedstock dependence on select international suppliers creates vulnerability in raw material security for implantable device manufacturers.
- BIS certification timelines:Electromagnetic compatibility and electrical safety testing protocols for active implantables extend product registration cycles, delaying commercialization of next-generation devices.
- Reimbursement fragmentation:State-level health procurement policies vary in alignment with central regulatory harmonization, creating access inequities across Maharashtra, Tamil Nadu, and Delhi-NCR markets.
Strategic Opportunities
- Rural and tier-2 penetration:Diagnostic reach expansion into Kerala and Karnataka secondary care networks opens volume pools for auditory rehabilitation ecosystems and cochlear implant services.
- Closed-loop control architectures:Convergence of microprocessor-controlled actuation with real-time sensor feedback is enabling next-generation biomechanical integration for motor impairment patients.
- Domestic component ecosystems:DGFT import substitution frameworks and local sourcing mandates for public procurement are creating captive supply opportunities for polymer matrix and electronics sub-assembly producers.
Industry Challenges
- Biomedical engineering talent scarcity:Specialized expertise in electromechanical system design and biocompatible materials processing remains concentrated in metro-based research institutions, constraining workforce scaling.
- Clinical trial infrastructure:CDSCO-mandated investigation protocols for novel implantable devices require dedicated catheterization laboratory and surgical suite access, limiting trial site availability.
- Legacy system integration:Hospital information system compatibility with device telemetry and remote monitoring platforms creates deployment friction in established tertiary care centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Artificial Organs and Bionics Market |
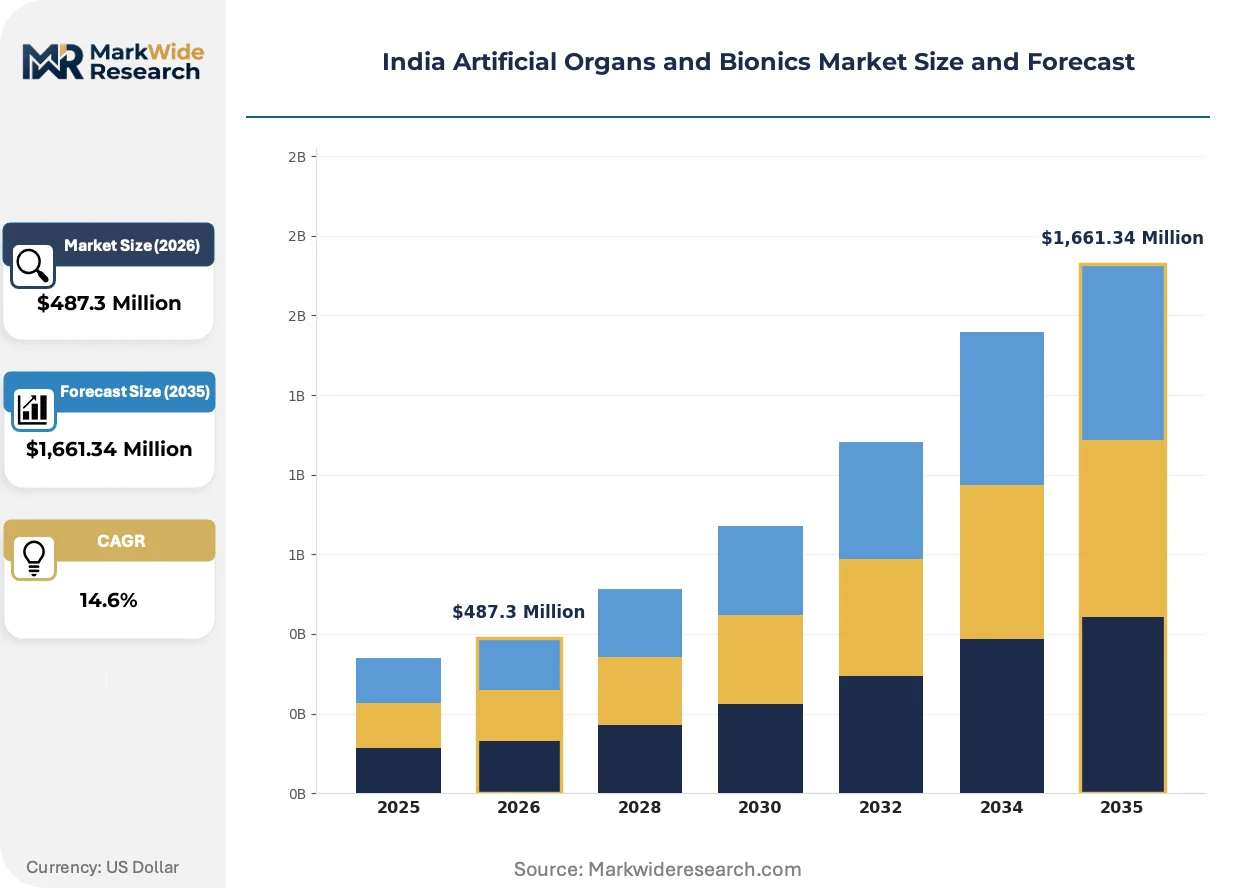
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,661.34 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cardiac Devices, Prosthetic Limbs, Cochlear Implants, Bionic Eyes End User: Hospitals, Rehabilitation Centers, Research Institutes, Home Care Technology: Biomechanics, Nanotechnology, Robotics, 3D Printing Application: Orthopedics, Neurology, Urology, Cardiovascular |
| Companies Covered | Abiomed, Ossur, Medtronic, Asahi Kasei Medical Co Ltd, Getinge AB, Boston Scientific Corporation, Ekso Bionics Holdings Inc, Cochlear Limited, Baxter, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Artificial Organs and Bionics Market Shifts & Advancements
Biomechanical systems are transitioning from passive mechanical substitutes toward intelligent, feedback-enabled platforms that adapt to patient physiology in real time, restructuring competitive advantage around software and sensor integration rather than hardware alone.
Closed-loop neuromodulation is hybridizing traditional cardiac rhythm management with real-time hemodynamic sensing, enabling automatic parameter adjustment without clinician intervention. Tertiary cardiac centers in Mumbai and Delhi are piloting these systems for heart failure patients, compressing the gap between implantable hardware and disease management platforms.
CDSCO's alignment with International Medical Device Regulators Forum harmonization principles is accelerating convergence between Indian and ISO 13485 quality management standards. Domestic manufacturers are restructuring documentation and risk management protocols to access export markets, with active implantable electrical safety requirements driving the most significant compliance investment.
Service unbundling is separating device hardware from rehabilitation therapy and maintenance contracts in auditory and orthopedic segments. Cochlear implant and advanced prosthetic limb vendors are facing pressure to price hardware independently from multi-year therapy support, with metropolitan hospital chains in Chennai and Bangalore leading the contractual restructuring.
India Artificial Organs and Bionics Market Segmentation
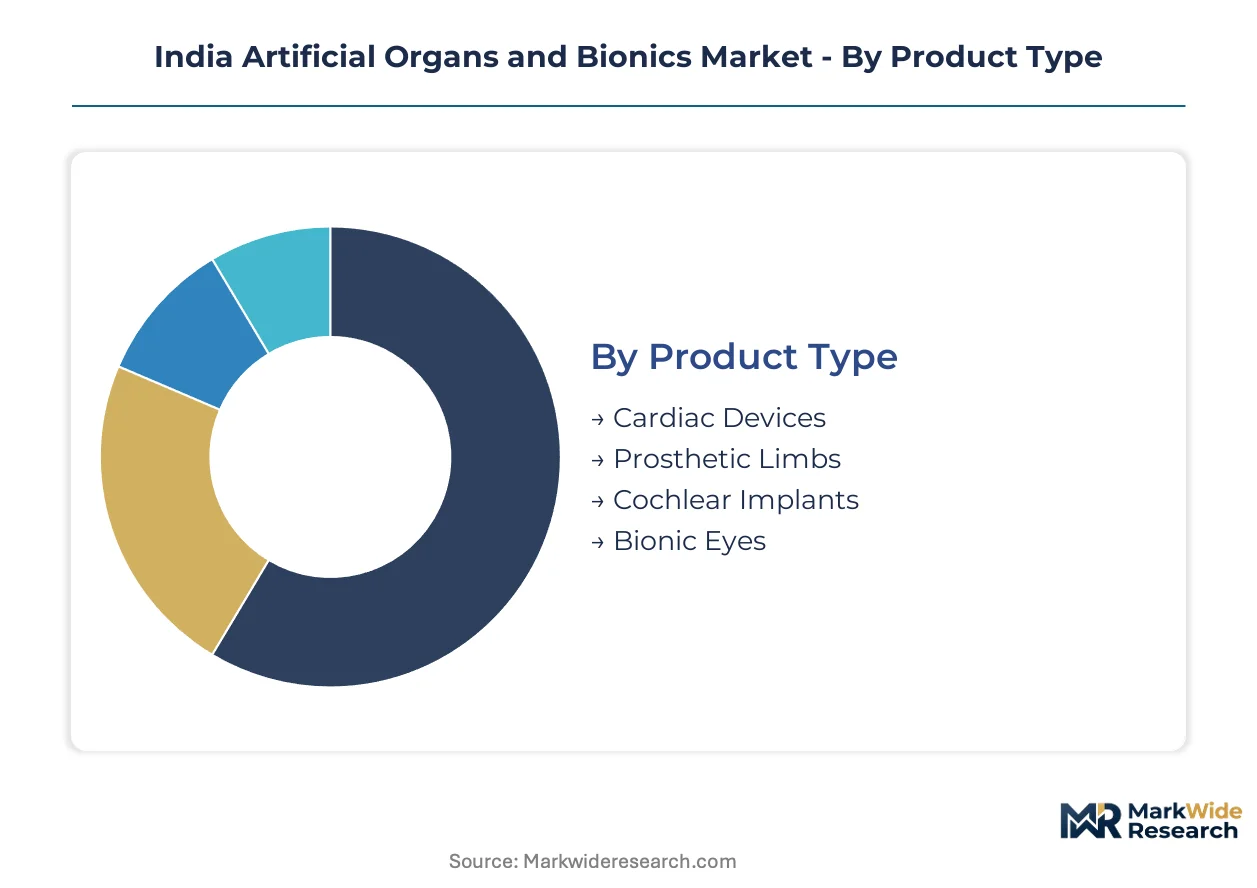
India's artificial organs and bionics market segments around distinct service intensity profiles, with cardiac and orthopedic applications demanding continuous clinical monitoring while auditory and visual prosthetics require extended rehabilitation protocols. Understanding these segment boundaries clarifies where procurement budgets concentrate and which technologies command premium pricing.
Product Type:
After-sales service intensity varies dramatically across implant categories, with active cardiac systems requiring remote monitoring infrastructure and passive prosthetics demanding fitting adjustments over years.
- Cardiac Devices:Implantable pacemakers and defibrillators incorporate lithium-iodine batteries and titanium enclosures with telemetry connectivity for remote parameter adjustment. Demand clusters at tertiary cardiac centers in Mumbai and Delhi where electrophysiology lab density supports complex implant procedures and follow-up care.
- Prosthetic Limbs:Carbon-fiber composite and silicone socket assemblies with microprocessor knee joints adapt gait patterns through real-time sensor feedback. Maharashtra and Tamil Nadu hospital chains are scaling procurement of tropical-optimized geometries that resist humidity degradation in monsoon conditions.
- Cochlear Implants:Electrode arrays and speech processors requiring surgical placement and auditory rehabilitation spanning months to years.
- Bionic Eyes:Retinal prosthesis systems with camera-mounted glasses and implanted electrode arrays for degenerative retinal conditions.
Cardiac devices hold the largest share; momentum sits with prosthetic limbs as 3D printing enables faster custom fabrication cycles.
End User:
Procurement authority and reimbursement pathways diverge sharply between institutional settings with centralized purchasing and dispersed home care environments where patient out-of-pocket burden dominates.
- Hospitals:Tertiary care centers in Delhi-NCR, Mumbai, and Chennai maintain catheterization laboratories and surgical suites for complex implant procedures. CDSCO registration requirements and BIS electrical safety certification filter supplier access to these high-volume procurement nodes.
- Rehabilitation Centers:Specialized facilities in Kerala and Karnataka provide post-implant therapy for cochlear and prosthetic patients. PLI scheme incentives for domestic manufacturing are expanding device availability to secondary city networks previously dependent on metro referrals.
- Research Institutes:Academic medical centers conducting CDSCO-mandated clinical trials for novel implantable devices.
- Home Care:Remote monitoring platforms and patient-managed maintenance for stable chronic conditions.
Hospitals dominate current procurement volume; rehabilitation centers are climbing the fastest as service unbundling separates hardware from therapy contracts.
Technology:
Manufacturing cost structures and regulatory pathways segment sharply between mature mechanical platforms and emerging additive fabrication methods.
- Biomechanics:Passive and active mechanical systems using aluminum, titanium, and polymer composites with established ISO 13485 quality frameworks. Domestic manufacturers in Maharashtra leverage PLI scheme benefits to scale production of socket assemblies and joint mechanisms.
- Robotics:Exoskeleton and precision surgical systems with servo motor control and haptic feedback for neurology and orthopedic applications.
- Nanotechnology:Surface modification coatings and drug-eluting interfaces for improved biocompatibility.
- 3D Printing:Additive manufacturing of patient-specific anatomical geometries from medical-grade polymers and metals. Tooling cost elimination and tropical climate customization are accelerating adoption for prosthetic sockets and dental implants in Chennai and Bangalore manufacturing clusters.
Biomechanics retains the largest installed base; 3D printing represents the steepest expansion trajectory as design-to-implant timelines compress from weeks to days.
Application:
Disease burden distribution and reimbursement policy alignment determine where procurement budgets concentrate across clinical specialties.
- Cardiovascular:Rhythm management and circulatory support devices addressing India's rising ischemic heart disease prevalence. CDSCO streamlined approval pathways under Medical Device Rules are accelerating market entry for next-generation pacemakers and implantable cardioverter-defibrillators.
- Orthopedics:Joint replacement and limb prosthesis systems for trauma and degenerative conditions. 3D printing adoption is concentrated here for patient-specific implant geometries matching individual bone structure.
- Neurology:Deep brain stimulation and neuromodulation systems for movement disorders and epilepsy.
- Urology:Artificial urinary sphincters and bladder replacement systems for incontinence and organ failure.
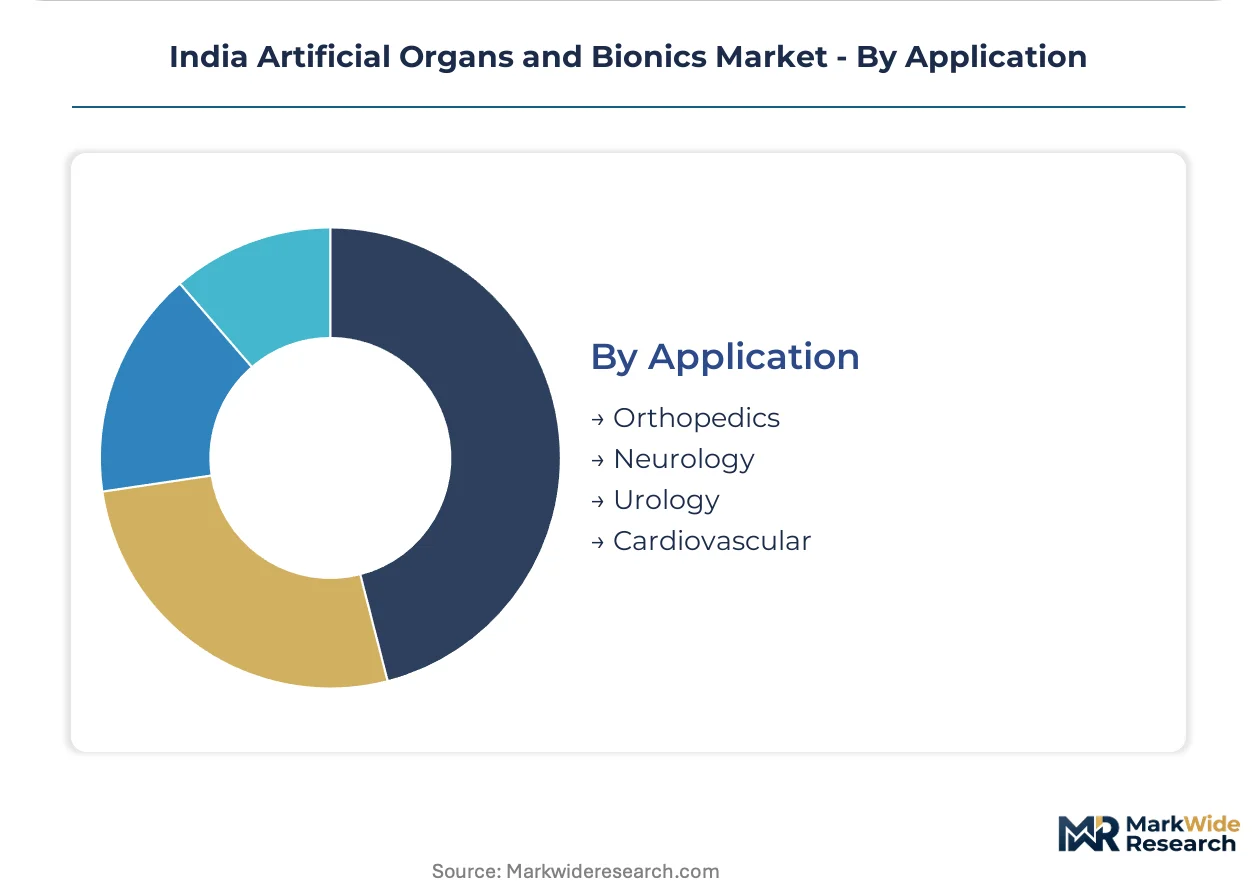
Cardiovascular commands the largest revenue pool; orthopedics is gaining share fastest as trauma incidence and aging demographics expand addressable patient populations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement managers in metropolitan tertiary centers drive demand concentration, with cardiac catheterization laboratories and orthopedic surgical suites serving as the primary purchase decision nodes across Indian states.
Maharashtra
Mumbai's hospital chains scale cardiac device procurement for rhythm management and heart failure interventions. CDSCO's streamlined Medical Device Rules compress registration timelines for active implantables entering this market. Pune and Nashik manufacturing clusters leverage PLI scheme incentives to expand domestic production of biocompatible alloy components and polymer socket assemblies.
Tamil Nadu
Chennai's tertiary cardiac centers generate concentrated demand for implantable cardioverter-defibrillators and pacemaker systems with telemetry connectivity. BIS certification mandates for electrical safety and electromagnetic compatibility filter supplier access to these procurement nodes. Coimbatore and Madurai rehabilitation networks expand cochlear implant therapy capacity beyond metropolitan referral patterns.
Delhi-NCR
Electrophysiology laboratory density in Delhi supports complex cardiac implant procedures and follow-up care protocols. DGFT import substitution frameworks redirect component sourcing toward domestic suppliers for public hospital procurement. Gurgaon and Faridabad medical device manufacturing zones attract PLI scheme beneficiaries scaling production of sensor-enabled prosthetic sub-assemblies.
Karnataka
Bangalore's hospital chains pilot closed-loop neuromodulation systems for movement disorder patients, compressing hardware-therapy integration timelines. State-level health procurement policies in Karnataka align with central regulatory harmonization to reduce reimbursement access inequities. Mysore and Hubli secondary care networks expand diagnostic reach for auditory rehabilitation services previously concentrated in Bangalore.
Kerala
Thiruvananthapuram and Kochi rehabilitation centers specialize in post-implant therapy for cochlear and prosthetic patients, extending service unbundling beyond hardware-only contracts. CDSCO-mandated clinical trial protocols for novel implantable devices concentrate at academic medical centers in this state. Kozhikode and Thrissur secondary city networks reduce metro referral dependency for prosthetic fitting and adjustment services.
India Artificial Organs and Bionics Market Competitive Landscape
Channel-controlling players compete with product-specialist players across procurement nodes in Mumbai, Chennai, and Delhi-NCR hospital chains. The vendor base clusters around three tiers: multinational device manufacturers with cardiac rhythm management portfolios, specialized prosthetic limb fabricators with tropical climate optimization capabilities, and auditory rehabilitation ecosystem providers extending into therapy networks. Strategic moves concentrate on portfolio diversification into sensor-enabled feedback systems and geographic expansion through state-level procurement contract capture.
Among cardiac-focused multinationals, Medtronic and Boston Scientific Corporation occupy positions anchoring premium implantable device portfolios across Indian metropolitan markets. Cochlear Limited exemplifies the auditory rehabilitation ecosystem archetype, extending hardware offerings into multi-year therapy support networks. Ossur represents specialized prosthetic limb optimization, competing on geometries engineered for tropical climate durability and humidity resistance during monsoon conditions.
| Leading Market Players |
|---|
| Abiomed |
| Ossur |
| Medtronic |
| Asahi Kasei Medical Co Ltd |
| Getinge AB |
| Boston Scientific Corporation |
| Ekso Bionics Holdings Inc |
| Cochlear Limited |
| Baxter |
| Others |
Supply & Pricing Matrix
Undercapacity in domestic biocompatible alloy smelting drives dual sourcing premiums for cardiac device manufacturers while compressing margins for prosthetic limb fabricators competing on tropical climate durability. CDSCO's Medical Device Rules and BIS electromagnetic compatibility mandates layer certification costs onto landed import prices, reshaping procurement negotiations between Maharashtra hospital chains and international suppliers.
Pricing Analysis
Cost-plus contracts with titanium and cobalt-chromium indexation dominate procurement agreements for implantable cardiac systems. Three-tier pricing structure across premium, standard, and economy levels separates telemetry-enabled active devices from passive mechanical substitutes, with CDSCO registration tier and BIS certification grade as primary differentiation drivers. Price erosion runs through standard-tier prosthetic sockets as domestic PLI scheme beneficiaries scale polymer matrix production. Public hospital procurement committees in Delhi-NCR exhibit highest price sensitivity; private tertiary cardiac centers in Mumbai maintain lowest sensitivity given bundled therapy contracts.
Supply Chain Analysis
Contract manufacturing capacity for medical-grade electronics concentrates at Foxconn and Dixon facilities in Tamil Nadu and Karnataka, with semiconductor packaging for implantable devices resting on Taiwan and South Korea foundries. Raw material flows draw from Australian titanium sponge, German cobalt-chromium master alloys, and Chinese rare earth magnet feedstock for microprocessor-controlled actuation. Single-source vulnerability in biocompatible polymer precursor supply creates exposure to DGFT import licensing delays. Distribution runs through hospital procurement committees and GPO contracts at tertiary cardiac centers, with rehabilitation center networks in Kerala and Karnataka extending last-mile fitting services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory entrenchment moat where CDSCO approval timelines and BIS certification protocols create switching costs that protect incumbent cardiac device portfolios while constraining new entrant speed-to-market.
For Market Incumbents: Harden defensive positioning by deepening backward integration into biocompatible alloy component production at Maharashtra and Tamil Nadu manufacturing clusters to offset titanium feedstock price volatility. Anchor channel control through exclusive telemetry infrastructure contracts with Delhi-NCR and Mumbai hospital chains, locking out emerging competitors lacking remote monitoring platform compatibility. For New Entrants and Emerging Players: Build out white-space presence in Karnataka and Kerala secondary care rehabilitation networks where cochlear implant therapy and prosthetic fitting services remain underpenetrated relative to metro referral concentration. Target auditory rehabilitation ecosystem partnerships as the most penetrable entry vector, leveraging service unbundling trends to price hardware independently from multi-year therapy support contracts. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across 3D printing-enabled custom prosthetic fabrication as additive manufacturing equipment and medical-grade polymer feedstock requirements escalate. Five-to-ten year viability favors acquisition targets possessing captive ISO 13485 quality management infrastructure and established CDSCO regulatory affairs capabilities rather than pure technology licensors. Monitor PLI scheme beneficiary lists as inflection signal for domestic manufacturing scale viability.| Strategic Initiative | Industry Significance |
|---|---|
| CDSCO Registration Pathway Acceleration | Streamlined Medical Device Rules compress time-to-market for active implantables entering Maharashtra and Delhi-NCR procurement nodes. |
| Domestic Manufacturing Scale-Up | PLI scheme incentives redirect biocompatible alloy and polymer matrix production toward Tamil Nadu and Karnataka clusters. |
| Hospital System Partnership | Exclusive telemetry infrastructure contracts with Mumbai and Chennai tertiary cardiac centers lock in recurring remote monitoring revenue streams. |
| Software Companion Development | Closed-loop control architectures with real-time sensor feedback differentiate next-generation prosthetic limb portfolios from passive mechanical substitutes. |
| Reimbursement Strategy Alignment | State-level health procurement policy harmonization with central CDSCO frameworks reduces access inequities across Maharashtra, Tamil Nadu, and Karnataka markets. |
Research Methodology
Cross-validation between hospital procurement database analysis and CDSCO registration filings anchors the qualitative findings on supplier access and device commercialization timelines. Primary interviews with biomedical engineers, tertiary cardiac center purchasing committees, GPO contracts managers, and rehabilitation center therapy directors combined with secondary validation against BIS certification records, PLI scheme beneficiary disclosures, and state health department procurement circulars. Bottom-up demand modeling from individual hospital catheterization laboratory capacity and top-down market sizing from import-export trade data complete the triangulation.
Calibration against historical cardiac device implant volumes and prosthetic limb fitting rates across Maharashtra, Tamil Nadu, and Delhi-NCR established baseline growth trajectories. Segmentation modeling spanned product type, end user institution class, technology platform, and clinical application with regional regulatory cluster as an additional dimension. CAGRs derive from fitted growth curves incorporating PLI scheme incentive phase-ins and CDSCO approval pathway efficiency gains. Industry-specific forecast inputs include tertiary care bed expansion rates and 3D printing adoption curves in Chennai and Bangalore manufacturing zones.
Sensitivities concentrate around biocompatible alloy supply disruptions, BIS certification timeline extensions, and state-level reimbursement policy fragmentation. Forecasts embed assumptions on CDSCO-IMDRF harmonization progress and domestic component ecosystem maturation that could revise trajectory if regulatory alignment stalls or PLI scheme participation undershoots targets. Quarterly review of CDSCO registration approval rates, titanium import customs data, and state health procurement budget allocations is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Manual Resuscitators Market
Medical Devices
Global Stabilometric Platform Market
Medical Devices
Polyp Trap Devices Market
Medical Devices
Gastric Bands Market
Medical Devices
Human Anatomical Models Market
Medical Devices
Neurodiagnostic and Monitoring Devices Market
Medical Devices
LAMEA External Defibrillators Market
Medical Devices
Japan Minimally Invasive Surgery Devices Market
Medical Devices
Global Body Contouring Devices Market
Medical Devices
Global Hemorrhoid Treatment Devices Market
Medical Devices
Europe Minimally Invasive Surgery Devices Market
Medical Devices
Global Medical Drones Market
Medical Devices
Blood Irradiator Device Market
Medical Devices
Global Oxygen Cylinders and Concentrators Market
Medical Devices
Drug Delivery Solutions Market
Medical Devices
South Korea Aesthetic Devices Market