
 Global Active Implantable Medical Devices Market | 2026-2036
Global Active Implantable Medical Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Active Implantable Medical Devices Market Analysis
Silicon-based microelectronics is pivoting toward biocompatible polymer substrates in neurostimulator housings, reducing device mass and improving charge-transfer efficiency. Medtronic leverages its vertically integrated component foundries to control critical supply nodes for implantable pulse generators. Abbott Laboratories sustains R&D intensity across its cardiac rhythm management portfolio through dedicated electrophysiology research centers. Boston Scientific differentiates via specialized manufacturing lines for leadless pacemaker platforms.
Active implantable medical devices are electronically powered apparatuses surgically placed within human tissue to deliver therapeutic electrical stimulation, monitor physiological parameters, or restore sensory function through integrated microprocessors, hermetically sealed power cells, and biocompatible electrode arrays. These systems serve cardiology, neurology, and audiology by correcting arrhythmias, modulating neural pathways, or converting acoustic signals to electrical impulses for direct nerve interface. Implantable defibrillators dominate value pools due to premium pricing and complex manufacturing, while neurostimulators represent the fastest-expanding category as spinal cord and deep brain indications broaden. Sensor-based technology platforms are capturing margin from conventional RF telemetry as real-time biometric feedback becomes standard in next-generation devices.
FDA premarket approval pathways and the EU MDR clinical evaluation requirements shape product development timelines and market access costs for manufacturers seeking multi-jurisdiction placement. Japan's PMDA imposes supplementary local clinical trials that extend commercialization schedules for foreign device makers. ISO 14708 active implantable standards govern electromagnetic compatibility and electrical safety testing protocols universally recognized by notified bodies. Stakeholders must monitor evolving cybersecurity guidance for wireless-enabled implants as connectivity expands attack surfaces and regulatory scrutiny intensifies.
Market Dynamics
EU MDR clinical evidence requirements are compressing product development timelines while cardiology departments in tertiary hospitals accelerate electrophysiology program expansion, creating simultaneous pressure and pull across the value chain.
Growth Catalysts
- EU MDR Implementation:Tightened clinical evidence requirements for implantable devices are elevating barriers for marginal competitors and consolidating market position among established manufacturers with robust trial infrastructure.
- Polymer Substrate Migration:Silicon-based microelectronics is pivoting toward biocompatible polymer substrates in neurostimulator housings, reducing device mass and improving charge-transfer efficiency for next-generation implants.
- Aging Demographics in Concentrated Markets:Demand is concentrating in the United States, Germany, and Japan where aging populations and reimbursement clarity support procedural volume expansion across cardiac rhythm management.
Market Restraints
- Premium Input Concentration:Implantable pulse generators depend on hermetically sealed power cells and specialized microprocessors supplied through a limited foundry base, creating vulnerability to capacity constraints.
- Extended Commercialization Schedules:Japan's PMDA imposes supplementary local clinical trials that delay market entry for foreign device makers and inflate upfront capital requirements.
- RF Telemetry Displacement Pressure:Sensor-based technology platforms are capturing margin from conventional radio-frequency telemetry as real-time biometric feedback becomes standard, threatening legacy installed base revenues.
Strategic Opportunities
- Deep Brain Indication Broadening:Neurostimulators represent expansion white space as spinal cord and deep brain therapeutic indications widen beyond traditional movement disorders into psychiatric and cognitive domains.
- Cybersecurity Compliance Services:Evolving FDA guidance for wireless-enabled implants creates adjacent revenue streams for firms capable of delivering integrated security validation and ongoing threat monitoring.
- Leadless Platform Manufacturing:Specialized production lines for leadless pacemaker platforms enable differentiation through miniaturization and elimination of transvenous lead complications.
Industry Challenges
- Electrophysiology Talent Scarcity:Cardiac rhythm management program expansion outpaces trained electrophysiologist supply, constraining procedural throughput despite device availability.
- ISO 14708 Certification Burden:Electromagnetic compatibility and electrical safety testing protocols consume 18-24 month validation cycles, compressing effective patent life and return on R&D investment.
- Multi-Jurisdiction Evidence Generation:FDA premarket approval pathways, EU MDR clinical evaluation, and PMDA local trial requirements demand parallel evidence packages that fragment clinical development resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Active Implantable Medical Devices Market |
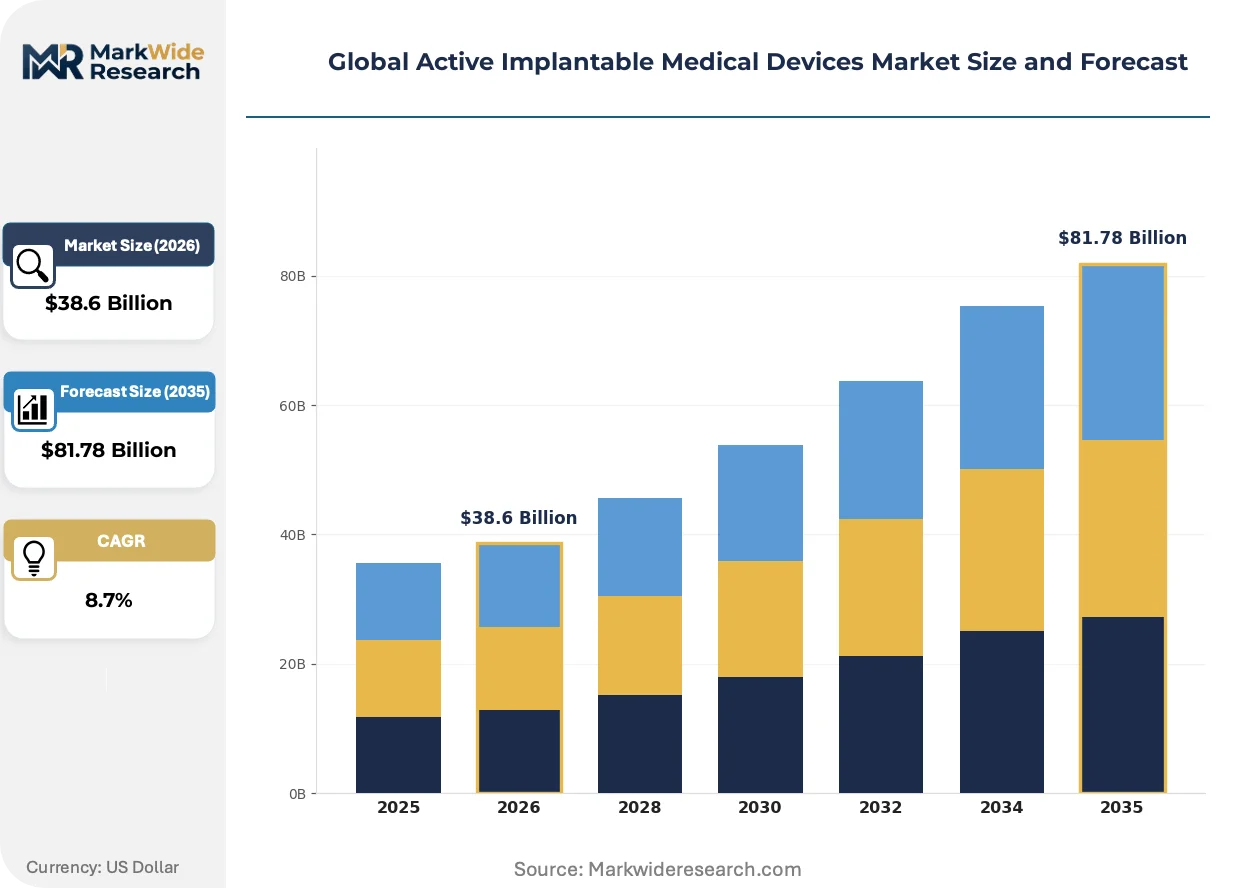
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $81.78 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Cardiac Pacemakers, Implantable Defibrillators, Cochlear Implants, Neurostimulators Application: Cardiology, Neurology, Audiology, Pain Management End User: Hospitals, Clinics, Ambulatory Surgical Centers, Home Care Technology: Wireless, Bluetooth, RF, sensor-based |
| Companies Covered | Medtronic, Abbott Laboratories, Boston Scientific, Cochlear Limited, BIOTRONIK, LivaNova PLC, Sonova Holding AG, William Demant Holding A/S, MED-EL, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Active Implantable Medical Devices Market Emerging Trajectories
Active implantable systems are converging around real-time biometric feedback architectures, regulatory harmonization pressures, and procurement models that prioritize total cost of ownership over device acquisition price.
Biocompatible polymer substrates are replacing silicon-based microelectronics in neurostimulator housings to reduce device mass and improve charge-transfer efficiency. Electrophysiology research centers in tertiary hospitals are accelerating adoption of these lighter platforms for deep brain and spinal cord applications. This materials transition is modularizing the traditional pacemaker and defibrillator supply chain by decoupling power management from structural housing design.
EU MDR clinical evaluation requirements are reshaping evidence generation obligations for implantable devices across all risk classes. Manufacturers must now submit systematic literature reviews and post-market clinical follow-up protocols that substantially expand regulatory affairs staffing. Cardiac rhythm management portfolios face the steepest compliance burden due to their established installed base and long device longevity.
Hospital procurement committees are unbundling after-sales service from device acquisition contracts and negotiating performance-based maintenance agreements separately. This purchasing pattern shift is compressing vendor margins in the United States and Germany while elevating importance of remote monitoring platform reliability. Tertiary cardiology departments now weight cybersecurity audit results alongside clinical efficacy in vendor selection criteria.
Global Active Implantable Medical Devices Market Segmentation
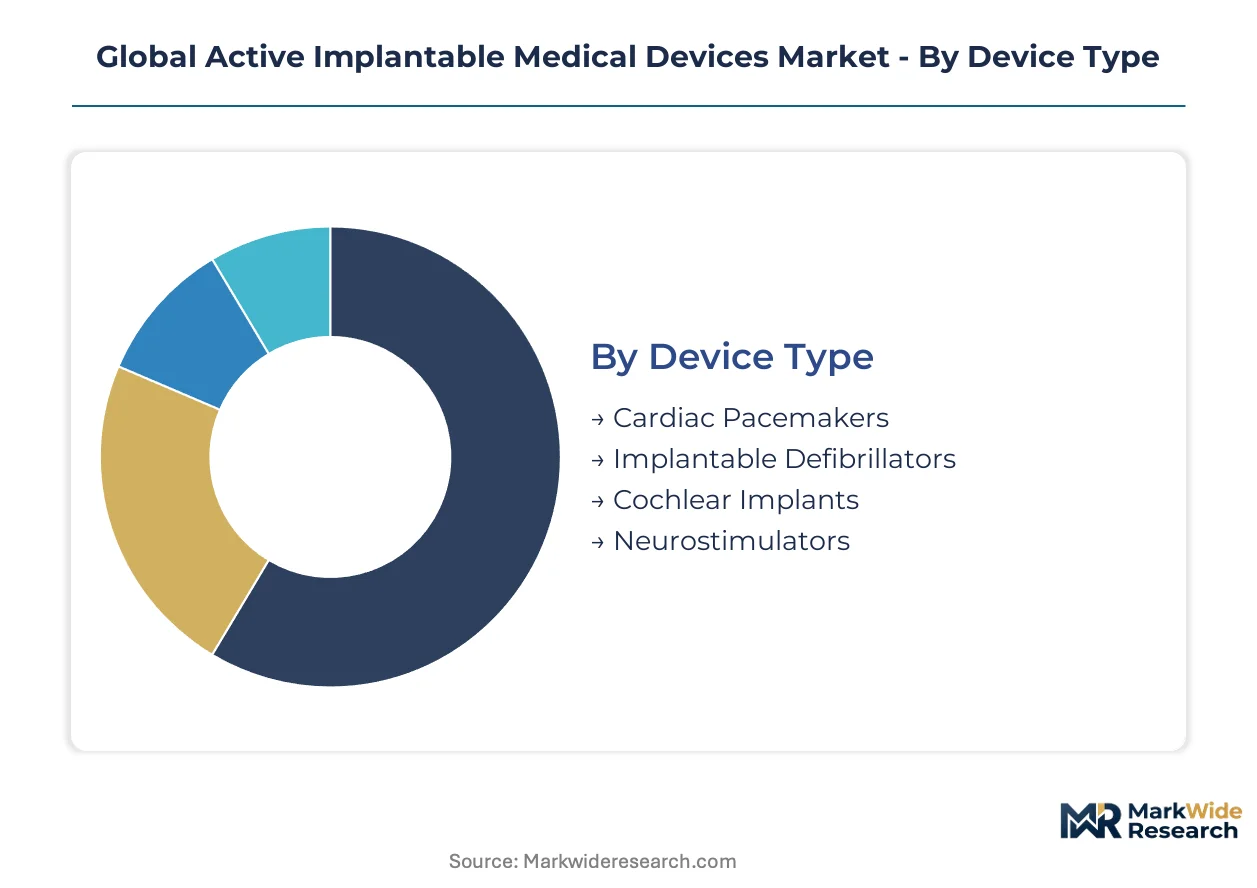
Active implantable medical devices fragment across therapeutic domains, care settings, and connectivity architectures that determine reimbursement pathways and regulatory scrutiny intensity. Understanding these divisions reveals where capital deployment concentrates and which technology transitions threaten incumbent revenue streams.
Device Type:
Buyers in this category differentiate by procedure complexity, device longevity requirements, and the specialist training needed for implantation and follow-up care.
- Implantable Defibrillators:These devices integrate high-voltage capacitors and sophisticated arrhythmia detection algorithms to deliver life-saving shocks. Demand clusters in tertiary cardiology departments across the United States and Germany where electrophysiology program expansion supports premium procedural volumes. Complex manufacturing and hermetic sealing requirements sustain elevated pricing power.
- Neurostimulators:Pulse generators modulate neural pathways through biocompatible polymer housings that reduce mass and improve charge-transfer efficiency. Deep brain and spinal cord indications are broadening beyond movement disorders into psychiatric domains, driving fastest category expansion. Tertiary neurology centers in Japan and the United States lead adoption.
- Cardiac Pacemakers:Rhythm correction devices with transvenous or leadless electrode configurations. Aging demographics in concentrated markets sustain procedural volume.
- Cochlear Implants:Auditory prostheses converting acoustic signals to electrical impulses for direct cochlear nerve interface. Pediatric and geriatric audiology programs in Germany and Japan anchor demand.
Volume sits with implantable defibrillators; growth tilts toward neurostimulators.
Application:
Margin profiles diverge sharply based on whether therapy addresses acute life-threatening conditions or chronic quality-of-life improvement.
- Cardiology:Arrhythmia management through pacemakers and defibrillators commands premium pricing and dedicated electrophysiology infrastructure. Cardiac rhythm management portfolios face steepest EU MDR compliance burden due to established installed base and long device longevity.
- Pain Management:Spinal cord stimulation for chronic refractory pain represents expanding indication breadth with less regulatory scrutiny than cardiac applications. United States reimbursement clarity supports ambulatory surgical center adoption.
- Neurology:Deep brain stimulation for movement disorders and emerging psychiatric indications. PMDA local trial requirements extend Japanese commercialization timelines.
- Audiology:Hearing restoration through cochlear implantation. Volume concentrates in pediatric programs with lifetime device management requirements.
Revenue concentrates in cardiology; steepest expansion trajectory belongs to pain management.
End User:
Procurement sophistication varies from centralized hospital committees negotiating performance-based maintenance to fragmented home care channels prioritizing remote monitoring reliability.
- Hospitals:Tertiary cardiology departments with expanding electrophysiology programs drive premium device adoption. Unbundling of after-sales service from acquisition contracts compresses vendor margins in the United States and Germany.
- Ambulatory Surgical Centers:Lower-acuity settings capturing leadless pacemaker and pain management procedures. Cost pressure favors streamlined device platforms with minimal follow-up requirements.
- Clinics:Specialist cardiology and neurology practices managing device programming and patient monitoring. Cybersecurity audit results now weight heavily in vendor selection.
- Home Care:Remote monitoring platforms enabling patient-managed follow-up. Real-time biometric feedback architectures displace conventional RF telemetry in next-generation systems.
Procedure volume anchors in hospitals; fastest share gain occurs in ambulatory surgical centers.
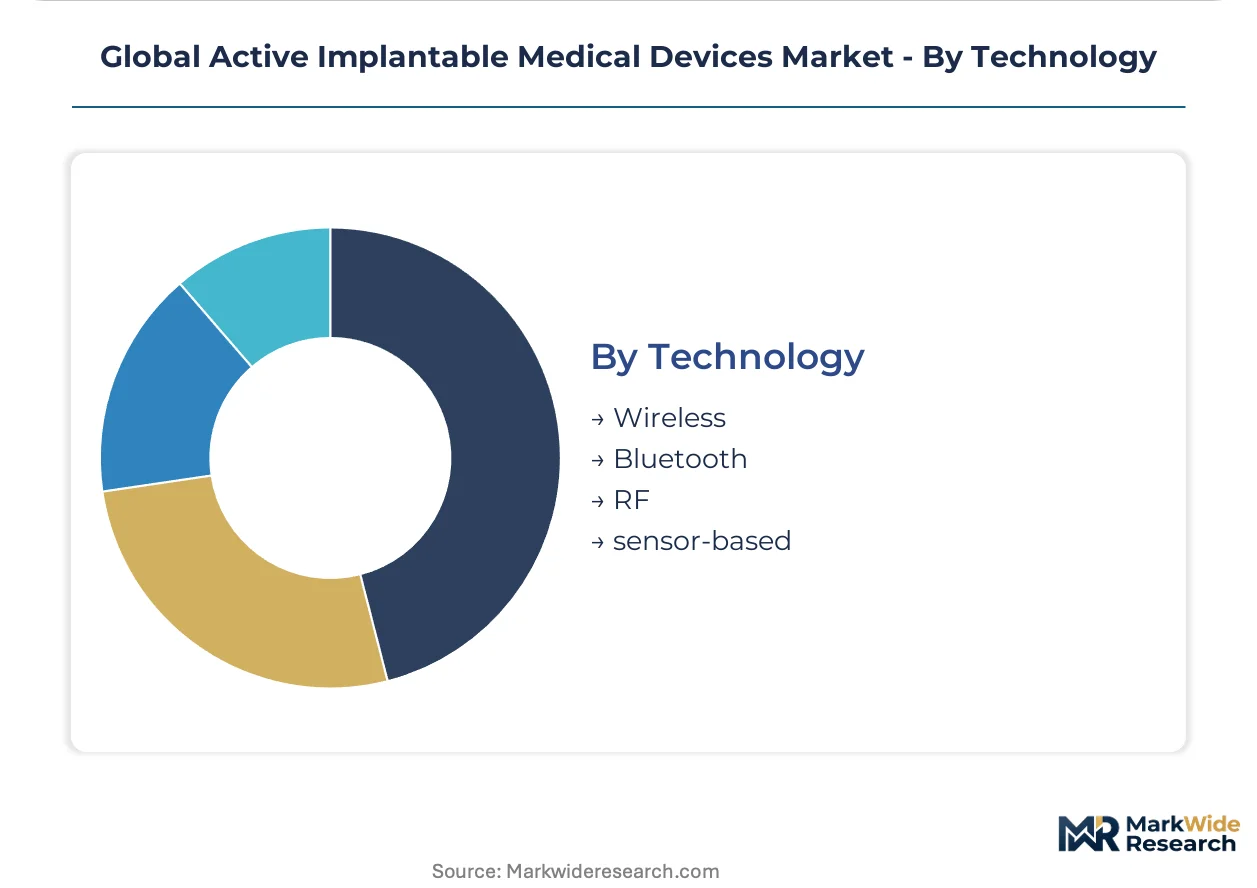
Technology:
Connectivity architecture determines cybersecurity exposure, battery consumption, and the regulatory evidence burden for wireless-enabled implants.
- Sensor-based:Real-time biometric feedback platforms capturing physiological parameters beyond traditional device telemetry. Hospital procurement committees in Germany and the United States prioritize these systems for total cost of ownership advantages. FDA cybersecurity guidance intensifies validation requirements.
- RF:Conventional radio-frequency telemetry facing margin displacement as sensor-based alternatives standardize. Legacy installed base revenues in cardiology face technology transition pressure.
- Bluetooth:Short-range connectivity for patient-facing mobile applications. Consumer electronics integration drives adoption in home care settings.
- Wireless:Broad category encompassing proprietary protocols and emerging standards. ISO 14708 electromagnetic compatibility testing governs safety validation universally.
Installed base concentrates in RF; capability investment flows toward sensor-based architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for active implantable medical devices concentrates in the United States, Germany, and Japan where aging populations and reimbursement clarity support procedural volume expansion across cardiac rhythm management and neurostimulation therapies.
United States
Tertiary cardiology departments in Cleveland Clinic and Mayo Clinic anchor electrophysiology program expansion. FDA premarket approval pathways shape product development timelines for implantable defibrillators and leadless pacemakers. The Minneapolis-St. Paul corridor hosts vertically integrated manufacturing clusters for implantable pulse generators.
Germany
Hospital procurement committees in Berlin and Munich unbundle after-sales service from device acquisition contracts. EU MDR clinical evidence requirements elevate barriers for marginal competitors and consolidate position among established manufacturers. The Baden-Württemberg region concentrates specialized foundry capacity for hermetically sealed power cells.
Japan
Aging demographics in Tokyo and Osaka metropolitan areas drive spinal cord and deep brain stimulation adoption. PMDA imposes supplementary local clinical trials that extend commercialization schedules for foreign device makers. The Kansai region hosts tertiary neurology centers leading psychiatric indication expansion for neurostimulators.
Switzerland
Swissmedic certification requirements align with ISO 14708 electromagnetic compatibility standards for wireless-enabled implants. Zurich and Geneva anchor precision manufacturing clusters for biocompatible polymer substrates in neurostimulator housings. The Basel region concentrates audiology research centers advancing cochlear implant signal processing.
Australia
TGA regulatory frameworks recognize FDA and CE markings to accelerate market entry for cardiac rhythm management devices. Sydney and Melbourne tertiary hospitals expand remote monitoring platform adoption for home care settings. The Victorian biomedical precinct hosts electrophysiology training programs addressing specialist talent scarcity.
Global Active Implantable Medical Devices Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with implantable defibrillators consolidating around vertically integrated incumbents while neurostimulators attract modular component suppliers. The vendor base organizes into three strategic archetypes: diversified conglomerates with captive foundries, focused device specialists with dedicated electrophysiology research infrastructure, and audiology pure-plays with cochlear implant expertise. Competitive moves center on backward integration into critical supply nodes and geographic expansion through localized clinical trial infrastructure.
Within the diversified conglomerate tier, Medtronic and Abbott Laboratories occupy positions defined by vertically integrated component foundries and sustained R&D intensity across cardiac rhythm management portfolios. Boston Scientific exemplifies the focused device specialist archetype through specialized manufacturing lines for leadless pacemaker platforms. Among audiology pure-plays, Cochlear Limited and Sonova Holding AG anchor hearing restoration segments with lifetime device management capabilities.
| Leading Market Players |
|---|
| Medtronic |
| Abbott Laboratories |
| Boston Scientific |
| Cochlear Limited |
| BIOTRONIK |
| LivaNova PLC |
| Sonova Holding AG |
| William Demant Holding A/S |
| MED-EL |
| Others |
Supply Flow & Price Mechanics
Captive foundry control over hermetically sealed power cells and specialized microprocessors anchors supply security for implantable pulse generator manufacturers while sustaining premium pricing power in cardiac rhythm management. This backward integration into critical component nodes insulates established vendors from capacity constraints that would otherwise compress margins.
Pricing Analysis
Volume concentrates in implantable defibrillators where complex manufacturing sustains premium positioning, while neurostimulators command margin expansion through indication broadening. Three-tier pricing structure across premium, standard, and economy levels separates FDA-approved devices with full PMA pathways from CE-marked equivalents and emerging market registrations. Cost compression in standard tiers is intensifying because hospital procurement committees unbundle after-sales service from acquisition contracts. Ambulatory surgical centers exhibit highest price sensitivity; tertiary cardiology departments weight cybersecurity audit results alongside clinical efficacy.
Supply Chain Analysis
Dual-sourcing requirements for biocompatible polymer substrates and hermetically sealed power cells mandate multi-supplier qualification across Germany, Japan, and Switzerland. Manufacturing draws from specialized foundry capacity in Baden-Württemberg, precision polymer substrate clusters in Zurich, and capacitor assembly lines in Osaka. Single-source vulnerability concentrates in implantable-grade lithium-iodine battery cells. Distribution runs through GPO contracts with hospital systems and direct-to-clinic channels for ambulatory settings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The active implantable medical devices sector sits in a technology-transition phase where sensor-based real-time biometric feedback architectures displace conventional RF telemetry, forcing portfolio reallocation across the value chain.
For Market Incumbents: Anchor market position through backward integration into biocompatible polymer substrate manufacturing and captive foundry expansion for power cell production. Defend against modular component suppliers by deepening ISO 14708 certification coverage across next-generation wireless-enabled platforms. For New Entrants and Emerging Players: Capture white space in cybersecurity compliance services for wireless-enabled implants and psychiatric indication expansion for deep brain stimulation. Target ambulatory surgical centers in the United States with streamlined leadless pacemaker platforms requiring minimal follow-up infrastructure. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified conglomerates seeking electrophysiology research infrastructure. Long-term viability hinges on regulatory trial infrastructure capable of parallel FDA, EU MDR, and PMDA evidence generation. Watch for inflection in hospital procurement committee weighting of remote monitoring platform reliability against device acquisition price.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Clinical Evidence Pathway | Systematic literature reviews and PMCF protocols expand regulatory affairs staffing requirements. |
| Hospital System Partnership | GPO contract access secures volume commitment from tertiary cardiology departments. |
| Software Companion Development | Mobile applications with Bluetooth connectivity enable patient-facing biometric feedback. |
| Reimbursement Strategy | CPT code alignment determines ambulatory surgical center adoption for pain management devices. |
| CE Marking Pathway | Notified body selection under MDR governs market access timelines for implantable defibrillators. |
Methodological Framework
Independent corroboration across electrophysiologists, hospital purchasing committees, biomedical engineers, and GPO contracts managers underwrites the qualitative findings. Primary interviews with regulatory affairs leads at notified bodies and FDA submission specialists were validated against secondary sources including FDA PMA and 510(k) filings, EUDAMED device registrations, hospital procurement databases, and CMS Medicare reimbursement schedules. Bottom-up device shipment modeling triangulates with top-down healthcare expenditure analysis.
Rate-of-change decomposition across the projection horizon segments volume by device type, application, end user, and connectivity architecture. Modeled dimensions include therapeutic domain, care setting sophistication, and regulatory approval pathway tier. CAGRs derive from procedural volume elasticity to aging demographics, reimbursement clarity indices, and electrophysiology program expansion rates. Industry-specific inputs incorporate EU MDR transition timelines and PMDA local trial duration assumptions.
The model holds under stable regulatory harmonization progress and reimbursement clarity; deviation in FDA cybersecurity guidance stringency or EU MDR notified body capacity constraints would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Multi Dose Drug Vial Adapters Market
Medical Devices
Global Abdominal Surgical Robot Market
Medical Devices
Contact Lens Lubricant Market
Medical Devices
Global Pathological Microscopes Market
Medical Devices
Electromagnetic Navigation Bronchoscopy Market
Medical Devices
Veterinary Radiography Flat Panel Detectors Market
Medical Devices
Digital BTE Market
Medical Devices
Transcatheter Mitral Valve Market
Medical Devices
Midline Catheters Market
Medical Devices
Spain Ultrasound Devices Market
Medical Devices
Ambulatory Polysomnography (Psg) Systems Market
Medical Devices
Cardiac Resynchronization Therapy (CRT) Devices Market
Medical Devices
Micro-Bypass Systems Market
Medical Devices
Concentrator O2 Devices Market
Medical Devices
Cranial Closure and Fixation Devices Market
Medical Devices
Intravascular Temperature Management Systems Market