
 Endoluminal Device Systems Market | 2026-2036
Endoluminal Device Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Endoluminal Device Systems Market Analytics
The split between premium robotic-assisted delivery platforms and commodity manual catheter systems is shifting as hospital procurement committees weigh capital expenditure against per-procedure economics. Medtronic plc anchors its position through backward integration into catheter manufacturing and proprietary stent alloys. Intuitive Surgical Inc. extends its ecosystem from abdominal surgery into endoluminal navigation with flexible robotic architectures. Boston Scientific competes on interventional cardiology heritage while diversifying into peripheral vascular and gastrointestinal luminal applications.
Endoluminal device systems comprise catheter-delivered instruments designed for diagnosis, intervention, or structural support within hollow organs and vessels, typically constructed from nickel-titanium alloys, stainless steel, or bioabsorbable polymers and deployed at diameters ranging from 2 to 40 millimeters depending on anatomical target. Their primary purpose is to restore or maintain luminal patency, extract foreign bodies, or deploy occlusive therapy without open surgical access. Stents and drug-eluting technologies capture concentrated margin pools where coating chemistry and controlled release kinetics differentiate clinical outcomes. Bioabsorbable platforms represent the fastest-expanding technology segment as physicians seek to eliminate permanent implant risks in younger patient cohorts. Hospitals dominate end-user demand, though ambulatory surgery centers are gaining share for lower-acuity procedures as anesthesia protocols and same-day discharge pathways mature.
FDA premarket approval and the EU MDR clinical evaluation requirements are elevating barriers for novel endoluminal entrants while accelerating consolidation among established manufacturers with regulatory infrastructure. Japan's PMDA and South Korea's MFDS impose additional local clinical testing mandates that shape product launch sequencing across Asia-Pacific markets. Stakeholders must monitor evolving reimbursement decisions for robotic-assisted delivery modes in Germany and the United States, as these determinations will dictate whether capital-intensive platforms achieve scalable adoption or remain confined to flagship academic centers.
Market Dynamics
The transition from permanent metallic implants to bioabsorbable scaffolds is restructuring competitive advantage around polymer chemistry capabilities and controlled-degradation engineering rather than traditional metallurgy expertise.
Growth Catalysts
- EU MDR clinical evidence mandates:Stricter biocompatibility documentation requirements are consolidating demand among manufacturers with established regulatory infrastructure, accelerating hospital preference for proven device platforms.
- Drug-eluting coating advances:Polymer formulations enabling targeted sirolimus or paclitaxel release are extending patency outcomes in peripheral vascular applications, differentiating premium stent portfolios.
- Japan's aging demographic profile:PMDA reimbursement pathways for interventional cardiology procedures are sustaining procedure volume expansion among patients over 75 years with comorbidities precluding open surgery.
Market Restraints
- Nickel-titanium alloy supply concentration:Controlled memory wire production remains concentrated among specialized metallurgical suppliers in Germany and the United States, creating input cost volatility for catheter manufacturers.
- FDA premarket approval timelines:Novel bioabsorbable stent platforms face extended clinical trial requirements compared to predicate devices, compressing effective patent life and delaying revenue recognition.
- Conventional open surgical alternatives:Vascular bypass grafting and transabdominal resection retain preference in rural hospital systems with limited interventional cardiology staffing, constraining addressable procedure volume.
Strategic Opportunities
- South Korea's MFDS accelerated review pathway:The Ministry of Food and Drug Safety priority designation for breakthrough devices enables faster market entry for robotic-assisted delivery systems in Seoul's flagship cardiac centers.
- Gastrointestinal luminal oncology:Endoluminal radiofrequency ablation and localized chemotherapy delivery represent underdeveloped applications beyond established vascular stenting, with procedure protocols still crystallizing.
- Same-day discharge anesthesia protocols:Ambulatory surgery centers are capturing lower-acuity peripheral vascular procedures previously hospitalized, creating channel expansion for simplified catheter systems.
Industry Challenges
- Interventional cardiology fellowship pipeline:Training program capacity constraints in the United States and Germany are limiting operator availability to support procedure volume targets for complex endoluminal interventions.
- ISO 10993 biocompatibility testing backlog:Contract laboratory capacity shortages are extending device certification timelines by 6-12 months, compressing product launch windows against competitor filings.
- Legacy hospital information system integration:Robotic-assisted platforms require middleware development to connect with proprietary electronic health record architectures, increasing implementation cost and timeline uncertainty.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Endoluminal Device Systems Market |
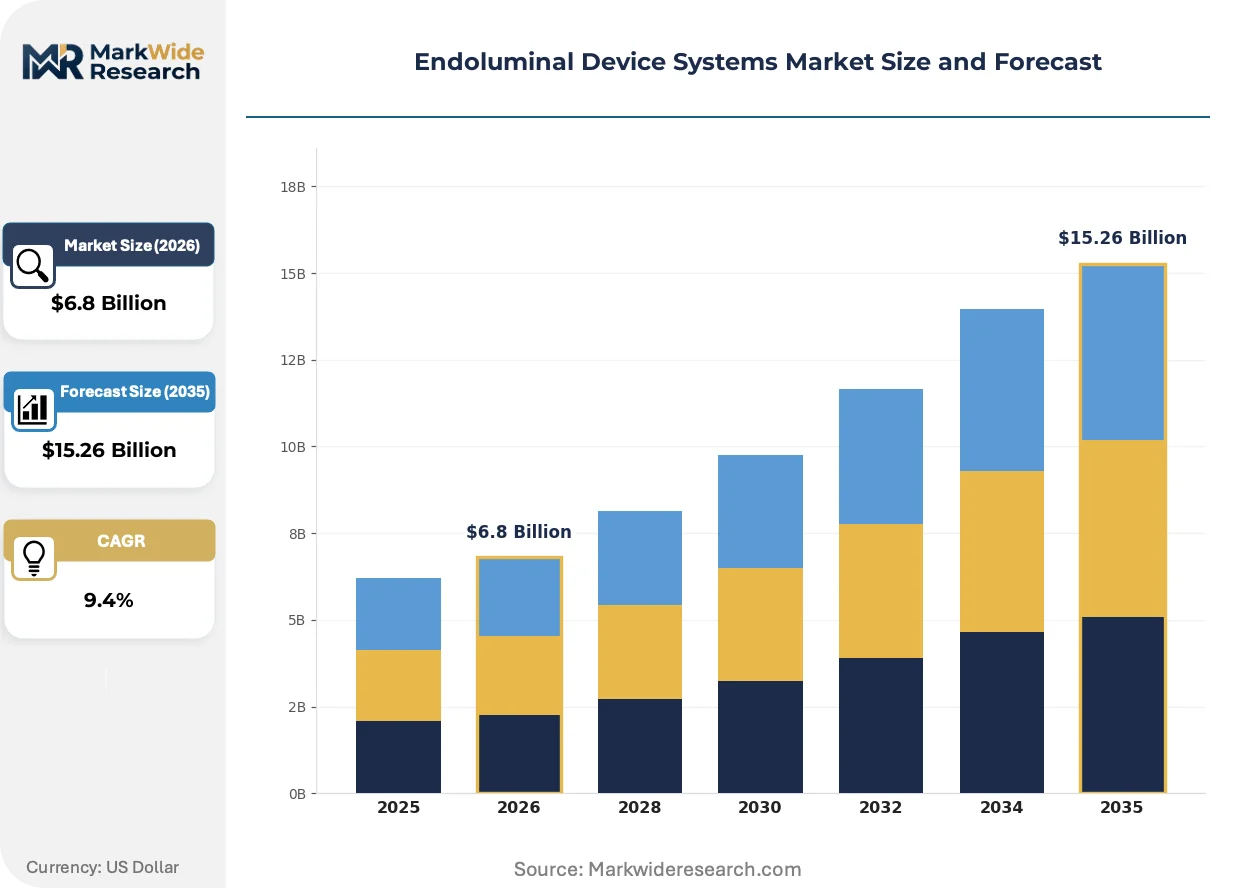
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $15.26 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stents, Balloons, Clips, Retrievers Technology: Bioabsorbable, Drug-Eluting, Coated, Non-Coated End User: Hospitals, Outpatient Clinics, Ambulatory Surgery Centers, Research Institutions Delivery Mode: Minimally Invasive, Robotic-Assisted, Manual, Traditional |
| Companies Covered | Olympus Corporation, CMR Surgical Ltd., Medtronic plc, Asensus Surgical Inc., Noah Medical Inc., Intuitive Surgical Inc., Cook Medical, Microbot Medical Inc., Boston Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Endoluminal Device Systems Market Evolving Landscape
Device architecture is converging with digital navigation and advanced materials science, producing catheter platforms that merge mechanical delivery precision with real-time anatomical feedback and bioresorbable structural elements.
Shape-memory polymer stents are integrating controlled degradation kinetics with radial force maintenance through the critical 6-12 month healing window. Academic medical centers in Germany and Japan are piloting these platforms in younger patient cohorts where permanent implant risks outweigh short-term scaffolding needs. The technology is integrating polymer synthesis expertise from adjacent drug delivery sectors into cardiovascular device manufacturing, compressing development cycles for next-generation platforms.
EU MDR Article 117 requirements for notified body involvement in legacy device recertification are elevating documentation burdens for stent manufacturers with extensive product portfolios. Industrial consequence includes portfolio rationalization as firms withdraw marginal SKUs rather than absorb clinical evaluation costs. Peripheral vascular applications face disproportionate impact given smaller addressable volumes relative to interventional cardiology mainstays, with manufacturers prioritizing coronary drug-eluting stent renewals.
Hospital procurement committees are consolidating vendor relationships through multi-year enterprise agreements that bundle capital equipment, disposables, and service contracts. The independent distributor channel serving smaller community hospitals is contracting as health system centralization concentrates purchasing authority. This pattern is most visible in the United States, where integrated delivery networks now control 60% of interventional cardiology procedure volume and negotiate directly with manufacturers for system-wide pricing.
Endoluminal Device Systems Market Segmentation
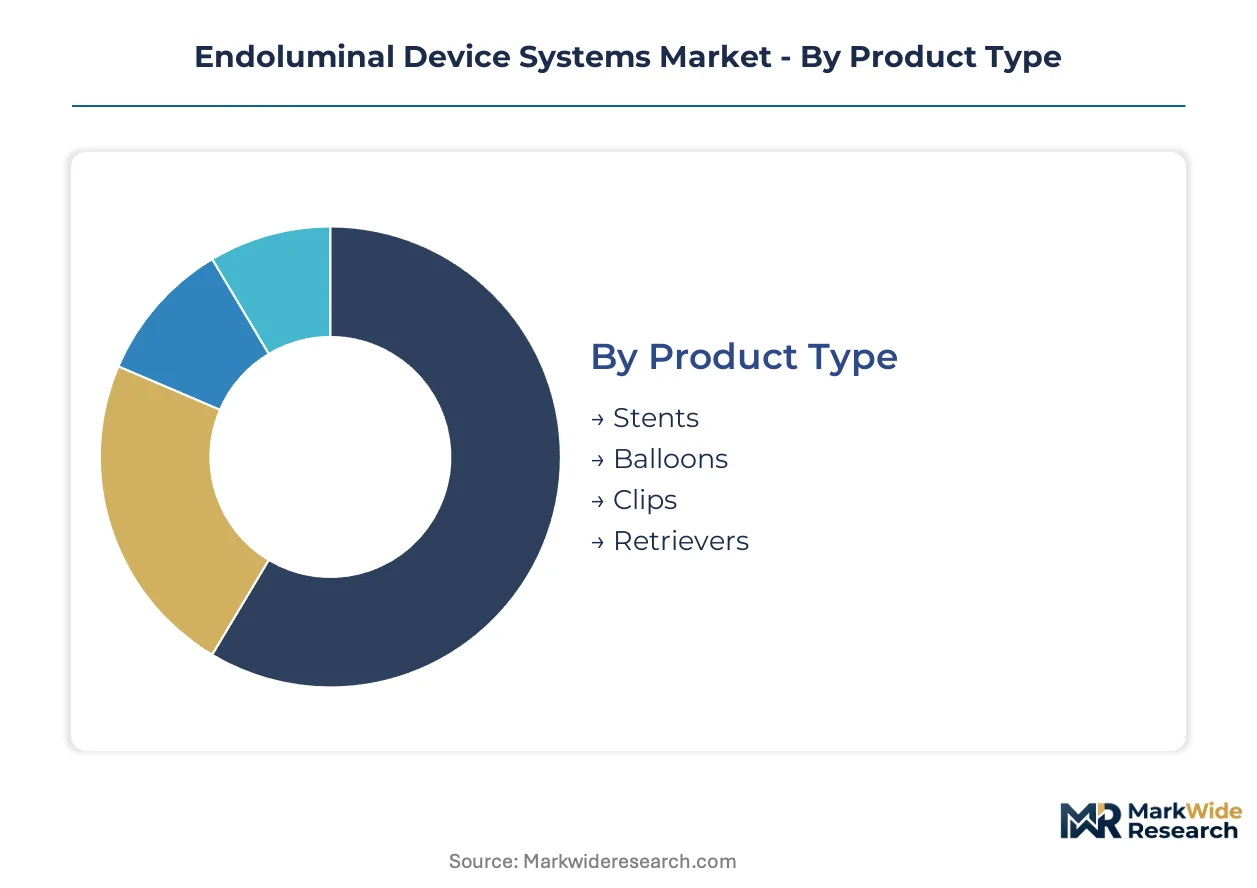
Endoluminal device systems fragment across four dimensions that determine procurement patterns and margin structures. Product type and technology tiers drive clinical differentiation, while delivery mode and end-user channel dictate capital intensity and reimbursement pathways.
Product Type:
Replacement cycles vary sharply across product categories, with stent platforms requiring scheduled surveillance and reintervention driving recurring demand.
- Stents:Self-expanding nitinol and balloon-expandable stainless steel platforms dominate vascular and gastrointestinal luminal scaffolding. Demand clusters in interventional cardiology suites at academic medical centers in the United States and Germany, where drug-eluting iterations command premium positioning against bare-metal alternatives.
- Balloons:Angioplasty catheters with compliant, non-compliant, and cutting balloon configurations enable predilation and postdilation workflows. Peripheral vascular specialists in Japan's regional hospitals favor high-pressure non-compliant designs for calcified lesions, though commodity pricing pressures compress margin contribution in high-volume coronary applications.
- Clips:Mechanical hemostasis and closure devices address luminal perforation and fistula management.
- Retrievers:Thrombectomy and foreign body extraction systems serve emergent intervention protocols.
Volume placements concentrate in stents; the faster expansion belongs to balloons as peripheral vascular indications broaden.
Technology:
Technology tiers stratify by clinical outcome differentiation and manufacturing complexity, with coating chemistry capabilities separating premium positioning from commodity supply.
- Bioabsorbable:Poly-lactic acid and polyglycolic acid scaffolds degrade through hydrolysis after 12-24 months, eliminating permanent implant risks. European regulatory pathways through notified bodies under EU MDR Article 117 are accelerating clinical evaluation requirements, favoring manufacturers with polymer synthesis expertise from adjacent drug delivery sectors.
- Drug-Eluting:Polymer matrices releasing sirolimus, paclitaxel, or everolimus suppress neointimal hyperplasia. Interventional cardiologists in Japanese flagship hospitals prioritize these platforms for diabetic patients with diffuse disease, where restenosis rates drive repeat procedure economics.
- Coated:Passive hydrophilic or hydrophobic surface modifications reduce thrombogenicity without pharmaceutical payload.
- Non-Coated:Bare-metal platforms serve cost-constrained procurement environments and emergent salvage scenarios.
Revenue concentration sits with drug-eluting platforms; bioabsorbable variants are climbing the fastest as polymer engineering matures.
End User:
Customer type determines capital equipment requirements, staffing models, and reimbursement capture rates across the care continuum.
- Hospitals:Integrated delivery networks and academic medical centers anchor procedure volume through 24/7 interventional coverage and complex case referral patterns. United States health systems controlling 60% of interventional cardiology volume negotiate enterprise agreements bundling robotic-assisted platforms with disposable commitments.
- Ambulatory Surgery Centers:Freestanding facilities capture lower-acuity peripheral vascular and gastrointestinal procedures as same-day discharge protocols mature. German outpatient clinics are expanding endoluminal radiofrequency ablation capacity under regional reimbursement carve-outs for varicose vein intervention.
- Outpatient Clinics:Physician office-based labs serve diagnostic and surveillance functions with limited intervention capability.
- Research Institutions:Academic consortia pilot next-generation bioabsorbable and robotic platforms under investigational device exemptions.
Procedure volume concentrates in hospitals; ambulatory surgery centers are gaining share fastest as anesthesia protocols enable same-day discharge.
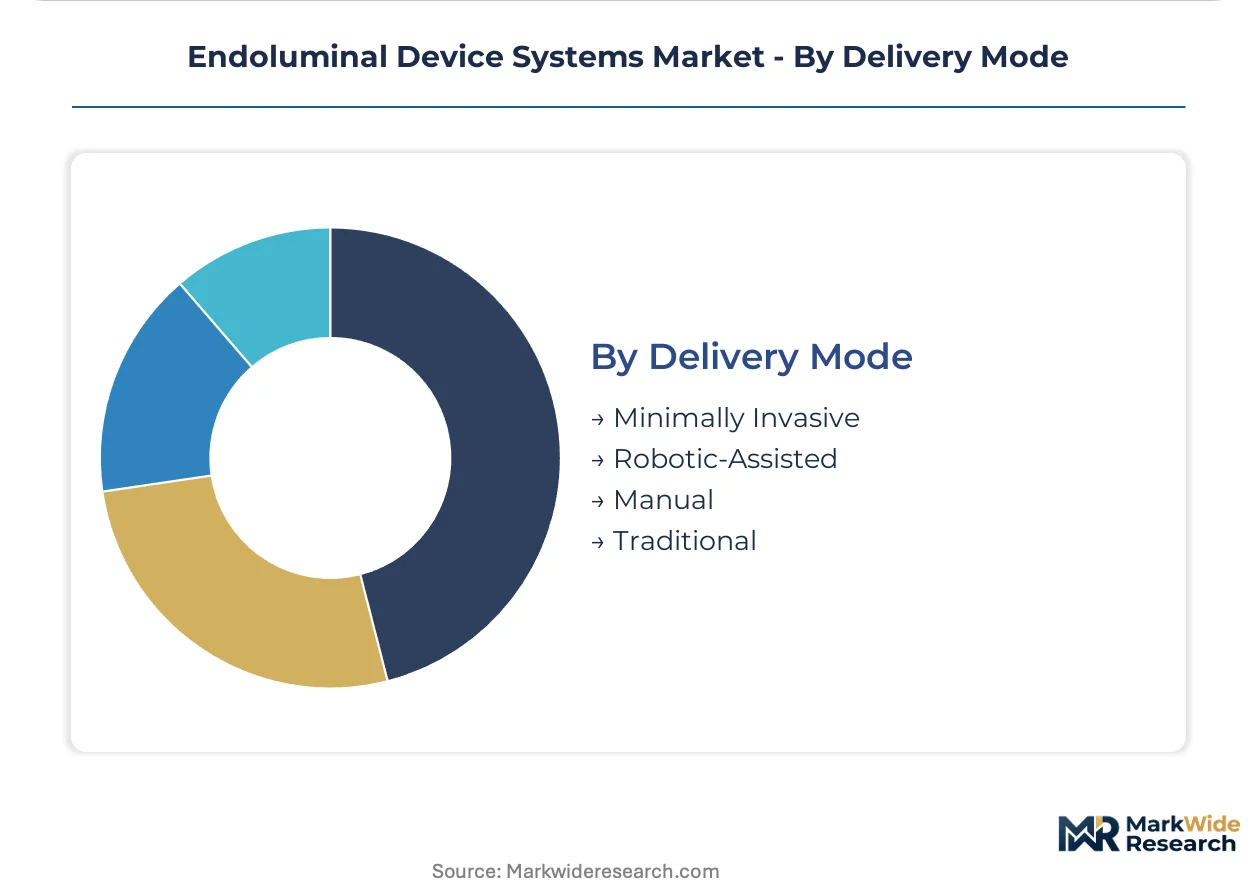
Delivery Mode:
Capital intensity and per-procedure economics diverge across delivery modalities, shaping hospital procurement committee trade-offs between upfront investment and operational flexibility.
- Minimally Invasive:Catheter-based access through femoral or radial approaches has displaced open surgical alternatives across vascular and gastrointestinal applications. Japanese PMDA reimbursement pathways sustain procedure volume expansion among elderly cohorts with comorbidities precluding conventional surgery.
- Robotic-Assisted:Flexible robotic architectures enable sub-millimeter navigation precision in tortuous anatomy. Seoul's flagship cardiac centers under South Korea's MFDS accelerated review pathway are piloting these systems for complex peripheral vascular interventions, though capital expenditure requirements constrain community hospital adoption.
- Manual:Operator-dependent catheter manipulation remains standard for emergent and resource-constrained settings.
- Traditional:Open surgical access retains preference for failed endoluminal interventions and anatomic variants unsuitable for catheter delivery.
Procedure volume concentrates in minimally invasive delivery; robotic-assisted platforms are expanding most quickly where capital budgets and specialist training align.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Minneapolis anchors North American endoluminal device manufacturing, hosting Medtronic's integrated catheter production campus and interventional cardiology training consortiums that feed specialist pipelines across the Upper Midwest corridor.
United States
FDA premarket approval pathways for bioabsorbable stents demand extended clinical evidence packages that compress effective patent windows. Integrated delivery networks controlling 60% of interventional cardiology volume negotiate enterprise agreements bundling capital equipment with disposable commitments. The Minneapolis-St. Paul corridor concentrates catheter manufacturing and physician training infrastructure.
Germany
EU MDR Article 117 recertification mandates are accelerating portfolio rationalization among stent manufacturers with extensive legacy SKUs. Notified body capacity constraints extend clinical evaluation timelines for peripheral vascular platforms. The Baden-Württemberg cluster around Tübingen and Freiburg anchors shape-memory polymer research consortia piloting next-generation scaffolds.
Japan
PMDA reimbursement carve-outs for patients over 75 sustain procedure volume expansion among comorbid cohorts precluding open surgery. Aging demographics concentrate demand in Tokyo and Osaka metropolitan cardiac centers. Yokohama's Kanagawa Prefecture hosts flagship interventional cardiology suites piloting robotic-assisted delivery systems under accelerated regulatory review.
South Korea
MFDS breakthrough device designation enables faster market entry for robotic-assisted platforms in Seoul's flagship cardiac centers. Capital expenditure requirements constrain community hospital adoption outside the capital region. The Seoul Capital Area concentrates both procedure volume and regulatory expertise for complex peripheral vascular interventions.
Switzerland
Swissmedic alignment with EU MDR standards streamlines market access for manufacturers with existing CE marking. Precision polymer synthesis capabilities from adjacent pharmaceutical sectors compress development cycles for bioabsorbable platforms. The Basel-Zurich corridor integrates materials science expertise from drug delivery into cardiovascular device engineering.
Endoluminal Device Systems Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across catheter manufacturing and robotic platform development. The vendor base stratifies into three tiers: integrated multinationals with captive metallurgy supply, specialized stent manufacturers with coating chemistry differentiation, and emerging robotic navigation entrants. Strategic moves concentrate on backward integration into nickel-titanium alloy supply and enterprise purchasing agreements that lock hospital system volume.
Among integrated multinationals, Medtronic plc and Boston Scientific exemplify the capital-intensive archetype with vertically structured manufacturing footprints. Intuitive Surgical Inc. occupies a distinct position bridging robotic-assisted delivery from abdominal surgery into endoluminal navigation. These three anchors demonstrate how regulatory infrastructure scale and clinical evidence libraries create defensive positioning against novel entrants facing extended FDA and EU MDR approval timelines.
| Leading Market Players |
|---|
| Olympus Corporation |
| CMR Surgical Ltd. |
| Medtronic plc |
| Asensus Surgical Inc. |
| Noah Medical Inc. |
| Intuitive Surgical Inc. |
| Cook Medical |
| Microbot Medical Inc. |
| Boston Scientific |
| Others |
Value Network & Pricing Analysis
Integrated delivery networks controlling 60% of United States interventional cardiology volume negotiate enterprise agreements that bundle capital equipment with disposable commitments, entrenching a contract-based pricing model where volume scale determines tier placement. This buyer concentration compresses margin contribution for commodity catheter systems while preserving premium positioning for robotic-assisted platforms with differentiated navigation capabilities.
Pricing Analysis
Value-based pricing anchors on clinical throughput and patency outcomes, with drug-eluting stent platforms commanding premium positioning against bare-metal alternatives through demonstrated restenosis reduction. Price differentiation rests on coating chemistry sophistication and FDA premarket approval tier, with Japanese PMDA reimbursement carve-outs sustaining premium capture for complex coronary applications. Cost compression in peripheral vascular balloon segments intensifies as German outpatient clinics expand same-day discharge protocols, while robotic-assisted delivery systems face limited price sensitivity among flagship academic centers with capital budget autonomy.
Supply Chain Analysis
Dual-sourcing requirements from United States and German catheter manufacturers mandate multi-supplier qualification for nickel-titanium alloy wire, mitigating concentration risk among specialized metallurgical suppliers in Germany and the United States. Raw material dependencies center on nitinol shape-memory alloys, polymer coating substrates, and bioabsorbable polymer resins. Single-source vulnerability in controlled memory wire production creates input cost volatility, while distribution runs through health system central procurement offices and independent distributor channels serving smaller community hospitals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply constraints in ISO 10993 biocompatibility testing capacity prop pricing power for manufacturers with established regulatory infrastructure, as contract laboratory backlogs extend certification timelines by 6-12 months. This bottleneck sustains margin premiums for incumbents with in-house testing capabilities.
For Market Incumbents: Acquire polymer synthesis capabilities from adjacent drug delivery sectors to compress bioabsorbable scaffold development cycles. Consolidate backward integration into nickel-titanium alloy supply chains to mitigate raw material volatility from German and United States metallurgical suppliers. Defend against emerging robotic navigation entrants by locking hospital system volume through multi-year enterprise agreements that bundle capital equipment with disposable commitments and service contracts. For New Entrants and Emerging Players: Ambulatory surgery centers represent the most penetrable channel as same-day discharge protocols mature for lower-acuity peripheral vascular procedures. Target gastrointestinal luminal oncology applications where endoluminal radiofrequency ablation protocols remain underdeveloped beyond established vascular stenting. Pursue regulatory arbitrage through South Korea's MFDS accelerated review pathway for breakthrough device designation, enabling faster market entry in Seoul's flagship cardiac centers before scaling to broader Asian markets. For Investors and Strategic Acquirers: The window for entry favors manufacturers with captive polymer chemistry capabilities and established EU MDR regulatory infrastructure. Long-term viability centers on five-to-ten year positioning around bioabsorbable platform transitions and robotic-assisted delivery mode reimbursement decisions in Germany and the United States. Watch for inflection signals in hospital procurement committee willingness to absorb capital expenditure for robotic platforms versus per-procedure disposable economics.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Article 117 Recertification Investment | Notified body engagement preserves market access for legacy stent portfolios in Germany and Western Europe. |
| Hospital System Partnership | Enterprise agreements with United States integrated delivery networks lock 60% of interventional cardiology procedure volume. |
| Polymer Synthesis Acquisition | Captive drug delivery expertise compresses development cycles for bioabsorbable scaffold platforms. |
| Reimbursement Strategy | PMDA pathway optimization sustains procedure volume expansion among Japanese patients over 75 with comorbidities. |
| Software Companion Development | Middleware integration with proprietary electronic health record architectures reduces robotic platform implementation friction. |
Research Methodology
Document review covered FDA premarket approval filings, EU MDR notified body guidance documents, and PMDA reimbursement bulletins, complemented by interviews with interventional cardiologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. Secondary validation drew from CMS Medicare procedure data, hospital procurement databases, and SEC 10-K disclosures from publicly traded device manufacturers. Bottom-up procedure volume estimates and top-down market size triangulation anchored the analytical framework.
Segment-level projections across product type, technology tier, delivery mode, and end-user channel fed into value and volume outputs over the projection horizon. CAGRs derived from procedure volume growth trajectories, replacement cycle dynamics, and pricing evolution assumptions. Industry-specific inputs included PMDA reimbursement pathway modifications, EU MDR Article 117 implementation timelines, and ambulatory surgery center capacity expansion rates.
Caveats apply where FDA premarket approval timeline extensions for novel bioabsorbable platforms or ISO 10993 testing capacity constraints could materially shift the outlook. Deviation in robotic-assisted delivery mode reimbursement decisions by German or United States payers would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Deflectable Catheters Market
Medical Devices
Gastric Electrical Stimulators Market
Medical Devices
Asia-Pacific Single-Use Medical Device Reprocessing Market
Medical Devices
Flexible and Semi-Rigid Ureteroscopy Market
Medical Devices
Electronic Skin Patch Market
Medical Devices
Global Oxygen Cylinders and Concentrators Market
Medical Devices
Global Self-Injection Device Market
Medical Devices
Electrical Stimulation Devices (Esds) Market
Medical Devices
South Korea Aesthetic Devices Market
Medical Devices
Asia-Pacific Ostomy Care and Accessories Market
Medical Devices
Needle-Free IV Connectors Market
Medical Devices
Nerve Locator Stimulator Market
Medical Devices
Cervical Artificial Discs Market
Medical Devices
Ophthalmic Microscopes Market
Medical Devices
US Biomedical Sensors Market
Medical Devices
3D Printed Implants Market