
 Artificial Respirator Market | 2026-2036
Artificial Respirator Market Size, Share, and Industry Trends Forecast 2026-2036
Artificial Respirator Market Intelligence
Aftermarket service revenue from long-term maintenance contracts is narrowing as hospitals increasingly utilize in-house biomedical engineering teams for routine upkeep. Philips Healthcare leverages its extensive hospital IT portfolio to bundle ventilation systems with patient monitoring platforms, creating integrated solutions. Drägerwerk AG & Co. KGaA sustains its market position through deep specialization in high-acuity critical care and anesthesia applications. ResMed dominates the non-hospital setting with its strong focus on CPAP and BiPAP devices for sleep apnea management.
An artificial respirator is a medical device that provides mechanical ventilation by moving breathable air into and out of the lungs of a patient unable to breathe sufficiently. These systems deliver precisely controlled parameters such as tidal volume, respiratory rate, and positive end-expiratory pressure (PEEP). Non-invasive ventilation technology is gaining significant share over traditional invasive methods, particularly for treating chronic conditions outside of intensive care. Demand from the home care application segment is expanding faster than the mature critical care segment within hospitals.
Regulatory pathways, including the US FDA's premarket approval (PMA) process and the EU's stringent Medical Device Regulation (MDR), govern market access and product design standards. In parallel, China's NMPA has established specific GB standards for ventilators intended for emergency and intensive care use. Manufacturers must now decide whether to prioritize feature-rich, high-acuity systems for hospitals or develop simplified, connected devices for the expanding home care market.
Market Dynamics
The market's central dynamic is the bifurcation between high-acuity, feature-rich systems for intensive care units and simplified, connected devices for the expanding home care segment. This split forces manufacturers to make critical strategic choices in product development, regulatory pathways, and go-to-market models.
Growth Catalysts
- Public Health Mandates:National health initiatives in countries like China, supported by specific GB standards for ventilators, are expanding critical care capacity and stockpiling for emergency preparedness, creating sustained state-level demand.
- Chronic Condition Prevalence:A rising incidence of chronic obstructive pulmonary disease (COPD) and other respiratory ailments in aging populations globally fuels consistent demand for long-term, non-invasive ventilation in home care settings.
- Non-Invasive Technology:The development of more comfortable and effective interfaces for non-invasive ventilation (NIV) is accelerating its adoption over traditional invasive methods, particularly for patients outside of the ICU.
Market Restraints
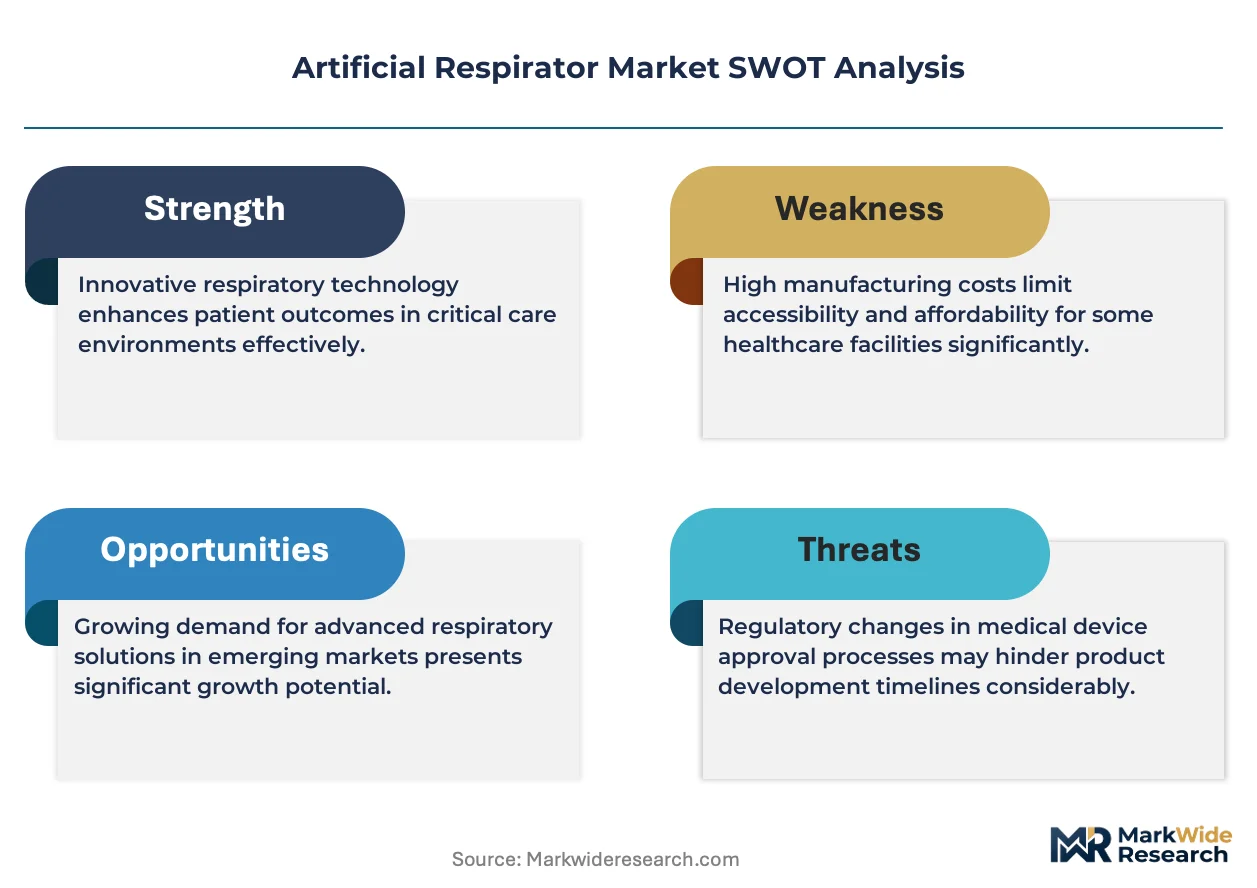
- Regulatory Compliance Burden:Stringent regulations like the EU's Medical Device Regulation (MDR) increase the time, cost, and complexity of achieving and maintaining market access, creating significant barriers for new entrants and smaller manufacturers.
- In-House Service Substitution:Large hospital systems are increasingly developing their own biomedical engineering teams to perform routine maintenance, eroding the lucrative aftermarket service and long-term contract revenue for device manufacturers.
- Component Cost Volatility:The reliance on specialized electronic components, such as pressure sensors and microcontrollers, exposes manufacturers to supply chain disruptions and price fluctuations that can compress profit margins on finished devices.
Strategic Opportunities
- Connected Home Care Ecosystems:Developing ventilators with integrated connectivity allows for remote patient monitoring, creating opportunities to sell data management platforms and telehealth services to home healthcare providers.
- Integrated Hospital Solutions:There is an opportunity to bundle ventilation systems with larger hospital IT infrastructures, such as electronic health records (EHR) and patient monitoring platforms, offering a single-vendor integrated solution.
- Emerging Market Expansion:Increasing healthcare investments and infrastructure development in regions like Southeast Asia and Latin America present significant white space for both high-acuity and home care ventilator models.
Industry Challenges
- Cybersecurity Vulnerabilities:As ventilators become more connected, ensuring device and patient data security against cyber threats becomes a critical and complex engineering challenge, subject to regulatory scrutiny from bodies like the FDA.
- Interoperability Standards:A lack of universal standards for data communication makes it difficult to ensure that ventilators can seamlessly integrate with the diverse array of patient monitoring systems and hospital IT platforms.
- Clinical Evidence Generation:Meeting the heightened demands for clinical data under frameworks like the EU MDR requires manufacturers to conduct extensive, costly, and time-consuming clinical trials to validate device performance and safety claims.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Artificial Respirator Market |
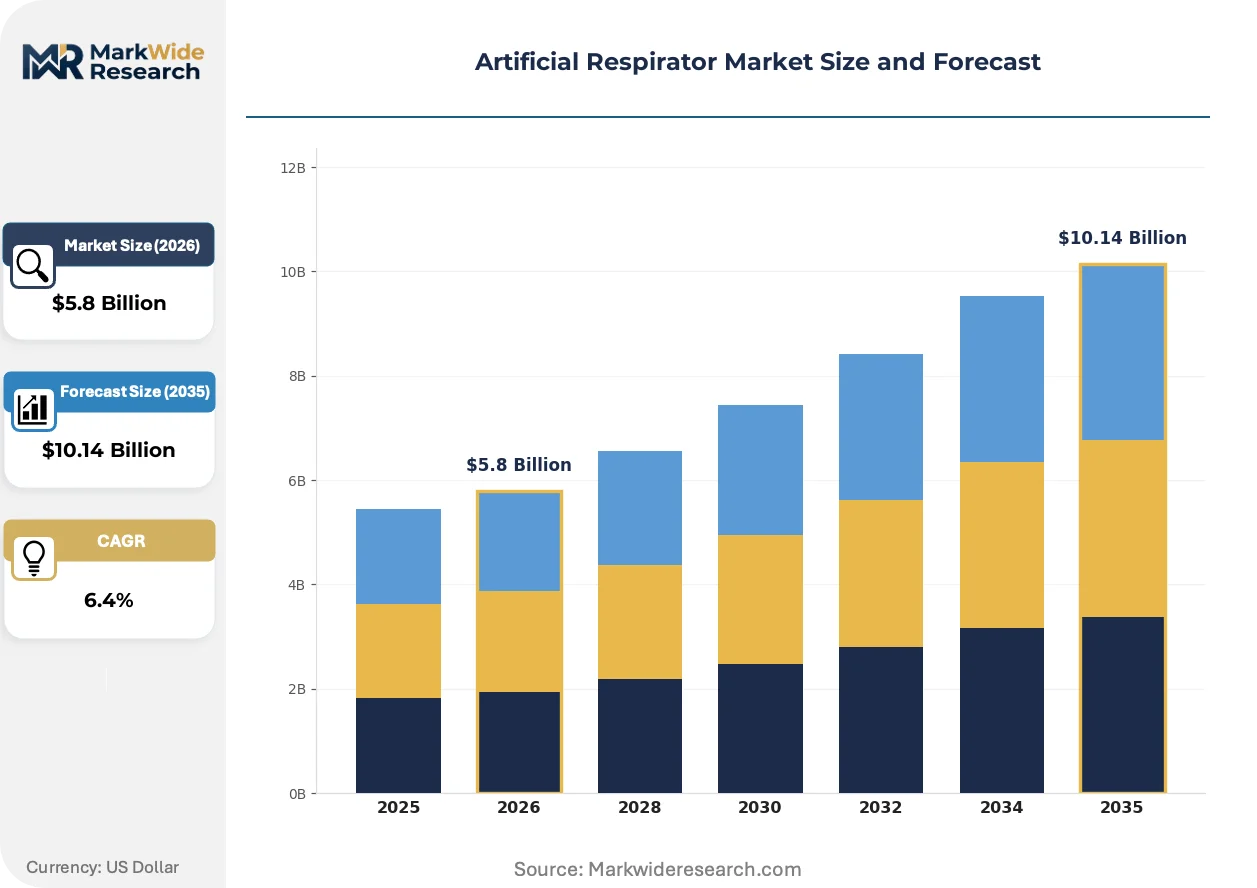
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $10.14 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical Ventilators, CPAP Devices, BiPAP Systems, Portable Respirators Application: Critical Care, Home Care, Anesthesia, Emergency Response End User: Hospitals, Clinics, Home Health Agencies, Emergency Medical Services Technology: Invasive Ventilation, Non-Invasive Ventilation, High-Flow Therapy, Adaptive Ventilation |
| Companies Covered | Drägerwerk AG & Co. KGaA, CareFusion, ResMed, Acutronic Medical Systems, Ambu, Philips Healthcare, Air Liquide Healthcare, GaleMed, Fisher & Paykel Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Artificial Respirator Market Strategic Shifts & Innovations
Product development is splitting into two distinct streams. One path focuses on sophisticated, software-driven ventilators for critical care, while the other prioritizes simplicity, reliability, and connectivity for the non-hospital environment, reshaping the entire value chain.
Ventilation systems are incorporating adaptive algorithms that continuously analyze patient breathing patterns to adjust support levels in real time. Critical care units in advanced hospitals are the primary adopters, seeking to improve patient outcomes and reduce weaning times. This technology is hybridizing traditional mechanical pressure support with AI-driven predictive analytics, enabling a more personalized approach to respiratory therapy.
The European Union's Medical Device Regulation (MDR) is a significant policy shift impacting the market. It mandates more rigorous clinical evidence, post-market surveillance, and unique device identification for enhanced traceability. All manufacturers selling into the EU are affected, forcing many to invest heavily in updating technical files and quality management systems to maintain compliance for their product portfolios.
A clear behavioral shift is the unbundling of device purchases from long-term service agreements. Hospital procurement departments are moving away from comprehensive contracts, instead opting to manage routine upkeep through in-house biomedical staff. This pattern is most visible in large, sophisticated hospital networks in the United States and Europe with the scale to justify specialized internal teams.
Artificial Respirator Market Segmentation
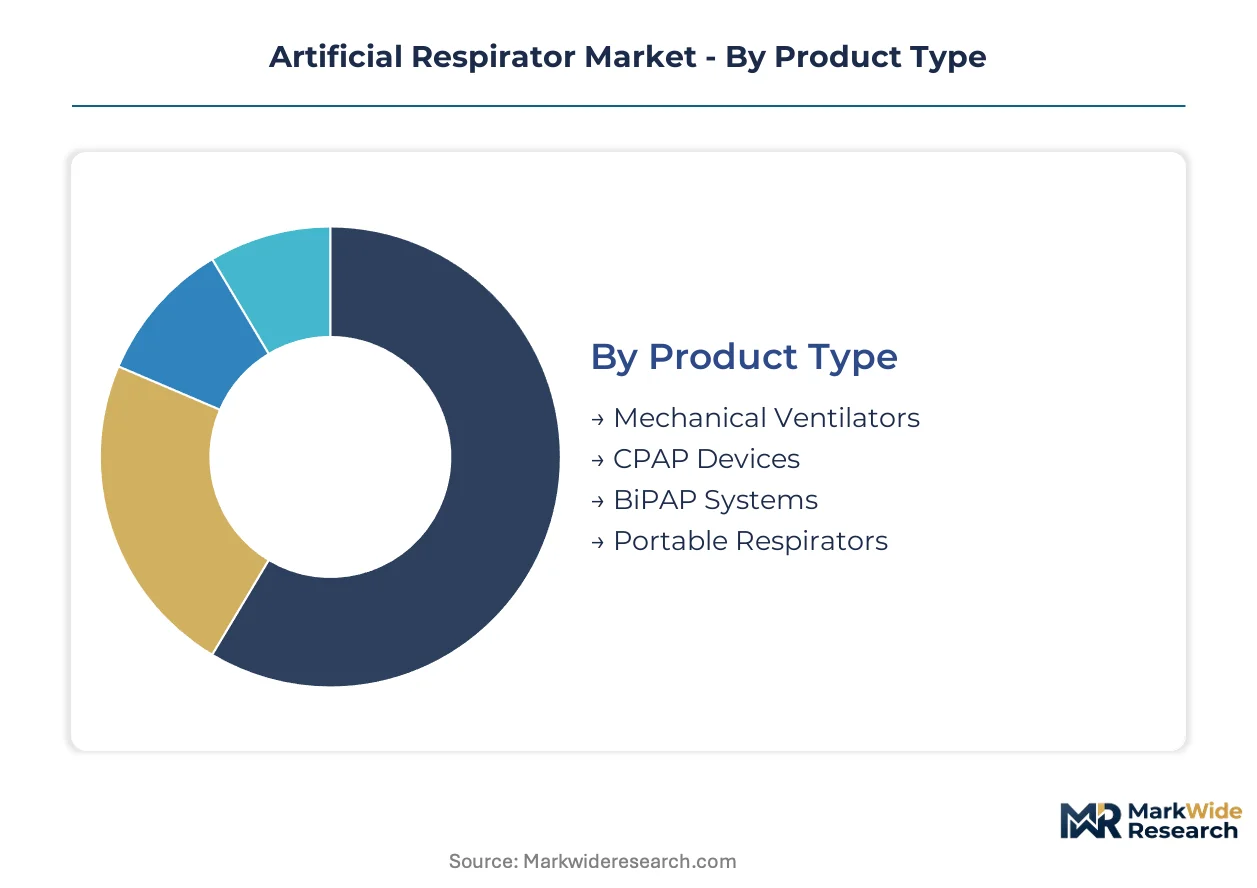
The artificial respirator market's segmentation provides a granular understanding of device types, clinical applications, end-user profiles, and underlying technologies. This detailed breakdown helps manufacturers align product development with specific patient needs and healthcare infrastructure capabilities across diverse global regions.
Product Type:
The product type segmentation differentiates devices based on their primary clinical application and operational environment, influencing design and feature sets.
- Mechanical Ventilators:These are complex systems providing full or partial breathing support, capable of delivering precise tidal volume, respiratory rate, and positive end-expiratory pressure. Demand concentrates in hospital intensive care units globally, driven by severe acute respiratory failure cases.
- CPAP Devices:These devices deliver continuous positive airway pressure, primarily utilized for the management of sleep apnea. Demand is robust in home care settings in countries like the United States and Germany, supported by increasing chronic respiratory diagnoses.
- BiPAP Systems:These provide bilevel positive airway pressure, offering distinct inspiratory and expiratory pressures for patients with conditions like chronic obstructive pulmonary disease.
- Portable Respirators:These are compact, battery-operated devices designed for patient mobility, emergency transport scenarios, and field hospitals.
Established volume favors Mechanical Ventilators; emerging adoption favors Portable Respirators.
Application:
Application segments delineate where artificial respirators are deployed, reflecting varying patient acuity and operational requirements for respiratory support.
- Critical Care:This involves life-sustaining ventilation for severely ill patients experiencing acute respiratory failure within intensive care units. Hospitals in developed economies like Japan and France drive this segment, requiring feature-rich, high-acuity devices.
- Home Care:This segment provides long-term respiratory support for stable patients with chronic conditions, allowing them to receive care outside the hospital. Demand is expanding significantly in China and the United Kingdom, fueled by aging populations and remote monitoring capabilities.
- Anesthesia:This application utilizes ventilation systems to maintain patient respiration and gas exchange during surgical procedures under general anesthesia.
- Emergency Response:This segment deploys robust, portable ventilators for pre-hospital care, mass casualty incidents, and disaster preparedness initiatives.
The Home Care segment is expanding most quickly, driven by a rising prevalence of chronic respiratory conditions.
End User:
End-user categories highlight the primary institutional and care settings procuring and utilizing artificial respirator systems, shaping distribution channels.
- Hospitals:These are major purchasers of high-end mechanical ventilators and integrated patient monitoring systems for critical care and surgical applications. Large hospital networks in countries like Canada and Australia represent significant procurement hubs for advanced devices.
- Home Health Agencies:These agencies facilitate the provision of respiratory therapy and equipment to patients in their residences, enabling long-term chronic disease management. These agencies in the Netherlands and Sweden are increasingly adopting connected devices for remote patient management.
- Clinics:These facilities utilize non-invasive ventilation devices for outpatient treatment of conditions like sleep apnea and other less acute respiratory disorders.
- Emergency Medical Services:These services equip ambulances, air medical transport, and first responders with portable ventilators for immediate patient stabilization during transport.
Hospitals consistently drive demand for high-acuity systems, while Home Health Agencies are experiencing significant growth in connected device procurement.
Technology:
Technology segments reflect the evolution of respiratory support, from traditional methods to advanced, patient-adaptive systems that enhance therapeutic precision.
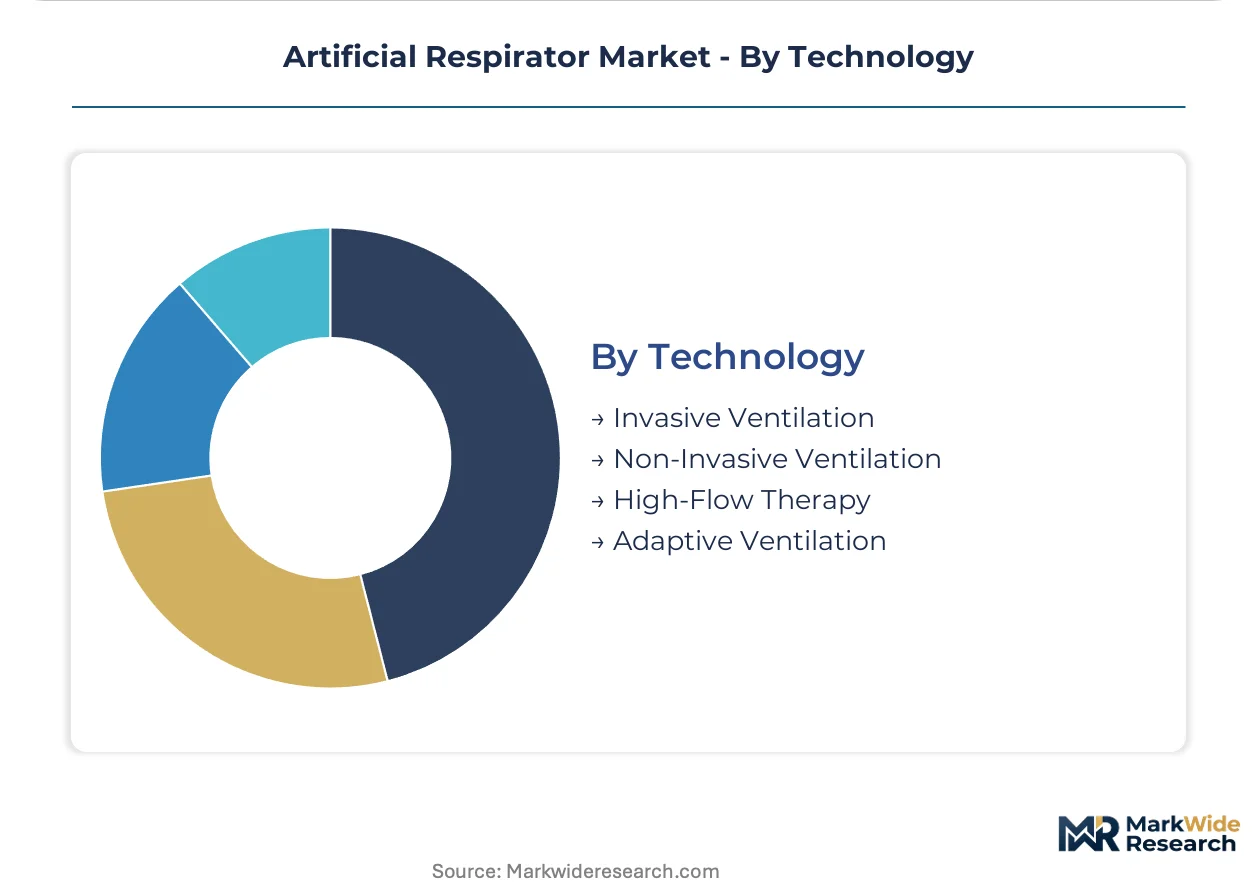
- Invasive Ventilation:This method delivers breathing support through an endotracheal or tracheostomy tube, directly connecting to the patient's airway. It is primarily used in critical care settings for severe respiratory compromise.
- Non-Invasive Ventilation:This technology provides respiratory assistance via masks or nasal prongs, avoiding airway intubation and improving patient comfort. This technology is gaining share in home care settings across the United States and Germany due to improved patient comfort.
- High-Flow Therapy:This involves delivering heated and humidified oxygen at high flow rates, offering a less invasive alternative to traditional oxygen therapy for some patients.
- Adaptive Ventilation:This technology incorporates algorithms to continuously adjust ventilation parameters based on real-time patient physiological feedback, personalizing therapy. Advanced hospitals in countries like Switzerland and Israel are early adopters, seeking improved patient outcomes.
Invasive Ventilation remains foundational for critical care, but Adaptive Ventilation is seeing rapid innovation in personalized therapy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The consumption mix for artificial respirators varies significantly across geographies. While mature markets prioritize advanced critical care systems and home care connectivity, emerging economies focus on expanding basic access and emergency preparedness. This bifurcation shapes regional investment patterns and regulatory priorities.
United States
Demand for artificial respirators in the United States is driven by the high prevalence of chronic respiratory diseases and sophisticated critical care infrastructure. The FDA's premarket approval (PMA) process governs market access for high-risk devices, ensuring stringent safety standards. Major medical device hubs like Boston and Minneapolis are centers for innovation in adaptive ventilation technologies.
Germany
Germany's market benefits from a well-established healthcare system and an aging population requiring long-term respiratory support. The EU's Medical Device Regulation (MDR) significantly influences product design and post-market surveillance for devices sold here. Munich and Stuttgart feature clusters of medical technology firms developing advanced non-invasive ventilation solutions.
China
China experiences substantial demand for ventilators due to public health initiatives and an expanding critical care capacity. The NMPA establishes specific GB standards for ventilators, supporting domestic manufacturing and emergency stockpiling efforts. Shanghai and Shenzhen are key manufacturing bases, focusing on both high-acuity hospital systems and connected home care devices.
Japan
An aging demographic in Japan fuels consistent demand for home care ventilation devices, particularly for sleep apnea management. Japan's PMDA oversees device approvals, emphasizing clinical data and post-market safety for respiratory support systems. Tokyo's medical technology sector explores integration of AI-driven analytics into personalized respiratory therapy.
India
India's market for artificial respirators is expanding, driven by increasing healthcare investments and infrastructure development. The CDSCO regulates medical devices, aiming to ensure quality and availability across diverse clinical settings. Bengaluru and Hyderabad are emerging as innovation hubs for cost-effective and portable ventilation solutions.
Artificial Respirator Market Key Industry Players
Capability concentration sits with one tier; scale advantage sits with another in the artificial respirator market. The market structure is tiered, with established global players dominating high-acuity segments and a diverse group of specialists catering to niche applications. Strategic archetypes include integrated solution providers, critical care specialists, and non-invasive home care device manufacturers. Dominant competitive moves involve portfolio diversification into adjacent patient monitoring and strategic partnerships for regional market access.
Specialists in critical care and anesthesia applications, such as Drägerwerk AG & Co. KGaA (Germany-based), anchor the premium segment with high-acuity systems. Philips Healthcare, a Netherlands-based technology conglomerate, exemplifies the integrated solutions archetype by bundling ventilation systems with patient monitoring platforms. ResMed, an Australia-based medical device company, represents the non-hospital setting focus, primarily through its strong emphasis on CPAP and BiPAP devices for sleep apnea management.
| Leading Market Players |
|---|
| Drägerwerk AG & Co. KGaA |
| CareFusion |
| ResMed |
| Acutronic Medical Systems |
| Ambu |
| Philips Healthcare |
| Air Liquide Healthcare |
| GaleMed |
| Fisher & Paykel Healthcare |
| Others |
Cost & Logistics Intelligence
China's concentrated manufacturing of specialized electronic components directly influences downstream pricing power for artificial respirators. Component cost volatility then compresses profit margins for device manufacturers.
Pricing Analysis
Long-term service contracts for artificial respirators are unbundling, shifting procurement towards per-unit transactional device purchases. Price differentiation stems from device complexity for critical care versus simplified home care models, alongside stringent regulatory certifications like FDA PMA. Pricing pressure intensifies as hospitals internalize routine maintenance, eroding aftermarket service revenue streams. Home care end-users and agencies exhibit higher price sensitivity compared to large hospital networks procuring high-acuity systems.
Supply Chain Analysis
Extended payment terms for key electronic components present a financing challenge for artificial respirator manufacturers. Supply concentration for specialized electronic components, including pressure sensors and microcontrollers, centers heavily in China. This reliance creates vulnerability to commodity price volatility and supply chain disruptions. Downstream distribution runs through direct sales channels for hospital systems and specialized medical equipment distributors serving home health agencies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The artificial respirator market is experiencing a cyclical recovery, driven by renewed public health mandates for emergency preparedness and critical care capacity expansion. This rebound follows periods of fluctuating demand and supply chain adjustments.
For Market Incumbents: Harden existing customer relationships by offering integrated hospital solutions that bundle ventilation systems with patient monitoring platforms. Invest in advanced R&D for adaptive ventilation technologies to maintain a premium in critical care. This strategy counters the threat of in-house service substitution by hospital biomedical teams. Deepen specialization in high-acuity critical care applications, leveraging established brand trust.
For New Entrants and Emerging Players: Establish a beachhead in the rapidly expanding home care segment with simplified, connected devices. Focus on developing integrated connectivity for remote patient monitoring, enabling telehealth services for home healthcare providers. Target emerging markets like Southeast Asia with cost-effective, portable ventilation solutions. This approach leverages white space where established players are less entrenched.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with mid-cap specialists focused on non-invasive home care or niche critical care applications. The long-term viability of this market remains strong, supported by an aging demographic and chronic respiratory disease prevalence. Seek out firms with robust regulatory compliance and strong intellectual property in adaptive ventilation. A key signal to watch is the acceleration of non-invasive ventilation adoption in home care settings.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Launch | Addresses the expanding home care market with remote monitoring capabilities. |
| Regulatory Approval Pathway | Ensures market access and compliance with stringent EU MDR standards. |
| Strategic Partnership | Expands reach and service offerings for home health agencies. |
| Manufacturing Scale-Up | Meets growing demand for simplified ventilators in emerging economies. |
| Software Companion Development | Enhances personalized therapy and patient outcomes in critical care. |
Research Approach
Cross-validation between in-depth primary interviews and extensive secondary research anchors the qualitative findings of this study. Primary insights were gathered from clinicians, hospital purchasing committee members, and home health agency directors. Secondary validation utilized regulatory filings such as FDA PMA applications, EU MDR guidance, and NMPA GB standards. A bottom-up and top-down triangulation approach ensured data integrity.
Calibration of the analytical framework involved aligning historical market data with projected growth drivers across the analysis window. Segmentation dimensions modeled included product type, application, end-user, technology, and country-specific demand patterns. Compound annual growth rates were derived from a blend of historical performance and anticipated market shifts. Key forecast inputs included global chronic respiratory disease prevalence rates and aging population demographics.
Stress conditions across component cost volatility and major regulatory shifts were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect current assumptions regarding market dynamics and technological progression. Geopolitical events or unforeseen public health crises would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Medical Laser Cutting Device Market
Medical Devices
South Korea Respiratory Devices Market
Medical Devices
United States Diabetes Devices Market
Medical Devices
Canada Anesthesia Devices Market
Medical Devices
Mexico Electrocardiograph (ECG) Market
Medical Devices
Asia-Pacific Viscosupplementation Market
Medical Devices
Europe Electroencephalography Devices Market
Medical Devices
Global Traumatic Brain Injury Assessment and Management Devices Market
Medical Devices
Chemotherapy Infusion Pumps Market
Medical Devices
Prefillable Inhalers Market
Medical Devices
Global Cosmetic Implants Market
Medical Devices
Pelvic Floor Stimulators Market
Medical Devices
Electrocardiograph (ECG) Market
Medical Devices
Europe Otoscope Market
Medical Devices
Smart Patches Market
Medical Devices
Cholesterol Monitors Market