
 Global Medical Device Testing and Certification Market | 2026-2036
Global Medical Device Testing and Certification Market Size, Share, and Industry Trends Forecast 2026-2036
Global Medical Device Testing and Certification Market Foresight
Capital-intensity divergence between in-house laboratories and outsourced specialists is redrawing competitive boundaries in medical device validation. Eurofins Scientific leverages its distributed laboratory footprint to compete on turnaround speed for biocompatibility assessment. TÜV SÜD anchors its position through deep integration with German Notified Body procedures and active implant expertise.
Medical device testing and certification encompasses the technical evaluation, quality system audit, and regulatory conformity confirmation required before commercial distribution of instruments intended for diagnosis, treatment, or patient monitoring; core protocols include electrical safety verification per IEC 60601, biocompatibility screening under ISO 10993, and software lifecycle validation per IEC 62304. Diagnostic devices and therapeutic equipment command the largest share of current certification volume, while software verification and sterilization effectiveness testing represent the fastest-expanding methodology categories as connected devices and single-use instrument volumes rise. Performance validation for cardiology applications generates premium pricing due to the life-critical nature of pacing and defibrillation systems.
FDA's Quality System Regulation, the EU's Medical Device Regulation administered by EMA-coordinated Notified Bodies, and Japan's PMDA ministerial ordinances collectively determine market access timelines and documentation depth for manufacturers seeking multi-jurisdictional approval. These frameworks mandate escalating clinical evidence and post-market surveillance, directly expanding the scope and recurrence of third-party testing engagements. Stakeholders must track convergence between FDA's digital health pre-certification pilot and EU AI Act risk classifications for software-as-a-medical-device to anticipate which testing competencies will command priority investment.
Market Dynamics
Hospital procurement departments now mandate third-party validation before contract awards, compressing vendor selection timelines and elevating certification from compliance checkbox to competitive gatekeeper.
Growth Catalysts
- EU Medical Device Regulation:Tightened conformity assessment pathways under MDR expand mandatory Notified Body engagement scope and recurrence for Class IIa through III devices entering European markets.
- Connected device proliferation:Software-as-a-medical-device and AI-integrated diagnostics trigger IEC 62304 and ISO 14971 validation demand that legacy hardware-centric labs cannot fulfill.
- Germany's testing corridor:Munich-Stuttgart concentration of Notified Bodies and specialized laboratories creates geographic clustering that accelerates turnaround for manufacturers targeting EU market access.
Market Restraints
- Notified Body capacity bottleneck:MDR transition reduced EU-designated bodies from over 80 to under 40, extending lead times for conformity assessment beyond 18 months for novel active implantables.
- Phthalate substitution costs:REACH Annex XVII restrictions on DEHP and DBP in medical devices force reformulation of PVC-based tubing and blood bags, requiring expensive biocompatibility revalidation.
- Reference laboratory concentration:Electrical safety and EMC testing for IEC 60601 compliance concentrates among three specialized facility networks, creating single-point vulnerability for manufacturers.
Strategic Opportunities
- Japan's PMDA ministerial ordinance alignment:Mutual recognition agreements between EU Notified Bodies and Japanese Registered Certification Bodies enable consolidated testing protocols for dual-market manufacturers.
- Sterilization validation services:Gamma and e-beam sterilization effectiveness testing for single-use instrument volumes represents methodology expansion beyond traditional biocompatibility screening.
- Digital health pre-certification:FDA's pilot program for software-based devices creates pathway for continuous validation models that replace point-in-time certification with real-world performance monitoring.
Industry Challenges
- Toxicological risk assessment expertise:ISO 10993-17 chemical characterization and toxicological equivalence evaluation requires specialized toxicologists that in-house quality teams rarely retain.
- Multi-jurisdictional dossier divergence:FDA 510(k) substantial equivalence arguments, EU technical documentation, and PMDA stokkai application requirements demand parallel but non-identical evidence generation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Medical Device Testing and Certification Market |
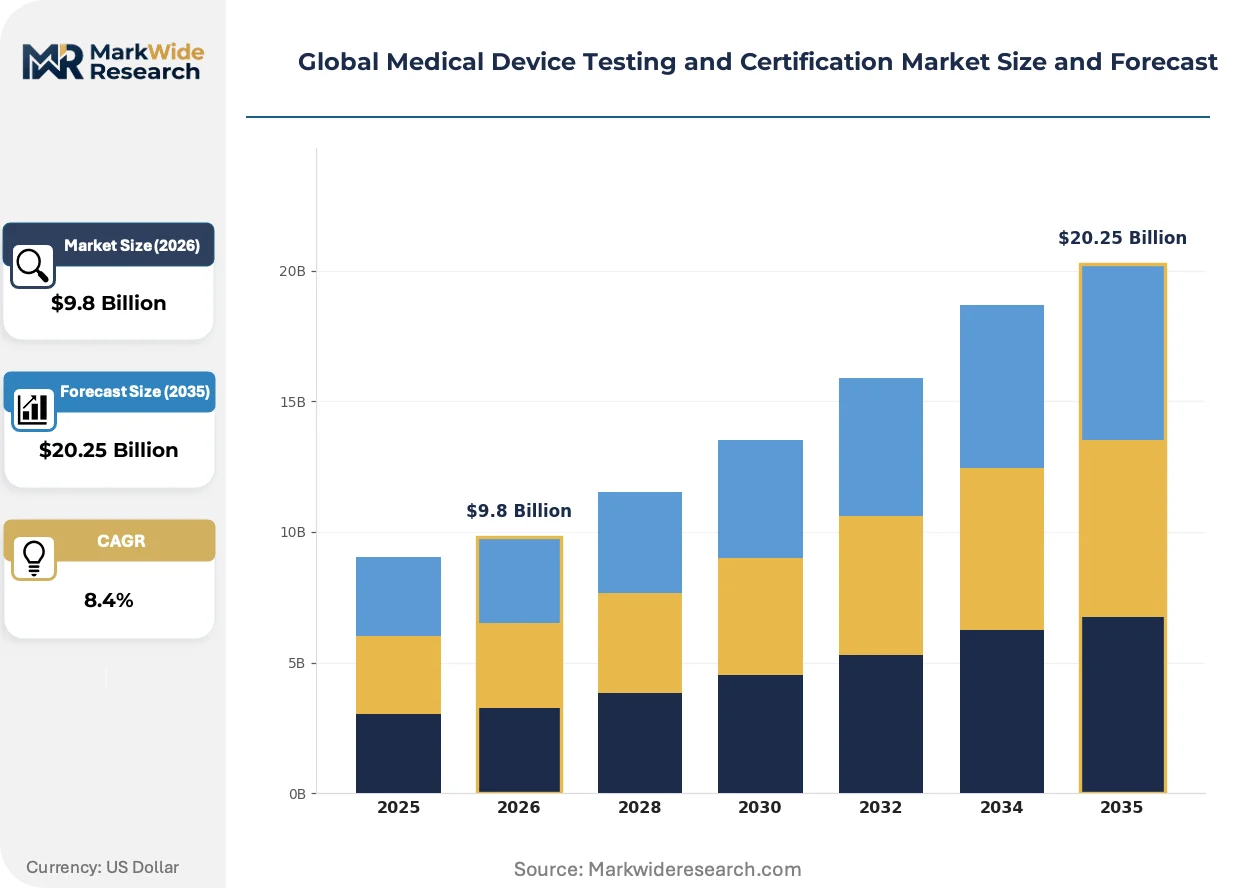
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $20.25 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
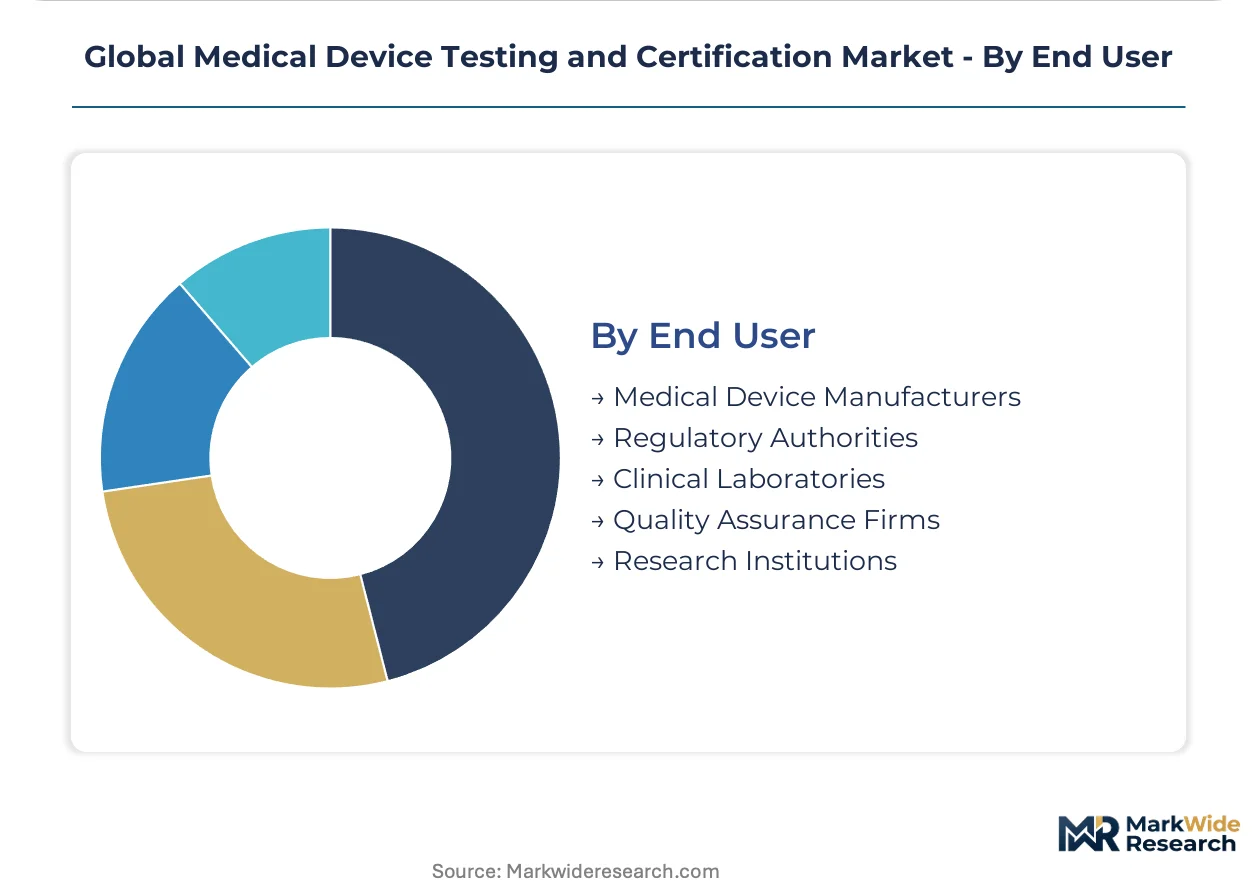
| Segmentation | Product Type: Diagnostic Devices, Therapeutic Equipment, Surgical Instruments, Monitoring Sensors, Imaging Systems Testing Methodology: Electrical Safety Testing, Biocompatibility Assessment, Performance Validation, Software Verification, Sterilization Effectiveness Application Area: Cardiology, Neurology, Orthopedics, Respiratory Care, Diabetes Management End User: Medical Device Manufacturers, Regulatory Authorities, Clinical Laboratories, Quality Assurance Firms, Research Institutions |
| Companies Covered | Eurofins Scientific, SGS SA, Intertek Group, TÜV SÜD, British Standards Institution, Bureau Veritas, WuXi AppTec, UL Solutions, TÜV Rheinland, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Medical Device Testing and Certification Market Shifts & Advancements
Validation methodologies are fragmenting between accelerated in-silico pathways and expanded physical testing matrices as software complexity and biological interaction depth both intensify simultaneously.
Computational modeling for biocompatibility assessment is bifurcating the testing landscape. Medical device manufacturers with mature quality systems now adopt in-silico toxicological screening to reduce animal study dependency. This technology is compressing early-phase validation timelines while creating capability gaps at mid-tier contract research organizations lacking bioinformatics infrastructure.
REACH Annex XVII phthalate restrictions are forcing material transitions across cardiovascular and infusion device portfolios. The regulation mandates DEHP elimination in neonatal and maternity care applications by 2025. German manufacturers are responding fastest, leveraging existing supply chain relationships with polymer compounders to secure alternative plasticizer validation ahead of enforcement deadlines.
Consolidated purchasing by US health system GPOs is elevating certification documentation to contract preconditions. Premier and Vizient now require ISO 13485 audit summaries and FDA establishment registration verification before vendor onboarding. This shift is most visible in cardiology device procurement, where hospital systems bundle pacemaker and defibrillator sourcing across multi-year agreements.
Global Medical Device Testing and Certification Market Segmentation
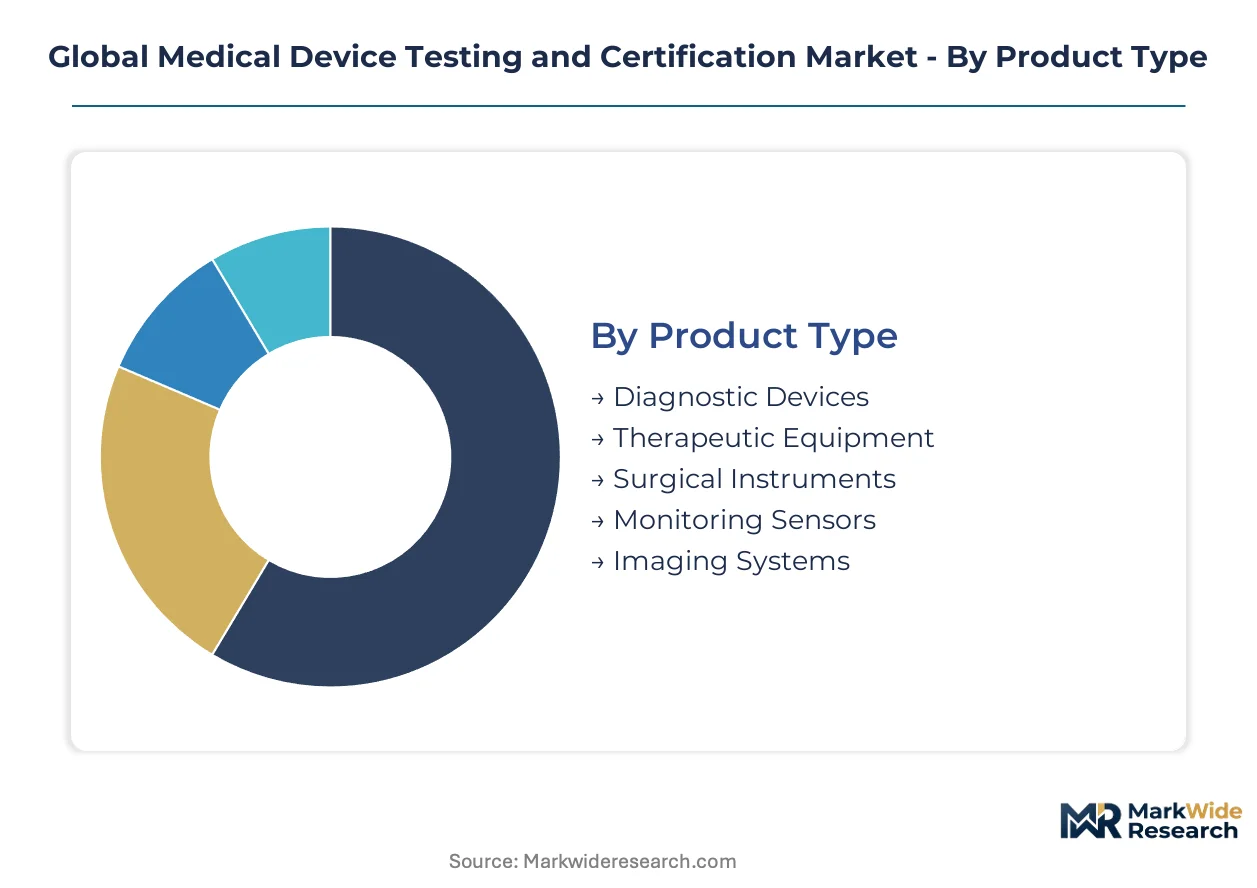
Testing protocols diverge sharply by device risk class and software complexity, creating distinct margin pools that reward specialized capability over generalized service breadth. Manufacturers now select validation partners based on segment-specific accreditation depth rather than geographic convenience alone.
Product Type:
Premium pricing concentrates in active implantable categories where failure carries life-critical consequences and regulatory scrutiny intensifies.
- Diagnostic Devices:In-vitro diagnostic platforms and point-of-care instruments require ISO 13485 quality system audits alongside analytical performance verification. Demand clusters in Germany's Munich-Stuttgart testing corridor where Notified Bodies maintain specialized IVD expertise under EU MDR.
- Therapeutic Equipment:Defibrillators, infusion pumps, and dialysis systems demand IEC 60601 electrical safety validation and EMC immunity testing. Cardiology applications command the highest certification fees due to pacing system reliability requirements and FDA premarket approval pathways.
- Surgical Instruments:Reusable and single-use instruments require biocompatibility screening under ISO 10993 and sterilization validation.
- Monitoring Sensors:Wearable patient monitors and connected biosensors trigger software lifecycle validation per IEC 62304.
- Imaging Systems:MRI, CT, and ultrasound modalities require electromagnetic compatibility testing and radiation safety verification.
The dominant share belongs to Diagnostic Devices, while Therapeutic Equipment is closing the gap fastest.
Testing Methodology:
Methodology selection tracks the shift from hardware-centric validation toward software and biological interaction assessment.
- Electrical Safety Testing:IEC 60601 compliance verification for leakage current, grounding integrity, and insulation resistance remains mandatory for all powered devices. Testing concentrates among three specialized facility networks in the US, Germany, and Japan, creating capacity constraints during product launch windows.
- Biocompatibility Assessment:ISO 10993 cytotoxicity, sensitization, and irritation screening evaluates tissue contact risks. REACH Annex XVII phthalate restrictions are forcing material reformulation and expensive revalidation for PVC-based cardiovascular devices.
- Performance Validation:Functional verification against declared specifications under clinical use conditions.
- Software Verification:IEC 62304 lifecycle validation for software-as-a-medical-device and AI-integrated diagnostics is expanding most quickly as connected device submissions multiply.
- Sterilization Effectiveness:Gamma and e-beam dose verification for single-use instrument sterility assurance.
Electrical Safety Testing retains the largest volume share, though Software Verification is expanding most quickly.
Application Area:
Application-driven segmentation reflects the clinical risk tiering that determines regulatory pathway intensity and testing recurrence frequency.
- Cardiology:Pacemakers, defibrillators, and cardiac monitors require the most extensive validation protocols. FDA premarket approval and EU Notified Body conformity assessment for active implantables generate the highest service fees and longest engagement durations.
- Neurology:Deep brain stimulators and seizure monitoring devices demand specialized electromagnetic compatibility testing.
- Orthopedics:Joint replacements and spinal fixation systems require mechanical fatigue testing and biocompatibility screening.
- Respiratory Care:Ventilators and oxygen concentrators require IEC 60601-1-8 alarm system validation.
- Diabetes Management:Continuous glucose monitors and insulin delivery systems combine software verification with biocompatibility assessment.
Cardiology commands the dominant revenue position, while Diabetes Management is gaining share fastest on connected device proliferation.
End User:
End-user segmentation reveals divergent procurement patterns between integrated manufacturers and outsourced quality functions.
- Medical Device Manufacturers:Original equipment manufacturers represent the core demand source, with large-cap firms maintaining captive laboratories and mid-tier companies outsourcing to Eurofins, TÜV SÜD, and specialized contract research organizations.
- Regulatory Authorities:FDA, EMA-coordinated Notified Bodies, and Japan's PMDA engage testing laboratories for reference method validation and compliance monitoring.
- Clinical Laboratories:Hospital-based and independent labs require IVD instrument validation for laboratory-developed tests.
- Quality Assurance Firms:Third-party auditors and consultants subcontract specialized testing for client certification support.
- Research Institutions:Academic medical centers and contract research organizations require preclinical device validation.
Medical Device Manufacturers retain the dominant share, though Regulatory Authorities are expanding their direct testing engagement fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement departments in the United States exhibit the lowest price elasticity, accepting premium certification fees for life-critical devices, while emerging market manufacturers in India and Brazil remain highly sensitive to validation costs, driving demand for consolidated multi-market testing protocols.
United States
FDA premarket approval pathways for Class III active implantables generate the highest testing fees globally, with cardiology device submissions requiring extensive clinical evidence packages. The agency's Quality System Regulation mandates recurring audits that sustain long-term laboratory engagement. Minneapolis and Boston host dense clusters of medical device headquarters that co-locate quality teams with specialized testing partners.
Germany
EU Medical Device Regulation conformity assessment concentrates demand among Munich-Stuttgart Notified Bodies, creating geographic clustering that accelerates turnaround for manufacturers targeting European market access. ECHA REACH Annex XVII phthalate restrictions force material reformulation and expensive biocompatibility revalidation for PVC-based cardiovascular devices. Stuttgart's polymer compounder ecosystem enables rapid alternative plasticizer validation ahead of enforcement deadlines.
Japan
PMDA ministerial ordinances for software-as-a-medical-device trigger IEC 62304 lifecycle validation demand that legacy hardware-centric labs cannot fulfill. Mutual recognition agreements between EU Notified Bodies and Japanese Registered Certification Bodies enable consolidated testing protocols for dual-market manufacturers. Tokyo and Osaka maintain specialized electromagnetic compatibility testing facilities for deep brain stimulators and seizure monitoring devices.
China
NMPA medical device registration regulations mandate escalating clinical evidence and post-market surveillance, directly expanding third-party testing engagement scope. Domestic manufacturers seeking export certification to EU and US markets drive demand for dual-accredited laboratories. Shanghai and Suzhou concentrate specialized contract research organizations serving both local registration and international market access requirements.
India
CDSCO medical device rules create compliance complexity for domestic manufacturers expanding into regulated export markets, elevating demand for internationally accredited testing partners. Cost-sensitive mid-tier device companies prioritize laboratories offering consolidated FDA-EU-CDSCO testing packages. Hyderabad and Bangalore host emerging clusters of quality assurance firms subcontracting specialized validation for client certification support.
Global Medical Device Testing and Certification Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with scale-driven multinational laboratories competing against regionally anchored Notified Bodies and technology-focused software validation boutiques. The market structure rewards accreditation depth over geographic breadth, as manufacturers select partners based on segment-specific regulatory recognition. Three archetypes dominate: diversified testing conglomerates with distributed laboratory footprints, German-engineered Notified Bodies with deep EMA coordination, and Asia-Pacific contract research organizations serving cost-optimized validation needs. Competitive moves center on strategic partnerships with polymer compounders for rapid material revalidation and geographic expansion into Japan's PMDA-aligned certification corridors.
Within the diversified testing conglomerate tier, Eurofins Scientific and SGS SA exemplify scale-driven positioning through distributed laboratory networks that compete on turnaround speed for biocompatibility assessment. TÜV SÜD occupies a distinctive position among German-engineered Notified Bodies, anchoring its market presence through deep integration with EMA-coordinated conformity assessment procedures and active implant expertise. WuXi AppTec represents the Asia-Pacific contract research archetype, serving manufacturers seeking consolidated testing protocols across FDA, EMA, and NMPA jurisdictions from a China-based operational footprint.
| Leading Market Players |
|---|
| Eurofins Scientific |
| SGS SA |
| Intertek Group |
| TÜV SÜD |
| British Standards Institution |
| Bureau Veritas |
| WuXi AppTec |
| UL Solutions |
| TÜV Rheinland |
| Others |
Supply & Pricing Matrix
Phthalate substitution in PVC-based cardiovascular devices simultaneously redistributes supply relationships toward German polymer compounders and compresses margins for manufacturers facing REACH Annex XVII revalidation costs. This material transition concentrates pricing power with laboratories capable of rapid toxicological equivalence assessment.
Pricing Analysis
Post-certification surveillance contracts and extended validation service agreements generate lifetime value exceeding initial testing fees by substantial multiples. Three-tier pricing structure across premium, standard, and economy levels separates active implantable validation from diagnostic device screening from sterilization effectiveness testing. Pricing pressure stems from Notified Body capacity constraints extending lead times beyond 18 months for novel devices. Mid-tier manufacturers in India and Brazil exhibit highest price sensitivity, while US hospital procurement departments accept premium fees for life-critical cardiology device certification.
Supply Chain Analysis
Germany and the United States anchor specialized electrical safety and EMC testing infrastructure for IEC 60601 compliance. Testing networks draw from reference laboratory partnerships, accredited toxicologist pools, and polymer compounder relationships for rapid material revalidation. Single-source vulnerability concentrates in gamma sterilization dose verification facilities serving single-use instrument manufacturers. Distribution runs through direct laboratory-manufacturer contracts with GPO-mediated procurement for hospital system validation requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent testing laboratories face substitution pressure from in-silico toxicological screening platforms that compress early-phase validation timelines without animal study dependency.
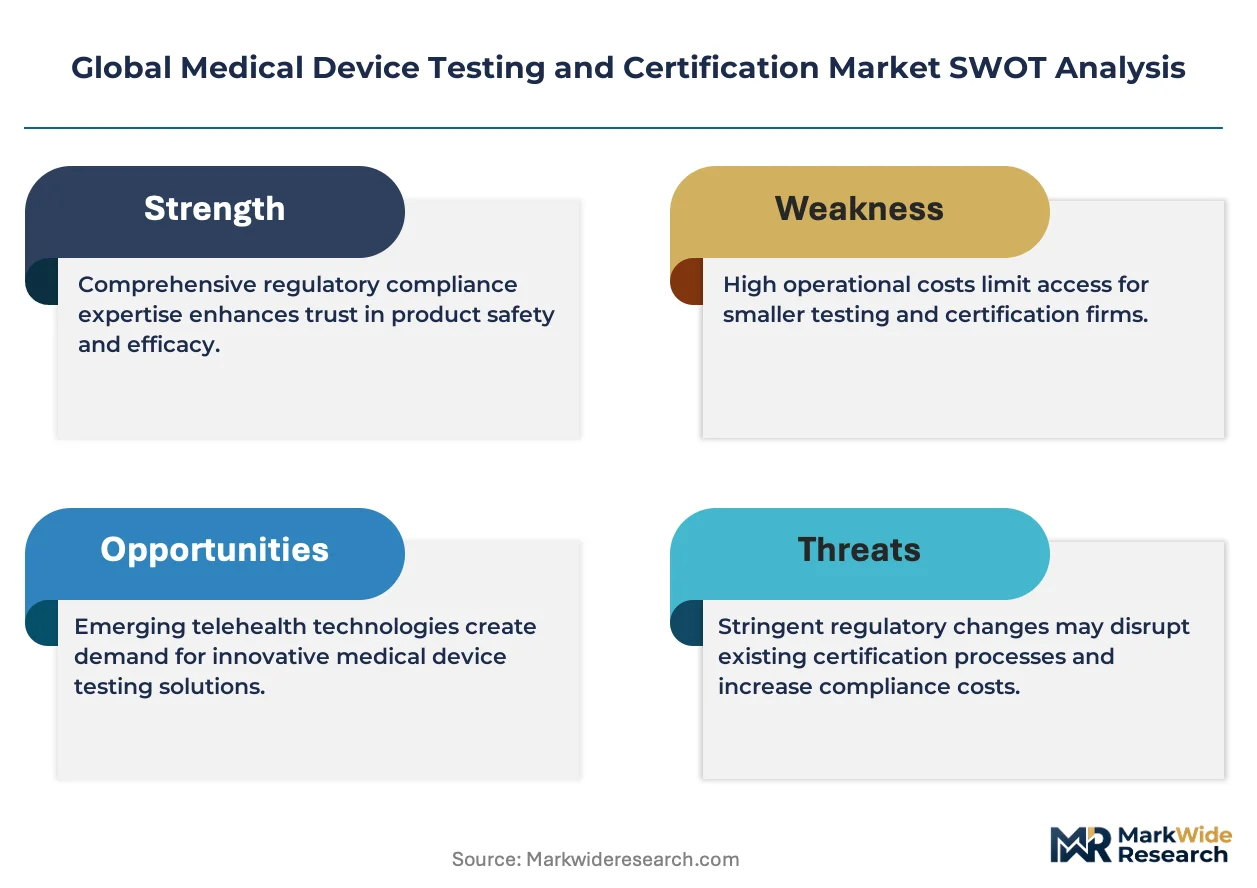
For Market Incumbents: Shield core revenue streams by deepening toxicological risk assessment expertise through specialized ISO 10993-17 chemical characterization capabilities that bioinformatics-driven entrants cannot replicate. Secure exclusive partnerships with Stuttgart polymer compounders for rapid phthalate-free material validation ahead of enforcement deadlines. Vertical integration into sterilization effectiveness testing captures methodology expansion beyond traditional biocompatibility screening. For New Entrants and Emerging Players: FDA's digital health pre-certification pilot offers accelerated pathway for continuous validation models replacing point-in-time certification with real-world performance monitoring. Target software-as-a-medical-device manufacturers seeking IEC 62304 lifecycle validation that legacy hardware-centric labs cannot fulfill. Lead with AI-integrated diagnostic expertise to bypass entrenched relationships in mature therapeutic equipment segments. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed contract research organizations in China's Shanghai-Suzhou corridor serving dual NMPA registration and export certification demand. Five-to-ten year viability favors laboratories with multi-jurisdictional accreditation depth over geographic breadth alone. Monitor convergence between FDA digital health pre-certification and EU AI Act risk classifications as inflection indicator for competency investment priority.| Strategic Initiative | Industry Significance |
|---|---|
| Notified Body Partnership Expansion | Deep EMA coordination secures MDR conformity assessment queue priority for Class III active implantables. |
| In-Silico Toxicology Platform Investment | Bioinformatics infrastructure reduces animal study dependency and compresses early-phase ISO 10993 timelines. |
| Polymer Compounder Alliance Formation | Stuttgart ecosystem relationships enable rapid DEHP-free material validation ahead of REACH Annex XVII deadlines. |
| Software Validation Capability Buildout | IEC 62304 expertise captures connected device and AI-integrated diagnostic submission volume expansion. |
| Dual-Market Testing Protocol Consolidation | EU-Japan mutual recognition agreements reduce redundant evidence generation for manufacturers targeting both jurisdictions. |
Research Methodology
A standing panel of hospital procurement directors, GPO contracts managers, biomedical engineers, and regulatory affairs leads at Notified Bodies provided ongoing calibration across the study period. Primary interview insights combined with secondary validation from FDA 510(k) filings, EMA-coordinated Notified Body designation records, PMDA ministerial ordinance updates, and hospital procurement database extracts. Bottom-up testing volume estimates triangulated against top-down market size benchmarks from accreditation body reports.
Consistency checks validated volume and value outputs against external regulatory submission trend data and laboratory capacity expansion announcements across the projection horizon. Segmentation modeling incorporated device risk class, testing methodology type, application area clinical risk tier, and end-user procurement pattern dimensions. CAGRs derived from regression analysis of historical certification volume growth against regulatory pathway intensity indicators including MDR transition timelines and FDA premarket approval queue depth.
Underlying assumptions cover sustained Notified Body capacity constraints, continued REACH Annex XVII enforcement trajectory, and stable mutual recognition agreement frameworks, with deviation risk concentrated in regulatory harmonization delays and phthalate substitution technology disruption. Recalibration cycles align with material shifts in MDR implementation progress and digital health pre-certification program expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Global Multiplex Assays Market
Testing Services
Aerospace and Life Science Testing Certification Market
Testing Services
Home Blood Testing Devices Market
Testing Services
Redox Meter Market
Testing Services
Influenza Home Testing Market
Testing Services
Asia Pacific Sterility Testing Market
Testing Services
US C-Reactive Protein Testing Market
Testing Services
Global Molecular Quality Controls Market
Testing Services
Self-Urinary Infection Testing Market
Testing Services
Bleeding Disorders Testing Market
Testing Services
Medical Device Testing Services Market
Testing Services
Pharmaceutical Analytical Testing Market
Testing Services
Healthcare Testing, Inspection, and Certification Outsourcing Market
Testing Services
Global Rapid Test Market
Testing Services
Lipase Testing Reagents Market
Testing Services
Global Biological Safety Testing Market