
 India Dental Devices Market | 2026-2036
India Dental Devices Market Size, Share, and Industry Trends Forecast 2026-2036
India Dental Devices Market Foresight
Zirconia is decoupling from premium-only positioning as Indian labs scale domestic milling capacity. Dentsply Sirona leverages its integrated CAD/CAM ecosystem to anchor digital dentistry adoption across metropolitan training centers. Danaher Corporation sustains instrument refurbishment networks that extend equipment life cycles in cost-sensitive settings. 3M competes through adhesive and restorative material portfolios calibrated to tropical climate performance requirements.
Dental devices encompass precision-engineered instruments, implants, equipment, and consumables designed for oral diagnosis, treatment, and rehabilitation, typically manufactured from surgical-grade stainless steel, titanium alloys, or ceramic composites to meet ISO 13485 biocompatibility standards. The primary commercial purpose centers on restoring masticatory function and aesthetic outcomes through minimally invasive interventions. Implants and digital imaging equipment command the deepest margin pools as procedural volumes shift from prosthodontics toward orthodontics and preventive care applications. CAD/CAM technology segments accelerate fastest as chairside milling reduces laboratory turnaround from weeks to hours, though consumables maintain steadier replacement-driven revenue profiles.
CDSCO medical device rules classify dental implants and imaging equipment under escalating risk tiers that mandate clinical evidence for market authorization, while BIS standards enforce dimensional and material specifications for domestically manufactured handpieces and burs. State-level dental council registrations further fragment distribution compliance across Maharashtra, Karnataka, and Tamil Nadu. Stakeholders must monitor how the PLI scheme for medical devices reshapes domestic manufacturing economics against incumbent import dependence.
Market Dynamics
Chairside digital workflows are compressing laboratory turnaround times from weeks to hours across Maharashtra and Gujarat, forcing equipment manufacturers to recalibrate service models around real-time milling support rather than traditional supply relationships.
Growth Catalysts
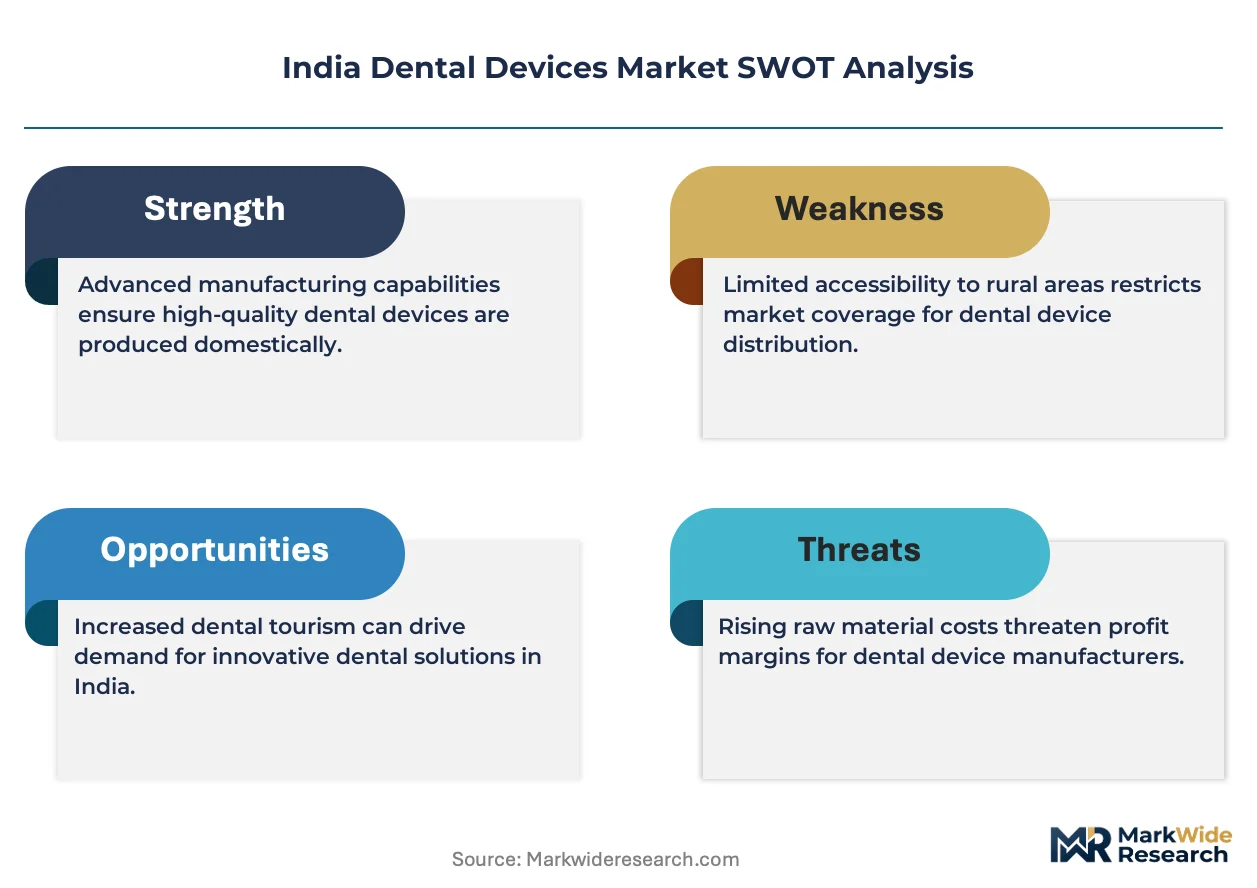
- CDSCO Risk-Based Classification:The regulator's escalating tier structure for implants and imaging equipment mandates clinical evidence, which filters out low-quality imports and creates protected market space for certified domestic manufacturers.
- Tier-2 Private Clinic Expansion:Dental chains in cities like Pune, Surat, and Indore are deploying CAD/CAM units to capture aesthetic dentistry demand outside saturated metros.
- PLI Scheme for Medical Devices:Production-linked incentives are reshaping capital allocation decisions, with domestic milling capacity scaling to reduce zirconia crown import dependence.
Market Restraints
- Titanium Alloy Supply Concentration:Surgical-grade feedstock for implants remains import-dependent, exposing margins to currency volatility and extended lead times from European and Japanese suppliers.
- BIS Certification Friction:Dimensional and material specifications for handpieces and burs create 12-18 month approval windows that delay product launches against uncertified competitors.
- Chairside 3D Printing Substitution:Photopolymer resin printing for surgical guides and temporary restorations threatens conventional milling equipment demand in price-sensitive clinic segments.
Strategic Opportunities
- Karnataka and Tamil Nadu Dental Council Registration Arbitrage:State-level compliance fragmentation creates first-mover advantages for distributors establishing direct regulatory relationships outside Maharashtra-Gujarat strongholds.
- Orthodontic Volume Pivot:Clear aligner manufacturing partnerships with domestic thermoforming facilities address the fastest-growing procedural segment as aesthetic demand shifts from prosthodontics.
- Integrated CAD/CAM-Imaging Convergence:CBCT-linked design software eliminates manual impression workflows, creating bundled equipment upgrade cycles in established metropolitan training centers.
Industry Challenges
- Digital Workflow Technician Scarcity:Chairside milling and intraoral scanning require cross-trained dental technicians that existing vocational programs in Gujarat and Maharashtra have not scaled to produce.
- Legacy Equipment Integration Complexity:Open-architecture CAD/CAM systems must interface with decade-old chair units in cost-sensitive tier-2 clinics, requiring costly middleware development.
- CDSCO Clinical Evidence Generation Burden:High-risk device classifications demand prospective studies that mid-cap domestic manufacturers lack the capital and regulatory affairs capacity to execute.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Dental Devices Market |
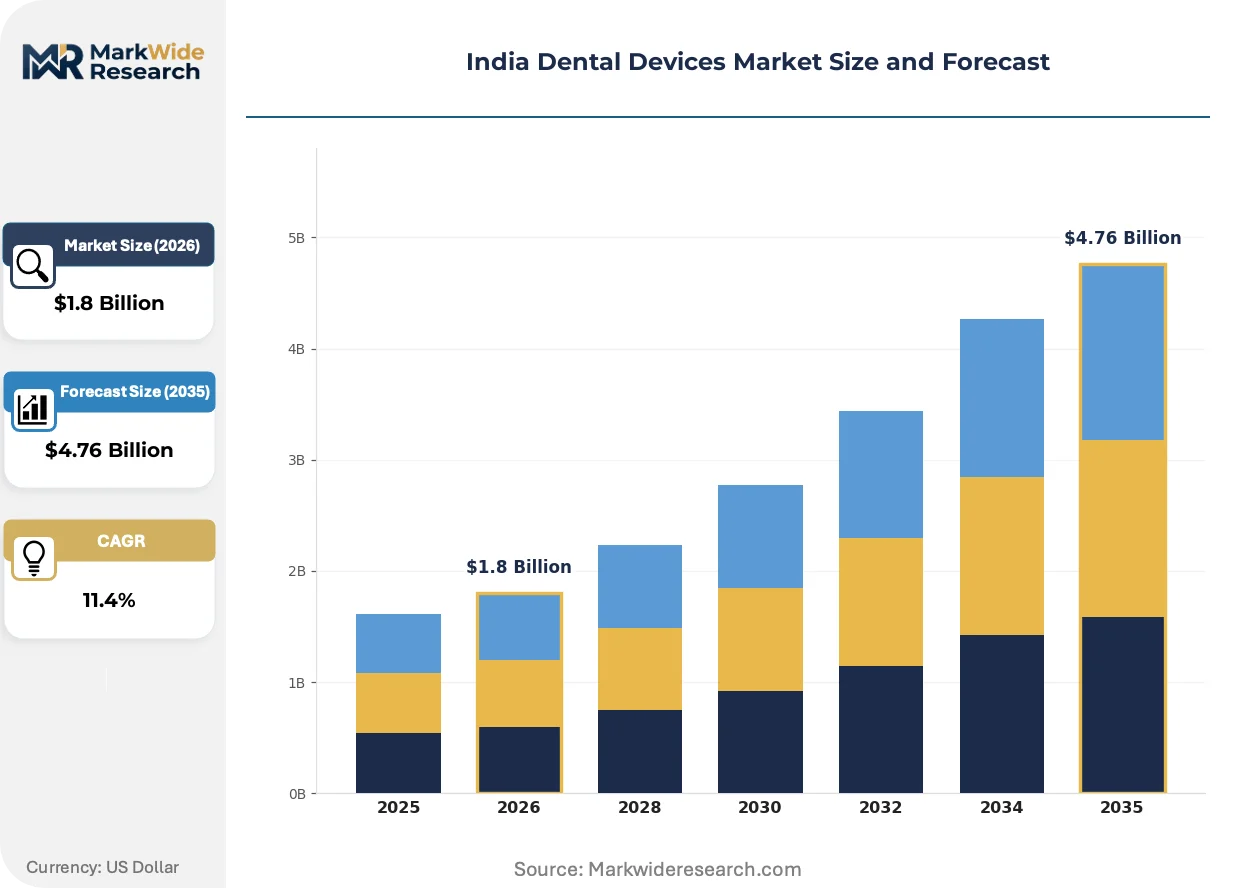
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Instruments, Implants, Equipment, Consumables End User: Dentists, Hospitals, Dental Clinics, Research Laboratories Technology: Digital Imaging, CAD/CAM, 3D Printing, Laser Technology Application: Orthodontics, Prosthodontics, Periodontics, Preventive Care |
| Companies Covered | Siemens Healthineers, Philips Healthcare, Dentsply Sirona, Carestream Health, Danaher Corporation, 3M, Kavo Dental, Align Technology, GE Healthcare, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Dental Devices Market Shifts & Advancements
Digital dentistry infrastructure is fragmenting along workflow integration depth, with standalone milling units giving way to ecosystem-locked platforms that capture recurring consumable revenue through proprietary material cartridges.
Intraoral scanning hardware is unifying diagnostic and restorative functions into single-visit workflows. Tier-2 private clinics in Surat and Pune are adopting these systems at twice the pace of metropolitan counterparts due to laboratory access constraints. The technology is unifying treatment planning with immediate provisional fabrication, collapsing the traditional multi-appointment model that required patient return visits.
CDSCO's 2023 amendment to Medical Device Rules escalates post-market surveillance requirements for Class C and D dental implants. Domestic manufacturers must now maintain adverse event reporting systems that mirror FDA structures, increasing compliance overhead but creating competitive separation from uncertified imports. Implant segment leaders are responding by building in-house clinical affairs teams rather than outsourcing regulatory functions.
After-sales service unbundling is disrupting equipment procurement patterns in Karnataka and Tamil Nadu. Large clinic chains now negotiate hardware and maintenance contracts separately, using third-party biomedical engineering networks to undercut manufacturer service premiums. This behavior is most visible in Bengaluru, where dental group practices have centralized technical support across 15-20 chair locations to drive 40% service cost reductions.
India Dental Devices Market Segmentation
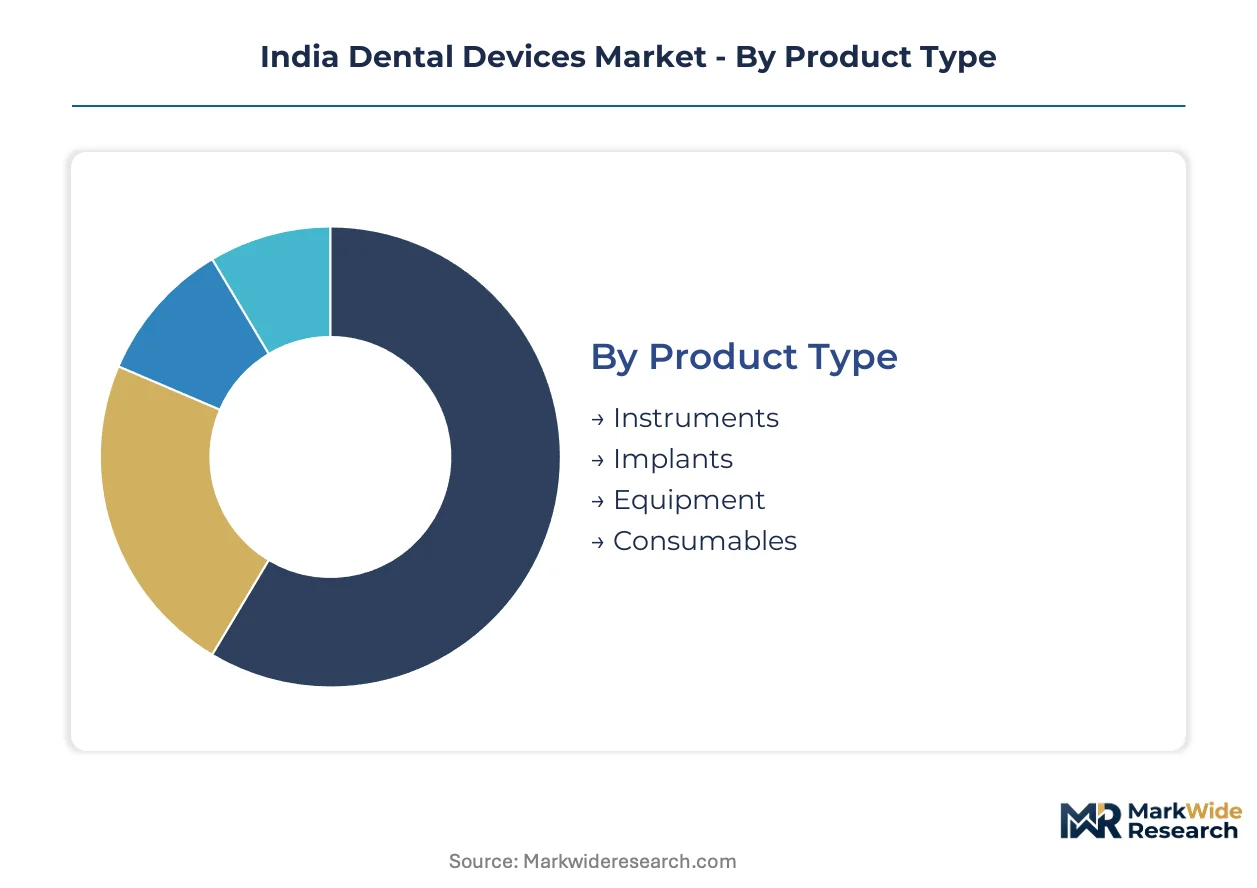
Segmentation in the India Dental Devices Market reveals how procurement priorities diverge between cost-sensitive tier-2 clinics and metropolitan training centers. Product type and technology splits expose where domestic manufacturing incentives reshape competitive dynamics.
Product Type:
Volume concentrates in consumables and hand instruments, while margin pools deepen in implants and digital equipment where CDSCO risk-tiering filters competition.
- Implants:Titanium alloy and zirconia fixtures command premium positioning as CDSCO Class C and D risk classifications mandate clinical evidence for market authorization. Maharashtra and Gujarat dental chains drive demand for domestically milled zirconia alternatives to reduce import dependence.
- Equipment:Chairside CAD/CAM units and CBCT imaging systems capture the steepest expansion trajectory as tier-2 private clinics in Pune and Surat deploy digital workflows to compress laboratory turnaround from weeks to hours.
- Instruments:Surgical-grade stainless steel handpieces and burs face BIS certification friction with 12-18 month approval windows delaying product launches against uncertified competitors.
- Consumables:Adhesive systems, restorative composites, and impression materials generate steadier replacement-driven revenue calibrated to tropical climate performance requirements.
Today's leader: Consumables. Tomorrow's challenger: Equipment.
End User:
Procurement authority fragments across institutional hierarchies, with dental clinics consolidating purchasing power faster than hospital dental departments.
- Dental Clinics:Private chains in tier-2 cities negotiate hardware and maintenance contracts separately, using third-party biomedical engineering networks to undercut manufacturer service premiums.
- Hospitals:Tertiary care centers in Karnataka and Tamil Nadu prioritize integrated CAD/CAM-imaging convergence for CBCT-linked design software that eliminates manual impression workflows.
- Dentists:Solo practitioners in cost-sensitive segments face legacy equipment integration complexity as open-architecture systems must interface with decade-old chair units.
- Research Laboratories:Academic institutions in Maharashtra and Gujarat concentrate demand for high-precision diagnostic equipment tied to training program expansion.
Clinics capture volume leadership. Hospital systems present the integration upside.
Technology:
Maturity gradients separate established digital imaging from emerging laser applications, with adoption pacing tied to technician training availability.
- CAD/CAM:Chairside milling and intraoral scanning unify diagnostic and restorative functions into single-visit workflows, though digital workflow technician scarcity constrains scaling in Gujarat and Maharashtra vocational programs.
- Digital Imaging:Intraoral scanners and CBCT systems are expanding most quickly in tier-2 markets where laboratory access constraints accelerate adoption versus metropolitan counterparts.
- 3D Printing:Photopolymer resin printing for surgical guides and temporary restorations threatens conventional milling equipment demand in price-sensitive clinic segments.
- Laser Technology:Soft-tissue and hard-tissue laser systems remain penetration-limited by capital intensity and specialized training requirements.
Digital Imaging anchors current deployment. 3D Printing reshapes the replacement cycle.
Application:
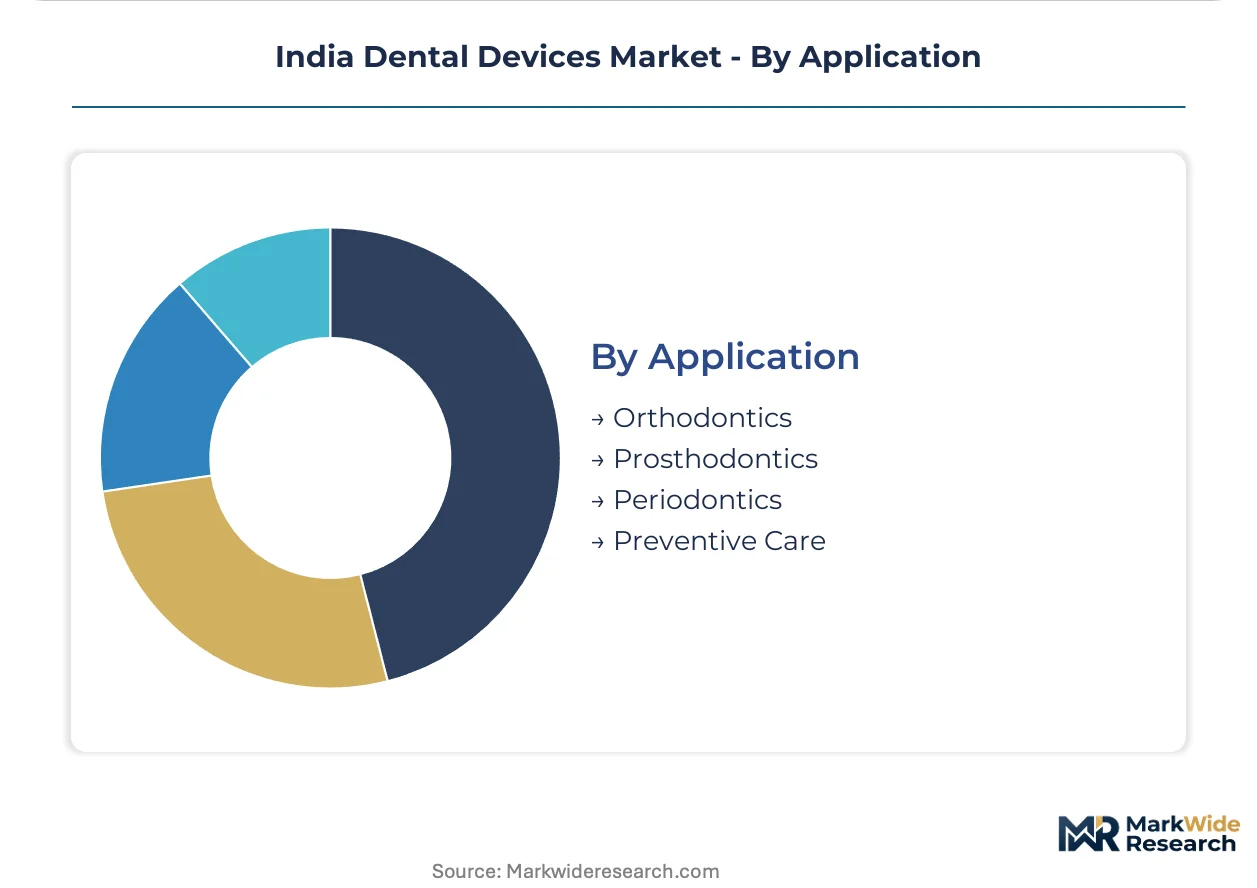
Procedural volume shifts from prosthodontics toward orthodontics and preventive care, reallocating equipment utilization patterns across clinical settings.
- Orthodontics:Clear aligner demand climbs the fastest as aesthetic preferences shift from prosthodontic restoration to preventive alignment, with domestic thermoforming partnerships addressing manufacturing scale.
- Prosthodontics:Crown and bridge fabrication retains volume dominance though margin compression intensifies as chairside milling reduces laboratory outsourcing.
- Periodontics:Implant-supported rehabilitation concentrates in metropolitan training centers with adverse event reporting infrastructure meeting CDSCO post-market surveillance mandates.
- Preventive Care:Diagnostic and early intervention protocols expand through government screening programs and private clinic chain standardization.
Prosthodontics holds volume share. Orthodontics captures the growth premium.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Maharashtra and Gujarat anchor India's dental device industrial base, with manufacturing clusters and training institutions concentrating procurement authority in these western states while Karnataka and Tamil Nadu emerge as compliance arbitrage opportunities.
Maharashtra
Mumbai and Pune dental chains drive demand for chairside CAD/CAM systems as tier-2 private clinics expand digital workflows. CDSCO's escalating risk-tier classifications for implants mandate clinical evidence that filters low-quality imports. The Mumbai-Ahmedabad corridor concentrates domestic zirconia milling capacity scaling.
Gujarat
Surat's laboratory access constraints accelerate intraoral scanner adoption at twice metropolitan rates. BIS dimensional specifications for handpieces create 12-18 month certification windows that delay launches. The Ahmedabad-Surat cluster scales vocational training programs for digital workflow technicians.
Karnataka
Bengaluru dental group practices centralize technical support across 15-20 chair locations to cut service costs. State dental council registration fragmentation creates first-mover advantages for distributors establishing direct regulatory relationships. The Bengaluru-Mysuru corridor prioritizes integrated CAD/CAM-imaging convergence for CBCT-linked design software.
Tamil Nadu
Chennai's tertiary care centers concentrate implant-supported rehabilitation with adverse event reporting infrastructure meeting CDSCO post-market surveillance mandates. The state's dental council registration requirements differ from western India, requiring localized compliance navigation. The Chennai-Coimbatore axis develops clear aligner thermoforming partnerships for orthodontic volume growth.
Telangana
Hyderabad's hospital dental departments negotiate hardware and maintenance contracts separately using third-party biomedical engineering networks. The PLI scheme for medical devices reshapes capital allocation decisions for domestic manufacturers. The Hyderabad-Warangal corridor attracts implant producers seeking alternatives to Maharashtra-Gujarat concentration.
India Dental Devices Market Competitive Landscape
Global majors compete with regional champions across technology integration depth, with the market structure consolidating around ecosystem-locked platforms that capture recurring consumable revenue. Three archetypes dominate: integrated CAD/CAM-imaging conglomerates, instrument refurbishment specialists extending equipment life cycles, and adhesive material formulators calibrated to tropical climates. Competitive moves concentrate on strategic partnerships with domestic thermoforming facilities and capacity expansion in zirconia milling.
Among the integrated technology providers, Dentsply Sirona and Danaher Corporation exemplify ecosystem-locked positioning, while 3M represents material science specialization. These three anchors occupy distinct competitive vectors—Dentsply Sirona through metropolitan training center relationships, Danaher through service network density in cost-sensitive settings, and 3M through climate-adapted formulation portfolios. Their collective presence filters market access for mid-cap domestic manufacturers navigating CDSCO clinical evidence burdens.
| Leading Market Players |
|---|
| Siemens Healthineers |
| Philips Healthcare |
| Dentsply Sirona |
| Carestream Health |
| Danaher Corporation |
| 3M |
| Kavo Dental |
| Align Technology |
| GE Healthcare |
| Others |
Supply & Pricing Matrix
Titanium alloy feedstock for dental implants flows from European and Japanese specialty mills through tiered pricing structures that separate CDSCO-certified Class C devices from uncertified imports. This upstream concentration shapes downstream margin pools, with domestic zirconia milling capacity scaling to capture mid-tier positioning between premium titanium fixtures and economy-grade alternatives.
Pricing Analysis
Input-cost pass-through from surgical-grade titanium and zirconia blanks drives three-tier pricing stratification across premium, standard, and economy levels. Certification grade under CDSCO risk tiers and brand premium from integrated CAD/CAM ecosystems differentiate price bands. Cost compression in the economy tier intensifies as chairside 3D printing substitutes for conventional milling. Solo practitioners in tier-2 cities exhibit highest price sensitivity, while metropolitan training centers prioritize ecosystem-locked platforms with bundled consumable revenue.
Supply Chain Analysis
Photopolymer resin for 3D-printed surgical guides rests on German and Japanese specialty chemical producers, while titanium alloy feedstock draws from Swedish and Japanese metallurgical specialists. Zirconia blanks for chairside milling increasingly source from domestic Indian facilities scaling under PLI incentives. Single-source vulnerability concentrates in surgical-grade titanium where European suppliers dominate implant-grade specifications. Distribution runs through Maharashtra and Gujarat dental manufacturing clusters before fragmenting across state-level dental council registration zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India Dental Devices Market functions as a geographic-arbitrage play where CDSCO clinical evidence requirements in Maharashtra and Gujarat create protected pricing corridors unavailable to uncertified imports entering Karnataka or Tamil Nadu through fragmented state registrations.
For Market Incumbents: Anchor ecosystem-locked CAD/CAM platforms in metropolitan training centers to capture recurring consumable revenue through proprietary material cartridges. Defend against chairside 3D printing substitution by accelerating CBCT-linked design software integration that eliminates manual impression workflows. Prioritize backward integration into domestic zirconia milling capacity to reduce titanium alloy import dependence. For New Entrants and Emerging Players: CDSCO's 2023 Medical Device Rules amendment in India opens a window for first-mover registration arbitrage in Karnataka and Tamil Nadu state dental council zones. Target orthodontic clear aligner manufacturing partnerships with domestic thermoforming facilities as the most penetrable segment. Pursue direct regulatory relationship building with state dental councils rather than distributor-dependent market entry. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-cap domestic manufacturers lack capital for CDSCO clinical evidence generation but possess BIS-certified handpiece and bur production capabilities. Five-to-ten year viability favors targets with established adverse event reporting infrastructure and in-house clinical affairs teams. Watch PLI scheme disbursement velocity as the inflection signal for domestic manufacturing economics shifting against import dependence.| Strategic Initiative | Industry Significance |
|---|---|
| CDSCO Class C/D Registration Pathway | Clinical evidence investment filters low-quality imports and secures premium positioning in Maharashtra-Gujarat corridors. |
| Domestic Zirconia Milling Scale-Up | PLI-supported capacity expansion reduces titanium import exposure and captures mid-tier crown and bridge fabrication demand. |
| State Dental Council Registration Arbitrage | Direct regulatory relationships in Karnataka and Tamil Nadu bypass Maharashtra-Gujarat distributor concentration. |
| CBCT-Linked Design Software Integration | Bundled equipment upgrades eliminate manual workflows and lock in recurring software maintenance revenue. |
| Clear Aligner Thermoforming Partnership | Domestic manufacturing partnerships address fastest-growing orthodontic segment as aesthetic demand shifts from prosthodontics. |
Research Methodology
Multiple input streams — primary interviews with dental clinic chains, biomedical engineering service networks, and CDSCO regulatory consultants; secondary validation through BIS certification databases, CDSCO medical device registration filings, and PLI scheme disbursement records; plus customs trade data on titanium alloy and zirconia blank imports — were reconciled through bottom-up and top-down triangulation. Clinicians at metropolitan training centers, hospital purchasing committees in tertiary care centers, and GPO contracts managers at dental group practices provided demand-side perspective.
Data-stream reconciliation across product type, technology maturity, end-user procurement authority, and application procedural volume yielded segment-specific growth trajectories over the projection horizon. CAGRs were derived from modeled equipment replacement cycles, consumable attachment rates, and procedural volume shifts from prosthodontics toward orthodontics. Forecast inputs incorporated CDSCO risk-tier classification timelines, state dental council registration fragmentation patterns, and domestic milling capacity scaling under PLI incentives.
Revisions become necessary when CDSCO regulatory enforcement intensity shifts, PLI scheme eligibility criteria change, or titanium alloy supply disruptions from European and Japanese suppliers materialize. Forecasts reflect assumptions about continued state-level registration fragmentation and sustained import dependence for surgical-grade feedstock. A small set of named triggers — CDSCO post-market surveillance mandate expansion, PLI disbursement acceleration, and chairside 3D printing resin cost curves — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Dental Contouring Market
Dental Devices
Dental Crown Removal Market
Dental Devices
Australia Dental Devices Market
Dental Devices
Digital Dental Cameras Market
Dental Devices
Dental Prosthetics Market
Dental Devices
Global Dental Hygiene Devices Market
Dental Devices
Dental Whitening Lamps Market
Dental Devices
Global Dental Restorative Market
Dental Devices
United States Dental Implants Market
Dental Devices
Global Dental Obturators Market
Dental Devices
Spain Dental Devices Market
Dental Devices
Dental Sealants Market
Dental Devices
Dental Impression Tray Market
Dental Devices
Dental Scalers Market
Dental Devices
South Africa Dental Devices Market
Dental Devices
Dental Chair Market