
 Global Cardiac Reader System Market | 2026-2036
Global Cardiac Reader System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cardiac Reader System Market Foresight
Home care providers is decoupling from traditional hospital-centric deployment as telemedicine services and remote patient monitoring platforms scale outpatient cardiac surveillance. GE HealthCare Technologies, Inc. leverages its imaging ecosystem to bundle cardiac reader hardware with enterprise data infrastructure. Koninklijke Philips N.V. anchors its position through sleep apnea screening workflows that integrate wearable ECG devices with cloud storage backends. Siemens Healthineers AG competes on AI-based analysis capabilities embedded directly into diagnostic center workflows.
A cardiac reader system comprises electrocardiographic acquisition hardware paired with signal processing software to detect, record, and transmit cardiac electrical activity for clinical interpretation, typically sampling at 250–1000 Hz with 12-lead or single-lead configurations depending on ambulatory versus diagnostic use. These systems serve the core commercial purpose of enabling continuous or event-driven arrhythmia detection outside traditional catheterization laboratory settings. Implantable loop recorders command premium pricing due to invasive placement requirements and extended multi-year monitoring horizons. Wearable ECG devices represent the fastest-expanding product category as Bluetooth connectivity and real-time monitoring protocols reduce latency between symptom onset and clinician notification. AI-based analysis is displacing manual over-reading in high-volume diagnostic centers, concentrating margin pools with vendors that own both algorithm training datasets and regulatory clearances.
FDA premarket review under 21 CFR 870 and CE marking under the EU MDR govern hardware safety and software validation for cardiac reader systems, with the FDA recently intensifying scrutiny of machine-learning-based arrhythmia classifiers. Japan's PMDA and South Korea's MFDS maintain parallel approval tracks that delay market entry for unproven algorithm architectures. Stakeholders must monitor evolving software-as-a-medical-device classifications that could force cloud storage providers into direct regulatory scope.
Market Dynamics
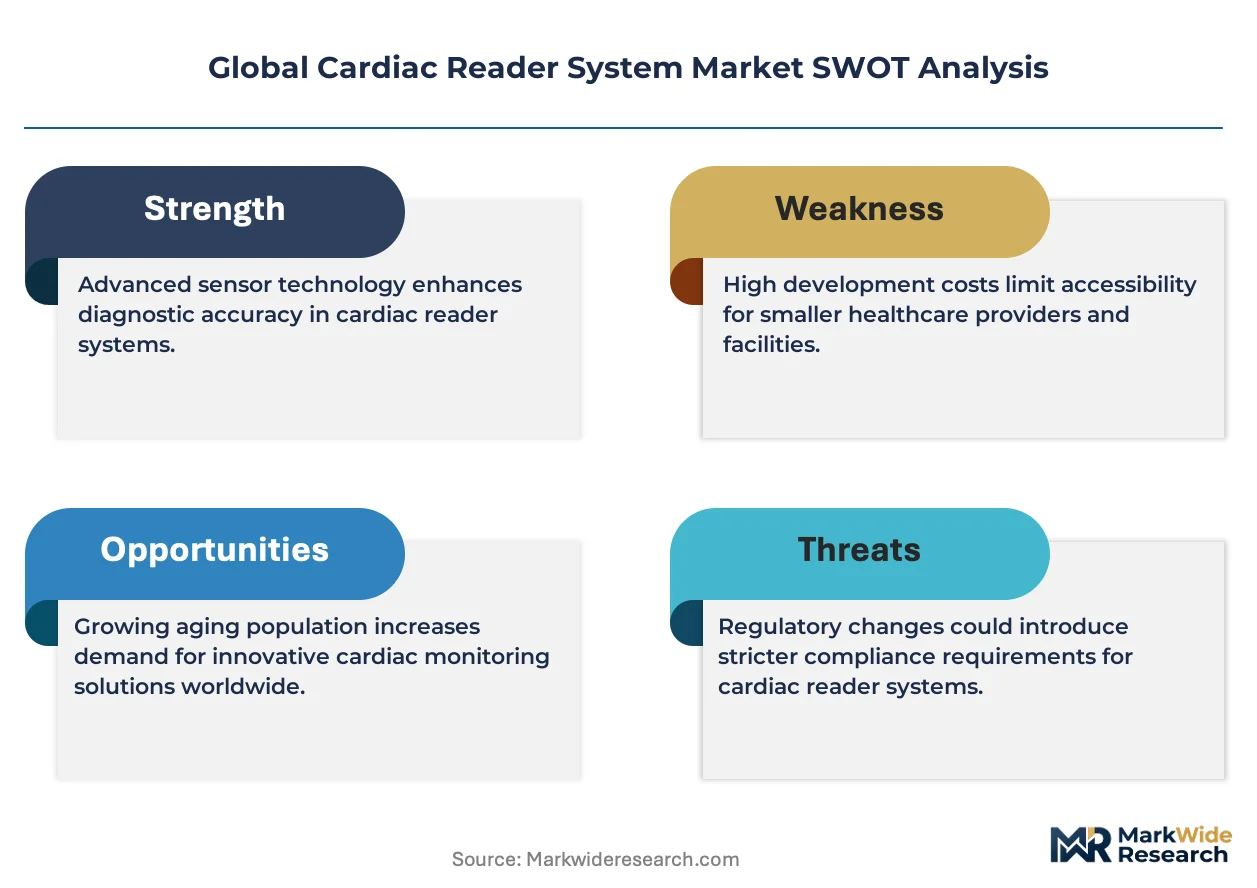
AI-based arrhythmia detection algorithms are compressing clinical review cycles and redistributing diagnostic authority from centralized hospital laboratories toward distributed outpatient settings. This technological shift is restructuring competitive advantage around proprietary training datasets and regulatory clearance portfolios rather than hardware manufacturing scale alone.
Growth Catalysts
- Remote patient monitoring reimbursement:CMS and private payers in the United States have established Category III CPT codes for wearable ECG patch services. Home care providers now deploy these devices for post-discharge cardiac surveillance.
- Wearable connectivity protocols:Bluetooth Low Energy and cellular-enabled monitors eliminate dependency on patient-triggered event recording. Real-time streaming enables immediate clinician intervention during acute episodes.
- EU MDR software classification clarity:The Medical Device Regulation's guidance on software-as-a-medical-device has reduced regulatory uncertainty for cloud-based cardiac analysis platforms seeking CE marking.
Market Restraints
- Algorithm validation costs:FDA premarket submissions for machine-learning classifiers require multi-site clinical trials with adjudicated ground truth. Small developers lack capital to generate statistically significant training datasets.
- Implantable component supply concentration:Miniaturized biosensors and long-life batteries for insertable cardiac monitors depend on Taiwanese and South Korean foundries. Geopolitical friction threatens component availability.
- Physician liability exposure:Automated rhythm interpretation without mandatory over-read creates malpractice uncertainty. Cardiology societies have issued cautious guidance on unsupervised AI diagnosis.
Strategic Opportunities
- Underpenetrated rural India:Telemedicine infrastructure expansion under the Ayushman Bharat Digital Mission creates distribution pathways for low-cost single-lead devices. CDSCO fast-track pathways for software-enabled diagnostics accelerate market entry.
- Sleep medicine convergence:Integration of nocturnal ECG with polysomnography enables simultaneous apnea and arrhythmia screening. Sleep clinics represent a channel bypassing traditional cardiology gatekeepers.
- EU AI Act compliance services:High-risk medical device AI systems face mandatory conformity assessments. Vendors offering validated algorithm documentation and post-market monitoring tools capture adjacent revenue streams.
Industry Challenges
- Electrophysiologist annotation bottleneck:Supervised learning requires expert-labeled ECG segments. The limited pool of certified electrophysiologists constrains training data generation velocity.
- Legacy EMR integration complexity:Hospital information systems use proprietary data formats. Bi-directional connectivity between cloud cardiac platforms and on-premise Epic or Cerner deployments demands custom interface engineering.
- Cross-border data residency mandates:China's Personal Information Protection Law and Russia's data localization requirements fragment cloud storage architectures. Multi-tenant platforms must maintain geographically isolated instances.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cardiac Reader System Market |
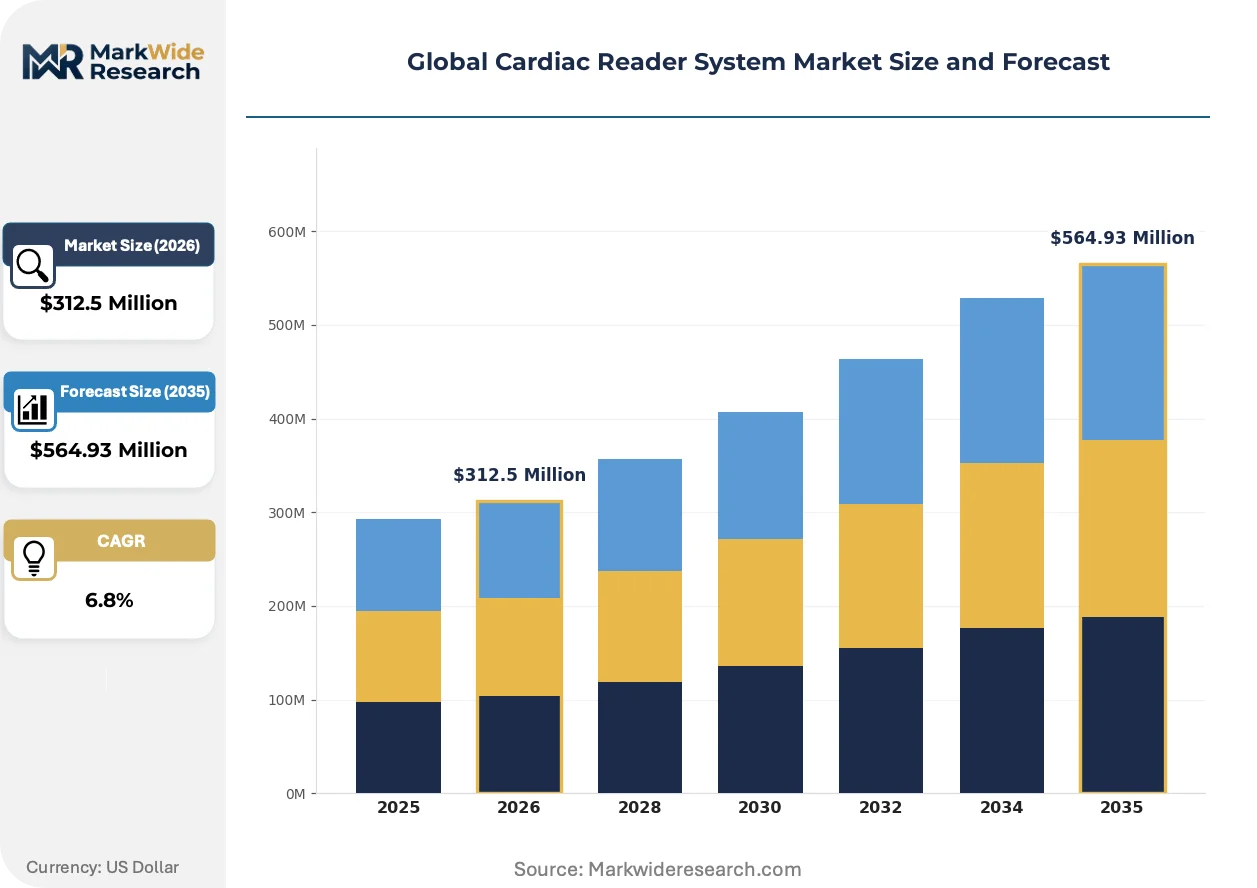
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $564.93 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Holter Monitors, Event Recorders, Implantable Loop Recorders, Wearable ECG Devices, Remote Cardiac Monitors Technology: Wireless Transmission, Bluetooth Connectivity, Cloud Storage, AI-Based Analysis, Real-Time Monitoring Application: Arrhythmia Detection, Heart Rate Variability Analysis, Post-Surgical Monitoring, Stress Testing, Sleep Apnea Screening End User: Cardiology Clinics, Diagnostic Centers, Research Institutes, Home Care Providers, Telemedicine Services |
| Companies Covered | GE HealthCare Technologies, Inc., Koninklijke Philips N.V., Siemens Healthineers AG, Mindray Medical International Limited, Medtronic, Boston Scientific Corporation, Abbott, OSI Systems, Inc., iRhythm Technologies, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cardiac Reader System Market Shifts & Advancements
Signal processing architectures and clinical workflow integration patterns are converging toward continuous, automated cardiac surveillance outside traditional diagnostic centers. Three developments dominate this transformation.
Edge computing on wearable ECG devices is decentralizing rhythm analysis from hospital servers to patient-worn processors. Semiconductor manufacturers now embed machine-learning accelerators capable of real-time atrial fibrillation detection directly into patch electrodes. Home care providers and emergency medical services deploy these devices to compress the interval between symptom onset and therapeutic decision.
Japan's PMDA has tightened software change control requirements for AI-enabled cardiac monitors under revised QMS Ministerial Ordinances. Manufacturers must now submit pre-defined algorithm modification protocols before receiving marketing authorization. This regulatory friction is concentrating product development resources among vendors with established Tokyo-based regulatory affairs capabilities.
Hospital procurement committees now unbundle hardware acquisition from algorithm licensing and cloud storage subscriptions. Cardiology departments negotiate separate contracts for device placement, interpretation services, and data hosting. This purchasing pattern is most visible in Germany, where hospital procurement associations leverage collective bargaining power to drive subscription pricing toward per-patient-per-month models.
Global Cardiac Reader System Market Segmentation
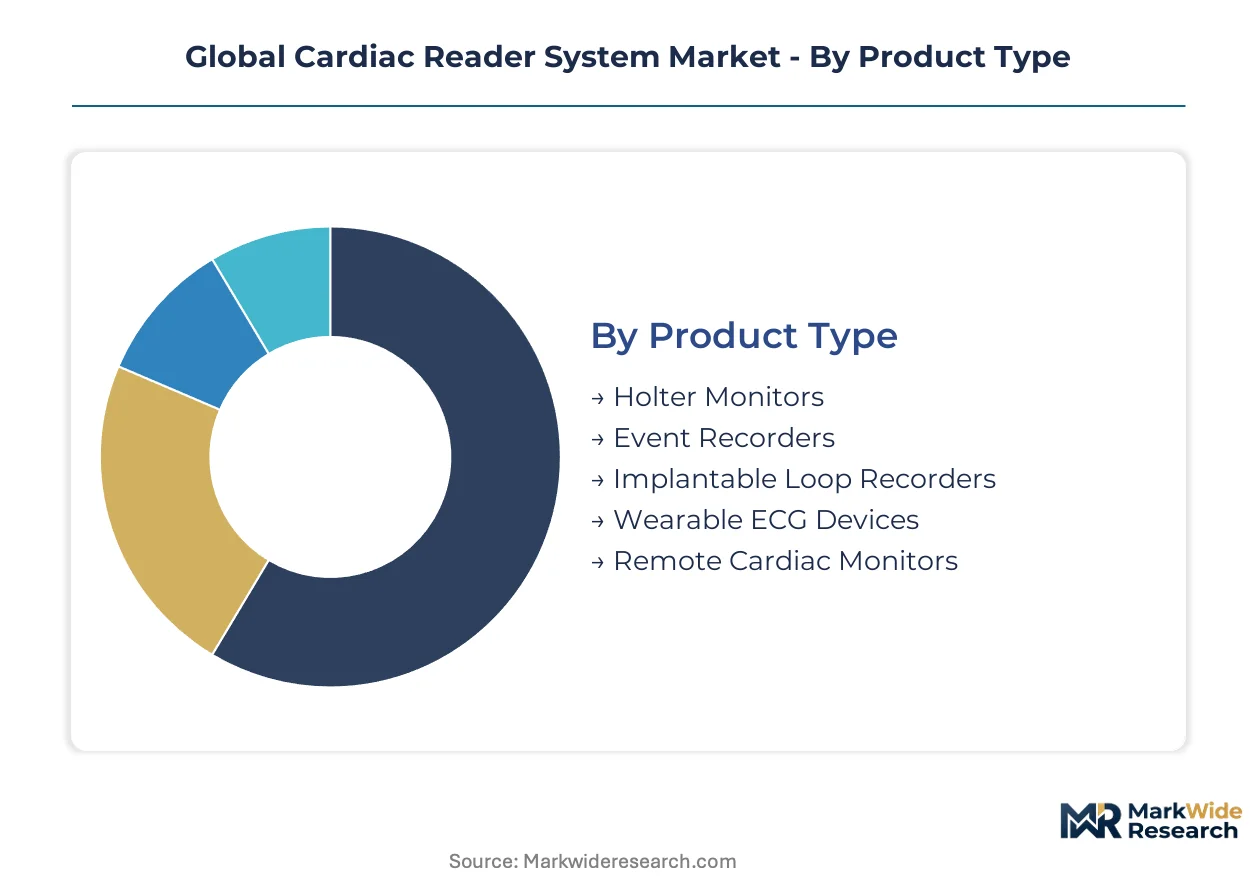
Cardiac reader system deployment patterns diverge sharply between embedded hospital infrastructure and standalone ambulatory devices. Segmentation by integration depth, connectivity protocol, clinical setting, and procurement authority reveals where margin pools concentrate versus where volumes expand fastest.
Product Type:
Integration depth separates invasive implantable systems requiring surgical placement from surface-worn devices that operate independently of hospital infrastructure.
- Wearable ECG Devices:Lightweight patch electrodes sample at 250–1000 Hz with Bluetooth Low Energy transmission to paired smartphones. Demand concentrates among home care providers in Germany and the United States where CMS reimbursement codes now cover post-discharge cardiac surveillance. Real-time streaming protocols eliminate patient-triggered event dependency.
- Implantable Loop Recorders:Subcutaneous devices with multi-year battery life capture continuous rhythm data via internal electrodes. Pricing premiums reflect invasive placement requirements and extended monitoring horizons; electrophysiology departments in Japan's university hospitals anchor procurement volume.
- Holter Monitors:Multi-lead ambulatory recorders with 24–48 hour data capture remain the standard for diagnostic center workflows.
- Event Recorders:Patient-activated or auto-triggered devices for intermittent symptom correlation.
- Remote Cardiac Monitors:Cellular-enabled systems for centralized telemetry outside traditional clinical settings.
Volume placements concentrate in Holter Monitors; the faster expansion belongs to Wearable ECG Devices.
Technology:
Cost tier stratification separates premium AI-enabled analysis platforms from commoditized connectivity modules.
- AI-Based Analysis:Machine-learning classifiers trained on adjudicated ECG datasets automate atrial fibrillation detection and reduce manual over-read requirements. FDA premarket submissions under 21 CFR 870 demand multi-site clinical trials with electrophysiologist-labeled ground truth, concentrating development resources among vendors with proprietary training databases.
- Cloud Storage:HIPAA-compliant and GDPR-aligned architectures enable multi-tenant data hosting with bi-directional EMR integration. Hospital procurement committees in Germany increasingly unbundle storage subscriptions from hardware acquisition, driving per-patient-per-month pricing models.
- Wireless Transmission:Cellular and Wi-Fi protocols for continuous data backhaul from patient-worn devices.
- Bluetooth Connectivity:Low-energy pairing protocols for smartphone-integrated monitoring ecosystems.
- Real-Time Monitoring:Latency-critical alert systems for emergency medical services and acute episode response.
Revenue margins peak in AI-Based Analysis; the steepest expansion trajectory runs through Cloud Storage.
Application:
Customer workflow integration determines whether systems embed into existing clinical pathways or require new specialty training.
- Arrhythmia Detection:Automated rhythm classification for atrial fibrillation, ventricular tachycardia, and bradyarrhythmia identification. Cardiology clinics in the United States deploy these systems to decompress electrophysiologist review queues; Japan's PMDA tightened software change control requirements under revised QMS Ministerial Ordinances.
- Sleep Apnea Screening:Nocturnal ECG integration with polysomnography enables simultaneous arrhythmia and respiratory event detection. Sleep clinics in Germany represent a distribution channel bypassing traditional cardiology gatekeepers.
- Heart Rate Variability Analysis:Autonomic function assessment for wellness and athletic performance applications.
- Post-Surgical Monitoring:Continuous surveillance following cardiac intervention or thoracic procedures.
- Stress Testing:Exercise-induced ischemia and rhythm abnormality detection in controlled laboratory settings.
Clinical volume concentrates in Arrhythmia Detection; Sleep Apnea Screening gains share fastest as polysomnography workflows expand.
End User:
Procurement authority and reimbursement pathway maturity create divergent customer economics across settings.
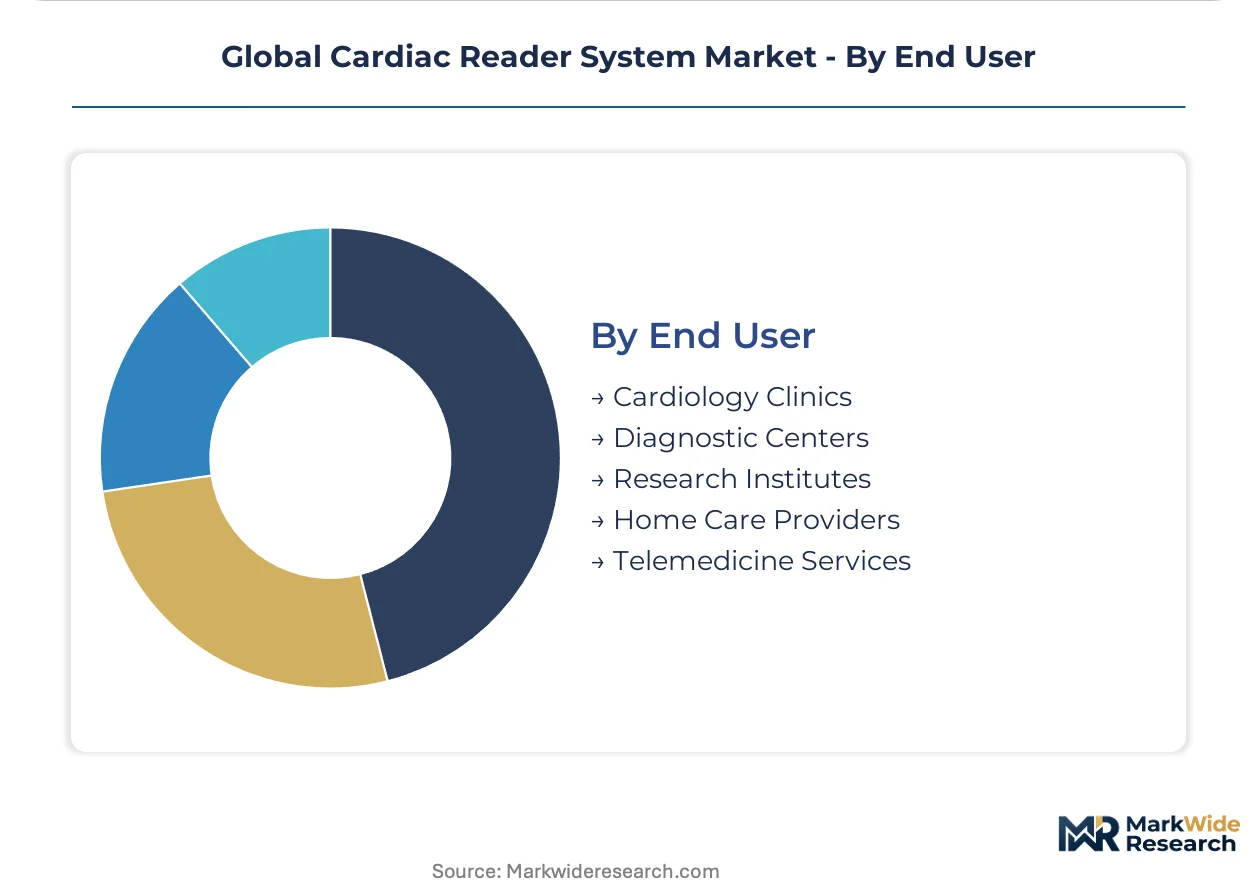
- Home Care Providers:Skilled nursing agencies and home health services deploy wearable ECG devices for post-acute cardiac surveillance. CMS Category III CPT codes in the United States established reimbursement pathways; telemedicine platforms in rural India under Ayushman Bharat Digital Mission create volume opportunities for low-cost single-lead systems.
- Telemedicine Services:Virtual-first care models integrate cardiac reader data into remote consultation workflows. Cloud storage backends with real-time dashboards enable clinician intervention without physical patient presence; EU MDR software classification clarity reduced regulatory uncertainty for cross-border platform operators.
- Cardiology Clinics:Specialist practices with in-house electrophysiology interpretation capabilities.
- Diagnostic Centers:High-throughput facilities processing batch ECG analysis with AI-assisted over-read.
- Research Institutes:Academic medical centers generating training data for algorithm development and regulatory submissions.
Procurement volume concentrates in Cardiology Clinics; Telemedicine Services climb the fastest as virtual care models scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones for medical device manufacturing in Penang, Malaysia, and Costa Rica concentrate component assembly and final-device production for cardiac reader systems. These zones attract investment through tax holidays and streamlined customs procedures. The resulting production clusters feed distribution networks across North America, Europe, and Asia-Pacific.
United States
CMS Category III CPT codes for wearable ECG patch services drive procurement volume among home care providers and telemedicine platforms. FDA premarket review under 21 CFR 870 intensifies scrutiny of machine-learning-based arrhythmia classifiers. The Minneapolis-St. Paul corridor anchors electrophysiology device development, with research institutes generating training data for algorithm submissions.
Germany
Hospital procurement associations leverage collective bargaining power to unbundle hardware acquisition from cloud storage subscriptions. EU MDR software classification clarity reduced regulatory uncertainty for cross-border cardiac analysis platforms. The Baden-Württemberg cluster around Stuttgart concentrates AI-enabled diagnostic workflow engineering for high-throughput cardiology clinics.
Japan
Reimbursement pathways for remote cardiac monitoring have matured under universal health coverage expansion. PMDA tightened software change control requirements under revised QMS Ministerial Ordinances. Tokyo-based university hospitals anchor procurement volume for implantable loop recorders with multi-year monitoring horizons.
India
Telemedicine infrastructure expansion under the Ayushman Bharat Digital Mission creates distribution pathways for low-cost single-lead wearable devices. CDSCO fast-track pathways for software-enabled diagnostics accelerate market entry for cloud-based cardiac platforms. Karnataka's Bengaluru cluster concentrates health-tech development for rural patient monitoring deployment.
South Korea
Miniaturized biosensors and long-life batteries for insertable cardiac monitors depend on foundry capacity concentrated in Seoul and Gyeonggi Province. MFDS maintains parallel approval tracks that delay market entry for unproven algorithm architectures. The Daejeon-Sejong corridor anchors semiconductor manufacturing for edge-computing wearable processors.
Global Cardiac Reader System Market Competitive Landscape
Top-tier vendors anchor the premium AI-analysis and implantable device segments, while mid-scale specialists concentrate on wearable hardware and regional cloud deployments. The vendor base stratifies across three tiers: diversified health technology conglomerates with imaging ecosystem bundling, pure-play cardiac monitoring specialists with algorithm-centric business models, and contract manufacturers supplying white-label patch electrodes. Dominant competitive moves include strategic partnerships for EMR integration and portfolio diversification into sleep medicine convergence.
Within the diversified health technology tier, GE HealthCare Technologies, Inc., Koninklijke Philips N.V., and Siemens Healthineers AG exemplify competing strategic archetypes. GE HealthCare leverages imaging ecosystem bundling to integrate cardiac reader hardware with enterprise data infrastructure. Philips anchors positioning through sleep apnea screening workflows that merge wearable ECG devices with cloud storage backends. Siemens Healthineers competes on AI-based analysis capabilities embedded directly into diagnostic center workflows, representing the algorithm-centric vector within this tier.
| Leading Market Players |
|---|
| GE HealthCare Technologies, Inc. |
| Koninklijke Philips N.V. |
| Siemens Healthineers AG |
| Mindray Medical International Limited |
| Medtronic |
| Boston Scientific Corporation |
| Abbott |
| OSI Systems, Inc. |
| iRhythm Technologies, Inc. |
| Others |
Supply & Pricing Matrix
Edge computing migration in wearable ECG processors is simultaneously collapsing per-unit manufacturing costs and concentrating semiconductor foundry relationships among vendors with captive access to Taiwanese and South Korean fabrication capacity. This technological inflection redraws margin allocation between hardware producers and algorithm licensors.
Pricing Analysis
Short lead-time premiums dominate pricing negotiations, with electrophysiology departments in Japan's university hospitals paying substantial markups for implantable loop recorders against 90-day manufacturing windows. The dominant structure is a three-tier pricing structure across premium, standard, and economy levels, with FDA 510(k) clearance tier and algorithm training dataset scale as primary differentiation drivers. Cost compression in economy-tier wearable patches is intensifying because of white-label electrode competition from contract manufacturers. Home care providers in rural India exhibit highest price sensitivity; electrophysiology departments in tertiary centers show least.
Supply Chain Analysis
Reverse logistics for explanted implantable devices and refurbished Holter monitors create secondary supply streams that pressure new-equipment pricing in European diagnostic centers. Component sourcing draws from Taiwan for miniaturized biosensors, South Korea for long-life batteries, and Malaysia for final assembly in Penang's special economic zone. Single-source vulnerability concentrates in 5-nanometer machine-learning accelerators for edge-computing patches. Distribution runs through hospital procurement associations in Germany and group purchasing organizations in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electrophysiologist annotation capacity constrains training data generation velocity, propping algorithm licensing premiums and sustaining vendor pricing power across the analysis window.
For Market Incumbents: Deepen proprietary training dataset accumulation through exclusive partnerships with Tokyo-based university hospitals generating adjudicated ECG ground truth. Add captive foundry capacity in South Korea's Gyeonggi Province to secure biosensor supply against geopolitical friction. Algorithm commoditization from open-source rhythm classifiers threatens margin pools in diagnostic center segments. For New Entrants and Emerging Players: Begin with sleep medicine convergence applications in German polysomnography clinics, where cardiology gatekeeper bypass enables faster reimbursement pathway establishment. Target rural India telemedicine infrastructure under Ayushman Bharat Digital Mission for lowest competitive density. Pursue CDSCO fast-track software-enabled diagnostic designation as primary go-to-market accelerant. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by diversified health technology conglomerates seeking algorithm-centric cardiac monitoring capabilities. Five-to-ten-year viability hinges on regulatory clearance portfolio breadth rather than hardware manufacturing scale alone. Monitor FDA premarket submission backlogs for machine-learning classifiers as inflection indicator for algorithm vendor consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission | 510(k) clearance under 21 CFR 870 anchors reimbursement eligibility with CMS. |
| CE Marking Pathway | EU MDR software-as-a-medical-device classification enables cross-border platform deployment. |
| Hospital System Partnership | Epic and Cerner EMR integration contracts secure recurring interpretation service revenue. |
| Software Companion Development | AI-based arrhythmia detection algorithms reduce electrophysiologist over-read labor costs. |
| Reimbursement Strategy | CMS Category III CPT code coverage drives home care provider procurement volume. |
Research Methodology
Independent corroboration across FDA 510(k) filing databases, EU MDR notified body technical documentation, and CMS reimbursement code histories underwrites the qualitative findings in this study. Primary interviews with electrophysiologists, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers combined with secondary validation from PMDA submission records, CDSCO fast-track approval logs, and hospital procurement database extracts. Bottom-up device placement estimates and top-down algorithm licensing revenue triangulation anchor segmentation outputs.
Rate-of-change decomposition separates volume expansion from pricing trajectory across product type, technology tier, clinical application, and end-user procurement authority dimensions throughout the forecast period. CAGRs derive from fitted growth curves against historical placement data and reimbursement pathway maturation timelines. Industry-specific forecast inputs include electrophysiologist workforce growth projections and semiconductor foundry capacity expansion announcements.
Underlying measurement precision varies by segment; AI-based analysis and implantable loop recorder categories carry tighter precision than commoditized Bluetooth connectivity modules. Forecasts reflect documented assumptions regarding regulatory clearance timelines and reimbursement code expansion. Practitioners should monitor FDA software premarket review queue lengths and EU AI Act high-risk device conformity assessment backlogs for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Contact Thermometer Market
Medical Devices
France Spinal Surgery Devices Market
Medical Devices
Power Wheelchairs and Mobility Scooters Market
Medical Devices
Global Otoscopes Market
Medical Devices
Wearable Defibrillators Market
Medical Devices
Automatic Pill Dispenser Machine Market
Medical Devices
Nano Healthcare Technology for Medical Equipment Market
Medical Devices
Global Large Volume Wearable Injectors Market
Medical Devices
Chile Extracorporeal Shock Wave Lithotripsy Market
Medical Devices
North America IVD Regulatory Affairs Outsourcing Market
Medical Devices
Blood Lancet Market
Medical Devices
Global Single-Use Medical Device Reprocessing Market
Medical Devices
United States Minimally Invasive Surgery Device Market
Medical Devices
Cardiac Poc Testing Devices Market
Medical Devices
Global Pelvic Floor Electric Stimulator Market
Medical Devices
Implantable Drug Eluting Devices Market